
 E Passport Market | 2026-2036
E Passport Market Size, Share, and Industry Trends Forecast 2026-2036
E Passport Market Intelligence
Direct government procurement channels is fragmenting across multiple national security printers and technology integrators. Thales Group leverages its semiconductor-to-system integration pipeline to sustain large-scale e-passport deployments across European and Middle Eastern contracts. IDEMIA anchors its position through biometric algorithm leadership and dedicated secure manufacturing facilities. Muhlbauer Group specializes in personalization equipment and end-to-end production line solutions that compete on automation density.
An e-passport embeds a contactless integrated circuit chip storing biometric data and cryptographic keys, manufactured through lamination of polycarbonate data pages with embedded RFID inlays and holographic security features, serving to authenticate traveler identity at automated border control gates. Biometric product types lead current deployment volumes as facial recognition and fingerprint templates become mandatory under ICAO Doc 9303 standards, while contactless technology segments capture expanding margin pools through NFC-enabled mobile verification extensions. Government application segments dominate procurement budgets, though security-focused implementations for diplomatic personnel represent a concentrated premium tier.
ICAO standards, EU GDPR biometric data frameworks, and national data protection authorities collectively shape product design requirements and cross-border interoperability mandates for e-passport vendors. The EU AI Act introduces additional scrutiny on automated biometric identification systems deployed at border checkpoints, forcing technology providers to demonstrate algorithmic audit trails. Stakeholders must monitor evolving cryptographic standards and quantum-resistant algorithm timelines to ensure document lifecycle compatibility.
Market Dynamics
ICAO Doc 9303 mandates for biometric data embedding are compressing procurement timelines and forcing security printer consolidation around chip-to-system integration capabilities.
Growth Catalysts
- ICAO Doc 9303 compliance deadlines:Government agencies across Indonesia, Vietnam, and India are accelerating e-passport rollout schedules to meet international aviation interoperability standards.
- Contactless chip technology maturation:NFC-enabled verification architectures now support mobile border gate extensions, expanding addressable infrastructure beyond traditional kiosk deployments.
- Facial recognition template standardization:Biometric algorithm performance benchmarks under ISO/IEC 19795 are driving procurement specifications toward multi-modal identity verification systems.
Market Restraints
- Polycarbonate substrate concentration:Three European chemical suppliers control specialized optical-grade polymer supply for data page lamination, creating input cost volatility exposure.
- EU AI Act algorithmic audit requirements:Automated biometric identification systems at border checkpoints face documentation burdens that extend vendor certification cycles.
- Legacy optical passport substitution:Machine-readable zone documents without chip infrastructure retain residual demand in cost-constrained procurement environments.
Strategic Opportunities
- Underpenetrated African markets:Nigeria, Kenya, and Egypt lack comprehensive biometric travel document infrastructure, representing greenfield deployment potential.
- EU Green Deal sustainable manufacturing incentives:Secure printing facilities adopting renewable energy and recyclable substrate formulations qualify for preferential procurement scoring.
- Blockchain-verified credential convergence:Distributed ledger authentication layers paired with e-passport chips enable self-sovereign identity pilot programs.
Industry Challenges
- Quantum-resistant cryptography migration:Document lifecycle planning must accommodate NIST post-quantum algorithm standards that remain partially undefined.
- Multi-jurisdiction data residency compliance:Cloud-based biometric verification backends face conflicting localization requirements across national data protection frameworks.
- Skilled personalization engineer scarcity:Automated production line programming for polycarbonate inlay embedding exceeds available technical training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E Passport Market |
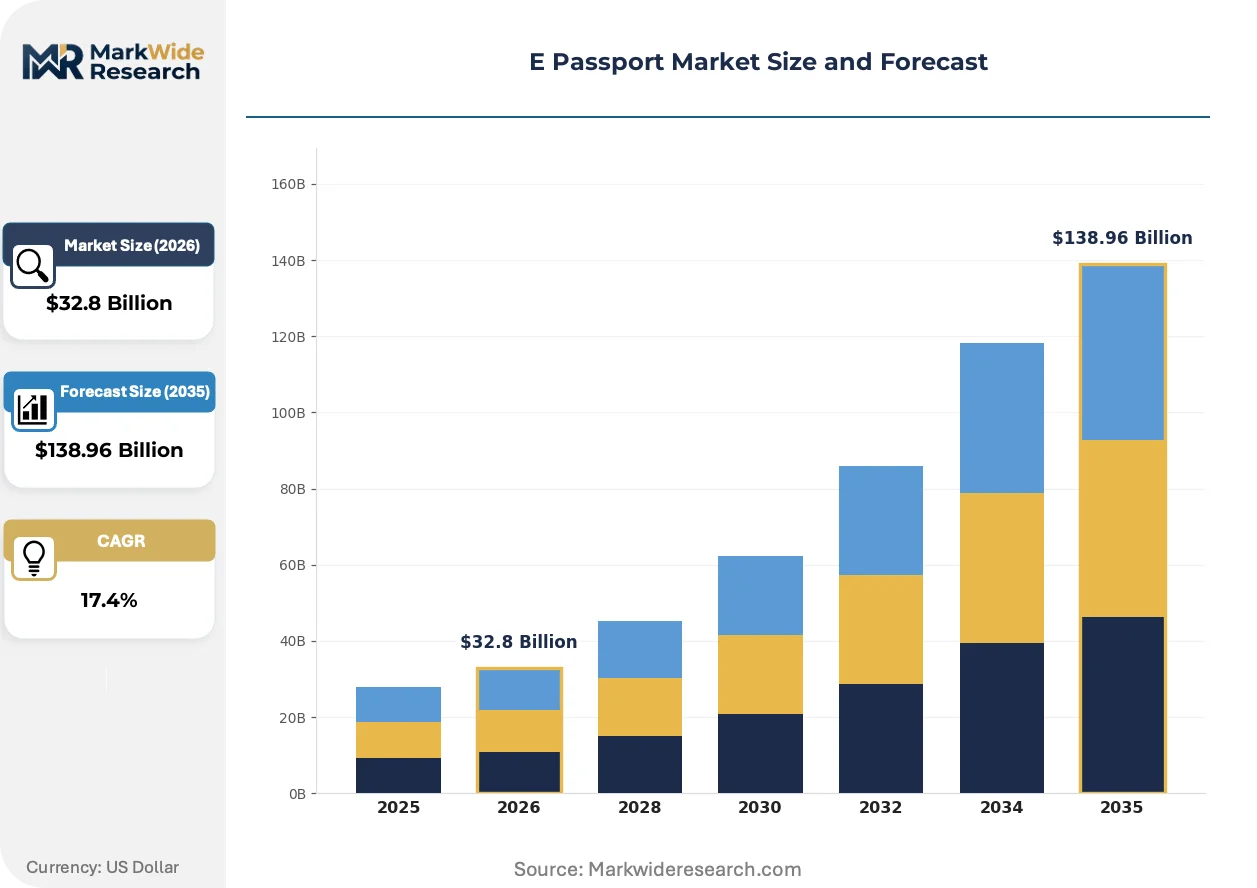
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $138.96 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless, Biometric, Electronic, Smart Card Application: Government, Travel, Immigration, Security End User: Citizens, Tourists, Business Travelers, Diplomatic Personnel Technology: RFID, NFC, Magnetic Stripe, Optical Storage |
| Companies Covered | Thales Group, IDEMIA, Muhlbauer Group, Entrust Corporation, HID Global Corporation, Infineon Technologies AG, 3M, 4G Identity Solutions, CardLogix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E Passport Market Strategic Shifts & Innovations
Document security architecture is pivoting from static holographic features toward dynamic cryptographic authentication and mobile-integrated verification layers.
Polycarbonate data pages with embedded RFID inlays are rendering obsolete traditional paper-based laminated passports across European and Asia-Pacific procurement channels. Border agencies in Germany, France, and Singapore have mandated chip-enabled documents for visa-waiver program participation. This shift compresses replacement cycles and elevates semiconductor-to-lamination integration requirements for security printers.
EU AI Act algorithmic transparency mandates are forcing biometric system vendors to document training data provenance and decision audit trails for automated border gate deployments. Machine learning-based facial recognition engines now require conformity assessment procedures that extend vendor qualification timelines. Airport operators in Spain, Italy, and the Netherlands are prioritizing explainable AI architectures to preempt regulatory enforcement actions.
Consolidated national identity platforms are displacing standalone passport procurement models in Nordic and Baltic markets. Estonia, Finland, and Latvia now issue travel documents through integrated digital identity wallets that synchronize with mobile verification applications. Government IT agencies in these jurisdictions are unbundling hardware manufacturing from software service contracts, redirecting vendor selection criteria toward API interoperability and cloud backend resilience.
E Passport Market Segmentation
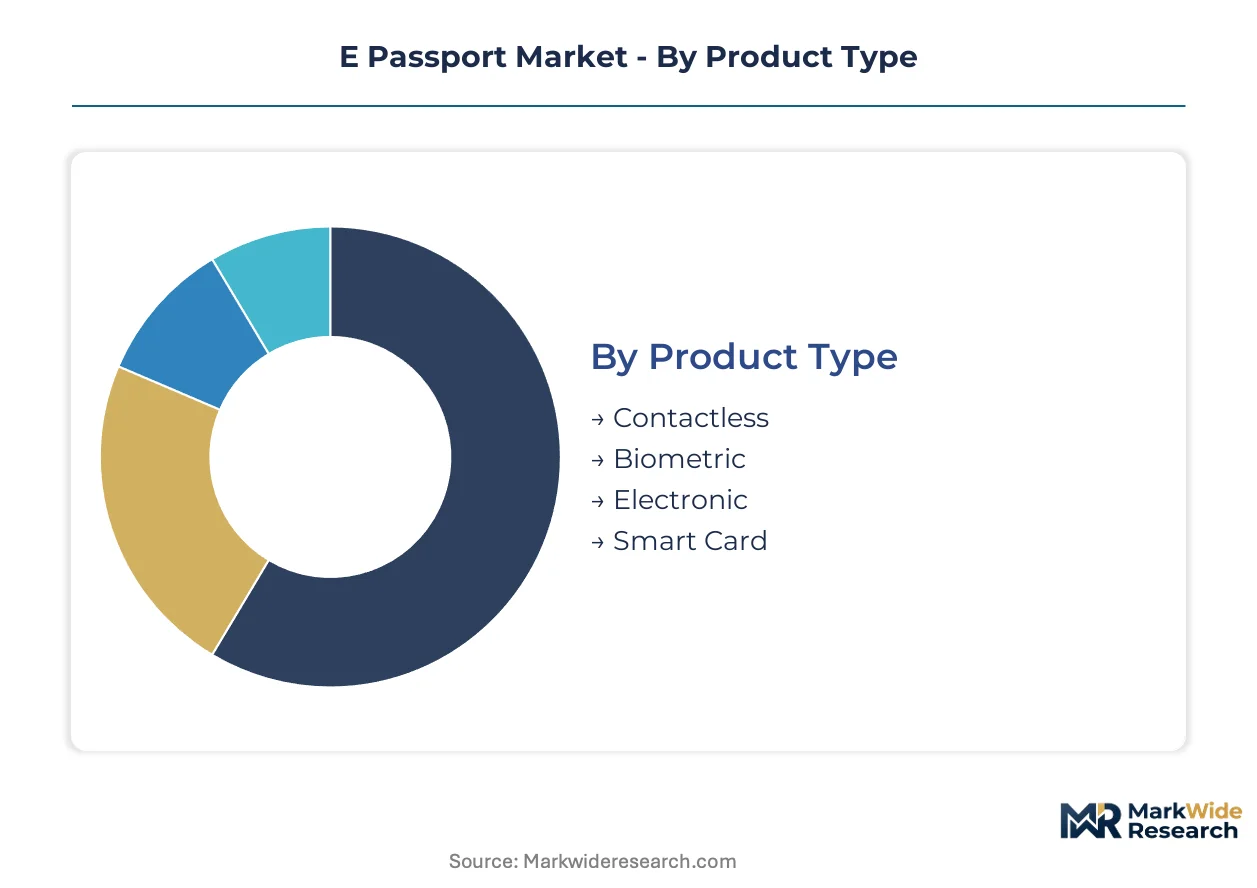
E-passport procurement specifications vary sharply across deployment contexts, with government buyers prioritizing document lifecycle durability while border infrastructure operators emphasize reader interoperability. Segmentation reveals where technical specifications diverge from commercial procurement patterns, exposing margin concentration points for security printer vendors.
Product Type:
After-sales-service intensity runs highest for biometric-enabled variants, where algorithm updates and template re-enrollment create recurring vendor touchpoints across document validity periods.
- Contactless:Embedded RFID inlays within polycarbonate data pages enable wireless chip communication at automated border gates. Demand concentrates in Germany, France, and Singapore as these jurisdictions mandate NFC-enabled documents for visa-waiver program participation, with procurement specifications tightening around ISO/IEC 14443 interoperability standards.
- Biometric:Facial recognition and fingerprint templates stored on secure elements comply with ICAO Doc 9303 mandates. India, Indonesia, and Vietnam are accelerating rollout schedules to meet international aviation interoperability standards, compressing procurement timelines for multi-modal identity verification systems.
- Electronic:Basic chip-enabled documents without biometric storage serve cost-constrained procurement environments.
- Smart Card:Hybrid form factors combining travel document with payment or national ID functionality.
By volume, Contactless leads. By growth pace, Biometric is ahead.
Application:
Cost tier stratification separates commodity document procurement from premium security implementations, with diplomatic and intelligence applications commanding five-to-ten-fold unit price multiples.
- Government:National passport authorities issue standardized documents to citizens through civil registration systems. Nigeria, Kenya, and Egypt lack comprehensive biometric travel document infrastructure, representing greenfield deployment potential where procurement budgets compete with other identity modernization priorities.
- Travel:Airline and airport operators deploy verification infrastructure for passenger processing acceleration. EU AI Act algorithmic transparency mandates are forcing biometric system vendors to document training data provenance and decision audit trails for automated border gate deployments in Spain, Italy, and the Netherlands.
- Immigration:Visa and residency permit systems require document authenticity verification at consular posts.
- Security:Law enforcement and intelligence applications demand tamper-evident features and restricted distribution channels.
Government captures the largest procurement volumes. Security applications deliver the steepest expansion trajectory as threat environments intensify.
End User:
Customer type determines document validity periods, biometric enrollment requirements, and fee structures, with diplomatic personnel receiving expedited processing and extended validity terms.
- Citizens:Standard passport holders constitute the baseline volume segment with ten-year validity cycles in most jurisdictions.
- Tourists:Emergency travel document issuance and temporary passport replacements serve disrupted itineraries.
- Business Travelers:Frequent flyer program integrations and expedited border crossing subscriptions create recurring revenue attachments.
- Diplomatic Personnel:Special passport categories with enhanced security features and privileged processing protocols.
Citizens generate absolute volume. Business Travelers are climbing the fastest as corporate mobility budgets recover.
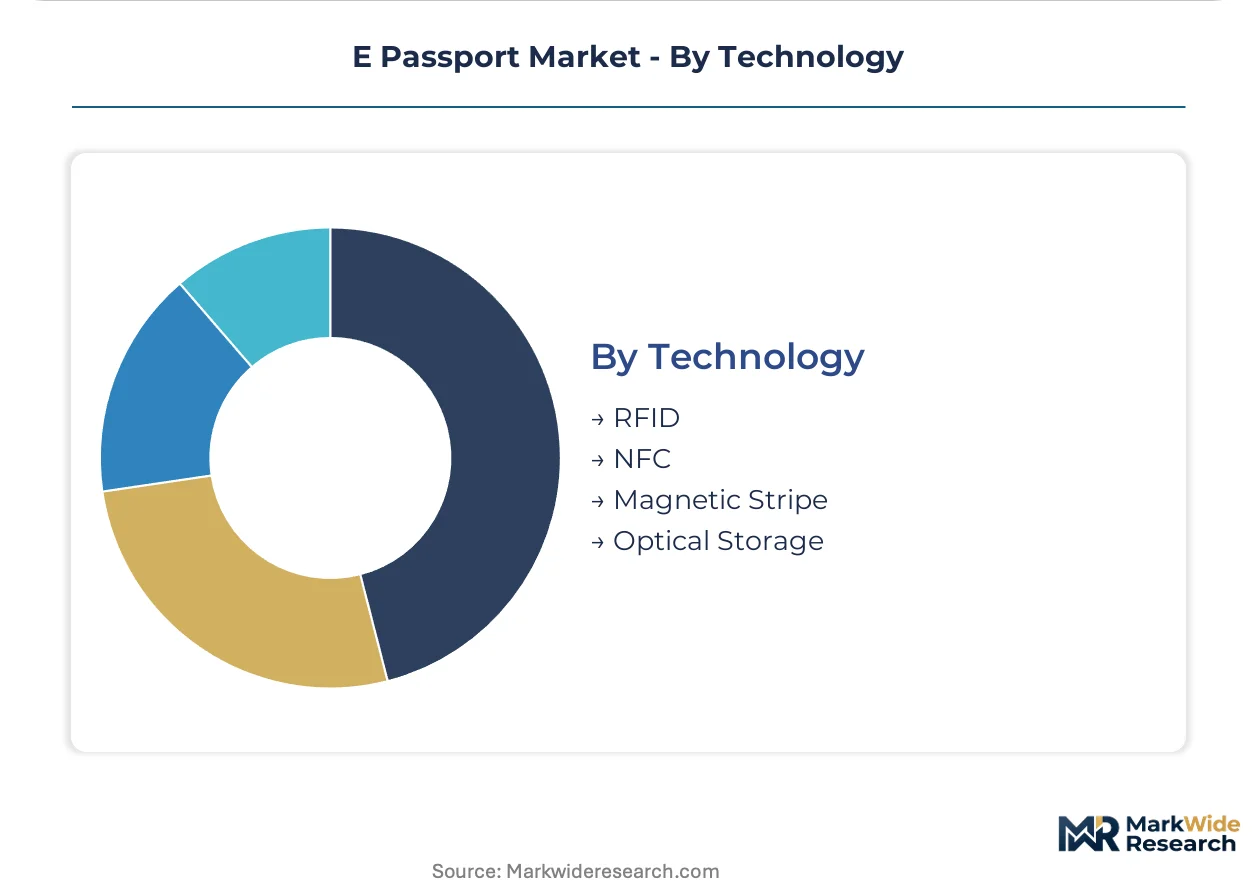
Technology:
Supply concentration in semiconductor fabrication shapes procurement risk profiles, with NFC controller availability constraining large-scale deployment timelines.
- RFID:UHF and HF radio frequency identification dominates current installed base for chip-to-reader communication.
- NFC:Near-field communication enables mobile phone verification and wallet integration. Estonia, Finland, and Latvia now issue travel documents through integrated digital identity wallets that synchronize with mobile verification applications, unbundling hardware manufacturing from software service contracts.
- Magnetic Stripe:Legacy technology retained in transitional deployments for backward compatibility.
- Optical Storage:Machine-readable zones and 2D barcodes serve fallback authentication when chip infrastructure fails.
RFID maintains installed base dominance. NFC is gaining share fastest as mobile verification architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for ICAO Doc 9303 compliance are compressing procurement timelines across jurisdictions with outdated passport infrastructure. Border modernization budgets in emerging economies now rival defense spending in absolute terms. Chip-enabled document procurement channels are fragmenting across regional security printer networks.
India
Passport Seva Kendra expansion targets biometric enrollment capacity of 50,000 daily applications by 2025. The Ministry of External Affairs mandates facial recognition templates under ICAO standards for all new issuances. Bangalore and Hyderabad host personalization facilities where polycarbonate inlay embedding automation is being retrofitted.
Germany
Federal Police procurement specifications require NFC-enabled documents for automated border gate interoperability at Frankfurt and Munich airports. The Bundesdruckerei operates under EU AI Act documentation requirements for biometric algorithm audit trails. Berlin anchors semiconductor-to-system integration capabilities serving Middle Eastern contract exports.
Indonesia
Directorate General of Immigration accelerated e-passport rollout schedules to meet 2024 ICAO compliance deadlines for visa-waiver program retention. National data protection authority guidelines shape local storage requirements for biometric templates. Jakarta and Surabaya concentrate personalization infrastructure with Chinese and European equipment integrators competing for line automation contracts.
United States
Department of State Next Generation Passport program embeds contactless chips with expanded data capacity for future biometric expansion. CBP facial recognition deployment at 30+ international airports drives document reader interoperability specifications. Washington DC and northern Virginia host systems integrators serving diplomatic and standard passport production lines.
Vietnam
Immigration Department procurement compresses vendor qualification timelines for chip-enabled document infrastructure ahead of 2025 ASEAN integration targets. National cybersecurity law mandates domestic data residency for biometric verification backends. Ho Chi Minh City and Hanoi concentrate secure printing partnerships with European technology licensors.
E Passport Market Key Industry Players
On the supply side, the industry is consolidating around chip-to-system integration capabilities as procurement specifications tighten. Three to five full-stack vendors dominate large-scale government contracts, while specialized equipment manufacturers compete on automation density for personalization lines. Strategic archetypes include semiconductor-to-security printers, biometric algorithm specialists, and production line automation engineers. Dominant competitive moves encompass strategic partnerships for polycarbonate substrate security and technology licensing for quantum-resistant cryptographic modules.
Within the full-stack integration tier, Thales Group and IDEMIA exemplify archetypes spanning semiconductor fabrication through secure document personalization. Muhlbauer Group occupies a position among production line automation specialists, representing equipment-centric competitive positioning. These three anchors illustrate how vendor selection criteria are unbundling hardware manufacturing from software service contracts across Nordic and Baltic procurement channels.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| Muhlbauer Group |
| Entrust Corporation |
| HID Global Corporation |
| Infineon Technologies AG |
| 3M |
| 4G Identity Solutions |
| CardLogix Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on European optical-grade polycarbonate suppliers compresses margin structures across document security tiers and forces procurement officers into multi-year offtake commitments. This concentration dynamic simultaneously widens price spreads between biometric-enabled premium documents and basic chip-enabled variants while reshaping vendor qualification criteria around supply assurance capabilities.
Pricing Analysis
Certification level under ICAO Doc 9303 and EU AI Act conformity assessment creates the primary spread between premium biometric deployments and standard electronic documents. Three-tier pricing structure separates diplomatic-grade multi-modal systems from government-standard facial recognition templates and cost-optimized basic chip documents. Pricing pressure stems from polycarbonate substrate volatility as three European chemical suppliers control specialized optical-grade polymer feedstock. Government procurement officers exhibit highest price sensitivity due to budget allocation competition with civil registration system modernization, while security applications for intelligence personnel show minimal elasticity.
Supply Chain Analysis
Tariff exposure between European substrate suppliers and Asian personalization equipment manufacturers dominates supply chain risk profiles for security printer vendors. Semiconductor fabrication concentrates in Germany, France, and Taiwan, while polycarbonate lamination equipment draws from German and Chinese automation specialists. Raw material dependencies span optical-grade polycarbonate resin, NFC controller chips, and holographic security foils. Single-source vulnerability in specialized polymer supply creates input cost volatility that propagates through document production timelines. Distribution runs through direct government procurement channels with limited aftermarket service penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-passport market is recovering from pandemic-induced document issuance backlogs as border reopening accelerates replacement cycle compression. Government modernization budgets are expanding to absorb deferred procurement from peak disruption years.
For Market Incumbents: Build algorithmic audit trail capabilities as the defensive moat against EU AI Act enforcement actions. Incumbent security printers should deepen backward integration into semiconductor fabrication to secure NFC controller supply against foundry allocation constraints. Certification investment in quantum-resistant cryptographic modules provides differentiation as NIST post-quantum standards crystallize. Channel control through exclusive personalization equipment leasing arrangements limits competitor access to government production facilities.
For New Entrants and Emerging Players: Underpenetrated African markets offer the most accessible white-space expansion for specialized equipment vendors lacking full-stack integration capabilities. Nigeria, Kenya, and Egypt lack comprehensive biometric travel document infrastructure and present greenfield deployment potential with less entrenched incumbent relationships. Equipment-centric positioning through automation density in polycarbonate inlay embedding competes effectively against integrated security printers. Partnering with Chinese technology licensors for line automation contracts provides a viable go-to-market angle in cost-constrained procurement environments.
For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshape the acquisition landscape toward biometric algorithm specialists with documented training data provenance. Long-term viability over the analysis window favors vendors with demonstrated post-quantum cryptography roadmaps and cloud backend interoperability capabilities. Acquisition target archetypes include production line automation engineers with installed base density in emerging economies. The signal to watch is ICAO compliance deadline acceleration in Southeast Asian markets as visa-waiver program retention pressures compress vendor qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Cryptography Migration | NIST post-quantum algorithm adoption future-proofs document lifecycle compatibility against cryptographic obsolescence. |
| Biometric Algorithm Audit Trail Investment | EU AI Act conformity assessment documentation extends vendor qualification timelines but creates regulatory moats. |
| Polycarbonate Substrate Backward Integration | Captive supply of optical-grade polymer resin mitigates input cost volatility from European chemical supplier concentration. |
| Mobile Verification Architecture Development | NFC-enabled wallet integration aligns with Estonia-Finland-Latvia digital identity platform unbundling trends. |
| African Market Localization Partnership | Jakarta and Surabaya equipment integrator relationships provide template for Nigeria-Kenya-Egypt greenfield deployment. |
Research Approach
Cross-validation between primary interviews with passport authority procurement officers and secondary analysis of ICAO implementation reports anchors the qualitative findings. Conversations with secure printing facility engineers, biometric system integration specialists, and national data protection authority officials informed supply chain risk assessments. Secondary validation drew from ICAO Doc 9303 implementation tracking, EU AI Act regulatory filings, and national immigration department procurement disclosures. Bottom-up document issuance volume modeling and top-down border infrastructure investment aggregation were triangulated against semiconductor foundry capacity disclosures.
Calibration against historical ICAO compliance deadline shifts and polycarbonate substrate price indices shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application security level, end-user category, and regional regulatory cluster. CAGRs were derived from document replacement cycle compression rates and border infrastructure modernization budget trajectories. Industry-specific forecast inputs encompass biometric enrollment capacity expansion timelines and quantum-resistant algorithm standardization progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment integrators or accelerated EU AI Act enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Disk Encryption Software Market
Security Software
Asia Pacific Video Management System Market
Security Software
Online Background Check Market
Security Software
Identity Governance and Administration Market
Security Software
Privileged Identity Management Market
Security Software
Extended Detection and Response Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Content Protection and Watermarking Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Key Management Service Market
Security Software
Decentralized Identity Software Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Geofencing Market
Security Software
Europe Encryption Software Market
Security Software
Broadcast Censorship Solutions Market