
 Mobile Threat Management Security Software Market | 2026-2036
Mobile Threat Management Security Software Market Size, Share, and Industry Trends Forecast 2026-2036
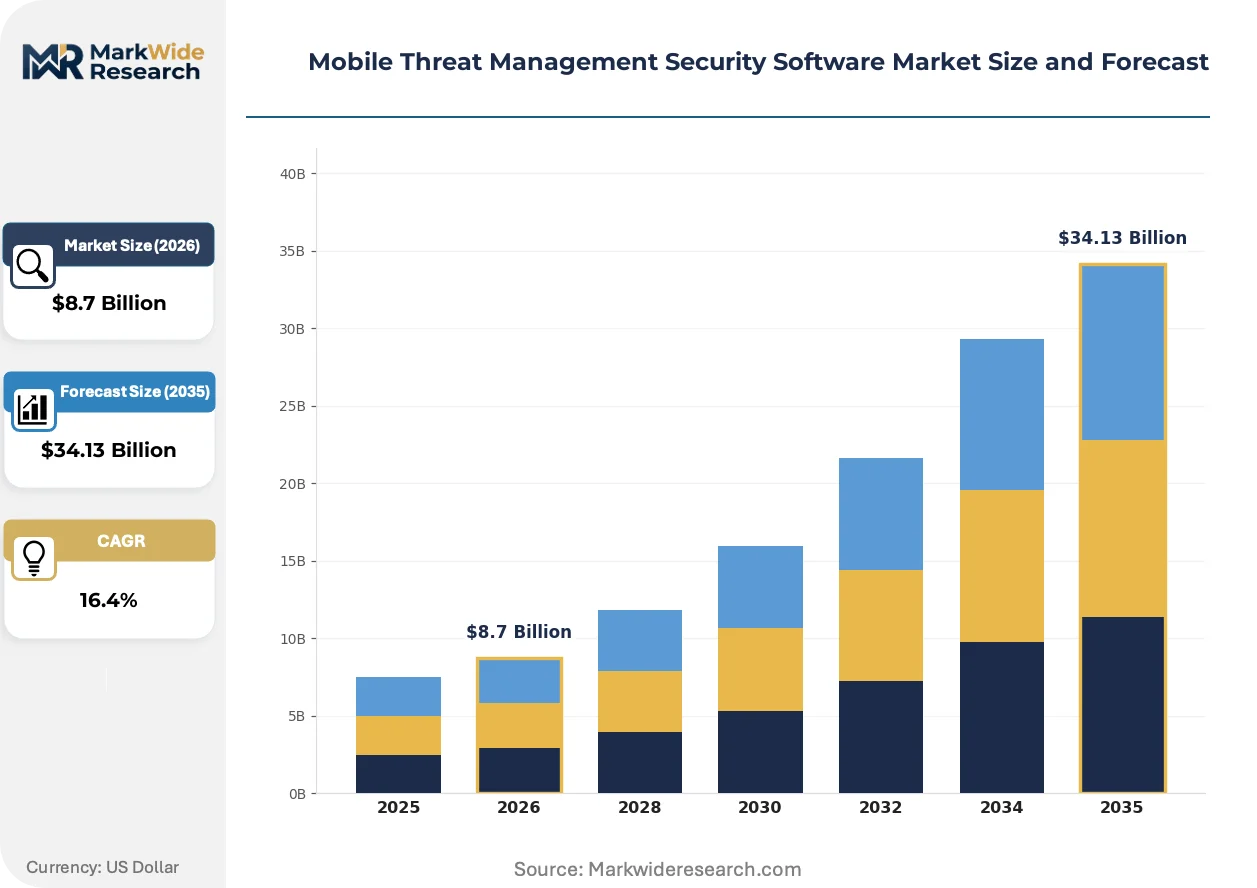
Mobile Threat Management Security Software Market Outlook
Financial services is decoupling from generic enterprise mobility patterns and driving specialized threat management procurement. Palo Alto Networks leverages its cloud-native architecture to capture this shift toward transaction-grade mobile security. Check Point Software Technologies anchors its position through deep integration with banking core systems and regulatory compliance tooling. SentinelOne differentiates via AI-driven behavioral detection on iOS and Android endpoints.
Mobile Threat Management Security Software encompasses endpoint agents, network gateways, and analytics engines that detect malware, phishing, and man-in-the-middle attacks on smartphones and tablets. These systems enforce encryption, application sandboxing, and real-time threat telemetry across iOS, Android, and emerging mobile operating systems. Endpoint Protection dominates current spending as organizations retrofit legacy mobile device management with active threat response. Cloud-Based deployment is expanding fastest among mid-market buyers seeking reduced operational overhead. Security Analytics commands premium pricing where financial services demand forensic-grade audit trails.
The EU AI Act, NIS2 Directive, and GDPR collectively mandate encryption standards, incident reporting timelines, and supply chain security attestations for mobile infrastructure. These frameworks push buyers toward certified platforms and compress vendor qualification cycles. Stakeholders must monitor how fragmentation between EU member state implementation timelines affects procurement urgency and vendor lock-in risk.
Market Dynamics
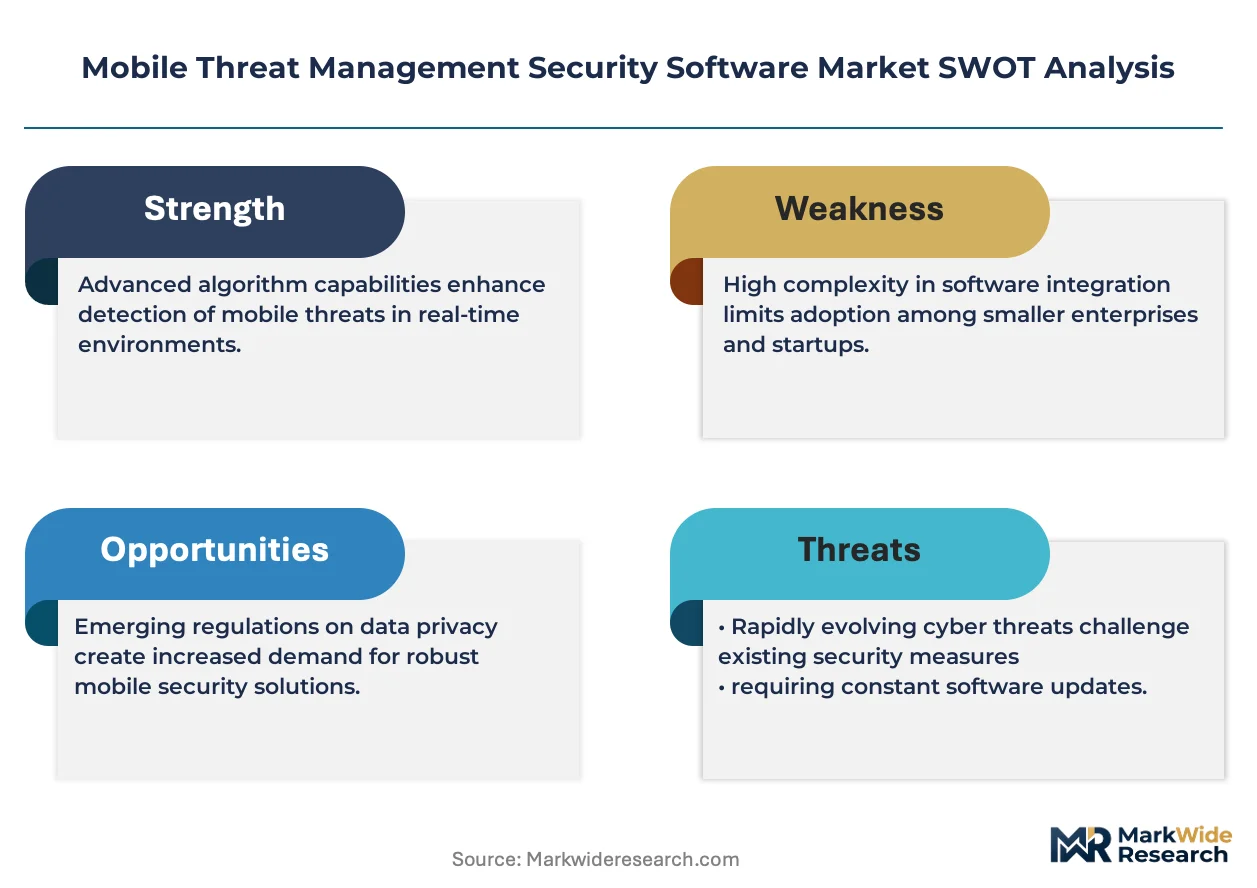
Financial institutions are forcing a structural upgrade from passive mobile device management to active threat defense systems capable of intercepting real-time transaction attacks. This demand pull is compressing vendor qualification cycles and elevating encryption standards across enterprise procurement.
Growth Catalysts
- EU AI Act compliance mandates:The EU AI Act and NIS2 Directive impose binding encryption standards and incident reporting timelines on mobile infrastructure, pushing enterprises toward certified threat management platforms.
- Remote banking transaction surge:Financial services institutions are deploying specialized mobile threat defense to secure high-value payment workflows outside branch networks.
- Behavioral AI detection:Machine learning models trained on device telemetry patterns are enabling zero-day malware identification on iOS and Android endpoints before signature updates.
Market Restraints
- Semiconductor supply concentration:Secure element chip fabrication for hardware-backed mobile encryption concentrates in Taiwan and South Korea, creating single-source vulnerability.
- GDPR forensic data friction:The GDPR's data minimization requirements conflict with security analytics platforms' need for extensive telemetry retention, complicating deployment architecture.
- Legacy MDM substitution threat:Basic mobile device management suites are adding threat detection modules, pressuring standalone MTM pricing at the mid-market tier.
Strategic Opportunities
- India's digital payment expansion:The Reserve Bank of India's push for universal mobile banking is creating demand for localized threat management platforms compliant with domestic data residency rules.
- 5G network slicing convergence:Integration between mobile threat agents and carrier-grade network segmentation is opening enterprise accounts previously served only by telco-managed security.
- Critical infrastructure designation:The EU NIS2 Directive's expansion of regulated entities to include mobile payment processors is mandating MTM deployment across smaller fintechs.
Industry Challenges
- Mobile forensics talent scarcity:Shortage of analysts capable of interpreting iOS and Android threat telemetry is extending deployment timelines and inflating professional services costs.
- Cross-platform integration complexity:Enterprises running mixed Apple and Android fleets face fragmented policy enforcement and inconsistent encryption key management across operating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Threat Management Security Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Protection, Mobile Device Management, Threat Intelligence, Security Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Enterprises, Large Enterprises, Government Agencies, Financial Services Integration Level: API Integration, Standalone Solutions, Third-Party Integration, Custom Solutions |
| Companies Covered | Cisco Systems, Check Point Software Technologies, SentinelOne, Palo Alto Networks, Trend Micro, Kaspersky, Broadcom, Ivanti, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Threat Management Security Software Market Strategic Shifts
Cloud-native security architectures are displacing on-premise mobile threat management deployments, with behavioral detection models replacing signature-based scanning as the primary defense mechanism.
On-device machine learning inference is integrating directly into mobile endpoint agents, enabling real-time phishing detection without cloud latency. Large European banks are piloting these lightweight neural networks for transaction authentication workflows. This architecture is compressing the competitive advantage of cloud-only threat vendors by reducing data egress costs and addressing GDPR data sovereignty concerns.
The EU AI Act's risk-based classification system is mandating algorithmic transparency for security software deployed in financial services. Vendors must now document training data provenance and model decision logic, increasing compliance overhead. German and French regulators are enforcing these documentation requirements earliest, creating a two-speed compliance landscape across member states.
Subscription-based threat intelligence feeds are displacing perpetual license models as the dominant procurement structure. Mid-market enterprises in the United Kingdom and Netherlands are consolidating vendor relationships around platforms offering bundled endpoint protection, analytics, and incident response. This bundling is squeezing standalone analytics providers and elevating platform breadth as the primary selection criterion.
Mobile Threat Management Security Software Market Segmentation
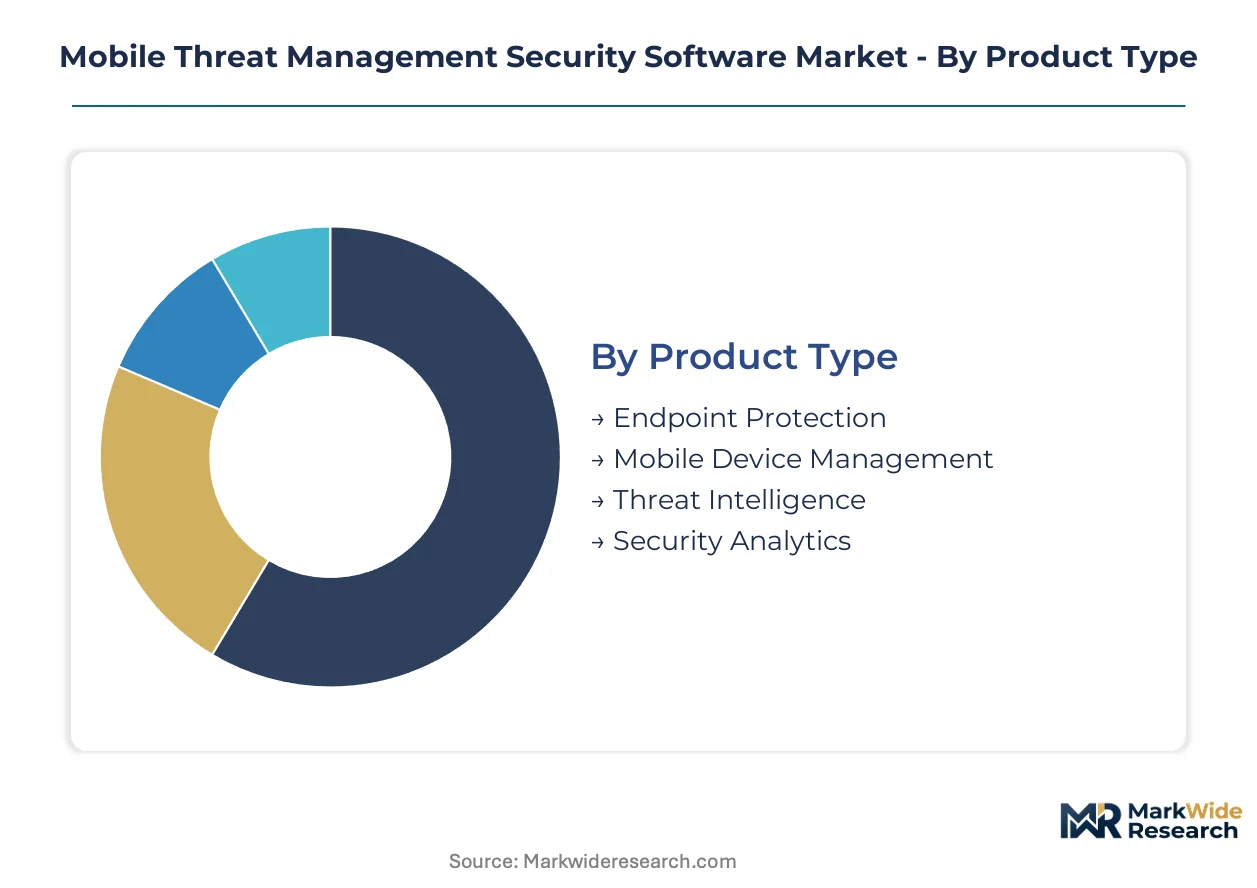
Mobile threat management procurement splits sharply between retrofitting legacy infrastructure and greenfield cloud deployments. Capital allocation patterns differ dramatically across product architectures, with endpoint-heavy solutions demanding sustained hardware investment while intelligence-layer products prioritize recurring data licensing spend.
Product Type:
Endpoint Protection commands the highest upfront capital intensity due to agent development, secure element integration, and cross-platform certification requirements. Threat Intelligence and Security Analytics operate at lower fixed costs but require continuous data acquisition and model retraining infrastructure.
- Endpoint Protection:Software agents deployed directly on iOS and Android devices enforce encryption, application sandboxing, and real-time threat telemetry. German automotive manufacturers and French banking consortia are retrofitting fleet-wide deployments to meet NIS2 Directive baseline requirements. Semiconductor supply constraints for hardware-backed key storage are extending procurement timelines.
- Security Analytics:Forensic-grade audit engines aggregate telemetry across mobile fleets for incident reconstruction and regulatory reporting. Financial services institutions in the United Kingdom are prioritizing these platforms for GDPR-compliant breach documentation. Data minimization mandates create architectural friction against long-term telemetry retention.
- Mobile Device Management:Policy enforcement frameworks controlling device configuration, application distribution, and remote wipe capabilities.
- Threat Intelligence:Subscription feeds delivering indicator-of-compromise updates and attack pattern signatures to endpoint agents.
Endpoint Protection absorbs the bulk of installed capacity; Security Analytics is expanding most quickly.
Deployment Model:
On-Premises deployments concentrate among regulated financial institutions requiring data sovereignty guarantees. Cloud-Based and SaaS models dominate mid-market procurement where operational overhead reduction outweighs customization needs.
- Cloud-Based:Vendor-managed infrastructure delivering elastic compute for threat detection and automated patch distribution. Netherlands-based logistics enterprises are consolidating around these platforms to reduce internal security operations staffing. EU AI Act algorithmic transparency requirements are forcing documentation of training data provenance and model decision logic.
- On-Premises:Self-hosted architectures maintaining complete data control within organizational firewalls. German federal agencies and French critical infrastructure operators mandate these deployments for classified mobile workflows. Capital expenditure concentrates in secure facility construction and dedicated hardware procurement.
- Hybrid:Split architectures processing sensitive data on-premise while leveraging cloud analytics for non-critical telemetry.
- SaaS:Fully managed software subscriptions with minimal client-side infrastructure beyond endpoint agents.
Cloud-Based deployments are climbing the fastest; On-Premises retains the largest committed installed base.
End User:
Financial Services drives the most specialized procurement with transaction-grade security requirements. Large Enterprises spread investment across integrated platforms while Small Enterprises prioritize cost-contained point solutions.
- Financial Services:Banks, payment processors, and fintech platforms requiring real-time interception of transaction-targeting attacks. The EU NIS2 Directive's expansion to mobile payment processors is mandating deployment across smaller fintechs previously exempt from critical infrastructure regulation. Remote banking transaction volumes are compressing vendor qualification cycles.
- Large Enterprises:Multinational corporations operating mixed Apple and Android fleets with fragmented policy enforcement challenges. Cross-platform integration complexity inflates professional services costs and extends deployment timelines.
- Government Agencies:Public sector entities with classified mobile communication requirements and domestic data residency mandates.
- Small Enterprises:Resource-constrained organizations selecting from streamlined threat management bundles with reduced customization.
Financial Services captures the steepest expansion trajectory; Large Enterprises maintain the broadest installed footprint.
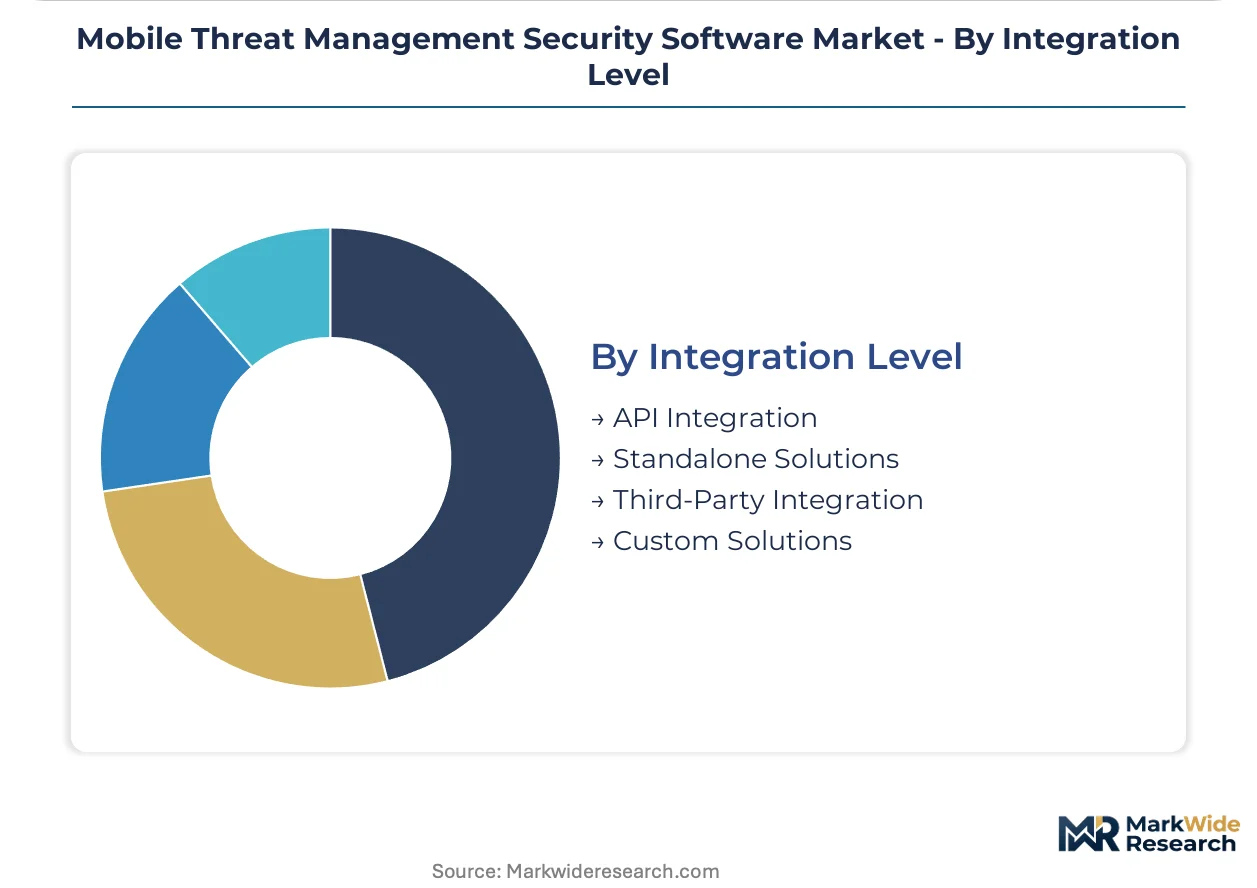
Integration Level:
API Integration and Third-Party Integration dominate procurement as enterprises consolidate around existing security stacks. Standalone Solutions face pricing pressure from bundled platform competition.
- API Integration:Programmatic interfaces embedding mobile threat capabilities into SIEM, SOAR, and identity management platforms. United Kingdom enterprises are prioritizing these connections for unified security operations center visibility.
- Third-Party Integration:Pre-built connectors to major enterprise mobility and endpoint protection suites.
- Standalone Solutions:Self-contained platforms operating without external system dependencies.
- Custom Solutions:Bespoke development for specialized operational technology or proprietary mobile operating systems.
API Integration is gaining share fastest; Third-Party Integration retains the largest deployment base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen Special Economic Zone concentrates mobile security R&D investment through hardware-software integration clusters serving Asia-Pacific financial institutions. German industrial zones anchor European demand for transaction-grade threat defense platforms. Indian fintech corridors drive localized platform development under domestic data residency mandates.
United States
Financial services institutions in New York and San Francisco are retrofitting legacy mobile device management with active threat interception capabilities for remote banking workflows. The SEC and state-level financial regulators mandate encryption standards for mobile payment processors. Silicon Valley cybersecurity clusters concentrate behavioral AI development for iOS and Android endpoint detection.
Germany
Automotive manufacturers in Stuttgart and Munich are deploying fleet-wide endpoint protection to meet NIS2 Directive baseline requirements for connected vehicle ecosystems. The BSI enforces algorithmic transparency documentation under EU AI Act risk classifications for financial services deployments. Frankfurt banking consortia anchor demand for forensic-grade security analytics with GDPR-compliant breach documentation.
United Kingdom
Mid-market enterprises in London and Manchester are consolidating vendor relationships around bundled endpoint protection and incident response platforms. The Financial Conduct Authority tightens mobile infrastructure security expectations for fintech licensing. Edinburgh and Belfast cybersecurity clusters specialize in threat intelligence feeds for European banking networks.
India
The Reserve Bank of India's universal mobile banking push is creating demand for localized threat management platforms with domestic data residency compliance. Mumbai and Bangalore fintech corridors anchor procurement concentration for transaction-grade security. Hyderabad and Chennai IT clusters develop cloud-native endpoint agents for mid-market enterprise adoption.
France
Critical infrastructure operators in Paris and Lyon mandate on-premises mobile threat architectures for classified communication workflows. The ANSSI enforces encryption certification for government and banking mobile deployments. Toulouse aerospace clusters extend threat management requirements to supply chain mobile communications.
Mobile Threat Management Security Software Market Competitive Environment
Top-tier vendors anchor cloud-native platform consolidation, while mid-tier specialists face pricing pressure from bundled security suites. The vendor base stratifies across three archetypes: network security incumbents extending into mobile endpoints, pure-play mobile threat specialists, and endpoint protection platforms adding behavioral detection. Dominant competitive moves include strategic partnerships with banking core system providers and technology licensing for on-device machine learning inference.
Among network security incumbents, Cisco Systems and Palo Alto Networks occupy positions emphasizing cloud-native architecture for financial services transaction workflows. Check Point Software Technologies anchors the banking integration specialist tier through deep compliance tooling relationships. SentinelOne exemplifies the AI-native detection archetype with behavioral models trained on mobile device telemetry patterns. These three vendors represent distinct competitive vectors: infrastructure breadth, regulatory integration depth, and algorithmic detection sophistication respectively.
| Leading Market Players |
|---|
| Cisco Systems |
| Check Point Software Technologies |
| SentinelOne |
| Palo Alto Networks |
| Trend Micro |
| Kaspersky |
| Broadcom |
| Ivanti |
| SAP |
| Others |
Value Chain & Pricing Dynamics
Mobile security engineering talent concentration in Israel and the United States generates labor-cost differentials that widen pricing-tier spreads between premium behavioral-AI platforms and commodity endpoint agents. European procurement teams absorb these spreads through NIS2-mandated certification premiums.
Pricing Analysis
Lead-time-driven pricing stratification rewards certified platforms with immediate deployment availability while discounting spot inventory of legacy MDM modules. Three-tier pricing structure across premium behavioral-AI, standard cloud-native, and economy agent-only levels dominates procurement. Price differentiation stems from EU AI Act algorithmic transparency certification and GDPR-compliant data residency architecture. Pricing pressure stems from legacy MDM vendors bundling threat modules at mid-market tiers. Small fintechs exhibit highest price sensitivity; Frankfurt banking consortia absorb premium tiers for forensic-grade audit trails.
Supply Chain Analysis
Secure element chip fabrication rests on Taiwanese and South Korean semiconductor foundries for hardware-backed mobile encryption. Software agent development draws from Indian and Polish engineering clusters for cost-contained endpoint development. Raw material dependencies center on silicon wafer supply, ARM architecture licensing, and threat intelligence data feeds. Single-source vulnerability in Taiwan semiconductor concentration creates supply chain risk. Distribution runs through direct enterprise sales for financial services and channel partners for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile threat management sector occupies a technology-transition phase where on-device machine learning inference displaces cloud-dependent behavioral detection. This shift compresses data egress costs while satisfying GDPR sovereignty requirements.
For Market Incumbents: Anchor platform consolidation around banking core system integration to defend against pure-play AI-native entrants. Deepen compliance tooling relationships with German BSI and French ANSSI certification pathways. Prioritize backward integration into secure element chip sourcing to mitigate Taiwan concentration risk.
For New Entrants and Emerging Players: Enter via India's domestic data residency corridor where RBI mandates create localized procurement requirements. Target mid-market Netherlands logistics enterprises seeking cloud-native bundles with reduced operational overhead. Deploy API-first architectures for SIEM integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with behavioral-AI specialists given EU AI Act algorithmic transparency mandates. Long-term viability favors platforms with on-device inference capabilities and carrier-grade 5G slicing partnerships. Watch NIS2 Directive implementation timelines across member states as the signal for procurement urgency inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding mobile threat agents into banking core systems satisfies NIS2 baseline requirements. |
| Strategic Partnership | Carrier alliances for 5G network slicing open enterprise accounts beyond telco-managed security. |
| Acquisition of Specialist Firm | Behavioral-AI boutiques accelerate on-device machine learning roadmap for GDPR compliance. |
| Geographic Expansion | Indian fintech corridor entry captures RBI-mandated domestic data residency procurement. |
| Product Launch | Cloud-native SaaS tiers reduce operational overhead for Netherlands mid-market logistics buyers. |
Study Parameters
Multi-period observation of mobile threat deployment timelines and certification completion rates anchored the trend analysis, supplemented by interviews with CISOs at financial institutions, mobile security engineering leads, banking IT procurement officers, and carrier security product managers. Secondary validation drew from SEC filings of network security vendors, EU NIS2 Directive implementation trackers, App Annie mobile security adoption data, and hyperscaler capex disclosures for cloud-native infrastructure. Bottom-up endpoint deployment estimates and top-down security software market sizing were triangulated against regulatory mandate timelines.
Segment-weighting across deployment models, end-user verticals, and integration complexity tiers structured the analytical framework throughout the forecast period. CAGRs were derived from regression analysis of historical endpoint protection spending against regulatory compliance deadlines. Industry-specific inputs included EU AI Act risk classification rollout schedules and Reserve Bank of India mobile banking penetration targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios and GDPR forensic data friction escalations. A small set of triggers warrants ongoing watch: NIS2 Directive enforcement intensity across member states, legacy MDM substitution velocity, and on-device machine learning adoption curves in European banking pilots.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Global Electronic Passports Market
Security Software
SSL Inspection Solution Market
Security Software
Global Data Breach Notification Software Market
Security Software
Private Virtual Communications for Police Network Market
Security Software
Robocall Mitigation Market
Security Software
Global Secure Mobile Communications Software Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Facial Recognition Market
Security Software
Global Network Encryption Market
Security Software
Global Mobile Identification Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
ATM Security Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Hardware Encryption Market