
 Converged Data Center Infrastructure Market | 2026-2036
Converged Data Center Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Converged Data Center Infrastructure Market Analysis
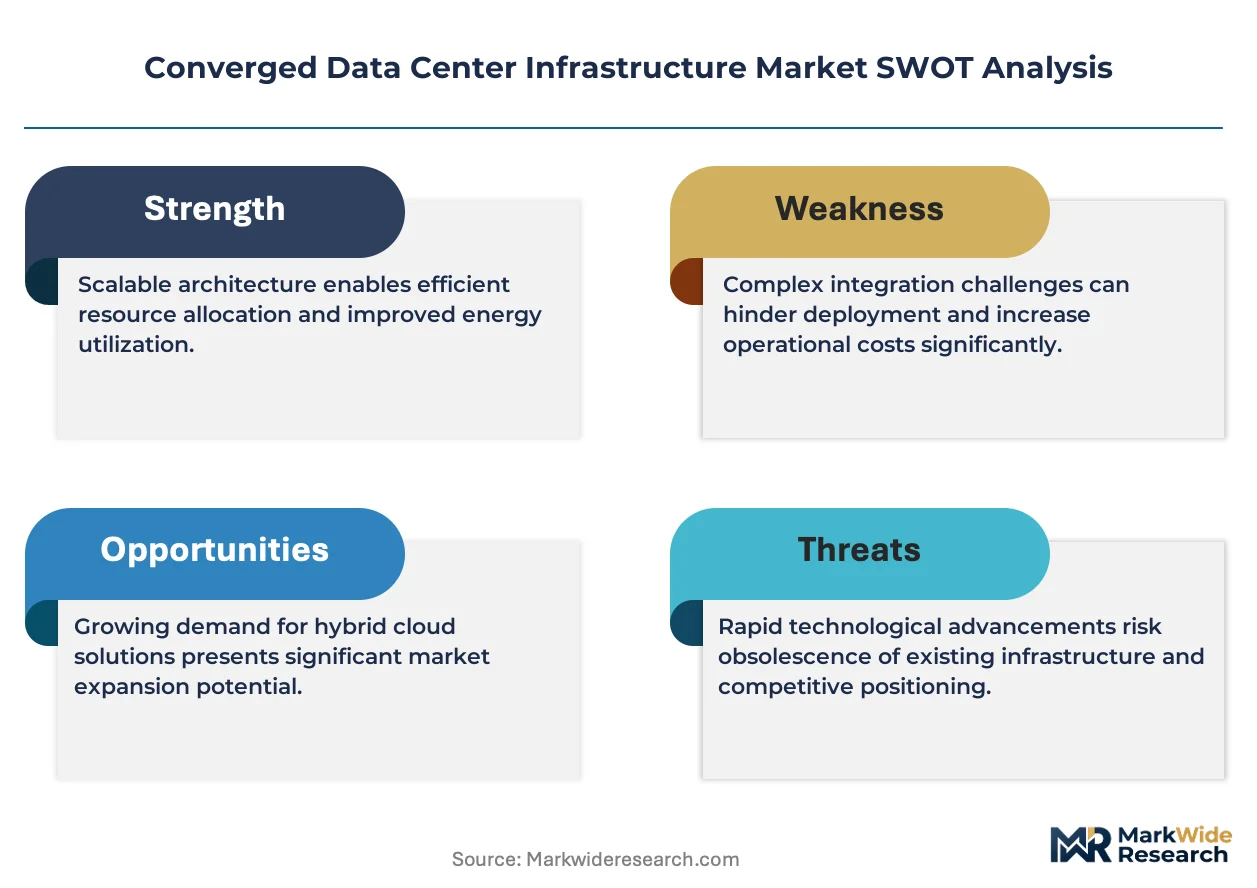
Enterprise-grade redundancy specifications is reorganizing procurement criteria across the converged data center infrastructure landscape. Dell Technologies leverages its server-storage-networking stack to control full-rack integration workflows. Cisco Systems anchors switching and fabric connectivity within hybrid-ready reference architectures. Nutanix specializes in software-defined storage compression that reduces physical rack counts for mid-market deployments.
Converged data center infrastructure unifies compute, storage, and networking resources into pre-validated, factory-integrated systems operating at rack-scale density with sub-1.5 PUE targets; its primary purpose is to eliminate siloed procurement cycles and accelerate workload provisioning for IT organizations managing heterogeneous environments. Hyper-converged infrastructure leads deployment growth by collapsing separate hardware tiers into x86-based nodes with embedded virtualization. Hybrid cloud configurations capture expanding margin pools as enterprises retain sensitive workloads on-premises while bursting analytics to public infrastructure. Disaster recovery applications sustain premium pricing where synchronous replication between converged clusters meets sub-15-minute recovery objectives.
FCC power-density guidelines shape equipment certification for US telecommunications deployments, while EU Energy Efficiency Directive reporting obligations force colocation providers to publish granular PUE metrics that favor converged designs. BIS certification requirements for Indian data center imports add compliance lead times that integrated system vendors navigate through pre-certified chassis configurations. Stakeholders must monitor how national AI sovereignty policies redirect hyperscaler capex toward domestic assembly of converged infrastructure rather than fully built unit imports.
Market Dynamics
Hyperscale cloud operators are consolidating procurement around rack-scale integrated systems, compressing vendor selection cycles from multi-quarter evaluations to single-source frameworks. This concentration is forcing infrastructure OEMs to pre-certify full-stack configurations before customer engagement.
Growth Catalysts
- EU CSRD disclosure mandates:The Corporate Sustainability Reporting Directive requires granular power-usage transparency from colocation providers, accelerating specification of sub-1.5 PUE converged designs.
- Frankfurt Rhine-Main land scarcity:Power constraints and limited real estate availability in Germany's primary data center cluster favor denser converged footprints over traditional three-tier builds.
- AI training workload density:GPU-intensive neural network training is driving demand for liquid-cooled rack-scale systems that unified infrastructure vendors pre-integrate.
Market Restraints
- Memory and GPU supply concentration:Advanced accelerators and HBM modules source from a concentrated East Asian supplier base, creating procurement bottlenecks for converged system assemblers.
- BIS certification timelines:India's Bureau of Indian Standards mandates extended compliance lead times for imported chassis, delaying deployment schedules for integrated rack systems.
- Three-tier legacy substitution:Established compute-storage-network silos retain entrenched operational expertise and sunk capital, slowing displacement by converged alternatives.
Strategic Opportunities
- India domestic assembly incentives:Production-linked incentive schemes for electronics manufacturing attract hyperscaler capex toward local converged infrastructure assembly rather than fully built unit imports.
- Edge AI inference nodes:Distributed machine learning inference at manufacturing facilities and retail locations creates demand for compact converged nodes with embedded GPU acceleration.
- EU Energy Efficiency Directive tailwinds:Mandatory PUE publication requirements for colocation operators favor factory-integrated systems with guaranteed efficiency metrics over custom-built alternatives.
Industry Challenges
- Converged architecture expertise gaps:System integration engineering and software-defined storage optimization skills remain scarce relative to traditional three-tier administration competencies.
- Multi-vendor certification complexity:Synchronous replication configurations spanning heterogeneous converged clusters require extended interoperability testing against sub-15-minute recovery objectives.
- Legacy SAN integration friction:Existing fibre channel storage area networks resist seamless incorporation into software-defined converged stacks without forklift replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converged Data Center Infrastructure Market |
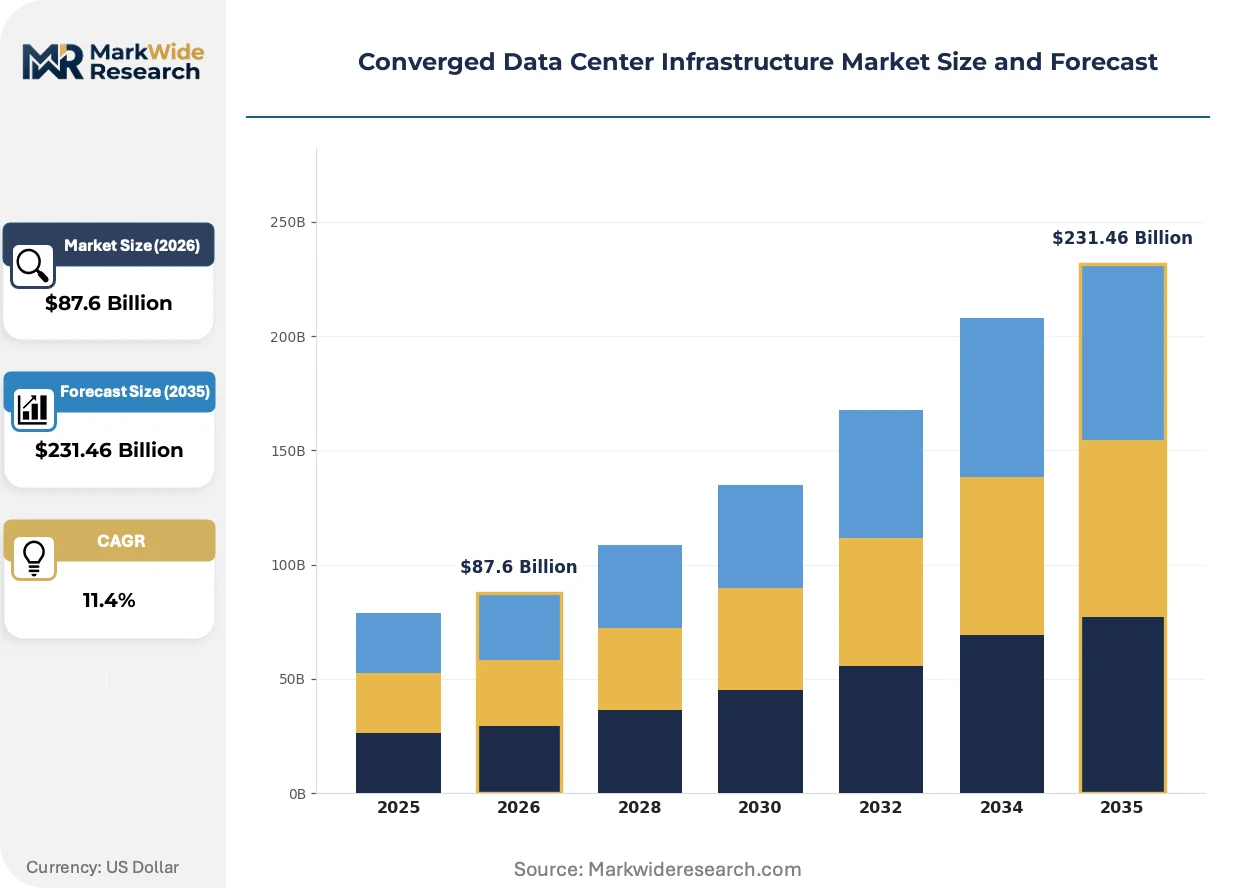
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Hyper-Converged Infrastructure, Converged Infrastructure, Reference Architectures End User: Telecommunications, BFSI, Healthcare, Government Deployment: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud Application: Data Storage, Disaster Recovery, Virtualization, Big Data Analytics |
| Companies Covered | Nutanix, VMware, Dell Technologies, IBM Corporation, Huawei Technologies, Cisco Systems, NetApp, Lenovo Group, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converged Data Center Infrastructure Market Emerging Trajectories
Software-defined disaggregation is dissolving hardware boundaries within rack-scale systems, enabling independent refresh cycles for compute, memory, and storage resources. This architectural shift is compressing capital deployment timelines and altering vendor competitive boundaries.
Composable infrastructure based on CXL memory fabric is supplanting fixed resource allocation in high-performance converged nodes. Financial services and genomics research facilities are adopting these disaggregated pools to match memory capacity to ephemeral workload spikes. The technology is supplanting traditional server-bound DIMM configurations, enabling infrastructure utilization rates previously unattainable with static blade architectures.
The EU Energy Efficiency Directive's granular PUE reporting obligations are compelling colocation operators to specify pre-certified converged systems with guaranteed efficiency envelopes. Facility operators must publish audited power metrics that expose thermal inefficiencies in custom-built alternatives. German and Dutch multi-tenant data centers are responding by mandating factory-integrated liquid cooling loops from approved vendor lists.
Utility-style consumption contracts are displacing capital purchase models for mid-market enterprise deployments. Managed service providers and regional systems integrators are capturing margin pools through subscription-based rack-scale infrastructure with embedded operational support. This financing structure is most visible in Nordic markets where clean energy availability supports long-term power purchase agreements bundled with hardware refresh cycles.
Converged Data Center Infrastructure Market Segmentation
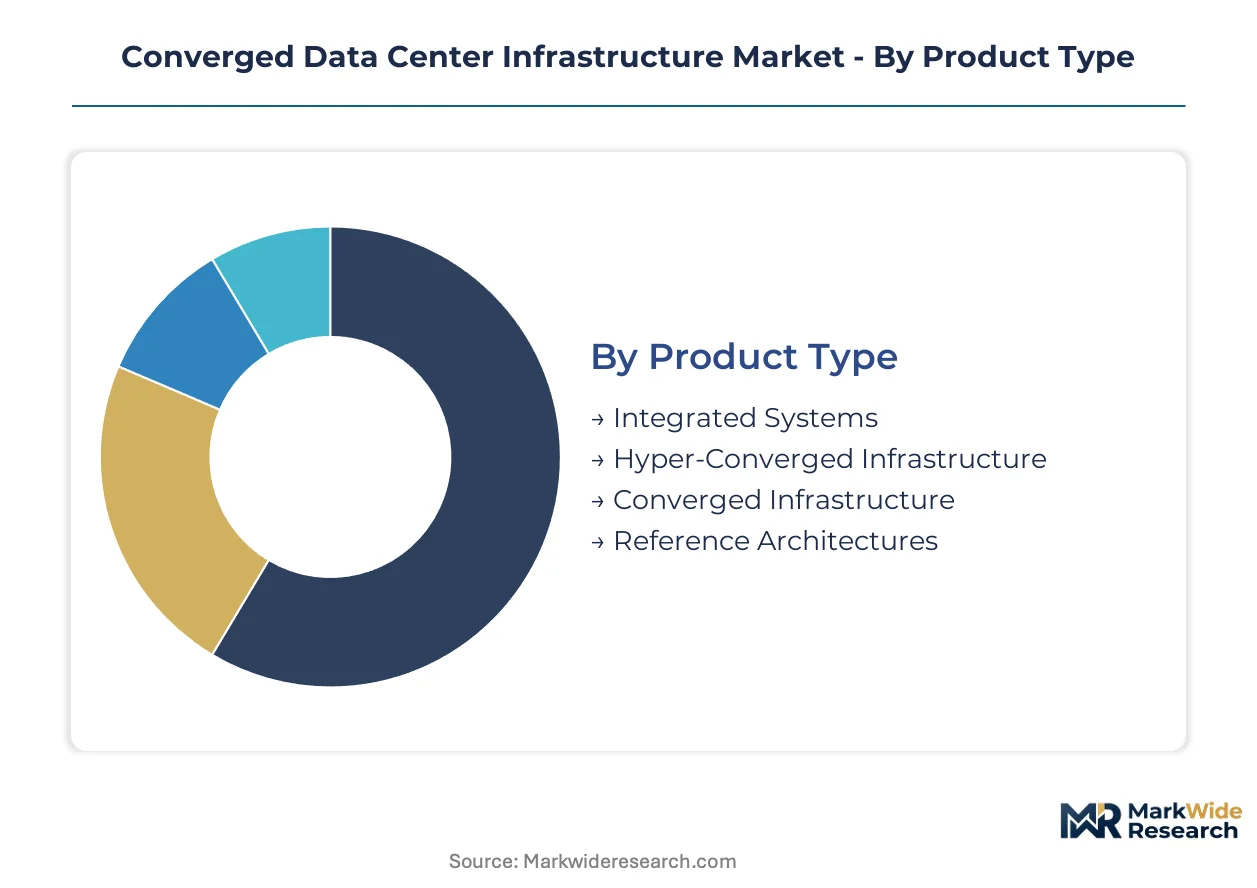
Segmentation in converged data center infrastructure reveals how procurement patterns split between rack-scale integrated systems and software-defined alternatives. Understanding these divisions exposes where vendor consolidation concentrates and where margin pools shift across deployment models.
Product Type:
Domestic assembly incentives in India and Germany's land-scarce Rhine-Main cluster favor locally integrated chassis, while hyper-converged nodes move through global distribution channels serving distributed enterprise footprints.
- Integrated Systems:Factory-assembled compute-storage-networking stacks ship as pre-validated rack units with unified management planes. Demand concentrates in Frankfurt's colocation facilities where EU CSRD disclosure mandates force specification of sub-1.5 PUE guaranteed configurations.
- Hyper-Converged Infrastructure:Collapses separate hardware tiers into x86-based nodes with embedded virtualization and distributed storage. Mid-market deployments across Germany's manufacturing belt drive procurement as facility operators seek denser footprints without three-tier complexity.
- Converged Infrastructure:Pre-validated hardware bundles with separate but coordinated management layers.
- Reference Architectures:Vendor-certified design blueprints guiding custom integration workflows.
Integrated systems command the established base. The steepest expansion runs through hyper-converged infrastructure.
End User:
Cost tier differentiation separates capital-intensive hyperscaler deployments from subscription-managed enterprise arrangements, with regulated verticals absorbing premium pricing for certified configurations.
- Telecommunications:FCC power-density guidelines shape equipment certification for US network operator procurement. Edge AI inference nodes at distributed cell towers create demand for compact converged systems with embedded GPU acceleration.
- BFSI:Financial services institutions adopt composable infrastructure with CXL memory fabric to match ephemeral workload spikes in algorithmic trading and risk modeling. Synchronous replication requirements between converged clusters sustain premium pricing.
- Healthcare:HIPAA compliance drives specification of encrypted-at-rest configurations with audit-ready management planes.
- Government:National AI sovereignty policies redirect capex toward domestic assembly rather than fully built unit imports.
BFSI absorbs the premium tier. Telecommunications provides the volume anchor.
Deployment:
Customer type stratification separates retained sensitive workloads from burst analytics, with hybrid configurations capturing expanding margin pools through bundled operational support.
- On-Premises:Dedicated rack-scale systems serving compliance-bound workloads with captive infrastructure ownership. German multi-tenant data centers mandate factory-integrated liquid cooling loops for these deployments under EU Energy Efficiency Directive obligations.
- Hybrid Cloud:Enterprises retain sensitive workloads on converged infrastructure while bursting analytics to public infrastructure. Nordic markets lead adoption where clean energy availability supports long-term power purchase agreements bundled with hardware refresh cycles.
- Private Cloud:Single-tenant virtualized environments with dedicated resource guarantees.
- Public Cloud:Hyperscaler-managed converged infrastructure delivered as utility-style consumption contracts.
On-premises retains the compliance-bound core. Hybrid cloud gains share fastest through bundled financing structures.
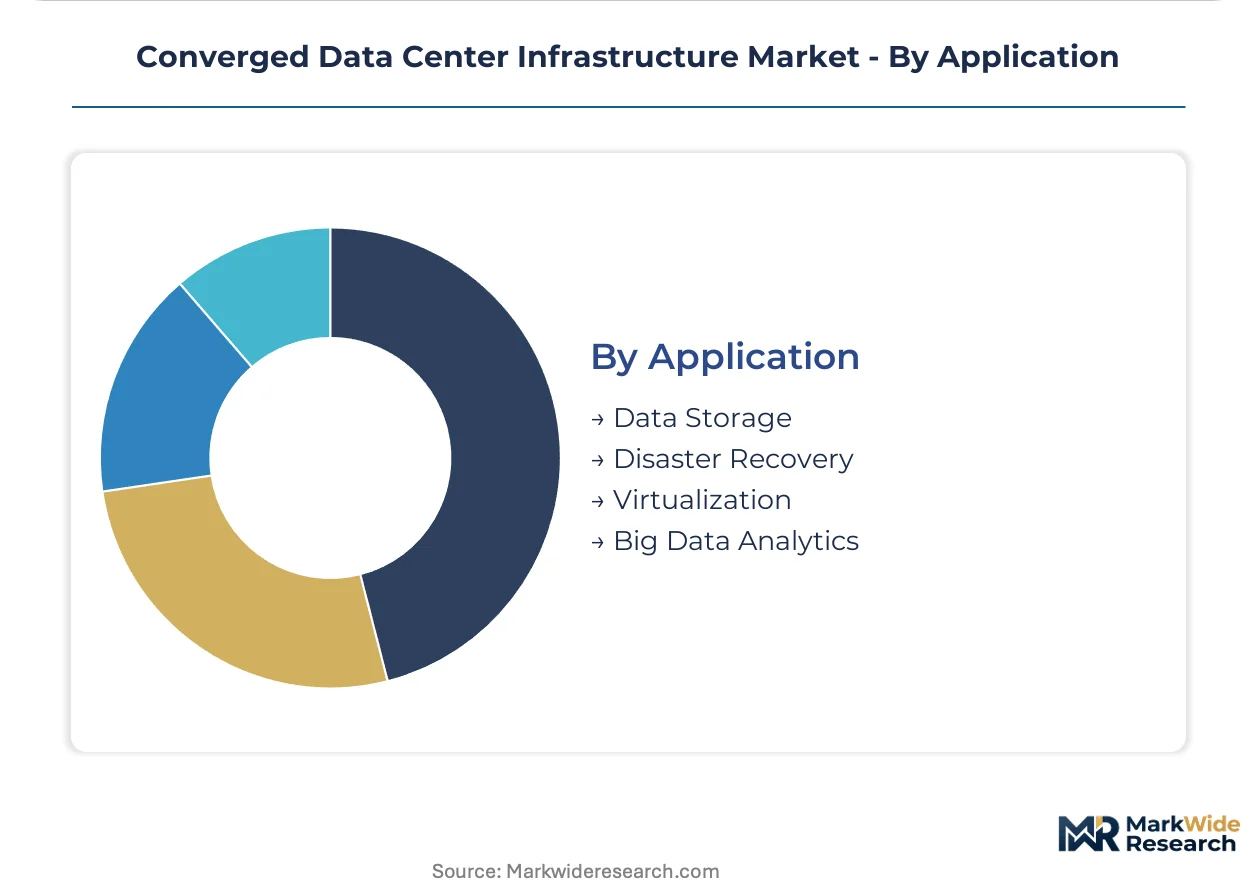
Application:
Supply concentration in memory and GPU sourcing shapes which applications vendors prioritize, with disaster recovery sustaining margins where sub-15-minute recovery objectives require certified synchronous replication.
- Disaster Recovery:Synchronous replication between converged clusters meeting sub-15-minute recovery objectives commands premium pricing. Multi-vendor certification complexity extends interoperability testing timelines, favoring single-source frameworks from pre-certified vendors.
- Big Data Analytics:GPU-intensive neural network training drives demand for liquid-cooled rack-scale systems that unified infrastructure vendors pre-integrate. Memory supply bottlenecks from East Asian HBM manufacturers constrain deployment velocity.
- Data Storage:Software-defined compression reducing physical rack counts for space-constrained facilities.
- Virtualization:Embedded hypervisor layers enabling workload mobility across converged node pools.
Disaster recovery anchors the premium tier. Big data analytics climbs the fastest as AI training density requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accelerator and high-bandwidth memory sourcing clusters in Taiwan, South Korea, and China constrain converged system assembly timelines worldwide. These supply nodes feed rack-scale integration facilities in Germany, the United States, India, and Japan where demand concentrates.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth drive procurement of liquid-cooled rack-scale systems for AI training workloads. FCC power-density guidelines shape equipment certification for telecommunications deployments at distributed cell towers. Enterprise adoption concentrates in Silicon Valley and Seattle where utility-style consumption contracts displace capital purchase models.
Germany
Frankfurt Rhine-Main cluster operators face acute land scarcity and power constraints that favor denser converged footprints over traditional three-tier builds. EU CSRD disclosure mandates force colocation providers to publish granular PUE metrics, accelerating specification of factory-integrated systems with guaranteed efficiency envelopes. Bavarian manufacturing facilities adopt compact hyper-converged nodes to compress physical rack counts.
India
Mumbai and Bengaluru data center operators absorb expanding hyperscaler capex redirected toward domestic assembly under production-linked incentive schemes. BIS certification requirements for imported chassis create compliance lead times that integrated system vendors navigate through pre-certified configurations. Telangana and Maharashtra host emerging rack-scale integration facilities serving South Asian demand.
Japan
Tokyo and Osaka financial services institutions adopt composable infrastructure with CXL memory fabric to match ephemeral workload spikes in algorithmic trading. METI efficiency standards shape procurement criteria for enterprise deployments. Fukuoka and Sapporo edge facilities deploy compact converged nodes with embedded GPU acceleration for distributed AI inference.
United Kingdom
London and Slough colocation operators respond to EU Energy Efficiency Directive-aligned domestic regulations by mandating factory-integrated liquid cooling loops. GDPR compliance drives specification of encrypted-at-rest configurations with audit-ready management planes. Manchester and Edinburgh enterprise deployments favor subscription-based rack-scale infrastructure with embedded operational support.
Converged Data Center Infrastructure Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the converged data center infrastructure landscape. Full-stack integration specialists command premium positioning through unified management planes and pre-validated rack configurations. Software-defined storage pure-plays capture mid-market share by collapsing hardware tiers into x86-based nodes. The market structure rewards backward integration into accelerator sourcing and strategic partnerships with liquid cooling subsystem vendors.
Among full-stack infrastructure vendors, Dell Technologies and Cisco Systems anchor the integrated systems tier with server-storage-networking combinations. Nutanix occupies a position within the software-defined specialist archetype, representing the compression-focused alternative for space-constrained deployments. These three companies exemplify how vendor selection cycles compress from multi-quarter evaluations to single-source frameworks as hyperscale procurement concentrates.
| Leading Market Players |
|---|
| Nutanix |
| VMware |
| Dell Technologies |
| IBM Corporation |
| Huawei Technologies |
| Cisco Systems |
| NetApp |
| Lenovo Group |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Long-term power purchase agreements bundled with hardware refresh cycles lock in both supply access and price visibility for Nordic colocation operators seeking clean energy guarantees. These contracts anchor procurement stability while compressing capital deployment timelines for converged infrastructure deployments.
Pricing Analysis
The EU Energy Efficiency Directive dictates the pricing tier structure across German and Dutch colocation markets, separating factory-integrated liquid-cooled systems with guaranteed sub-1.5 PUE metrics from custom-built alternatives lacking certified efficiency envelopes. Subscription-based consumption models capture mid-market enterprise share in Nordic markets where bundled operational support commands premium positioning. Cost compression in standard-tier rack configurations is intensifying because hyperscaler procurement concentration forces vendors into single-source framework competition. Mid-market manufacturing facilities in Germany exhibit the highest price sensitivity, while Frankfurt Rhine-Main colocation operators absorbing CSRD compliance costs show the least.
Supply Chain Analysis
Taiwan and South Korea anchor advanced accelerator and HBM module fabrication, feeding rack-scale integration facilities in Germany, the United States, and India where demand concentrates. Converged system assemblers draw from concentrated East Asian suppliers for GPU and memory components while sourcing liquid cooling subsystems from specialized vendors. Single-source vulnerability in advanced semiconductor sourcing creates procurement bottlenecks when geopolitical friction disrupts wafer fabrication schedules. Distribution runs through pre-certified chassis configurations that navigate BIS compliance timelines for Indian data center deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The converged data center infrastructure market is accelerating through a regulatory inflection as EU CSRD disclosure mandates and national AI sovereignty policies simultaneously reshape procurement criteria and supply chain geography.
For Market Incumbents: Secure captive supply agreements for GPU and HBM components through backward integration into East Asian semiconductor sourcing. Pre-certify full-stack liquid-cooled configurations before customer engagement to compress vendor selection cycles threatened by hyperscaler single-source frameworks. For New Entrants and Emerging Players: BIS certification fast-tracks for pre-certified chassis configurations unlock Indian data center procurement delayed by import compliance lead times. Target Telangana and Maharashtra rack-scale integration facilities where domestic assembly incentives redirect hyperscaler capex from fully built unit imports. Lead with subscription-based operational support bundles to bypass capital purchase barriers in Nordic mid-market segments. For Investors and Strategic Acquirers: Software-defined storage pure-plays with CXL memory fabric capabilities represent attractive acquisition targets as composable infrastructure displaces fixed resource allocation in financial services and genomics research. Monitor national AI sovereignty policy announcements as the primary signal for capex redirection toward domestic assembly facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GPU Sourcing | Captive supply of NVIDIA and AMD accelerators insulates against East Asian procurement bottlenecks. |
| Pre-Certified Liquid Cooling Integration | Factory-integrated loops from approved vendor lists satisfy EU Energy Efficiency Directive obligations. |
| Domestic Assembly Facility Establishment | Indian PLI schemes attract hyperscaler capex toward local chassis integration rather than imports. |
| Subscription-Based Consumption Contracts | Utility-style financing displaces capital purchase barriers in Nordic clean energy markets. |
| CXL Memory Fabric Platform Development | Composable infrastructure enables utilization rates unattainable with static blade architectures. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with data center facility operators, infrastructure OEM procurement leads, and colocation provider engineering directors; and secondary validation through hyperscaler capex disclosures, EU regulatory filings, and BIS certification databases. Primary fieldwork captured deployment timelines, PUE specification trends, and vendor selection criteria across Frankfurt, Mumbai, and Northern Virginia clusters. Secondary sources included SEC 10-K infrastructure segments, CDSCO import records, and METI efficiency standard documentation. Bottom-up unit economics triangulated against top-down market sizing across product type, deployment model, and end-user vertical dimensions.
Across the analysis window, the forecasting framework modeled segmentation by infrastructure tier, workload sensitivity, cooling architecture, and regional regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle compression rather than extrapolated shipment growth. Industry-specific inputs included GPU supply concentration indices, land scarcity metrics for Frankfurt Rhine-Main, and domestic assembly incentive uptake rates in Indian states.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscaler capex concentration and stable East Asian semiconductor supply; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in national AI sovereignty policies and EU energy disclosure enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market