
 Banking Encryption Software Market | 2026-2036
Banking Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Encryption Software Market Intelligence
Subscription-based delivery of encryption key management is shifting how vendors monetize banking security. Thales Group leverages its hardware security module heritage to anchor enterprise trust in financial data protection. Microsoft Corporation competes through Azure-native encryption services that integrate with core banking platforms. Sophos Ltd. differentiates by specializing in endpoint encryption tailored for branch-bank networks.
Banking encryption software comprises cryptographic applications that protect data at rest, in transit, and in use through algorithms such as AES-256 and TLS 1.3, serving primarily to prevent unauthorized access to financial records and payment instructions. Data encryption solutions lead revenue contribution as transaction volumes surge across digital channels. Cloud-based deployment models represent the fastest-expanding structural category, driven by hybrid infrastructure adoption among mid-tier commercial banks.
US financial institutions navigate FFIEC examination standards alongside state-level data privacy laws that mandate encryption for customer information. The European Banking Authority enforces DORA technical standards requiring end-to-end encryption for critical financial infrastructure. Stakeholders must monitor quantum-resistant algorithm migration timelines and assess how post-cryptographic standards reshape product roadmaps before regulatory deadlines crystallize.
Market Dynamics
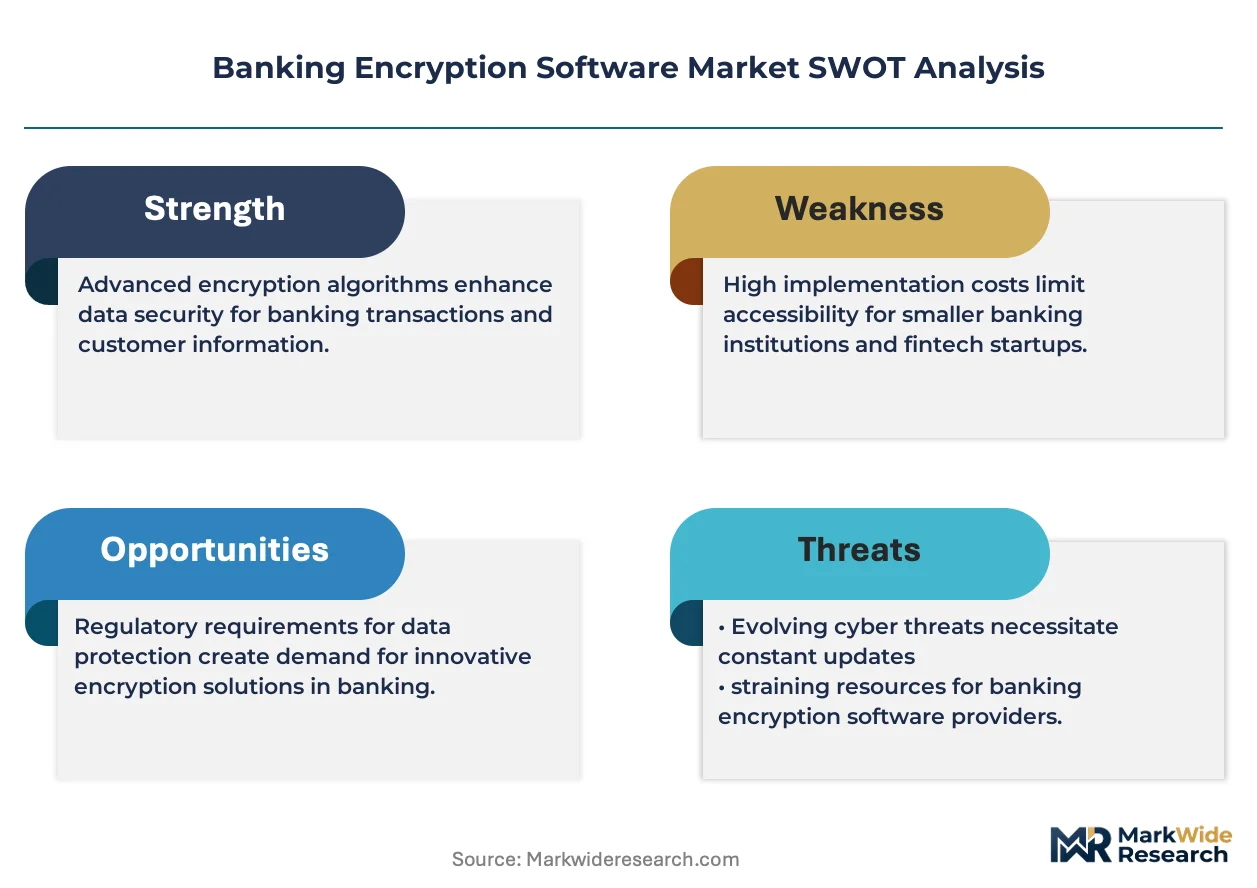
Post-quantum cryptography migration is compressing vendor product roadmaps as commercial banks confront algorithm obsolescence timelines. The shift from hardware security modules to cloud-native key management services is redistributing competitive advantage across infrastructure layers.
Growth Catalysts
- EU Digital Operational Resilience Act:Mandates end-to-end encryption for critical financial infrastructure, compelling European commercial banks to replace legacy cryptographic systems before enforcement deadlines crystallize.
- Cloud-native key management services:Mid-tier commercial banks in the United States are abandoning on-premises hardware security modules for subscription-based encryption orchestration, reducing capital deployment cycles.
- Real-time payment network expansion:FedNow and SEPA Instant Credit Transfer volume growth requires TLS 1.3 and AES-256 encryption at transaction speeds that legacy architectures cannot sustain.
Market Restraints
- Hardware security module supply concentration:Production of FIPS 140-3 Level 3 certified modules concentrates among three European and Asian manufacturers, creating procurement bottlenecks for North American banks.
- Quantum-resistant algorithm patent thickets:NIST post-quantum cryptographic standards are encumbered by overlapping intellectual property claims from academic institutions and defense contractors, complicating licensing.
- Legacy core banking integration costs:COBOL-based transaction processing systems at regional US banks require custom cryptographic middleware that consumes 40-60% of encryption project budgets.
Strategic Opportunities
- Homomorphic encryption for fraud analytics:Convergence of privacy-preserving computation and machine learning enables banks to analyze encrypted transaction patterns without decryption, opening new compliance-automation revenue streams.
- India's digital public infrastructure:The RBI's Account Aggregator framework and UPI expansion create demand for encryption solutions that bridge centralized identity systems with decentralized financial services.
- Confidential computing in hybrid cloud:AMD SEV-SNP and Intel TDX technologies allow banks to process sensitive data in encrypted memory enclaves, reducing regulatory friction for workloads migrating to AWS and Azure.
Industry Challenges
- Post-quantum cryptography talent scarcity:Cryptographic engineering expertise in lattice-based and hash-based algorithms remains concentrated among academic researchers and national laboratory personnel, constraining vendor hiring.
- FIPS 140-3 certification timelines:US commercial banks face 18-24 month validation queues at NIST-accredited laboratories, delaying product launches and freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Encryption Software Market |
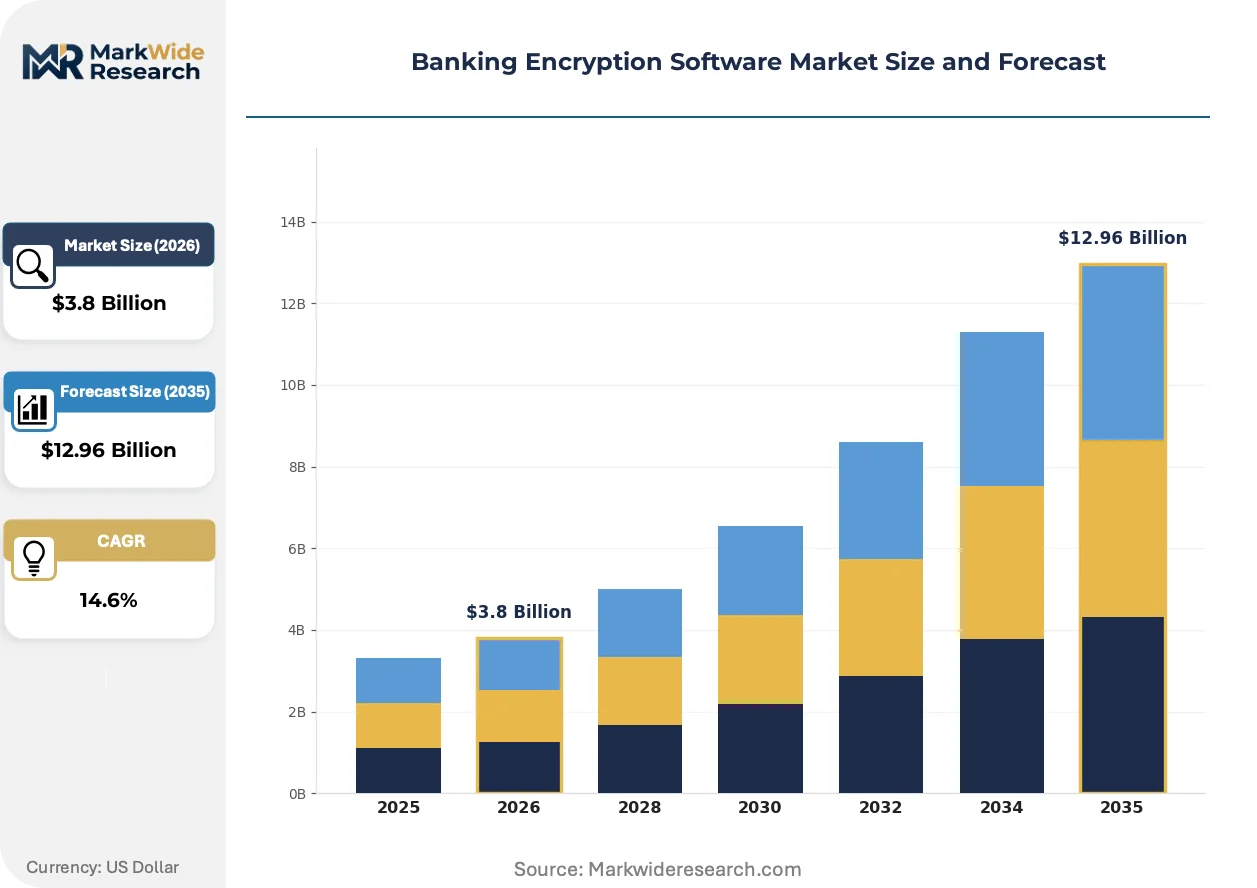
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Encryption, Endpoint Encryption, Network Encryption, Full Disk Encryption Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Commercial Banks, Investment Firms, Credit Unions, Mortgages Technology: AES, RSA, AES-GCM, TLS |
| Companies Covered | IBM Corporation, Microsoft Corporation, Broadcom Inc., Thales Group, McAfee, LLC, Sophos Ltd., Trend Micro Incorporated, Intel Corporation, ESET North America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Encryption Software Market Strategic Shifts & Innovations
Software-defined encryption key lifecycle management is displacing hardware-centric trust architectures across commercial banking infrastructure. This transformation is compressing deployment timelines while elevating the strategic importance of cloud-native cryptographic orchestration platforms.
Confidential computing is overtaking traditional data-at-rest encryption as the primary mechanism for protecting financial analytics workloads. Banks are deploying AMD SEV-SNP and Intel TDX enclaves to process transaction data in encrypted memory states, eliminating decryption exposure during machine learning inference. This architecture is overtaking conventional approaches because it satisfies regulatory requirements for data minimization while enabling cloud migration of previously restricted workloads.
The EU AI Act's risk-based classification system imposes encryption mandates on high-risk financial AI applications, including credit scoring and fraud detection algorithms. Credit institutions must demonstrate that training data and model weights remain encrypted throughout the development lifecycle. German and French commercial banks are responding by embedding hardware security modules directly into MLOps pipelines, creating new procurement categories that bridge AI infrastructure and cryptographic compliance.
Consolidated vendor relationships are displacing point-solution procurement as regional banks seek unified encryption platforms spanning endpoint, network, and cloud workloads. CISOs at US mid-tier institutions are reducing supplier counts from 8-12 specialized vendors to 3-4 integrated platforms, prioritizing vendors with native SOAR and SIEM connectors. This concentration is most visible in the southeastern United States, where mutual bank holding companies are standardizing on single-vendor encryption stacks to simplify FFIEC examination preparation.
Banking Encryption Software Market Segmentation
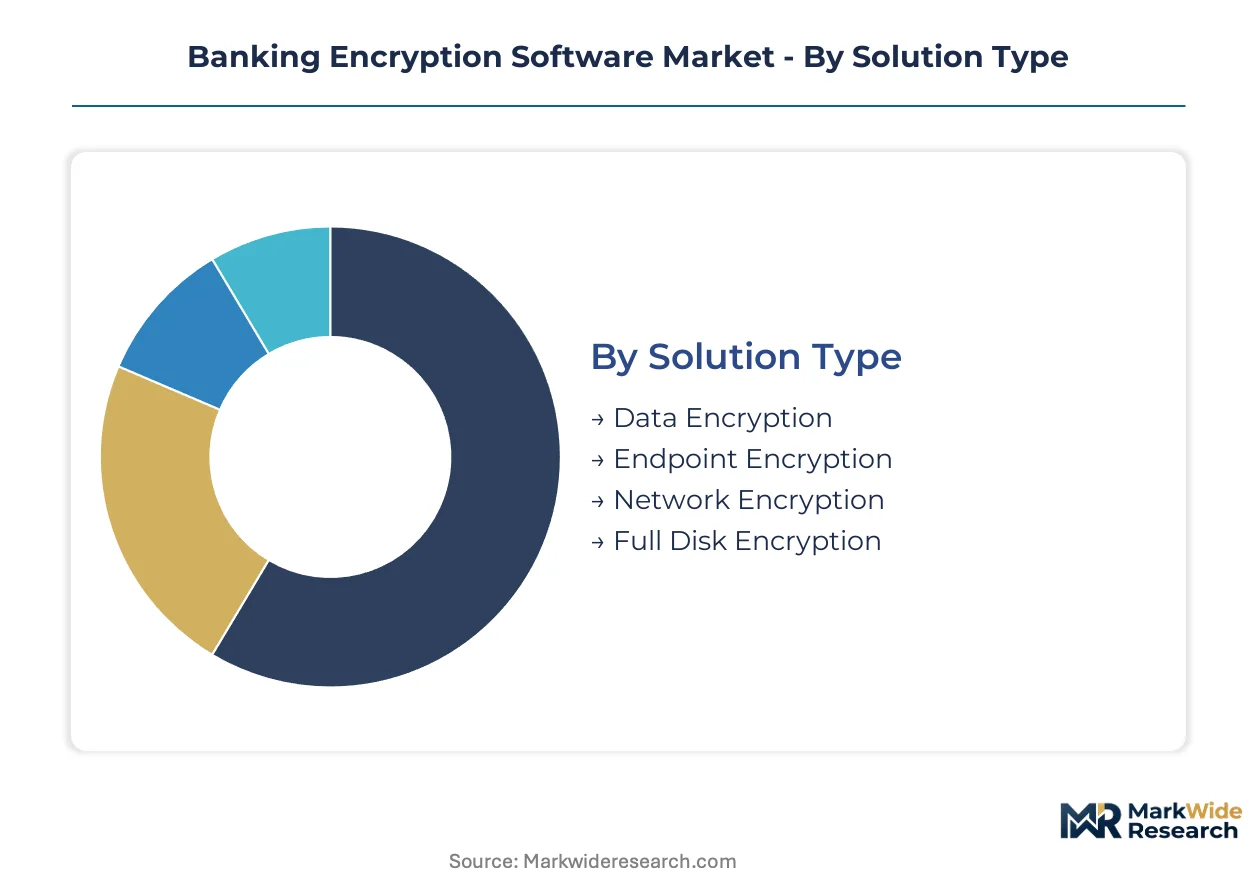
Encryption software segmentation in banking reflects divergent risk appetites across infrastructure layers. Procurement patterns cluster around deployment velocity versus cryptographic control trade-offs.
Solution Type:
Technical sophistication and regulatory exposure define solution selection across bank tiers.
- Data Encryption:Protects structured and unstructured financial records through AES-256 and format-preserving algorithms. Commercial banks in the United States deploy these solutions to satisfy FFIEC examination standards for customer information protection. Demand concentrates where transaction volumes strain legacy cryptographic architectures.
- Endpoint Encryption:Secures branch workstations, mobile banking devices, and executive laptops through full-volume and file-level encryption. Regional bank networks prioritize this segment following FFIEC guidance on endpoint security controls. Procurement accelerates where remote work policies expand device attack surfaces.
- Network Encryption:TLS 1.3 and IPsec implementations for payment rails and interbank communications.
- Full Disk Encryption:Hardware-rooted drive encryption for servers and operational technology systems.
Mature deployment sits with Data Encryption. Newer deployment is concentrated in Endpoint Encryption.
Deployment Model:
Capital efficiency pressures are redistributing procurement toward operational expenditure structures.
- Cloud-Based:Native key management services from AWS, Azure, and Google Cloud eliminate hardware procurement cycles. Mid-tier US commercial banks adopt this model to compress FFIEC examination preparation timelines. Expansion is steepest where core banking modernization programs coincide with datacenter lease expirations.
- Hybrid:Combines on-premises hardware security modules with cloud-native encryption orchestration. Large commercial banks in Germany and France favor this architecture under EBA DORA technical standards requiring operational resilience testing. Adoption concentrates where regulatory deadlines mandate cryptographic system replacement.
- On-Premises:Dedicated hardware security modules and self-managed key lifecycle systems.
- SaaS:Subscription-delivered encryption key management without infrastructure ownership.
Established infrastructure favors On-Premises. Fastest share gains are occurring in Cloud-Based.
End User:
Regulatory scrutiny intensity and transaction complexity shape encryption investment priorities.
- Commercial Banks:Retail and corporate banking operations with high-frequency payment processing. These institutions drive AES-256 and TLS 1.3 deployment across FedNow and SEPA Instant Credit Transfer integrations. Investment concentrates where real-time payment volume growth exposes legacy cryptographic latency.
- Investment Firms:Asset managers and broker-dealers protecting algorithmic trading data and client portfolios. Firms in the United States deploy homomorphic encryption prototypes for privacy-preserving analytics. Demand clusters where SEC cybersecurity disclosure rules elevate encryption to board-level priority.
- Credit Unions:Member-owned financial cooperatives with constrained IT budgets.
- Mortgages:Specialized lenders handling high-value loan origination and servicing data.
Deep encryption maturity resides with Commercial Banks. Steepest expansion trajectory belongs to Investment Firms.
Technology:
Algorithm selection reflects the tension between performance requirements and post-quantum migration timelines.
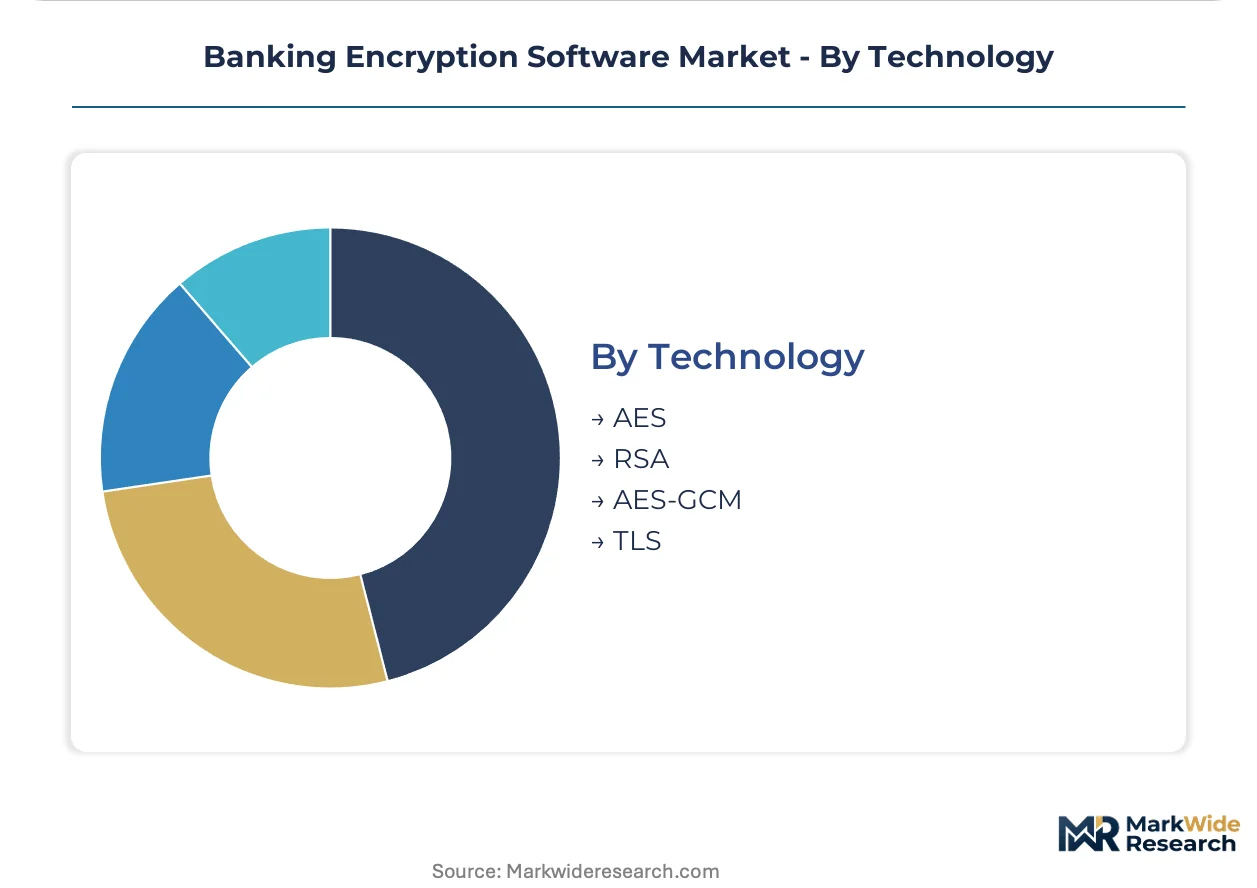
- AES:Symmetric block cipher standardized by NIST for bulk data encryption at rest. AES-256 dominates US commercial bank deployments under FIPS 140-3 validation requirements. Procurement concentrates where quantum-resistant algorithm migration deadlines compress product roadmaps.
- TLS:Transport Layer Security protocols for data in transit across payment networks and API ecosystems. TLS 1.3 adoption accelerates among US regional banks modernizing for FedNow connectivity. Deployment clusters where latency-sensitive transactions demand reduced handshake overhead.
- RSA:Asymmetric encryption for key exchange and digital signatures.
- AES-GCM:Authenticated encryption mode combining confidentiality with integrity verification.
Proven infrastructure relies on AES. Emerging deployment is concentrating in TLS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of banking encryption software concentrates in the United States and Western Europe, while consumption spreads across commercial banking centers in North America, Europe, and Asia-Pacific. Cloud infrastructure providers in the US and Germany generate the core intellectual property, but deployment velocity now depends on regional regulatory deadlines and payment modernization cycles.
United States
Regional banks accelerate FedNow integration and cloud migration, driving demand for TLS 1.3 and AES-256 implementations. The FFIEC examination standards mandate encryption for customer information protection, tightening compliance timelines. New York and Charlotte banking clusters host the densest concentrations of encryption procurement decisions as mutual bank holding companies consolidate vendor relationships.
Germany
Commercial banks under EBA DORA technical standards replace legacy cryptographic systems with hybrid cloud-native architectures. The EU AI Act imposes encryption mandates on high-risk financial AI applications, including credit scoring algorithms. Frankfurt's financial district anchors the largest concentration of hardware security module deployments integrated directly into MLOps pipelines.
United Kingdom
Investment firms deploy homomorphic encryption prototypes for privacy-preserving analytics under SEC-influenced disclosure frameworks. The Financial Conduct Authority's operational resilience requirements parallel DORA implementation timelines. London's fintech corridor concentrates demand for endpoint encryption solutions serving branch-bank networks and remote trading operations.
India
The RBI's Account Aggregator framework and UPI expansion create demand for encryption bridging centralized identity systems with decentralized financial services. India's digital public infrastructure investments accelerate cloud-based key management adoption among mid-tier commercial banks. Mumbai and Bangalore technology clusters host the fastest-growing deployment of software-defined encryption orchestration platforms.
Japan
METI guidelines on financial data protection drive AES-256 adoption across regional banking networks modernizing core infrastructure. Post-quantum cryptography migration timelines compress product roadmaps as institutions confront algorithm obsolescence risks. Tokyo's financial district concentrates procurement of confidential computing technologies for encrypted memory enclave processing.
Banking Encryption Software Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the banking encryption software landscape. Hardware security module manufacturers maintain foundry-like control over cryptographic trust anchors, while cloud-native key management vendors operate asset-light orchestration layers. The market structure fragments across three strategic archetypes: legacy hardware security module incumbents, hyperscale cloud platform providers, and specialized endpoint encryption vendors. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud providers, plus portfolio diversification into post-quantum cryptographic algorithms.
Within the legacy hardware security module tier, Thales Group and Broadcom Inc. exemplify capital-intensive producers anchoring enterprise trust architectures. Microsoft Corporation occupies a position bridging hyperscale cloud infrastructure with native encryption services integrated into core banking platforms. Among specialized endpoint providers, Sophos Ltd. represents the branch-bank network focus that differentiates smaller vendors from integrated platform competitors. These three companies collectively illustrate how competitive positioning now depends on the infrastructure layer where cryptographic control resides.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Broadcom Inc. |
| Thales Group |
| McAfee, LLC |
| Sophos Ltd. |
| Trend Micro Incorporated |
| Intel Corporation |
| ESET North America |
| Others |
Cost & Logistics Intelligence
Cloud-native key management service adoption is redistributing cost structures across the banking encryption software landscape while compressing hardware security module procurement cycles. This shift simultaneously elevates subscription-based pricing models and concentrates supply leverage among hyperscale cloud infrastructure providers.
Pricing Analysis
Margin tightening in hardware security module tiers reflects FIPS 140-3 certification backlog bottlenecks at NIST-accredited laboratories. Three-tier pricing structure across premium, standard, and economy levels separates validated Level 3 modules from uncertified alternatives and open-source implementations. Cost-down pressure on mid-tier commercial banks accelerates because FedNow integration timelines compress procurement windows. Regional US banks exhibit highest price sensitivity due to constrained IT budgets, while investment firms prioritize certification grade over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for cloud-native encryption orchestration platforms, while value-added resellers serve mid-tier commercial bank segments. Hardware security module production concentrates in Germany, France, and Taiwan, with cryptographic semiconductor fabrication anchored in South Korea and the United States. Supply chains draw from specialized silicon foundries, tamper-resistant packaging facilities, and NIST-accredited validation laboratories. Single-source vulnerability in FIPS 140-3 Level 3 certified module supply creates procurement risk for North American banks. Distribution runs through systems integrators with core banking modernization expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FIPS 140-3 validation queue congestion functions as the primary supply constraint, sustaining pricing power for certified hardware security module vendors across the analysis window.
For Market Incumbents: Hedge against cloud-native key management service displacement by embedding hardware security modules directly into MLOps pipelines for EU AI Act compliance. Acquire post-quantum cryptography engineering talent from academic research institutions before NIST standardization deadlines crystallize. Expand capacity in Germany to capture EBA DORA technical standard replacement cycles.
For New Entrants and Emerging Players: Capture white-space opportunity in India's Account Aggregator framework encryption bridging centralized identity systems with decentralized UPI services. Target mid-tier US commercial banks abandoning on-premises hardware security modules for subscription-based orchestration. Pursue partnership-first go-to-market angle with AWS and Azure marketplace listings.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by hyperscale cloud providers seeking cryptographic trust anchor capabilities. Long-term viability favors vendors with lattice-based algorithm patent portfolios and confidential computing enclave integration expertise. Watch NIST post-quantum cryptographic standard finalization as inflection indicator for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Patent Acquisition | Lattice-based algorithm portfolios secure licensing revenue streams before NIST standardization crystallizes. |
| Confidential Computing Enclave Integration | AMD SEV-SNP and Intel TDX embedding enables cloud migration of previously restricted financial analytics workloads. |
| EU DORA Compliance Certification | End-to-end encryption validation opens procurement channels at European commercial banks facing replacement deadlines. |
| FedNow Payment Rail Integration | TLS 1.3 optimization for real-time transaction speeds captures regional bank modernization budgets. |
| Homomorphic Encryption R&D Partnership | Privacy-preserving computation development creates fraud analytics revenue streams without decryption exposure. |
Research Approach
Document review covered SEC filings from encryption software vendors, NIST cryptographic standard publications, and EBA DORA technical implementation guidelines, complemented by interviews with bank CISOs, cloud platform engineers, and hardware security module procurement leads. Primary fieldwork included discussions with FFIEC examination specialists and EU AI Act compliance officers. Secondary validation drew from FIPS 140-3 certification databases, FedNow deployment tracking, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market construction.
Cross-referencing historical adoption curves with panel input from commercial bank technology executives anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, bank tier by asset size, regulatory jurisdiction cluster, and payment network integration status. CAGRs derived from algorithmic obsolescence timelines and compliance deadline clustering. Industry-specific forecast inputs incorporated FedNow volume trajectories and SEPA Instant Credit Transfer expansion patterns.
The model holds under stable NIST certification throughput and unaltered DORA enforcement schedules; deviation in post-quantum cryptography standard finalization or hardware security module supply disruption would shift vendor competitive positioning. Forecasts reflect base-case assumptions regarding cloud migration velocity and regional regulatory harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Internet Filter Software Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Global Password Management Software Market
Security Software
Saudi Arabia Managed Security Services Market
Security Software
Automotive Over-the-Air Cybersecurity Hardening Test Equipment Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Disk Encryption Software Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Antivirus Software Market
Security Software
Mass Notification System Market
Security Software
E Passport Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
Software Assurance Market