
 Privacy Management Software Market | 2026-2036
Privacy Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Privacy Management Software Market Intelligence
The bundling of discrete privacy functions into unified platforms is consolidating buyer choice around comprehensive solutions. This trend favors vendors offering integrated suites covering data discovery, consent, and risk assessment. OneTrust leverages its extensive feature set to capture large enterprise accounts. TrustArc specializes in deep compliance and certification workflows, while Securiti differentiates through its data-centric security and automation capabilities.
Privacy management software automates the operational workflows required for compliance with data protection regulations. These systems execute functions such as processing data subject access requests (DSARs) and maintaining auditable records of data processing activities. Cloud-based deployment models dominate due to their scalability and lower upfront costs. Within solution types, consent management serves as a foundational component, while the financial services sector remains a primary end user due to stringent data handling requirements.
A complex web of regulations underpins the market's structure. Frameworks like Europe's GDPR, Brazil's LGPD, and state-level laws in the United States such as the CCPA create non-negotiable requirements for data handling. These mandates impose significant financial penalties for non-compliance, directly compelling investment in automation tools. Vendor selection will increasingly hinge on a platform's ability to adapt to this evolving and fragmented regulatory landscape.
Market Dynamics
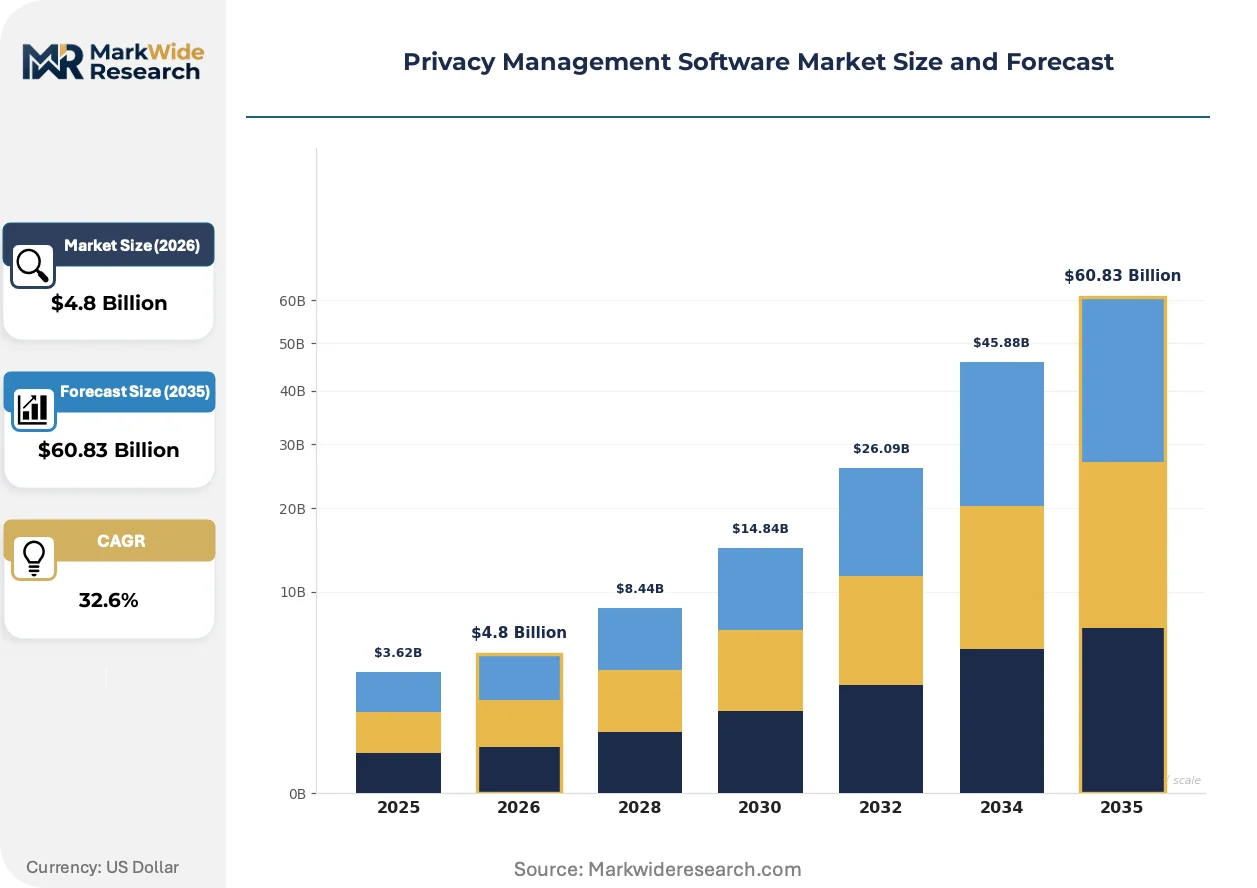
The proliferation of stringent and often conflicting data privacy regulations across jurisdictions represents the central force shaping the market. Mandates like Europe's GDPR and state-level laws in the United States create a complex, high-stakes compliance environment, compelling enterprise investment in automated software.
Growth Catalysts
- Regulatory Mandates:The enactment of comprehensive data protection laws, such as Brazil's Lei Geral de Proteção de Dados (LGPD), creates immediate, non-negotiable demand for tools that can automate compliance and generate auditable records of data processing activities.
- Financial Services Adoption:The financial services industry, facing severe penalties for data breaches and strict data handling rules, is a primary adopter, using these platforms to manage customer data, consent, and cross-border data transfer requirements.
- Data Discovery Technology:Advances in automated data discovery and classification technologies are a key enabler, allowing organizations to find and map personal data across disparate systems, which is a foundational step for any privacy program.
Market Restraints
- High Total Cost of Ownership:Beyond initial licensing fees, the total cost of ownership, which includes complex implementation, integration with legacy systems, and the need for specialized staff to operate the software, can be a significant barrier for many organizations.
- Integration Complexity:The technical difficulty of integrating privacy management platforms with a wide array of existing enterprise applications, databases, and cloud services creates significant deployment friction and can delay time-to-value.
- Regulatory Fragmentation:The constantly evolving and fragmented landscape of privacy laws, with new regulations emerging at state and national levels, creates uncertainty and requires continuous platform updates, increasing complexity for both vendors and users.
Strategic Opportunities
- Emerging Geographies:Markets in Asia-Pacific, including India and Japan, represent significant growth opportunities as they develop and implement their own national data protection frameworks, creating new demand for localized compliance solutions.
- AI Governance:The application of privacy management principles to artificial intelligence development offers a new frontier, with tools needed to manage data inputs for machine learning models and ensure compliance with emerging regulations like the EU AI Act.
- Security and Privacy Convergence:Integrating privacy management functions with broader data security and governance platforms presents a major opportunity, allowing vendors to offer a single, unified solution for managing data risk, security, and compliance.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with hybrid expertise in privacy law, information technology, and data management hinders the effective deployment and operation of sophisticated privacy management software within enterprises.
- Vendor Lock-In:High switching costs associated with deeply embedding a specific vendor's platform into core business and compliance workflows create significant vendor lock-in, limiting an organization's flexibility to adapt to new technologies or pricing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Privacy Management Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $60.83 Billion |
| CAGR (2026 – 2036) | 32.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Data Discovery, Consent Management, Risk Assessment, Compliance Automation, Incident Management End User Industry: Financial Services, Telecommunications, Manufacturing, Education, Government Pricing Model: Subscription, Perpetual License, Freemium, Usage-Based |
| Companies Covered | Transcend, OvalEdge, OneTrust, Enzuzo, Osano, TrustArc, Sprinto, Feroot Security, Securiti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Privacy Management Software Market Strategic Shifts & Innovations
The market is shifting from reactive, checklist-driven compliance to proactive, automated data intelligence. This evolution favors platforms that not only manage consent but also provide deep, continuous insight into data lineage, risk, and cross-system data flows, fundamentally changing how organizations approach privacy.
AI-powered data discovery and classification is a transformative technology that automates the mapping of sensitive personal information. Large enterprises, particularly in the healthcare and financial services sectors, are rapidly adopting these automated tools. This automated intelligence is overtaking manual, survey-based data mapping exercises, providing a more accurate and dynamic view of data risk across the organization.
The California Privacy Rights Act (CPRA) expands upon the original CCPA, introducing stricter rules for sensitive personal information and extending privacy rights to employee data. This regulatory enhancement forces businesses to upgrade their data subject request and consent management systems to cover a wider scope of data types and individuals. The technology and retail sectors in the United States are most affected, prompting investment in more granular platform controls.
A notable behavioral shift sees enterprise buyers consolidating their spending away from disparate point solutions for individual privacy tasks. Instead, organizations are standardizing on integrated privacy management platforms that cover the entire compliance lifecycle, from data discovery to breach notification. This trend is most visible in North America and Europe, where regulatory maturity favors comprehensive, auditable systems over a patchwork of disconnected tools.
Privacy Management Software Market Segmentation
Effective segmentation clarifies the diverse requirements driving investment in privacy management software. Distinct deployment preferences, solution functionalities, and end-user demands shape vendor offerings. Understanding these categories is essential for strategic market positioning.
Deployment:
The supply of privacy management software is concentrating around flexible deployment models that cater to varying organizational infrastructure and security postures.
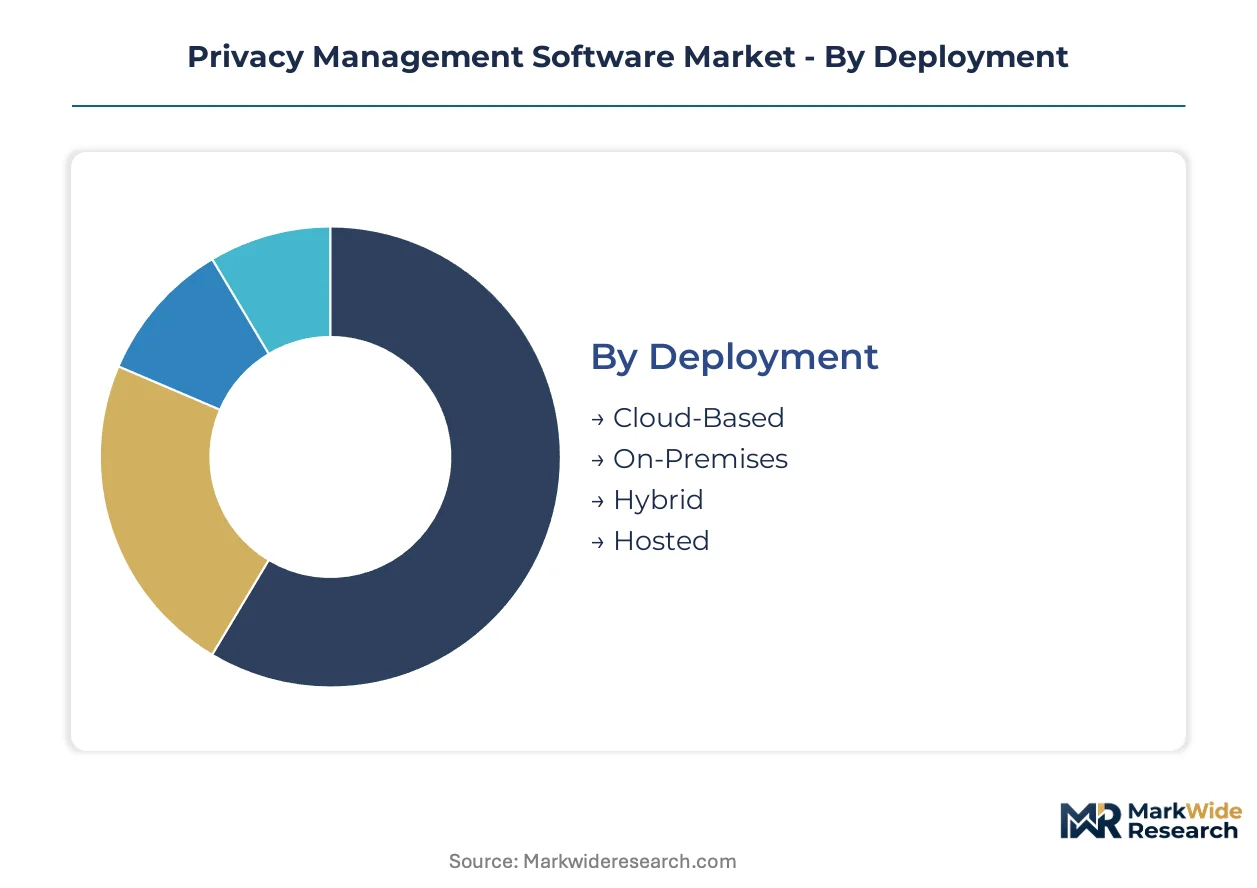
- Cloud-Based:Cloud-based platforms deliver privacy management as a service, hosted and maintained by the vendor. This model sees strong demand from enterprises seeking scalability and reduced IT overhead, particularly for global compliance initiatives.
- On-Premises:On-premises solutions involve software installed directly on an organization's internal servers and infrastructure. Financial services and government entities often prefer this model for enhanced data control and adherence to strict regulatory requirements.
- Hybrid:Hybrid deployments combine elements of both cloud and on-premises environments, offering flexibility for sensitive data.
- Hosted:Hosted solutions are managed by a third party but often reside on dedicated infrastructure, providing a balance of control and outsourced management.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
Application-specific functionalities define the utility of privacy management platforms, addressing distinct facets of data protection and compliance workflows.
- Consent Management:Consent management modules automate the collection, tracking, and enforcement of individual data preferences and permissions. Demand is high across all sectors, driven by regulations like GDPR and CCPA, requiring explicit user consent for data processing.
- Data Discovery:Data discovery tools automatically identify, classify, and map personal data across an organization's disparate IT systems. Large enterprises in healthcare and financial services leverage these for foundational privacy program development and risk assessment.
- Risk Assessment:Risk assessment solutions evaluate data processing activities for privacy risks, helping organizations prioritize mitigation efforts.
- Compliance Automation:Compliance automation streamlines regulatory reporting and policy enforcement, reducing manual effort for legal and privacy teams.
- Incident Management:Incident management platforms facilitate the rapid response and reporting of data breaches, minimizing regulatory penalties and reputational damage.
Data Discovery is gaining share fastest, driven by the increasing complexity of data environments.
End User Industry:
Customer type significantly influences the specific privacy management features prioritized, reflecting varied regulatory pressures and data sensitivity.
- Financial Services:Financial services firms handle vast amounts of sensitive personal and transactional data, necessitating robust privacy management. Strict regulations from bodies like the SEC and GDPR compel significant investment in these platforms for data governance and breach prevention.
- Telecommunications:Telecommunications providers manage extensive customer data and call detail records, facing unique challenges in data retention and lawful interception. Regulations like Europe's ePrivacy Directive shape their demand for secure data handling and consent mechanisms.
- Manufacturing:Manufacturing companies utilize privacy software for managing employee data and intellectual property, complying with global data transfer rules.
- Education:Educational institutions manage student and staff records, requiring privacy solutions for FERPA compliance in the United States and similar global mandates.
- Government:Government agencies implement privacy software to protect citizen data, adhering to public sector regulations and national security protocols.
The Financial Services sector generates the highest demand for advanced privacy management capabilities.
Pricing Model:
Cost tier differentiation is evident across pricing models, reflecting vendor strategies for market penetration and value capture.
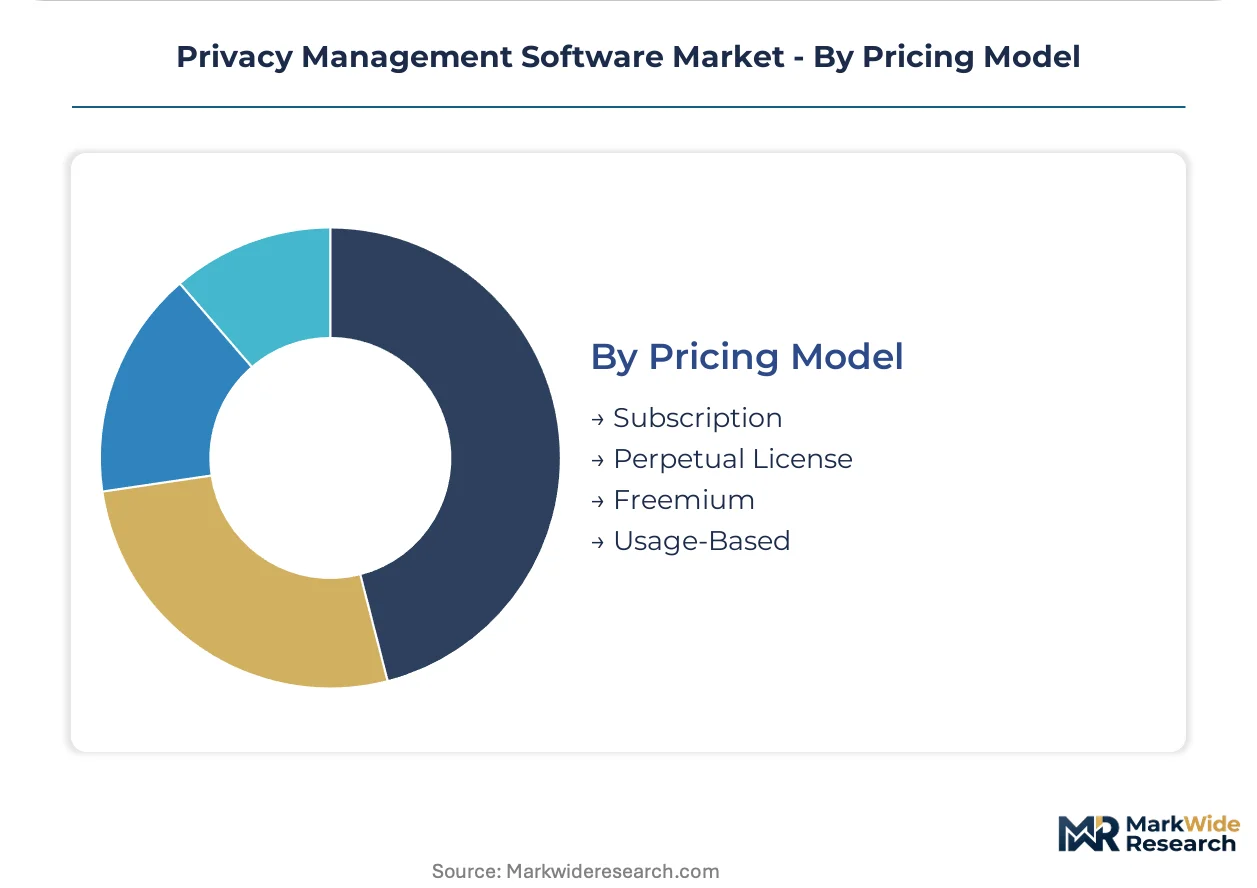
- Subscription:Subscription models offer access to software and updates for a recurring fee, typically monthly or annually. This model appeals to most organizations due to predictable costs and continuous feature enhancements, driving widespread adoption across industries.
- Perpetual License:Perpetual licenses involve a one-time upfront payment for indefinite software use, often with separate fees for maintenance and support. Larger enterprises with stable IT budgets sometimes prefer this model for long-term cost control and ownership.
- Freemium:Freemium models provide basic privacy features at no cost, with advanced functionalities available through paid upgrades.
- Usage-Based:Usage-based pricing charges customers according to their actual consumption of resources or specific features, suitable for variable data processing needs.
Subscription models represent the dominant preference for privacy management software acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for privacy management software initially scaled in regions with early, stringent data protection laws. Europe's GDPR and early US state-level privacy initiatives established foundational demand. These regulations compelled enterprises to invest in tools for automated compliance.
United States
Demand for privacy management platforms stems from a complex patchwork of state-level laws, including the CCPA and CPRA. HIPAA mandates specific data handling for healthcare organizations. Technology hubs like Silicon Valley and Seattle drive adoption, particularly for cloud-based solutions managing consumer data. Financial services firms in New York City also invest significantly.
Germany
Compliance with the GDPR significantly shapes the German privacy management market. The Federal Data Protection Act (BDSG) refines national data protection requirements. Industrial powerhouses in Bavaria and Baden-Württemberg adopt advanced software for managing employee and customer data, ensuring adherence to strict European standards. Data discovery tools are highly valued here.
Japan
Japan's Act on the Protection of Personal Information (APPI) drives investment in robust privacy solutions. The country's strong manufacturing and automotive sectors require sophisticated tools for data lifecycle management. Tokyo's financial district and Osaka's industrial clusters prioritize platforms ensuring secure data transfer and consent management for international operations.
Brazil
The Lei Geral de Proteção de Dados (LGPD) created substantial demand for privacy management software across Brazil. Financial institutions and telecommunications providers are primary adopters due to stringent data handling requirements. São Paulo and Rio de Janeiro, as major economic centers, see concentrated adoption of compliance automation and incident management platforms.
India
India's Digital Personal Data Protection Act (DPDPA) is catalyzing significant demand for privacy management tools. The country's booming IT and business process outsourcing sectors require platforms for managing vast datasets. Technology centers in Bengaluru and Hyderabad are rapidly implementing consent management and data discovery solutions to meet new regulatory mandates.
Privacy Management Software Market Key Industry Players
Premium-margin players sit above commodity-margin players across solution depth and integration capabilities. The privacy management software market exhibits a tiered structure, with established vendors offering comprehensive suites alongside specialized challengers focused on specific compliance niches. Strategic archetypes include integrated platform providers, deep compliance specialists, and data security-focused innovators. Vendors are pursuing strategic partnerships to expand ecosystem reach and engaging in portfolio diversification to address evolving regulatory needs.
Integrated platform providers, such as OneTrust, represent a comprehensive approach to privacy management, offering broad feature sets for large enterprises seeking unified solutions. TrustArc occupies a position as a deep compliance and certification specialist, serving organizations with complex regulatory requirements and requiring detailed workflow management. Securiti exemplifies innovation through its data-centric security and automation capabilities, often targeting businesses seeking advanced AI-driven privacy solutions and proactive risk assessment. These firms collectively anchor the market's capabilities across varying scales and compliance needs, reflecting the diverse strategic priorities of privacy management buyers.
| Leading Market Players |
|---|
| Transcend |
| OvalEdge |
| OneTrust |
| Enzuzo |
| Osano |
| TrustArc |
| Sprinto |
| Feroot Security |
| Securiti |
| Others |
Cost & Logistics Intelligence
Venture-capital-backed software developers and private-equity-rolled-up specialists influence aggressive pricing strategies within the privacy management software market, shaping both supply behavior and market consolidation. This financing pattern often prioritizes rapid market share acquisition over long-term margin stability.
Pricing Analysis
Subscription models dominate privacy management software acquisition, offering predictable costs and continuous feature enhancements to organizations. Price differentiation stems from the breadth of platform functionalities, such as advanced data discovery versus basic consent management, and the scale of the enterprise deployment. Pricing pressure originates from intense competition among vendors and buyer consolidation towards comprehensive, integrated solutions. Large enterprises facing stringent regulatory mandates are less price-sensitive for mission-critical compliance tools.
Supply Chain Analysis
Direct sales teams and channel partners distribute privacy management software across global markets. Supply concentration for core development talent exists in technology hubs including the United States, Europe, and India. Key raw material dependencies involve access to skilled software engineers and reliable cloud infrastructure services. Regulatory fragmentation across jurisdictions presents a structural risk, necessitating continuous platform adaptation and localization. This complexity impacts vendor resource allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The privacy management software market functions as a regulatory compounder, with initiatives like Europe's GDPR continuously expanding demand for compliance automation across industries.
For Market Incumbents:Anchor existing enterprise accounts by deepening platform integration with broader IT ecosystems and expanding feature sets for emerging AI governance requirements. Consolidate market share through strategic acquisitions of niche specialists to counter point solution threats. Invest in R&D for predictive analytics capabilities to stay ahead of evolving regulatory changes, mitigating risk from new compliance frameworks. Expand geographic reach into high-growth Asia-Pacific markets.
For New Entrants and Emerging Players:A significant price-point gap exists between premium enterprise solutions and more basic small-to-medium business offerings. Target small-to-medium enterprises with streamlined, cloud-native platforms focusing on core consent management and data discovery functionalities. Go-to-market through freemium models and strategic channel partnerships with managed IT service providers. Specialize in localized compliance solutions for emerging geographies like India, addressing specific DPDPA requirements.
For Investors and Strategic Acquirers:Valuations sit cheapest among smaller, specialized point solution providers lacking comprehensive integration capabilities. Long-term viability favors platforms demonstrating robust adaptability to evolving global privacy laws and new AI governance requirements. Target acquisition archetypes include data security-focused innovators with strong automation intellectual property. The signal to watch is the successful integration of privacy management functions with broader cybersecurity and data governance platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-powered data lineage tools | Automates critical data mapping, reducing manual effort for enterprises. |
| Platform integration with security suites | Unifies data risk management, offering a single pane of glass for compliance. |
| Strategic partnerships with cloud providers | Embeds privacy by design into foundational infrastructure services. |
| Acquisition of a niche AI governance startup | Expands capabilities into an emerging, high-value regulatory domain. |
| Geographic expansion into Asia-Pacific | Captures new demand driven by developing national data protection frameworks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary data validation. Industry stakeholders included privacy officers, chief technology officers, legal compliance leads, and IT procurement managers. Secondary sources comprised regulatory filings, government reports, technology vendor whitepapers, and financial disclosures. Bottom-up market sizing was triangulated with top-down revenue estimations.
Segment weighting applied across deployment models, solution types, end-user industries, and regional regulatory maturity. The analytical framework projected market evolution over the projection horizon. Compound annual growth rates were derived from historical trends, adoption rates, and anticipated regulatory impacts. Forecast inputs included new privacy legislation announcements and enterprise IT spending projections.
Caveats apply where unforeseen geopolitical events or rapid technological shifts could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement and enterprise investment priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Vsaas Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Europe Smart Doorbell Market
Security Software
Asia-Pacific Extended Detection and Response Market
Security Software
Privileged Access Management (PAM) Market
Security Software
Global Advanced Authentication Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Decentralized Identity Software Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Biometric POS Terminals Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Data Privacy Software Market
Security Software
Mobile Identity Management Market
Security Software
Battery-Powered Doorbell Camera Market