
 Video Door Phones Market | 2026-2036
Video Door Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Video Door Phones Market Analysis
GDPR's data-processing mandates for video capture is decoupling low-cost Asian manufacturers from European distribution channels. Aiphone Corporation leverages in-house camera module production to sustain margin control across Japanese and European markets. Honeywell International Inc. anchors its position through building-automation integration, while Ring LLC competes aggressively on cloud-storage subscription attach rates in North American retail.
Video door phones combine audio-visual capture, visitor verification, and remote access control into a single entry-management device, typically operating on two-wire analog or Power-over-Ethernet IP architectures with resolution thresholds starting at 720p. The primary commercial purpose centers on security screening and access logging for multi-unit dwellings, commercial offices, and gated industrial facilities. Smartphone-integrated systems now command the fastest expansion within product type segmentation as renters and homeowners prioritize off-premise visitor management. IP-based technology segments carry the steepest growth trajectory, though analog installations retain dominance in cost-sensitive retrofit projects across developing economies. Within end-user segmentation, hospitality deployments generate premium margin pools due to property-management system integration requirements and recurring software licensing.
The EU AI Act imposes algorithmic transparency requirements on facial-recognition features, while FCC Part 15 governs radio-frequency emissions for Wi-Fi enabled units sold in the United States. India's BIS certification mandates safety testing for electrical components in wired intercom systems, creating compliance delays for new market entrants. Stakeholders must decide whether to absorb certification costs across multiple regulatory regimes or narrow geographic focus to capture faster payback in less regulated jurisdictions.
Market Dynamics
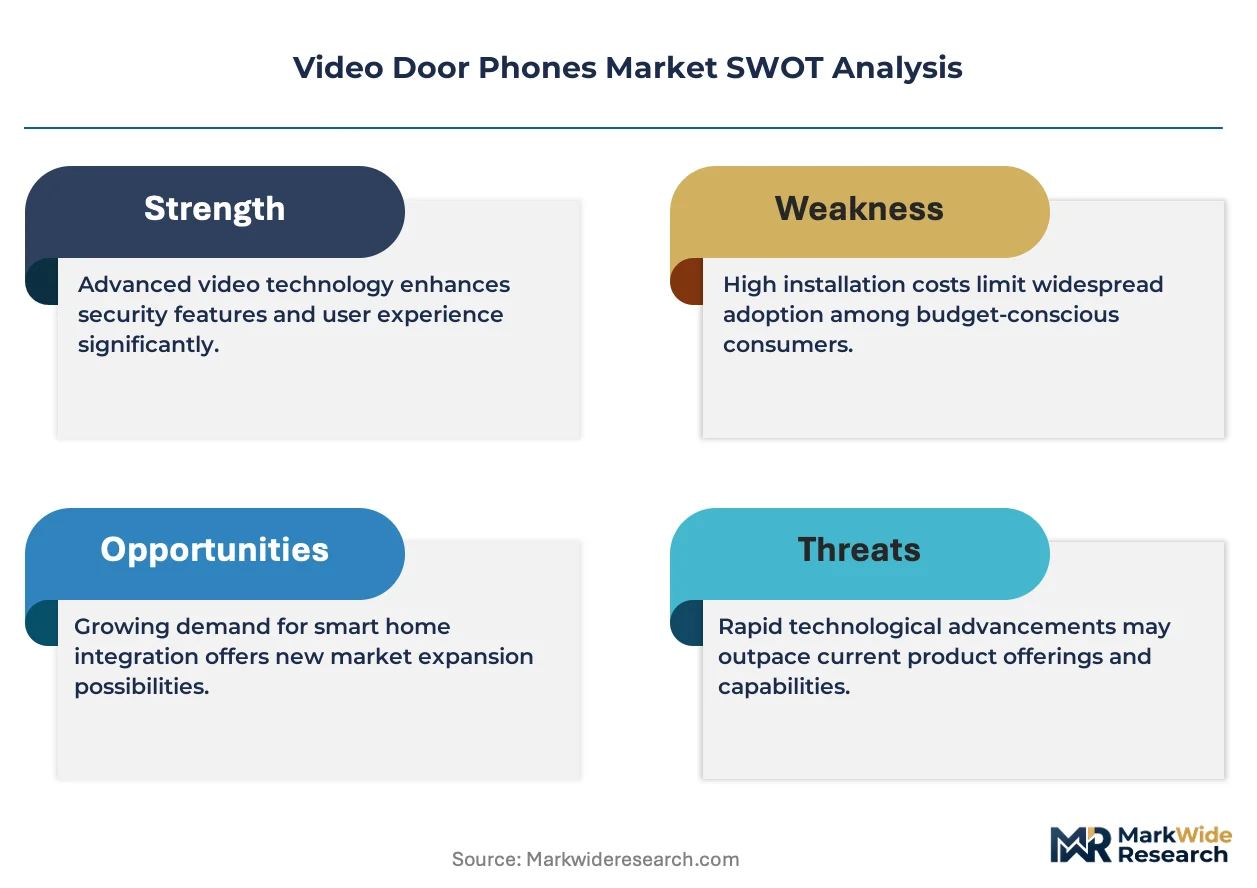
The Video Door Phones Market is experiencing structural pressure from regulatory fragmentation as the EU AI Act and GDPR impose divergent compliance burdens on facial-recognition and data-capture features, forcing manufacturers to engineer region-specific firmware variants rather than unified global platforms.
Growth Catalysts
- EU Cyber Resilience Act:Mandated encryption baselines for connected home devices are accelerating replacement cycles in European residential complexes, creating pull-through demand for IP-based entry systems with hardware-level security modules.
- Smartphone-native renters:Vietnam's urban condominium developments are procuring visitor-management systems with off-premise mobile access as standard amenity, compressing sales cycles for cloud-integrated hardware.
- Power-over-Ethernet architecture:Single-cable installation is reducing retrofit labor costs in Southeast Asian multi-unit dwellings, expanding addressable market beyond new construction.
Market Restraints
- Image sensor cost volatility:CMOS module pricing fluctuations constrain margin predictability for camera-integrated units, particularly affecting mid-tier product lines.
- Certification timeline friction:India's BIS electrical safety testing creates 4-6 month market entry delays, advantaging incumbent suppliers with established compliance infrastructure.
- Legacy analog substitution:Two-wire intercom systems retain installed-base dominance in cost-sensitive retrofit projects across developing economies, compressing IP upgrade velocity.
Strategic Opportunities
- Property-management system convergence:Hospitality verticals generate premium attach rates through integrated guest-access workflows and recurring software licensing.
- Cloud-storage subscription models:North American retail channels are capturing recurring revenue streams through video archival services, shifting hardware margin pressure to services.
- Algorithmic transparency tooling:EU AI Act compliance creates white space for explainable-AI middleware that documents facial-recognition decision logic for audit trails.
Industry Challenges
- Multi-regime firmware engineering:Product teams must maintain parallel codebases to satisfy FCC Part 15 radio-frequency emissions, GDPR data-localization, and BIS electrical safety within single hardware SKUs.
- Integration complexity with building automation:Honeywell and competing building-management protocols require bespoke API development for seamless elevator and access-control handoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Door Phones Market |
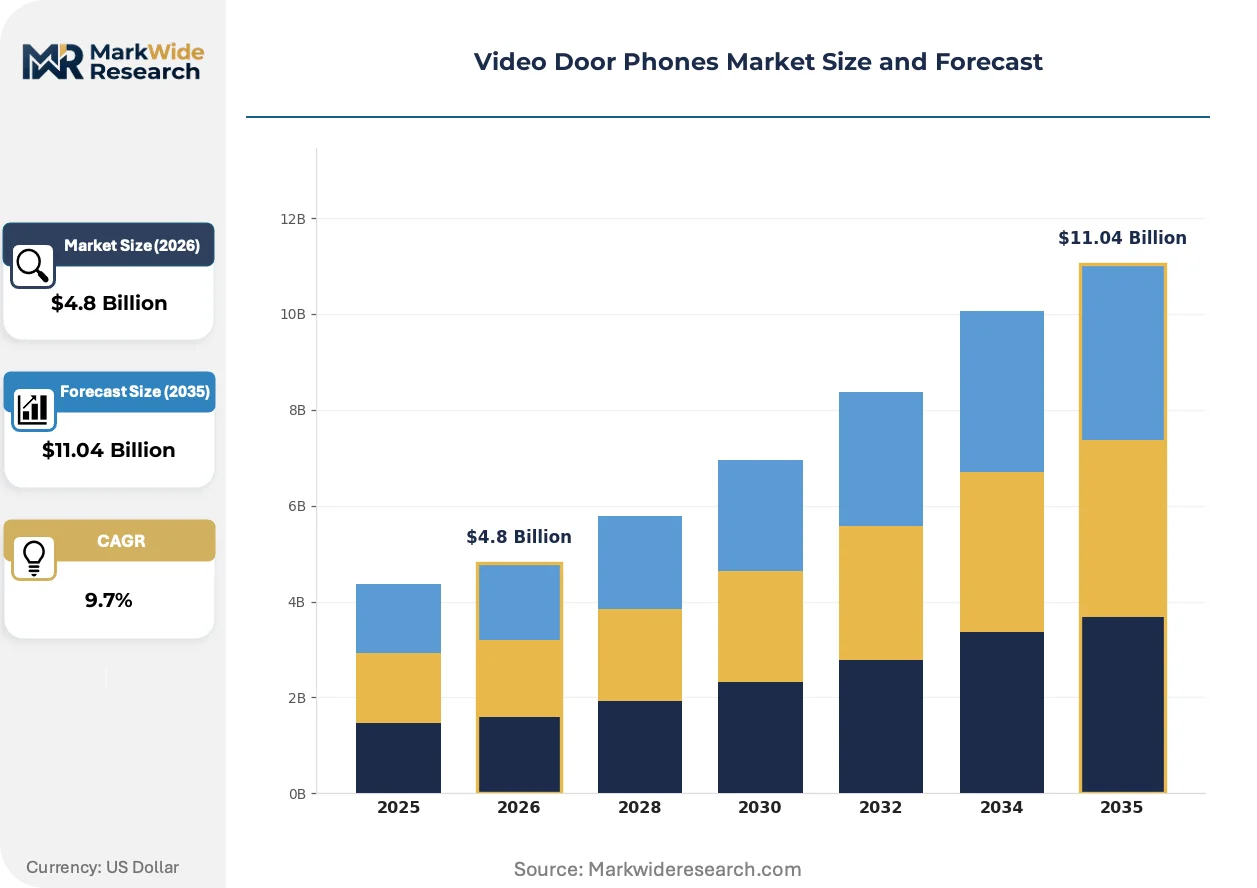
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Smartphone-integrated, Intercom-enabled Technology: Analog, IP-based, Wi-Fi enabled, Smart Home Compatible End User: Residential, Commercial, Hospitality, Industrial Features: Video Recording, Night Vision, Motion Detection, Two-way Audio |
| Companies Covered | Aiphone Corporation, VTech Holdings Limited, Panasonic Holdings Corporation, KOCOM Co. Ltd., Commax Co. Ltd., Honeywell International Inc., Fermax Global SL, Ring LLC, Legrand SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Door Phones Market Emerging Trajectories
Edge-computing architectures and on-device inference are displacing cloud-dependent processing for latency-sensitive visitor verification, while regulatory pressure on biometric data is fragmenting product roadmaps across jurisdictions.
On-device facial-recognition inference is rewriting competitive requirements for entry-system processors. Japanese and European security integrators are specifying NPU-equipped chipsets for sub-200ms identification latency. This capability compression is eliminating second-tier suppliers lacking semiconductor partnerships.
GDPR's data-processing mandates for video capture are decoupling low-cost Asian manufacturers from European distribution channels. Hardware vendors must now certify data-residency architectures and encryption key management. Residential and small-commercial segments in Germany and France are experiencing supplier-base contraction as compliance costs filter downstream.
Renter-dominated urban housing is compressing hardware ownership models toward landlord-provisioned services. Property managers in Vietnam and Thailand are bundling video door phone access into lease agreements, displacing retail purchase channels. This shift concentrates procurement decision-making with real-estate developers and facility-management firms rather than individual occupants.
Video Door Phones Market Segmentation
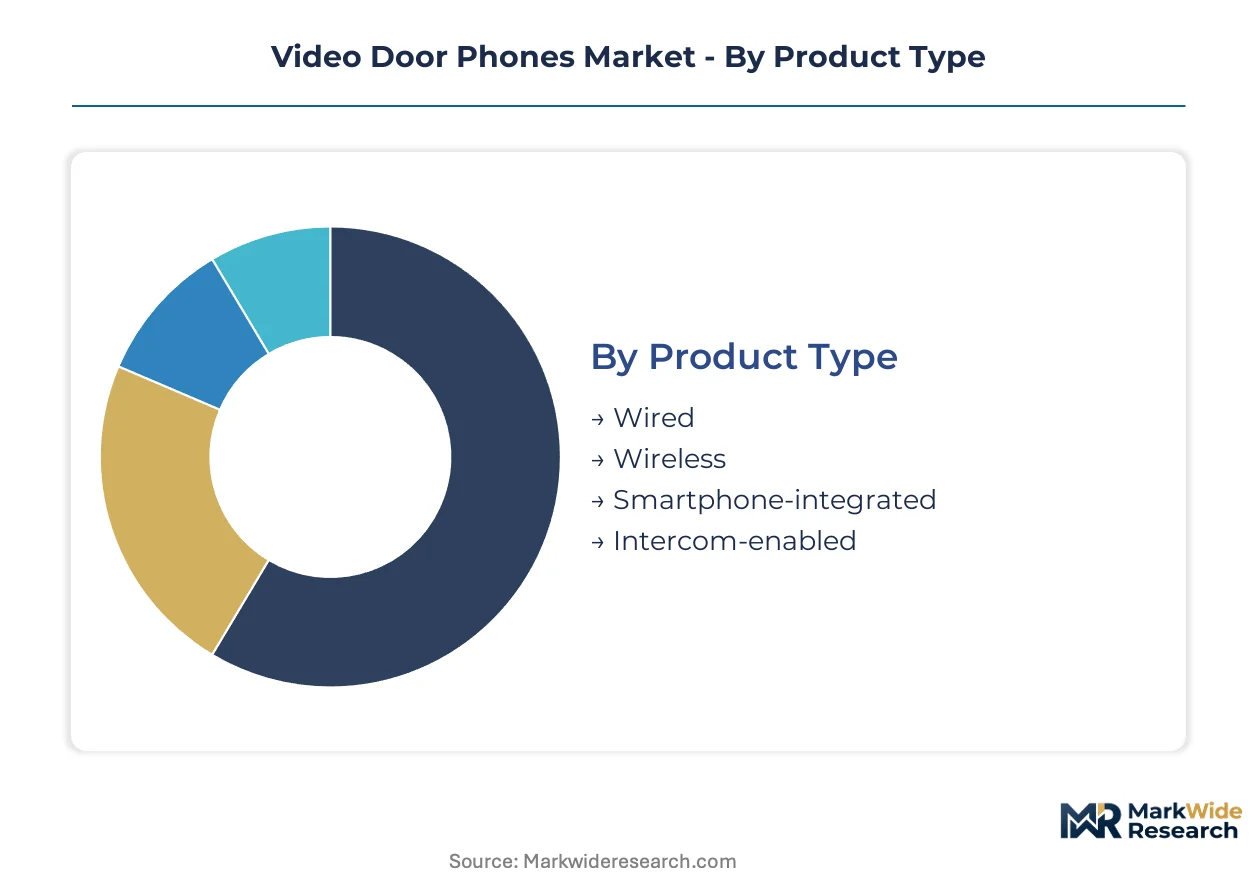
Video door phone procurement splits across installation constraints, connectivity protocols, and feature sophistication. Upgrade cycles vary dramatically by segment—retrofit projects favor backward-compatible architectures while new construction embeds cloud-native systems from foundation.
Product Type:
Replacement cycles accelerate where landlords retain hardware ownership and bundle access into lease agreements.
- Smartphone-integrated:Systems pair dedicated door hardware with native iOS and Android applications for remote unlock, visitor logging, and cloud video archival. Vietnam's condominium developers specify these as standard amenities, compressing sales cycles and displacing retail purchase channels.
- Wired:Two-wire analog and Power-over-Ethernet installations deliver stable power and signal transmission through existing building infrastructure. Southeast Asian multi-unit dwellings favor single-cable retrofit to minimize labor costs and wall damage during upgrade.
- Wireless:Battery-powered or Wi-Fi dependent units eliminate cabling requirements entirely. Battery maintenance obligations and signal reliability concerns limit deployment in high-traffic commercial entrances.
- Intercom-enabled:Hardware integrates with legacy building communication networks for centralized lobby control. Property-management firms in aging European housing stock specify these for elevator and access-control handoff compatibility.
Volume placements concentrate in Wired systems; the faster expansion belongs to Smartphone-integrated.
Technology:
Cost tier differentiation separates premium IP deployments from economy analog retrofits.
- IP-based:Power-over-Ethernet architectures transmit power and data through single cable runs, supporting 1080p+ resolution and encrypted cloud connectivity. EU Cyber Resilience Act mandates for hardware-level security modules are accelerating replacement of legacy installations in German and French residential complexes.
- Analog:Two-wire systems utilizing CVBS or similar protocols dominate installed-base across cost-sensitive retrofit markets. Image quality ceilings at 720p and lack of encryption constrain expansion in jurisdictions with data-protection mandates.
- Wi-Fi enabled:Radio-frequency transmission eliminates structured cabling requirements for single-family and small multi-unit applications. FCC Part 15 emissions compliance adds certification burden for North American market entry.
- Smart Home Compatible:Hardware integrates with Matter, Zigbee, or proprietary ecosystems for unified device control. Integration complexity with competing building-automation protocols requires bespoke API development.
Unit economics favor Analog for volume; margin capture concentrates in IP-based.
End User:
Application-specific requirements drive feature bundling and pricing stratification.
- Hospitality:Property-management system integration demands dominate procurement specifications, with guest-access workflows and recurring software licensing generating premium attach rates. PMS connectivity requirements filter supplier eligibility to established building-automation vendors.
- Residential:Single-family and multi-unit dwellings prioritize smartphone-native visitor management and cloud archival subscription models. Renter-dominated urban housing in Vietnam and Thailand shifts procurement decision-making to real-estate developers.
- Commercial:Office buildings and retail entrances demand high-throughput visitor verification with audit-trail compliance. GDPR data-localization requirements constrain supplier selection for European deployments.
- Industrial:Gated facilities and manufacturing plants specify ruggedized hardware with extended temperature tolerance and vandal resistance. Access-logging integration with time-and-attendance systems adds procurement complexity.
Revenue concentration sits with Hospitality; Residential claims the steepest expansion trajectory.
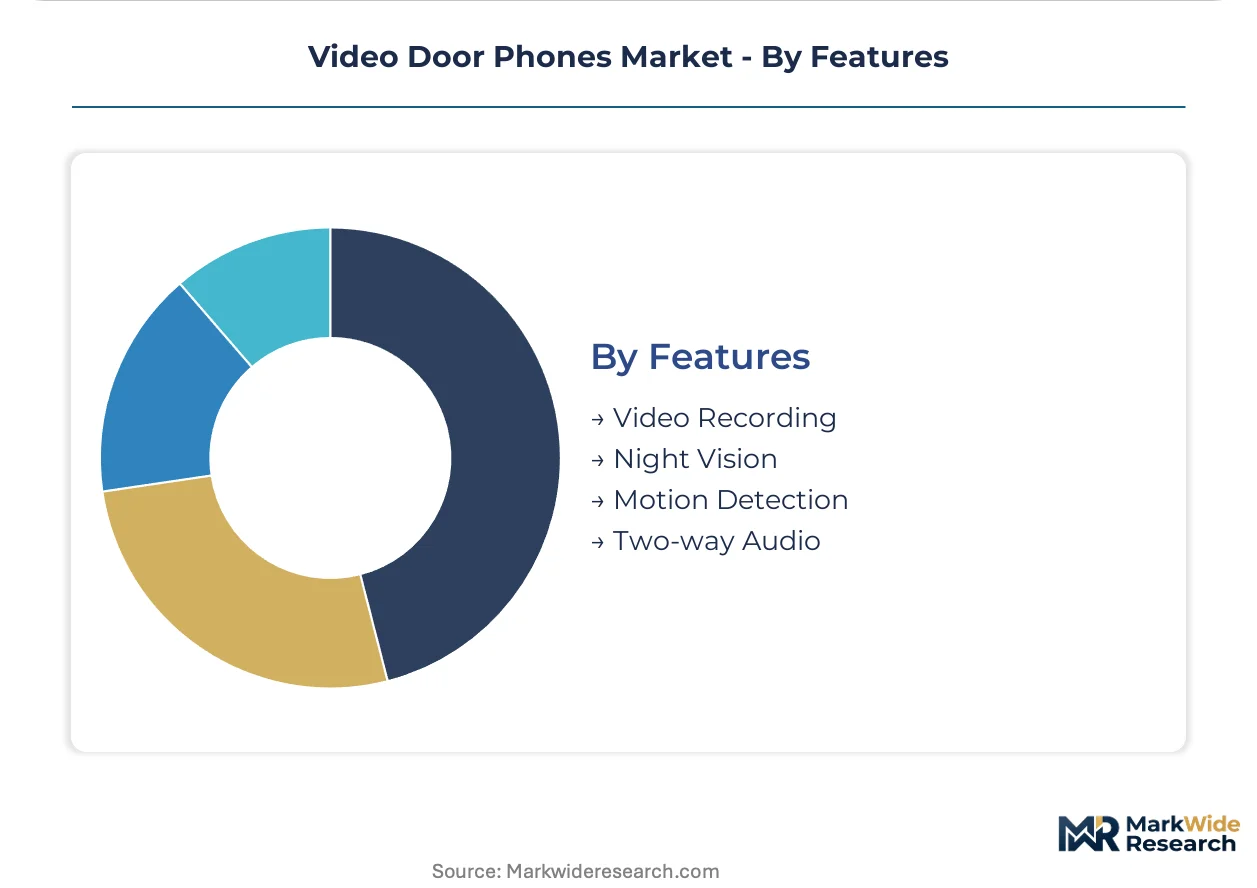
Features:
Feature bundling correlates with jurisdiction-specific regulatory mandates rather than pure end-user preference.
- Video Recording:Continuous or event-triggered capture with local SD or cloud archival options. GDPR data-residency architectures and encryption key management certification filter low-cost Asian suppliers from European distribution.
- Motion Detection:PIR or pixel-change algorithms trigger recording and mobile alerts for unattended visitor detection. False-positive rates from environmental motion constrain algorithm sophistication in economy tiers.
- Night Vision:Infrared LED illumination enables low-light identification with specified lux thresholds. CMOS module cost volatility affects margin predictability for camera-integrated units.
- Two-way Audio:Full-duplex or half-duplex voice communication between door unit and interior panel or smartphone. Audio quality specifications separate premium hospitality deployments from residential economy tiers.
Baseline penetration is highest for Two-way Audio; Motion Detection is climbing the fastest on smart-home integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial parks in Bac Ninh Province and Ho Chi Minh City's Thu Duc district concentrate assembly operations for IP-based entry systems, drawing component suppliers into Vietnam's northern and southern manufacturing corridors.
United States
FCC Part 15 emissions compliance governs Wi-Fi enabled unit certification, creating 3-4 month pre-market timelines that favor established suppliers with dedicated testing facilities. Single-family housing retrofits and multi-unit property-management conversions drive volume demand. California's Title 24 building efficiency codes accelerate Power-over-Ethernet adoption in new residential construction.
Germany
GDPR data-localization mandates and the EU Cyber Resilience Act's encryption baselines filter low-cost Asian manufacturers from distribution channels. Residential complexes in Berlin and Munich accelerate replacement cycles for hardware with certified security modules. Bavarian industrial clusters supply precision camera modules to domestic integrators.
Japan
METI guidelines on connected device security shape procurement specifications for multi-unit dwellings. Tokyo and Osaka condominium developers specify sub-200ms facial recognition latency, eliminating suppliers lacking NPU-equipped chipsets. Kanto region integrators dominate hospitality verticals through property-management system partnerships.
India
BIS electrical safety testing creates 4-6 month certification delays, advantaging incumbents with established compliance infrastructure. Analog two-wire systems retain dominance in cost-sensitive retrofit projects across Mumbai and Delhi-NCR residential stock. Karnataka's electronics manufacturing clusters absorb component assembly for regional brands.
Vietnam
Urban condominium developments in Ho Chi Minh City and Hanoi procure smartphone-integrated visitor management as standard lease amenities, compressing sales cycles. Bac Ninh Province industrial parks host final assembly for IP-based systems serving Southeast Asian export markets. Developers bundle hardware access into rental agreements, displacing retail purchase channels.
Video Door Phones Market Vendor Landscape
Japanese and Korean producers anchor premium-tier supply; Chinese fabricators hold economy segments through component cost advantages. The vendor base splits between building-automation conglomerates with protocol integration capabilities and specialized entry-system houses with captive camera module production. Three archetypes dominate: semiconductor-integrated specialists, cloud-service bundlers, and legacy intercom retrofitters. Competitive moves concentrate on API partnerships with property-management software platforms and backward integration into image sensor sourcing.
Among Japanese specialists, Aiphone Corporation exemplifies the vertically integrated archetype through in-house camera module production. Honeywell International Inc. occupies a position representing building-automation convergence, while Ring LLC anchors the cloud-subscription bundler tier. These three entities represent distinct strategic postures: captive manufacturing control, multi-system integration capability, and recurring revenue platform economics.
| Leading Market Players |
|---|
| Aiphone Corporation |
| VTech Holdings Limited |
| Panasonic Holdings Corporation |
| KOCOM Co. Ltd. |
| Commax Co. Ltd. |
| Honeywell International Inc. |
| Fermax Global SL |
| Ring LLC |
| Legrand SA |
| Others |
Supply Flow & Price Mechanics
Captive camera module production anchors both supply security and margin control for Japanese specialists serving European and North American channels. Aiphone Corporation's in-house sensor sourcing insulates against CMOS volatility while sustaining premium positioning against cloud-subscription bundlers.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations for EU Cyber Resilience Act-compliant hardware, compressing margins for manufacturers without certified inventory buffers. Three-tier pricing structure across premium, standard, and economy levels separates NPU-equipped facial-recognition units from basic intercom retrofits. Pricing pressure stems from image sensor cost volatility affecting mid-tier product lines. Residential retrofit buyers in Southeast Asia exhibit highest price sensitivity; hospitality integrators in Japan and Germany absorb premiums for PMS-compatible systems.
Supply Chain Analysis
India's BIS domestic-content testing mandates are forcing component localization for wired intercom assemblies, extending certification timelines. Manufacturing concentrates in Vietnam, China, and Japan, with Bac Ninh Province hosting final assembly for IP-based export production. Supply chains draw from Taiwan for NPU chipsets, South Korea for display panels, and domestic Chinese sources for CMOS modules. Single-source vulnerability sits with advanced semiconductor fabrication. Distribution runs through building-automation integrators in developed markets and property-developer direct procurement in Southeast Asian condominium construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across GDPR, EU AI Act, and BIS certification is accelerating supplier-base contraction, eliminating sub-scale players lacking multi-jurisdictional compliance infrastructure.
For Market Incumbents: Acquire NPU semiconductor partnerships to secure sub-200ms facial-recognition latency specifications demanded by Tokyo and Osaka developers. Build captive cloud-archival capacity to capture recurring subscription revenue streams before Ring LLC and cloud-native entrants dominate North American retail channels. EU AI Act algorithmic transparency requirements threaten hardware-only vendors lacking software audit-trail capabilities. For New Entrants and Emerging Players: The EU Cyber Resilience Act in Germany and France opens a window for hardware-security-module specialists to displace low-cost Asian manufacturers decoupled from European distribution. Target Vietnam's urban condominium developers bundling smartphone-integrated access into lease agreements, bypassing saturated retail channels. Pursue white-label manufacturing partnerships with Bac Ninh Province assemblers serving Southeast Asian export markets. For Investors and Strategic Acquirers: Exit pathways concentrate in building-automation conglomerates seeking entry-system capabilities for vertical integration. Long-term viability favors vendors with simultaneous semiconductor partnerships, cloud infrastructure, and multi-regime firmware engineering capacity. Watch India's BIS certification timeline compression as inflection indicator for incumbent advantage erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Camera Modules | Aiphone Corporation's captive sensor production sustains margin control against CMOS volatility. |
| Cloud-Storage Subscription Platform | Ring LLC's recurring revenue model shifts hardware margin pressure to services in North American retail. |
| Property-Management System API Partnerships | Honeywell's building-automation integration captures hospitality verticals through guest-access workflow licensing. |
| EU AI Act Compliance Tooling | Explainable-AI middleware for facial-recognition audit trails addresses algorithmic transparency mandates in Germany. |
| Power-over-Ethernet Architecture Expansion | Single-cable retrofit compatibility expands addressable market beyond new construction in Southeast Asian multi-unit dwellings. |
Methodological Framework
Independent corroboration across security integrator interviews, property-developer procurement data, and regulatory filing analysis underwrites the qualitative findings. Primary fieldwork engaged building-automation engineers, facility-management procurement directors, semiconductor distribution specialists, and hospitality technology integrators. Secondary validation drew from FCC Part 15 equipment authorization databases, EU Cyber Resilience Act implementation guidance, BIS certification records, and customs trade data for video door phone component flows. Bottom-up unit shipment modeling triangulated against top-down addressable market sizing across connectivity protocols and end-use verticals.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, technology architecture, end-user vertical, and regional regulatory cluster. CAGRs derive from installed-base replacement cycle analysis, new construction penetration assumptions, and upgrade velocity modeling for analog-to-IP transitions. Industry-specific forecast inputs include Vietnam condominium completion schedules, EU encryption mandate compliance deadlines, and CMOS sensor pricing elasticity coefficients.
The model assumes a particular technology adoption path; alternative pathways for edge-computing facial-recognition inference would alter the outlook if on-device processing latency fails to meet Japanese sub-200ms specifications. Forecasts reflect assumptions regarding BIS timeline normalization, GDPR enforcement consistency, and Power-over-Ethernet retrofit labor cost stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Canada Hosted PBX Market
Telecommunications
Cloud RAN Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Thailand ICT Market
Telecommunications
Denmark ICT Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Algeria Telecom Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Argentina Telecom Market
Telecommunications
Iran Telecom Market
Telecommunications
Romania Telecom Market