
 Global Automatic Number Plate Recognition (ANPR) System Market | 2026-2036
Global Automatic Number Plate Recognition (ANPR) System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Number Plate Recognition (ANPR) System Market Analysis
Market Context
Edge AI inference on camera hardware is reshaping how ANPR systems process data locally rather than transmitting raw feeds to central servers. Kapsch TrafficCom AG leverages its European installed base to sustain long-term service contracts across tolling corridors. Hikvision Digital Technology Co., Ltd. anchors its competitive position through vertical control over image sensor supply chains and manufacturing scale. Siemens AG differentiates via deep integration with urban traffic signal networks, positioning its ANPR modules as nodes within broader intelligent infrastructure ecosystems.
Technical Definition and Segment Structure
Automatic Number Plate Recognition (ANPR) systems comprise camera assemblies, illumination subsystems, optical character recognition engines, and database matching software that capture and decode vehicle registration plates for enforcement, access control, or revenue collection purposes. Fixed camera deployments dominate current revenue pools due to permanent installations on highways and urban corridors, while mobile camera units represent the fastest-expanding segment as police forces and parking operators seek flexible deployment without civil works. Cloud-based solutions are displacing on-premise architectures in new procurements, particularly among transportation agencies managing multi-jurisdiction vehicle databases.
Regulatory Frame and Outlook
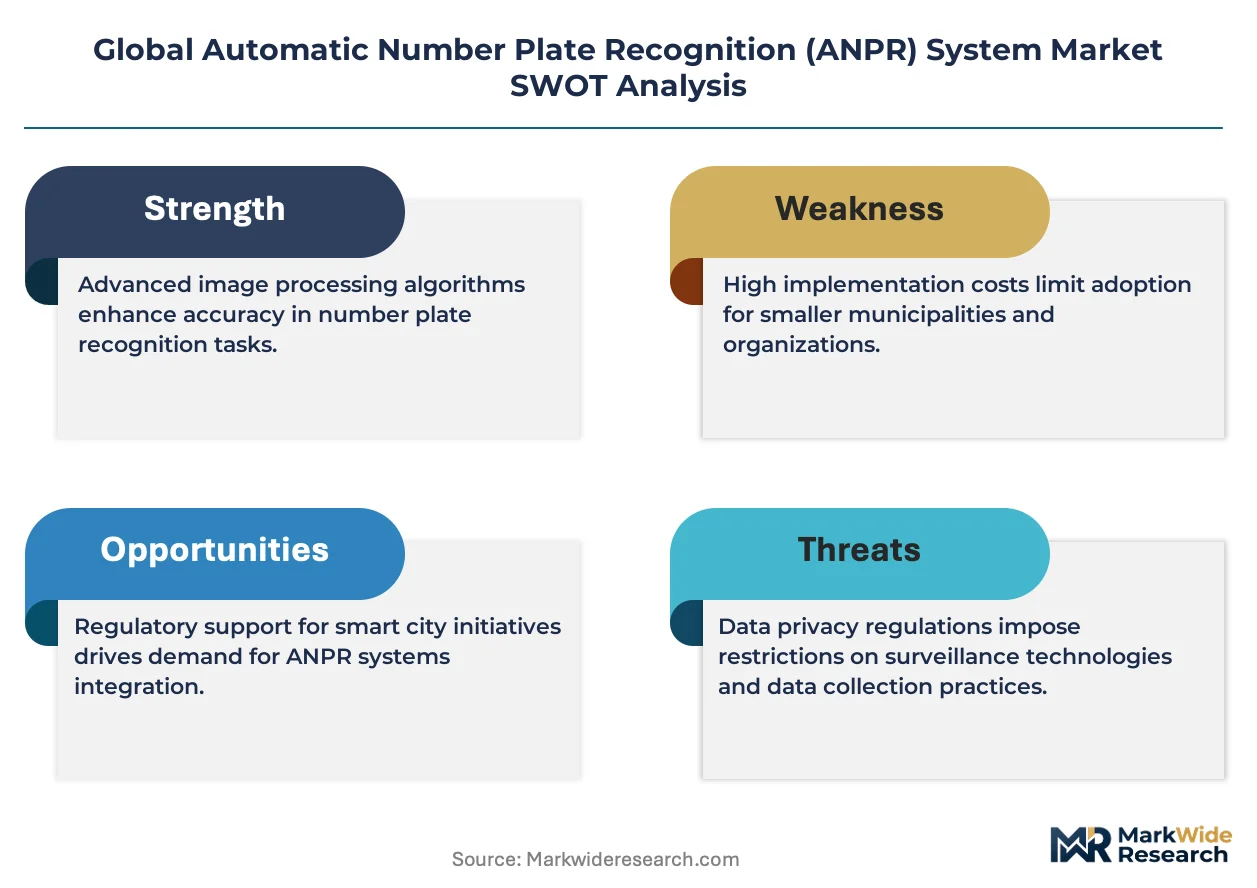
The EU AI Act imposes risk classification and conformity assessment obligations on biometric identification systems including ANPR, while the GDPR limits data retention periods and mandates purpose specification for plate image storage. The US lacks federal biometric surveillance legislation, leaving NHTSA guidelines and state-level privacy laws such as California's Consumer Privacy Act to fragment compliance requirements. Stakeholders must monitor whether emerging algorithmic auditing mandates in Europe propagate to procurement standards in Asia-Pacific jurisdictions.
Market Dynamics
Edge AI inference is collapsing the traditional centralized processing architecture, forcing vendors to redesign hardware-software bundles around on-camera computation rather than server-dependent workflows.
Growth Catalysts
- EU AI Act compliance mandates:The risk classification framework for biometric surveillance systems is accelerating replacement cycles as transportation agencies preemptively upgrade to conformant hardware before enforcement deadlines.
- Smart city traffic management:Dubai's integrated corridor digitization program is creating template procurement specifications that neighboring Gulf Cooperation Council members are adopting verbatim.
- Highway digitization budgets:Germany's federal infrastructure ministry continues expanding dedicated funding streams for automated enforcement networks along Autobahn corridors.
Market Restraints
- Image sensor supply concentration:Taiwan and South Korean foundries control critical CMOS sensor fabrication, exposing camera OEMs to geopolitical disruption risks and allocation constraints.
- GDPR retention limits:The 72-hour maximum storage window for biometric data in many EU member states compresses the value extraction timeline from enforcement evidence.
- Optical performance degradation:Adverse weather conditions including heavy precipitation and glare angles continue generating false-negative read rates that human verification cannot economically eliminate.
Strategic Opportunities
- India national highway expansion:The Golden Quadrilateral corridor upgrade program lacks legacy camera infrastructure, creating greenfield deployment opportunities without integration burdens.
- Cloud-native architectures:Multi-jurisdiction transportation agencies in Australia and Canada are consolidating vehicle databases into federated cloud platforms that favor API-first ANPR vendors.
- Parking enforcement automation:Municipal operators in France and Spain are replacing permit-based systems with camera-guided dynamic pricing zones that generate recurring SaaS revenue streams.
Industry Challenges
- Embedded systems engineering talent:The shortage of firmware developers capable of optimizing neural network inference on resource-constrained camera SoCs is extending product development cycles.
- Legacy analog infrastructure:Eastern European and Latin American municipalities maintain coaxial cable networks that resist IP camera migration without complete civil works replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Number Plate Recognition (ANPR) System Market |
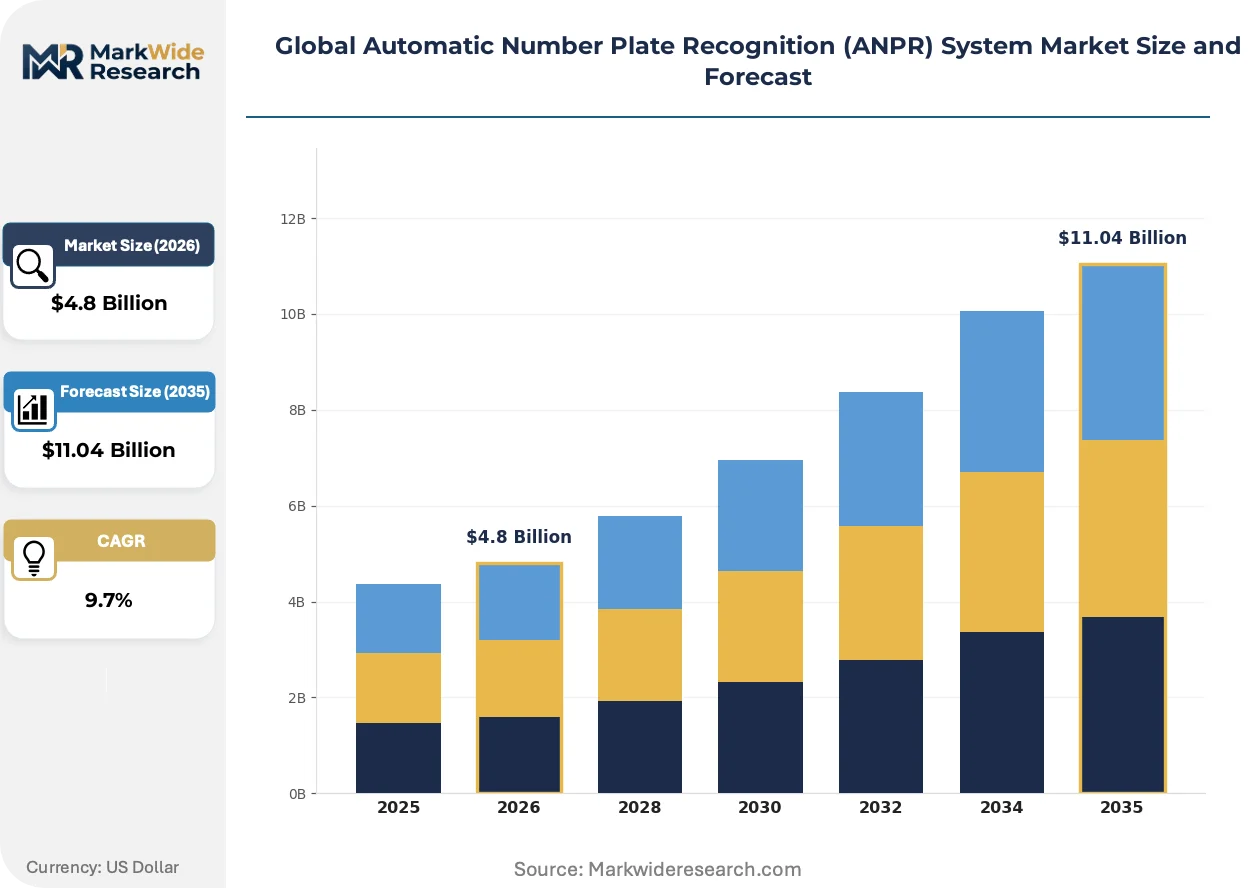
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
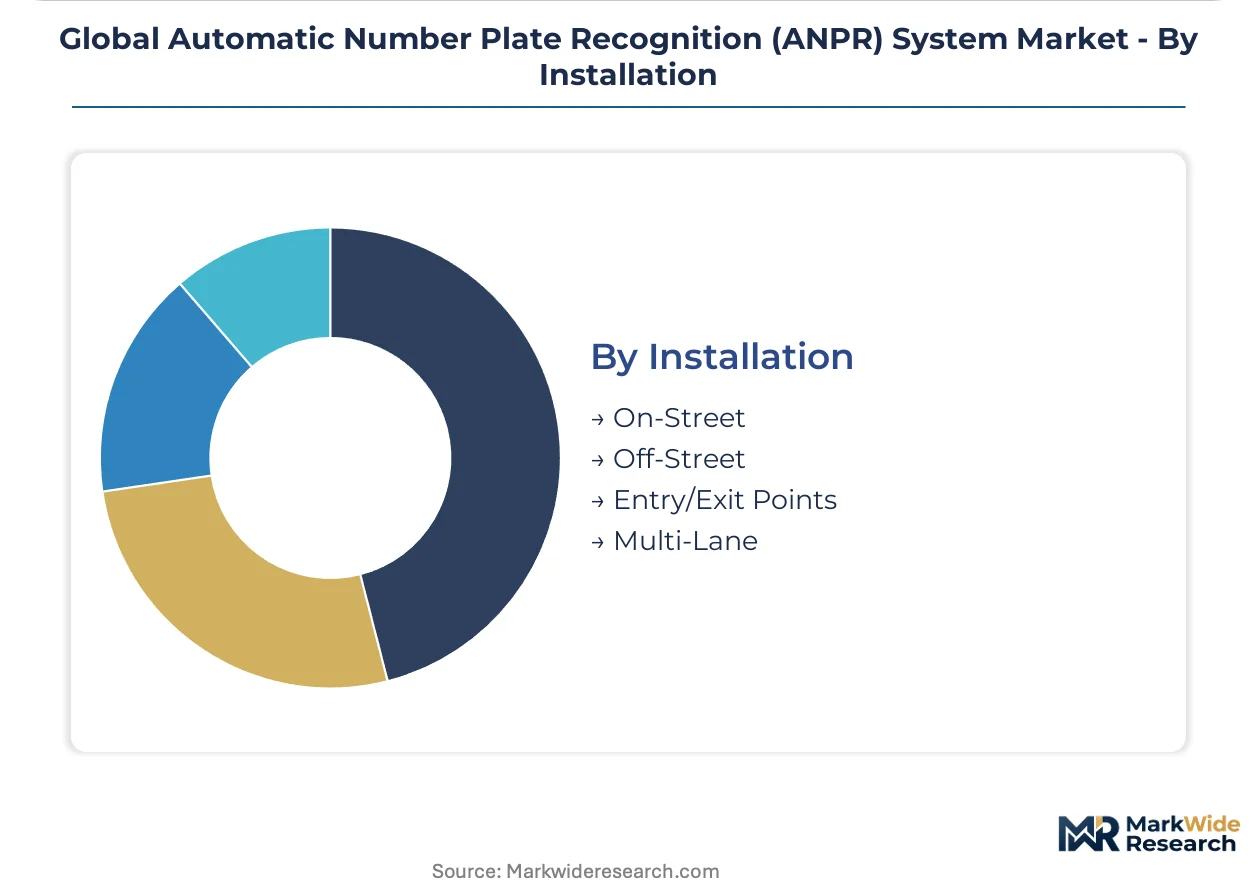
| Segmentation | Product Type: Fixed Cameras, Mobile Cameras, Portable Systems, Software Solutions Technology: Optical Character Recognition, Infrared Technology, Image Processing, Cloud-Based Solutions End User: Law Enforcement, Transportation Agencies, Parking Management, Toll Collection Installation: On-Street, Off-Street, Entry/Exit Points, Multi-Lane |
| Companies Covered | Siemens AG, Kapsch TrafficCom AG, Hikvision Digital Technology Co., Ltd., Axis Communications AB, Genetec Inc., Jenoptik Group, Q-Free ASA, Nedap N.V., Motorola Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Number Plate Recognition (ANPR) System Market Emerging Trajectories
Computational photography and federated learning architectures are redistributing intelligence across the capture-to-decision pipeline, compressing latency budgets and data transmission costs simultaneously.
Solid-state illumination is collapsing the mechanical complexity of traditional strobe and halogen subsystems. CMOS-integrated LED arrays from automotive lighting suppliers now deliver sufficient lux output for plate capture at highway speeds. Traffic enforcement agencies in Italy and Poland are specifying solid-state modules exclusively in new tenders, eliminating moving parts that previously drove maintenance callouts.
The EU AI Act's conformity assessment procedures are restructuring vendor certification timelines. Third-party notified bodies must validate algorithmic accuracy and bias metrics before biometric surveillance systems receive CE marking. German and Dutch procurement offices are inserting AI Act compliance clauses into framework agreements eighteen months ahead of full enforcement, favoring incumbent suppliers with established quality management systems.
Outcome-based service contracts are displacing capital expenditure procurement for mid-sized municipal fleets. Parking operators in Denmark and Sweden now compensate vendors per verified violation rather than per installed camera, transferring utilization risk to equipment providers. This model concentrates contract awards among vertically integrated suppliers capable of financing hardware deployment against future revenue shares.
Global Automatic Number Plate Recognition (ANPR) System Market Segmentation
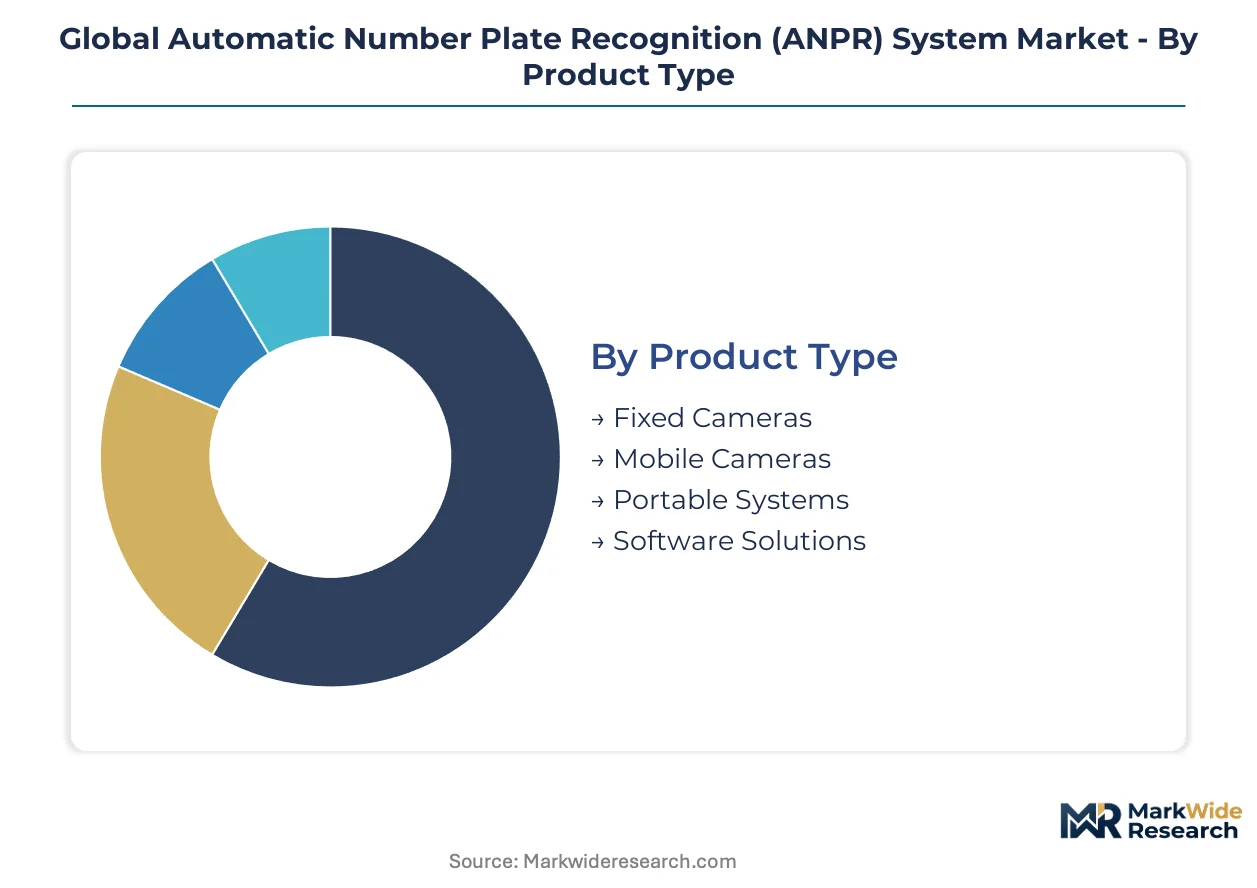
ANPR procurement patterns diverge sharply across hardware configurations, processing architectures, enforcement applications, and civil infrastructure requirements. Understanding these segment boundaries reveals where vendor specialization creates pricing power versus where modular competition erodes margins.
Product Type:
Hardware form factor determines deployment economics, from permanent highway installations to vehicle-mounted patrol units.
- Fixed Cameras:Pole-mounted assemblies with integrated illumination and edge processors dominate highway enforcement and urban corridor monitoring. German Autobahn digitization budgets concentrate procurement volume here, though civil works costs extend payback periods.
- Mobile Cameras:Roof-mounted or dashboard-integrated units enable traffic patrols and temporary enforcement zones without infrastructure investment. Police forces in Spain and Italy are expanding fleet deployments for dynamic violation capture.
- Portable Systems:Battery-powered tripods with wireless transmission suit construction zones and special events. French municipalities specify these for temporary low-emission zone enforcement.
- Software Solutions:Standalone OCR engines and database matching platforms license to existing camera networks. Australian transportation agencies favor API-first architectures for multi-state vehicle registry integration.
Fixed cameras hold installed capacity. Mobile cameras are rotating up the share rankings.
Technology:
Capture and processing methodology segments by spectral range, computational location, and algorithmic approach.
- Optical Character Recognition:Traditional visible-light character decoding remains cost-effective for controlled lighting environments. Parking operators in Denmark rely on OCR for permit validation in covered structures.
- Infrared Technology:Active IR illumination penetrates darkness and glare without visible light pollution. Night enforcement specifications in Poland and Sweden mandate IR capability for 24-hour operation.
- Image Processing:Advanced denoising and geometric correction algorithms improve read accuracy on dirty or angled plates. UAE smart city tenders require multi-angle capture with sub-200ms processing latency.
- Cloud-Based Solutions:Centralized inference and federated database access reduce on-camera hardware costs. Canadian provincial agencies are consolidating enforcement platforms into cloud-native architectures.
Infrared technology holds installed capacity. Cloud-based solutions are rotating up the share rankings.
End User:
Enforcement mandate and revenue model shape procurement specifications and vendor relationships.
- Law Enforcement:Police departments prioritize real-time warrant and stolen vehicle database matching. Mobile deployment flexibility and ruggedized hardware dominate specifications.
- Transportation Agencies:Highway operators focus on traffic flow analytics and automated incident detection. German federal procurement emphasizes integration with intelligent transportation system backbones.
- Parking Management:Municipal and private operators seek permitless enforcement with dynamic pricing integration. Outcome-based contracts in Nordic markets compensate vendors per verified violation.
- Toll Collection:Open-road and barrier systems demand 99.5%+ read accuracy at highway speeds. Italian motorway concessionaires specify solid-state illumination to minimize maintenance callouts.
Law enforcement holds installed capacity. Parking management is rotating up the share rankings.
Installation:
Physical mounting configuration determines camera specifications, civil works requirements, and coverage geometry.
- On-Street:Curb-mounted or overhead gantries serve urban enforcement and congestion pricing. Dubai's integrated corridor program templates these specifications for GCC adoption.
- Off-Street:Parking structure and lot deployments prioritize compact form factors and PoE connectivity. Spanish retail park operators specify off-street systems for customer dwell-time analytics.
- Entry/Exit Points:Controlled access gates require near-perfect read rates with barrier interlock. Campus and industrial security managers in India specify entry/exit configurations for visitor management.
- Multi-Lane:Overhead span-mounted arrays capture plates across several traffic lanes simultaneously. German Autobahn widening projects drive multi-lane procurement for enforcement without lane restriction.
On-street installations hold installed capacity. Multi-lane configurations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German camera OEMs export integrated ANPR hardware to transportation agencies across the Gulf Cooperation Council, while Chinese manufacturers supply cost-optimized assemblies to India's highway expansion programs.
Germany
Federal highway digitization budgets and Autobahn enforcement network upgrades drive procurement volume. The EU AI Act's conformity assessment mandates accelerate replacement cycles for biometric surveillance hardware. Kapsch TrafficCom AG leverages its European installed base across tolling corridors in Bavaria and North Rhine-Westphalia.
United Arab Emirates
Dubai's smart city corridor program creates template specifications for integrated camera networks. The UAE's national cybersecurity regulator imposes data localization requirements on biometric surveillance systems. Abu Dhabi transportation authorities are adopting Dubai's procurement frameworks verbatim for federal highway monitoring.
India
The Golden Quadrilateral national highway expansion lacks legacy camera infrastructure, enabling greenfield ANPR deployment without integration burdens. The Ministry of Road Transport and Highways mandates automated enforcement for new expressway segments. Maharashtra and Gujarat state agencies are bundling camera networks with toll plaza modernization contracts.
United States
State transportation departments consolidate vehicle databases into federated cloud platforms favoring API-first vendors. NHTSA guidelines and fragmented state privacy laws create compliance complexity without federal biometric surveillance legislation. California and Texas DOTs are piloting multi-jurisdiction plate recognition for commercial vehicle screening.
Australia
Provincial transportation agencies migrate enforcement platforms to cloud-native architectures requiring federated database access. The national privacy regulator enforces strict purpose specification for biometric data retention. Victoria and New South Wales are consolidating toll collection systems under unified camera network specifications.
Global Automatic Number Plate Recognition (ANPR) System Market Vendor Landscape
Channel-controlling players compete with product-specialist players for procurement contracts across transportation and security verticals. The vendor base clusters around three tiers: integrated infrastructure conglomerates with traffic signal network control, traffic technology specialists with long-term service contract expertise, and camera hardware manufacturers with captive image sensor supply. Dominant competitive moves include strategic partnerships for cloud platform integration and geographic expansion through framework agreement positioning.
Within the integrated infrastructure tier, Siemens AG and Kapsch TrafficCom AG exemplify contrasting approaches to long-term contract sustainability. Hikvision Digital Technology Co., Ltd. occupies a position among vertically integrated camera manufacturers with manufacturing scale advantages.
| Leading Market Players |
|---|
| Siemens AG |
| Kapsch TrafficCom AG |
| Hikvision Digital Technology Co., Ltd. |
| Axis Communications AB |
| Genetec Inc. |
| Jenoptik Group |
| Q-Free ASA |
| Nedap N.V. |
| Motorola Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwan and South Korean foundries control CMOS image sensor fabrication, anchoring margin capture upstream while camera OEMs compete on assembly economics and software differentiation downstream.
Pricing Analysis
Edge-AI-enabled camera generations command 40-60% premiums over legacy server-dependent architectures, while prior-generation optical-only units face commoditization in price-sensitive municipal segments. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-certified systems with third-party algorithmic auditing from basic CE-marked hardware and unlicensed gray-market imports. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Southeast Asian procurement offices are consolidating framework agreements around lowest-compliant-bid criteria. Parking management operators exhibit highest price sensitivity due to outcome-based contract structures, while toll collection concessionaires prioritize accuracy guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for camera OEMs with assembly footprints spanning both jurisdictions. Component sourcing draws from Taiwan and South Korea for CMOS sensors, Germany and Japan for precision optics, and China for LED illumination modules and mechanical housings. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where foundry allocation constraints extend lead times for edge-AI system-on-chips. Distribution runs through systems integrators with traffic engineering expertise in Europe, direct OEM relationships with federal transportation agencies in the Gulf Cooperation Council, and value-added resellers serving fragmented municipal markets in Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANPR deployment remains early-cycle across India's national highway network and Southeast Asian smart city programs, with greenfield infrastructure investment outpacing replacement demand in saturated European corridors.
For Market Incumbents: Build regulatory certification moats by pre-positioning EU AI Act conformity assessments and GDPR-compliant data architecture ahead of enforcement deadlines. Incumbents should anchor long-term service contracts with German Autobahn operators and Dubai transportation authorities while accelerating firmware development hiring to offset embedded systems talent scarcity. Threatening margin compression from Chinese camera manufacturers with captive sensor supply demands defensive localization of final assembly within European customs unions. For New Entrants and Emerging Players: India's Golden Quadrilateral corridor expansion offers the most penetrable geographic entry point, with state-level bundling of toll modernization and enforcement camera procurement creating vendor-neutral specification windows. New entrants should target cloud-native software licensing to Australian and Canadian provincial agencies consolidating federated vehicle databases, avoiding capital-intensive hardware competition. A SaaS-first go-to-market angle with API-first architecture minimizes upfront infrastructure investment while capturing recurring revenue from dynamic parking enforcement contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed traffic technology specialists holding framework agreements across Nordic toll corridors and Italian motorway concessions. Long-term viability over the coming decade hinges on successful transition from hardware shipment models to outcome-based service revenue with municipal parking operators. Acquisition candidates with established notified body relationships for EU AI Act compliance and existing cloud platform integrations present the most defensible positioning. The signal to watch is procurement clause insertion rate for algorithmic transparency requirements across German and Dutch transportation tenders.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Third-party conformity assessment from notified bodies accelerates procurement access in German and Dutch markets. |
| Cloud-Native Platform Integration | API-first architectures capture Australian and Canadian provincial agency consolidation of federated vehicle databases. |
| Outcome-Based Contract Structuring | Per-violation compensation models transfer utilization risk to vendors in Danish and Swedish parking enforcement markets. |
| Edge-AI Hardware Development | On-camera neural network inference reduces transmission costs and latency for Dubai smart city corridor specifications. |
| Geographic Assembly Localization | European customs union manufacturing mitigates tariff exposure and satisfies EU public procurement content requirements. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ANPR system procurement officers at German federal transportation agencies, firmware engineering directors at camera OEMs, and parking enforcement contract managers at Nordic municipal operators; and secondary validation through EU AI Act implementation guidance, NHTSA automated enforcement guidelines, SEC filings from traffic technology specialists, and customs data on CMOS sensor import flows. Bottom-up triangulation of unit deployment volumes across highway, urban, and parking segments was cross-checked against top-down market sizing from transportation infrastructure budget disclosures.
Forecast inputs span hardware form factor adoption curves, processing architecture migration from server-dependent to edge-AI systems, enforcement application mix across toll collection and parking management, and civil infrastructure requirements by installation type. CAGRs were derived from segment-level growth rate reconciliation across the projection horizon. Industry-specific inputs include EU AI Act compliance timeline acceleration, Germany's federal highway digitization budget trajectory, and India's Golden Quadrilateral expansion phasing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese camera manufacturers with vertical sensor integration or hyperscaler cloud entrants with AI platform bundling would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Security Information and Event Management Software Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Global Log Management Market
Security Software
Global Network Encryption Market
Security Software
Global Hardware Security Modules (HSM) Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
VPN Software Market
Security Software
Source Code Escrow Market
Security Software
Endpoint Detection and Response Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Cloud Identity and Access Management Software Market
Security Software
Stalkerware Market
Security Software
Global Wireless Intrusion Prevention System Market