
 Web Content Filtering Market | 2026-2036
Web Content Filtering Market Size, Share, and Industry Trends Forecast 2026-2036
Web Content Filtering Market Outlook
Enterprise-grade filtering with real-time SSL inspection is redrawing competitive benchmarks in the Web Content Filtering space. Cisco Systems leverages its networking hardware installed base to bundle filtering at the edge. Palo Alto Networks specializes in integrating URL filtering with next-generation firewall policy engines. Zscaler anchors its position through a cloud-native proxy architecture that eliminates on-premises appliance dependency.
Web Content Filtering encompasses technologies that inspect, categorize, and control access to internet destinations based on policy rules, typically operating at throughput rates exceeding 10 Gbps in carrier deployments. URL Filtering and DNS Filtering dominate current procurement volumes, though DNS Security is gaining traction as encrypted DNS protocols complicate traditional inspection methods. Cloud-Based deployment is expanding fastest among mid-market buyers, while On-Premises retains stronghold status in regulated sectors where data residency controls apply. Enterprises represent the deepest end-user margin pool, with Educational Institutions emerging as a volume growth segment driven by student safety mandates.
FCC net-neutrality frameworks and EU GDPR data-processing restrictions shape how filtering vendors architect traffic inspection without violating privacy boundaries. The EU AI Act adds compliance complexity for platforms employing machine-learning classification models. Health Insurance Portability and Accountability Act obligations in the United States extend filtering requirements to healthcare cloud migrations. Stakeholders must weigh sovereign data requirements against the operational simplicity of centralized cloud filtering as procurement patterns diverge across jurisdictions.
Market Dynamics
Encrypted DNS protocols and TLS 1.3 adoption are dismantling traditional deep-packet inspection architectures, forcing vendors to rebuild filtering engines around passive DNS analysis and browser-integrated policy enforcement rather than inline traffic decryption.
Growth Catalysts
- EU AI Act:Automated content classification systems now require algorithmic transparency audits, creating procurement urgency for filtering platforms with built-in explainability dashboards and model documentation tools.
- Educational Institutions:K-12 student safety mandates in multiple jurisdictions are mandating real-time threat detection and suicide-prevention keyword monitoring, expanding addressable demand beyond traditional enterprise cybersecurity budgets.
- Zero Trust Architecture:Network perimeter dissolution is repositioning web filtering from gateway appliances to identity-bound policy enforcement points attached to individual user sessions.
Market Restraints
- Silicon supply concentration:Specialized SSL inspection accelerators depend on FPGA fabrication capacity concentrated in Taiwan, creating lead-time vulnerability for high-throughput appliance vendors.
- GDPR inspection friction:European data-protection authorities are questioning whether URL logging constitutes unlawful traffic data retention, chilling deployment confidence in EU-regulated enterprises.
- DNS-over-HTTPS substitution:Browser-native encrypted resolution from Cloudflare and Google is bypassing organizational DNS controls entirely, eroding the technical foundation of DNS-based filtering tiers.
Strategic Opportunities
- India:Data localization requirements under the Digital Personal Data Protection Act are blocking foreign cloud-filtering architectures, opening space for domestic platform development and sovereign infrastructure partnerships.
- Healthcare cloud migration:HIPAA-covered entities moving electronic health records to SaaS environments need filtering that audits clinician access to external resources without breaking clinical workflow integration.
- Managed Security Service Providers:Mid-market buyers lacking internal SOC capability are outsourcing policy tuning and threat feed curation, creating recurring revenue attachments beyond software licensing.
Industry Challenges
- ML model explainability:Security analysts cannot interpret why neural classification engines flag specific URLs, creating operational friction during false-positive investigations and incident response.
- Certificate pinning breakage:Applications implementing hardcoded certificate validation fail when filtering proxies intercept TLS connections, requiring application-by-application exemption management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Web Content Filtering Market |
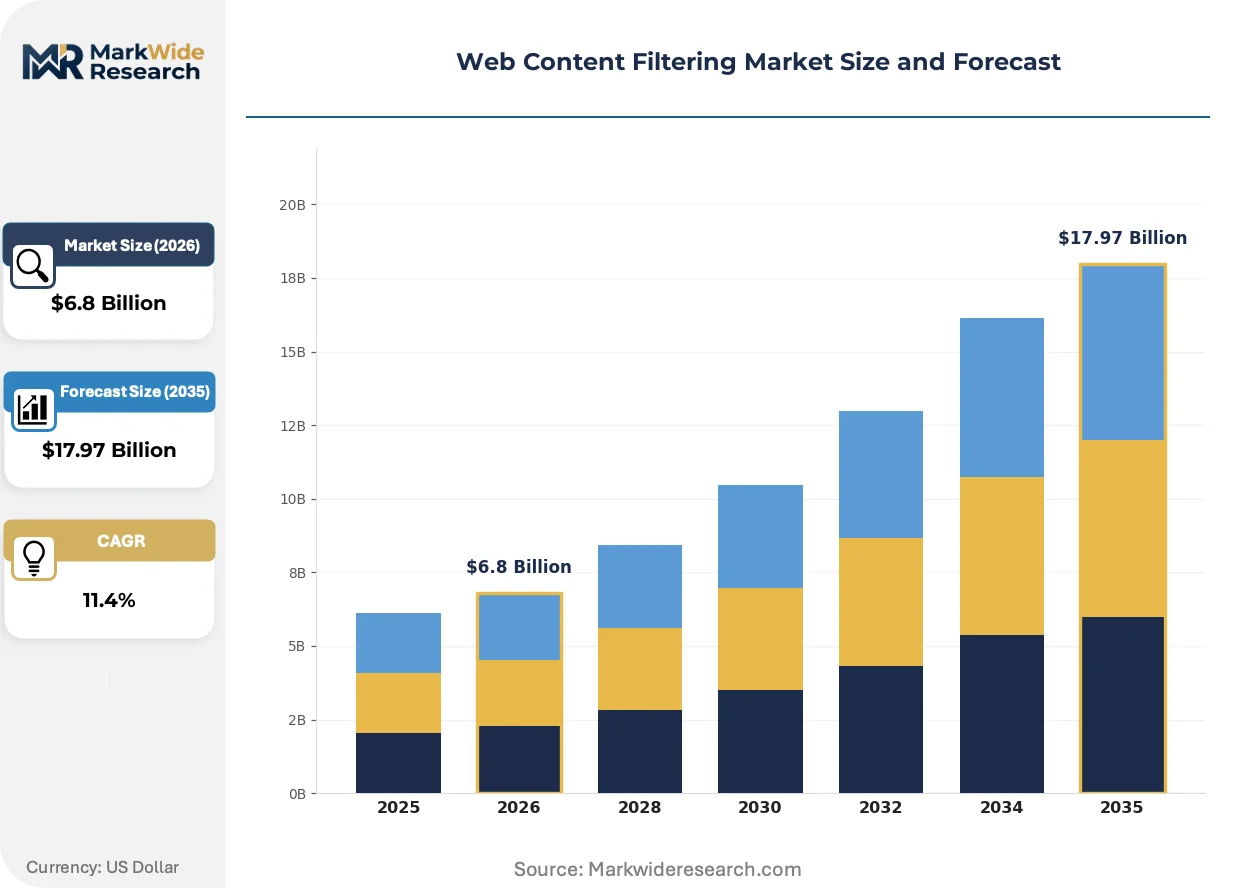
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: URL Filtering, DNS Filtering, DNS Security, Keyword Filtering Deployment: On-Premises, Cloud-Based, Hybrid, Software-as-a-Service End User: Enterprises, Educational Institutions, Government Agencies, Healthcare Providers Service Type: Security Services, Compliance Management, Threat Intelligence, Incident Response |
| Companies Covered | Cisco Systems, Inc., Palo Alto Networks, Inc., Fortinet, Inc., Barracuda Networks, Inc., McAfee Corp., Symantec Corporation, Zscaler, Inc., Forcepoint LLC, Trend Micro Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Web Content Filtering Market Strategic Shifts
Filtering architectures are fragmenting across three simultaneous vectors: encryption-breaking inspection is becoming technically infeasible, policy enforcement is migrating closer to endpoints, and compliance documentation is becoming as critical as threat blocking.
Zero Trust Network Access architectures are displacing traditional secure web gateway deployments. Enterprise buyers are adopting identity-aware proxies that authenticate every session before URL resolution rather than inspecting traffic at network boundaries. This compression is collapsing the distinction between remote access and web filtering product categories.
The EU AI Act's risk-classification framework is reshaping vendor development priorities. Machine-learning models used for content categorization now require conformity assessments and CE marking when deployed in high-risk contexts. German and French enterprise buyers are prioritizing platforms with pre-certified algorithmic impact assessments.
Consumption-based licensing is replacing perpetual appliance purchases. Mid-market buyers in the United States and Germany are subscribing to cloud-filtering services with usage-scaled pricing rather than capitalizing hardware. This rotation is compressing vendor revenue recognition cycles while expanding total account lifetime value through automatic feature tier upgrades.
Web Content Filtering Market Segmentation
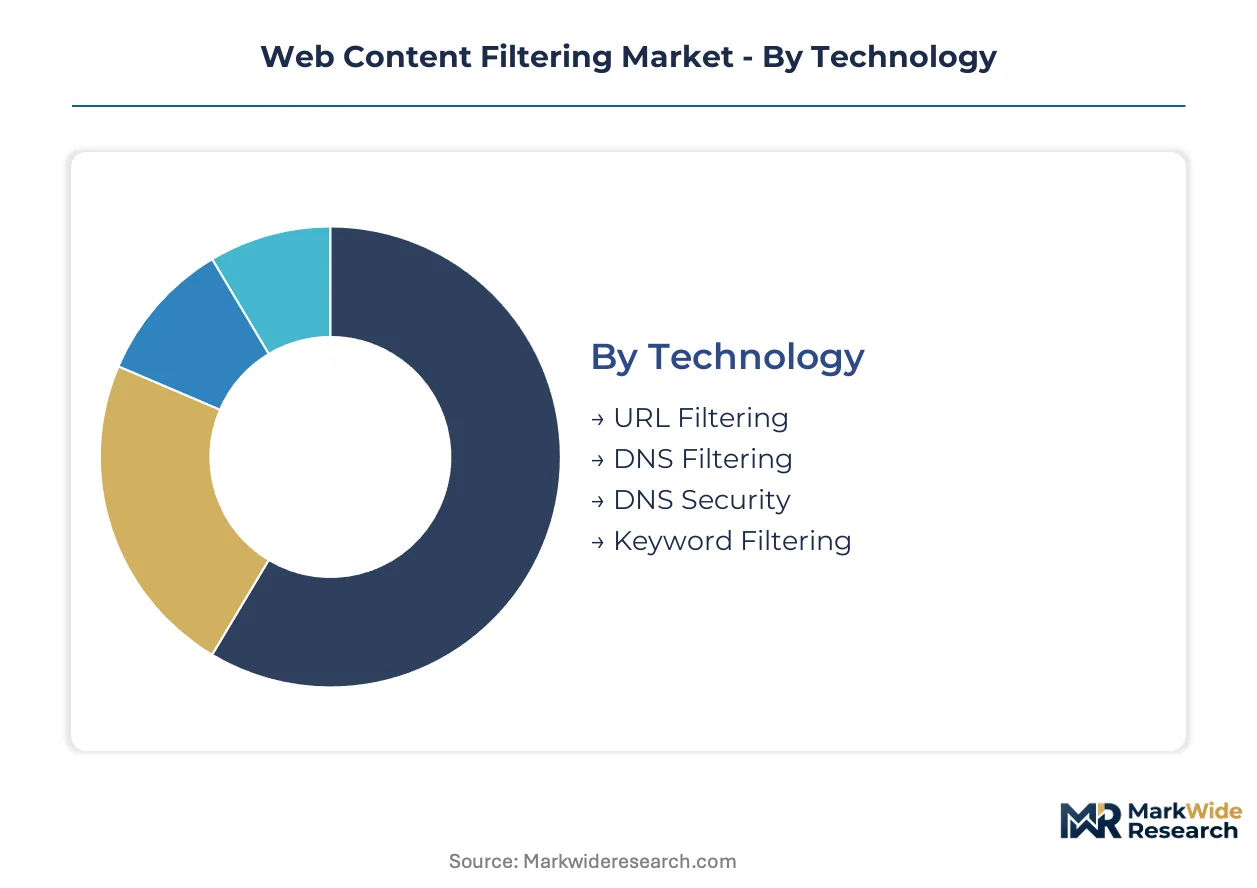
Web Content Filtering procurement patterns diverge sharply across technology maturity, deployment economics, and regulatory exposure. Buyers prioritize segments that align encryption-handling capabilities with compliance documentation requirements specific to their jurisdiction and industry vertical.
Technology:
Channel mix varies by inspection depth — high-throughput appliance vendors dominate URL Filtering sales through value-added resellers, while DNS Security routes primarily through cloud-native direct subscriptions and managed security service providers.
- URL Filtering:Operates through real-time database lookups against categorized destination lists, typically processing decisions at sub-millisecond latency for user-transparent enforcement. Enterprise cybersecurity teams in the United States and Germany concentrate procurement here, driven by GDPR audit requirements for logged access decisions and the EU AI Act's documentation mandates for automated classification systems.
- DNS Filtering:Intercepts resolution requests at the network perimeter to block malicious or policy-violating destinations before connection establishment. Educational Institutions across multiple jurisdictions represent expanding demand, compelled by K-12 student safety mandates requiring suicide-prevention keyword monitoring and real-time threat detection without endpoint agent deployment.
- DNS Security:Extends filtering with encrypted protocol handling and threat feed integration for zero-day domain detection.
- Keyword Filtering:Applies lexical analysis to page content and search queries for policy enforcement in regulated workplace environments.
By volume, URL Filtering leads. By growth pace, DNS Security is gaining share fastest as TLS 1.3 and encrypted DNS protocols dismantle traditional deep-packet inspection architectures.
Deployment:
Cost tier stratification separates capital-intensive appliance purchases from operational expenditure cloud subscriptions, with hybrid configurations capturing buyers seeking data residency controls without full infrastructure ownership.
- Cloud-Based:Delivers filtering through geographically distributed proxy infrastructure with auto-scaling throughput capacity and zero on-premises hardware footprint. Mid-market buyers in the United States and Germany are expanding procurement fastest, attracted by consumption-scaled pricing and automatic feature tier upgrades that compress revenue recognition cycles for vendors while extending account lifetime value.
- On-Premises:Deploys dedicated appliances within organizational network boundaries for complete traffic inspection and local policy enforcement. Regulated sectors in Germany and India maintain stronghold demand here, where GDPR data-processing restrictions and the Digital Personal Data Protection Act's localization requirements block pure cloud architectures.
- Hybrid:Combines edge appliance inspection with cloud intelligence feeds for policy synchronization across distributed locations.
- Software-as-a-Service:Packages filtering as browser-integrated or endpoint-resident agents without network infrastructure dependency.
By installed base, On-Premises retains plurality share. By expansion trajectory, Cloud-Based deployment is climbing the fastest among buyers lacking internal security operations centers.
End User:
Application context determines feature prioritization — threat detection depth versus compliance documentation granularity versus student safety response time — with each vertical imposing distinct procurement evaluation criteria.
- Enterprises:Demand identity-bound policy enforcement integrated with Zero Trust Network Access architectures, replacing perimeter gateway inspection with session-authenticated filtering. United States-based financial services and technology firms anchor this segment, compelled by SEC cybersecurity disclosure rules and HIPAA obligations for healthcare cloud migrations.
- Educational Institutions:Require real-time keyword monitoring and suicide-prevention alerting with mandatory reporting workflows. Jurisdictions across the United States, Germany, and India are mandating these capabilities, expanding addressable demand beyond traditional enterprise cybersecurity budgets into dedicated student safety funding streams.
- Government Agencies:Prioritize sovereign infrastructure with domestic data residency and classified network isolation.
- Healthcare Providers:Need filtering that audits clinician access to external resources without disrupting clinical workflow integration during electronic health record cloud migrations.
By revenue contribution, Enterprises dominate. By procurement velocity, Educational Institutions show the steepest expansion trajectory driven by regulatory mandate proliferation.
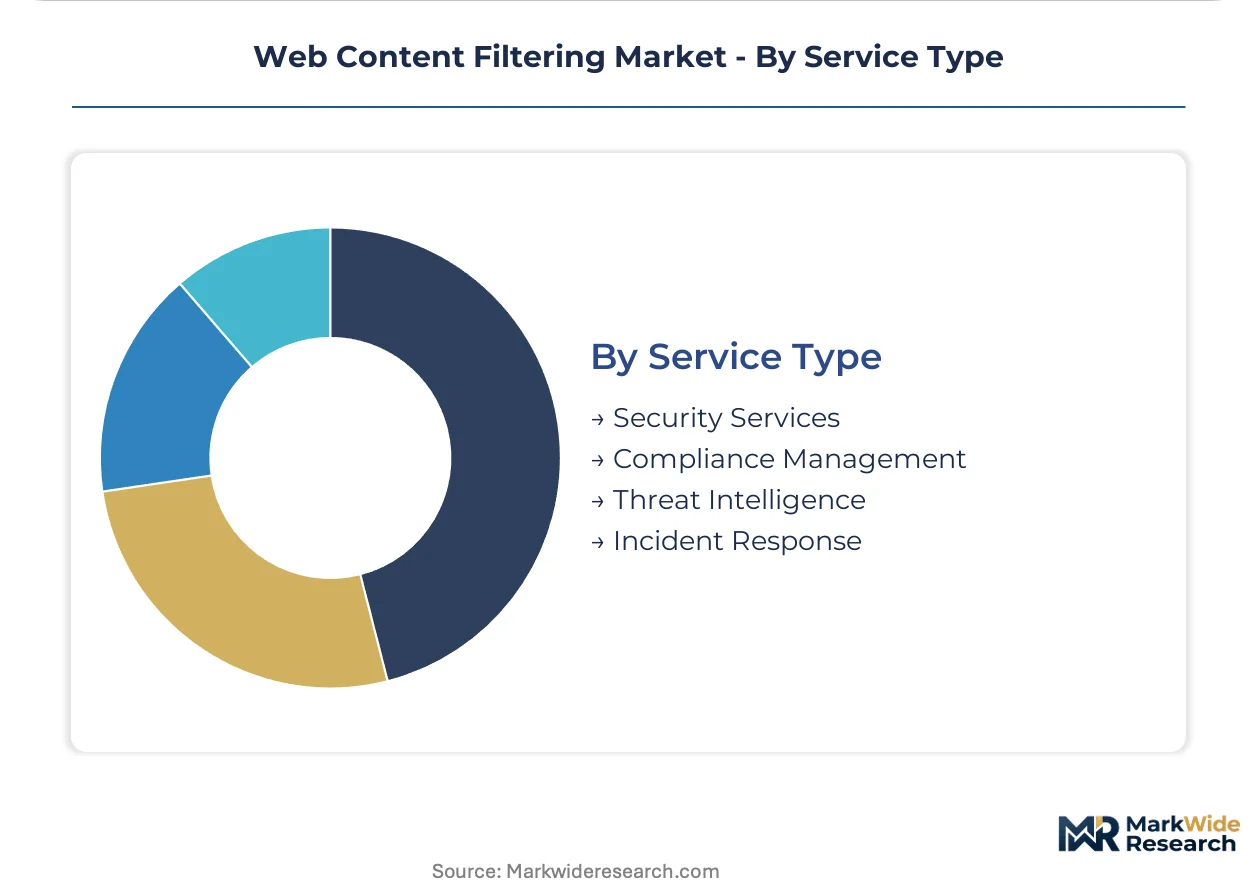
Service Type:
Customer capability gaps determine attachment rates — organizations lacking internal security operations centers outsource policy tuning and threat feed curation, while compliance-heavy verticals purchase documentation and audit preparation services.
- Security Services:Encompasses managed policy configuration, threat feed integration, and false-positive tuning delivered through recurring subscription. Managed Security Service Providers in the United States and Germany are capturing mid-market buyers, creating recurring revenue attachments beyond software licensing through outsourced security operations.
- Compliance Management:Provides algorithmic transparency documentation, model impact assessments, and audit trail preparation for regulatory examination. German and French enterprise buyers prioritize these services under the EU AI Act's conformity assessment requirements for high-risk automated classification systems.
- Threat Intelligence:Delivers curated indicator feeds and adversary infrastructure tracking for proactive defense.
- Incident Response:Supplies forensic investigation and containment support for filtering-bypass events or policy violations.
By attach rate, Security Services leads. By margin expansion, Compliance Management is expanding most quickly as the EU AI Act and GDPR enforcement intensify documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in web content filtering technologies tilt toward net-import dependence in Europe and Asia-Pacific, while the United States maintains trade surplus in cloud-native filtering services. Sovereign data requirements are fragmenting procurement patterns across jurisdictions.
United States
Federal cybersecurity mandates and SEC disclosure rules drive enterprise procurement of identity-bound filtering platforms. FCC net-neutrality frameworks constrain how vendors architect traffic inspection without privacy violations. Silicon Valley and Boston cybersecurity clusters concentrate cloud-native proxy development for mid-market buyers.
Germany
GDPR data-processing restrictions and the EU AI Act's conformity assessment requirements chill deployment confidence in URL logging practices. BSI cybersecurity certification programs shape vendor qualification criteria for federal procurement. Munich and Frankfurt financial services hubs anchor demand for algorithmic transparency documentation tools.
India
Data localization requirements under the Digital Personal Data Protection Act block foreign cloud-filtering architectures, opening space for domestic platform development. TRAI regulations on encrypted communications complicate DNS-based filtering deployment. Bengaluru and Hyderabad technology corridors concentrate sovereign infrastructure partnerships.
United Kingdom
Post-Brexit regulatory divergence from EU AI Act frameworks creates compliance complexity for multinational enterprises operating across jurisdictions. NCSC cybersecurity guidance shapes public sector filtering procurement specifications. London financial services and Manchester digital clusters drive Zero Trust Network Access adoption.
Japan
METI industrial cybersecurity guidelines mandate filtering integration with critical infrastructure protection frameworks. PMDA and JIS standards influence healthcare cloud migration security requirements. Tokyo and Osaka enterprise technology markets prioritize session-authenticated filtering over perimeter gateway inspection.
Web Content Filtering Market Competitive Environment
Concentration sits with diversified cybersecurity conglomerates that bundle filtering with adjacent network security products. The vendor base spans three tiers: networking hardware incumbents with edge-installed bases, cloud-native specialists with proxy-only architectures, and endpoint-security vendors extending into web traffic control. Strategic moves center on consumption-based licensing rotation and Zero Trust architecture integration to displace legacy secure web gateway deployments.
Within the networking-hardware tier, Cisco Systems, Inc. and Palo Alto Networks, Inc. exemplify platform consolidation strategies that embed filtering within broader security stacks. Zscaler, Inc. occupies a distinct position as a cloud-native archetype eliminating on-premises dependency entirely. These three anchors represent divergent architectural bets as encrypted protocols dismantle traditional deep-packet inspection.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Palo Alto Networks, Inc. |
| Fortinet, Inc. |
| Barracuda Networks, Inc. |
| McAfee Corp. |
| Symantec Corporation |
| Zscaler, Inc. |
| Forcepoint LLC |
| Trend Micro Incorporated |
| Others |
Value Chain & Pricing Dynamics
FPGA fabrication scale economies in Taiwan and South Korea concentrate SSL inspection accelerator supply, compressing unit economics for high-throughput appliance vendors while elevating price floors for cloud-native alternatives that bypass hardware dependency entirely. This capacity concentration shapes procurement bifurcation between capital-intensive edge deployments and operational expenditure cloud subscriptions.
Pricing Analysis
Enterprise cybersecurity teams anchor subscription-based SaaS pricing across cloud-native filtering platforms, with three-tier pricing structure across premium, standard, and economy levels differentiated by throughput capacity and compliance documentation granularity. Price differentiation stems from EU AI Act certification tier and geographic data residency configuration. Pricing pressure intensifies as encrypted DNS protocols erode DNS-based filtering value propositions. Educational institutions exhibit highest price sensitivity due to dedicated student safety funding constraints, while healthcare providers demonstrate lowest sensitivity given HIPAA-mandated audit requirements.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites supply risk for specialized SSL inspection hardware, with Taiwan, South Korea, and the United States concentrating FPGA and ASIC fabrication capacity. Component dependencies include programmable logic devices, high-bandwidth memory modules, and cryptographic acceleration cores. Single-source vulnerability in Taiwan-based foundry capacity exposes appliance vendors to extended lead times. Distribution runs through value-added resellers for on-premises hardware and direct cloud-native subscriptions for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
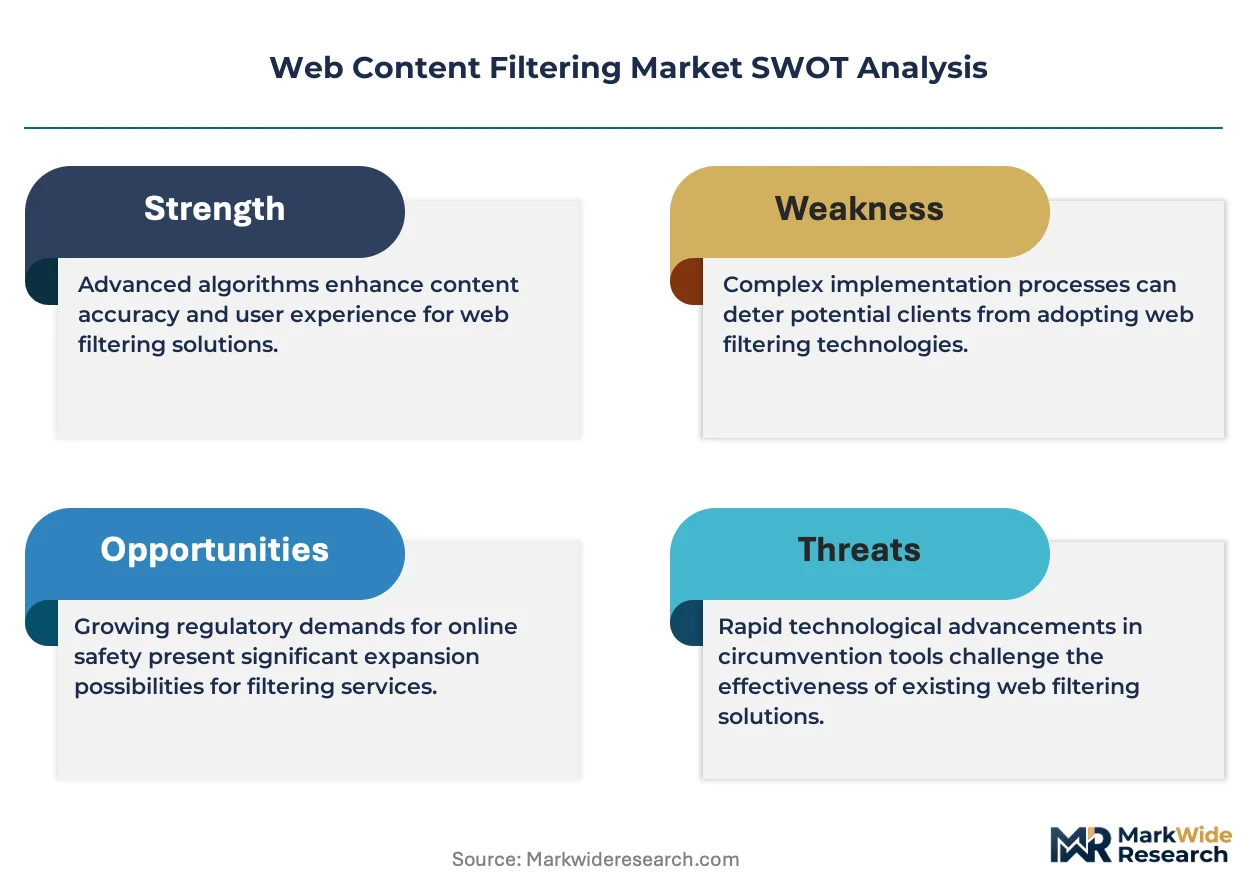
Browser-native encrypted DNS from Cloudflare and Google threatens to substitute organizational filtering controls entirely, forcing incumbents to defend through endpoint-integrated policy enforcement and identity-bound architectures.
For Market Incumbents: Compound defensive positioning through backward integration into endpoint agent development and algorithmic transparency tooling that satisfies EU AI Act conformity assessments. Certificate pinning breakage risks and ML model explainability gaps represent immediate threats requiring R&D redirection toward browser-integrated policy enforcement rather than inline decryption. For New Entrants and Emerging Players: Differentiate on sovereign infrastructure compliance for India and Germany data localization mandates, targeting domestic platform partnerships blocked to foreign cloud architectures. The most penetrable white-space sits in managed security service provider channels for mid-market buyers lacking internal SOC capability, with go-to-market execution through compliance-documentation bundling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native proxy specialists with pre-built EU AI Act documentation frameworks over hardware-dependent appliance vendors facing encrypted protocol obsolescence. Long-term viability hinges on Zero Trust architecture integration depth. Acquisition target archetype: compliance-automation platforms with CE marking pathways. The signal to watch is DNS-over-HTTPS browser adoption rates as inflection indicator for DNS-based filtering revenue erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding filtering within Zero Trust Network Access architectures displaces legacy secure web gateway procurement. |
| Compliance Certification | EU AI Act CE marking and algorithmic impact assessments unlock German and French federal procurement channels. |
| Geographic Expansion | Domestic infrastructure partnerships in India satisfy Digital Personal Data Protection Act localization mandates. |
| Strategic Partnership | Managed security service provider alliances capture mid-market buyers outsourcing policy tuning and threat curation. |
| Product Launch | Browser-integrated policy agents bypass encrypted DNS substitution without certificate interception breakage. |
Study Parameters
Desk research of regulatory filings, hyperscaler infrastructure disclosures, and cybersecurity vendor SEC submissions preceded structured interviews with CISOs, network security architects, managed security service provider operations leads, and educational technology procurement officers. Primary fieldwork across the United States, Germany, and India validated deployment pattern assumptions. Secondary sources included FCC net-neutrality frameworks, EU AI Act conformity assessment guidelines, TRAI encrypted communications regulations, and BSI cybersecurity certification databases. Bottom-up sizing of vendor-reported subscription metrics and top-down triangulation against enterprise IT security budget allocations anchored value estimates.
Variance decomposition across technology, deployment, end user, and service type segments structured the analytical framework throughout the forecast period. Modeled dimensions encompassed inspection depth capability, infrastructure ownership model, organizational vertical, and compliance service attachment. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included K-12 student safety mandate proliferation timelines and healthcare cloud migration velocity for HIPAA-covered entities.
Decision-makers should treat outputs as directional under assumptions of sustained TLS 1.3 adoption and stable EU AI Act enforcement intensity; material deviation in encrypted DNS browser integration rates or data localization regulation scope would warrant model refresh. Practitioners should keep alternative scenarios live as sovereign infrastructure requirements and machine-learning classification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Bot Mitigation Market
Security Software
Parental Control Software Market
Security Software
Global Mobile Identification Market
Security Software
Global Software-Defined Security Market
Security Software
Data Leakage Prevention Product Market
Security Software
Spam Blocking Software Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Key Management Service Market
Security Software
Home Webcam Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Global Enterprise Key Management Market
Security Software
Global Mobile Security Software Market
Security Software
Secaas Market
Security Software
Global User Activity Monitoring Market
Security Software
Identity and Access Management (IAM) Market