
 Europe Enterprise Firewall Market | 2026-2036
Europe Enterprise Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Enterprise Firewall Market Foresight
Managed security service revenue is rewriting how European enterprises consume firewall protection, shifting capital expenditure into operational contracts. Palo Alto Networks sustains technology leadership in cloud-native firewall platforms across continental Europe. Fortinet leverages its integrated security fabric to dominate mid-market banking deployments in France and Italy. Check Point Software Technologies anchors its position through deep channel control and government certification pathways.
Europe Enterprise Firewall denotes network security appliances and software platforms that inspect, filter, and log traffic between trusted internal networks and untrusted external zones using stateful inspection, application awareness, and intrusion prevention capabilities. These systems enforce access policies, block malicious payloads, and generate compliance audit trails for regulated organizations. Cloud-based solutions now represent the fastest-expanding deployment model as enterprises migrate workloads to distributed infrastructure. Hardware appliances retain the largest installed base among large enterprises with legacy data center footprints. The finance vertical concentrates the highest security spending intensity due to PSD2 and DORA compliance obligations.
The EU NIS2 Directive and GDPR framework compel critical infrastructure operators and data processors to implement certified boundary protection, directly expanding mandatory procurement pools. ETSI cybersecurity standards and CE marking requirements shape product certification timelines and cross-border market access for vendors. Stakeholders must monitor how the EU AI Act intersects with automated threat detection capabilities to anticipate compliance redesign cycles.
Market Dynamics
The EU NIS2 Directive is compressing procurement cycles for certified firewall platforms across critical infrastructure operators, forcing rapid hardware refresh decisions before compliance deadlines crystallize in late 2024.
Growth Catalysts
- PSD2 and DORA frameworks:Financial institutions in Germany and France must deploy application-aware inspection capabilities to satisfy transaction security mandates, expanding next-generation firewall procurement pools.
- Automotive manufacturing corridors:Connected vehicle production lines in Stuttgart and Wolfsburg require segmented network architectures that hardware firewalls with industrial protocol support uniquely satisfy.
- Cloud workload migration:Distributed infrastructure deployments are pulling virtual firewall instances into hybrid architectures alongside physical appliances.
Market Restraints
- Semiconductor supply concentration:Specialized packet-processing chipsets depend on Taiwanese foundry capacity, creating 18-24 week lead time volatility for high-throughput appliances.
- ETSI certification timelines:Common Criteria evaluation cycles extend product launch windows by 8-14 months, delaying revenue recognition for vendors.
- Managed security service substitution:Operational expenditure contracts for firewall-as-a-service are compressing direct appliance sales to mid-market enterprises.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Eastern European industrial automation investments lack mature security postures, creating greenfield deployment opportunities for integrated firewall platforms.
- EU AI Act intersection:Automated threat detection modules will require algorithmic transparency documentation, opening compliance consulting adjacencies for vendors with interpretable ML pipelines.
- Operational technology convergence:Firewall vendors bundling industrial control system protocol inspection with standard enterprise features can capture unified budget pools from CISO and plant manager stakeholders.
Industry Challenges
- Certified security architect scarcity:Enterprises struggle to source personnel with both CISSP credentials and hands-on experience configuring hybrid cloud-native and hardware-based perimeter defenses.
- Legacy mainframe integration:Banking and insurance incumbents in London and Frankfurt require custom policy translation layers to bridge decades-old transaction systems with modern zero-trust architectures.
- Cross-border data sovereignty:GDPR Article 44 restrictions complicate centralized security operations center deployments for multinational enterprises with distributed European subsidiaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Enterprise Firewall Market |
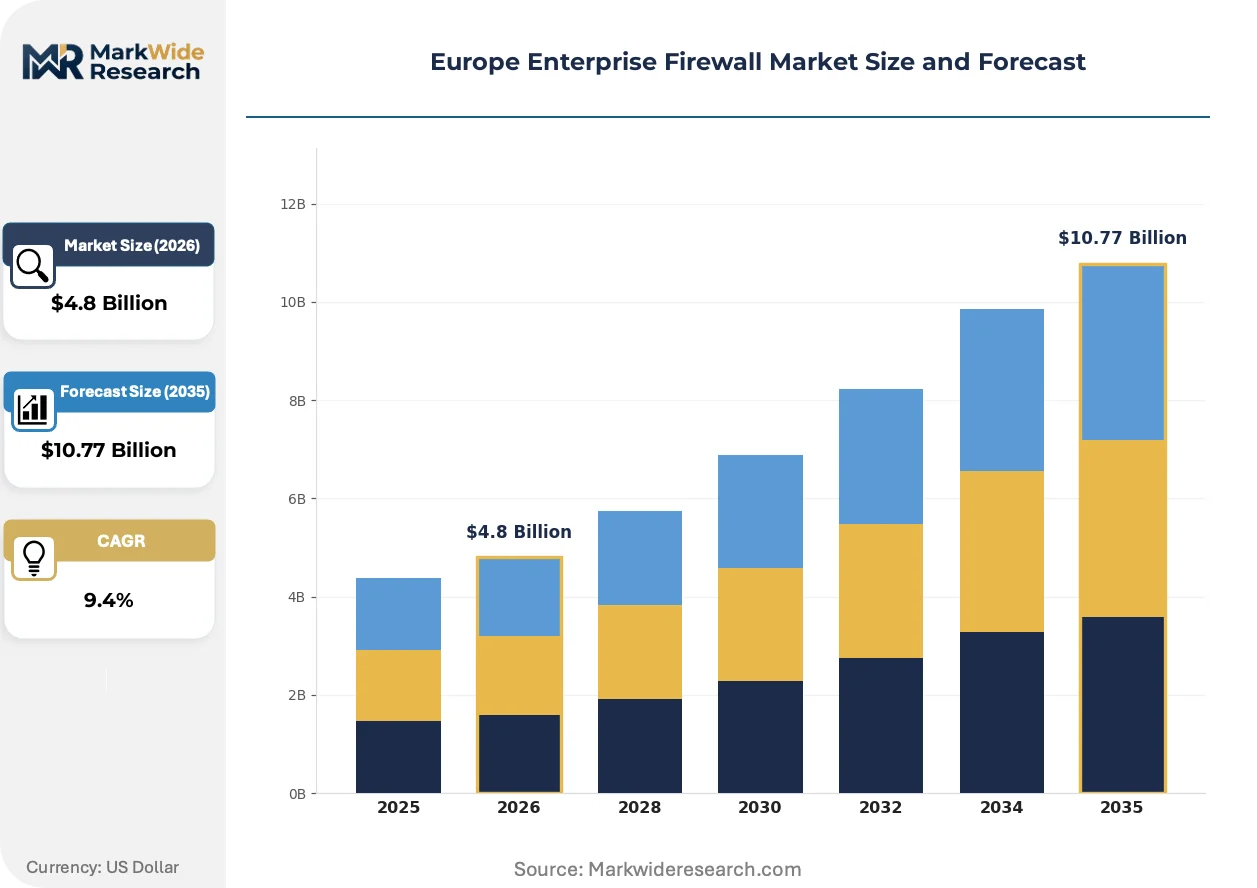
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hardware, Software, Cloud-Based, Hybrid Deployment Model: On-Premises, Hosted, Managed Service, Virtual Appliance End User: SMEs, Large Enterprises, Government, Educational Institutions Industry Vertical: Healthcare, Finance, Retail, Telecommunications |
| Companies Covered | Cisco Systems Inc., Palo Alto Networks Inc., Fortinet Inc., Check Point Software Technologies Ltd., Dell Inc., Sophos Group PLC, Juniper Networks Inc., Barracuda Networks Inc., SonicWall Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Enterprise Firewall Market Shifts & Advancements
Firewall functionality is fragmenting across multiple enforcement points as microsegmentation and cloud-native controls displace monolithic perimeter appliances. Vendors are racing to unify policy orchestration across these distributed enforcement layers.
Zero-trust network access architectures are migrating from pilot deployments to production mandates. Large German automotive groups and French banking consortiums are removing implicit trust from internal network segments. This migration is compressing standalone VPN appliance markets while expanding software-defined perimeter licensing.
The EU AI Act's risk classification system for automated decision-making systems is reshaping product development roadmaps for threat detection vendors. High-risk cybersecurity AI applications will face conformity assessment procedures before CE marking. French and Dutch critical infrastructure operators are already demanding algorithmic audit trails from suppliers.
Consumption models for firewall protection are fragmenting between capital expenditure hardware refresh cycles and operational expenditure managed detection contracts. Mid-market enterprises in Italy and Spain are unbundling appliance procurement from monitoring services, selecting point solutions from competing vendors. This unbundling is pressuring integrated security fabric pricing strategies in Southern European markets.
Europe Enterprise Firewall Market Segmentation
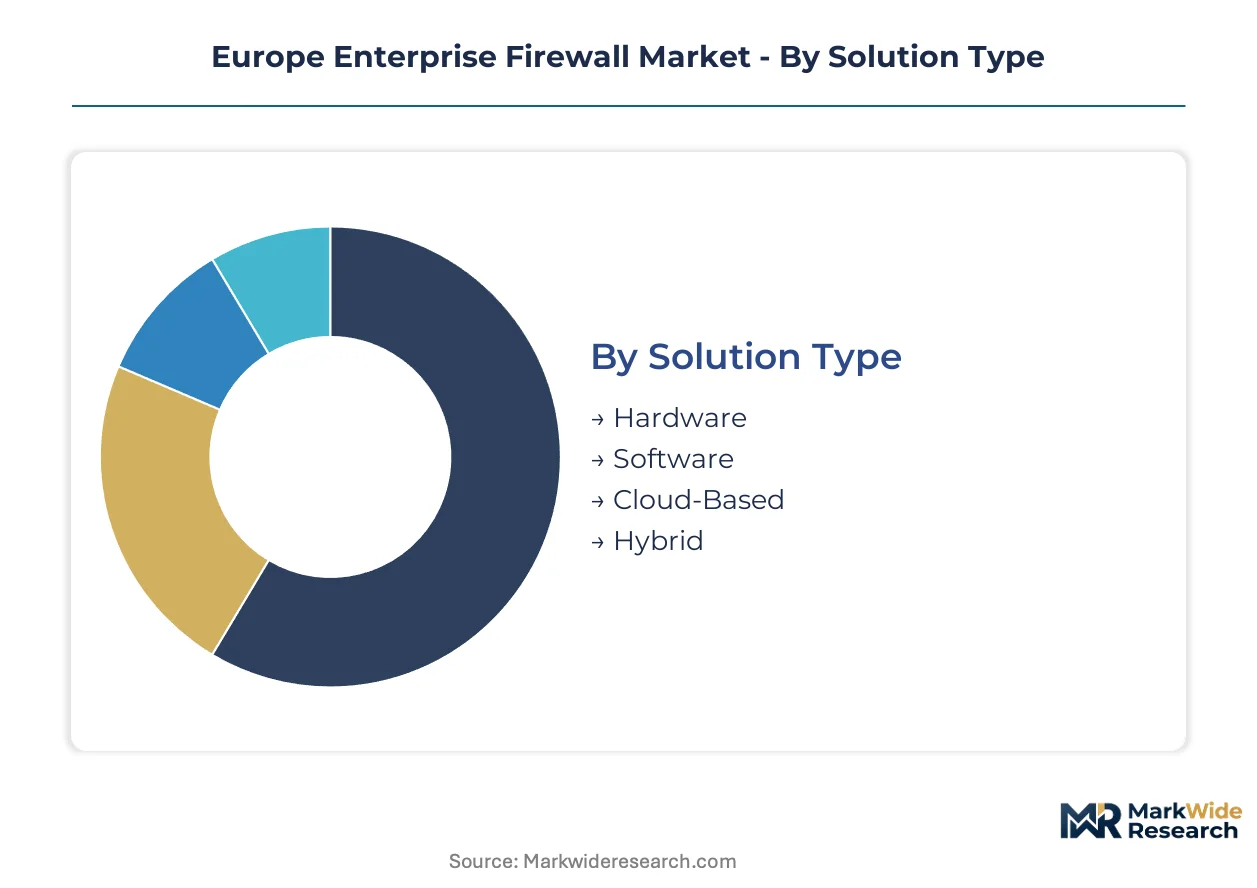
European firewall procurement patterns fragment sharply across infrastructure maturity and compliance exposure. Solution architecture, delivery mechanism, and buyer risk profiles each create distinct commercial battlegrounds for vendors.
Solution Type:
Mature hardware installations coexist with emerging cloud-native deployments as enterprises straddle legacy and transformed infrastructure.
- Hardware:Purpose-built appliances with dedicated packet-processing chipsets handle high-throughput inspection for data centers. German automotive manufacturers in Stuttgart and Wolfsburg rely on these for industrial protocol segmentation under EU NIS2 mandates.
- Cloud-Based:Virtual firewall instances scale elastically across distributed workloads. French banking consortiums migrating to multi-cloud architectures are pulling these into hybrid security fabrics fastest.
- Software:Deployable on commodity servers, these solutions appeal to cost-conscious mid-market buyers. Italian SMEs favor them for branch office protection without appliance refresh cycles.
- Hybrid:Unified policy orchestration across physical and virtual enforcement points. UK financial services firms use these to bridge on-premises transaction systems with cloud-native applications.
Hardware handles the majority of throughput; cloud-based is the fastest mover on share.
Deployment Model:
Cost tier separation distinguishes capital-intensive ownership from operational expenditure flexibility.
- Managed Service:Third-party operators assume monitoring, patching, and policy tuning. Spanish and Portuguese mid-market enterprises are shifting procurement here to bypass certified security architect scarcity.
- On-Premises:Direct appliance ownership with internal operations teams. German critical infrastructure operators prefer this model for air-gapped control system environments.
- Virtual Appliance:Pre-configured software images deployable on hypervisors. Dutch cloud-first enterprises use these for rapid workload spin-up in distributed architectures.
- Hosted:Provider-managed infrastructure with customer-defined policies. Eastern European manufacturing greenfield sites adopt these to accelerate security posture maturity.
On-premises retains the largest installed base; managed service is climbing the fastest.
End User:
Volume concentration and margin structure diverge sharply across organizational scale and regulatory exposure.
- Large Enterprises:Complex multi-site deployments with dedicated security operations centers. These buyers command the deepest vendor negotiation leverage and longest evaluation cycles.
- Government:National and EU-level certification requirements dominate procurement. Common Criteria evaluation and CE marking compliance filter vendor pools aggressively.
- SMEs:Resource-constrained buyers prioritizing operational simplicity over feature depth. Managed security service penetration is highest in this tier.
- Educational Institutions:Research network protection with open academic access constraints. These deployments emphasize identity-aware policy enforcement.
Large enterprises absorb the greatest absolute spending; government is gaining share fastest amid NIS2 compliance deadlines.
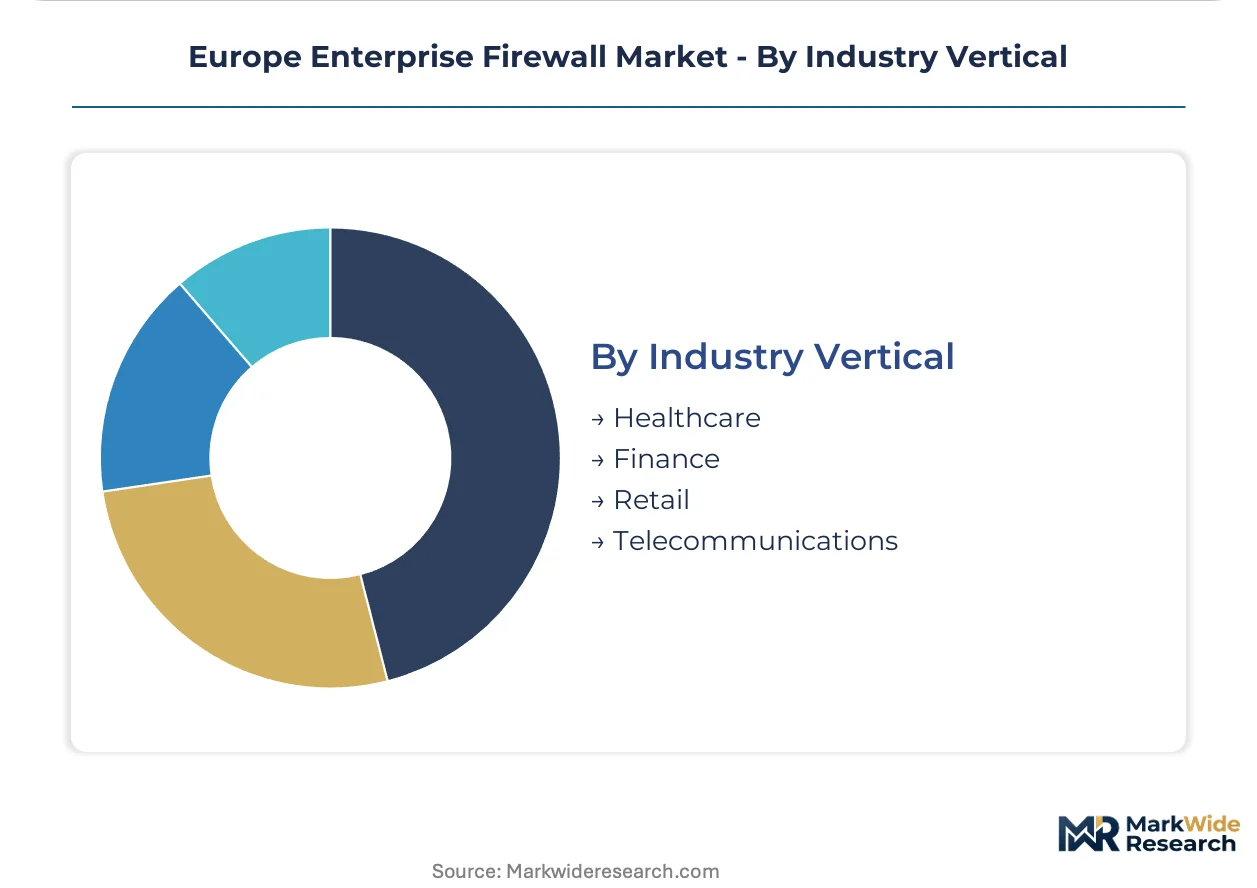
Industry Vertical:
Application-specific risk profiles and regulatory frameworks shape technology requirements and budget authority.
- Finance:Transaction integrity mandates under PSD2 and DORA drive application-aware inspection investment. German and French institutions lead procurement intensity.
- Healthcare:Patient data protection under GDPR Article 9 creates stringent audit trail requirements. These buyers prioritize logging granularity and breach notification automation.
- Telecommunications:Network edge scale and 5G core security expand virtual firewall demand. Operators face NIS2 designation as critical infrastructure.
- Retail:Seasonal traffic spikes and payment card environment segmentation dominate needs. E-commerce concentration in UK and Scandinavian markets pulls cloud-native solutions.
Finance commands the highest security spending intensity; telecommunications is expanding most quickly on infrastructure rollout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across European firewall procurement, with Southern European mid-market buyers demanding operational expenditure flexibility while German critical infrastructure operators absorb premium hardware premiums for air-gapped certification compliance.
Germany
Automotive manufacturing corridors in Stuttgart and Wolfsburg drive demand for industrial protocol segmentation. The EU NIS2 Directive compels certified hardware refresh cycles across energy and transport operators. Frankfurt's banking concentration anchors application-aware inspection investment for DORA compliance deadlines.
France
French banking consortiums migrating to multi-cloud architectures accelerate virtual firewall procurement. The EU AI Act's risk classification system reshapes vendor selection criteria for automated threat detection. Paris-based critical infrastructure operators now demand algorithmic audit trails from security suppliers.
United Kingdom
London financial services firms bridge legacy transaction systems with cloud-native applications through hybrid deployments. GDPR Article 44 cross-border data restrictions complicate centralized security operations center designs. The UK National Cyber Security Centre certification pathway filters government procurement pools aggressively.
Italy
Italian SMEs favor software firewall deployments for branch office protection without capital-intensive appliance cycles. Managed security service penetration peaks here as buyers bypass certified security architect scarcity. Milan's financial services sector concentrates mid-market next-generation firewall adoption.
Poland
Eastern European manufacturing greenfield sites adopt hosted firewall models to accelerate security posture maturity. EU structural funds for industrial automation create greenfield deployment opportunities. Warsaw's emerging fintech cluster pulls cloud-native protection into hybrid architectures.
Europe Enterprise Firewall Market Competitive Landscape
Cloud-native specialists and integrated security fabric providers split the European enterprise firewall market between architectural philosophies. The vendor landscape concentrates around three strategic archetypes: platform consolidators bundling multiple security functions, pure-play firewall specialists defending feature depth, and networking incumbents leveraging existing infrastructure relationships. Dominant competitive moves include strategic partnerships with managed security service providers and geographic expansion into Eastern European manufacturing corridors.
Within the platform consolidator tier, Palo Alto Networks and Fortinet occupy positions exemplifying divergent approaches to cloud-native integration, while Cisco Systems anchors the networking incumbent archetype through infrastructure relationship leverage. Check Point Software Technologies sits within the specialist tier, representing deep channel control and government certification pathway strategies. These three companies collectively illustrate how vendor positioning fragments across architectural philosophy rather than geographic origin.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Palo Alto Networks Inc. |
| Fortinet Inc. |
| Check Point Software Technologies Ltd. |
| Dell Inc. |
| Sophos Group PLC |
| Juniper Networks Inc. |
| Barracuda Networks Inc. |
| SonicWall Inc. |
| Others |
Supply & Pricing Matrix
Taiwanese foundry concentration for packet-processing chipsets creates 18-24 week lead time volatility that compresses hardware pricing spreads between certified premium tiers and standard configurations while forcing buyers into longer-term supply commitments. This single-source dependency simultaneously widens margin capture for vendors with secured wafer allocation and accelerates managed security service substitution among mid-market buyers seeking operational expenditure flexibility.
Pricing Analysis
Managed security service contracts now drive lifetime value beyond initial appliance sales, with recurring monitoring and policy tuning revenue streams outpacing hardware margin trajectories. Three-tier pricing structure across premium, standard, and economy levels separates EU NIS2-certified platforms with Common Criteria evaluation from uncertified alternatives and entry-level software deployments. Cost compression in mid-market hardware stems from firewall-as-a-service unbundling in Italy and Spain. Government and critical infrastructure buyers in Germany absorb premium pricing for air-gapped certification compliance, while Spanish and Portuguese SMEs exhibit highest price sensitivity.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit Taiwanese foundry capacity expansion and constrain specialized packet-processing chipset availability for European firewall vendors. Supply concentration centers on Taiwan for advanced silicon, South Korea for memory components, and China for commodity server hardware. Raw material dependencies include silicon wafers, high-bandwidth memory modules, and specialized ASIC designs. Single-source vulnerability in Taiwanese foundry capacity creates procurement risk amplification. Distribution runs through authorized channel partners with government certification pathways and direct enterprise sales teams for large account coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
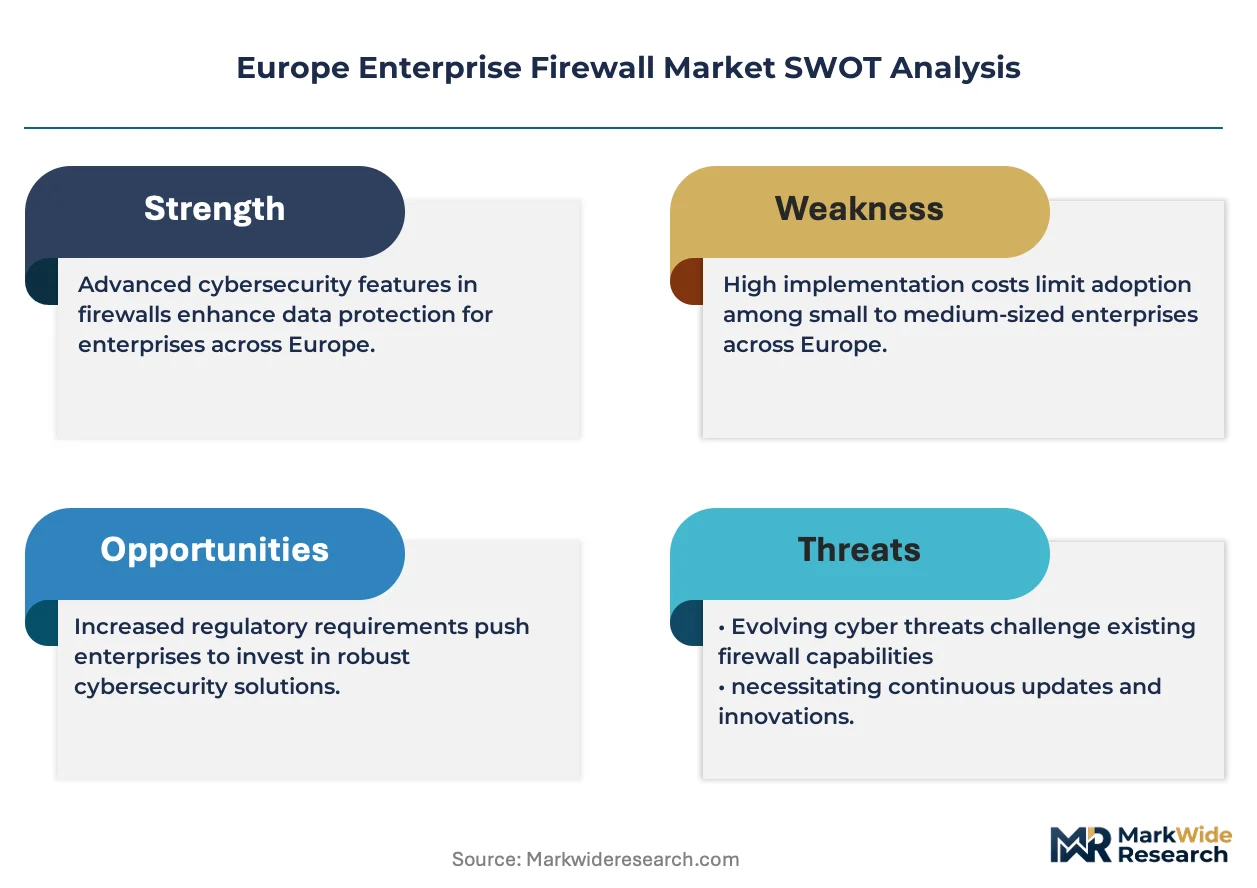
Europe's enterprise firewall market functions as a defensive-moat arena where regulatory entrenchment through EU NIS2 certification pathways creates sustainable competitive positioning. Switching costs compound as certified security architects become scarcer and hybrid architecture complexity deepens.
For Market Incumbents: Insulate market position by deepening vertical integration into managed security service delivery to capture operational expenditure migration, and accelerate certification investment for EU AI Act algorithmic transparency requirements. Cloud-native specialists threaten hardware-centric revenue streams. Channel control and government certification pathways anchor defensive leverage. For New Entrants and Emerging Players: Mid-market manufacturing corridors in Poland and Czech Republic represent the most penetrable entry point, with EU structural funds financing greenfield security deployments lacking incumbent relationships. Hosted firewall models accelerate time-to-revenue without certification timeline delays. Partner-centric go-to-market through Eastern European system integrators bypasses direct sales infrastructure requirements. For Investors and Strategic Acquirers: The market sits at a compliance-driven refresh phase that favors platform consolidators with multi-product bundling capability. Long-term viability across the projection horizon rests on unified policy orchestration across distributed enforcement layers. Acquisition targets with interpretable ML pipelines for automated threat detection align with EU AI Act trajectory. Watch for NIS2 deadline acceleration as inflection indicator for procurement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies policy orchestration across hardware, virtual, and cloud-native enforcement points for hybrid architectures. |
| Strategic Partnership | Managed security service provider alliances capture operational expenditure migration in Southern European mid-markets. |
| Acquisition of Specialist Firm | Industrial control system protocol expertise enables OT/IT convergence budget capture from manufacturing buyers. |
| Geographic Expansion | Eastern European manufacturing corridors offer greenfield deployment opportunities with EU structural fund tailwinds. |
| Product Launch | Algorithmic transparency documentation for EU AI Act compliance opens French and Dutch critical infrastructure procurement. |
Research Methodology
Desk research of regulatory filings, vendor certification databases, and trade flow records preceded structured interviews with CISOs at German automotive manufacturers, security architects at French banking consortiums, channel partners in Italy and Spain, and procurement officers at Polish manufacturing sites. Secondary validation drew from EU NIS2 implementation guidance, ETSI cybersecurity standards documentation, and hyperscaler infrastructure disclosure reports. Bottom-up segmentation sizing and top-down macro constraint checks ensured triangulation integrity.
Assumptions held fixed include EU NIS2 compliance deadline adherence, semiconductor foundry capacity allocation patterns, and GDPR enforcement continuity across member states. Variables modeled encompass cloud workload migration velocity, managed security service penetration rates, and OT/IT convergence investment cycles. CAGRs derive from segment-level demand elasticity and vendor pricing power assessments. Forecast inputs include firewall-as-a-service subscription growth curves and hardware refresh cycle compression under regulatory mandates.
Macroeconomic conditions sit as an overlay; deviation in eurozone industrial investment, semiconductor trade flows, or EU regulatory enforcement intensity would shift the trajectory. Material shifts in EU AI Act implementation timelines or NIS2 penalty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Security Software
Data Leakage Prevention Product Market
Security Software
Network Camera and Video Analytics Market
Security Software
Home Webcam Market
Security Software
Global Electronic Passports Market
Security Software
Key Management Service Market
Security Software
IAM Security Services Market
Security Software
United States Lawful Interception Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Global Enterprise Key Management Market
Security Software
Content Protection and Watermarking Market
Security Software
Secure Digital Card Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Global Visitor Management System Market