
 Security Software for Consumers Market | 2026-2036
Security Software for Consumers Market Size, Share, and Industry Trends Forecast 2026-2036
Security Software for Consumers Market Analysis
Subscription renewal revenue is reshaping how consumer security vendors allocate engineering resources. Microsoft leverages its Windows ecosystem to bundle endpoint protection at scale. Bitdefender anchors its position through advanced threat detection engines that compete on independent test scores. Norton sustains brand recognition among family subscribers through identity theft coverage and parental controls.
Security software for consumers encompasses applications designed to detect, prevent, and remediate malicious code, unauthorized network intrusions, and data exfiltration on personal computing devices, typically employing signature-based detection, heuristic analysis, and real-time behavioral monitoring with automated update cycles. The primary commercial purpose is to protect individual users from financial fraud, identity theft, and privacy breaches while maintaining system performance. Antivirus and anti-malware suites command the largest installed base, though VPN deployments are expanding fastest as consumers confront public Wi-Fi risks and geo-restricted content access. Cloud-based and SaaS delivery models now dominate new subscriptions, while freemium pricing structures serve as the dominant customer acquisition funnel for paid tier conversion.
The FTC enforces truth-in-advertising standards for cybersecurity claims, while GDPR and the EU AI Act impose algorithmic transparency obligations on vendors processing European consumer data. These frameworks elevate compliance costs but also create barriers against low-integrity entrants who misrepresent protection capabilities. Stakeholders must monitor how generative AI tools lower the barrier for sophisticated phishing campaigns, forcing continuous recalibration of detection heuristics and user education investments.
Market Dynamics
Generative AI tools are compressing the sophistication gap between amateur and professional threat actors, forcing consumer security vendors to accelerate behavioral detection engine development while absorbing elevated cloud infrastructure costs.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic accountability requirements are elevating vendor investment in explainable threat detection, creating competitive differentiation for compliant providers.
- Multi-device household proliferation:Family subscribers now average fourteen connected endpoints per residence, expanding addressable license volume per account.
- Remote work normalization:Persistent hybrid employment patterns sustain elevated consumer cybersecurity consciousness and willingness-to-pay for premium tiers.
Market Restraints
- Cloud infrastructure cost volatility:Real-time behavioral analysis consumes substantial compute resources, compressing gross margins during energy price spikes.
- Platform bundling concentration:Operating system vendors integrating baseline protection threaten standalone vendor pricing power and customer acquisition economics.
- Freemium conversion ceiling:Limited differentiation between free and paid tiers restricts upgrade rates among price-sensitive user segments.
Strategic Opportunities
- Identity protection service bundling:Credit monitoring and dark web surveillance integration commands premium pricing from family subscribers concerned with financial fraud.
- Generative AI defense modules:Deepfake detection and AI-generated phishing identification represent nascent attachable revenue streams.
- Cross-platform consolidation:Unified protection across mobile, desktop, and IoT endpoints reduces vendor fragmentation for overwhelmed consumers.
Industry Challenges
- Adversarial ML expertise scarcity:Recruitment of machine learning security researchers lags behind threat actor automation capabilities.
- False positive calibration:Aggressive heuristic settings degrade user experience and drive uninstalls; conservative settings miss novel threats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Software for Consumers Market |
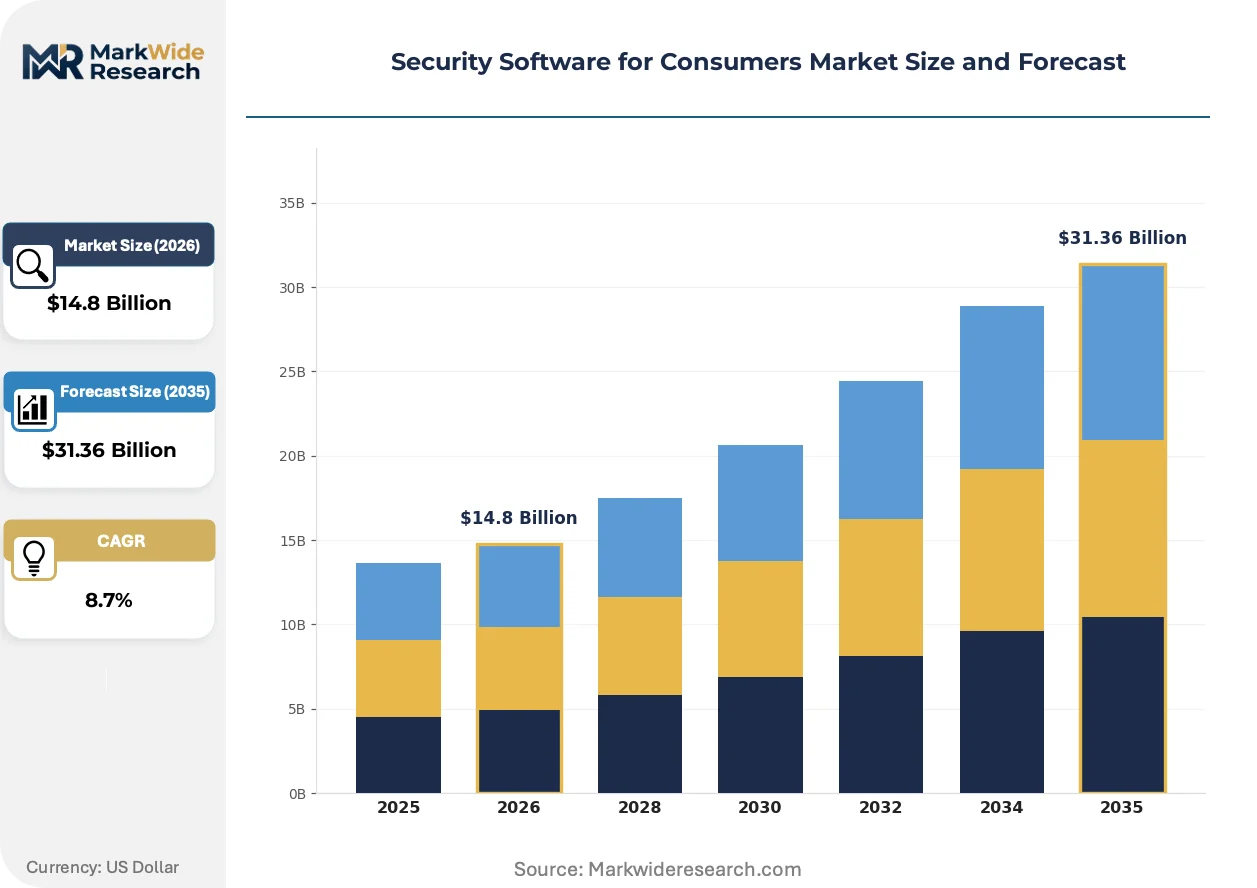
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirus, Firewall, VPN, Anti-malware Deployment: On-premise, Cloud-based, Hybrid, SaaS End User: Individuals, Families, Small Businesses, Students Price Tier: Free, Subscription, One-time Purchase, Freemium |
| Companies Covered | Microsoft, McAfee, Norton, Gen Digital, Trend Micro, Bitdefender, Kaspersky Lab, Avast Software, F-Secure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Software for Consumers Market Emerging Trajectories
Behavioral detection architectures are supplanting signature-dependent systems as polymorphic malware renders static definition files obsolete. Three convergent developments are compressing vendor technology roadmaps and reshaping subscriber value propositions.
On-device neural inference is collapsing the latency advantage previously held by cloud-only scanning architectures. Edge-optimized threat models now process suspicious file behavior locally on consumer hardware, eliminating round-trip delays that degraded gaming and streaming performance. Family subscribers with bandwidth-constrained connections are migrating toward hybrid architectures that reserve cloud verification for ambiguous classifications.
The EU AI Act's algorithmic transparency obligations are compelling disclosure of automated decision logic in threat scoring systems. Vendors serving European consumers must document how behavioral heuristics classify benign versus malicious activity, elevating documentation burdens but creating defensible moats against low-integrity competitors. Compliance investments concentrate among mid-tier providers lacking in-house regulatory counsel.
Subscription fatigue is fragmenting renewal patterns across the consumer base. Households confronting stacked recurring charges for streaming, productivity, and security services are compressing evaluation cycles and demanding granular tier unbundling. United States subscribers exhibit highest propensity to downgrade from comprehensive suites to single-function applications when household budgets tighten.
Security Software for Consumers Market Segmentation
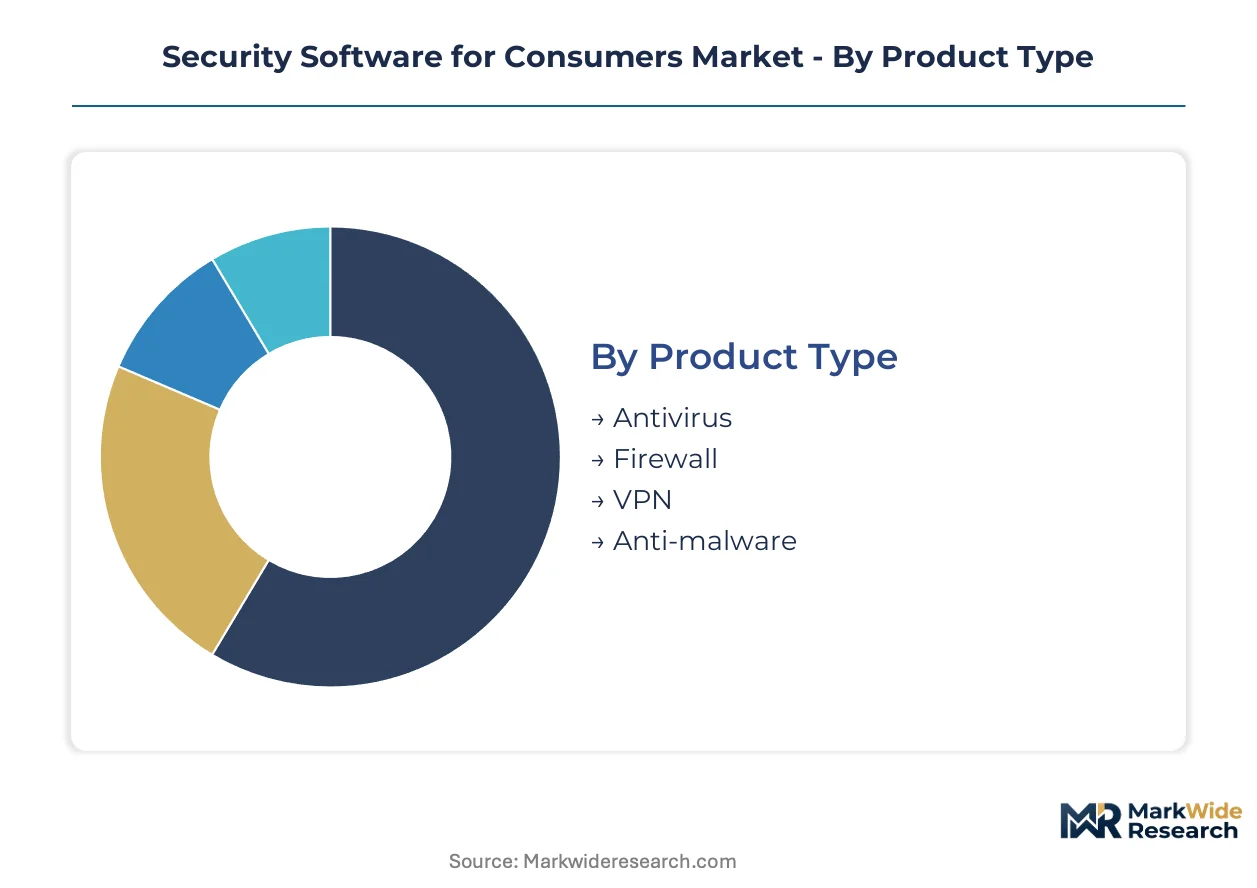
Consumer security software segments along four functional axes that determine vendor engineering priorities and customer acquisition economics. Each dimension reflects distinct technical requirements, pricing elasticity, and renewal pattern variation that shape competitive positioning.
Product Type:
Mature signature-based solutions anchor installed base volume while emerging behavioral engines capture upgrade spend from threat-conscious households.
- Antivirus:Signature-detection engines with automated definition updates protect against known malware strains. Family subscribers in the United States drive renewal concentration as multi-device licenses bundle parental controls and identity monitoring.
- Firewall:Network traffic inspection systems block unauthorized inbound connections and application-level data exfiltration. Remote workers confronting home network vulnerabilities sustain demand acceleration for hardware-integrated and software variants alike.
- VPN:Encrypted tunneling services mask IP addresses and secure public Wi-Fi sessions. Geo-restriction circumvention and streaming access sustain freemium conversion funnels.
- Anti-malware:Heuristic behavioral analysis targets zero-day exploits and polymorphic threats beyond signature databases. GDPR and EU AI Act compliance requirements elevate development costs for European deployment.
Antivirus handles the majority of throughput; anti-malware is climbing the fastest on share as signature-dependent systems lose efficacy against automated threat generation.
Deployment:
Cost tier stratification separates enterprise-grade infrastructure investments from lightweight consumer implementations.
- Cloud-based:Centralized threat intelligence and real-time behavioral analysis offload processing from consumer hardware. Energy price volatility compresses provider margins during demand spikes.
- SaaS:Subscription-native delivery with automatic feature updates and cross-platform license management. United States households show highest willingness-to-pay for integrated family dashboards.
- Hybrid:On-device inference for latency-sensitive operations with cloud verification for ambiguous classifications. Bandwidth-constrained subscribers favor this architecture for gaming and streaming performance preservation.
- On-premise:Local installation with manual update cycles retains relevance for privacy-maximalist users and air-gapped systems. FTC truth-in-advertising enforcement elevates documentation burdens for standalone vendors.
Cloud-based deployment absorbs the dominant share of new subscriptions; hybrid architectures are gaining share fastest among performance-sensitive family accounts.
End User:
Application context determines feature bundling complexity and support cost structure across subscriber types.
- Families:Multi-device protection averaging fourteen endpoints per residence with parental controls and identity theft coverage. EU AI Act transparency mandates complicate automated threat scoring explanations for European households.
- Individuals:Single-user licenses prioritizing performance minimalism and granular privacy settings. Price sensitivity drives highest freemium-to-paid conversion friction.
- Small Businesses:Crossover solutions blending consumer UX with business-grade compliance documentation. FTC cybersecurity claim enforcement elevates vendor liability exposure.
- Students:Discounted educational pricing with device-count limitations and campus network optimization. Seasonal purchasing patterns concentrate around academic calendar cycles.
Families generate the majority of recurring revenue; small business crossover accounts are expanding most quickly as remote work blurs consumer-commercial boundaries.
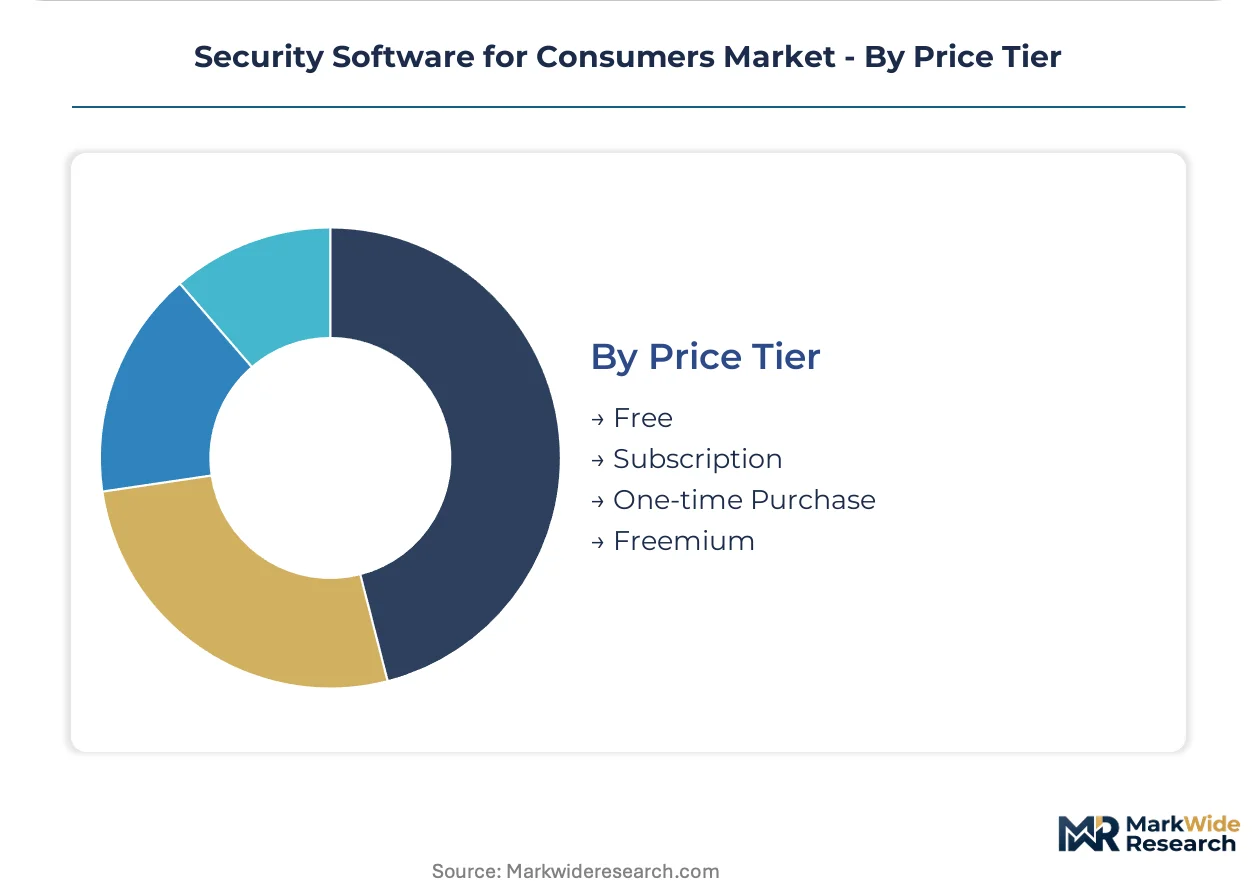
Price Tier:
Customer acquisition economics vary dramatically across monetization models that shape lifetime value calculations.
- Subscription:Recurring annual or monthly billing with continuous feature updates and threat intelligence feeds. United States subscribers exhibit highest renewal rates when identity protection services are bundled.
- Freemium:Baseline protection with feature-gated upgrade paths to premium tiers. Limited differentiation between free and paid functionality constrains conversion rates among price-sensitive segments.
- Free:Advertising-supported or data-monetized models serving as competitive moat against paid alternatives. GDPR data processing restrictions limit European deployment viability.
- One-time Purchase:Perpetual licenses with time-limited update support appealing to budget-constrained users. Platform bundling from operating system vendors threatens standalone pricing power.
Subscription billing captures the dominant share of vendor revenue; freemium models are expanding fastest as customer acquisition costs escalate in saturated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer cybersecurity spending exhibits stark demand elasticity variation across geographies. United States households demonstrate highest willingness-to-pay for premium bundled tiers, while price-sensitive markets in Southern Europe and Southeast Asia concentrate freemium adoption. Regulatory stringency in the European Union elevates compliance costs that reshape vendor go-to-market economics.
United States
Remote work normalization and multi-device household proliferation drive subscription renewal concentration. The FTC enforces truth-in-advertising standards for cybersecurity claims, elevating documentation burdens for standalone vendors. Silicon Valley and Seattle-Tacoma clusters host behavioral detection engineering centers serving North American subscriber bases.
Germany
Privacy-maximalist consumer preferences sustain demand for on-premise deployment variants with local data processing. GDPR and the EU AI Act impose algorithmic transparency obligations on vendors serving German households. Berlin and Munich cybersecurity hubs concentrate explainable AI research for compliant threat detection systems.
United Kingdom
Identity theft coverage and parental control bundling command premium pricing from family subscribers in Greater London and Southeast England. Post-Brexit regulatory divergence from EU AI Act creates compliance complexity for vendors maintaining cross-channel operations. Manchester and Edinburgh emerging as alternative engineering talent pools.
Japan
Mobile-first security consumption patterns dominate as smartphone-dependent households exceed desktop penetration. METI guidelines on consumer data protection shape vendor disclosure requirements for behavioral analytics. Tokyo-Osaka corridor concentrates cloud infrastructure investments serving Asia-Pacific latency requirements.
Australia
Public Wi-Fi security consciousness accelerates VPN deployment fastest among English-speaking markets. The Australian Competition and Consumer Commission scrutinizes subscription renewal practices and freemium tier differentiation claims. Sydney and Melbourne host regional headquarters for vendors targeting Oceania family subscriber expansion.
Security Software for Consumers Market Vendor Landscape
Capability concentration sits with specialized threat detection vendors; scale advantage sits with platform-integrated providers. The market structures around three tiers: operating system bundlers with captive distribution, independent security specialists competing on test scores, and regional players with localized compliance expertise. Dominant competitive moves include cross-platform license consolidation and identity protection service attach.
Among platform-integrated providers, Microsoft leverages Windows ecosystem distribution to anchor baseline protection penetration. Bitdefender and Norton exemplify the independent specialist tier, competing through advanced detection engine performance and family subscriber bundling respectively. These three occupy positions across the capability-scale spectrum without exclusive segment lock-in.
| Leading Market Players |
|---|
| Microsoft |
| McAfee |
| Norton |
| Gen Digital |
| Trend Micro |
| Bitdefender |
| Kaspersky Lab |
| Avast Software |
| F-Secure |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States and Ireland anchors cost structures for real-time behavioral analysis, concentrating margin pools with hyperscale providers who command premium compute pricing during demand spikes. Subscription renewal economics hinge on these upstream arrangements, forcing consumer security vendors to absorb volatility or pass through via tier restructuring.
Pricing Analysis
Subscription renewal revenue and identity protection service attach drive lifetime value for family subscriber accounts. Three-tier pricing structure across premium, standard, and economy levels segments households by endpoint count and bundled feature depth. Price differentiation rests on dark web surveillance scope and parental control granularity. Cost compression in mid-tier SaaS offerings is intensifying because hyperscaler egress fees are escalating. Individual license holders exhibit highest price sensitivity, while multi-device family plans show lowest downgrade propensity.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and Samsung Foundry hold dominant capacity for neural inference chips powering on-device threat detection. Engineering talent draws from Israel, Estonia, and Singapore where cybersecurity research clusters concentrate. Raw material dependencies include advanced node silicon, high-bandwidth memory modules, and specialized FPGA arrays. Single-source vulnerability runs through TSMC's 5nm and 3nm allocation priority for consumer edge devices. Distribution runs through direct-to-consumer digital storefronts and OEM preload agreements with hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as operating system bundling and cross-device interoperability standards compress standalone vendor addressable markets. Microsoft's Windows Security integration exemplifies this ecosystem shift.
For Market Incumbents: Insulate core detection engine differentiation through adversarial ML research investments in Berlin and Tel Aviv clusters. Deepen backward integration into threat intelligence data sourcing to reduce reliance on third-party feed providers. Platform bundling from Apple and Google threatens pricing power in mobile endpoint protection.
For New Entrants and Emerging Players: Establish a beachhead in small business crossover segments where remote work has blurred consumer-commercial security boundaries. Target privacy-maximalist households in Germany and Nordic markets with on-premise deployment variants. Lead with GDPR-compliant transparency dashboards as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward behavioral detection specialists with explainable AI compliance infrastructure already operational. Long-term viability favors vendors who can demonstrate algorithmic transparency documentation for EU AI Act enforcement. Monitor FTC cybersecurity claim enforcement actions as the signal to watch for regulatory escalation affecting customer acquisition economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform License Consolidation | Unifies protection across fourteen-device households, reducing vendor fragmentation for overwhelmed consumers. |
| Identity Protection Service Attach | Commands premium pricing from family subscribers concerned with financial fraud and dark web exposure. |
| Generative AI Defense Module Launch | Addresses deepfake detection and AI-generated phishing as nascent attachable revenue streams. |
| Strategic Partnership with Hyperscalers | Secures preferential cloud compute pricing for real-time behavioral analysis infrastructure. |
| Acquisition of Explainable AI Specialist | Accelerates EU AI Act compliance documentation for automated threat scoring systems. |
Methodological Framework
Initial hypotheses were tested against primary input from consumer security product managers, threat intelligence researchers, family subscriber focus groups, and hyperscaler cloud infrastructure planners and refined through secondary validation. Primary fieldwork combined structured interviews with CTOs at independent security vendors and procurement officers at OEM preload partners. Secondary sources included SEC 10-K filings, FTC enforcement action databases, GDPR decision registers, and hyperscaler capex disclosures. Bottom-up subscription volume estimates and top-down addressable market sizing were triangulated for consistency.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, end-user household type, price tier structure, and regional regulatory cluster. CAGRs were derived from installed base growth trajectories and average revenue per account expansion curves. Forecast inputs incorporated multi-device household proliferation rates and remote work persistence indicators.
Sensitivities concentrate around hyperscaler pricing volatility, EU AI Act enforcement intensity, and platform bundling acceleration. Forecasts reflect assumptions about subscriber retention patterns and freemium conversion elasticity. Quarterly review of FTC complaint filings and hyperscaler earnings call commentary is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Broadcast Censorship Solutions Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Data Masking Technology Market
Security Software
Anti-Fraud Management System Market
Security Software
US Hardware Encryption Market
Security Software
E Passport Market
Security Software
Global Visitor Management System Market
Security Software
Global Digital Identity Solutions Market
Security Software
Asia-Pacific Smart Doorbell Market
Security Software
Network Security Appliance Market
Security Software
AI Security Platforms Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Global Network Security Software Market
Security Software
Content Protection and Watermarking Market
Security Software
Identity Verification Software Market