
 Anti-Fraud Management System Market | 2026-2036
Anti-Fraud Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fraud Management System Market Analysis
Platform licensing revenue is fragmenting between pure-play SaaS vendors and infrastructure-anchored incumbents. Oracle Corporation leverages its cloud database ecosystem to bundle fraud detection with core banking workloads. IBM Corporation anchors enterprise trust through mainframe-integrated security modules that sustain long-term contract renewals. SAS Institute Inc. specializes in statistical modeling layers that differentiate its offerings in insurance scoring verticals.
An anti-fraud management system constitutes an integrated software platform that applies machine learning algorithms, behavioral biometrics, and real-time data analytics to detect, investigate, and prevent fraudulent transactions across digital channels. Its primary commercial purpose centers on reducing financial losses while ensuring regulatory compliance for institutions processing high-velocity payment flows. Transaction monitoring solutions command the largest installed base due to mandatory suspicious activity reporting requirements in banking, though identity verification deployments are expanding fastest as e-commerce platforms face escalating account takeover attacks. Cloud-based delivery now dominates new procurement decisions, while on-premises retention persists among tier-one banks with sovereign data constraints.
The Federal Reserve's real-time payment infrastructure mandates and FFIEC authentication guidance shape US product roadmaps, while the EU AI Act and GDPR impose algorithmic transparency requirements on automated fraud scoring systems deployed across European financial institutions. Compliance deadlines are tightening documentation standards for model governance and customer notification protocols. Stakeholders must evaluate whether their current technology stacks can adapt to emerging cross-border data localization rules without sacrificing detection latency.
Market Dynamics
The Federal Reserve's real-time payment infrastructure mandates are compressing detection latency requirements from batch to millisecond-grade response, forcing institutions to rebuild core transaction monitoring architectures around streaming data pipelines.
Growth Catalysts
- FFIEC Authentication Guidance:US financial institutions must deploy multi-factor verification for high-risk transactions, expanding identity verification platform procurement.
- EU AI Act Algorithmic Transparency:European banks face mandatory documentation standards for automated fraud scoring, driving replacement of opaque legacy rule engines.
- Card-Not-Present Fraud Volumes:Payment processors in the United States confront escalating e-commerce chargeback rates, accelerating real-time transaction monitoring adoption.
Market Restraints
- Sovereign Data Localization:Tier-one banks in Germany and France retain on-premises infrastructure due to national data residency requirements, constraining cloud-native vendor expansion.
- Legacy System Integration Complexity:Core banking platforms running on IBM mainframes create technical debt that slows machine learning module deployment.
- Behavioral Biometric Sensor Costs:Specialized hardware for keystroke dynamics and touch-pattern analysis elevates deployment expenses for mid-tier institutions.
Strategic Opportunities
- Open Banking API Convergence:PSD2-mandated data sharing in the United Kingdom creates attack surfaces requiring new fraud orchestration layers.
- Insurance Scoring Vertical:SAS Institute's statistical modeling expertise transfers to property-casualty fraud detection, an underpenetrated segment.
- Edge Computing Deployment:Real-time inference on payment terminals in Brazil and India bypasses cloud latency for emerging market processors.
Industry Challenges
- Machine Learning Operations Talent:Banks struggle to recruit engineers capable of productionizing fraud models with sub-100-millisecond inference times.
- Model Governance Documentation:GDPR Article 22 requirements for automated decision explanations demand new audit trail infrastructure.
- Cross-Border Data Fragmentation:Divergent privacy rulings between EU member states complicate centralized fraud intelligence sharing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fraud Management System Market |
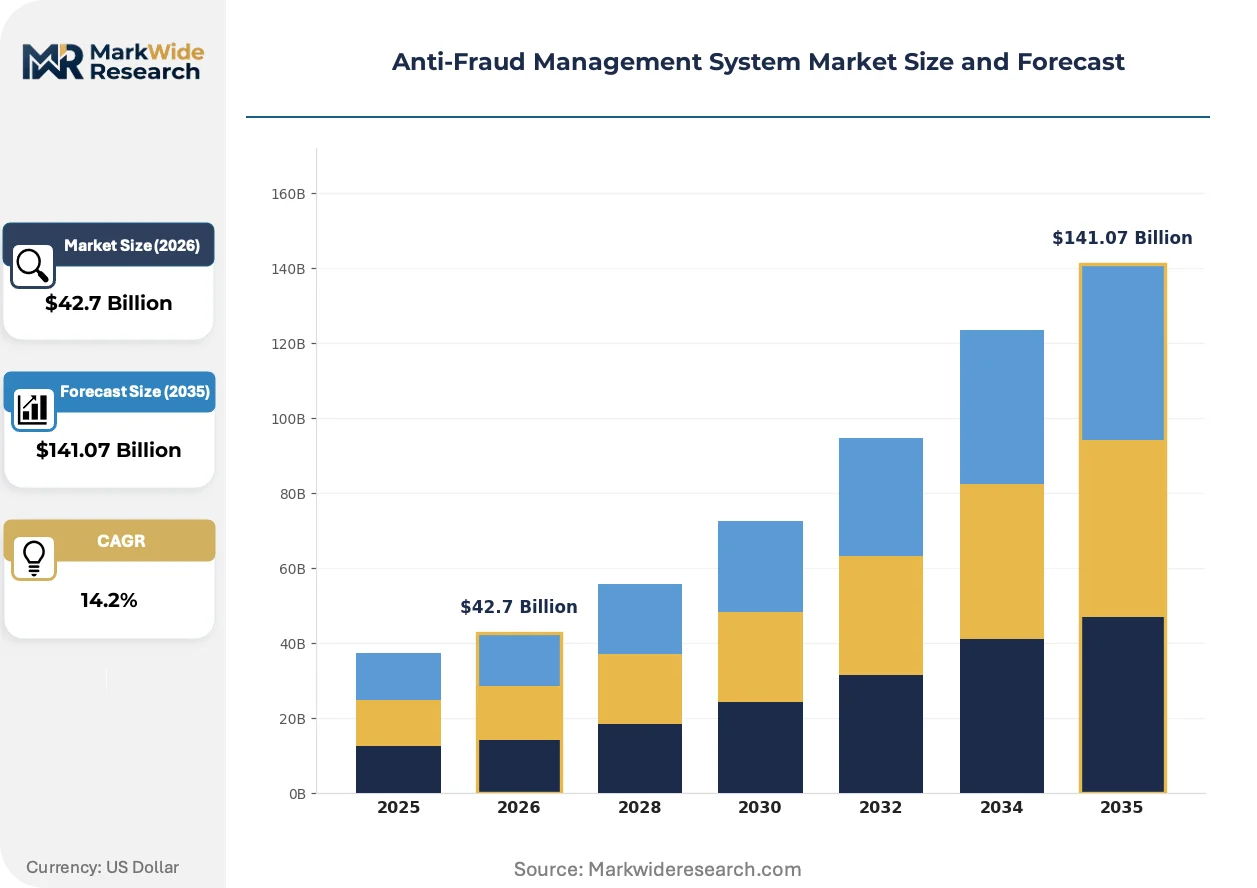
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $141.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transaction Monitoring, Identity Verification, Case Management, Compliance Management End User: Banks, Insurance Companies, E-commerce Platforms, Payment Processors Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Technology: Machine Learning, Artificial Intelligence, Data Analytics, Rule-Based Systems |
| Companies Covered | Oracle Corporation, IBM Corporation, SAS Institute Inc., Fair Isaac Corporation, ACI Worldwide Inc., Fiserv Inc., SAP SE, Feedzai, LexisNexis Risk Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fraud Management System Market Emerging Trajectories
Behavioral biometrics and streaming analytics are converging to eliminate the latency-performance tradeoff that has constrained fraud detection architecture for two decades.
Graph neural networks analyzing transaction relationships in real-time is collapsing the distinction between batch risk scoring and instantaneous authorization decisions. Tier-one US banks are deploying these models at the network edge, cutting false-positive rates while maintaining sub-50-millisecond response times. The technology is collapsing legacy tiered alert queues into single-stream automated case resolution.
The EU AI Act's risk classification framework imposes mandatory human oversight on high-risk automated fraud decisions, compelling European institutions to rebuild model governance infrastructure. Banks must now maintain technical documentation proving algorithmic fairness across demographic segments. French and German regulators are conducting the first compliance audits, with institutions facing operational disruption if documentation gaps emerge.
Payment processors are unbundling fraud detection from core banking contracts, creating standalone procurement for best-of-breed solutions. Mid-tier US credit unions now source transaction monitoring through API-integrated specialist vendors rather than bundled legacy suites. This pattern is most visible in the Southeastern United States, where regional processors prioritize detection accuracy over single-vendor convenience.
Anti-Fraud Management System Market Segmentation
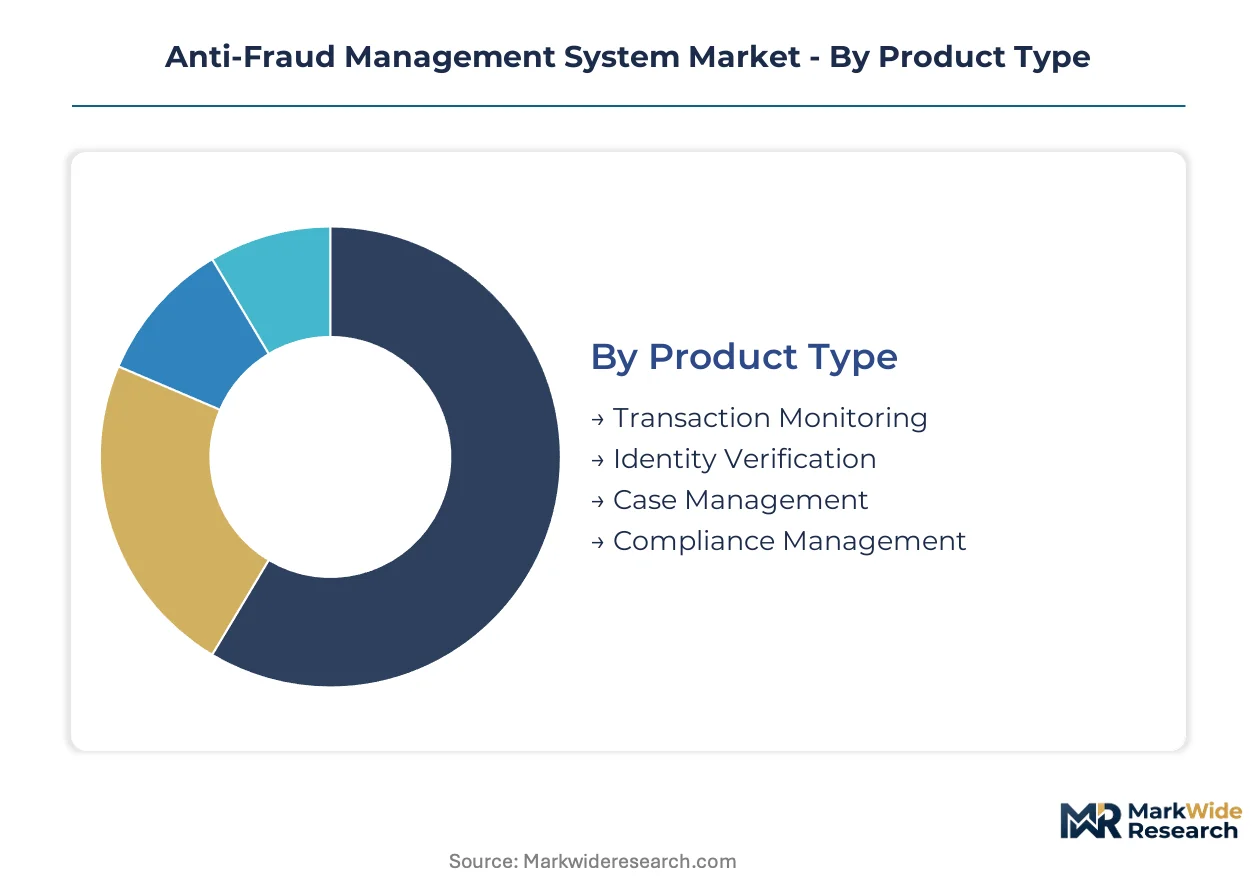
Segmentation in anti-fraud management systems reveals distinct procurement cycles and technical requirements across product architectures. Deployment patterns vary sharply between real-time transaction processing demands and batch compliance reporting workflows.
Product Type:
Replacement cycles diverge dramatically across product categories, with transaction monitoring platforms refreshing every 3-4 years while case management tools persist for 7-10 years in institutional environments.
- Transaction Monitoring:Real-time streaming analytics platforms process high-velocity payment flows through behavioral pattern recognition engines. US payment processors facing FFIEC mandates drive the steepest procurement acceleration as card-not-present fraud volumes escalate.
- Identity Verification:Multi-factor authentication and biometric verification modules anchor customer onboarding workflows. E-commerce platforms in the United States prioritize these deployments to counter account takeover attacks and reduce chargeback exposure.
- Case Management:Investigation workflow tools support analyst teams in fraud alert disposition and evidence documentation.
- Compliance Management:Regulatory reporting automation ensures suspicious activity documentation meets jurisdictional filing deadlines.
Transaction monitoring anchors the volume base while identity verification gains share at the steepest rate.
End User:
Procurement sophistication stratifies sharply across customer types, with tier-one banks demanding sub-50-millisecond inference latency while mid-tier credit unions prioritize API integration speed.
- Banks:Core banking integration requirements dominate vendor selection, with mainframe compatibility and sovereign data controls shaping RFP criteria. German and French institutions retain on-premises infrastructure due to national data residency mandates.
- Payment Processors:Real-time authorization decisioning demands edge-deployed inference models with minimal cloud dependency. Brazilian and Indian processors pioneer terminal-level deployment to bypass network latency.
- Insurance Companies:Statistical scoring models for claims fraud detection leverage historical loss data and external risk databases.
- E-commerce Platforms:Account takeover prevention and bot detection prioritize frictionless customer experience alongside security efficacy.
Banks command the largest installed base though payment processors exhibit the most aggressive modernization timelines.
Deployment:
Cost tier differentiation separates sovereign-constrained infrastructure from elasticity-optimized cloud-native architectures.
- Cloud-Based:Elastic compute resources support variable transaction volumes without capital-intensive hardware procurement. Mid-tier US institutions favor this model for rapid model deployment and automated scaling.
- SaaS:Subscription licensing eliminates upfront capital expenditure while ensuring continuous feature updates. Regional credit unions in the Southeastern United States source transaction monitoring through API-integrated specialist vendors.
- On-Premises:Air-gapped environments satisfy data localization requirements in regulated jurisdictions.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud analytics for non-critical workloads.
Cloud-based deployment captures the majority of new procurement decisions while on-premises retention persists among tier-one banks with sovereign constraints.
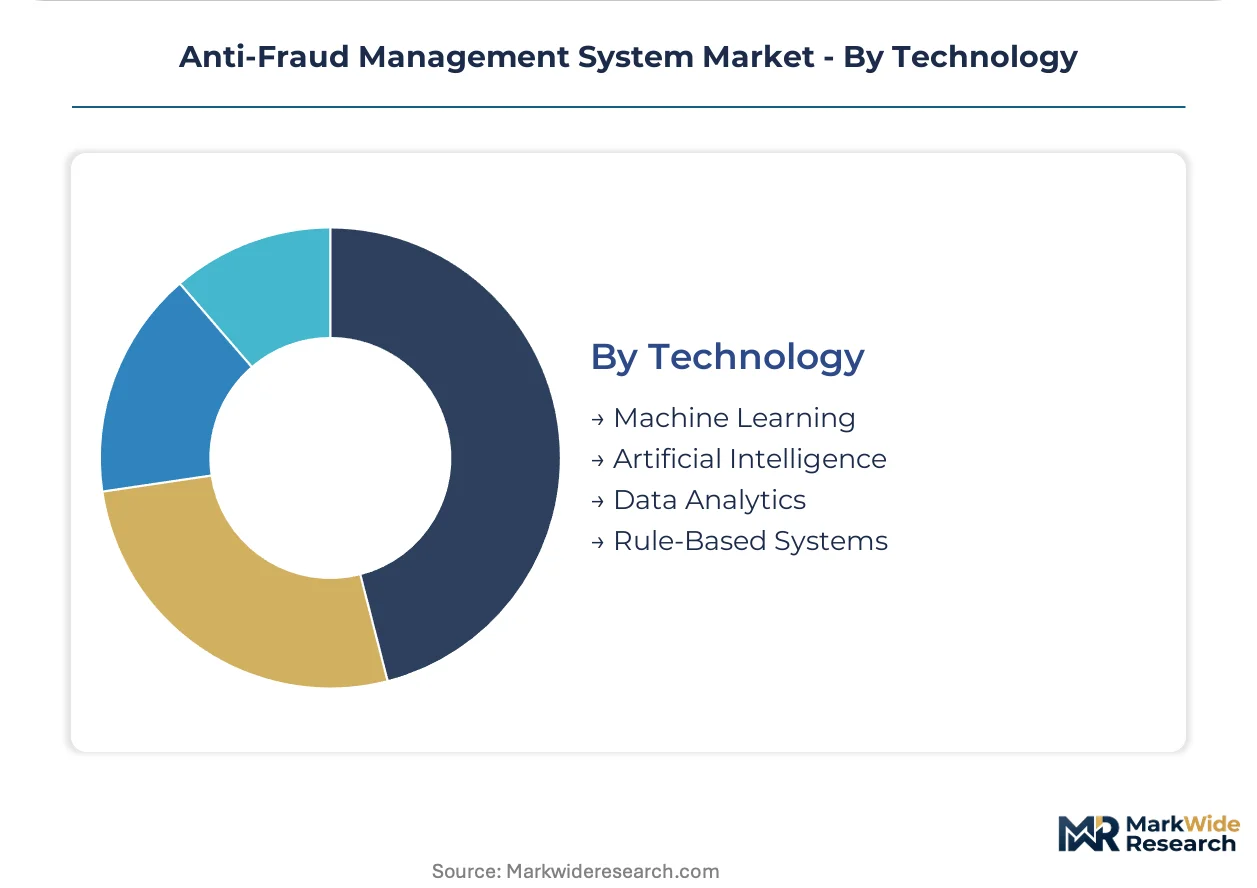
Technology:
Model governance maturity separates production-grade machine learning deployments from legacy rule-based maintenance.
- Machine Learning:Graph neural networks analyzing transaction relationships collapse batch and real-time scoring into single-stream decisions. Tier-one US banks deploy these at network edges to cut false-positive rates.
- Artificial Intelligence:Automated decisioning systems face EU AI Act documentation requirements for algorithmic transparency and demographic fairness testing.
- Data Analytics:Descriptive and diagnostic tools support investigator workflows and regulatory reporting.
- Rule-Based Systems:Static threshold engines persist in legacy environments but face replacement pressure from European algorithmic transparency mandates.
Machine learning dominates new platform architecture while rule-based systems face accelerated replacement cycles in European jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European institutions prioritize algorithmic transparency compliance, US payment processors optimize for sub-50-millisecond authorization latency, and emerging market banks deploy edge-computing architectures to bypass network infrastructure constraints.
United States
The Federal Reserve's real-time payment infrastructure mandates compress detection latency requirements from batch to millisecond-grade response. FFIEC authentication guidance forces multi-factor verification deployment for high-risk transactions. Payment processors in the Southeastern United States unbundle fraud detection from core banking contracts to source API-integrated specialist vendors.
Germany
Tier-one banks retain on-premises infrastructure due to sovereign data residency requirements under national privacy frameworks. The EU AI Act imposes mandatory documentation standards for automated fraud scoring systems. Frankfurt's financial services cluster drives replacement of opaque legacy rule engines with transparent machine learning architectures.
United Kingdom
PSD2-mandated open banking data sharing creates new attack surfaces requiring fraud orchestration layers. The Financial Conduct Authority enforces strict suspicious activity reporting timelines. London's fintech concentration pioneers graph neural network deployment at network edges to collapse batch and real-time scoring into single-stream decisions.
Brazil
Payment processors deploy edge computing on terminals to bypass cloud latency in real-time authorization decisioning. The central bank's instant payment infrastructure expansion accelerates modernization timelines. São Paulo's merchant acquiring hub leads terminal-level inference model deployment across Latin America.
India
Digital payment volume explosion strains legacy transaction monitoring architectures. RBI mandates on digital lending fraud detection tighten compliance deadlines. Mumbai's banking headquarters and Bangalore's technology corridor drive procurement of behavioral biometrics and streaming analytics platforms.
Anti-Fraud Management System Market Vendor Landscape
Capability concentration sits with pure-play specialists commanding algorithmic sophistication; scale advantage sits with infrastructure-anchored incumbents leveraging installed base relationships. The vendor base stratifies across three tiers: cloud-native challengers, mainframe-integrated legacy providers, and statistical modeling specialists. Dominant competitive moves include strategic partnerships for API ecosystem integration and portfolio diversification into adjacent identity verification verticals.
Within the infrastructure-anchored tier, Oracle Corporation and IBM Corporation exemplify scale-driven positioning through cloud database ecosystem bundling and mainframe-integrated security module retention respectively. SAS Institute Inc. occupies the statistical modeling specialist position, transferring expertise from insurance scoring into property-casualty fraud detection. These three entities represent the archetypal competitive vectors—cloud ecosystem leverage, legacy infrastructure lock-in, and vertical-specific algorithmic depth—that structure procurement decisions across tier-one financial institutions.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAS Institute Inc. |
| Fair Isaac Corporation |
| ACI Worldwide Inc. |
| Fiserv Inc. |
| SAP SE |
| Feedzai |
| LexisNexis Risk Solutions |
| Others |
Supply Flow & Price Mechanics
EU AI Act compliance documentation mandates concentrate procurement power among tier-one banks with dedicated governance infrastructure, compressing pricing spreads between premium transparent-ML architectures and legacy rule-based tiers while forcing vendors to restructure delivery models around sovereign data residency requirements.
Pricing Analysis
Long-term enterprise licensing contracts dominate tier-one bank procurement, with three-year SaaS subscriptions capturing mid-tier credit unions and per-transaction fees anchoring payment processor arrangements. Price differentiation separates sub-50-millisecond edge-deployed inference from cloud-native batch processing, with customization for mainframe integration commanding substantial premiums. Cost compression in the mid-market tier is intensifying because API-integrated specialist vendors displace bundled legacy suites. Regional credit unions in the Southeastern United States exhibit the highest price sensitivity, while German and French tier-one banks prioritize sovereign compliance over cost optimization.
Supply Chain Analysis
Tariff exposure between the United States and China on specialized GPU hardware elevates deployment costs for behavioral biometric sensor arrays and edge-computing inference modules. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in domestic jurisdictions to satisfy data localization mandates. The supply chain rests on semiconductor fabrication from Taiwan, specialized biometric sensor production from South Korea, and open-source machine learning framework maintenance from distributed global contributors. Single-source vulnerability in NVIDIA GPU supply creates procurement bottlenecks for graph neural network deployment. Distribution runs through direct enterprise sales teams for tier-one banks and API marketplace integrations for mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among payment processors unbundling fraud detection from core banking contracts, fragmenting the vendor landscape and compressing margins for bundled legacy providers.
For Market Incumbents: Entrench mainframe-integrated security module relationships through accelerated EU AI Act compliance documentation support, defending against cloud-native challengers exploiting API-integrated procurement preferences. Prioritize backward integration into behavioral biometric sensor supply to reduce hardware cost exposure and accelerate edge-deployment capabilities. For New Entrants and Emerging Players: Build out insurance scoring vertical penetration by transferring statistical modeling expertise from property-casualty fraud detection into claims automation workflows, the most penetrable segment given SAS Institute's legacy concentration in adjacent analytics. Target Brazilian and Indian payment processors through terminal-level inference partnerships, leveraging the central bank instant payment infrastructure expansion as primary go-to-market channel. For Investors and Strategic Acquirers: The EU AI Act's high-risk system classification deadline reshapes the acquisition landscape toward vendors with pre-built algorithmic transparency documentation and demographic fairness testing infrastructure. Long-term viability centers on model governance platform ownership rather than point-solution detection algorithms. Watch for FFIEC authentication guidance enforcement intensity as the signal indicating US procurement acceleration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native orchestration layers capture unbundled procurement from regional US payment processors. |
| Acquisition of Specialist Firm | Behavioral biometrics expertise addresses escalating account takeover attack volumes in e-commerce. |
| Geographic Expansion | Edge-computing deployment in Brazil and India bypasses cloud latency for real-time authorization. |
| Strategic Partnership | Open banking API convergence under PSD2 mandates creates fraud orchestration layer demand in the UK. |
| Product Launch | Graph neural network deployment at network edges collapses batch and real-time scoring for tier-one banks. |
Methodological Framework
A spread of perspectives from fraud operations executives at tier-one banks, payment processor CTOs, insurance claims analytics directors, regulatory compliance officers, and API integration specialists converged on the working assumptions underlying this analysis. Primary interview insights were validated against secondary sources including SEC 10-K filings, FFIEC examination reports, EU AI Act technical documentation requirements, and central bank instant payment infrastructure disclosures. Bottom-up transaction volume modeling and top-down IT security budget allocation analysis were triangulated to establish market sizing boundaries.
Demand-supply balance framing anchored the forecast framework, with procurement cycle analysis across the analysis window informing adoption curve assumptions. Segmentation dimensions modeled include deployment architecture, end-user institution type, technology maturity tier, and regional regulatory compliance cluster. CAGRs were derived from installed base replacement velocity and new platform procurement intensity. Industry-specific forecast inputs incorporated real-time payment infrastructure mandate timelines and algorithmic transparency audit preparation schedules.
Stress conditions across sovereign data localization enforcement intensity, GPU supply chain disruption severity, and machine learning engineering talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory deadline adherence and infrastructure modernization budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Digital Vehicle Forensics Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Global Digital Signature Software Market
Security Software
Managed Security Services Market
Security Software
Digital Risk Protection Software Market
Security Software
Global Anti-Spam Software Market
Security Software
Europe Anti-Money Laundering Software Market
Security Software
Communication Encryption Software Market
Security Software
Data Masking Technology Market
Security Software
Certificate Authority Market
Security Software
Europe Smart Doorbell Market
Security Software
POS Security Market
Security Software
Employee Computer Monitoring Software Market
Security Software
VPN Software Market
Security Software
US Evidence Management Market
Security Software
AI in Security Market