
 Digital Credential Management Software Market | 2026-2036
Digital Credential Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Credential Management Software Market Outlook
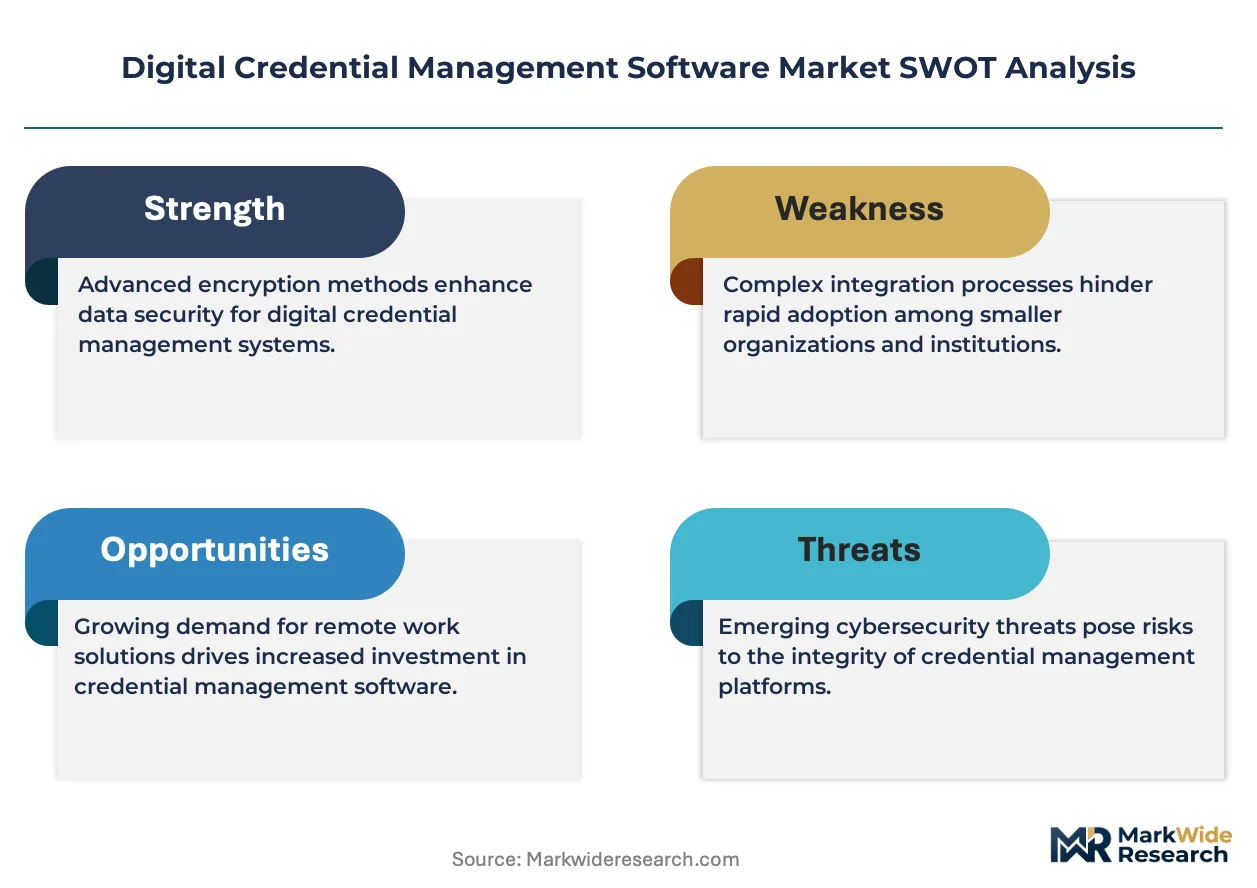
ISO/IEC 27001 certification for information security management is rotating as the gatekeeping standard that determines vendor eligibility in procurement cycles. Credly leverages its established partnerships with major technology platforms to sustain broad credential interoperability. Digitary anchors European academic credentialing through its specialized focus on higher education transcript verification. Accredible competes aggressively on API depth, extending integration capabilities across learning management systems.
Digital credential management software comprises platforms that issue, verify, and store tamper-evident credentials using cryptographic signing, decentralized identifiers, or blockchain-anchored proofs, with throughput benchmarks typically exceeding 10,000 verifications per second for enterprise deployments. Its primary commercial purpose is eliminating credential fraud while reducing administrative overhead in qualification verification. Cloud-based deployment leads volume adoption due to elastic scaling for seasonal issuance peaks such as graduation cycles. API integration captures expanding margin pools as enterprises demand seamless embedding of verification into existing HR and academic workflows. SaaS delivery models are displacing on-premises installations among mid-market organizations seeking reduced infrastructure burden.
FDA 21 CFR Part 11 requirements for electronic records shape product development trajectories for credential platforms serving pharmaceutical training compliance. EMA guidelines on qualification documentation and GDPR data portability mandates collectively tighten data architecture specifications across European deployments. Stakeholders must monitor evolving interoperability standards between national digital identity frameworks and private credential networks to anticipate platform obsolescence risks.
Market Dynamics
EU AI Act compliance mandates are compressing procurement cycles for auditable credential infrastructure, forcing vendors to pre-certify platforms before enterprise HR departments will engage. This regulatory pressure is concentrating demand among vendors holding ISO/IEC 27001 certification.
Growth Catalysts
- GDPR Data Portability:European employers must verify workforce qualifications without cross-border data friction, accelerating demand for decentralized identifier architectures that keep personal data within jurisdictional boundaries.
- Industrial Certification Bodies:German trade associations are digitizing journeyman credentials at scale, creating template demand across adjacent EU member states with comparable apprenticeship structures.
- Blockchain-Anchored Proofs:Pharmaceutical manufacturers under FDA 21 CFR Part 11 are adopting tamper-evident training records, expanding the addressable market beyond academic and HR use cases.
Market Restraints
- Cloud Infrastructure Concentration:Three hyperscale providers dominate hosting for credential platforms, creating single-point-of-failure risk for verification uptime during seasonal issuance peaks.
- Legacy System Integration Costs:Enterprises with SAP or Oracle HCM deployments face six-figure customization bills to embed verification APIs, slowing mid-market adoption.
- Skills-Based Hiring Substitution:Some technology employers are de-emphasizing formal credentials in favor of portfolio-based assessment, compressing demand in the fastest-growing hiring segment.
Strategic Opportunities
- UAE Digital Identity Framework:MOHAP and federal identity authorities are building interoperability protocols that private credential networks can plug into, opening Gulf Cooperation Council expansion paths.
- CSRD-Linked Credentialing:European sustainability reporting mandates require verified training records for ESG disclosures, creating new product lines linking credentials to corporate compliance dashboards.
- AI-Generated Credential Fraud:Deepfake document detection is converging with cryptographic verification, enabling premium pricing for platforms offering dual-layer authentication.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge proof engineering and decentralized identifier protocol development require specialized skill sets that command premium compensation, constraining vendor R&D velocity.
- Multi-Jurisdiction Compliance Burden:Platforms serving multinational employers must maintain parallel audit trails for FDA, EMA, and national data protection authorities, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Credential Management Software Market |
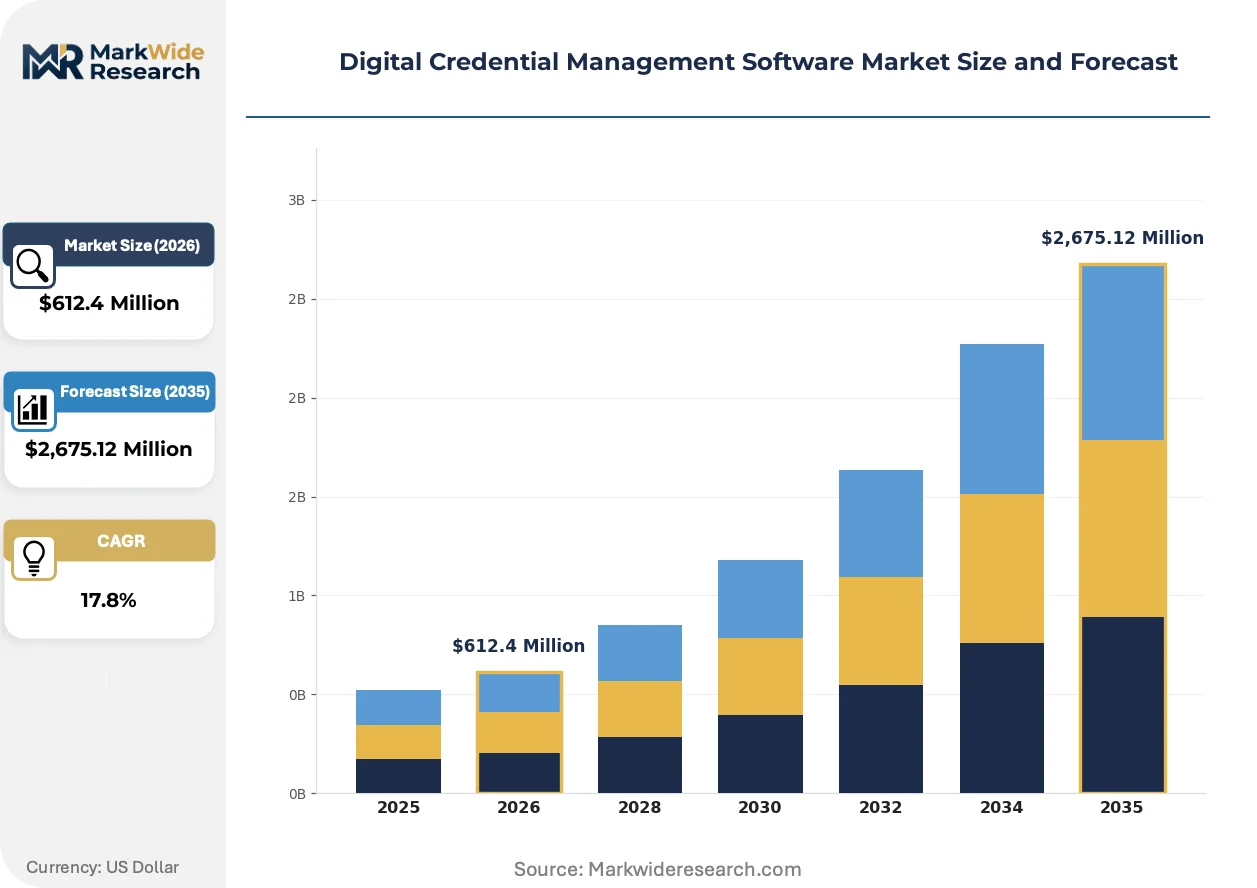
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,675.12 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Education Sector, Corporate Training, Regulatory Compliance, Personal Identification Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS User Type: Academic Institutions, Organizations, Government Agencies, Individuals Integration Level: API Integration, Standalone Solutions, Custom Integrations, Third-Party Services |
| Companies Covered | Digitary, Open Badge Factory, Credly, Accredify, Certifier, Accredible, Badgr, CertifyMe, Hyperstack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Credential Management Software Market Strategic Shifts
Verification throughput benchmarks are becoming the primary competitive differentiator as enterprise buyers stress-test platforms against 10,000+ concurrent verification scenarios. Vendors are re-architecting infrastructure to meet these elastic scaling demands.
Blockchain-anchored credential issuance is bifurcating between permissioned enterprise chains and public decentralized networks. Pharmaceutical and defense contractors are adopting permissioned architectures for audit trail control. Public networks are capturing academic credentialing where institutional reputation substitutes for network-level trust. This split is forcing vendors to maintain dual infrastructure stacks, compressing margins for single-architecture specialists.
EMA guidelines on qualification documentation are tightening data retention and audit trail specifications across European deployments. Platforms must now demonstrate immutable record-keeping for the full credential lifecycle plus seven years. German pharmaceutical manufacturers and French hospital systems are most affected, accelerating procurement of EMA-prevalidated verification modules.
Enterprise buyers are unbundling issuance from verification services, contracting separate vendors for each function. Large employers with internal L&D departments are keeping issuance in-house while outsourcing verification to specialized platforms. This pattern is most visible in US technology and financial services sectors, where procurement teams favor best-of-breed over integrated suites.
Digital Credential Management Software Market Segmentation
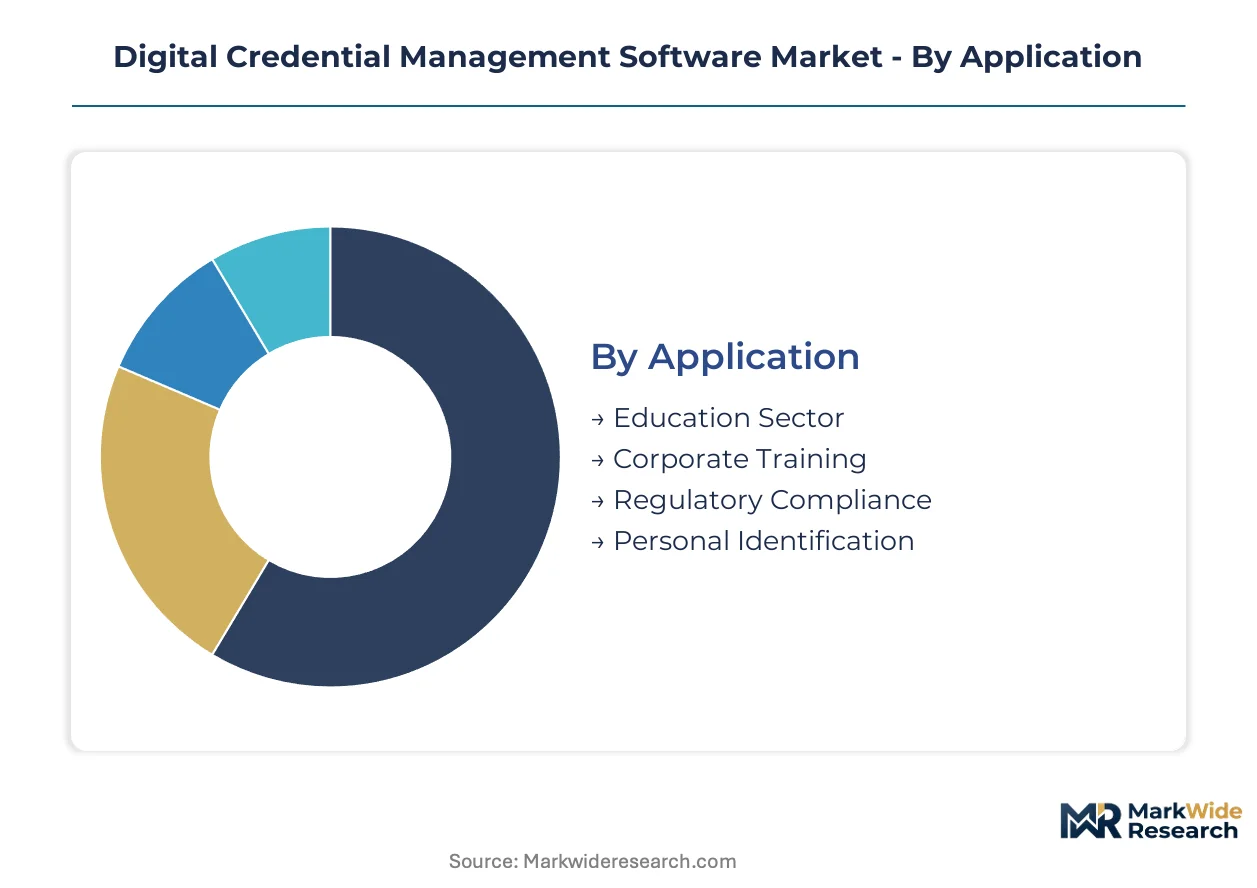
Digital credential management software fragments across four distinct dimensions that determine pricing power and technical requirements. Application context dictates compliance architecture, while deployment model governs scalability economics and integration depth shapes customer retention.
Application:
Margin pools concentrate in regulatory compliance deployments where audit trail requirements justify premium pricing.
- Education Sector:Platforms issue tamper-evident academic transcripts and micro-credentials using cryptographic signing. German universities and French grandes écoles are digitizing diploma verification at scale under GDPR portability mandates. This segment holds installed capacity.
- Corporate Training:HR departments embed verification APIs into learning management systems for workforce credentialing. Pharmaceutical manufacturers under FDA 21 CFR Part 11 drive demand for immutable training records. This segment is rotating up the share rankings.
- Regulatory Compliance:EMA guidelines and FDA electronic record requirements shape product specifications for audit-ready credential infrastructure.
- Personal Identification:Decentralized identifier architectures enable self-sovereign credential wallets for cross-border employment verification.
Corporate Training commands the highest contract values. Education Sector delivers the most predictable recurring revenue streams.
Deployment Model:
Cost tier stratification separates enterprise buyers seeking control from mid-market organizations prioritizing operational simplicity.
- Cloud-Based:Elastic infrastructure scales through seasonal issuance peaks such as university graduation cycles. German industrial certification bodies leverage cloud deployments for journeyman credential digitization across apprenticeship networks.
- SaaS:Subscription pricing reduces upfront infrastructure burden for academic institutions with constrained IT budgets. French hospital systems and UAE healthcare regulators are adopting SaaS delivery for rapid deployment without capital expenditure.
- On-Premises:Defense contractors and pharmaceutical manufacturers maintain air-gapped credential issuance for classified or proprietary qualification data.
- Hybrid:Split architectures keep sensitive issuance operations on-premises while outsourcing verification to cloud nodes.
Cloud-Based deployments dominate transaction volume. SaaS is climbing fastest among new customer acquisitions.
User Type:
Customer type determines procurement complexity and sales cycle duration, with government tenders extending timelines but locking in multi-year commitments.
- Organizations:Enterprise HR departments demand API-first platforms with SAP and Oracle HCM integration capabilities. GDPR compliance requirements accelerate procurement of auditable credential infrastructure across European multinational employers.
- Academic Institutions:Universities prioritize transcript interoperability with national digital identity frameworks. Digitary anchors European higher education through specialized verification modules.
- Government Agencies:Federal identity authorities in the UAE and EU member states specify decentralized identifier protocols for cross-border credential recognition.
- Individuals:Self-sovereign credential wallets enable direct control over qualification data portability.
Organizations represent the deepest wallet share. Academic Institutions are expanding most quickly as credential digitization becomes standard.
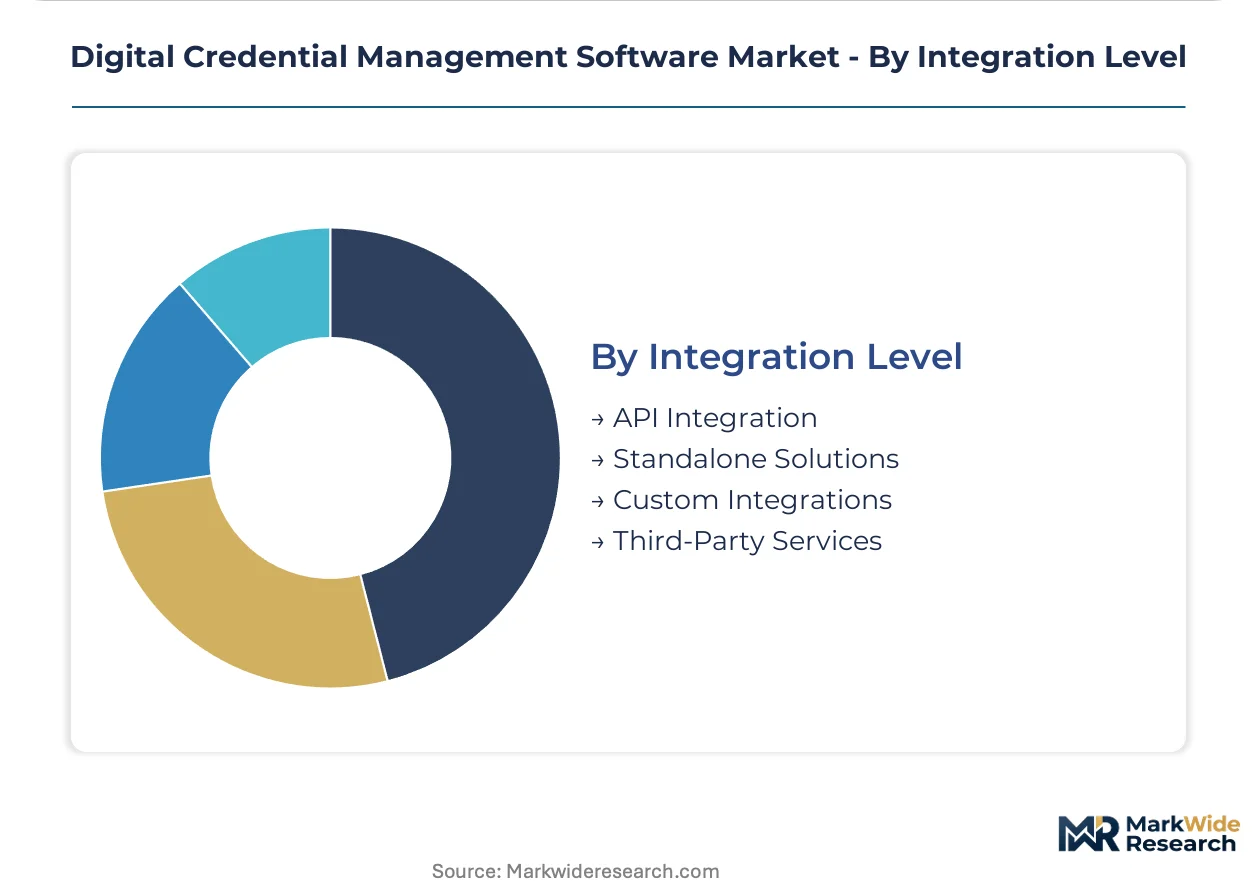
Integration Level:
Supply concentration among API specialists is compressing margins for standalone platform vendors unable to embed into existing enterprise workflows.
- API Integration:RESTful and GraphQL endpoints enable seamless embedding of verification into HR and learning management systems. Accredible competes aggressively on API depth across LMS ecosystems.
- Third-Party Services:Pre-built connectors to Workday, Salesforce, and LinkedIn reduce implementation timelines for mid-market buyers.
- Standalone Solutions:Full-stack platforms with native issuance and verification capture smaller organizations without dedicated development resources.
- Custom Integrations:Six-figure customization projects serve enterprises with legacy SAP or Oracle HCM deployments requiring bespoke credential workflows.
API Integration captures expanding margin pools. Third-Party Services are gaining share fastest among time-constrained procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German trade associations are digitizing journeyman credentials at scale under EU AI Act compliance timelines, while UAE federal identity authorities build interoperability protocols for Gulf expansion. The EU GDPR data portability mandate and FDA 21 CFR Part 11 requirements are compressing procurement cycles across multiple jurisdictions.
Germany
Industrial certification bodies in Baden-Württemberg and North Rhine-Westphalia are converting paper-based trade qualifications into verifiable digital formats. The KBA and federal employment agency coordinate apprenticeship credential standards under EU AI Act auditability requirements. Munich and Stuttgart clusters host concentrated vendor deployment for automotive and precision engineering workforce verification.
United States
Enterprise HR departments in technology and financial services sectors are unbundling issuance from verification services. FDA 21 CFR Part 11 requirements drive pharmaceutical manufacturers toward tamper-evident training record platforms. The Boston-Cambridge biotech corridor and San Francisco Bay Area represent dense adoption zones for compliance-linked credentialing.
France
French grandes écoles and hospital systems are digitizing diploma verification under ANSM and CNIL data architecture specifications. EMA guidelines on qualification documentation tighten retention requirements for pharmaceutical training records. The Paris-Saclay university cluster and Lyon healthcare hub are accelerating procurement of prevalidated verification modules.
UAE
MOHAP and federal identity authorities are constructing decentralized identifier protocols for cross-border employment verification. Healthcare regulators in Dubai and Abu Dhabi adopt SaaS delivery models for rapid deployment without capital expenditure. The Emirates' digital identity framework creates template demand across Gulf Cooperation Council member states.
United Kingdom
UK universities prioritize transcript interoperability with national digital identity frameworks following post-Brexit data governance adjustments. The Information Commissioner's Office enforces GDPR-aligned portability standards for academic credential transfers. London's fintech cluster and Edinburgh's financial services sector drive API-first verification demand for compliance-linked hiring workflows.
Digital Credential Management Software Market Competitive Environment
Listed leaders compete with private specialists across certification depth and API integration capabilities. The vendor base stratifies between established platform incumbents and emerging specialists focused on narrow compliance verticals. Three strategic archetypes dominate: cloud-native SaaS providers, legacy-integrated enterprise suites, and blockchain-anchored verification specialists. Competitive moves concentrate on ISO/IEC 27001 pre-certification for procurement eligibility and API ecosystem partnerships for workflow embedding.
Within the academic credentialing tier, Digitary anchors European higher education through specialized transcript verification modules. Credly occupies a position exemplifying broad credential interoperability through platform partnerships. Accredible sits within the API-specialist archetype, competing on integration depth across learning management system ecosystems. These three represent distinct strategic postures rather than direct functional substitutes.
| Leading Market Players |
|---|
| Digitary |
| Open Badge Factory |
| Credly |
| Accredify |
| Certifier |
| Accredible |
| Badgr |
| CertifyMe |
| Hyperstack |
| Others |
Value Chain & Pricing Dynamics
ISO/IEC 27001 certification gates both vendor eligibility and price positioning simultaneously, compressing procurement cycles toward pre-certified suppliers while enabling premium capture for compliant platforms. Enterprise buyers facing EU AI Act auditability mandates tolerate higher subscription tiers for certified infrastructure, concentrating margin pools among vendors holding dual compliance credentials.
Pricing Analysis
Certification level creates the primary spread between premium ISO/IEC 27001-certified deployments and standard-tier uncertified offerings. SaaS subscription models dominate, with annual contracts scaling by verification volume and API call thresholds. Price differentiation hinges on audit trail depth and cross-border data residency guarantees. Cost compression in the mid-market tier is intensifying because hyperscale cloud providers are bundling credential verification into broader identity suites. Academic institutions exhibit highest price sensitivity, while pharmaceutical manufacturers under FDA 21 CFR Part 11 demonstrate lowest sensitivity due to compliance liability exposure.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes intermittently inflate hardware delivery timelines for on-premises deployments. Software development concentrates in Ireland, Germany, and the United States, with cryptographic engineering talent clustering in Zurich and Singapore. Platform infrastructure rests on hyperscale cloud capacity from AWS, Azure, and Google Cloud. Single-source vulnerability pervades the cloud substrate layer, where three providers control verification uptime during seasonal issuance peaks. Distribution runs through direct enterprise sales teams for large contracts and channel partners for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance mandates are compressing procurement cycles toward pre-certified infrastructure, creating a high-growth disruption window for auditable credential platforms. Vendors must pre-validate architectures before enterprise HR departments will engage, accelerating winner-take-most dynamics.
For Market Incumbents: Fortify ISO/IEC 27001 certification depth across regional data centers to defend against emerging cloud-native entrants bundling verification into identity suites. Expand API partnership ecosystems with Workday and SAP to lock in workflow embedding. Prioritize zero-knowledge proof engineering investments to maintain cryptographic differentiation as open-source protocols commoditize baseline verification. For New Entrants and Emerging Players: API-native verification layers for mid-market LMS integrations represent the most penetrable white space, where incumbent platform complexity creates service gaps. Target French hospital systems and UAE healthcare regulators with rapid-deployment SaaS offerings that bypass lengthy procurement cycles. Lead with pre-built connectors to national digital identity frameworks as the primary go-to-market wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native verification sub-segments, enabling asset-light scaling for API-first specialists. Long-term viability favors vendors with embedded workflow positioning rather than standalone platform plays. Monitor procurement pre-certification timelines at German industrial certification bodies as the signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Pre-Certification | Gates enterprise procurement eligibility under EU AI Act compliance timelines. |
| API Ecosystem Expansion | Deepens workflow embedding with SAP and Oracle HCM integration modules. |
| Zero-Knowledge Proof Development | Enables privacy-preserving verification for GDPR data portability mandates. |
| Regional Data Center Expansion | Satisfies data residency requirements for German and French deployments. |
| Strategic Partnership with National ID Frameworks | Opens UAE and Gulf Cooperation Council expansion paths through interoperability protocols. |
Study Parameters
Initial hypotheses were tested against primary input from CTOs at enterprise HR departments, platform engineers at credential vendors, integration specialists at learning management system providers, and procurement officers at pharmaceutical manufacturers, then refined through secondary validation. Data synthesis combined SEC filings from publicly traded software vendors, hyperscaler capex disclosures, EU regulatory filings on AI Act implementation, and academic credentialing databases. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Variance decomposition across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from segment-level growth rate blending weighted by revenue contribution. Forecast inputs incorporated EU AI Act implementation timelines, FDA 21 CFR Part 11 audit frequency trends, and cloud infrastructure elasticity benchmarks for seasonal issuance peaks.
Forecasts assume regulatory continuity in EU AI Act and GDPR enforcement regimes; material policy shifts would require re-modeling. Cryptographic protocol standardization and hyperscaler bundling strategies represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Application Control Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Identity Governance and Administration Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Security Software for Consumers Market
Security Software
Spam Blocking Software Market
Security Software
Global Privileged Access Management (PAM) Solutions Market
Security Software
Security Testing Market
Security Software
Europe Encryption Software Market
Security Software
Mobile Threat Management Security Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Global Data Classification Market
Security Software
Global User Activity Monitoring Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
GDPR Software and Tools Market