
 Australia Telecom Tower Market | 2026-2036
Australia Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Telecom Tower Market Insights
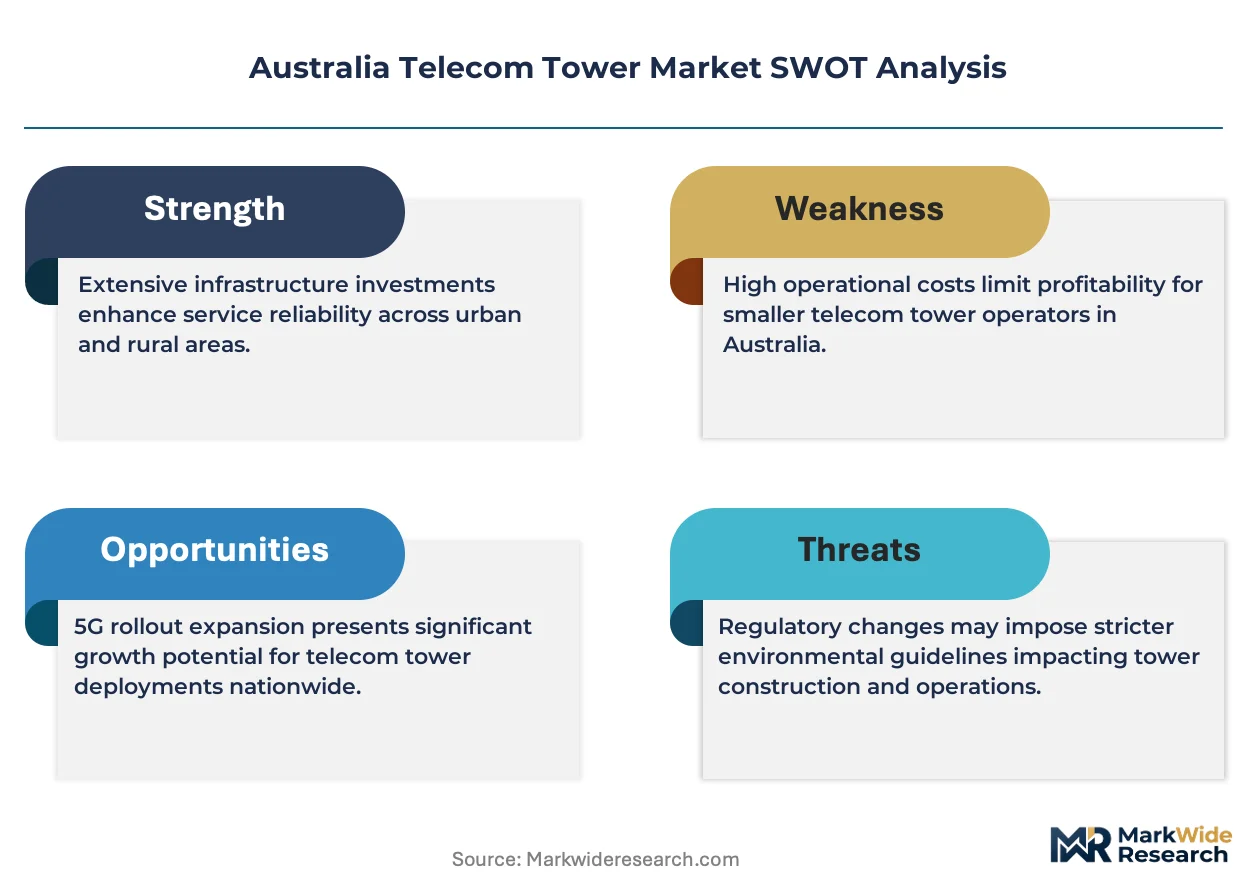
A shift from carrier-owned towers to third-party infrastructure sharing is pivoting capital allocation across the sector. Amplitel leverages its Telstra heritage to dominate tenancy ratios in metropolitan rings. BAI Communications sustains competitive positioning through specialized broadcast and transit corridor coverage. Indara Digital Infrastructure anchors its growth model on regional and rural site consolidation.
Australia telecom towers are steel or composite structures ranging from 15 to 120 meters in height, engineered to host multiple antenna arrays, transmission equipment, and power systems for wireless communication networks. These structures serve the fundamental commercial purpose of extending radio frequency coverage across vast geographic areas with low population density. Lattice tower configurations retain the largest installed base due to their load-bearing capacity for multi-tenant 5G equipment, while stealth tower demand accelerates fastest in urban heritage zones where visual impact restrictions apply. Microwave backhaul technology segments command premium tenancy rates as fiber optic extension proves uneconomical across remote terrain.
The Australian Communications and Media Authority governs spectrum allocation and electromagnetic emission standards, directly influencing tower placement density and height restrictions. The Australian Competition and Consumer Commission scrutinizes infrastructure access terms, shaping how tower companies negotiate tenancy pricing with mobile network operators. Standards Australia maintains structural loading and wind resistance codes that govern tower engineering specifications nationwide. Stakeholders must monitor how the federal government's regional connectivity programs reshape subsidy flows between urban tower oversupply and rural coverage gaps.
Market Dynamics
The Australian telecom tower sector pivots on spectrum densification mandates from the Australian Communications and Media Authority, which force mobile network operators to multiply site counts per coverage zone rather than expand macro tower footprints.
Growth Catalysts
- 5G mid-band rollout:Mobile network operators deploy 3.5 GHz infrastructure across Queensland mining corridors and Western Australia remote communities, creating sustained demand for multi-tenant lattice configurations.
- Regional Connectivity Program:Federal subsidy flows redirect capital toward greenfield rural deployments that private tower economics previously excluded from buildout schedules.
- Stealth tower technology:Local councils in Sydney and Melbourne heritage zones approve concealed monopole designs that circumvent visual impact objections blocking traditional lattice permits.
Market Restraints
- Steel price volatility:Raw material input costs for lattice tower fabrication fluctuate with global iron ore markets, compressing margin predictability for infrastructure builders.
- Electromagnetic emission compliance:Australian Communications and Media Authority proximity restrictions limit co-location density in suburban zones, capping tenancy revenue per structure.
- Fiber backhaul economics:Terrestrial cable deployment across the Nullarbor and Pilbara regions remains uneconomical, forcing reliance on microwave links with higher maintenance burdens.
Strategic Opportunities
- Tasmanian coverage gaps:Bass Strait island communities and rugged highland terrain present underserved demand pockets for specialized off-grid tower solutions with solar-hybrid power.
- Broadcast-transit convergence:BAI Communications' rail corridor infrastructure offers template for integrating passenger Wi-Fi, emergency services, and commercial mobile onto unified mast structures.
- Indigenous land access frameworks:Native title agreements create preferential siting pathways for towers on Aboriginal-owned land, accelerating permitting timelines versus Crown land processes.
Industry Challenges
- RF engineer scarcity:Specialized electromagnetic field planning expertise concentrates in Sydney and Melbourne, forcing regional deployments to absorb premium labor mobility costs or accept design quality trade-offs.
- Legacy 3G decommissioning:Equipment removal obligations from Telstra and Optus impose parallel site access coordination burdens without corresponding revenue offsets during 5G overlay construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Telecom Tower Market |
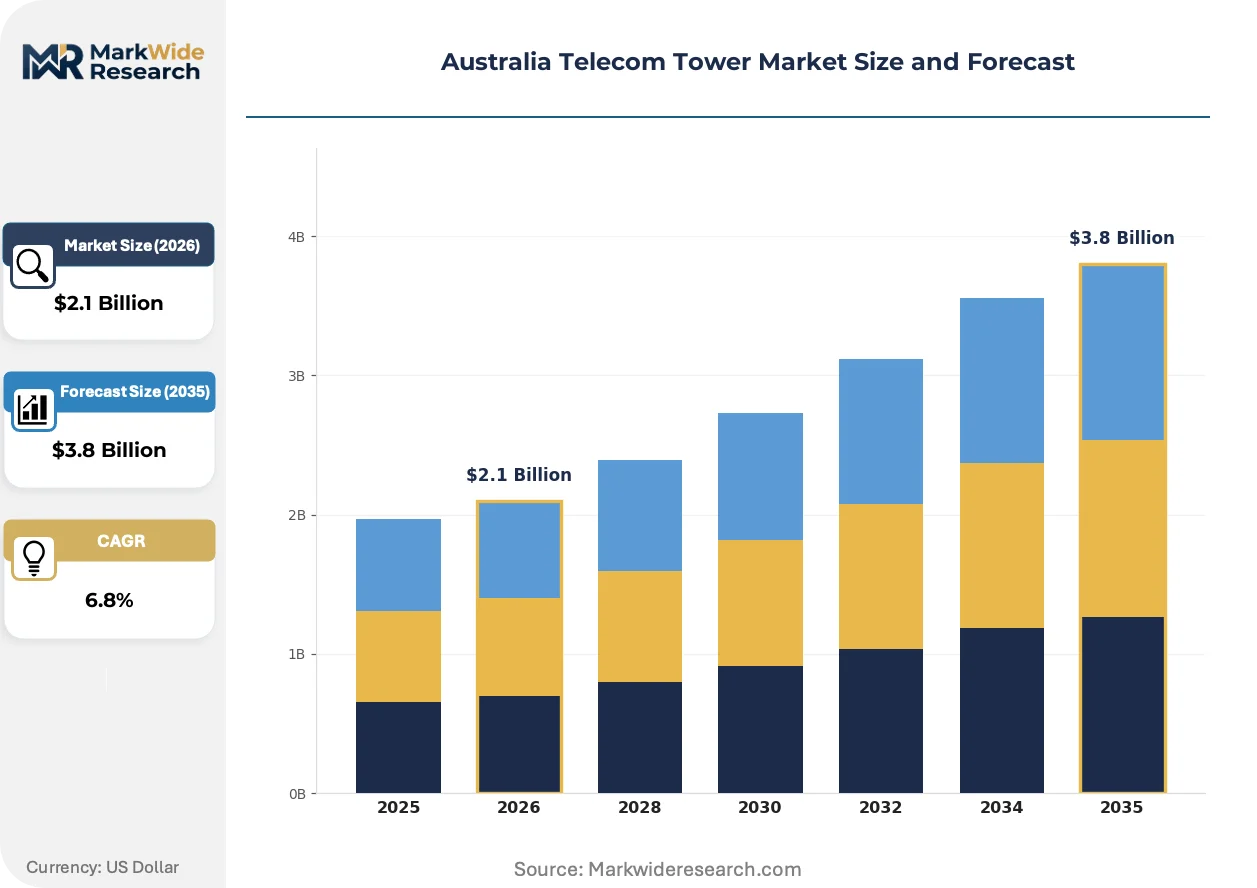
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice Tower, Guyed Tower, Stealth Tower End User: MNOs, Tower Companies, Private Enterprises, Government Agencies Deployment Model: Onshore, Offshore, Urban, Rural Technology: LTE, 5G, Microwave, Fiber Optics |
| Companies Covered | Amplitel, Indara Digital Infrastructure, Waveconn, BAI Communications, Everest Infrastructure Partners AU, Telstra Group, Optus, TPG Telecom, Macquarie Telecom Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Telecom Tower Market Trends and Innovations
Active network sharing agreements and edge computing integration are restructuring how tower assets generate returns beyond basic tenancy rentals.
Containerized edge data centers are electrifying tower base compounds into distributed compute nodes. Mobile network operators lease rack space for low-latency video analytics and autonomous vehicle coordination. Regional Queensland mining operators now specify tower infrastructure with redundant power and climate control for on-site server hosting, compressing the traditional separation between telecommunications and IT infrastructure procurement.
The Australian Competition and Consumer Commission's 2024 infrastructure access determinations mandate standardized tenancy pricing disclosure. Tower companies must publish reference offers for dark fiber and power backup services. Smaller regional mobile virtual network operators leverage this transparency to negotiate colocation terms previously accessible only to tier-one carriers, eroding the historical information asymmetry in lease negotiations.
Consolidated procurement through tower companies is displacing direct vendor relationships between mobile network operators and original equipment manufacturers. Amplitel and Indara Digital Infrastructure now aggregate antenna and radio unit purchases across multiple tenants, extracting volume discounts unavailable to single-carrier deployments. This shift concentrates technical specification influence with infrastructure owners rather than network operators, most visible in Western Australia where remote site logistics amplify procurement scale advantages.
Australia Telecom Tower Market Segmentation
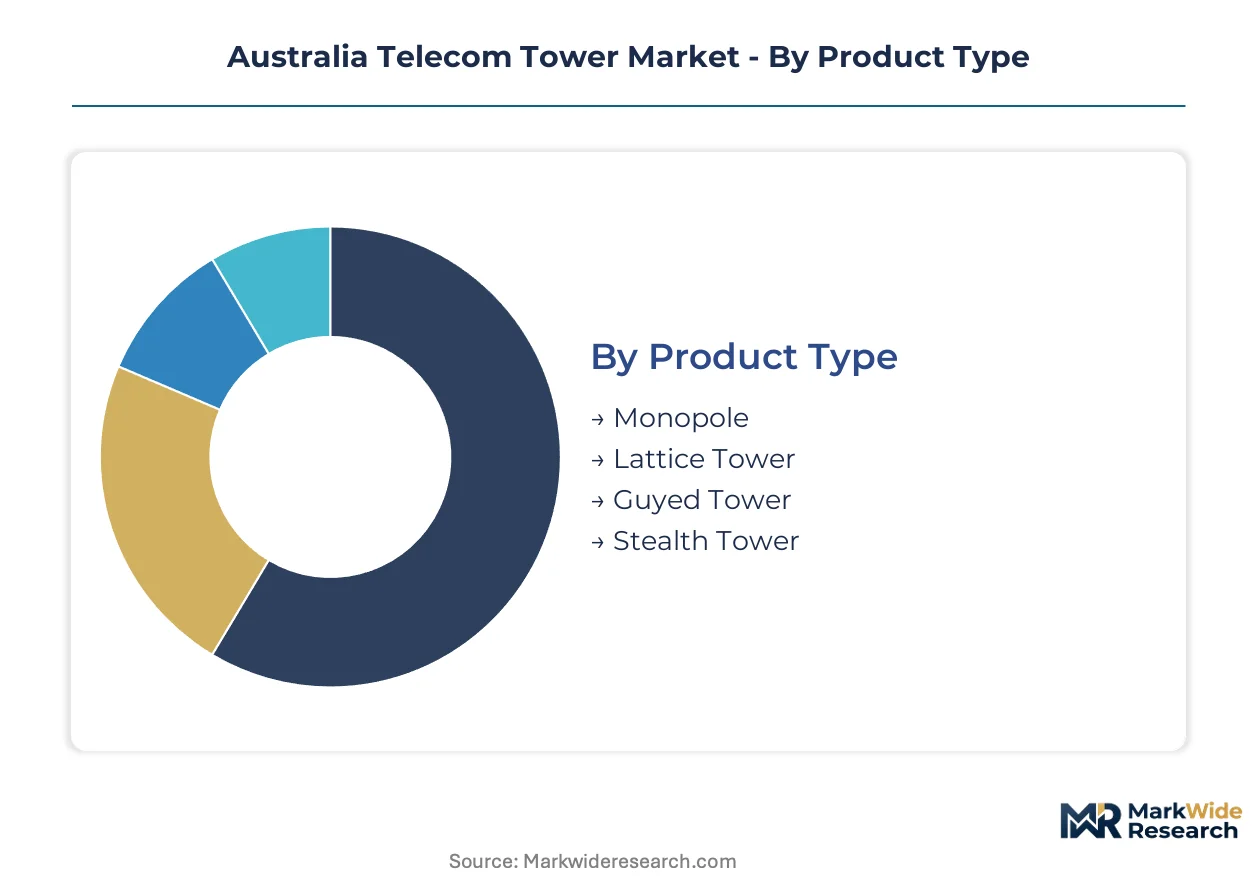
Capital allocation across Australia's telecom tower sector diverges sharply by structural configuration and tenancy model. Investment intensity varies from standardized urban monopoles to specialized offshore installations requiring marine-grade engineering.
Product Type:
Capital intensity peaks with lattice configurations engineered for multi-tenant load-bearing capacity across remote terrain.
- Monopole:Single-pole steel or composite structures ranging 15-45 meters, optimized for suburban and metropolitan zoning compliance. Demand clusters in Sydney and Melbourne heritage precincts where visual impact restrictions dominate permitting outcomes.
- Lattice Tower:Triangular or square-section steel frameworks reaching 120 meters, designed for heavy antenna arrays and microwave backhaul equipment. Queensland mining corridors and Western Australia remote communities drive sustained procurement for multi-tenant 5G densification.
- Guyed Tower:Mast structures stabilized by tension cables, deployed where footprint constraints exceed height requirements. Cost efficiency attracts regional broadcast and emergency services applications.
- Stealth Tower:Concealed designs mimicking architectural or natural features, manufactured for local council approval in sensitive visual zones. Heritage overlay districts in capital cities accelerate specification.
Most installed capacity flows through lattice configurations. Expansion is steepest in stealth tower specifications.
End User:
Tenancy economics reshape procurement authority, with infrastructure specialists displacing carrier direct ownership.
- MNOs:Mobile network operators including Telstra, Optus, and TPG Telecom retain build-to-suit programs for strategic coverage gaps while divesting passive infrastructure to specialist owners. Spectrum densification mandates from the Australian Communications and Media Authority force accelerated site acquisition.
- Tower Companies:Amplitel, BAI Communications, and Indara Digital Infrastructure aggregate tenancy portfolios across multiple carriers, extracting scale economies in power backup and site maintenance. Their procurement specifications now dominate antenna and radio unit standards.
- Private Enterprises:Mining operators and logistics corridors commission captive towers for fleet management and autonomous vehicle coordination. Queensland resource projects specify containerized edge compute integration at tower bases.
- Government Agencies:Federal Regional Connectivity Program subsidies redirect capital toward uneconomic rural deployments. State emergency services mandate hardened infrastructure for bushfire and flood response networks.
Carrier direct ownership still dominates installed base. Specialist tower companies are capturing new deployment volume fastest.
Deployment Model:
Site logistics and backhaul availability segment capital requirements across geographic contexts.
- Onshore:Continental deployments spanning coastal population belts and inland transport corridors. Standardized construction methods and established supply chains compress deployment timelines.
- Offshore:Bass Strait island installations requiring marine logistics, corrosion-resistant materials, and satellite or submarine cable backhaul. Tasmanian coverage gaps present specialized procurement opportunities.
- Urban:High-density metropolitan zones with fiber backhaul availability and restrictive zoning codes. Stealth configurations and rooftop colocations predominate.
- Rural:Low-density regional and remote areas dependent on microwave backhaul and solar-hybrid power systems. Federal subsidy programs offset uneconomic standalone economics.
Urban deployments concentrate tenancy revenue per site. Rural greenfield construction is expanding most quickly under subsidy programs.
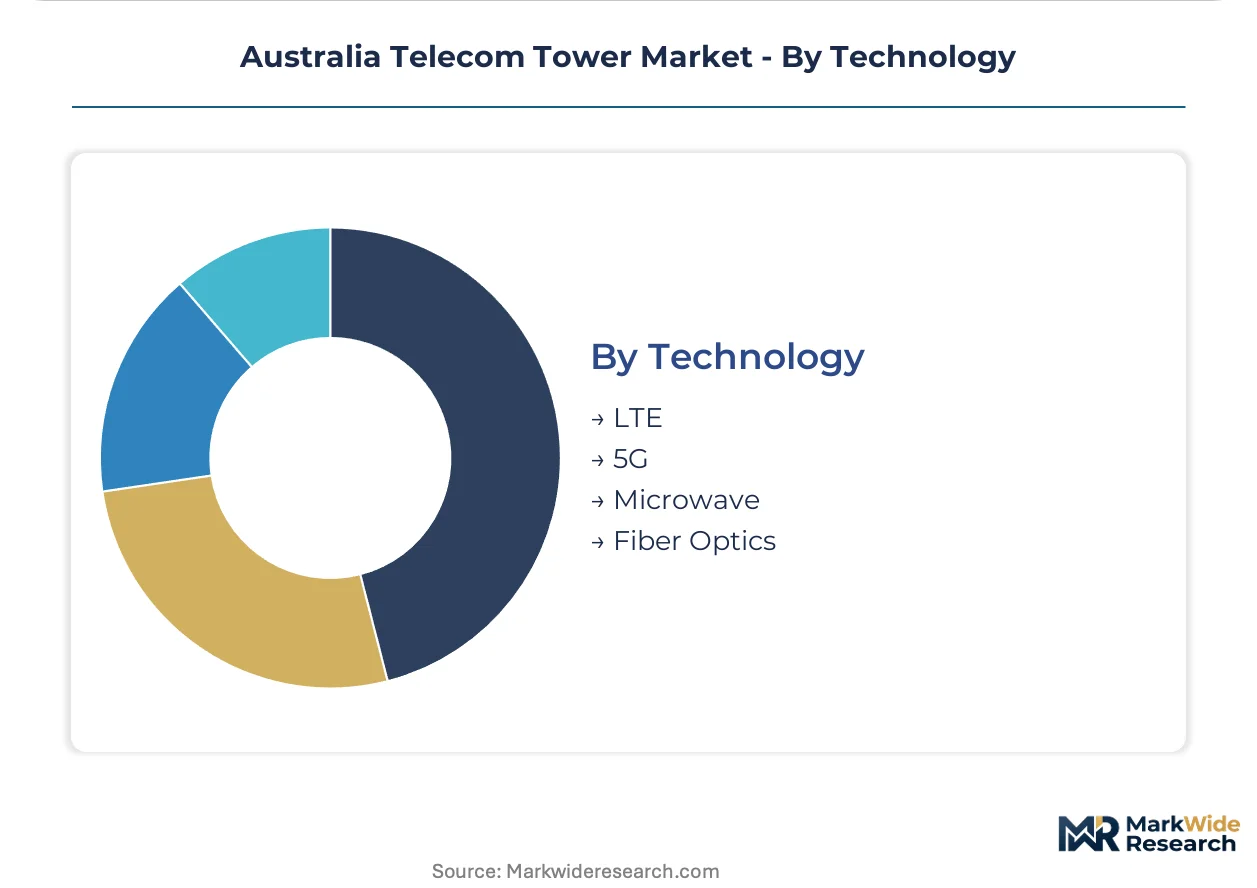
Technology:
Radio access generation and backhaul medium determine equipment loading specifications and power requirements.
- LTE:Legacy 4G infrastructure facing overlay requirements and eventual decommissioning obligations. Equipment removal coordination burdens site access without offsetting revenue.
- 5G:Mid-band 3.5 GHz and millimeter-wave deployments demanding densified site counts and upgraded power systems. Australian Communications and Media Authority spectrum reforms accelerate rollout timelines.
- Microwave:Point-to-point radio backhaul essential across remote terrain where fiber deployment proves uneconomical. Nullarbor and Pilbara regions remain dependent on microwave links with higher maintenance intensity.
- Fiber Optics:Terrestrial cable backhaul where population density justifies trenching economics. Metropolitan rings and coastal corridors achieve lowest latency through fiber termination at tower bases.
5G overlay construction commands current capital deployment. Microwave backhaul retains indispensable status in remote coverage zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland mining corridors anchor Australian tower deployment intensity. Western Australia remote communities and Tasmanian coverage gaps concentrate greenfield investment. New South Wales and Victoria metropolitan rings drive stealth tower specifications for heritage compliance.
New South Wales
Sydney metropolitan densification and regional transport corridors sustain multi-tenant lattice demand. The Australian Communications and Media Authority spectrum reforms accelerate 3.5 GHz site acquisition timelines. Greater Sydney heritage precincts concentrate stealth tower approvals where visual impact restrictions block conventional structures.
Victoria
Melbourne metropolitan rings and regional rail corridors generate sustained infrastructure procurement. Standards Australia wind loading codes govern structural specifications for Bass Strait-adjacent installations. The Latrobe Valley and Gippsland industrial cluster hosts broadcast-transit convergence projects integrating passenger connectivity networks.
Queensland
Bowen Basin mining operations and remote community connectivity programs drive specialized tower configurations. Federal Regional Connectivity Program subsidies redirect capital toward uneconomic rural deployments previously excluded from private buildout schedules. Mount Isa and Gladstone industrial zones specify containerized edge compute integration at tower bases.
Western Australia
Pilbara mining corridors and Nullarbor transit routes depend on microwave backhaul where fiber deployment proves uneconomical. Native title agreements create preferential siting pathways on Aboriginal-owned land versus Crown land processes. Karratha and Port Hedland logistics hubs anchor procurement for autonomous vehicle coordination infrastructure.
Tasmania
Bass Strait island communities and rugged highland terrain present underserved demand for off-grid tower solutions. Marine logistics and corrosion-resistant materials requirements elevate capital intensity for offshore installations. Hobart metropolitan zones and Launceston regional centers concentrate fiber-backhaul-enabled urban deployment.
Australia Telecom Tower Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized regional coverage and edge compute integration. The Australian tower sector consolidates around infrastructure specialists with carrier heritage and broadcast-transit convergence capabilities. Three archetypes dominate: tenancy aggregators extracting scale economies, regional consolidation specialists, and integrated carrier-tower hybrids. Competitive positioning hardens through site portfolio acquisitions and standardized procurement specifications that displace direct operator-vendor relationships.
Among carrier-derived infrastructure specialists, Amplitel leverages its Telstra heritage to dominate metropolitan tenancy ratios. BAI Communications sustains positioning through broadcast and transit corridor specialization. Indara Digital Infrastructure anchors growth on regional site consolidation across Queensland and Western Australia remote zones. These three occupy distinct competitive vectors without direct overlap in geographic or functional positioning.
| Leading Market Players |
|---|
| Amplitel |
| Indara Digital Infrastructure |
| Waveconn |
| BAI Communications |
| Everest Infrastructure Partners AU |
| Telstra Group |
| Optus |
| TPG Telecom |
| Macquarie Telecom Group |
| Others |
Pricing and Supply Chain Analysis
Federal Regional Connectivity Program procurement concentration anchors pricing power with specialist tower companies, forcing mobile network operators toward standardized tenancy rate cards mandated by the Australian Competition and Consumer Commission.
Pricing Analysis
Steel price volatility in global iron ore markets passes through directly to lattice tower fabrication costs, compressing margin predictability for infrastructure builders. Three-tier pricing structure across premium metropolitan tenancy, standard regional colocation, and economy rural subsidy-dependent deployments separates revenue tiers. Pricing pressure stems from electromagnetic emission compliance proximity restrictions that cap co-location density in suburban zones. Government agencies exhibit highest price sensitivity due to fixed subsidy allocations, while mining operators show lowest sensitivity given captive infrastructure requirements.
Supply Chain Analysis
Regional distribution centers in Perth, Brisbane, and Sydney anchor hub-and-spoke logistics for tower component staging across remote deployment zones. Manufacturing concentration rests on China for steel lattice sections, South Korea for microwave radio equipment, and domestic Australian fabricators for monopole assemblies. Raw material dependencies include high-tensile structural steel, galvanized cable assemblies, and lithium-ion battery storage systems. Single-source vulnerability runs through specialized RF filter suppliers for 3.5 GHz 5G equipment. Distribution runs through Amplitel and Indara Digital Infrastructure consolidated procurement platforms that aggregate multi-tenant antenna purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian Communications and Media Authority spectrum densification mandates compound demand through regulatory obligation rather than organic carrier economics, creating structural procurement volume.
For Market Incumbents: Extend tenancy ratio optimization across Queensland mining corridors and Western Australia remote zones before BAI Communications consolidates broadcast-transit convergence assets. Defend against Indara Digital Infrastructure's regional site aggregation by securing Native Title land access agreements that accelerate permitting timelines. Prioritize containerized edge compute integration at tower bases to capture mining operator IT infrastructure procurement. For New Entrants and Emerging Players: Australian Communications and Media Authority spectrum reforms in regional Australia open a window for specialized off-grid tower solutions targeting Tasmanian coverage gaps and Bass Strait island communities. White-space concentration sits with solar-hybrid power systems for uneconomic rural deployments excluded from private buildout schedules. Entry through Indigenous land access frameworks offers preferential siting pathways versus Crown land processes. For Investors and Strategic Acquirers: Infrastructure funds with broadcast heritage are the most active acquirer in this space, seeking carrier-tower convergence platforms with tenancy aggregation scale. Long-term viability hinges on 5G mid-band densification sustaining site count multiplication across low-population-density terrain. Signal to monitor: microwave backhaul equipment procurement volumes in Pilbara and Nullarbor regions as fiber economics threshold indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Native Title Land Access Agreements | Accelerates permitting timelines on Aboriginal-owned land versus Crown land processes in Western Australia. |
| Containerized Edge Compute Integration | Captures mining operator IT infrastructure procurement at Queensland Bowen Basin tower bases. |
| Stealth Tower Specification Expansion | Unlocks Sydney and Melbourne heritage precinct deployments blocked by visual impact restrictions. |
| Microwave Backhaul Technology Investment | Secures indispensable status across Nullarbor and Pilbara regions where fiber remains uneconomical. |
| Regional Site Portfolio Consolidation | Extracts scale economies in power backup and maintenance across Queensland and Western Australia. |
Research Methodology
Multiple input streams — tower company procurement directors, mobile network operator infrastructure planners, Australian Communications and Media Authority spectrum policy leads, regional mining operator IT executives — were reconciled against regulatory filings and steel import customs data. Secondary validation drew from Australian Competition and Consumer Commission infrastructure access determinations, Standards Australia structural loading codes, and federal Regional Connectivity Program subsidy disbursement records. Bottom-up site deployment modeling and top-down sector revenue triangulation anchored market size estimation.
Cross-referencing historical tenancy rate evolution against industry panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include structural configuration type, deployment geography, radio access generation, and backhaul technology medium. CAGRs were derived from site densification requirements tied to spectrum allocation timelines and subsidy program budget trajectories. Forecast inputs incorporated microwave equipment procurement patterns and solar-hybrid power system adoption curves for off-grid installations.
Revisions become necessary when Australian Communications and Media Authority emission standard changes, iron ore price volatility thresholds, or Indigenous land access framework modifications materialize outside baseline assumptions. Forecasts reflect documented parameter sets without claiming predictive certainty. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Utility Communications Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Hungary ICT Market
Telecommunications
Managed M2M Services Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Switzerland Telecom Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Broadband Services Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Optical Fronthaul Market