
 Global IT Outsourcing Services Market | 2026-2036
Global IT Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global IT Outsourcing Services Market Foresight
Single-source captive IT operations is pivoting toward multi-vendor ecosystems as enterprises seek resilience and specialized capability access. Accenture leverages its global delivery network to anchor complex transformation programs across financial services and healthcare clients. Tata Consultancy Services sustains dominant scale in infrastructure management through its integrated automation platforms and workforce depth. IBM Corporation differentiates via hybrid cloud consulting strength, positioning its Red Hat portfolio as a foundational layer for client modernization roadmaps.
IT outsourcing services encompass the contractual delegation of information technology functions—spanning application development, infrastructure management, cloud services, and business process outsourcing—to external providers operating under defined service-level agreements with measurable uptime, security, and performance parameters. These arrangements enable client organizations to convert fixed technology costs into variable operating expenditures while accessing specialized skills unavailable in-house. Cloud services within the service-type dimension is capturing accelerated investment as enterprises migrate legacy workloads to distributed environments. The deployment-model split reveals hybrid structures gaining preference, blending onshore accountability with offshore cost arbitrage rather than maintaining pure offshore or nearshore configurations.
India's BIS standards for data center infrastructure, the EU's GDPR framework governing cross-border data processing, and the US SEC's cybersecurity disclosure rules for publicly traded firms collectively elevate compliance complexity in vendor selection and contract structuring. These regulatory layers mandate audit trails, incident reporting protocols, and geographic data residency that directly influence outsourcing location strategy and provider certification requirements. Stakeholders must monitor evolving AI governance frameworks across multiple jurisdictions to anticipate where compliance obligations will next reshape service delivery models and pricing structures.
Market Dynamics
Multi-vendor ecosystems are displacing single-source captive IT operations as enterprises seek resilience against supply disruptions and access to specialized capabilities. This structural pivot toward distributed delivery networks is fundamentally reshaping contract structures, risk allocation, and provider selection criteria across the outsourcing landscape.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face binding audit requirements for automated decision-making systems, driving demand for certified outsourcing partners with documented governance frameworks.
- Cloud migration acceleration:Financial services firms in the BFSI sector are expanding external provider relationships to manage complex workload transitions to distributed environments.
- India's delivery hub concentration:Bengaluru, Hyderabad, and Pune continue deepening their positions as primary locations for application development and infrastructure management services.
Market Restraints
- Cross-border data friction:GDPR's geographic data residency requirements create structural complexity in vendor selection and contract structuring for European-bound services.
- Specialized talent scarcity:Shortage of certified cybersecurity architects and cloud-native engineers constrains provider capacity expansion and service quality consistency.
- Hybrid infrastructure complexity:Technical limitations in seamless workload portability between on-premise and cloud environments increase integration costs and timeline uncertainty.
Strategic Opportunities
- US SEC cybersecurity disclosure rules:Publicly traded firms face new incident reporting mandates, creating demand for outsourced security operations centers with pre-built compliance documentation.
- Healthcare digitization gaps:Underpenetrated clinical systems in secondary markets present white space for specialized providers offering HIPAA-compliant managed services.
- AI governance convergence:Integration of machine learning operations with traditional IT service management is opening new contract categories for providers with dual competency.
Industry Challenges
- Legacy system entanglement:Mainframe-dependent financial institutions face execution complexity when integrating modern cloud services with decades-old core banking platforms.
- Multi-jurisdictional certification timelines:Providers must simultaneously maintain ISO 27001, SOC 2, and country-specific data center certifications, stretching compliance resources across audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IT Outsourcing Services Market |
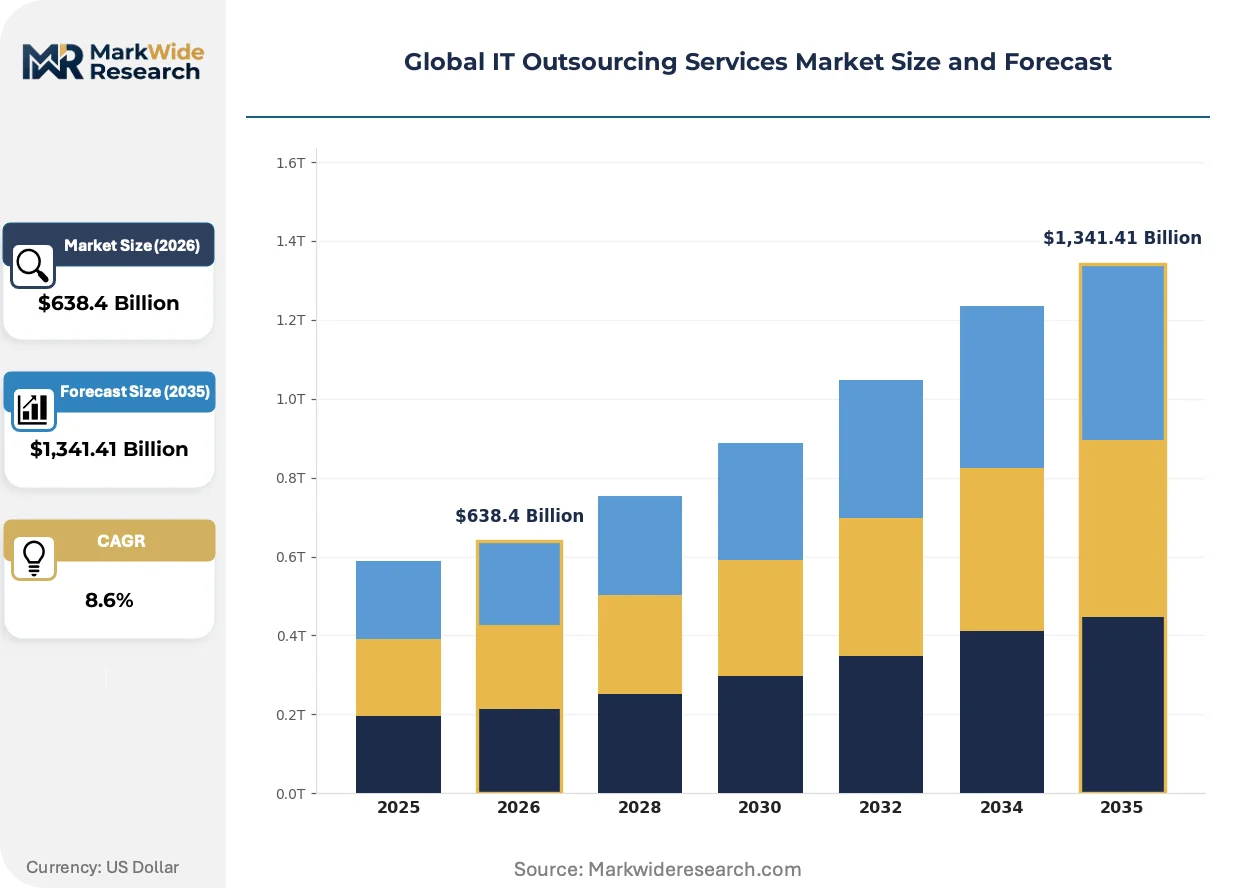
| Market Size in 2026 | $638.4 Billion |
| Market Size in 2035 | $1,341.41 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
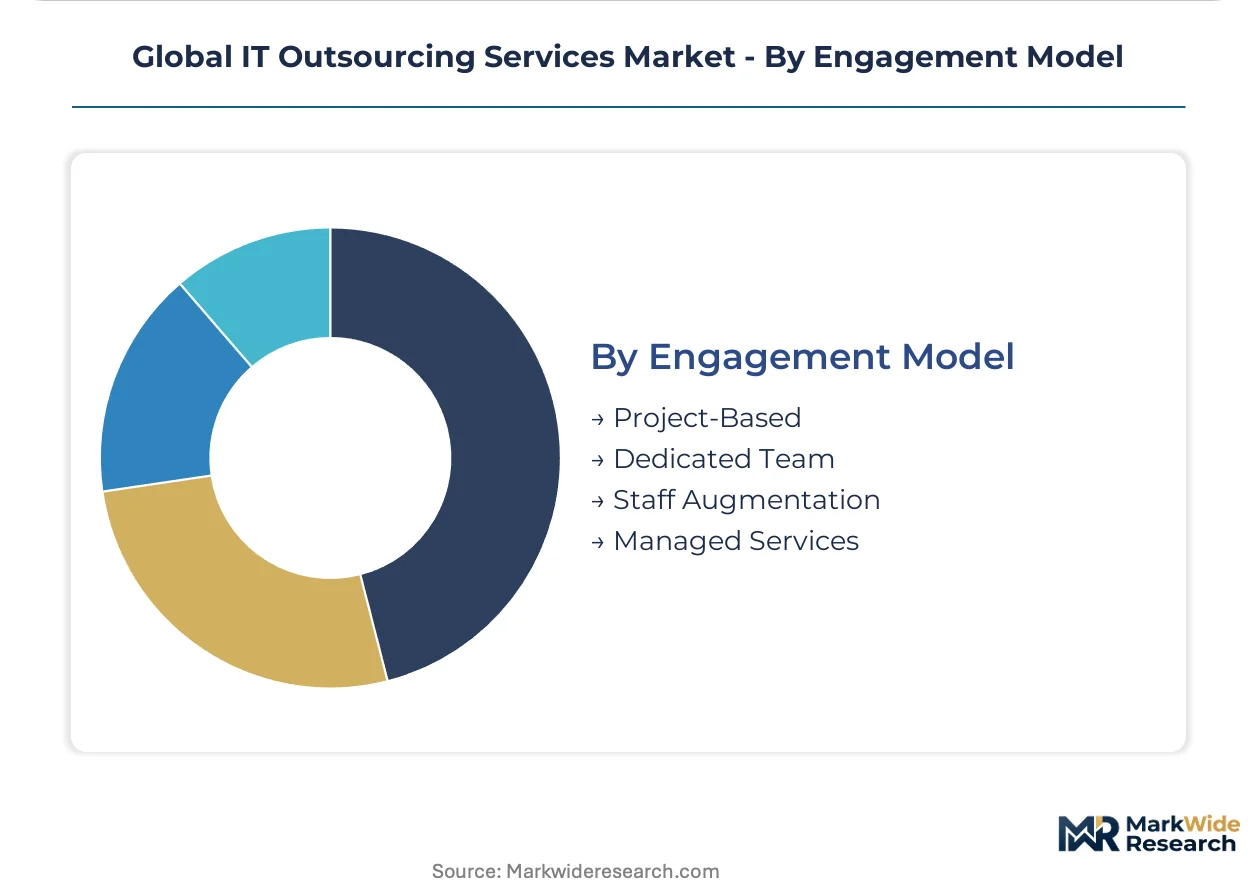
| Segmentation | Service Type: Application Development, Infrastructure Management, Cloud Services, Technical Support, Business Process Outsourcing, Analytics Services Deployment Model: Onshore, Offshore, Nearshore, Hybrid Client Industry: BFSI, Telecommunications, Manufacturing, Retail & E-commerce, Government, Education Engagement Model: Project-Based, Dedicated Team, Staff Augmentation, Managed Services |
| Companies Covered | Accenture, Tata Consultancy Services, Infosys Limited, IBM Corporation, Capgemini, Cognizant Technology Solutions Corporation, Wipro Limited, NTT DATA Corporation, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IT Outsourcing Services Market Shifts & Advancements
Generative AI capabilities are embedding into service delivery models, compressing traditional automation timelines and forcing providers to restructure workforce deployment. This technological inflection is simultaneously elevating client expectations and creating new competitive differentiation vectors.
Hybrid cloud management platforms are consolidating previously fragmented infrastructure orchestration tools into unified control planes. Large enterprises with distributed operations are adopting these integrated stacks at accelerated pace. This consolidation is compressing vendor margins while raising the technical bar for market participation.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes automated decisions. Financial services and healthcare providers face the steepest compliance obligations. European enterprises are responding by embedding audit rights and documentation requirements directly into outsourcing contracts.
Enterprise buyers are unbundling monolithic outsourcing agreements into modular service components with discrete pricing and performance metrics. Technology procurement teams are replacing single-master-service-agreement structures with portfolio-based vendor management. This pattern is most visible in North American financial services and healthcare verticals where cost transparency pressures are most acute.
Global IT Outsourcing Services Market Segmentation
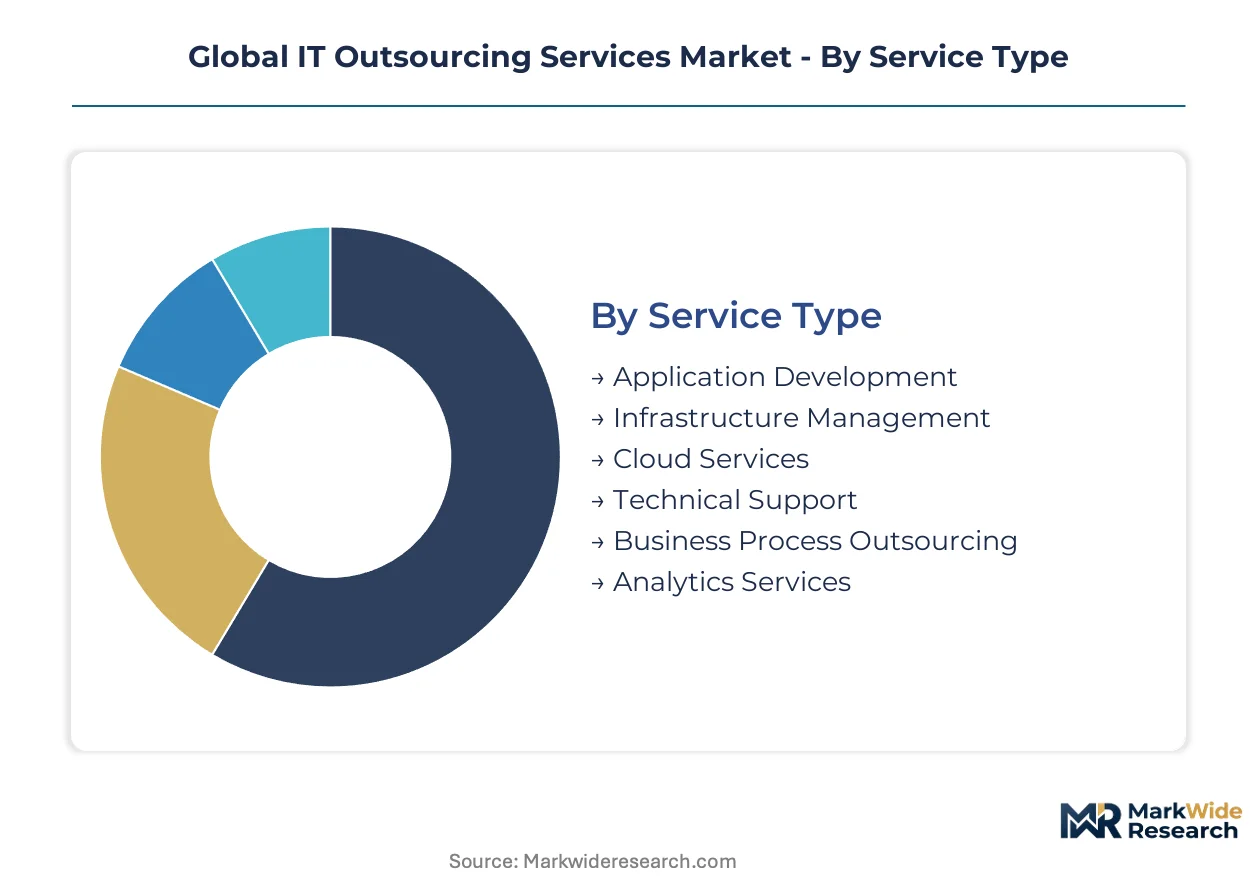
Service configuration determines how enterprises balance cost control against operational sovereignty. Procurement teams evaluate segments through the lens of compliance burden, talent access, and workload criticality rather than price alone.
Service Type:
Budget tier shapes provider selection more than any other factor, with premium segments commanding certified governance and economy segments competing on unit cost.
- Cloud Services:Distributed workload migration and container orchestration dominate contract scope. Financial services firms in Germany and the United States drive demand for FedRAMP and BSI-certified environments.
- Application Development:Custom software engineering spans legacy modernization and greenfield builds. India's Bengaluru and Hyderabad clusters absorb the majority of complex enterprise engagements.
- Infrastructure Management:Data center operations and network administration delivered under strict uptime guarantees.
- Technical Support:Help desk and field service operations with tiered response commitments.
- Business Process Outsourcing:Back-office functions including finance, HR, and customer operations.
- Analytics Services:Data engineering and business intelligence implementations.
Cloud Services leads on scale; Application Development leads on momentum.
Deployment Model:
Geographic dispersion of delivery teams directly determines regulatory exposure and labor arbitrage potential.
- Hybrid:Blended onshore-offshore structures balance accountability with cost efficiency. EU enterprises favor this model to satisfy GDPR data residency while retaining India-based engineering capacity.
- Offshore:India, Poland, and the Philippines anchor delivery with specialized talent pools and established vendor ecosystems.
- Onshore:Domestic delivery eliminates cross-border compliance complexity.
- Nearshore:Regional proximity for time zone alignment and cultural affinity.
Hybrid configurations dominate contract value; Offshore maintains the steepest expansion trajectory.
Client Industry:
Sector-specific compliance mandates filter provider eligibility before commercial terms enter discussion.
- BFSI:Banking and insurance operations face SEC cybersecurity disclosure rules and ECB oversight requirements. Cloud migration and fraud detection analytics concentrate procurement spending.
- Telecommunications:Network infrastructure management and customer billing systems. India's TRAI regulations and the United States' FCC frameworks govern data handling.
- Manufacturing:Supply chain systems and industrial IoT integration.
- Retail & E-commerce:Peak-load scaling and omnichannel platform support.
- Government:Sovereign cloud and classified systems with strict citizenship requirements.
- Education:Learning management systems and administrative modernization.
BFSI commands the largest contract sizes; Telecommunications is gaining share fastest.
Engagement Model:
Duration and outcome accountability define how risk distributes between client and provider.
- Managed Services:Long-term operational responsibility with outcome-based pricing. Healthcare providers in the United States adopt this for HIPAA-compliant security operations.
- Dedicated Team:Exclusive personnel assignment with client-directed priorities. Technology firms in Israel and Singapore favor this for product engineering velocity.
- Project-Based:Defined deliverables with fixed scope and timeline.
- Staff Augmentation:Temporary skill injection without operational handover.
Managed Services leads on scale; Dedicated Team leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru anchors global delivery capacity for application development and infrastructure management, with the city's vendor ecosystem absorbing complex enterprise migrations from financial services and healthcare clients across multiple continents.
United States
SEC cybersecurity disclosure mandates and FedRAMP certification requirements drive procurement of outsourced security operations centers. Financial services firms in New York and Chicago expand cloud migration contracts with audited partners. The Dallas-Fort Worth metroplex concentrates data center infrastructure serving domestic compliance-bound workloads.
Germany
EU AI Act risk classifications and BSI data center standards reshape vendor selection criteria for automated decision-making systems. Industrial manufacturers in Bavaria and Baden-Württemberg delegate IoT platform management to certified providers. Frankfurt's financial district demands GDPR-compliant hybrid delivery structures blending onshore accountability with offshore engineering.
India
BIS data center infrastructure standards and RBI oversight requirements govern cross-border service delivery to banking clients. Hyderabad and Pune deepen specialization in cloud-native engineering and cybersecurity operations. The National Capital Region attracts healthcare digitization contracts requiring HIPAA-aligned process documentation.
United Kingdom
FCA operational resilience directives and post-Brexit data adequacy arrangements complicate multi-jurisdictional contract structuring. London's insurance sector procures fraud detection analytics from providers with documented algorithmic governance. Manchester and Edinburgh emerge as secondary delivery hubs for technical support and business process outsourcing.
Japan
METI digital transformation incentives and JIS standards for IT service management elevate certification requirements in vendor procurement. Tokyo-based financial institutions integrate legacy mainframe systems with modern cloud architectures through specialized integration partners. Osaka's manufacturing base drives demand for industrial IoT managed services.
Global IT Outsourcing Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled automation and vertical-specific compliance specializations. The vendor base stratifies across three capability tiers: global integrators with multi-jurisdictional certification depth, regional specialists with sector-specific process expertise, and niche automation providers with machine learning operations competency. Consolidation pressure intensifies as clients unbundle monolithic contracts into modular components. Geographic expansion and strategic capability acquisitions represent the dominant competitive moves as providers defend position in high-compliance verticals.
Within the global integrator tier, Accenture and Tata Consultancy Services exemplify scale-driven positioning with established delivery networks across financial services and healthcare verticals. IBM Corporation occupies a hybrid cloud consulting position, anchoring modernization programs through its Red Hat portfolio foundation. These three entities represent the archetype of providers capable of absorbing complex multi-year transformation contracts with embedded regulatory compliance obligations.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services |
| Infosys Limited |
| IBM Corporation |
| Capgemini |
| Cognizant Technology Solutions Corporation |
| Wipro Limited |
| NTT DATA Corporation |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Certified cloud engineering talent in India flows through three distinct pricing tiers as client procurement teams balance FedRAMP compliance costs against offshore labor arbitrage. GDPR-mandated data residency in Germany and SEC disclosure requirements in the United States add compliance premiums that separate premium managed services from economy staff augmentation contracts.
Pricing Analysis
Input-cost pass-through from certified cybersecurity architects and cloud-native engineers drives margin compression across standard-tier providers. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified managed services from uncertified staff augmentation, with customization depth and SLA guarantees as the primary differentiation vectors. Price erosion runs through the economy tier as Indian vendors compete on unit rates for commodity application development. Healthcare providers in the United States show least price sensitivity due to HIPAA compliance mandates, while mid-market retailers drive hardest bargain on technical support contracts.
Supply Chain Analysis
Specialized talent supply rests on Indian engineering institutes, Polish technical universities, and Philippine business process training centers. Cloud infrastructure provisioning draws from hyperscaler data center networks, BSI-certified German facilities, and BIS-compliant Indian operations. Single-source vulnerability concentrates in certified cybersecurity architect pools where demand outstrips training pipeline output. Distribution runs through direct enterprise sales teams for complex transformation contracts and channel partners for standardized managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
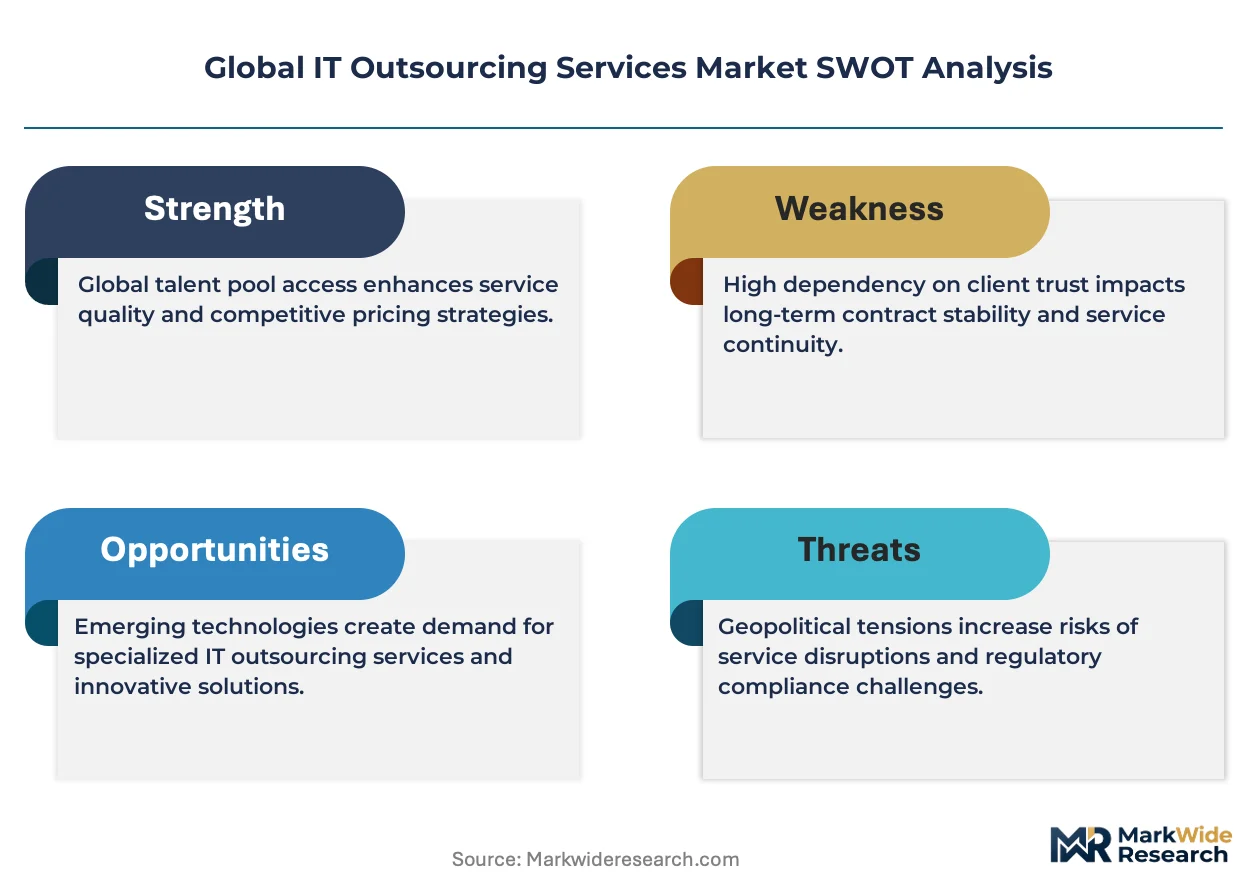
Margin expansion in IT outsourcing services hinges on automation platform deployment compressing delivery headcount per contract and clients upgrading to premium compliance tiers under regulatory pressure.
For Market Incumbents: Deepen vertical integration into proprietary automation platforms to defend against AI-native entrants eroding application development margins. Accentuate FedRAMP and BSI certification moats as regulatory complexity rises. Lock in multi-year managed services contracts with healthcare and BFSI clients before compliance mandates fully mature. For New Entrants and Emerging Players: EU AI Act in Germany opens a window for algorithmic governance specialists to capture audit and documentation services from incumbent generalists. Target underpenetrated clinical systems in secondary US markets with HIPAA-aligned process documentation as the wedge offering. Lead with AI operations tooling that integrates with existing IT service management stacks rather than rip-and-replace positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier compliance specialists because multi-jurisdictional certification requirements create barriers that favor scaled platforms over fragmented boutiques. Focus on providers with ISO 27001, SOC 2, and EU AI Act readiness across the analysis window. Watch for hyperscaler partnership announcements as the inflection signal indicating which automation platforms achieve enterprise distribution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Integration | Compresses delivery headcount per contract while elevating SLA performance for BFSI clients. |
| Multi-Jurisdictional Certification Investment | Builds moats against uncertified competitors as EU AI Act and SEC rules tighten vendor eligibility. |
| Healthcare Vertical Specialization | Captures HIPAA-compliant security operations spending from US providers facing talent scarcity. |
| Hybrid Cloud Consulting Capability | Positions providers for mainframe-to-cloud integration contracts at German and Japanese financial institutions. |
| AI Governance Service Development | Opens new contract categories as European enterprises embed audit rights into outsourcing agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from CTOs at financial services firms, IT procurement officers at healthcare systems, platform engineers at hyperscaler partners, and integration specialists at global systems integrators. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, BIS data center infrastructure standards, and RBI cross-border service delivery circulars. Bottom-up contract value estimates triangulated against top-down market sizing from delivery hub capacity analysis.
Segment-weighting across service type, deployment model, client industry, and engagement model dimensions shaped the analytical framework. CAGRs derived from elasticity modeling against cloud migration investment cycles and regulatory compliance spending trajectories. Workforce pipeline data from Indian technical institutes and Polish engineering programs informed capacity expansion assumptions. Hyperscaler capex disclosures and BFSI technology budget surveys provided demand-side calibration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt tariff shifts or accelerated AI automation adoption. Projections reflect assumptions about regulatory implementation timelines and talent supply elasticity. A small set of named triggers warrants ongoing watch: EU AI Act enforcement intensity, SEC cybersecurity disclosure litigation volume, and Indian engineering graduate output trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market