
 Internet Filter Software Market | 2026-2036
Internet Filter Software Market Size, Share, and Industry Trends Forecast 2026-2036
Internet Filter Software Market Insights
Cloud-native DNS architectures are repositioning traditional appliance-based filtering economics toward subscription models with lower upfront capital requirements. Cisco Umbrella leverages its DNS-layer security heritage to anchor enterprise deployments across distributed workforces. Zscaler sustains competitive pressure through zero-trust architecture integration that extends filtering into application-layer policies. DNSFilter specializes in mid-market channel delivery, competing on deployment speed against legacy gateway vendors.
Internet filter software comprises rule-based and machine-learning systems that inspect network traffic against categorized databases to enforce access policies, operating through DNS redirection, proxy inspection, or endpoint agents with throughput ratings exceeding 10 Gbps in enterprise appliances. Cloud-based deployment leads segment adoption as educational institutions and enterprises migrate from on-premise appliances to scalable SaaS platforms with API-driven policy management. Content filtering features command the largest feature-segment footprint, though malware protection integration is capturing fastest expansion as vendors bundle threat intelligence with access control. Browsing safety applications dominate volume, while compliance-driven deployments in government and regulated enterprises concentrate margin pools through audit-ready reporting modules.
The FCC's Children's Internet Protection Act mandates filtering in US schools receiving E-rate funding, while GDPR and the EU AI Act shape European requirements for automated content classification transparency. India's BIS cybersecurity framework and CERT-In directives are accelerating enterprise filter adoption beyond voluntary implementation. Stakeholders must evaluate whether AI-generated content detection capabilities will become a procurement prerequisite before the next regulatory cycle completes.
Market Dynamics
Cloud-native DNS filtering is compressing the traditional appliance market as educational institutions and enterprises abandon capital-intensive gateway hardware for subscription-based SaaS platforms with API-driven policy orchestration.
Growth Catalysts
- FCC E-rate mandates:US K-12 schools receiving federal connectivity subsidies must deploy CIPA-compliant filtering, creating recurring procurement cycles for cloud-based solutions with audit-ready reporting modules.
- Remote workforce security policies:Distributed enterprise teams require DNS-layer protection that travels with endpoints rather than tethering to physical gateways, accelerating zero-trust architecture adoption.
- EU AI Act transparency requirements:Automated content classification systems in European enterprises must demonstrate explainable decision-making, driving upgrades from opaque blocklist engines to auditable machine-learning platforms.
Market Restraints
- Input cost volatility:Threat intelligence feed licensing from specialized cybersecurity vendors constitutes 30-40% of platform operating costs, squeezing margins for mid-market SaaS providers.
- Technical latency constraints:Real-time SSL/TLS inspection at scale demands specialized hardware acceleration that cloud-native architectures struggle to match, limiting performance-sensitive financial services adoption.
- Regulatory fragmentation:India's CERT-In data localization directives conflict with global cloud filtering architectures, forcing vendors to maintain sovereign infrastructure instances.
Strategic Opportunities
- Underpenetrated Indian enterprise segment:BIS cybersecurity framework compliance deadlines are accelerating filter adoption beyond voluntary implementation among mid-sized domestic corporations.
- AI-generated content detection:Convergence of natural language processing with image classification enables real-time synthetic media identification, a capability procurement teams are evaluating ahead of anticipated regulatory mandates.
- Managed security service provider channels:MSSPs are bundling filtering with broader SOC offerings, creating indirect routes to small-business segments previously uneconomical for direct sales.
Industry Challenges
- Machine-learning engineer scarcity:Developing accurate multilingual content classification models requires specialized talent concentrated in US and European technology hubs, constraining vendor R&D velocity.
- Legacy proxy integration complexity:Enterprises with decade-old web gateway investments face painful migration paths to cloud-native architectures, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet Filter Software Market |
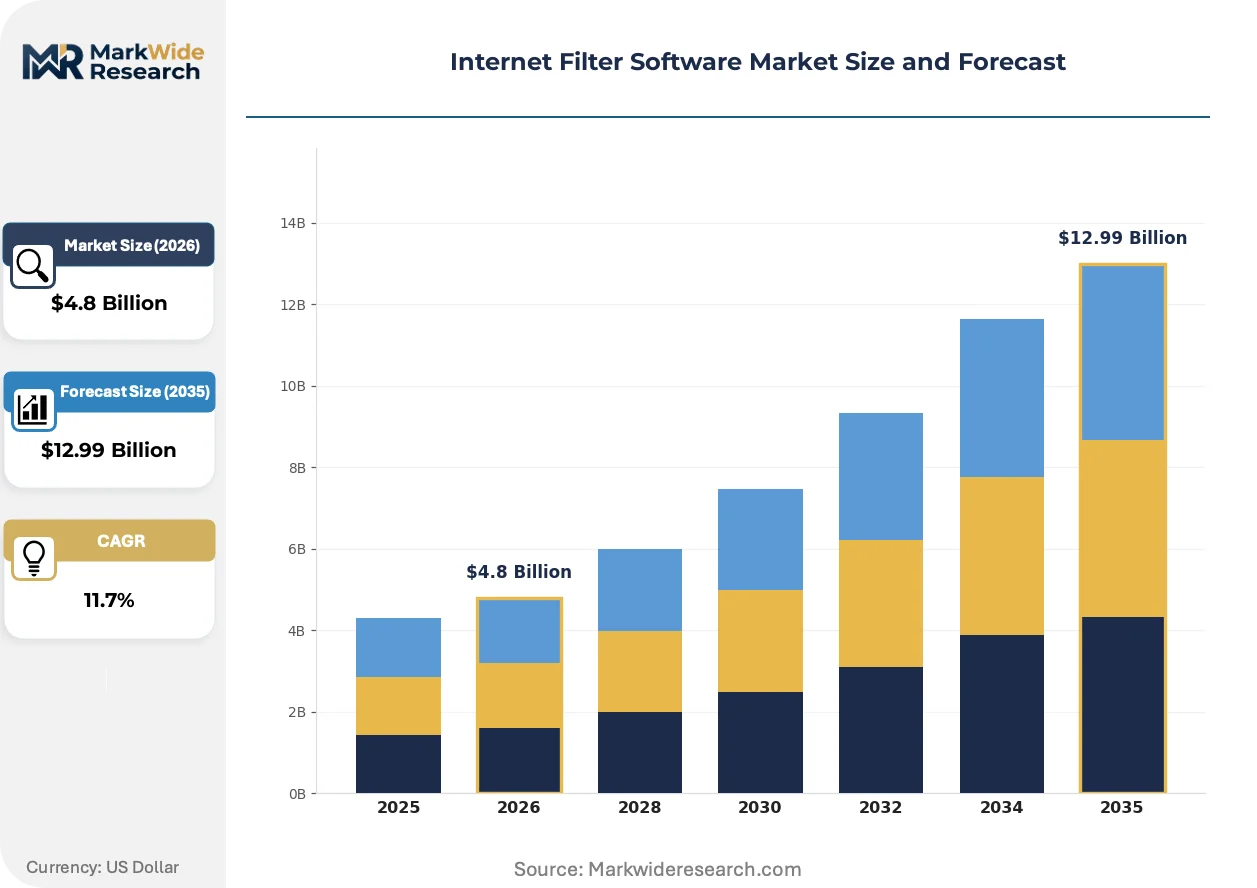
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Remote End User: Educational Institutions, Enterprises, Government, Individuals Feature: Content Filtering, Malware Protection, Reporting, User Management Application: Browsing Safety, Network Security, Compliance, Parental Control |
| Companies Covered | Cloudflare, OpenDNS, Net Nanny, CleanBrowsing, Kaspersky Safe Kids, Cisco Umbrella, DNSFilter, WebTitan, Zscaler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet Filter Software Market Trends and Innovations
Filtering architectures are converging toward single-vendor security stacks that embed access control within broader zero-trust frameworks, collapsing the standalone market into integrated platform competition.
Secure access service edge technology is unifying networking and security functions into cloud-delivered service bundles. Large enterprises with distributed workforces are adopting these consolidated platforms at accelerating rates. This convergence is compressing pricing power for standalone filtering vendors unable to match breadth.
The EU AI Act's automated decision-making transparency mandates are reshaping European procurement specifications. Vendors must now document classification logic and provide human-appeal mechanisms for blocked content. Educational institutions in Germany and France are leading this compliance-driven replacement cycle.
Buying committees are consolidating vendor relationships around platform breadth rather than best-of-breed point solutions. Channel partners report that procurement teams now prioritize unified security stacks over specialized filtering appliances. This preference shift is most pronounced among US healthcare systems navigating HIPAA technical safeguard requirements.
Internet Filter Software Market Segmentation
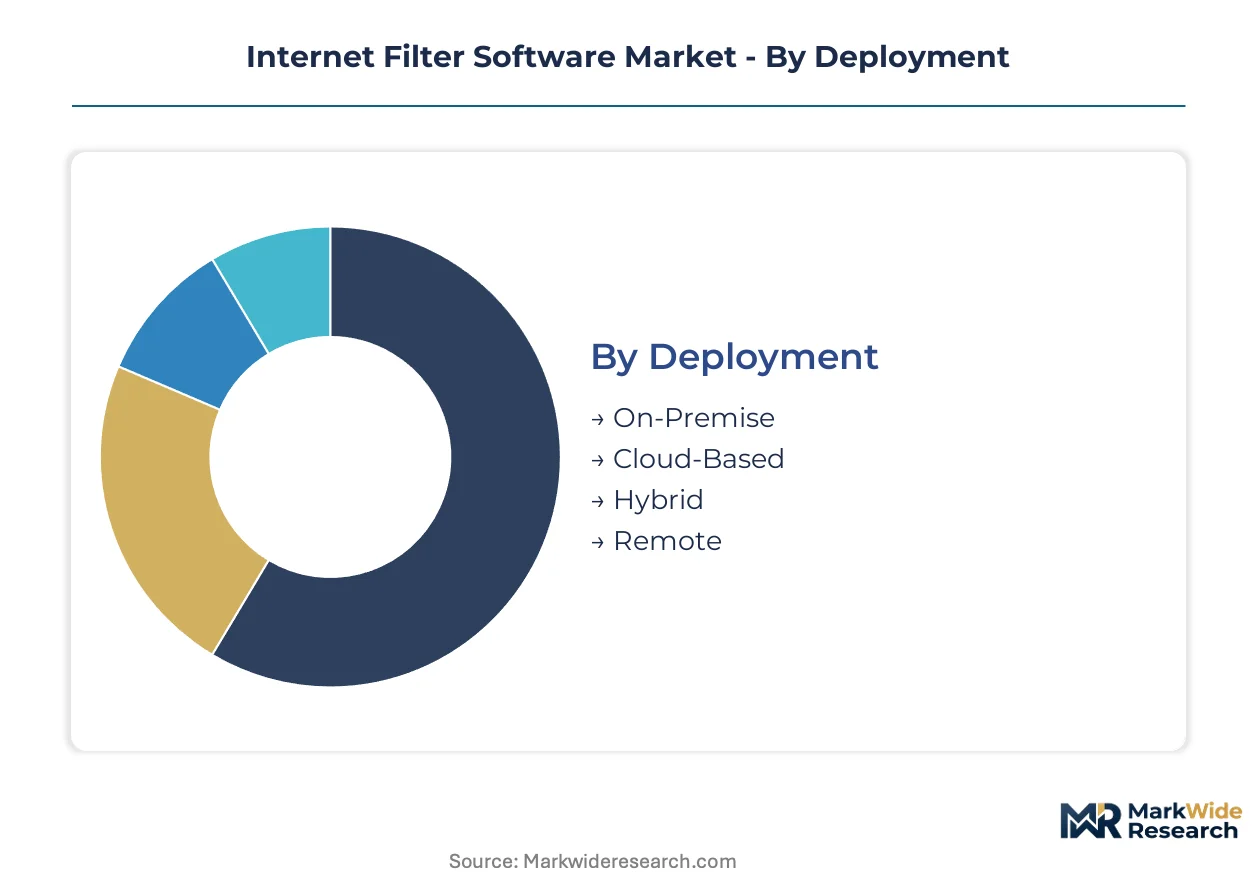
Internet filter software vendors structure product portfolios around deployment flexibility and compliance depth. Procurement teams evaluate segments through the lens of existing infrastructure investments and regulatory audit requirements.
Deployment:
Migration from capital-intensive hardware to subscription models is reshaping procurement patterns across institutional buyers.
- On-Premise:Physical appliance installations with dedicated hardware acceleration for SSL/TLS inspection. Financial services firms in Frankfurt and Singapore retain these deployments for sub-millisecond latency requirements.
- Cloud-Based:SaaS platforms with API-driven policy orchestration and DNS-layer enforcement. US K-12 districts receiving E-rate funding drive volume through CIPA-mandated procurement cycles.
- Hybrid:Split architectures routing critical traffic through local gateways while cloud handles distributed endpoints. Manufacturing conglomerates with branch networks favor this model for cost containment.
- Remote:Endpoint-resident agents enforcing policies independent of network location. Enterprise security teams deploy these for zero-trust workforce architectures.
Cloud-Based sits at the top of the volume ranking, with Remote climbing the fastest.
End User:
Customer type determines pricing tolerance and feature depth requirements across the install base.
- Educational Institutions:K-12 and university deployments requiring CIPA or GDPR-compliant audit trails. German federal states and Indian CBSE-affiliated schools are expanding procurement.
- Enterprises:Corporate networks with BYOD policies and remote workforce protection. Compliance-driven upgrades in regulated sectors concentrate margin pools.
- Government:Sovereign infrastructure mandates with data localization requirements. India's CERT-In directives accelerate domestic cloud instance deployments.
- Individuals:Consumer-grade parental control subscriptions with basic content blocking. Mobile-first adoption in emerging markets expands the addressable base.
Educational Institutions command the largest installed base, though Government is expanding most quickly.
Feature:
Capability bundling is shifting from standalone filtering toward integrated threat intelligence platforms.
- Content Filtering:URL categorization and keyword-based blocking with machine-learning classification. EU AI Act transparency mandates are forcing upgrades from opaque blocklist engines.
- Malware Protection:Real-time threat intelligence integration with sandboxing and behavioral analysis. MSSP channel bundling drives fastest segment expansion.
- Reporting:Audit-ready dashboards documenting policy enforcement and incident response. Healthcare systems navigating HIPAA technical safeguards prioritize this capability.
- User Management:Role-based access control with granular permission hierarchies. Large enterprises with complex organizational structures require this for policy segmentation.
Content Filtering retains the broadest footprint, with Malware Protection gaining share fastest.
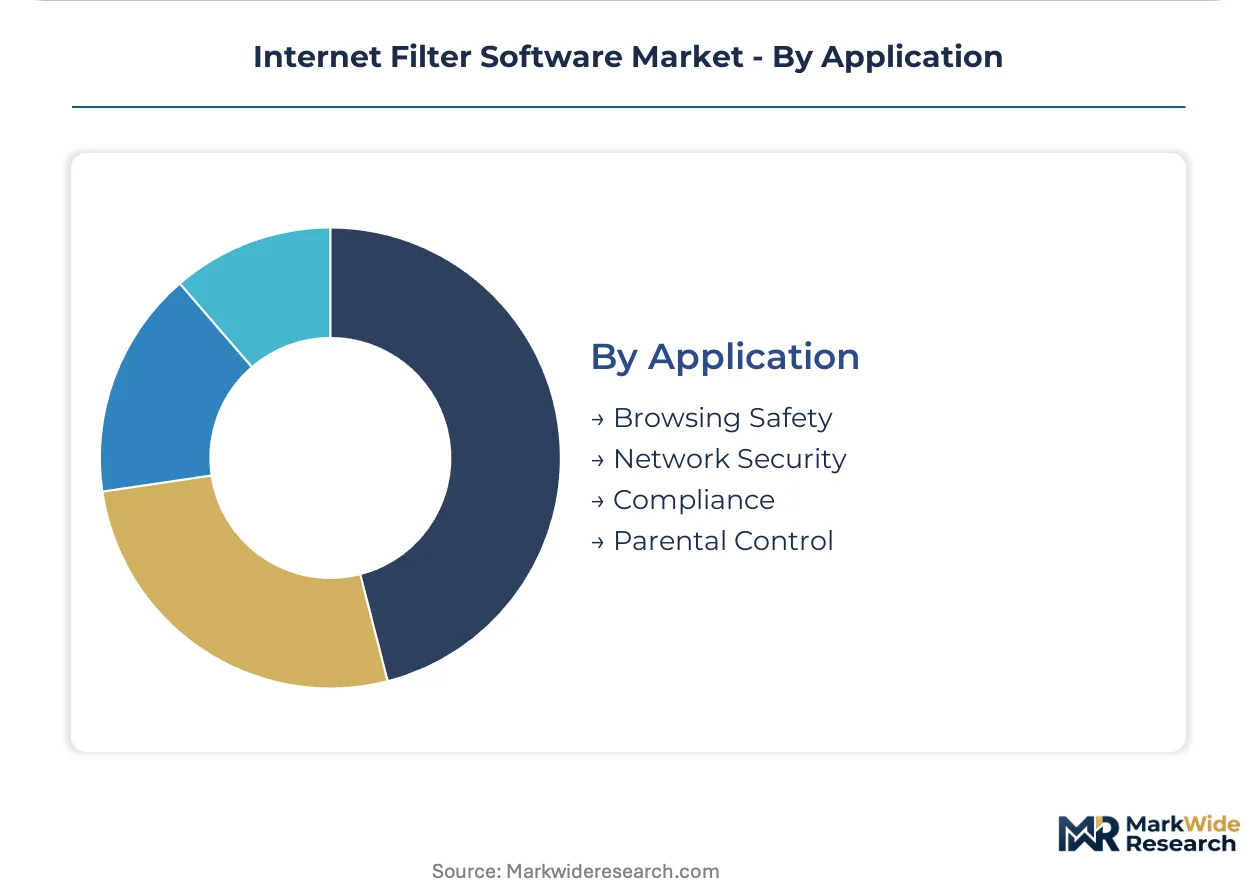
Application:
Use case specificity determines integration complexity and deployment architecture choices.
- Browsing Safety:Web access protection against inappropriate or malicious content. Volume concentrates in consumer and educational segments with straightforward policy requirements.
- Network Security:Perimeter defense integrating filtering with firewall and intrusion detection capabilities. Enterprises consolidate around SASE platforms for distributed workforce coverage.
- Compliance:Regulatory adherence with documented classification logic and human appeal mechanisms. GDPR and EU AI Act mandates in France and Germany accelerate replacement cycles.
- Parental Control:Household-level content restriction with time-limiting and activity monitoring. Mobile app stores distribute these solutions to price-sensitive consumers.
Browsing Safety leads by deployment count, while Compliance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley enterprise adoption patterns are reshaping procurement specifications for internet filter software across distributed workforce architectures worldwide.
United States
FCC E-rate mandates and CIPA compliance requirements drive K-12 district procurement cycles in Texas and Florida. Federal connectivity subsidies require audit-ready filtering platforms with documented policy enforcement. School districts in California's Bay Area are migrating from legacy appliances to cloud-native DNS architectures.
Germany
EU AI Act transparency mandates and GDPR technical safeguards compel enterprises in Bavaria and North Rhine-Westphalia to upgrade from opaque blocklist engines. Federal states require explainable content classification with human appeal mechanisms. Frankfurt's financial services cluster retains on-premise deployments for sub-millisecond latency requirements.
India
BIS cybersecurity framework deadlines and CERT-In data localization directives accelerate filter adoption among mid-sized corporations in Maharashtra and Karnataka. Domestic cloud instance deployments satisfy sovereign infrastructure requirements. Bangalore's technology corridor leads enterprise migration from voluntary to mandatory compliance implementations.
United Kingdom
GDPR enforcement patterns and UK-specific online safety obligations shape procurement in Greater London and the Southeast. Healthcare systems navigating technical safeguard requirements prioritize audit-ready reporting modules. Manchester's educational technology cluster is consolidating vendor relationships around unified security stacks.
Japan
METI cybersecurity guidelines and remote workforce protection policies drive enterprise adoption in Tokyo and Osaka metropolitan areas. Manufacturing conglomerates with branch networks favor hybrid architectures for cost containment. Kansai region enterprises are evaluating AI-generated content detection capabilities ahead of anticipated regulatory mandates.
Internet Filter Software Market Competitive Landscape
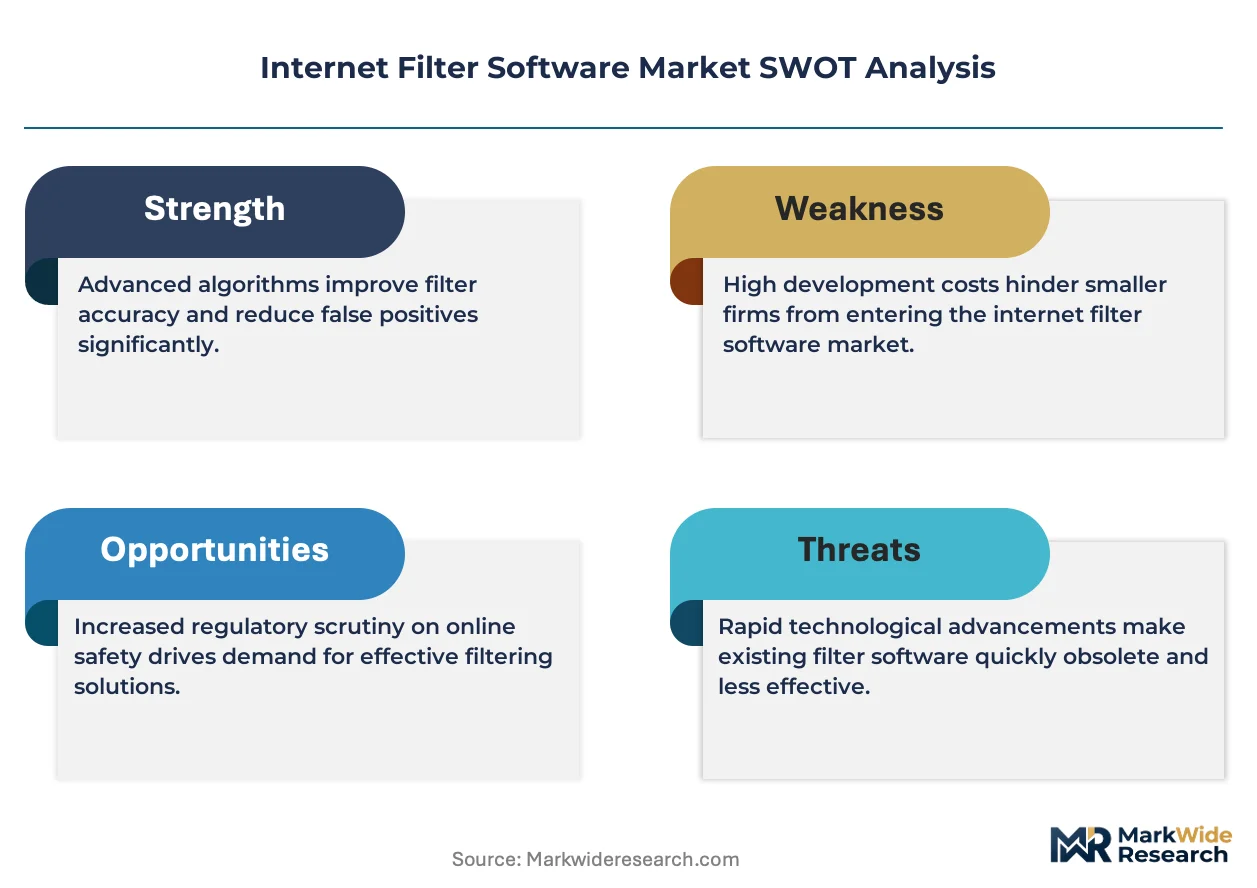
Global majors compete with regional champions across cloud-native deployment architectures and compliance depth capabilities. The vendor base spans consolidated platform providers and specialized filtering specialists serving distinct institutional segments. Three archetypes dominate: zero-trust security stacks, DNS-layer specialists, and compliance-focused channel players. M&A activity concentrates on threat intelligence feed acquisitions, while portfolio diversification moves target adjacent malware protection bundling.
Within the cloud-native platform tier, Cisco Umbrella and Zscaler occupy positions anchoring enterprise deployments through integrated security architectures. DNSFilter represents the mid-market channel specialist archetype, competing on deployment velocity against legacy gateway vendors. These three entities exemplify the strategic segmentation between comprehensive zero-trust frameworks and targeted filtering solutions.
| Leading Market Players |
|---|
| Cloudflare |
| OpenDNS |
| Net Nanny |
| CleanBrowsing |
| Kaspersky Safe Kids |
| Cisco Umbrella |
| DNSFilter |
| WebTitan |
| Zscaler |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up SaaS specialists have consolidated threat intelligence feed sourcing across the mid-market tier, compressing vendor margins while enforcing subscription pricing discipline through annual contract value commitments.
Pricing Analysis
Threat intelligence feed licensing costs pass through to end-user subscriptions at 30-40% of platform operating spend, forcing SaaS providers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SSL/TLS inspection throughput certification and GDPR audit-ready reporting module inclusion. Pricing pressure stems from hyperscaler bundling of DNS-layer security into broader cloud contracts. Educational institutions receiving E-rate funding show highest price sensitivity; financial services firms in Frankfurt tolerate premium tiers for sub-millisecond latency guarantees.
Supply Chain Analysis
Dual-sourcing requirements for threat intelligence feeds compel enterprise buyers to qualify both US-based and European data providers, fragmenting supplier concentration across California, Virginia, and Frankfurt data center clusters. The supply chain draws from semiconductor hardware for SSL acceleration cards, categorized URL databases from cybersecurity vendors, and machine-learning training data from content moderation specialists. Single-source vulnerability concentrates around proprietary classification algorithms. Distribution runs through managed security service providers and direct enterprise sales teams with API-driven provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet Filter Software Market functions as a stable compounder anchored by recurring regulatory procurement cycles that refresh installed bases regardless of macroeconomic conditions.
For Market Incumbents: Deepen vertical integration into proprietary threat intelligence feeds to offset third-party licensing margin compression. Incorporate AI-generated content detection capabilities ahead of anticipated EU regulatory mandates. Expand sovereign cloud instance deployments in India to satisfy CERT-In data localization directives. For New Entrants and Emerging Players: Managed security service provider channel partnerships offer the most penetrable route to small-business segments previously uneconomical for direct sales. Target mid-sized Indian corporations facing BIS cybersecurity framework compliance deadlines with rapid-deployment SaaS offerings. Lead generation through cybersecurity certification training programs builds trust with IT procurement officers. For Investors and Strategic Acquirers: Valuations sit cheapest among compliance-focused channel players with established E-rate procurement relationships in US K-12 districts. The segment exhibits durable recurring revenue characteristics across 5-10 year holding periods. Acquisition candidates with explainable AI classification documentation will command scarcity premia as EU AI Act enforcement intensifies. Watch for FCC E-rate funding authorization renewals as inflection indicators for district procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Content Classification Integration | EU AI Act transparency mandates in Germany and France accelerate replacement cycles for opaque blocklist engines. |
| Sovereign Cloud Infrastructure Deployment | CERT-In data localization directives in India force vendors to maintain domestic instance compliance architectures. |
| Managed Security Service Provider Channel Expansion | MSSP bundling creates indirect routes to small-business segments with compressed customer acquisition costs. |
| Zero-Trust Architecture Platform Convergence | Enterprise consolidation around SASE frameworks collapses standalone filtering vendor pricing power. |
| Threat Intelligence Feed Backward Integration | Proprietary data sourcing reduces 30-40% licensing cost exposure squeezing mid-market SaaS margins. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with chief information security officers, IT procurement officers, K-12 technology directors, and managed security service provider channel heads informed demand-side assumptions. Secondary sources include FCC E-rate disbursement records, EU AI Act implementation guidance, BIS cybersecurity framework circulars, and vendor SEC filings. Bottom-up district-level procurement tracking triangulates against top-down market sizing.
Granularity-level modeling deploys deployment architecture, end-user institution type, feature bundle depth, and application use case as core segmentation dimensions across the projection horizon. CAGRs derive from cohort-based replacement cycle analysis and regulatory mandate timing. Forecast inputs incorporate E-rate funding authorization schedules, EU AI Act enforcement phase-ins, and BIS compliance deadline clustering.
The model assumes a particular technology adoption path; alternative pathways for on-premise appliance retention in financial services would alter the outlook. Forecasts reflect assumptions about cloud migration velocity and regulatory harmonization across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Cloud Security Software Market
Security Software
Certification Authority Market
Security Software
Online Background Check Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Software Protection Dongle Market
Security Software
Global Software-Defined Security Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Device Vulnerability Management Market
Security Software
Identity Verification Software Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Geofencing Market
Security Software
Global Advanced Authentication Market
Security Software
US Evidence Management Market