
 Consumer Cloud Storage Services Market | 2026-2036
Consumer Cloud Storage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Cloud Storage Services Market Analysis
Market Context
Freelancer adoption is repositioning demand patterns within the Consumer Cloud Storage Services Market as gig-economy professionals require seamless multi-device synchronization and client collaboration tools. Google Drive leverages its workspace integration to anchor productivity-centric subscribers across creative and consulting verticals. Dropbox specializes in design-forward workflows with advanced versioning controls that differentiate its platform for media professionals. Microsoft OneDrive sustains enterprise-adjacent individual users through native Office 365 bundling that extends ecosystem lock-in.
Technical Definition and Structural Segments
Consumer cloud storage services deliver remotely hosted data repositories accessible via internet protocols, typically employing AES-256 encryption at rest and TLS 1.3 in transit to protect user files across distributed server architectures. These platforms enable automated backup, real-time synchronization, and cross-platform file sharing for personal and small-scale commercial use cases. Backup and syncing services capture the most mature revenue pools where subscription renewals remain sticky, while file sharing functionality exhibits the fastest expansion as collaboration features migrate from enterprise tiers into consumer plans. Public deployment models dominate volume due to hyperscaler economies, though hybrid configurations are gaining traction among privacy-sensitive subscribers who segment sensitive archives locally while maintaining routine access through cloud gateways.
Regulatory Frame and Forward Outlook
The EU AI Act and GDPR impose strict data residency and algorithmic transparency obligations on cloud providers serving European consumers, forcing infrastructure localization that raises operational costs but creates compliance moats. In the United States, FTC oversight of subscription billing practices and state-level privacy statutes such as the California Consumer Privacy Act shape pricing transparency and data deletion protocols. India's Digital Personal Data Protection Act introduces consent-layer requirements that vendors must architect into onboarding flows. Stakeholders should monitor emerging sovereign cloud certification schemes and cross-border transfer mechanism rulings that could fragment vendor architectures into jurisdiction-specific instances.
Market Dynamics
Freelancer adoption is compressing synchronization latency requirements and forcing vendors to architect edge-first infrastructure that prioritizes real-time collaboration over simple archival storage.
Growth Catalysts
- GDPR data localization mandates:European residency requirements compel hyperscalers to deploy sovereign infrastructure, creating compliance-based switching costs that lock subscribers into localized instances.
- Gig-economy workflow integration:Freelancers in creative and consulting verticals demand seamless client handoff capabilities, pulling feature development toward granular permissioning and watermarking tools.
- India's cloud-first procurement policies:Government digitalization directives accelerate consumer subscription uptake by normalizing cloud dependency across banking, taxation, and identity verification workflows.
Market Restraints
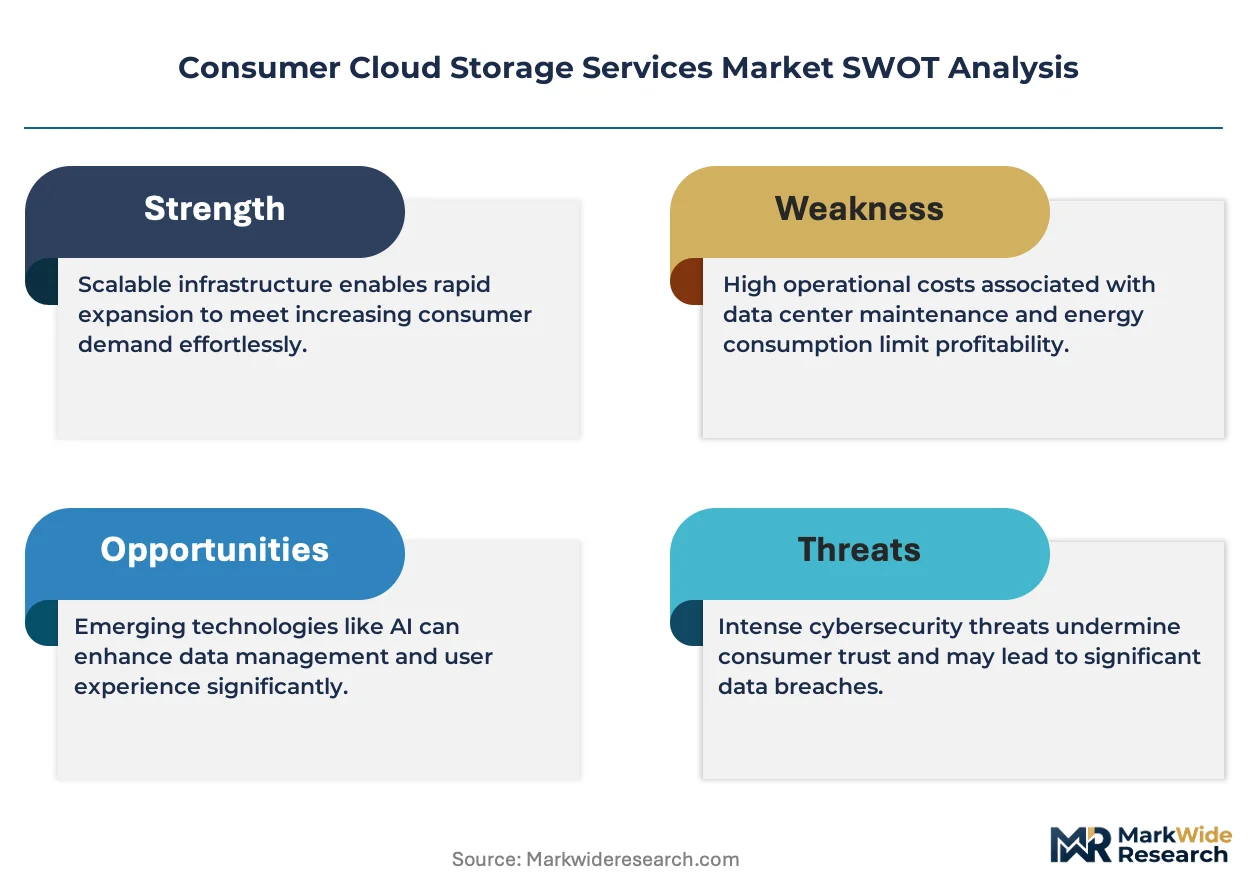
- EU AI Act algorithmic transparency obligations:Automated content classification systems face audit requirements that extend compliance timelines and raise operational overhead for feature deployment.
- Electricity cost volatility in Nordic data center hubs:Norway and Sweden's hydropower-dependent grids expose hyperscaler margin structures to renewable generation intermittency during drought cycles.
- On-premise NAS substitution:Privacy-sensitive professionals in legal and healthcare verticals retain local RAID arrays for sensitive archives, capping cloud penetration in high-value segments.
Strategic Opportunities
- Brazil's underserved creative professional base:São Paulo's design and advertising clusters lack localized low-latency infrastructure, presenting first-mover advantages for Portuguese-language workflow optimization.
- AI-powered semantic search convergence:Natural language document retrieval layered atop object storage is automating archive discovery for users with terabyte-scale personal libraries.
- TRAI data governance frameworks:India's emerging consent-layer architecture creates white space for vendors architecting granular permissioning tools that exceed baseline compliance.
Industry Challenges
- Post-quantum cryptography migration timelines:NIST standardization delays compress vendor preparation windows for TLS 1.3 successor protocols, risking trust erosion among security-conscious subscribers.
- Legacy enterprise storage integration friction:SMBs with decade-old on-premise archives face brittle API compatibility when attempting hybrid cloud synchronization, elevating churn risk during migration attempts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Cloud Storage Services Market |
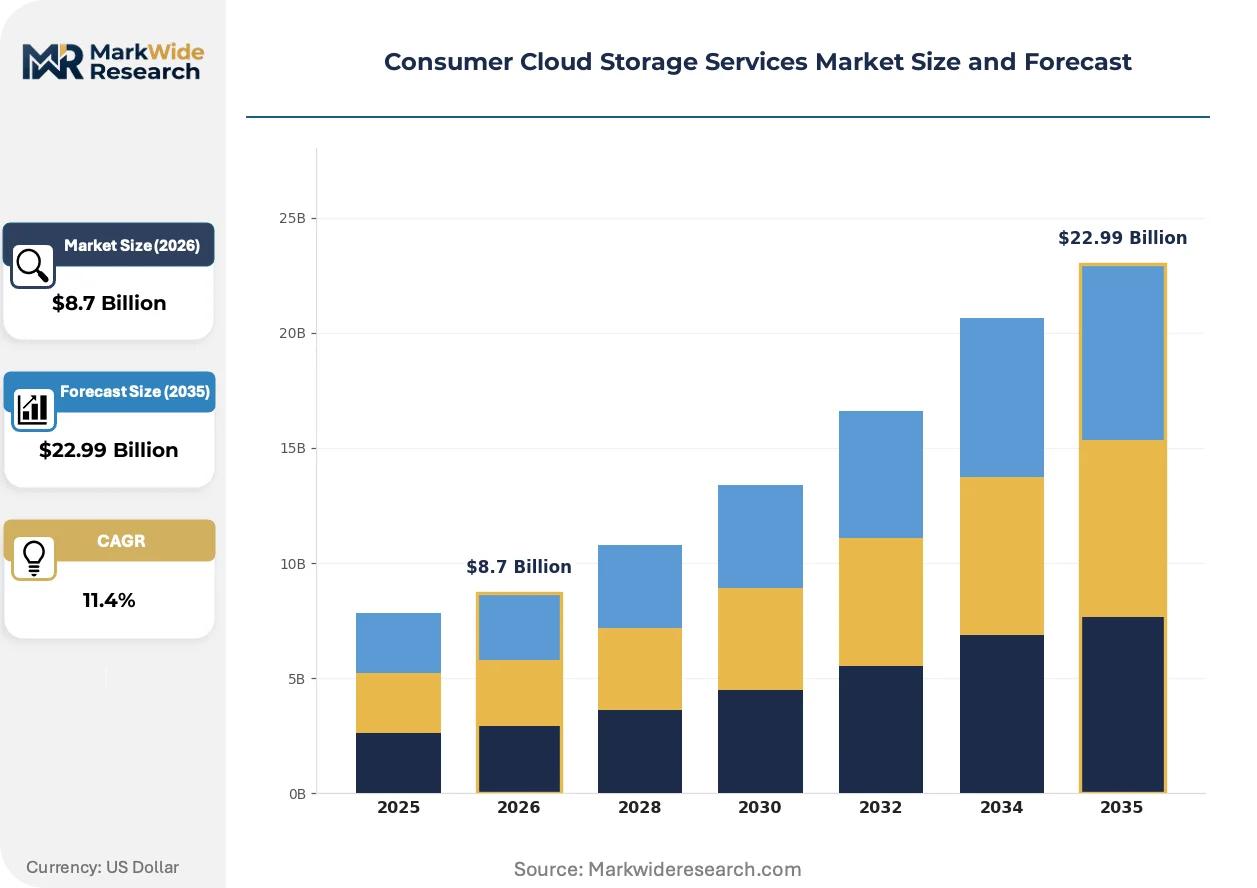
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup, File Sharing, Syncing, Archiving Deployment Model: Public, Private, Hybrid, Community Storage Capacity: 1TB, 2TB, 5TB, Unlimited End User: Individuals, Small Businesses, Large Enterprises, Freelancers |
| Companies Covered | Apple iCloud, Box, Google Drive, Proton Drive, Sync.com, Microsoft OneDrive, Dropbox, IDrive, Amazon Drive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Cloud Storage Services Market Emerging Trajectories
Edge computing architectures and AI-native interfaces are compressing the latency-performance tradeoff that historically constrained remote storage utility for professional workflows.
AI-powered content indexing is automating metadata generation and cross-document relationship mapping for users managing terabyte-scale media libraries. Solo practitioners in video production and photography are adopting these tools fastest, replacing manual folder hierarchies with semantic search. This capability is automating the archival overhead that previously justified dedicated digital asset management subscriptions.
GDPR Article 44 cross-border transfer mechanism rulings are fragmenting vendor architectures into jurisdiction-specific instances with isolated failover domains. Hyperscalers now maintain separate European, Indian, and Brazilian control planes rather than unified global namespaces. Consumer plans in Germany and France face the strictest segmentation, with data replication restricted to sovereign-certified facilities.
Subscription fatigue among price-sensitive freelancers is compressing switching cycles and elevating freemium conversion friction. Tiered storage models that gate collaboration features behind premium paywalls face displacement by workspace-integrated alternatives bundling storage with productivity tools. This pattern concentrates most visibly in India's independent contractor market, where payment integration and storage utility merge into single-app dependency.
Consumer Cloud Storage Services Market Segmentation
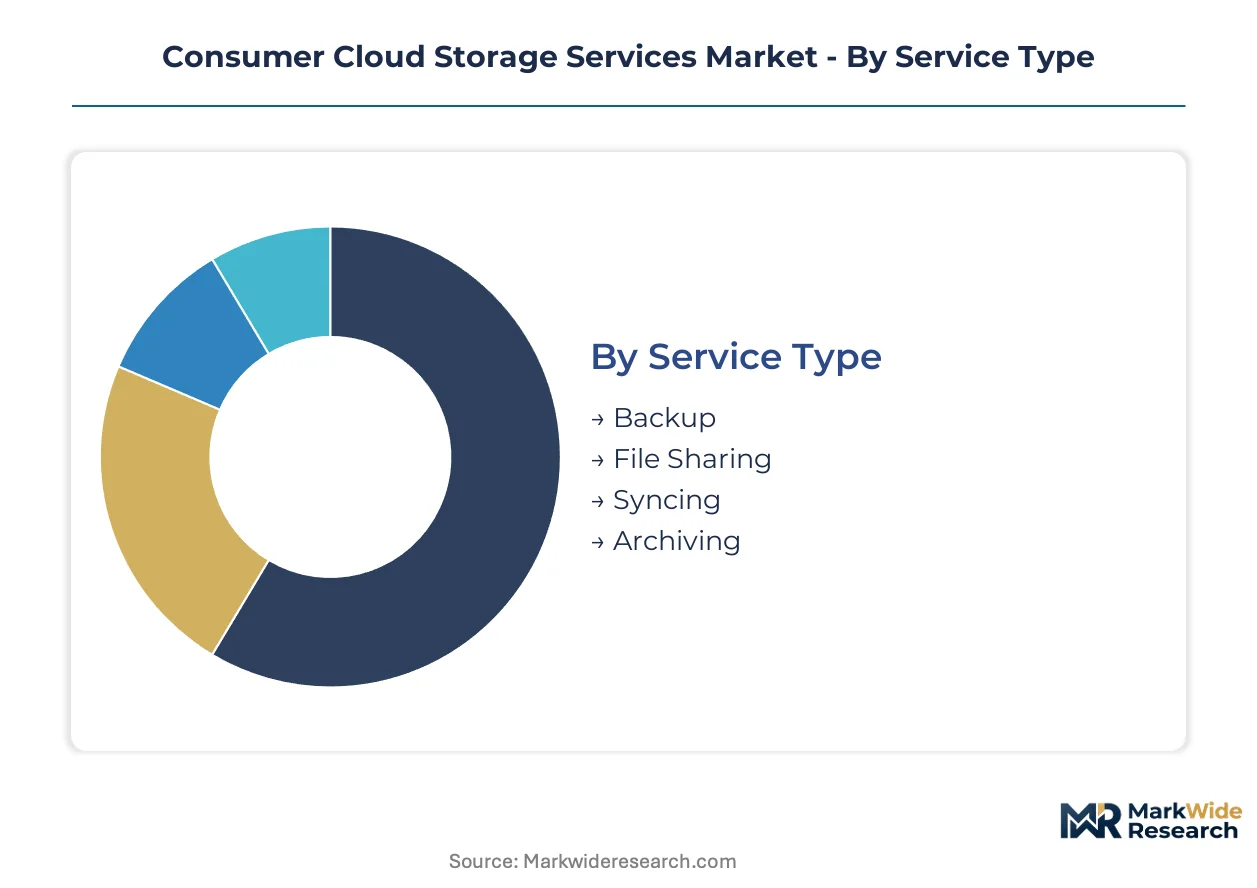
Segmentation in consumer cloud storage reveals how infrastructure investments and pricing architectures map to distinct user workflows. Vendors optimize server density, encryption protocols, and edge node placement differently across each dimension.
Service Type:
Supply concentration in backup services reflects hyperscaler economies in cold storage tape libraries and erasure-coded object repositories. File sharing and syncing demand separate latency-optimized edge infrastructure.
- Backup:Automated incremental uploads to geographically redundant data centers protect against device failure and ransomware. Demand concentrates among privacy-conscious professionals in Germany and France where GDPR residency requirements mandate sovereign-certified facilities. Subscription renewals exhibit the highest stickiness due to migration friction.
- File Sharing:Granular permissioning and watermarking tools enable client collaboration without full access grants. Freelancers in India's creative clusters adopt these features fastest, pulled by payment-integrated workflows that merge storage with invoice generation. Real-time co-editing requirements compress synchronization latency targets below 100ms.
- Syncing:Delta-encoded block-level updates minimize bandwidth consumption for multi-device professionals.
- Archiving:Glacier-class storage tiers serve infrequently accessed legal and financial records with retrieval delay tradeoffs.
Today's leader: Backup. Tomorrow's challenger: File Sharing.
Deployment Model:
Cost tier differentiation separates hyperscale public deployments from compliance-premium private instances. Hybrid architectures capture margin expansion from privacy-sensitive subscribers willing to pay for local-segmentation control.
- Public:Shared multi-tenant infrastructure delivers lowest per-gigabyte economics through hyperscaler scale. Demand concentrates in India's price-sensitive independent contractor market where government cloud-first policies normalize subscription dependency for banking and taxation workflows. Margin compression from electricity volatility in Nordic hydro markets pressures pricing flexibility.
- Hybrid:Local RAID arrays sync selective folders to cloud gateways, segmenting sensitive archives from routine access. Legal and healthcare professionals in the United States retain on-premise control for HIPAA-regulated records while leveraging cloud collaboration for non-protected materials. API friction during legacy enterprise integration elevates implementation risk.
- Private:Single-tenant dedicated hardware serves sovereign cloud certification requirements in European regulated industries.
- Community:Shared infrastructure among affiliated organizations reduces compliance overhead for university and nonprofit consortia.
Public deployments anchor volume. Hybrid configurations gain share fastest among security-conscious verticals.
Storage Capacity:
Volume concentration in 2TB plans reflects the median personal media library size across developed markets. Unlimited tiers absorb edge cases in video production and genomic data archiving.
- 2TB:The standard offering balances photo collections, document archives, and moderate video libraries for typical households. Demand concentrates in São Paulo's design and advertising clusters where localized low-latency infrastructure remains undersupplied. Portuguese-language workflow optimization presents first-mover advantages for vendors entering this whitespace.
- Unlimited:Removes capacity anxiety for terabyte-scale users managing raw footage and high-resolution render files. Solo practitioners in video production and photography adopt these plans fastest, pulled by AI-powered semantic search that automates archive discovery without manual folder hierarchies. Subscription fatigue among price-sensitive freelancers compresses conversion rates.
- 1TB:Entry tier captures price-sensitive users with modest document and photo storage needs.
- 5TB:Mid-premium positioning for growing media libraries before unlimited economics become favorable.
2TB dominates subscriber counts. Unlimited tiers show steepest expansion trajectory among creative professionals.
End User:
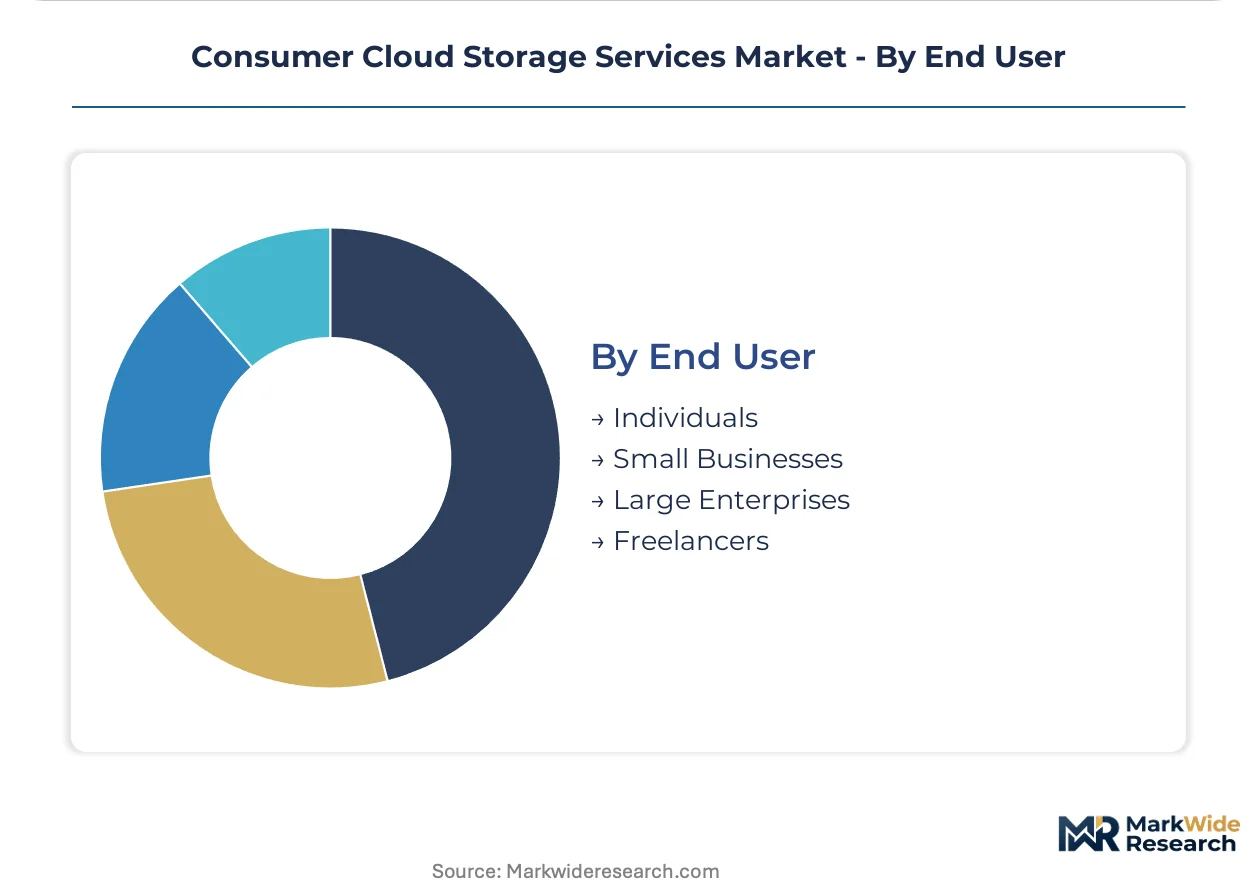
Customer type determines feature prioritization and support infrastructure intensity. Freelancers force the fastest product evolution through workflow integration demands.
- Freelancers:Gig-economy professionals require seamless multi-device synchronization and client handoff capabilities without enterprise procurement overhead. Demand concentrates in India's independent contractor market where digital payment integration and storage utility merge into single-app dependency. Granular permissioning and watermarking tools differentiate vendor selection.
- Individuals:Personal photo backup and cross-platform file access drive subscription decisions. Privacy-sensitive users in European markets select vendors with GDPR Article 44 compliant data residency, accepting higher pricing for sovereign-certified replication restricted to localized facilities.
- Small Businesses:Shared team folders and basic admin controls serve micro-enterprises without IT departments.
- Large Enterprises:SSO integration and advanced audit logging extend consumer-adjacent plans into enterprise-adjacent individual users through ecosystem bundling.
Freelancers reshape feature roadmaps most aggressively. Individuals provide the revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor infrastructure deployment as compliance-cost differentials between jurisdictions accelerate data center localization strategies. Hyperscalers now fragment global architectures into sovereign-certified instances to satisfy divergent residency mandates.
United States
FTC oversight of subscription billing practices and state-level privacy statutes shape pricing transparency protocols. California's Consumer Privacy Act imposes data deletion requirements that vendors architect into retention policies. Seattle and San Francisco Bay Area clusters anchor hyperscaler headquarters and primary control plane development.
Germany
GDPR Article 44 cross-border transfer restrictions mandate sovereign-certified replication facilities. The Federal Network Agency enforces strict data residency audits for consumer-facing platforms. Frankfurt's financial services corridor drives demand for low-latency synchronization among freelance consultants.
India
Digital Personal Data Protection Act consent-layer requirements reshape onboarding architecture for subscription flows. TRAI data governance frameworks create compliance white space for permissioning-tool innovation. Bangalore and Hyderabad's technology corridors concentrate independent contractor adoption where payment integration merges with storage utility.
Brazil
ANVISA and national data protection authority rulings introduce localization obligations for consumer health and financial records. São Paulo's design and advertising clusters lack localized low-latency infrastructure, presenting whitespace for Portuguese-language workflow optimization. Rio de Janeiro's creative verticals show rising freelancer subscription uptake.
Japan
METI guidelines on cloud security certification create procurement filters for government-adjacent consumer plans. Personal Information Protection Commission audits enforce strict breach notification timelines. Tokyo and Osaka metropolitan areas concentrate demand among solo practitioners requiring multi-device synchronization for client collaboration.
Consumer Cloud Storage Services Market Vendor Landscape
Portfolio diversification dominates the current landscape as vendors bundle storage with adjacent productivity and security services. The market exhibits consolidated hyperscaler dominance at the volume tier, with specialized privacy-first providers occupying defensible niches. Three archetypes define competitive positioning: ecosystem-integrated platforms, security-specialized independents, and workspace-productivity bundlers. M&A activity and strategic technology licensing represent the dominant competitive moves as scale advantages compound.
Among ecosystem-integrated hyperscalers, Google LLC and Microsoft Corporation exemplify the workspace-bundling archetype that extends enterprise-adjacent individual user lock-in through native productivity tool integration. Dropbox, Inc. occupies a differentiated position within the design-forward workflow specialist tier. IDrive Inc. represents the backup-centric heritage provider archetype with cross-platform breadth.
| Leading Market Players |
|---|
| Apple iCloud |
| Box |
| Google Drive |
| Proton Drive |
| Sync.com |
| Microsoft OneDrive |
| Dropbox |
| IDrive |
| Amazon Drive |
| Others |
Supply Flow & Price Mechanics
Site reliability engineering talent concentration in Bangalore and Hyderabad compresses operational labor costs for hyperscalers, widening pricing-tier spreads between premium sovereign-certified instances and economy public-cloud tiers. European GDPR compliance investments and Nordic electricity volatility feed back into supply chain localization decisions that segment vendor architectures by jurisdiction.
Pricing Analysis
Direct-to-consumer subscription billing eliminates distributor margin layers, compressing price transparency into recurring SaaS-tiered structures. Pricing stratifies across premium sovereign-certified, standard GDPR-compliant, and economy public tiers driven by data residency certification level and edge-node proximity. Pricing pressure stems from subscription fatigue among India's price-sensitive freelancers, forcing feature bundling with productivity tools. Individual consumers exhibit highest price sensitivity; regulated European professionals accept premium pricing for localized replication guarantees.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating concentrates server hardware procurement through audited supply chains in Taiwan, South Korea, and the United States. NAND flash and specialized cooling systems draw from concentrated semiconductor foundries and precision manufacturing hubs. Single-source vulnerability in advanced encryption chipsets exposes margin structures to foundry allocation constraints. Distribution runs through hyperscaler-direct provisioning with regional edge-node deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in consumer cloud storage rests on AI-powered feature tiering that captures premium pricing from creative professionals while automated cold-storage tiering reduces data center energy costs.
For Market Incumbents: Cement ecosystem lock-in through deeper workspace integration that embeds storage into client invoicing and payment workflows. Defend against specialized privacy-first entrants by accelerating sovereign cloud certification in Germany and France. Prioritize backward integration into edge-node real estate to control latency performance for freelancer collaboration tools. For New Entrants and Emerging Players: Brazil's ANVISA localization obligations in São Paulo open a window for Portuguese-language workflow optimization targeting underserved creative advertising clusters. India's TRAI consent-layer frameworks create white space for granular permissioning tools that exceed baseline compliance. Pursue vertical-specific positioning in legal and healthcare hybrid deployments where on-premise RAID retention creates service integration opportunities. For Investors and Strategic Acquirers: Hyperscaler platform divisions are the most active acquirer in this space, seeking specialized AI-indexing and semantic search capabilities. Long-term viability hinges on architectural adaptability to post-quantum cryptography standards and jurisdiction-specific control plane fragmentation. Monitor NIST post-quantum standardization rulings as the critical inflection signal for trust-erosion risk among security-conscious subscriber segments.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 44 compliance in Germany and France locks subscribers into localized instances with elevated switching costs. |
| AI-Powered Semantic Search Integration | Natural language document retrieval automates archive discovery for terabyte-scale video production and photography libraries. |
| Edge Node Geographic Expansion | Low-latency infrastructure deployment in São Paulo and Bangalore captures freelancer workflow integration demand. |
| Post-Quantum Cryptography Migration | NIST-standardized encryption protocols preserve subscriber trust as quantum computing threats materialize. |
| Hybrid Deployment Architecture Development | Local RAID gateway synchronization serves HIPAA-regulated healthcare and legal professionals with segmented control. |
Methodological Framework
Direct dialogue with cloud infrastructure architects, data center procurement officers, freelance creative professionals, and regulatory compliance consultants grounded qualitative insights in operational reality. Secondary validation drew from hyperscaler capex disclosures, SEC filings, TRAI regulatory frameworks, GDPR Article 44 rulings, and Nordic grid operator generation data. Bottom-up subscriber segmentation triangulated against top-down infrastructure investment patterns.
Bottom-up modeling aggregated individual user cohorts by service tier, deployment model, and geographic jurisdiction across the projection horizon. Top-down analysis calibrated aggregate capacity expansion against hyperscaler facility announcements and sovereign certification timelines. Segmentation dimensions included service type, deployment architecture, storage capacity tier, and end-user archetype. CAGRs derived from subscriber growth trajectories and average revenue per user evolution, with electricity cost volatility and regulatory compliance overhead as industry-specific forecast inputs.
Revisions become necessary when cross-border data transfer mechanism rulings fragment architectures beyond modeled jurisdiction counts or when post-quantum cryptography standardization accelerates beyond anticipated timelines. Forecasts reflect documented assumptions regarding freelancer adoption curves and sovereign cloud certification penetration rates. A model refresh is warranted upon material change in EU AI Act algorithmic transparency enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Media and Entertainment Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Cloud Native Storage Market