
 Disposable Surgical Devices Market | 2026-2036
Disposable Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Surgical Devices Market Intelligence
Project finance and equipment leasing for surgical suites is reconfiguring capital deployment across the disposable surgical devices supply chain. Medtronic leverages its end-to-end platform to anchor hospital system contracts at scale. B. Braun sustains manufacturing depth across latex and synthetic glove portfolios in Europe and Asia.
Disposable surgical devices encompass single-use instruments, drapes, gloves, sutures, and blades manufactured from latex, polyethylene, non-woven fabrics, or PVC, then sterilized via gamma irradiation or ethylene oxide before sealed packaging for immediate intraoperative use. Surgical gloves and sutures represent the largest volume categories, with sutures capturing disproportionate margin pools due to absorbable polymer formulations and proprietary needle designs. Ambulatory surgical centers constitute the fastest-growing end-use channel as outpatient procedure migration accelerates instrument turnover rates.
FDA 510(k) clearance pathways and EU MDR Class I/IIa conformity requirements govern material biocompatibility, sterility assurance levels, and traceability across the United States and European markets. The EPA regulates ethylene oxide sterilization emissions, pushing manufacturers toward gamma and e-beam alternatives with different capital intensity profiles. Stakeholders must monitor how sterilization modality shifts reshape facility compliance costs and supplier qualification timelines.
Market Dynamics
Outpatient surgical migration is compressing instrument turnover cycles and forcing suppliers to reconfigure sterilization workflows around gamma irradiation and ethylene oxide alternatives. Ambulatory surgical centers now dictate volume terms, while FDA and EU MDR compliance costs filter smaller manufacturers from contract pools.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volumes in the United States and Germany are accelerating single-use instrument procurement as facilities prioritize cross-contamination prevention over reprocessing economics.
- EU MDR Class IIa conformity:Stricter traceability and sterility assurance mandates are consolidating supplier relationships toward qualified manufacturers with validated gamma irradiation capabilities.
- Absorbable polymer suture innovation:Proprietary needle designs and synthetic formulations are capturing disproportionate margin pools in cardiac and orthopedic closure applications.
Market Restraints
- Ethylene oxide regulatory pressure:EPA emission caps on EtO sterilization are forcing facility requalification and capital redeployment toward electron beam alternatives with steeper upfront equipment costs.
- Latex raw material concentration:Natural rubber supply sensitivity to Southeast Asian climate volatility creates input cost instability for glove manufacturers.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization protocols extend FDA 510(k) clearance timelines by 8-14 months for novel materials.
Strategic Opportunities
- China outpatient surgical buildout:Tier-2 and Tier-3 city hospital expansions are creating procurement entry points for single-use drapes and sutures as surgical volumes decentralize from Beijing and Shanghai.
- Kit consolidation models:Procedure-specific disposable packs combining blades, drapes, and closure devices are displacing individual SKU purchasing in United States ambulatory centers.
- NMPA harmonization pathways:China's acceptance of FDA and CE testing data is compressing dual-market registration costs for manufacturers with existing Western approvals.
Industry Challenges
- Sterilization modality transition:Converting EtO-dependent product lines to gamma or e-beam validation requires redundant facility qualification and destabilizes existing supply contracts.
- Polymer formulation IP density:Absorbable suture chemistry patents held by incumbent manufacturers create licensing barriers for entrants targeting premium surgical closure segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Surgical Devices Market |
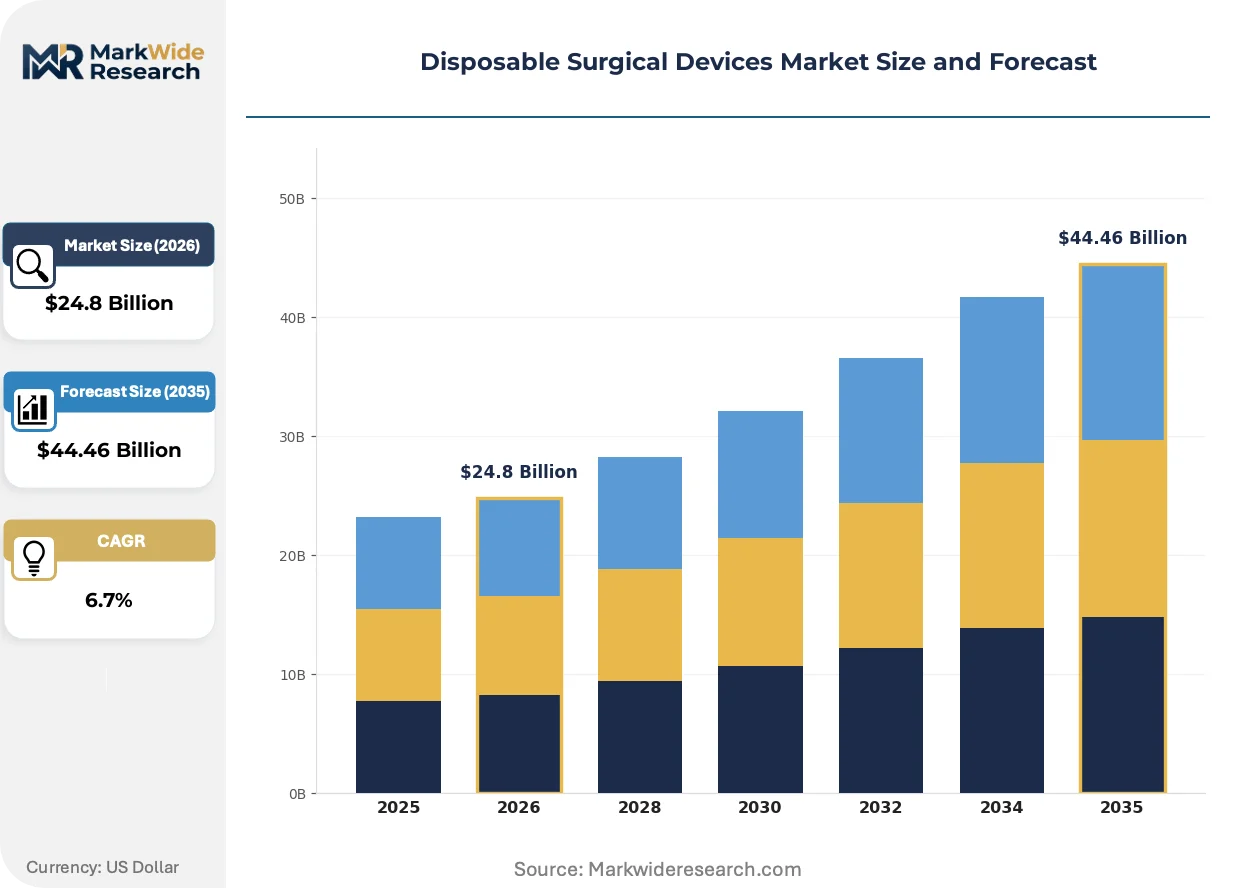
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gloves, Scalpel Blades, Sutures, Surgical Drapes Material: Latex, Polyethylene, Non-woven Fabrics, PVC End Use: Hospitals, Ambulatory Surgical Centers, Clinics, Long-term Care Facilities Distribution Channel: Direct Sales, Online Retail, Medical Supply Distributors, Third-party Retailers |
| Companies Covered | Medtronic, Ethicon (Johnson & Johnson), B. Braun, Smith+Nephew, Stryker, Zimmer Biomet, BD (Becton Dickinson), Aspen Surgical, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Surgical Devices Market Strategic Shifts & Innovations
Material science advances and sterilization modality shifts are restructuring competitive advantage around validated supply chains rather than manufacturing scale alone. Regulatory divergence between FDA 510(k) and EU MDR pathways is fragmenting product development roadmaps.
Bioabsorbable synthetic polymers with controlled degradation profiles are rendering obsolete traditional catgut and silk sutures in soft-tissue approximation. Cardiac surgery departments in German university hospitals are adopting these materials at replacement rates exceeding 60% for internal closure procedures. The shift is compressing margin structures for natural-fiber suture manufacturers while elevating polymer chemistry capabilities as a qualifying criterion for supplier selection.
EU MDR technical documentation requirements are extending conformity assessment timelines for Class IIa surgical devices by 40-60% compared to the prior Medical Device Directive framework. Notified body capacity constraints are forcing manufacturers to front-load clinical evaluation reports and post-market surveillance protocols. Suture and surgical mesh suppliers with legacy MDD certificates face renewal cliffs that favor mid-cap competitors with dedicated regulatory affairs infrastructure.
Hospital procurement departments are consolidating disposable surgical device purchasing through integrated delivery networks that unbundle distributor markups. United States health systems with over 500 beds are migrating toward direct manufacturer contracts with price transparency mandates. The model is most visible in the southeastern United States, where ambulatory surgery joint ventures between hospital systems and physician groups are negotiating procedure-based bundled payments that include instrument costs.
Disposable Surgical Devices Market Segmentation
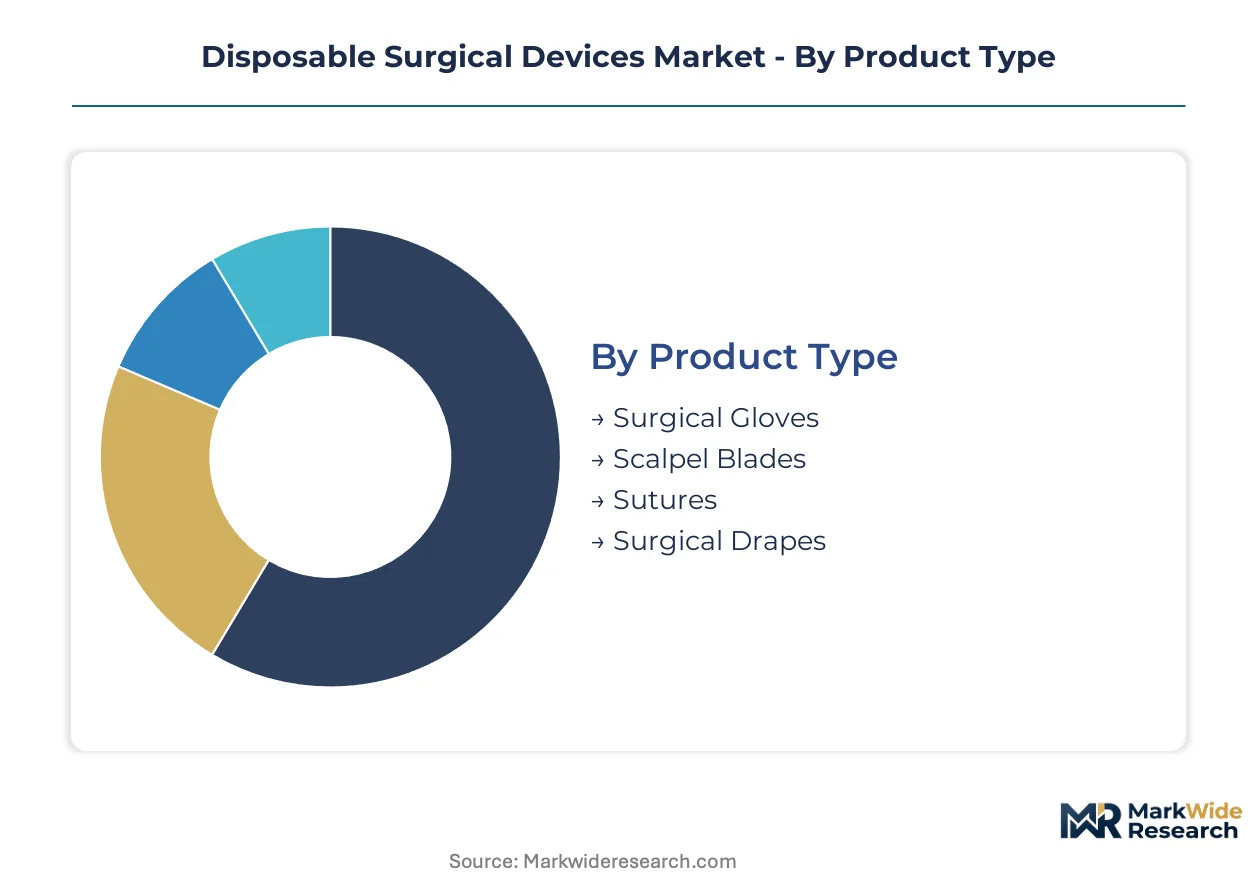
Segmentation in disposable surgical devices reveals how procurement patterns diverge across clinical settings and supply chain configurations. Each dimension—product, material, end-use, and distribution—exposes distinct margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Use cases span from barrier protection through tissue manipulation to operative site isolation, creating divergent technical specifications and sterilization requirements.
- Surgical Gloves:Manufactured from latex, nitrile, or neoprene with thickness gradients from 0.05mm to 0.15mm and textured fingertips for instrument grip. Demand concentrates in United States ambulatory surgical centers where OSHA bloodborne pathogen compliance mandates double-gloving protocols for invasive procedures.
- Sutures:Comprising absorbable synthetic polymers (polyglycolic acid, polylactic acid) or non-absorbable materials (polypropylene, silk) with proprietary needle attachments for tissue approximation. German cardiac surgery departments are capturing disproportionate margin pools through absorbable polymer formulations with controlled degradation profiles for internal closure.
- Scalpel Blades:Carbon or stainless steel edges bonded to polymer handles, gamma-sterilized for immediate use in incision procedures. China tier-2 city hospitals are scaling procurement as outpatient surgical volumes decentralize from Beijing and Shanghai.
- Surgical Drapes:Non-woven fabric barriers with adhesive apertures for operative site isolation, manufactured via spunbond-meltblown-spunbond layering. United States integrated delivery networks are consolidating purchasing through procedure-specific kit configurations.
Established volume favors surgical gloves; emerging adoption favors sutures with proprietary polymer chemistry.
Material:
Cost tiers stratify from commodity petrochemical derivatives to specialized medical-grade formulations with distinct sterilization compatibility profiles.
- Latex:Natural rubber harvested from Hevea brasiliensis with protein content below 50 micrograms per gram for hypoallergenic certification. Southeast Asian climate volatility is creating input cost instability for glove manufacturers dependent on Malaysian and Thai supply.
- Polyethylene:Low-density and linear low-density grades extruded into films for drape manufacturing and glove liners. Ambulatory surgical centers in Germany are displacing PVC alternatives due to EU MDR substance restriction compliance requirements.
- Non-woven Fabrics:Polypropylene or polyester fibers thermally or chemically bonded into barrier materials with bacterial filtration efficiency exceeding 98%. Direct manufacturer contracts with United States health systems above 500 beds are compressing distributor markups.
- PVC:Plasticized polyvinyl chloride formulated for glove and tubing applications with di(2-ethylhexyl) phthalate or alternative plasticizers. EPA emission caps on ethylene oxide sterilization are forcing material qualification toward gamma-compatible alternatives.
Commodity pricing dominates polyethylene; premium positioning concentrates in latex with certified hypoallergenic grades.
End Use:
Customer type determines volume scale, reimbursement pathway, and instrument turnover velocity across the care continuum.
- Hospitals:Acute care facilities with surgical suites performing inpatient and emergency procedures requiring comprehensive disposable instrument portfolios. United States health systems are migrating toward bundled payment models that internalize instrument costs within procedure-based pricing.
- Ambulatory Surgical Centers:Freestanding facilities specializing in same-day procedures with compressed turnover cycles and cross-contamination prevention priorities. This segment is climbing the fastest as outpatient migration accelerates single-use procurement across ophthalmology, orthopedics, and gastroenterology.
- Clinics:Primary and specialty care settings with limited procedural capacity requiring basic disposable supplies for minor surgical interventions. China tier-3 city expansions are creating procurement entry points for standardized drape and blade configurations.
- Long-term Care Facilities:Skilled nursing and rehabilitation centers with wound care and minor procedure requirements. Reimbursement constraints are limiting premium material adoption toward economy-grade polyethylene and PVC alternatives.
Volume concentration remains with hospitals; margin expansion favors ambulatory surgical centers with kit consolidation models.
Distribution Channel:
Supply concentration varies from manufacturer-direct relationships to fragmented retail intermediaries with divergent service and pricing structures.
- Direct Sales:Manufacturer-to-provider contracts with price transparency mandates and volume commitment terms. United States southeastern health systems are negotiating direct agreements for ambulatory surgery joint ventures.
- Medical Supply Distributors:Specialized intermediaries with inventory management, logistics, and regulatory documentation services. EU MDR traceability requirements are consolidating relationships toward distributors with validated quality management systems.
- Online Retail:E-commerce platforms serving smaller clinics and long-term care facilities with fragmented purchasing patterns. NMPA harmonization pathways are enabling cross-border procurement for China facilities with existing Western approvals.
- Third-party Retailers:General medical supply stores and pharmacy chains with limited technical support and standardized product offerings. Procurement is shifting toward integrated delivery networks that displace these channels in acute care settings.
Contract value concentrates in direct sales; channel expansion favors online retail for decentralized clinic procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in disposable surgical devices reveal net manufacturing concentration in Germany and the United States against import dependency in China and emerging Asian markets. Sterilization modality shifts and outpatient surgical buildouts are redistributing procurement volumes across national healthcare systems.
United States
Ambulatory surgical center expansion and double-gloving OSHA mandates are accelerating single-use instrument procurement. FDA 510(k) clearance pathways govern material biocompatibility and sterility assurance levels for market entry. Southeastern health systems with ambulatory surgery joint ventures are negotiating direct manufacturer contracts for procedure-based bundled payments.
Germany
Cardiac surgery departments in university hospitals are adopting absorbable polymer sutures at replacement rates exceeding 60% for internal closure procedures. EU MDR Class IIa conformity requirements extend technical documentation timelines by 40-60% compared to the prior Medical Device Directive framework. Bavarian medical device clusters are consolidating gamma irradiation capabilities to serve sterilization modality transitions.
China
Tier-2 and Tier-3 city hospital expansions are decentralizing surgical volumes from Beijing and Shanghai toward provincial procurement markets. NMPA harmonization pathways now accept FDA and CE testing data, compressing dual-market registration costs for Western-approved manufacturers. Yangtze River Delta manufacturing zones are scaling domestic production of non-woven surgical drapes for regional distribution.
India
Government hospital procurement under the Ayushman Bharat scheme is expanding access to basic disposable surgical supplies across secondary care facilities. CDSCO medical device rules classify surgical gloves and sutures under regulated import categories with mandatory quality testing. Maharashtra and Gujarat industrial corridors are attracting contract manufacturing investments for latex glove production serving Middle East export markets.
Japan
Aging demographic pressures are expanding outpatient surgical volumes in metropolitan hospital systems with compressed instrument turnover requirements. PMDA quality management system ordinances mandate traceability protocols equivalent to EU MDR standards for foreign manufacturer registration. Kansai region medical device distributors are consolidating procurement relationships toward qualified suppliers with validated sterilization documentation.
Disposable Surgical Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower manufacturing depth. The supplier base organizes around three archetypes: diversified conglomerates with end-to-end surgical portfolios, mid-cap specialists with concentrated material expertise, and regional fabricators serving price-sensitive procurement channels. Competitive positioning depends on gamma irradiation validation capabilities and regulatory affairs infrastructure rather than manufacturing scale alone. Consolidation pressure favors players with dedicated EU MDR technical documentation resources and direct hospital system contracting relationships.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson's Ethicon division occupy positions defined by platform breadth and hospital system anchoring. B. Braun exemplifies the mid-cap specialist archetype with concentrated manufacturing depth across European and Asian production bases. These three entities represent the competitive spectrum from integrated system provision to focused material competence.
| Leading Market Players |
|---|
| Medtronic |
| Ethicon (Johnson & Johnson) |
| B. Braun |
| Smith+Nephew |
| Stryker |
| Zimmer Biomet |
| BD (Becton Dickinson) |
| Aspen Surgical |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta freight corridors carry sterilized device shipments from manufacturing zones to provincial distribution hubs, with logistics cost differentials between coastal and inland China creating price stratification that suppliers exploit to segment premium gamma-irradiated sutures from economy-grade polyethylene drapes. This corridor dynamic concentrates pricing power with manufacturers possessing validated sterilization facilities near Shanghai and Ningbo, while buyers in western provinces absorb elevated landed costs that compress their procurement flexibility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments across multi-year procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared absorbable sutures with proprietary needle designs from basic latex gloves and unbranded drape configurations. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are scaling spunbond-meltblown-spunbond production for regional hospital networks. Ambulatory surgical centers exhibit the highest price sensitivity due to bundled payment constraints, while German cardiac surgery departments show minimal sensitivity given reimbursement premiums for internal closure procedures.
Supply Chain Analysis
Tariff exposure between Malaysia and the United States dominates risk calculations for latex glove manufacturers dependent on Southeast Asian natural rubber harvesting. Raw material sourcing draws from Malaysian Hevea brasiliensis plantations, Thai nitrile butadiene rubber processors, and German polylactic acid polymerization facilities. Single-source vulnerability concentrates in gamma irradiation validation capabilities, where Bavarian medical device clusters and select Yangtze River Delta zones control qualified sterilization capacity. Distribution runs through medical supply distributors with EU MDR-traceable quality management systems serving hospital systems and ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization-as-a-service contracts are expanding faster than hardware procurement as ambulatory surgical centers outsource gamma irradiation validation and ethylene oxide alternative qualification to specialized providers. This recurring-revenue layer offers margin stability that pure device manufacturing cannot match.
For Market Incumbents: Pre-empt EU MDR technical documentation renewal cliffs by acquiring mid-cap competitors with dedicated regulatory affairs infrastructure and validated notified body relationships. Consolidate gamma irradiation capacity in Bavaria and the Yangtze River Delta to capture sterilization modality transition demand from EtO-dependent product lines. Backward integration into polylactic acid polymerization secures absorbable suture input supply against German chemical sector consolidation.
For New Entrants and Emerging Players: China tier-3 city hospital expansions offer the most penetrable geographic entry point for standardized drape and blade configurations as surgical volumes decentralize from Beijing and Shanghai. NMPA harmonization pathways accepting FDA and CE testing data compress dual-market registration costs for Western-approved manufacturers. Target direct manufacturer contracts with southeastern United States health systems negotiating procedure-based bundled payments for ambulatory surgery joint ventures.
For Investors and Strategic Acquirers: Gamma irradiation specialists with EU MDR-validated quality management systems represent the priority acquisition archetype as sterilization modality shifts accelerate EtO facility obsolescence. Long-term viability over the projection horizon rests on regulatory affairs infrastructure depth rather than manufacturing scale alone. Watch notified body capacity constraints as the inflection signal—extended conformity assessment timelines favor targets with existing Class IIa surgical device certifications.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Extended technical documentation timelines favor incumbents with dedicated regulatory infrastructure and notified body relationships. |
| Gamma Irradiation Facility Partnership | Bavarian medical device clusters are consolidating sterilization capabilities to serve modality transitions from ethylene oxide alternatives. |
| Hospital System Direct Contracting | United States southeastern health systems with ambulatory surgery joint ventures are negotiating procedure-based bundled payments. |
| Absorbable Polymer R&D Investment | German cardiac surgery departments are adopting synthetic sutures at replacement rates exceeding sixty percent for internal closure. |
| NMPA Harmonization Registration | China's acceptance of FDA and CE testing data compresses dual-market entry costs for Western-approved manufacturers. |
Research Approach
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and sterilization facility operators and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract records. Bottom-up demand modeling across ambulatory surgical centers, acute care hospitals, and clinic settings was triangulated against top-down manufacturing capacity assessments from Malaysian latex processors and German polymer chemical facilities.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, material grade, end-use facility tier, and distribution channel configuration. CAGRs were derived from procedure volume growth rates, outpatient migration patterns, and sterilization modality transition timelines. Forecast inputs incorporated EU MDR conformity assessment capacity constraints, EPA ethylene oxide emission cap implementation trajectories, and NMPA harmonization pathway adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic drape manufacturers or accelerated gamma irradiation facility buildouts by mid-cap specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
United States Minimally Invasive Surgery Market