
 Medical Devices and Equipment Logistics Market | 2026-2036
Medical Devices and Equipment Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Devices and Equipment Logistics Market Insights
Hospital procurement consolidation is recalibrating volume concentration across the logistics value chain. Cardinal Health leverages its direct-to-site distribution infrastructure to sustain contracted relationships with integrated delivery networks. DHL International GmbH anchors temperature-controlled lane density across European medical technology corridors. FedEx competes through time-definite express protocols calibrated to implantable device shelf-life constraints.
Medical devices and equipment logistics encompasses the specialized handling, storage, and transportation of regulated healthcare products requiring temperature integrity, serialization tracking, and contamination-free transit, typically maintaining cold chains between two and eight degrees Celsius for biologics and active implantables. The primary purpose is ensuring sterile, traceable delivery from manufacturer to clinical end-user while preserving regulatory compliance and patient safety. Diagnostic equipment commands the largest product-type volume pool due to replacement cycles and point-of-care expansion, while surgical instruments generate premium margin concentration through kitting complexity and sterilization requirements. RFID Tracking leads technology adoption by enabling real-time location verification, yet Predictive Analytics is expanding fastest as fleets optimize route sequencing around hospital receiving windows.
The FDA enforces unique device identification and quality system regulation across domestic distribution, while the EU MDR mandates enhanced traceability documentation that reshapes cross-border warehousing requirements. EMA post-market surveillance obligations further tighten adverse-event reporting timelines, compressing logistics response windows for field safety corrective actions. Stakeholders must monitor regulatory divergence between US and European serialization standards as compliance costs redistribute across network nodes.
Market Dynamics
Hospital procurement consolidation is compressing distribution tiers, forcing logistics providers to reconfigure networks around integrated delivery networks rather than fragmented point-to-point delivery models. This structural shift concentrates volume with fewer buyers who demand direct-to-site capabilities and real-time visibility.
Growth Catalysts
- FDA Unique Device Identification:The mandate forces serialization infrastructure investment across distribution networks, creating standardized tracking demand that benefits specialized medical logistics operators with pre-built compliance systems.
- EU MDR traceability requirements:Enhanced documentation obligations expand cross-border warehousing complexity, driving demand for qualified importers and authorized representatives with established European distribution footprints.
- Germany's medical technology clusters:Concentrated manufacturing around Tuttlingen and Erlangen generates specialized lane density for temperature-controlled surgical instrument and implantable device transport.
Market Restraints
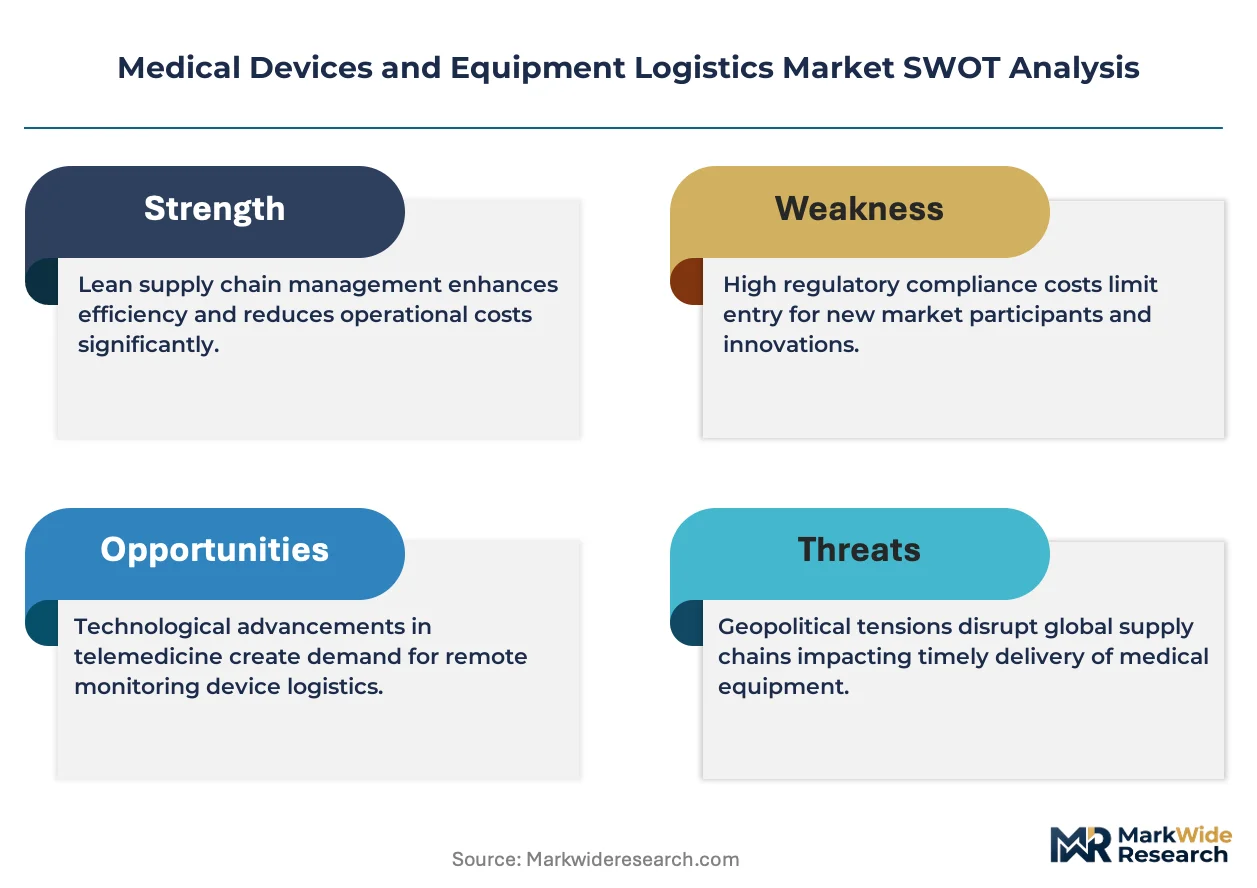
- Refrigerated fleet capital intensity:Cold chain maintenance for biologics and active implantables requires specialized vehicle investment that locks smaller operators out of premium segments.
- EU-UK customs friction:Post-Brexit regulatory divergence creates dual warehousing requirements for devices serving both markets, inflating inventory carrying costs.
- Active implantable shelf-life constraints:Short-dated cardiac devices and neurostimulators compress delivery windows, limiting route optimization flexibility and increasing failed-delivery penalties.
Strategic Opportunities
- India's expanding hospital infrastructure:Greenfield medical cities in Andhra Pradesh and Gujarat lack established cold chain partners, creating first-mover advantage for temperature-qualified entrants.
- Predictive analytics convergence with IoT sensors:Real-time location and condition monitoring enables dynamic rerouting around hospital receiving window constraints, reducing dwell time penalties.
- Japan's PMDA traceability alignment:Upcoming serialization harmonization with international standards creates upgrade demand for legacy distribution networks serving Japanese medical device manufacturers.
Industry Challenges
- Qualified cold chain technician scarcity:GDP-compliant handling certification for biologics and cell therapies remains concentrated among limited training providers, constraining workforce scaling.
- Legacy warehouse management system integration:Hospital ERP platforms require bespoke EDI connections for ASN transmission and proof-of-delivery confirmation, extending onboarding timelines for new logistics contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Devices and Equipment Logistics Market |
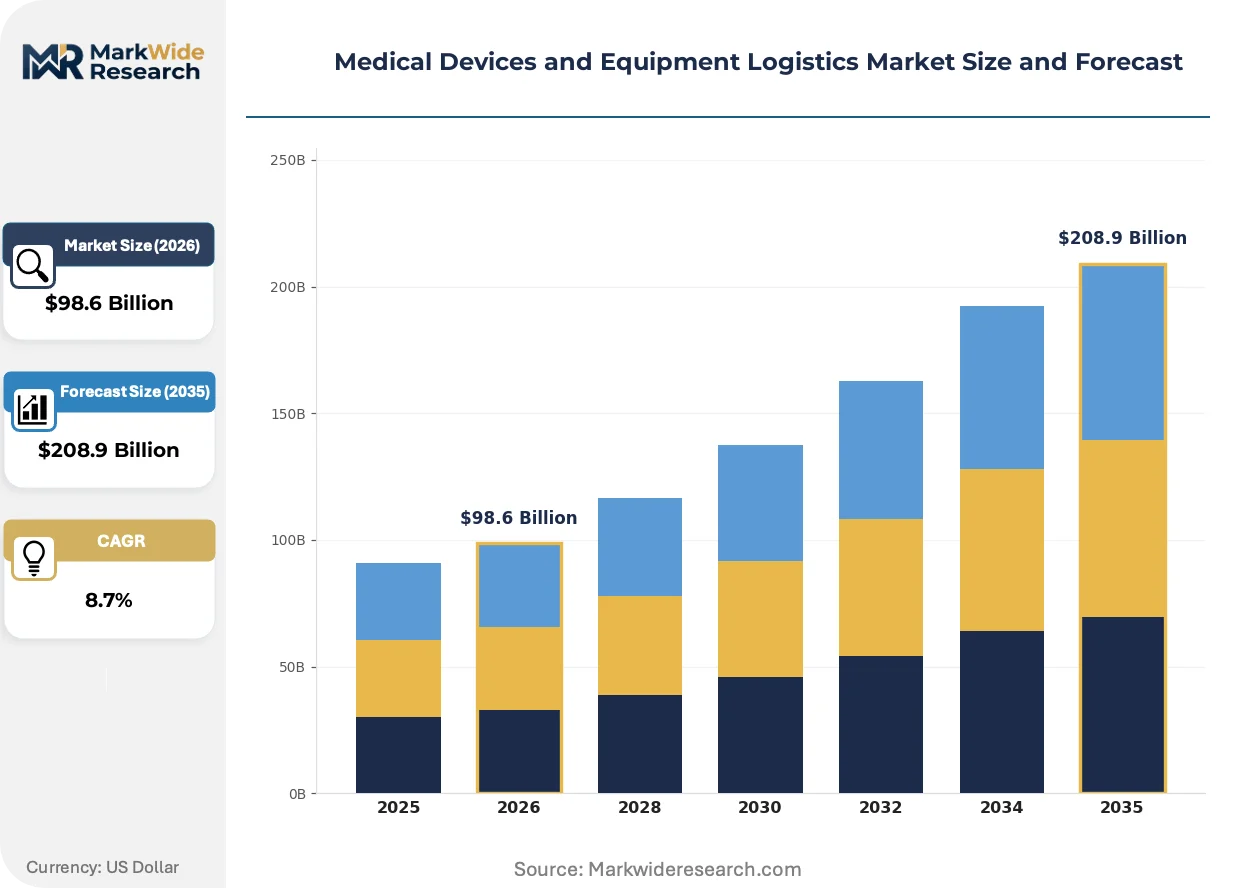
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Life Support Devices, Therapeutic Equipment End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Providers Service Type: Transportation, Warehousing, Inventory Management, Installation Services Technology: Telemedicine, RFID Tracking, IoT Devices, Predictive Analytics |
| Companies Covered | Cardinal Health, DHL International GmbH, United Parcel Service of America, Inc., FedEx, Cencora, SF Express, Kinesis Medical B.V., Plexus Corp., Warehousing and Fulfillment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Devices and Equipment Logistics Market Trends and Innovations
RFID-enabled real-time location systems are displacing barcode scanning across high-value device segments, while predictive analytics platforms compress route planning cycles. These technology layers are converging with hospital inventory management systems to create closed-loop supply chains.
Autonomous mobile robots are automating kitting and sterilization tray assembly in centralized distribution centers serving consolidated hospital networks. Integrated delivery networks in the United States are deploying these systems fastest, reducing human touchpoints for implantable device handling. This automation is compressing order-to-delivery cycles while maintaining FDA quality system regulation compliance for sterile product integrity.
EU MDR Article 14 obligations are reshaping importer liability structures, requiring authorized representatives to maintain device history records and field safety corrective action capabilities. German and Dutch distributors are absorbing compliance costs through dedicated regulatory affairs functions. Implantable device categories face the tightest documentation requirements, driving warehousing consolidation around qualified importers with established pharmacovigilance systems.
Point-of-care diagnostic expansion is fragmenting demand geography, pulling inventory positioning toward ambulatory surgical centers and specialty clinics away from central hospital pharmacies. Distributors are responding with micro-fulfillment nodes in metropolitan corridors. This pattern is most visible in Germany's outpatient surgery growth zones and United States suburban health campus developments.
Medical Devices and Equipment Logistics Market Segmentation
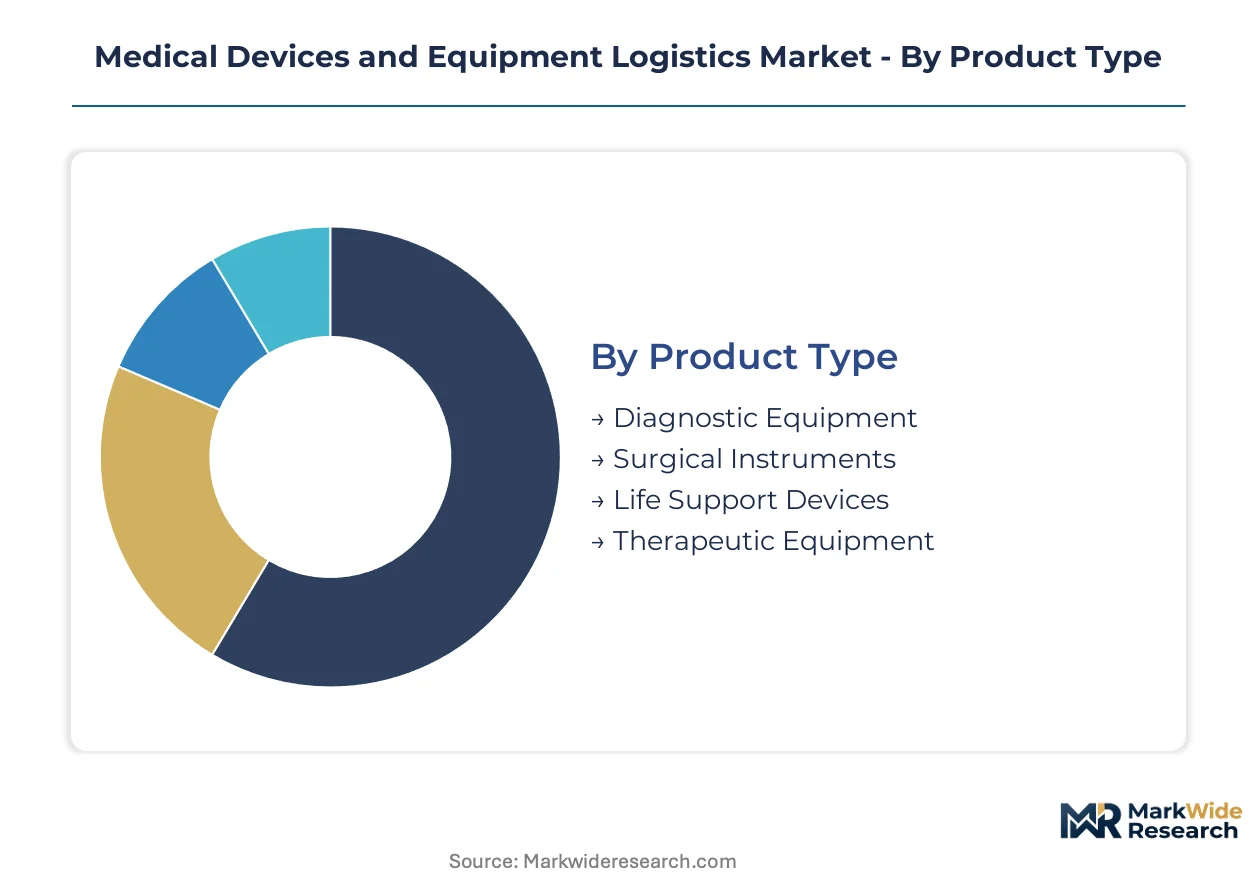
Medical device logistics segmentation reveals distinct capital requirements across product handling protocols and customer service tiers. Each category demands specialized infrastructure investments that reshape competitive positioning among third-party logistics providers.
Product Type:
Capital intensity varies sharply across device categories, with temperature-controlled biologics and sterile surgical kits requiring the steepest upfront infrastructure commitments.
- Diagnostic Equipment:Imaging systems and laboratory analyzers dominate volume flows due to replacement cycles and point-of-care expansion. Hospital procurement consolidation concentrates demand with integrated delivery networks seeking direct-to-site delivery and real-time visibility protocols.
- Surgical Instruments:Sterile kits and implantable devices command premium handling margins through contamination-free transit requirements and kitting complexity. Germany's Tuttlingen cluster generates specialized lane density for temperature-controlled instrument transport serving European surgical centers.
- Life Support Devices:Ventilators and dialysis equipment require calibrated installation protocols and field service integration.
- Therapeutic Equipment:Infusion pumps and radiation therapy systems demand serialized tracking under FDA unique device identification mandates.
Diagnostic Equipment absorbs the bulk of installed capacity; Surgical Instruments is expanding most quickly.
End User:
Customer type determines service tier configuration, with acute care facilities demanding the most comprehensive direct-to-site capabilities.
- Hospitals:Integrated delivery networks compress distribution tiers and mandate real-time ASN transmission and proof-of-delivery confirmation through bespoke EDI connections. Consolidated procurement amplifies volume concentration with fewer buyers controlling larger contract values.
- Clinics:Ambulatory surgical centers and specialty clinics pull inventory positioning toward metropolitan micro-fulfillment nodes. Point-of-care diagnostic expansion fragments demand geography away from central hospital pharmacies.
- Rehabilitation Centers:Long-term care facilities require scheduled delivery windows and equipment calibration services.
- Home Care Providers:Patient-direct delivery demands last-mile cold chain integrity for biologics and active implantables with compressed shelf-life constraints.
Hospitals command the deepest logistics integration; Home Care Providers is gaining share fastest.
Service Type:
Margin structure diverges across the value chain, with value-added services capturing premium pricing over commodity transport.
- Transportation:Time-definite express protocols for implantable devices require specialized refrigerated fleet investment that locks smaller operators out of premium segments. Temperature integrity between two and eight degrees Celsius for biologics demands GDP-compliant handling certification.
- Warehousing:EU MDR Article 14 obligations reshape importer liability structures, requiring authorized representatives to maintain device history records and field safety corrective action capabilities. German and Dutch distributors absorb compliance costs through dedicated regulatory affairs functions.
- Inventory Management:RFID-enabled real-time location systems displace barcode scanning across high-value device segments.
- Installation Services:Imaging equipment and radiation therapy systems require certified technician deployment and calibration protocols.
Transportation anchors revenue scale; Inventory Management is climbing the fastest.
Technology:
Adoption maturity separates legacy operators from digital-first competitors, with sensor convergence enabling predictive capabilities.
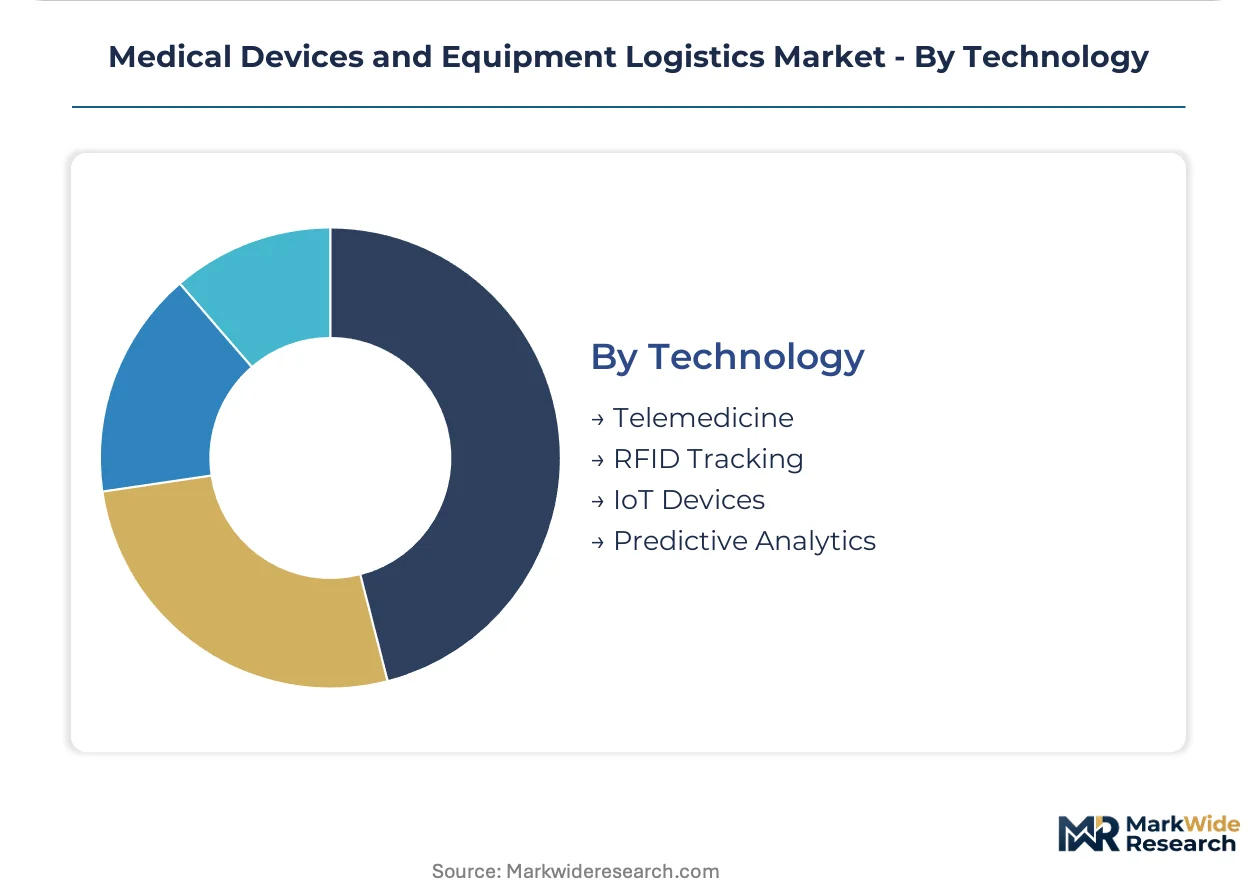
- RFID Tracking:Real-time location verification dominates high-value device segments through sterile supply chain visibility. Autonomous mobile robots automate kitting and sterilization tray assembly in centralized distribution centers serving consolidated hospital networks.
- Predictive Analytics:Route optimization around hospital receiving windows reduces dwell time penalties and failed-delivery exposure. IoT sensor convergence enables dynamic rerouting for temperature excursions and delivery window constraints.
- Telemedicine:Remote diagnostic platforms create new logistics requirements for consumer-grade device distribution.
- IoT Devices:Condition monitoring sensors track temperature, humidity, and shock events across transit lanes.
RFID Tracking holds the largest installed base; Predictive Analytics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters anchor European medical device logistics infrastructure. Tuttlingen and Erlangen generate specialized lane density for temperature-controlled surgical instrument transport. The country's medical technology corridor concentrates qualified importer capabilities under EU MDR Article 14 obligations.
United States
Integrated delivery networks compress distribution tiers around direct-to-site delivery mandates. FDA unique device identification enforcement drives serialization infrastructure investment across domestic networks. The Minneapolis medical device corridor and Boston biotech cluster sustain specialized cold chain density for implantable devices.
Germany
Tuttlingen's surgical instrument manufacturers and Erlangen's imaging equipment producers generate temperature-controlled transport demand. EU MDR traceability requirements reshape cross-border warehousing around qualified importer networks. The country's medical technology clusters anchor specialized logistics corridors serving European surgical centers.
China
Greenfield hospital infrastructure in tier-two cities pulls inventory positioning toward domestic distribution nodes. NMPA medical device registration reforms tighten documentation requirements for imported active implantables. The Yangtze River Delta medical device manufacturing belt concentrates outbound cold chain investment.
India
Andhra Pradesh and Gujarat medical cities lack established cold chain partners for biologics and cell therapies. CDSCO medical device rules alignment with international standards drives qualified importer network expansion. The country's hospital infrastructure buildout creates first-mover advantage for temperature-qualified logistics entrants.
Japan
PMDA traceability harmonization with international serialization standards upgrades legacy distribution networks. METI medical device industry support programs accelerate domestic logistics capability investment. The Osaka-Tokyo medical device manufacturing corridor sustains premium handling demand for short-dated cardiac devices.
Medical Devices and Equipment Logistics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue predictive analytics and IoT-enabled visibility layers. The market consolidates around three structural archetypes: integrated healthcare distributors with direct-to-site infrastructure, global express carriers with temperature-controlled lane density, and specialized medical logistics operators with GDP-compliant certification. Consolidation pressures intensify as hospital procurement centralization concentrates contract values with fewer buyers. Dominant competitive moves include strategic partnerships with integrated delivery networks and geographic expansion into underpenetrated medical city corridors.
Among integrated healthcare distributors, Cardinal Health and Cencora occupy positions exemplifying the direct-to-site service archetype. Global express carriers include DHL International GmbH and FedEx, representing temperature-controlled lane density models. Kinesis Medical B.V. sits within the specialized European medical logistics tier, anchoring qualified importer capabilities under EU MDR obligations. These three archetypes—integrated distribution, global express, and specialized compliance—define competitive positioning as regulatory complexity and procurement consolidation reshape contract structures.
| Leading Market Players |
|---|
| Cardinal Health |
| DHL International GmbH |
| United Parcel Service of America, Inc. |
| FedEx |
| Cencora |
| SF Express |
| Kinesis Medical B.V. |
| Plexus Corp. |
| Warehousing and Fulfillment |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between GDP-compliant cold chain operators and commodity transport providers manifests in pricing power concentration and supply chain node selection. Premium handlers capture margin through bundled regulatory documentation and temperature integrity guarantees, while standard freight operators compete on lane density alone.
Pricing Analysis
Warranty and service bundling separates qualified medical logistics operators from unbundled freight providers, with FDA serialization compliance and EU MDR traceability documentation commanding substantial premiums. Three-tier pricing structure across certified cold chain, standard healthcare transport, and economy freight tiers reflects handling protocol complexity. Price differentiation hinges on GDP certification grade and real-time visibility capability, with hospital procurement consolidation intensifying cost compression in standard tiers. Integrated delivery networks exhibit lowest price sensitivity due to patient-safety liability exposure, while ambulatory surgical centers prioritize cost minimization.
Supply Chain Analysis
Domestic-content requirements in India's medical device rules and China's NMPA registration reforms are reshaping sourcing patterns toward qualified local distribution partners. Manufacturing concentration in Germany, China, and the United States generates specialized lane density for temperature-controlled surgical instruments and implantable devices. Supply chains draw from lithium battery cells for active implantables, sterile barrier packaging, and specialized refrigerants for cold chain maintenance. Single-source vulnerability in qualified cold chain technician certification constrains network scaling. Distribution runs through integrated healthcare distributors with direct-to-site capabilities, bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cold chain technician scarcity props pricing across premium handling tiers, constraining supply expansion faster than hospital procurement consolidation can compress margins.
For Market Incumbents: Anticipate margin compression from autonomous mobile robot deployment by integrated delivery networks seeking in-house kitting capabilities. Defend positioning through backward integration into sterilization tray assembly and predictive analytics platform development. Prioritize certification investment in Japan's PMDA traceability harmonization to capture upgrade demand from legacy distribution networks. For New Entrants and Emerging Players: Capture white-space opportunity in India's Andhra Pradesh and Gujarat medical cities, where greenfield hospital infrastructure lacks established temperature-qualified partners. Target ambulatory surgical center micro-fulfillment nodes in Germany's outpatient surgery growth zones and United States suburban health campuses. Pursue hospital system partnership go-to-market models with direct-to-site capability guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with specialized European medical logistics operators given EU MDR Article 14 importer liability consolidation. Long-term viability favors qualified importers with established pharmacovigilance systems and dedicated regulatory affairs functions. Monitor PMDA traceability implementation timelines as inflection indicator for Japanese distribution network upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Authorized Representative Qualification | Establishes liability-compliant warehousing for implantable device distribution across European surgical centers. |
| Hospital System Direct-to-Site Partnership | Locks in volume concentration from integrated delivery network procurement consolidation. |
| Predictive Analytics Platform Deployment | Enables dynamic rerouting around FDA-mandated receiving window constraints for serialized devices. |
| GDP-Compliant Cold Chain Certification | Creates regulatory moat for biologics and active implantable handling in premium segments. |
| Autonomous Mobile Robot Kitting Integration | Compresses order-to-delivery cycles while maintaining sterile supply chain integrity. |
Research Methodology
Multi-period observation of hospital procurement consolidation patterns, cold chain infrastructure deployment, and regulatory compliance cost trajectories anchored the trend analysis, supplemented by interviews with logistics operations directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at qualified importers. Secondary validation drew from FDA UDI database filings, EMA post-market surveillance reports, EU MDR notified body documentation, and hospital procurement database records. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Segment-weighting applied product-type splits across diagnostic equipment, surgical instruments, life support devices, and therapeutic equipment, crossed with service-type tiers spanning transportation, warehousing, inventory management, and installation services. Technology adoption curves for RFID tracking, predictive analytics, and IoT condition monitoring shaped growth rate derivation across the projection horizon. Modeled inputs included replacement cycle timing for imaging systems, point-of-care diagnostic expansion rates, and active implantable shelf-life constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU-UK regulatory divergence, qualified technician training pipeline expansion, and autonomous logistics technology maturation. Forecasts reflect documented assumptions regarding hospital network consolidation velocity and serialization mandate enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Medical Spa Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Acute Care Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Spa Services Market
Healthcare Services
Retail Clinics Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Long Term Care Market
Healthcare Services
US Medical Billing Outsourcing Market