
 Knotless Tissue Control Devices Market | 2026-2036
Knotless Tissue Control Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Knotless Tissue Control Devices Market Foresight
North American surgical instrument manufacturers is restructuring supply chains to secure polymer resin allocations for knotless anchor production. Johnson & Johnson Services, Inc. leverages its DePuy Synthes orthopedic franchise to dominate sports medicine channel access. Medtronic anchors its tissue control portfolio through broad spine and extremities distribution networks. Stryker Corporation differentiates via integrated operating room systems that bundle knotless devices with visualization platforms.
Knotless tissue control devices are implantable or handheld surgical instruments designed to secure soft tissue to bone without traditional suture knots, typically employing braided polyethylene suture threaded through an eyelet anchor and secured by friction or mechanical interference fit. These instruments serve primarily to reduce operative time, eliminate knot stack irritation, and improve fixation strength in arthroscopic and open procedures across orthopedic, cardiovascular, and general surgery disciplines. The application dimension shows orthopedics occupying the deepest installed base while cardiovascular represents the fastest clinical validation pipeline as transcatheter techniques mature. Technology segmentation reveals polymer-based constructs sustaining the largest revenue pool, though bioengineered variants with osteoconductive coatings are capturing disproportionate R&D investment from device firms seeking premium positioning.
FDA 510(k) clearance pathways govern US market entry for knotless suture anchors, while the EU Medical Device Regulation demands expanded clinical data and notified body scrutiny for class IIa and IIb implantables. ISO 13485 quality management certification and ASTM F1839 bone analog testing standards further constrain supplier eligibility, filtering out contract manufacturers lacking validated cleanroom injection molding capabilities. Stakeholders must monitor evolving FDA guidance on bioresorbable polymer degradation profiles and EU MDR technical documentation requirements to sustain product registrations across both jurisdictions.
Market Dynamics
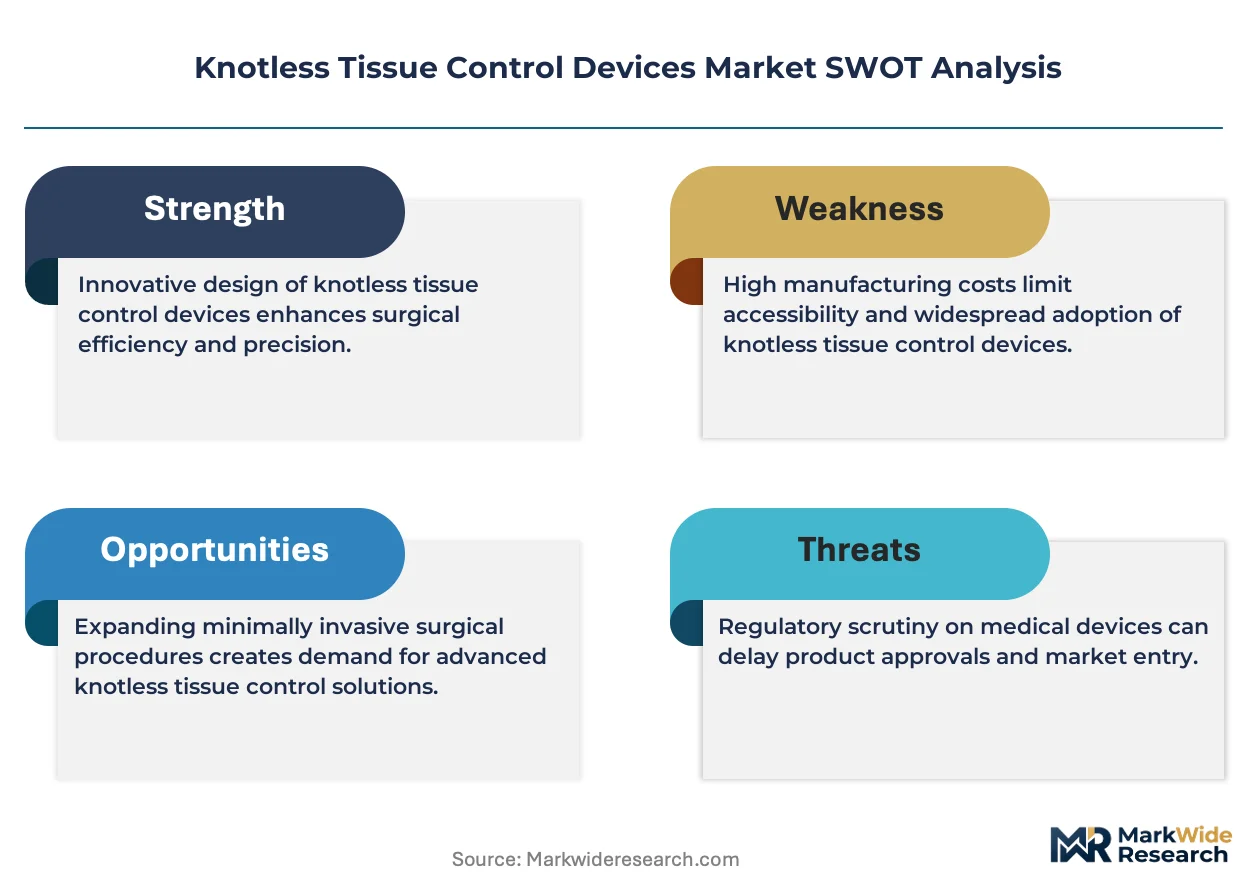
EU MDR technical documentation requirements and FDA bioresorbable polymer guidance are compressing supplier eligibility, forcing orthopedic device firms to consolidate around validated cleanroom injection molding capabilities and dual-jurisdiction quality systems.
Growth Catalysts
- Arthroscopic procedure conversion:Ambulatory surgical centers in the United States are systematically replacing open tissue repair with minimally invasive knotless fixation, expanding addressable procedure volumes across rotator cuff and meniscal applications.
- MDR compliance acceleration:The EU Medical Device Regulation's tightened clinical evidence mandates for class IIb implantables is filtering out marginal competitors and concentrating procurement among notified body-certified manufacturers with robust technical files.
- Bioengineered coating pipelines:Osteoconductive surface modifications on polyethylene suture anchors are advancing through preclinical validation, promising premium positioning for firms that secure breakthrough device designations.
Market Restraints
- Polymer resin allocation volatility:North American surgical instrument manufacturers face constrained supply of medical-grade ultra-high molecular weight polyethylene from specialty chemical producers, creating input cost uncertainty.
- Bioresorbable degradation profile limitations:Current PLLA and PGA constructs exhibit unpredictable mechanical strength loss timelines in vivo, restricting their deployment to low-load anatomic sites despite theoretical advantages.
- Notified body capacity bottlenecks:EU MDR implementation has collapsed the pool of designated conformity assessment bodies, extending product registration timelines for knotless anchor portfolios by twelve to eighteen months.
Strategic Opportunities
- Transcatheter cardiovascular expansion:Transcatheter mitral valve repair and left atrial appendage closure procedures in Germany and Switzerland are validating knotless tissue approximation for cardiac applications beyond orthopedics.
- Integrated operating room bundling:Visualization platform vendors are constructing preference contracts that wrap knotless devices with arthroscopy towers, creating captive demand channels for compatible fixation systems.
- Osteoconductive premium tiering:Hydroxyapatite-coated and biologic-enhanced anchors command three-to-five-fold price multiples against standard polymer constructs, rewarding R&D investment with sustained margin expansion.
Industry Challenges
- Cleanroom molding capability scarcity:Validated ISO 13485 injection molding capacity for complex anchor geometries concentrates among a handful of contract manufacturers, creating qualification backlogs for new market entrants.
- Dual-jurisdiction quality system complexity:Sustaining simultaneous FDA 510(k) and EU MDR technical documentation demands redundant clinical evidence packages and divergent post-market surveillance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knotless Tissue Control Devices Market |
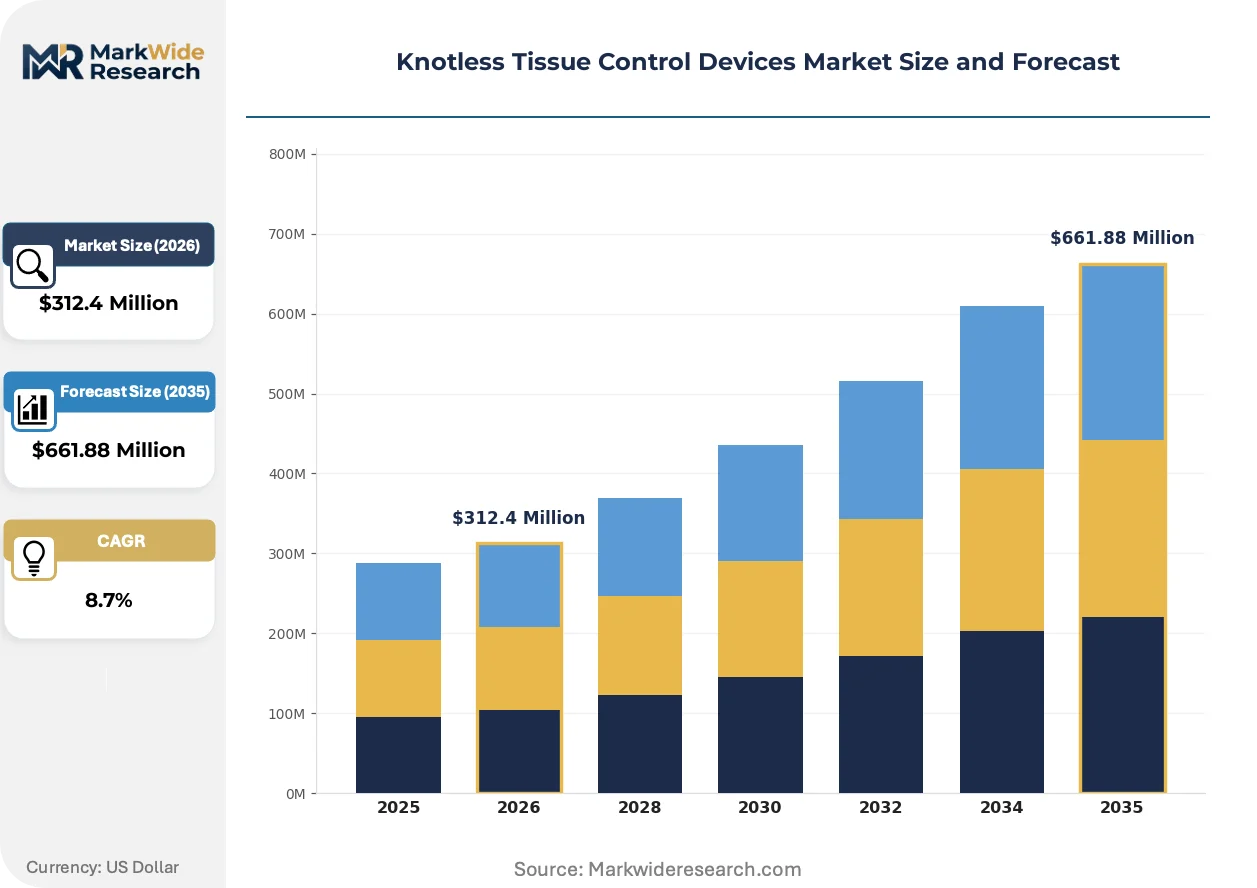
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Devices, Tools, Equipment, Kits Application: Orthopedics, Cosmetics, Cardiovascular, General Surgery End User: Hospitals, Clinics, Surgery Centers, Patients Technology: Biodegradable, Non-biodegradable, Polymer-based, Bioengineered |
| Companies Covered | Johnson & Johnson Services, Inc., Medtronic, Stryker Corporation, Smith & Nephew, Zimmer Biomet, Medline Industries, Inc., ConMed Corporation, Boston Scientific, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knotless Tissue Control Devices Market Shifts & Advancements
Friction-based mechanical interference designs are displacing traditional eyelet anchors across arthroscopic applications, while regulatory convergence and procurement consolidation are compressing the viable supplier base.
Braided polyethylene suture with integrated tensioning mechanisms is unifying fixation and tension control within single-device platforms. Sports medicine surgeons in German orthopedic surgery centers are adopting these constructs for rotator cuff repair at accelerating rates. This convergence is compressing operative time and eliminating knot stack complications that previously drove revision procedures.
The EU Medical Device Regulation's expanded clinical data requirements for soft-tissue fixation products are forcing manufacturers to generate prospective registry outcomes. This documentation burden favors incumbent firms with established post-market surveillance infrastructure. Class IIb implantable reclassifications are most acutely affecting suture anchor portfolios, driving consolidation toward notified body relationships in Germany and Ireland.
Hospital procurement committees are consolidating vendor lists around full-line orthopedic suppliers capable of spanning implants, instruments, and capital equipment. Independent knotless device specialists face exclusion from integrated delivery networks that prefer single-source contracting. This concentration is most visible in United States ambulatory surgical centers, where GPO-affiliated purchasing is displacing surgeon-directed preference.
Knotless Tissue Control Devices Market Segmentation
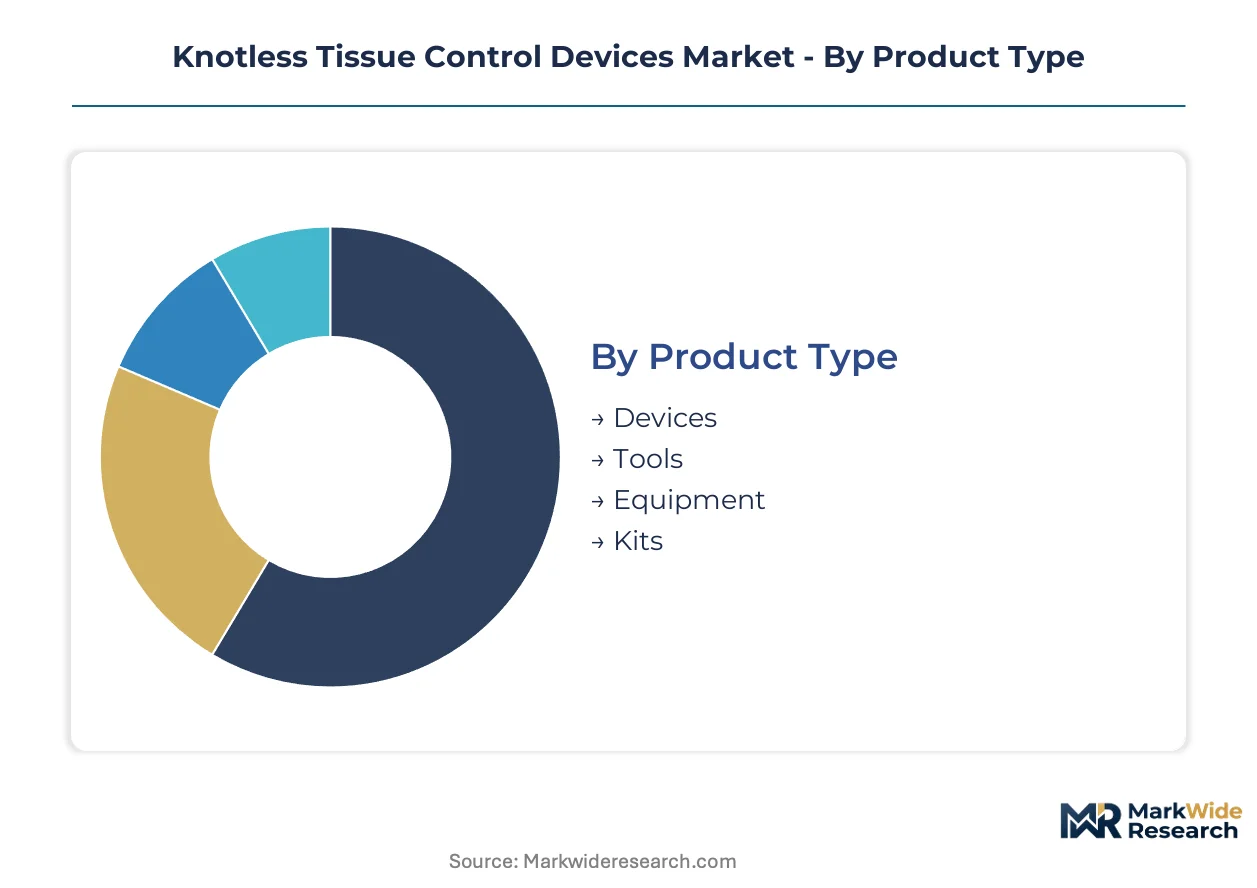
Segmentation in knotless tissue control devices reveals how procurement criteria diverge across surgical settings and material technologies. Understanding these splits enables suppliers to align R&D investment with the highest-margin demand pockets and regulatory pathways.
Product Type:
Cost tier separates occasional purchasers from high-volume institutional buyers in this category.
- Devices:Implantable anchors and fixation constructs dominate hospital procurement budgets. German orthopedic surgery centers are standardizing on pre-loaded disposable devices to reduce OR turnover time and sterilization costs.
- Kits:Procedure-specific bundles combine multiple anchor sizes with dedicated instrumentation. Ambulatory surgical centers in the United States prefer kits for rotator cuff repairs to minimize inventory complexity and capture GPO contract discounts.
- Tools:Reusable tensioning and insertion instruments serve cost-conscious mid-tier hospitals.
- Equipment:Capital equipment for anchor deployment occupies a narrow niche in academic medical centers.
Volume sits with Devices; growth tilts toward Kits.
Application:
Clinical validation maturity determines reimbursement security and sales cycle length across surgical disciplines.
- Orthopedics:Arthroscopic rotator cuff and meniscal repair procedures generate the deepest installed base. Sports medicine surgeons in United States ambulatory surgical centers are converting open repairs to knotless fixation at accelerating rates.
- Cardiovascular:Transcatheter mitral valve repair and left atrial appendage closure are validating knotless tissue approximation. Swiss and German cardiac centers are piloting these constructs for procedures beyond traditional orthopedics.
- General Surgery:Hernia mesh fixation and soft-tissue retraction applications remain underdeveloped relative to orthopedic adoption curves.
- Cosmetics:Minimal access facelift and body contouring procedures employ knotless sutures for scar reduction in private clinic settings.
Revenue concentrates in Orthopedics; Cardiovascular is expanding most quickly.
End User:
Procurement authority and volume scale fragment sharply across care settings.
- Surgery Centers:Freestanding ambulatory facilities in the United States are converting open procedures to minimally invasive techniques. GPO-affiliated purchasing is displacing surgeon-directed preference in these settings.
- Hospitals:Academic medical centers and community hospitals maintain the largest absolute procedure volumes. Integrated delivery networks are consolidating vendor lists around full-line orthopedic suppliers capable of spanning implants, instruments, and capital equipment.
- Clinics:Office-based cosmetic and minor orthopedic procedures generate sporadic demand for handheld knotless tools.
- Patients:Direct-to-consumer channels remain negligible due to implantable device regulations.
Procedure volume clusters at Surgery Centers; margin protection favors Hospitals.
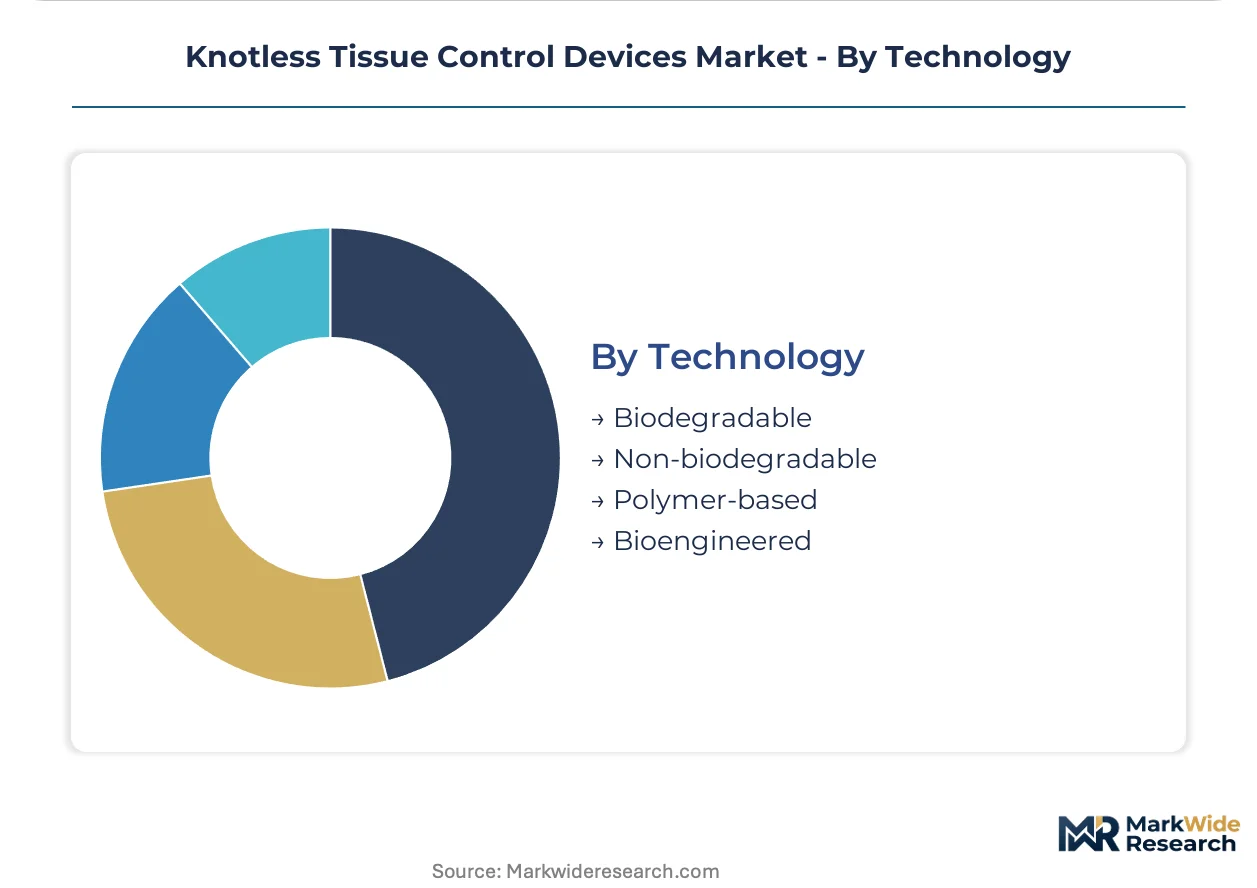
Technology:
Material degradation profile and surface engineering separate premium positioning from commodity competition.
- Polymer-based:Braided polyethylene suture with friction-lock anchors sustains the largest revenue pool. North American manufacturers face constrained supply of medical-grade ultra-high molecular weight polyethylene from specialty chemical producers.
- Bioengineered:Hydroxyapatite-coated and biologic-enhanced constructs command premium multiples. Device firms are capturing disproportionate R&D investment for osteoconductive surface modifications that promise sustained margin expansion.
- Biodegradable:PLLA and PGA constructs exhibit unpredictable mechanical strength loss timelines in vivo, restricting deployment to low-load anatomic sites.
- Non-biodegradable:Permanent polymer and metallic anchors retain fixation strength indefinitely, dominating high-load orthopedic applications.
Commercial traction favors Polymer-based; Bioengineered is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade ultra-high molecular weight polyethylene from specialty chemical producers in Germany and the United States anchors regional supply chains for knotless anchor manufacturing. Orthopedic surgery centers and ambulatory facilities drive demand concentration across developed markets with mature arthroscopic procedure adoption.
United States
Ambulatory surgical centers in Texas and Florida are converting open rotator cuff repairs to knotless fixation at accelerating rates. FDA 510(k) clearance pathways govern market entry for suture anchors, with bioresorbable polymer guidance tightening degradation profile documentation. The Southeast surgical corridor from Atlanta to Tampa concentrates GPO-affiliated procurement activity.
Germany
Orthopedic surgery centers in Bavaria and North Rhine-Westphalia are expanding arthroscopic procedure volumes for meniscal and rotator cuff applications. EU Medical Device Regulation class IIb implantable requirements filter procurement toward notified body-certified manufacturers with robust technical files. The Munich-Stuttgart medical technology cluster anchors polymer processing and cleanroom molding capabilities.
Switzerland
Swiss cardiac centers in Zurich and Geneva are piloting knotless tissue approximation for transcatheter mitral valve repair beyond traditional orthopedics. Swissmedic oversight aligns with EU MDR standards for implantable device registration. The Basel-Zurich corridor concentrates precision polymer engineering and surface coating innovation.
United Kingdom
London and Manchester academic medical centers maintain the largest absolute procedure volumes for sports medicine applications. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR technical documentation requirements. The Oxford-Cambridge-London triangle concentrates medical device R&D and clinical validation infrastructure.
Japan
PMDA regulatory pathways govern knotless anchor approvals for orthopedic and cardiovascular applications in Tokyo and Osaka metropolitan areas. METI industrial policy supports domestic polymer processing capabilities for medical device manufacturing. The Kansai medical device cluster around Osaka anchors regional distribution networks.
Knotless Tissue Control Devices Market Competitive Landscape
Global majors compete with regional champions across distribution network depth and regulatory certification breadth. The vendor base concentrates around full-line orthopedic suppliers capable of spanning implants, instruments, and capital equipment. Three archetypes dominate: diversified conglomerates with channel bundling power, mid-tier specialists with procedure-specific kits, and contract manufacturers with validated cleanroom capabilities. M&A activity targets notified body-certified portfolios and dual-jurisdiction quality systems.
Within the diversified conglomerate tier, Johnson & Johnson Services, Inc., Medtronic, and Stryker Corporation exemplify scale-driven positioning. These entities occupy positions anchored by broad orthopedic and spine distribution networks, with channel access reinforced through integrated operating room system bundling. Their archetype represents the consolidation pressure filtering procurement toward full-line suppliers capable of spanning implants, instruments, and visualization platforms.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Medtronic |
| Stryker Corporation |
| Smith & Nephew |
| Zimmer Biomet |
| Medline Industries, Inc. |
| ConMed Corporation |
| Boston Scientific |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
GPO-affiliated purchasing consolidation across United States ambulatory surgical centers is compressing vendor lists and forcing supply responses toward standardized kit configurations with embedded instrumentation. This procurement concentration shifts pricing power toward full-line orthopedic suppliers capable of bundling knotless devices with arthroscopy towers and visualization platforms.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from transactional competitors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO 13485 certification grade and osteoconductive coating presence. Pricing pressure stems from constrained medical-grade ultra-high molecular weight polyethylene resin allocations from specialty chemical producers. Ambulatory surgical centers exhibit highest price sensitivity due to GPO contract discipline, while academic medical centers prioritize fixation performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States anchor hub-and-spoke patterns for knotless anchor fulfillment. Manufacturing draws from validated cleanroom injection molding capabilities concentrated in the Munich-Stuttgart medical technology cluster and North American polymer processing hubs. Raw material dependencies include medical-grade ultra-high molecular weight polyethylene, braided suture fibers, and hydroxyapatite coating precursors. Single-source vulnerability concentrates around notified body-certified contract manufacturers with dual-jurisdiction quality systems. Distribution runs through orthopedic distributor networks and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where EU MDR technical documentation requirements and FDA bioresorbable polymer guidance are filtering out marginal competitors without robust clinical evidence infrastructure.
For Market Incumbents: To counter cleanroom molding capability scarcity among contract manufacturers, secure captive supply through backward integration into polymer processing or long-term capacity reservations with validated ISO 13485 facilities. Deepen channel control by constructing preference contracts that bundle knotless devices with integrated operating room visualization platforms. For New Entrants and Emerging Players: Begin with transcatheter cardiovascular applications in Swiss and German cardiac centers, where knotless tissue approximation for mitral valve repair remains underpenetrated relative to orthopedic saturation. Target procedure-specific kits for rotator cuff repair in mid-tier United States ambulatory surgical centers seeking GPO-compliant alternatives to full-line suppliers. For Investors and Strategic Acquirers: The window for entry favors notified body-certified manufacturers with established EU MDR technical files and dual-jurisdiction quality systems. Long-term viability hinges on osteoconductive coating pipelines and breakthrough device designations. Watch FDA guidance evolution on bioresorbable polymer degradation profiles as the inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR class IIb implantable reclassification demands expanded clinical evidence and notified body relationships. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate vendor lists around full-line orthopedic suppliers. |
| Backward Integration | Captive supply of medical-grade polymer resin buffers input cost volatility from specialty chemical producers. |
| Osteoconductive Coating Development | Hydroxyapatite surface modifications command premium multiples and sustain margin expansion. |
| Software Companion Development | Tensioning mechanism integration with arthroscopy visualization platforms creates preference contract stickiness. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with sports medicine surgeons, hospital purchasing committee members, GPO contracts managers, and biomedical engineers validated procedural adoption curves and procurement criteria. FDA 510(k) clearance databases, EU MDR notified body certificates, and ASTM F1839 bone analog testing standards provided regulatory pathway documentation. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation converged on market sizing.
Data-stream reconciliation across implant shipment records, hospital procurement databases, and distributor inventory movements informed the analytical framework. Segmentation dimensions modeled include product type, application discipline, end-user setting, and material technology platform across the projection horizon. CAGRs derived from procedure volume growth rates, price trajectory assumptions, and technology substitution curves. Industry-specific inputs encompassed arthroscopic conversion rates in ambulatory settings and transcatheter cardiovascular validation timelines.
Underlying measurement precision varies by segment; orthopedics applications carry tighter precision than emerging cardiovascular indications due to mature reimbursement coding and established procedure registries. Forecasts reflect assumptions regarding EU MDR implementation pace, notified body capacity expansion, and polymer resin supply stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Global Veterinary Surgical Instruments Market