
 Global Arthroscopy Instruments Market | 2026-2036
Global Arthroscopy Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Arthroscopy Instruments Market Foresight
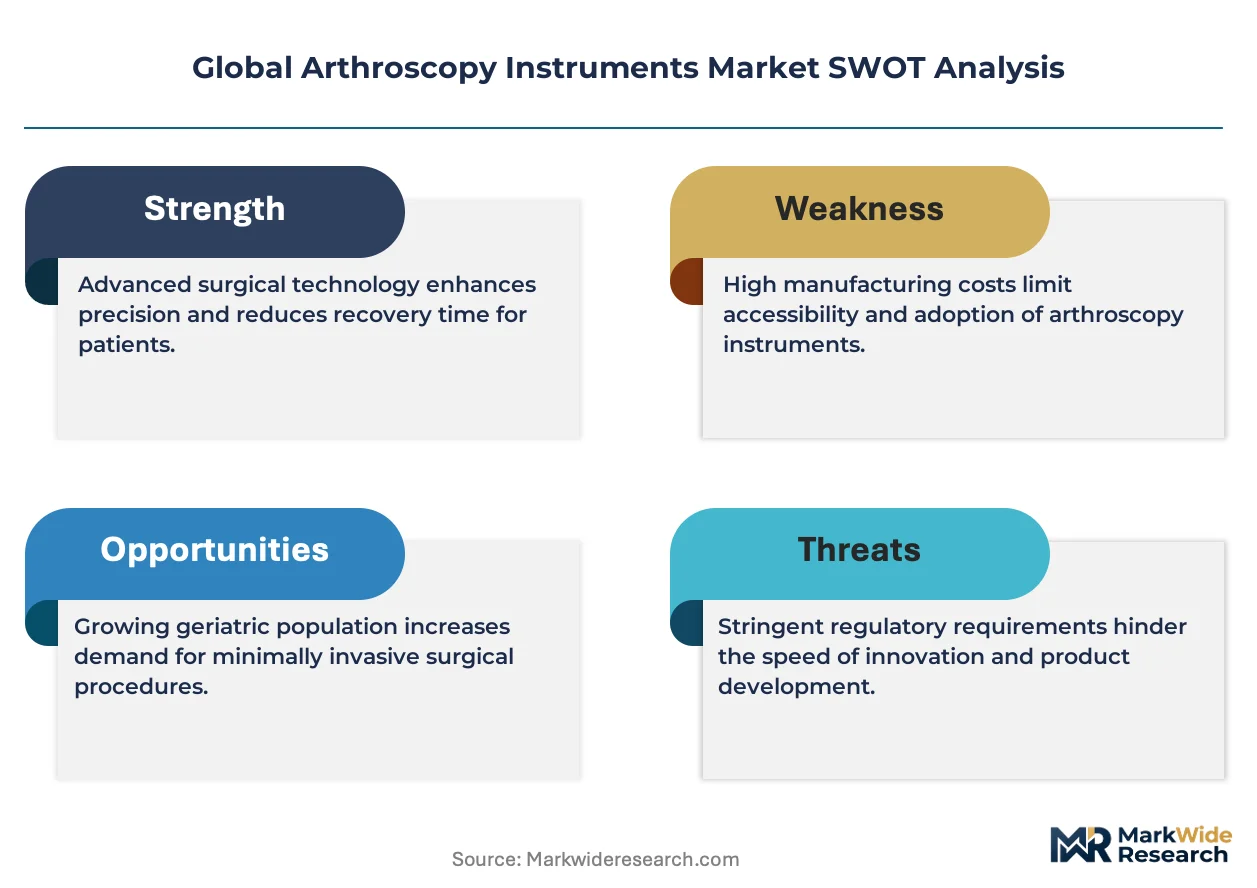
Equipment leasing and pay-per-procedure financing is fragmenting the competitive landscape for high-cost arthroscopy towers and integrated visualization systems. Arthrex leverages its surgeon training infrastructure to sustain loyalty across ambulatory settings. Zimmer Biomet anchors its position through broad orthopedic portfolio bundling that spans implants and instruments. Smith & Nephew differentiates via advanced radiofrequency ablation systems for soft-tissue shoulder repair.
Arthroscopy instruments comprise rigid endoscopes, motorized shavers, and specialized hand instruments designed for minimally invasive joint visualization and intervention, typically featuring 4 mm outer diameter scopes with 0-degree to 70-degree viewing angles and high-definition camera heads for real-time tissue discrimination. These systems enable diagnostic inspection and therapeutic manipulation through 2-3 portal incisions, reducing open-surgical morbidity and accelerating postoperative rehabilitation timelines. Shavers and radiofrequency wands capture the deepest margin pools as recurring consumables with strong surgeon preference stickiness, while fluid management systems face accelerating replacement cycles as pressure-controlled pump technology displaces gravity-dependent irrigation. Knee surgery applications retain the largest procedure volume base, though shoulder repair segments command premium pricing due to instrument complexity and longer operative durations.
The FDA's 510(k) premarket notification pathway governs arthroscope and shaver clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb instruments entering European markets. Japan's PMDA maintains distinct quality management system inspections for foreign manufacturers seeking access through its Foreign Manufacturer Registration program. Stakeholders must monitor how notified body capacity constraints under MDR delay CE mark timelines and reshape competitive entry sequencing across European markets.
Market Dynamics
Pressure-controlled fluid management pumps are displacing gravity-dependent irrigation systems across ambulatory surgical centers, compressing replacement cycles and reshaping capital equipment procurement patterns for arthroscopy towers.
Growth Catalysts
- MDR clinical evidence requirements:Stricter EU Medical Device Regulation standards for Class IIb instruments are accelerating portfolio rationalization among notified bodies, concentrating supplier relationships with established manufacturers.
- Radiofrequency ablation systems:Advanced energy platforms for soft-tissue shoulder repair command premium pricing and generate recurring consumable revenue through proprietary wand designs.
- Pay-per-procedure financing:Equipment leasing models reduce upfront capital barriers for ambulatory surgical centers expanding arthroscopy service lines under payor cost pressure.
Market Restraints
- Notified body capacity constraints:EU MDR implementation bottlenecks delay CE mark timelines for shaver and visualization system entrants, extending time-to-revenue for new product launches.
- Precise optical component sourcing:German precision endoscope manufacturing clusters in Tuttlingen and Knittlingen create geographic concentration risk for rod-lens supply chains.
- High-definition camera head standardization:Surgeon preference stickiness around 4K and 8K imaging platforms limits switching flexibility and locks facilities into integrated tower ecosystems.
Strategic Opportunities
- Hip arthroscopy expansion:Underpenetrated femoroacetabular impingement procedures in the United States offer volume growth as technique standardization improves.
- Japan PMDA Foreign Manufacturer Registration:Streamlined quality management system inspections for foreign shaver and endoscope producers open access to Asia-Pacific's second-largest orthopedic device market.
- 4K-3D visualization convergence:Integration of ultra-high-definition imaging with depth-perception enhancement creates differentiated positioning for next-generation arthroscopy towers.
Industry Challenges
- Surgeon training infrastructure scaling:Cadaveric lab capacity constraints and proctorship availability limit safe adoption velocity for advanced shoulder repair techniques.
- 510(k) predicate device pathway:FDA substantial equivalence determinations for iterative shaver designs face heightened scrutiny, extending premarket notification review timelines.
- Legacy gravity irrigation system compatibility:Ambulatory facilities maintaining mixed pump generations encounter workflow friction and sterilization protocol complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Arthroscopy Instruments Market |
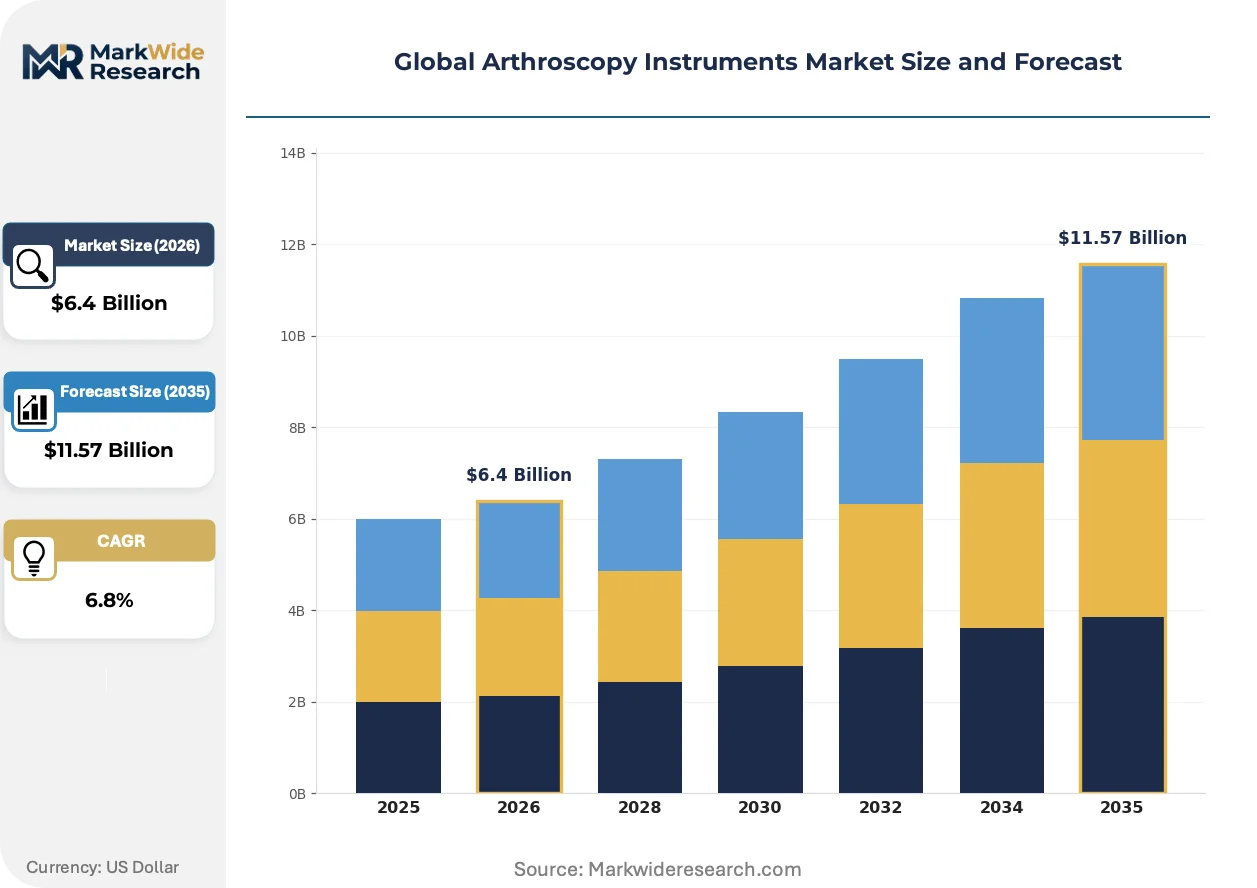
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Shavers, Graspers, Scissors, Punches, Cannulas Technology: Fiber Optic, Video Camera, Fluid Management, Radio Frequency, Laser, Ultrasonic Application: Knee Surgery, Shoulder Repair, Elbow Treatment, Wrist Procedures, Ankle Surgery, Hip Repairs End User: Orthopedic Clinics, Surgical Centers, Ambulatory Care Facilities, Sports Medicine Clinics, Rehabilitation Centers |
| Companies Covered | Johnson & Johnson (DePuy Synthes), Zimmer Biomet, Arthrex, Medtronic, Karl Storz, Smith & Nephew, CONMED Corporation, Richard Wolf, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Arthroscopy Instruments Market Shifts & Advancements
Digital surgical integration and disposable instrument adoption are compressing the traditional reusable equipment lifecycle while elevating real-time data capture requirements for arthroscopy platforms.
Single-use shaver blades and radiofrequency wands are rendering obsolete central sterilization dependencies for high-volume ambulatory centers. Outpatient facilities in the United States are adopting disposable consumables at accelerating rates to reduce turnover time between cases. This shift is compressing per-procedure economics and forcing manufacturers to balance recurring revenue models against environmental waste regulations.
The EU Medical Device Regulation's Unique Device Identification mandates are restructuring traceability infrastructure across arthroscope and instrument supply chains. Manufacturers must now embed persistent identifiers on Class IIa and IIb devices, adding compliance cost layers. German and Swiss precision instrument producers are responding by integrating laser-etched UDI carriers directly into stainless steel hand instrument manufacturing workflows.
Surgeon-owned distributorships are losing share to direct hospital contracting as health system consolidation accelerates in the United States. Integrated delivery networks are centralizing arthroscopy tower procurement through value analysis committees, unbundling traditional rep-surgeon relationships. This concentration is most visible in the Southeast and Midwest regions where hospital merger activity has compressed vendor access points.
Global Arthroscopy Instruments Market Segmentation
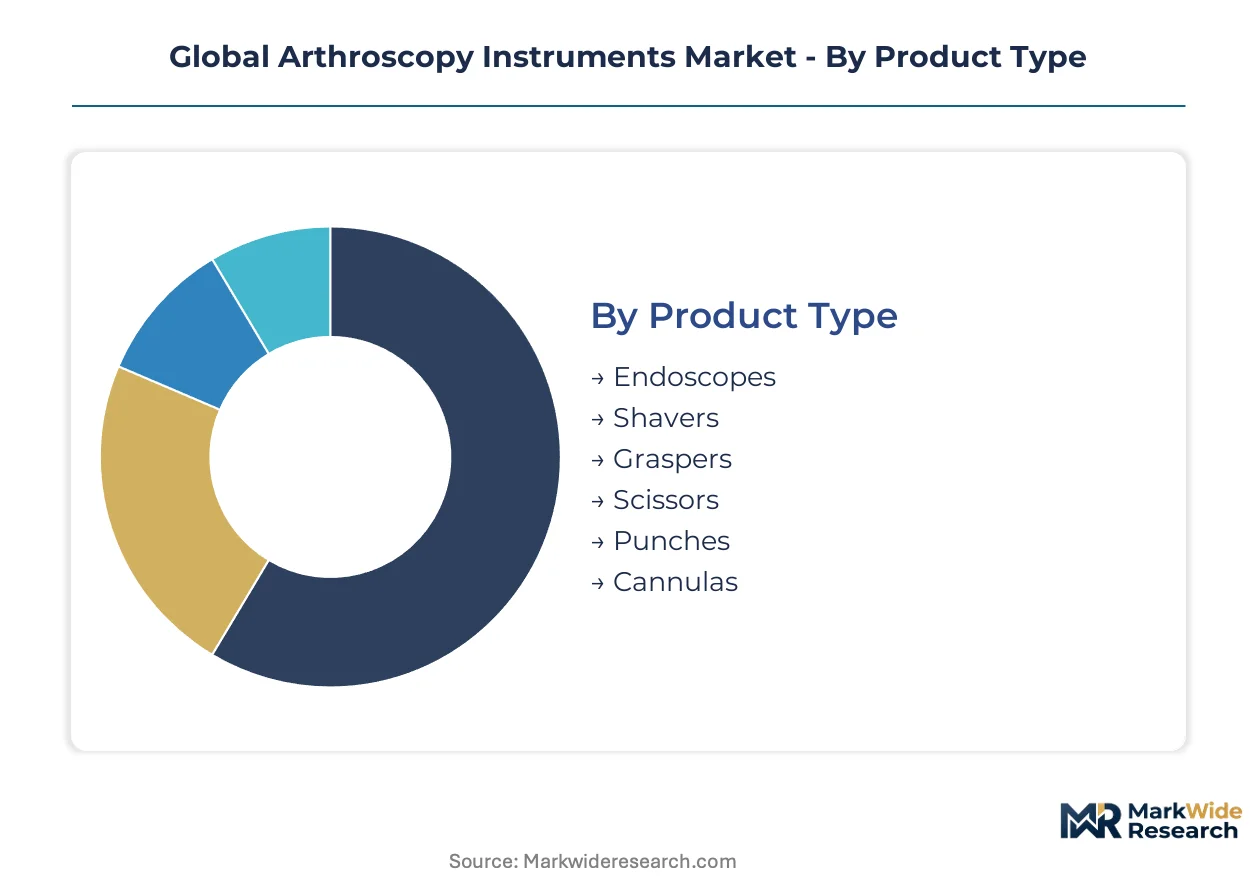
Arthroscopy instrument segmentation reveals distinct procurement patterns across product maturity levels. Technology lifecycle positioning and clinical application specificity determine margin architecture and replacement cadence for manufacturers.
Product Type:
Mature mechanical instruments coexist with digitally integrated shaver systems across the product spectrum.
- Endoscopes:Rigid rod-lens arthroscopes with 4 mm outer diameter and 0-degree to 70-degree viewing angles anchor diagnostic visualization. German precision optics clusters in Tuttlingen supply high-definition lens assemblies to facilities prioritizing tissue discrimination clarity.
- Shavers:Motorized resection systems with reciprocating blades and integrated suction channels enable synovial debridement. Recurring blade replacement generates consumable revenue streams for ambulatory surgical centers performing high knee arthroscopy volumes.
- Graspers:Ratcheted tissue retrieval instruments with fenestrated jaws.
- Scissors:Curved and straight blade configurations for meniscal trimming.
- Punches:Oval and round biting profiles for osteophyte removal.
- Cannulas:Portal maintenance sleeves with instrument interchangeability.
Shavers retain volume leadership; endoscopes hold the steepest expansion curve through 4K-3D visualization convergence.
Technology:
Cost tier stratification separates capital-intensive visualization platforms from disposable energy delivery systems.
- Video Camera:4K and 8K CMOS sensor heads with autoclavable sterilization ratings command premium positioning. United States health system consolidation drives integrated tower procurement through centralized value analysis committees.
- Radio Frequency:Bipolar energy platforms with proprietary wand geometries enable hemostatic soft-tissue ablation. Shoulder repair applications in Germany absorb premium pricing for advanced thermal modulation capabilities.
- Fiber Optic:Illumination transmission bundles for legacy scope compatibility.
- Fluid Management:Pressure-controlled pump systems displacing gravity-dependent irrigation.
- Laser:Holmium and thulium wavelength platforms for cartilage sculpting.
- Ultrasonic:Piezoelectric handpieces for bone cutting with thermal sparing.
Video camera systems dominate capital expenditure allocation; radio frequency platforms are expanding most quickly through consumable attachment rates.
Application:
Procedure volume concentration varies sharply by joint complexity and technique standardization.
- Knee Surgery:Meniscectomy and anterior cruciate ligament reconstruction constitute the foundational arthroscopy volume base. United States ambulatory surgical centers prioritize knee service line expansion under payor pressure for lower-cost settings.
- Shoulder Repair:Rotator cuff fixation and labral reconstruction demand specialized instrument arrays with extended operative duration. German orthopedic clinics absorb premium pricing for advanced radiofrequency ablation systems in soft-tissue stabilization.
- Elbow Treatment:Ulnar collateral ligament evaluation and loose body retrieval.
- Wrist Procedures:Triangular fibrocartilage complex repair and synovectomy.
- Ankle Surgery:Osteochondral lesion debridement and impingement resection.
- Hip Repairs:Femoroacetabular impingement correction with traction table requirements.
Knee surgery retains volume leadership; hip repairs are gaining share fastest as technique standardization improves.
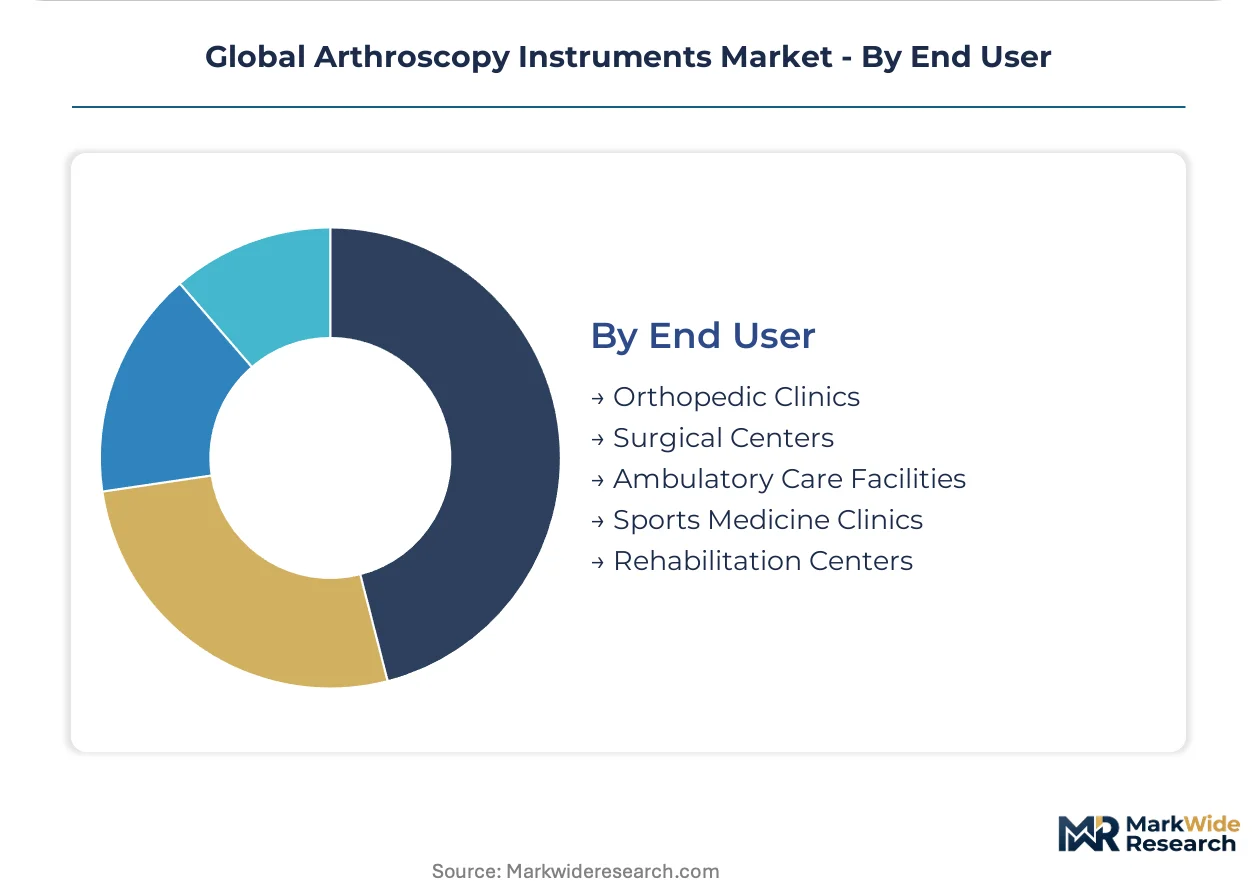
End User:
Customer type determines procurement authority structure and equipment financing preferences.
- Surgical Centers:Ambulatory facilities with dedicated orthopedic service lines drive shaver blade consumable velocity. Pay-per-procedure financing models reduce upfront capital barriers for tower acquisition in the United States.
- Orthopedic Clinics:Specialist-owned practices with diagnostic arthroscopy capabilities anchor endoscope replacement cycles. Japan's PMDA Foreign Manufacturer Registration requirements shape supplier qualification timelines for these facilities.
- Ambulatory Care Facilities:Multi-specialty settings with intermittent arthroscopy utilization.
- Sports Medicine Clinics:Athlete-focused practices with seasonal procedure concentration.
- Rehabilitation Centers:Postoperative monitoring sites with limited therapeutic intervention scope.
Surgical centers retain volume leadership; orthopedic clinics hold the steepest expansion curve through diagnostic service line addition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payor pressure for lower-cost surgical settings is accelerating ambulatory migration across developed markets. Germany's precision optics clusters anchor European supply chains. Japan's regulatory streamlining opens Asia-Pacific access for foreign manufacturers.
United States
Ambulatory surgical centers are expanding arthroscopy service lines as commercial payors and Medicare Advantage plans steer procedures away from hospital outpatient departments. The FDA's 510(k) clearance pathway for shavers and visualization systems shapes product development timelines for domestic launches. Integrated delivery networks in the Southeast and Midwest are centralizing procurement through value analysis committees.
Germany
Orthopedic clinics absorb premium pricing for advanced radiofrequency ablation systems in soft-tissue shoulder repair applications. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIb instruments entering European markets through notified bodies. Precision endoscope manufacturing clusters in Tuttlingen and Knittlingen supply high-definition lens assemblies to facilities prioritizing tissue discrimination clarity.
Japan
Foreign manufacturers are accessing Asia-Pacific's second-largest orthopedic device market through streamlined PMDA Foreign Manufacturer Registration quality management system inspections. METI industrial policy supports domestic production capacity for minimally invasive surgical instruments. Tokyo and Osaka metropolitan areas concentrate demand for diagnostic arthroscopy capabilities in specialist-owned practices.
Switzerland
Swissmedic maintains distinct quality management system oversight for precision instrument producers targeting premium market segments. The country's medical device sector benefits from proximity to German supply chains while maintaining regulatory autonomy. Precision instrument producers are integrating laser-etched UDI carriers directly into stainless steel hand instrument manufacturing workflows.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks is creating dual compliance obligations for manufacturers serving both markets. The MHRA operates transitional arrangements for CE-marked devices while developing domestic UKCA requirements. London and Southeast England health systems are consolidating orthopedic service lines under integrated care board structures.
Global Arthroscopy Instruments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. The vendor base separates into three tiers: integrated orthopedic conglomerates with broad portfolio bundling, visualization and instrument pure-plays with surgeon training infrastructure, and regional precision manufacturers with optical component captive production. Dominant competitive moves include portfolio diversification spanning implants and instruments, and backward integration into rod-lens supply chains.
Among integrated orthopedic conglomerates, Johnson & Johnson (DePuy Synthes) and Zimmer Biomet occupy positions defined by broad portfolio bundling across implants and instruments. Within the visualization pure-play tier, Karl Storz exemplifies German precision manufacturing concentration. These anchors represent distinct strategic archetypes: the diversified health conglomerate leveraging cross-selling economics, and the family-owned optical specialist maintaining surgeon loyalty through training infrastructure investment.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet |
| Arthrex |
| Medtronic |
| Karl Storz |
| Smith & Nephew |
| CONMED Corporation |
| Richard Wolf |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on German precision optics clusters in Tuttlingen and Knittlingen determines both pricing tier spreads and supply chain configuration for arthroscope manufacturers. This geographic concentration creates asymmetric pricing power for rod-lens suppliers while forcing downstream buyers into long-term offtake commitments to secure allocation.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked under MDR) creates the primary spread between premium visualization towers and standard instrument sets. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and training infrastructure access. Cost compression in the economy tier is intensifying because ambulatory surgical centers are consolidating procurement through value analysis committees. Hospital purchasing committees exhibit highest price sensitivity; specialist-owned orthopedic clinics absorb premium positioning for advanced radiofrequency platforms.
Supply Chain Analysis
Optical glass feedstock draws from German and Swiss precision manufacturing clusters before rod-lens assembly. Stainless steel instrument blanks source from Italian and Spanish forgers; CMOS sensor fabrication rests on Taiwanese and South Korean semiconductor foundries. Single-source vulnerability concentrates in the Tuttlingen endoscope manufacturing corridor where Karl Storz and Richard Wolf anchor captive production. Distribution runs through surgeon-owned distributorships losing share to direct hospital contracting as United States health system consolidation accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arthroscopy instruments market is exiting a regulatory-driven investment trough as EU MDR implementation bottlenecks clear and notified body capacity stabilizes. This cyclical recovery phase favors incumbents with established CE-mark portfolios and entrants with streamlined quality management systems.
For Market Incumbents: Pre-empt disposable instrument commoditization by deepening backward integration into rod-lens supply chains. Lock in ambulatory surgical center loyalty through expanded cadaveric training infrastructure before proctorship scarcity limits adoption velocity for advanced shoulder repair techniques. Defend against integrated delivery network procurement concentration by unbundling tower components for selective replacement cycles.
For New Entrants and Emerging Players: Pursue hip arthroscopy instrument arrays as the most penetrable segment where femoroacetabular impingement technique standardization is improving but established vendor relationships remain thin. Target Japan's PMDA Foreign Manufacturer Registration pathway as a streamlined entry mechanism into Asia-Pacific's second-largest orthopedic device market. Anchor go-to-market strategy on pay-per-procedure financing models that reduce upfront capital barriers for ambulatory facilities.
For Investors and Strategic Acquirers: EU MDR notified body capacity stabilization reshapes the acquisition landscape toward manufacturers with cleared Class IIb portfolios and established European distribution. Mid-cap visualization pure-plays with surgeon training infrastructure represent the optimal target archetype for platform expansion. Monitor CE-mark approval velocity at BSI and TÜV SÜD as the critical inflection signal for competitive entry sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Notified body relationships determine European market access timelines for visualization systems. |
| Surgeon Training Infrastructure | Cadaveric lab capacity builds preference stickiness for advanced shoulder repair platforms. |
| Backward Integration into Optics | Rod-lens captive production insulates margin from German supply chain concentration risk. |
| Pay-per-Procedure Financing | Equipment leasing models unlock ambulatory surgical center expansion under payor cost pressure. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement authority in Southeast and Midwest regions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body registration databases, hospital procurement records, and CMS Medicare procedure volume data. Bottom-up instrument shipment modeling triangulated against top-down healthcare expenditure analysis across the projection horizon.
Forecast inputs span product type segmentation by technology lifecycle maturity, application concentration across knee and shoulder procedures, and end-user procurement authority structure distinguishing ambulatory surgical centers from hospital outpatient departments. CAGRs derived from procedure volume elasticity modeling and equipment replacement cycle analysis incorporate 4K-3D visualization convergence adoption curves and disposable instrument penetration rates.
Sensitivities concentrate around notified body capacity constraints extending CE-mark timelines, single-source optical component supply disruption, and ambulatory migration velocity under commercial payor steerage. Cross-checking against hospital capital expenditure surveys and orthopedic device trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Needle Holders Market