
 Spinal Implants and Surgical Devices Market | 2026-2036
Spinal Implants and Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Implants and Surgical Devices Market Outlook
Ambulatory surgical centers is collapsing the historical hospital-centric procurement model for spinal implants. Medtronic leverages its navigated robotics portfolio to sustain premium positioning in minimally invasive spine surgery. DePuy Synthes anchors its competitive stance through broad pedicle screw and interbody cage portfolios with deep hospital GPO relationships. Globus Medical differentiates via vertically integrated manufacturing of PEEK and titanium implants with proprietary imaging integration.
Spinal implants and surgical devices comprise metallic, polymeric, and composite constructs designed for stabilization, fusion, or motion preservation of the vertebral column, typically manufactured through CNC machining, additive manufacturing, or injection molding of biocompatible grades with ASTM F136 titanium or ASTM F2026 PEEK specifications. Their primary commercial purpose is to restore spinal alignment and load-bearing function in degenerative, traumatic, or deformity pathologies. Pedicle screws and interbody cages capture the largest volume pools as mature fusion workhorses with established surgeon training pathways and reimbursement codes. Robotic assistance and navigation systems represent the fastest-expanding technology tier, commanding outsized capital equipment spend and recurring instrument revenue. Titanium and PEEK materials dominate current implantable volumes, though composite materials are penetrating at the premium tier where modulus-matching to bone drives clinical differentiation.
FDA 510(k) premarket notification and EU MDR technical documentation requirements shape product development timelines, clinical evidence burdens, and market access costs for manufacturers seeking US and European commercialization. Japan's PMDA and China's NMPA impose additional localization testing and in-country trial obligations that filter market entrants by capital depth. Stakeholders must monitor reimbursement recalibration for outpatient spine procedures and robotic surgery add-on payments as these directly determine adoption velocity and capital return periods.
Market Dynamics
Ambulatory surgical centers are collapsing the historical hospital-centric procurement model for spinal implants, forcing manufacturers to restructure sales organizations and inventory deployment around decentralized, high-velocity case volumes rather than bulk capital contracts.
Growth Catalysts
- EU MDR recertification timelines:Compressed approval pathways are accelerating competitive product launches across European markets, enabling faster market penetration for compliant device portfolios.
- Titanium additive manufacturing:Powder bed fusion and directed energy deposition processes are reducing lead times for patient-specific interbody cages and enabling lot-size-one production economics.
- Aging demographics in Japan:PMDA reimbursement density for motion-preservation devices aligns with expanding elderly populations requiring cervical and lumbar interventions.
Market Restraints
- PEEK raw material concentration:Virgin polymer supply chains concentrate among a limited set of European and US chemical suppliers, exposing implant manufacturers to input cost volatility and allocation risk.
- FDA 510(k) clinical evidence burdens:Substantial equivalence demonstrations for predicate devices now require expanded biomechanical testing and retrieval data, extending development timelines.
- Non-fusion motion preservation:Artificial disc replacement and dynamic stabilization systems threaten traditional fusion hardware volumes in younger patient cohorts with single-level pathologies.
Strategic Opportunities
- China NMPA localization mandates:In-country trial obligations and manufacturing joint venture requirements create structural barriers that reward early entrants with sustained market access.
- Robotic-navigation convergence:Integration of optical tracking with preoperative planning software enables real-time screw trajectory optimization and expands addressable case complexity.
- Direct-to-ASC distribution:Bypassing hospital GPO contracts through specialized implant consignment models captures higher margins on high-volume outpatient lumbar fusions.
Industry Challenges
- Stereotactic navigation training gaps:Surgeon proficiency in robotic-assisted pedicle screw placement requires extended proctoring programs that constrain capital equipment utilization rates.
- EU MDR technical documentation:Legacy product portfolios face costly clinical evaluation report updates and notified body re-audits that strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Implants and Surgical Devices Market |
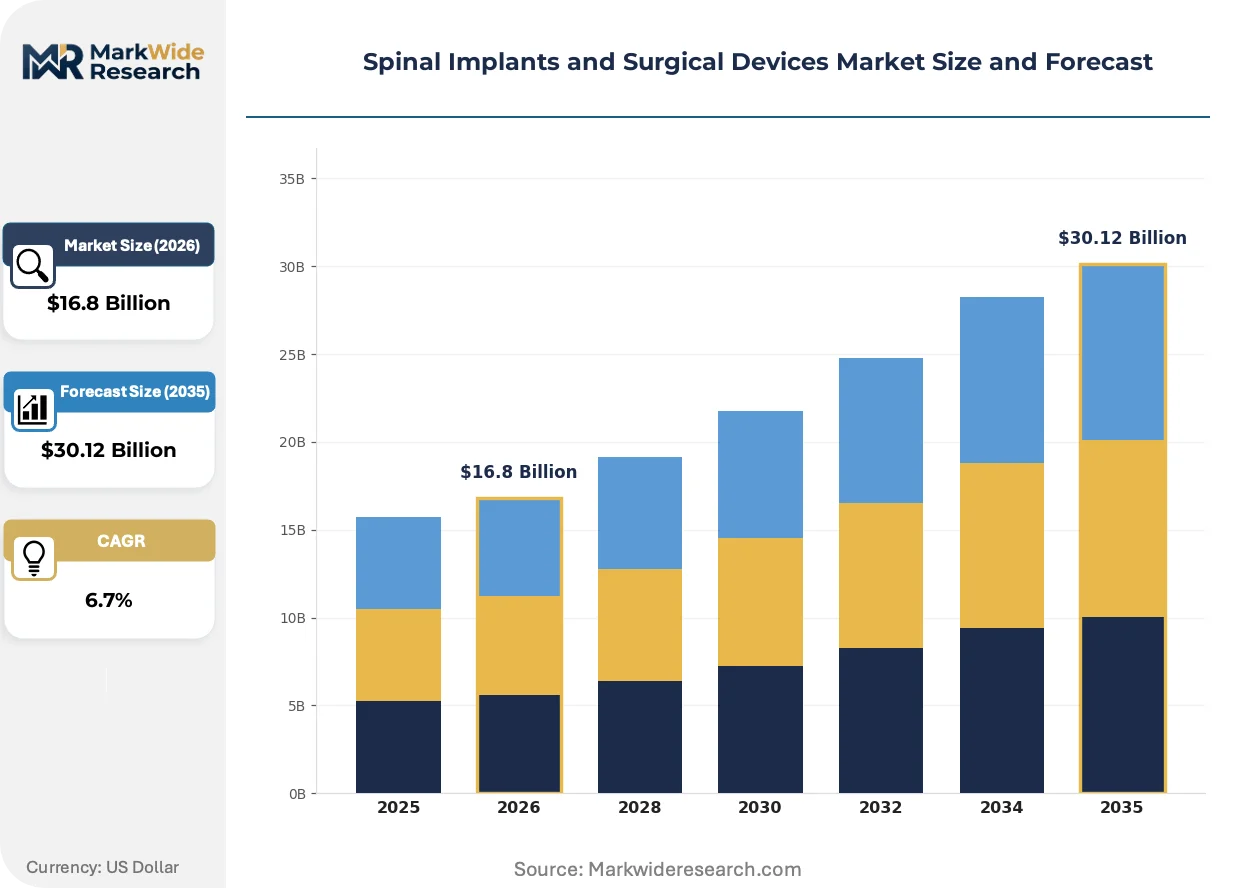
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $30.12 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedicle Screws, Interbody Cages, Rods, Plates End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Material: Titanium, PEEK, Stainless Steel, Composite Materials Technology: Minimally Invasive Surgery, Robotic Assistance, Navigation Systems, Imaging Techniques |
| Companies Covered | Medtronic, DePuy Synthes, Stryker Corporation, Zimmer Biomet, Globus Medical, NuVasive, Orthofix Holdings, Alphatec Spine, RTI Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Implants and Surgical Devices Market Strategic Shifts
Spinal implant markets are experiencing simultaneous technology substitution, regulatory recalibration, and channel restructuring that reward integrated capability stacks over point-product positioning.
Additive-manufactured titanium lattice structures with engineered porosity gradients are supplanting solid machined cages in complex deformity and revision cases. Academic medical centers in Germany and the United States are adopting these constructs at accelerating rates for long-segment fusions requiring osteointegration performance. This substitution is compressing differentiation windows for conventional machined titanium and forcing portfolio rationalization among mid-tier suppliers.
EU MDR technical documentation requirements now mandate systematic post-market clinical follow-up and periodic safety update reports for all implantable spinal devices. Manufacturers must maintain active implant registries and retrieval analysis programs that were previously voluntary. Class III devices with higher risk profiles face disproportionate notified body scrutiny, driving consolidation of regulatory affairs functions among larger portfolio holders.
Hospital purchasing committees are fragmenting decision authority between spine service line chiefs, value analysis teams, and supply chain directors, complicating traditional surgeon-vendor relationships. Ambulatory surgical centers are consolidating vendor lists to three or fewer implant suppliers per procedure category to streamline consignment logistics. This concentration is most visible in Florida and Texas markets where ASC joint ventures between physician groups and private equity sponsors dominate outpatient spine volume growth.
Spinal Implants and Surgical Devices Market Segmentation
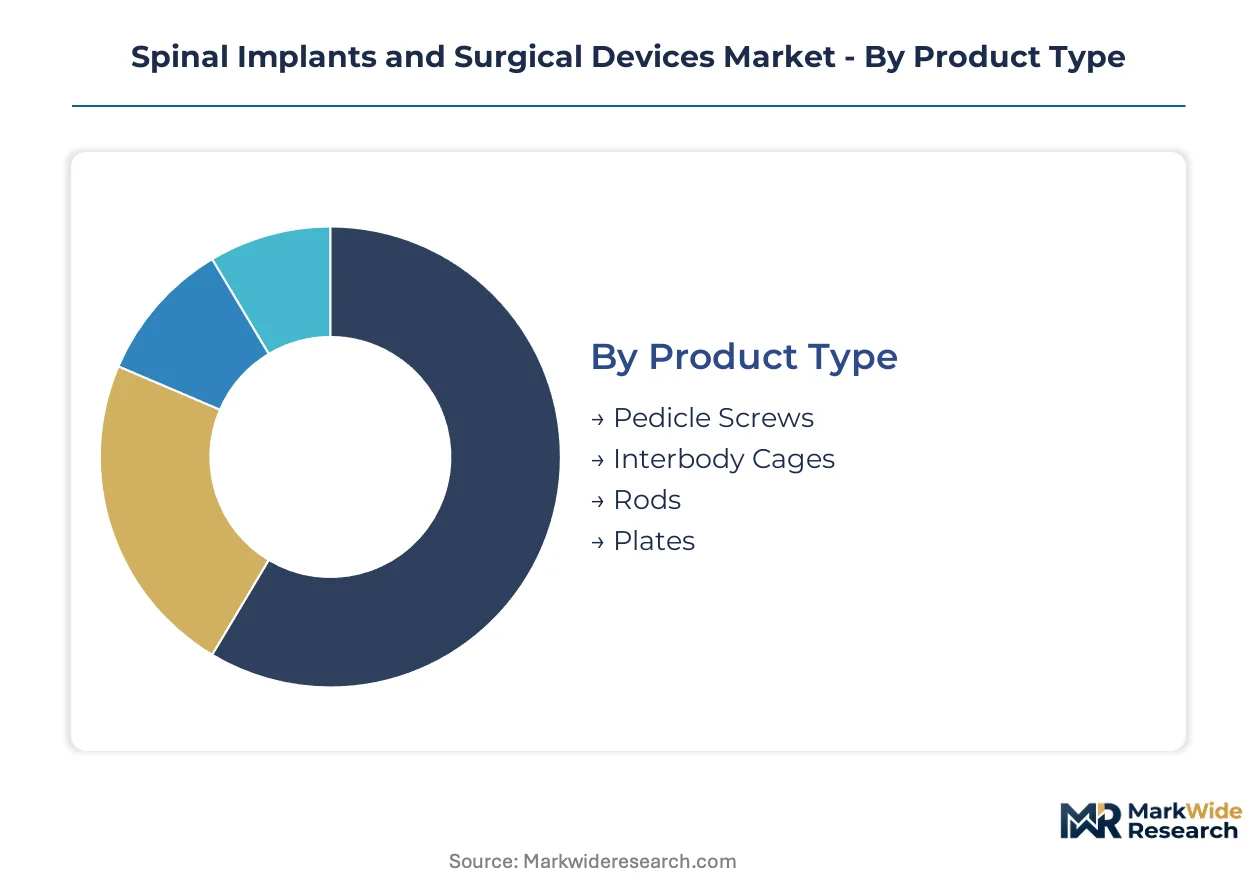
Segmentation in spinal implants reveals how regulatory pathways, material specifications, and site-of-care economics partition commercial opportunity. Manufacturers must align portfolio depth against reimbursement density and surgeon training infrastructure.
Product Type:
FDA 510(k) clearance density varies sharply by construct complexity, with predicate-rich categories accelerating faster through regulatory review than novel geometries.
- Pedicle Screws:Threaded titanium constructs with polyaxial heads and modular extensions anchor posterior fixation constructs. Demand concentrates in United States academic medical centers where deformity correction volumes and GPO contract density align. FDA maintains extensive predicate libraries for standard screw designs, compressing development timelines relative to novel interbody geometries.
- Interbody Cages:Hollow rectangular or lordotic devices manufactured via CNC machining or powder bed fusion from ASTM F136 titanium or ASTM F2026 PEEK. German spine centers drive adoption of additive-manufactured lattice variants with engineered porosity gradients for osteointegration performance.
- Rods:Longitudinal titanium or cobalt-chrome members spanning multiple vertebral levels. Japan PMDA reimbursement codes favor pre-contoured anatomical designs over straight stock in cervical applications.
- Plates:Anterior cervical and thoracolumbar fixation plates with locking screw mechanisms. Smaller addressable volume than screws or cages, concentrated in trauma and deformity subsets.
Pedicle screws handle the majority of throughput; interbody cages are expanding most quickly on share as additive manufacturing enables patient-specific geometries.
End User:
Procurement authority is fragmenting as site-of-care migration restructures inventory deployment and consignment economics.
- Hospitals:Integrated delivery networks with value analysis committees and GPO-negotiated contracts dominate complex deformity and revision cases. United States hospital purchasing committees now require health economic evidence for robotic capital equipment.
- Surgical Centers:Ambulatory facilities in Florida and Texas are consolidating vendor lists to three suppliers per category, forcing manufacturers to restructure sales organizations around high-velocity case volumes.
- Orthopedic Clinics:Physician-owned settings with limited in-house surgical capacity, primarily referring to affiliated hospitals or ASCs for operative intervention.
- Rehabilitation Facilities:Post-acute settings managing non-operative spinal care, minimal direct implant procurement authority.
Hospitals retain the steepest contract values; surgical centers are climbing the fastest as outpatient lumbar fusion reimbursement expands.
Material:
Supply concentration and modulus-matching requirements partition pricing tiers and clinical indication access.
- Titanium:ASTM F136 wrought or additive-manufactured grade with elastic modulus approximately 110 GPa. United States and German academic centers favor titanium lattice cages for long-segment fusions requiring radiographic fusion assessment.
- PEEK:Polyetheretherketone per ASTM F2026 with modulus approximating cortical bone. Virgin polymer supply concentrates among limited European and US chemical suppliers, exposing manufacturers to allocation risk.
- Stainless Steel:316L grade with higher modulus than bone, declining share in implantables but persisting in temporary external fixation.
- Composite Materials:Carbon fiber-reinforced PEEK and polymer-ceramic hybrids commanding premium positioning where modulus-matching and radiolucency drive clinical differentiation.
Titanium commands the deepest volume penetration; composite materials are gaining share fastest at the premium tier.
Technology:
Capital equipment intensity and recurring revenue models separate technology tiers by payback period and surgeon training burden.
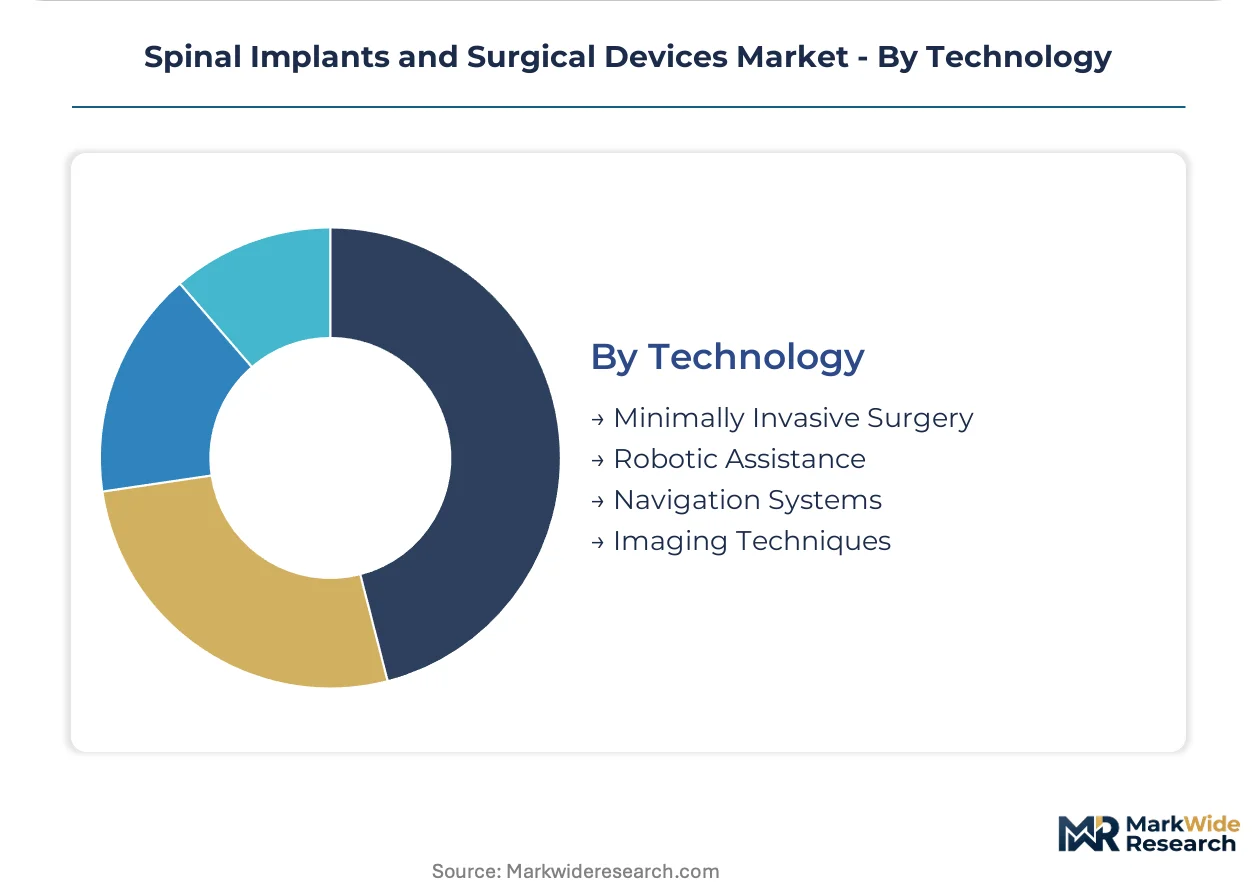
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reducing soft tissue disruption. Mature training pathways and established reimbursement support broad adoption across United States community hospitals.
- Robotic Assistance:Optical tracking with preoperative planning software enabling real-time screw trajectory optimization. Medtronic's navigated robotics portfolio commands premium positioning as capital equipment utilization rates constrain adoption velocity.
- Navigation Systems:Fluoroscopy-based or electromagnetic tracking for instrument guidance. Stereotactic navigation training gaps require extended proctoring programs that limit deployment speed.
- Imaging Techniques:Intraoperative CT and 3D fluoroscopy integration with implant placement verification. EU MDR technical documentation mandates systematic post-market follow-up for imaging-linked devices.
Minimally invasive surgery carries the broadest installed base; robotic assistance is expanding most quickly on capital spend intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for spinal implant manufacturers serving continental markets.
United States
Academic medical centers in the Northeast Corridor drive complex deformity procedure volumes with established GPO contract density. FDA 510(k) predicate libraries compress development timelines for standard pedicle screw designs. The Texas Medical Center in Houston anchors outpatient lumbar fusion expansion as ASC joint ventures proliferate across the state.
Germany
Additive-manufactured titanium lattice cages command premium positioning in long-segment fusion cases requiring osteointegration performance. EU MDR technical documentation mandates systematic post-market clinical follow-up through notified body re-audits. The Rhine-Ruhr metropolitan region concentrates spine center density with university hospital networks adopting robotic navigation systems.
Japan
Aging demographics expand cervical and lumbar intervention volumes among elderly populations requiring motion-preservation alternatives. PMDA reimbursement density favors pre-contoured anatomical rod designs over straight stock in spinal applications. The Keihin industrial corridor spanning Tokyo and Yokohama hosts manufacturing joint ventures serving domestic implant demand.
China
NMPA localization mandates require in-country trials and manufacturing partnerships that filter market entrants by capital depth. The Yangtze River Delta medical device cluster in Shanghai and Suzhou concentrates domestic production capacity for titanium and PEEK constructs. Provincial reimbursement expansion for minimally invasive spine procedures accelerates adoption velocity in tertiary hospitals.
Spinal Implants and Surgical Devices Market Competitive Environment
Listed leaders compete with private specialists across capital equipment intensity and regulatory bandwidth dimensions. The vendor base fragments across three capability tiers: diversified orthopedic conglomerates with navigated robotics portfolios, mid-tier suppliers with vertically integrated manufacturing, and regional specialists with narrow geographic focus. Consolidation pressures intensify as EU MDR compliance costs and robotic R&D requirements favor scale. Dominant competitive moves include strategic partnerships for additive manufacturing capacity and geographic expansion through distribution joint ventures in Asia-Pacific markets.
Within the diversified conglomerate tier, Medtronic and Stryker Corporation exemplify scale-driven positioning through broad implant portfolios and capital equipment integration. DePuy Synthes anchors the hospital GPO relationship archetype with deep contracting infrastructure. Among mid-tier specialists, Globus Medical and NuVasive occupy positions emphasizing manufacturing integration and procedural technology convergence respectively.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| Orthofix Holdings |
| Alphatec Spine |
| RTI Surgical |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) predicate device libraries and EU MDR technical documentation requirements simultaneously gate supplier qualification and stratify implant pricing across certification tiers, compressing margin capture for manufacturers lacking regulatory bandwidth while rewarding compliant portfolios with premium positioning in hospital GPO negotiations.
Pricing Analysis
Volume-discount tiering structures dominate hospital GPO contracting, with three-tier pricing separating robotic-navigation bundles from standard pedicle screw systems and economy interbody cages. Price differentiation rests on FDA clearance tier and surgeon training infrastructure, with academic medical centers showing lowest price sensitivity for capital equipment and ambulatory surgical centers driving hardest bargains on high-volume lumbar fusion sets. Pricing pressure stems from ASC vendor list consolidation to three suppliers per category, forcing mid-tier manufacturers toward cost compression in standard screw and cage portfolios.
Supply Chain Analysis
Just-in-time consignment models prevail in ambulatory surgical centers, while hospital systems maintain strategic stockpiles of revision hardware for complex deformity cases. Geographic supply concentration centers on Germany for additive-manufactured titanium lattice structures, the United States for PEEK polymer compounding, and China for machined cobalt-chrome rods. Raw material dependencies include ASTM F136 titanium bar stock, virgin PEEK resin from European chemical suppliers, and surgical-grade cobalt-chrome alloy. Single-source vulnerability in PEEK polymer allocation exposes manufacturers to input cost volatility. Distribution runs through specialized implant distributors with surgeon-proctoring capabilities and direct-to-ASC consignment logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal implant market tracks a cyclical recovery anchored to EU MDR recertification completion, as notified body re-audits compress competitive supply and restore pricing discipline for compliant device portfolios.
For Market Incumbents: Consolidate regulatory affairs functions to absorb EU MDR clinical evaluation report burdens that strain mid-tier competitors, while deepening backward integration into titanium powder supply for additive manufacturing cost control. Defend against non-fusion motion preservation threats by expanding robotic-navigation bundled pricing that locks hospital capital committees into multi-year contracts.
For New Entrants and Emerging Players: FDA 510(k) predicate pathway fast-tracks market entry for standard pedicle screw designs with established biomechanical testing protocols, offering lower clinical evidence burdens than novel interbody geometries. Target ambulatory surgical center direct distribution in Florida and Texas markets where vendor list consolidation creates openings for specialized consignment models. Pursue additive manufacturing partnerships with German lattice structure specialists as the fastest penetration route in academic deformity centers.
For Investors and Strategic Acquirers: EU MDR recertification completion reshapes the acquisition landscape by eliminating regulatory bandwidth-constrained targets and concentrating viable assets among scale players with notified body relationships. Long-term viability favors manufacturers with integrated robotics portfolios and PEEK polymer supply chain control. Watch PMDA reimbursement recalibration for motion-preservation devices in Japan as the signal indicating cyclical inflection toward premium-tier volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Optimization | Accelerates clearance timelines for standard screw designs against novel geometries. |
| EU MDR Technical Documentation Investment | Preserves European market access as notified body re-audits eliminate non-compliant competitors. |
| Robotic-Navigation Bundle Development | Captures capital equipment spend and recurring instrument revenue from academic medical centers. |
| Additive Manufacturing Capacity Expansion | Enables patient-specific titanium lattice production for complex deformity and revision cases. |
| Direct-to-ASC Distribution Infrastructure | Bypasses hospital GPO contracts to capture higher margins on outpatient lumbar fusions. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and hospital GPO contract filings preceded structured interviews with spine surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, PMDA pricing circulars, and additive manufacturing supplier disclosures. Bottom-up implant volume modeling triangulated against top-down market sizing from regulatory filing analysis.
Variance decomposition across product type, material specification, end-user site-of-care, and technology tier anchored the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by reimbursement code density and surgeon training penetration rates. Forecast inputs included ASC joint venture formation rates in target states and PEEK polymer supplier allocation announcements.
Underlying assumptions cover stable FDA 510(k) predicate library expansion and EU MDR notified body capacity constraints, with deviation risk concentrated in PMDA reimbursement recalibration timing and NMPA localization mandate enforcement intensity. Revision becomes warranted when outpatient spine procedure reimbursement crosses hospital-ASC parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Global Orthopedic Digit Implants Market