
 Minimally Invasive Surgical Instruments Market | 2026-2036
Minimally Invasive Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Surgical Instruments Market Intelligence
Hospital procurement channels are tilting toward bundled contracting models that pair capital equipment with multi-year service agreements. Medtronic leverages its integrated surgical ecosystem to lock in recurring revenue streams across installed bases. Johnson & Johnson sustains competitive pressure through its broad orthopedics-to-surgery portfolio breadth. Intuitive Surgical dominates the robotic-assisted segment with proprietary console-instrument-cartridge architecture that raises switching costs.
Minimally invasive surgical instruments encompass precision-engineered devices designed for insertion through small incisions or natural orifices, typically fabricated from medical-grade stainless steel, titanium alloys, or polymer composites with tolerances measured in micrometers to ensure tissue preservation and operator control. These instruments serve the primary purpose of enabling therapeutic intervention with reduced trauma, shorter recovery intervals, and lower complication rates relative to open surgical approaches. Robotic surgical systems command the highest capital intensity and margin pools as hospitals amortize million-dollar platforms over decade-long depreciation schedules. Laparoscopic tools represent the most mature volume category, while electromechanical and navigation technology integrations are capturing disproportionate R&D allocation as vendors differentiate through digital surgery ecosystems.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for instrument manufacturers seeking dual jurisdiction approval. ISO 13485 quality management certification and IEC 60601 electrical safety standards function as baseline predicates for commercial traction in regulated markets. Stakeholders must monitor how FDA's evolving software-as-a-medical-device guidance and EU AI Act risk classifications will reshape predicate logic for next-generation intelligent instruments.
Market Dynamics
Hospital procurement consolidation and the migration of surgical volumes to outpatient settings are compressing vendor margins while accelerating platform replacement cycles for laparoscopic and robotic systems.
Growth Catalysts
- Ambulatory surgical center expansion:United States outpatient facilities are absorbing complex procedures previously restricted to inpatient settings, expanding addressable volume for disposable instrument kits.
- EU MDR recertification timelines:Compressed approval windows are forcing vendors to accelerate next-generation platform launches, creating replacement demand across European installed bases.
- Navigation and imaging integration:Real-time fluorescence overlay and augmented reality guidance are extending the addressable case mix for minimally invasive approaches into oncologic resections.
Market Restraints
- Capital intensity concentration:Robotic console depreciation absorbs disproportionate hospital capex budgets, squeezing instrument procurement flexibility.
- Supply chain geographic concentration:German and Japanese precision component suppliers dominate high-tolerance electromechanical subassemblies, creating single-source vulnerability.
- Technical limitation in haptic feedback:Current robotic platforms lack force-sensing fidelity for tissue palpation, restricting adoption in specific surgical specialties.
Strategic Opportunities
- Underpenetrated Japanese market:Robotic surgery penetration in Japan lags United States benchmarks by substantial margin, creating expansion runway for platform vendors.
- Regulatory tailwind from FDA software guidance:Evolving SaMD pathways are clarifying predicate logic for AI-enabled instruments, accelerating intelligent device commercialization.
- Convergence of surgical robotics with diagnostic imaging:Intraoperative CT and MRI compatibility is opening intra-hospital placement opportunities beyond traditional operating suites.
Industry Challenges
- Surgeon training pipeline constraints:Robotic credentialing requires substantial proctored case volume, limiting platform expansion speed.
- EU MDR technical documentation burden:Clinical evidence requirements for legacy instrument recertification are consuming regulatory affairs bandwidth.
- Integration complexity with hospital IT infrastructure:Surgical platform connectivity demands are colliding with cybersecurity mandates and legacy system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Surgical Instruments Market |
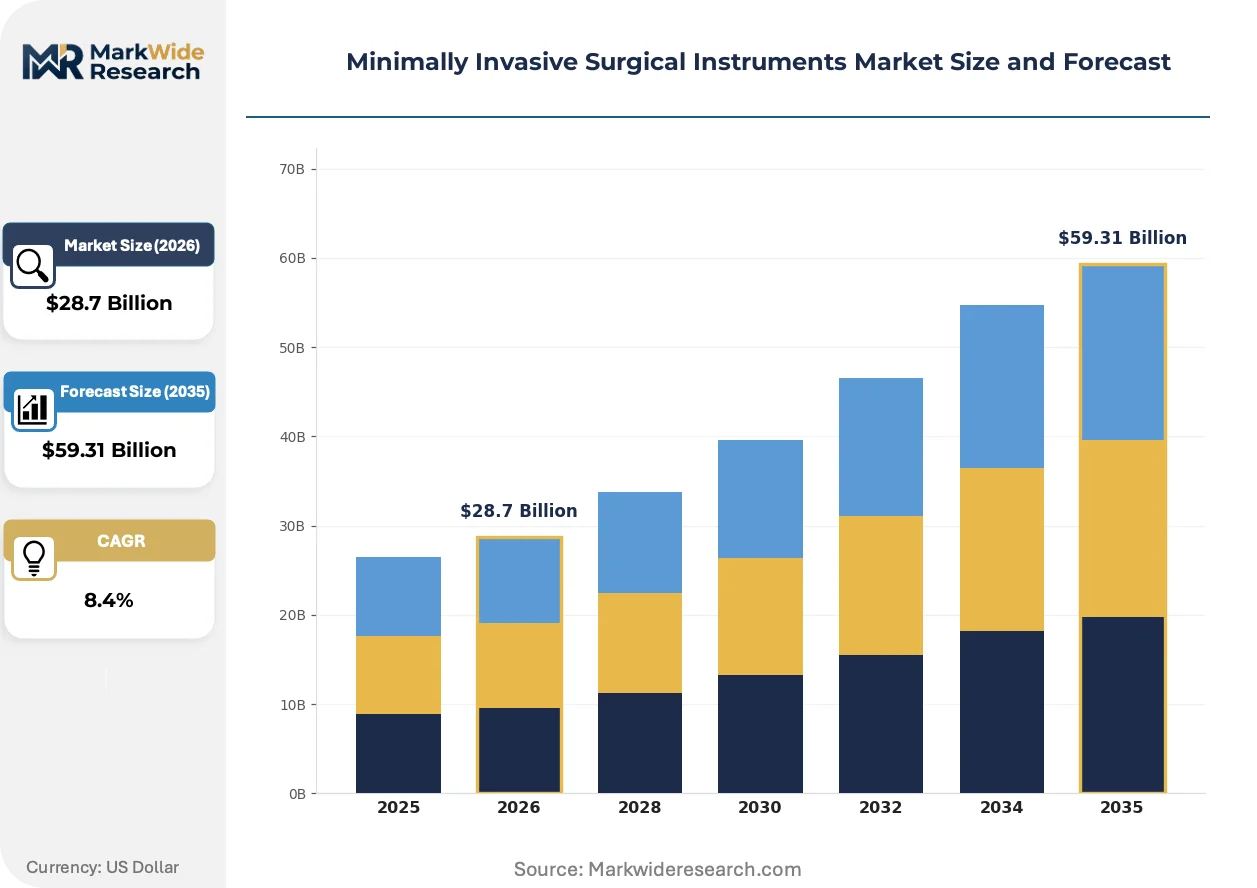
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Instruments, Laparoscopic Tools, Robotic Surgical Systems, Arthroscopic Devices, Micro-Instruments Technology: Electromechanical, Fiber Optic, Imaging Systems, Ultrasonic, Laser-Assisted, Navigation Application: General Surgery, Gynecological Procedures, Orthopedic Surgeries, Urological Operations, Cardiothoracic Interventions End User: Specialty Clinics, Ambulatory Surgical Centers, Academic Medical Facilities, Outpatient Clinics, Diagnostic Centers |
| Companies Covered | Medtronic, Johnson & Johnson, Intuitive Surgical, Stryker, Boston Scientific Corporation, Abbott Laboratories, Olympus Corporation, Zimmer Biomet, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Surgical Instruments Market Strategic Shifts & Innovations
Digital surgery ecosystems are redefining competitive advantage as vendors bundle hardware, software, and data services into integrated therapeutic platforms that capture procedure economics across the care continuum.
Single-port robotic systems are digitizing abdominal access by consolidating multiple instrument arms through one incision, reducing port-site complications. Academic medical centers in Germany and Japan are piloting these platforms for colorectal and gynecologic procedures. The technology is digitizing surgical workflow by enabling instrument exchange without port re-docking, compressing operative time and platform turnover intervals.
FDA software-as-a-medical-device guidance is reshaping predicate logic for intelligent instruments that incorporate real-time tissue characterization algorithms. Manufacturers must now delineate between hardware and software regulatory pathways, extending development timelines. Electromechanical instrument categories with embedded AI capabilities face the steepest compliance burden as FDA reviewers apply evolving risk classification frameworks.
After-sales service unbundling is disrupting traditional capital equipment contracts as German hospital purchasing cooperatives negotiate instrument-only supply agreements separate from maintenance obligations. Third-party reprocessors are capturing share of disposable instrument replacement cycles. United States ambulatory surgical centers are driving this fragmentation, prioritizing per-procedure cost transparency over bundled long-term commitments.
Minimally Invasive Surgical Instruments Market Segmentation
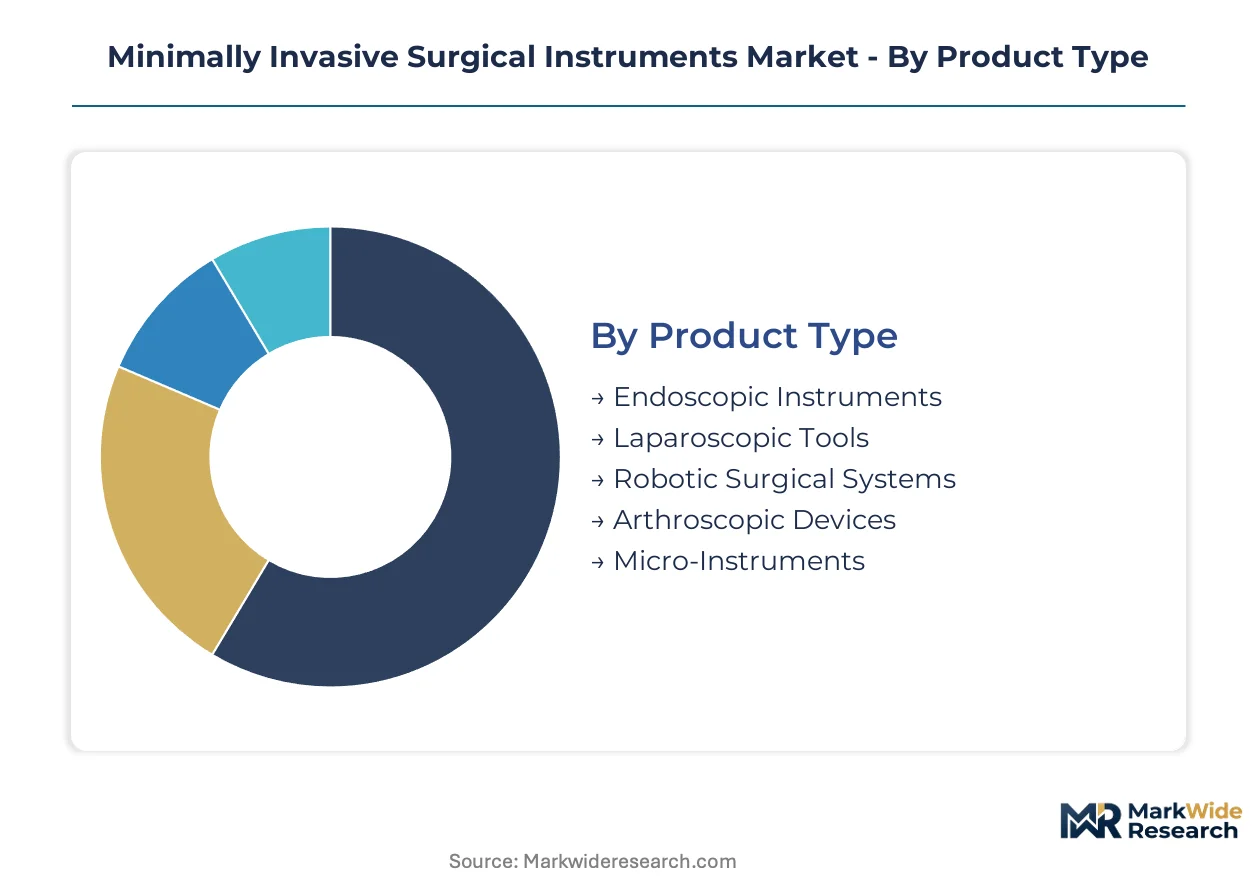
Segmentation in minimally invasive surgical instruments reveals how procurement economics, reimbursement pathways, and clinical workflow requirements reshape vendor priorities across distinct product and customer categories. Each dimension carries implications for after-sales service intensity, capital deployment cycles, and margin sustainability.
Product Type:
After-sales service intensity varies dramatically across product types, with robotic platforms demanding decade-long maintenance contracts while disposable laparoscopic kits generate recurring revenue through procedure volume.
- Robotic Surgical Systems:Million-dollar console platforms integrate proprietary instrument-cartridge architectures with embedded software requiring continuous firmware updates and predictive maintenance protocols. German university hospitals and United States academic medical centers absorb the majority of new system placements as they amortize capital costs across high surgical volumes.
- Laparoscopic Tools:Mature electromechanical instruments—graspers, dissectors, and clip appliers—fabricated from medical-grade stainless steel with micrometer tolerances dominate procedure economics through disposable kit configurations. Ambulatory surgical centers in the United States drive procurement acceleration as outpatient migration compresses replacement cycles.
- Endoscopic Instruments:Flexible insertion tubes with distal tip articulation serve diagnostic and therapeutic gastrointestinal interventions.
- Arthroscopic Devices:Rigid optical systems with irrigation channels target joint space visualization for orthopedic sports medicine.
- Micro-Instruments:Sub-millimeter precision tools address ophthalmic and otologic microsurgical applications requiring extreme tactile sensitivity.
By volume, Laparoscopic Tools leads. By growth pace, Robotic Surgical Systems is ahead.
Technology:
Cost tier stratification separates capital-intensive navigation and imaging platforms from commoditized fiber optic bundles, with electromechanical categories capturing disproportionate R&D allocation.
- Navigation:Real-time electromagnetic tracking and augmented reality overlay systems enable instrument localization relative to preoperative imaging datasets. Japanese academic medical centers pilot intraoperative CT compatibility for oncologic resections, extending addressable case mix beyond traditional operating suites.
- Imaging Systems:Fluorescence-guided visualization platforms integrate near-infrared dye detection with standard laparoscopic optics, permitting real-time tissue perfusion assessment. United States hospital procurement channels bundle these capabilities with capital equipment contracts spanning multi-year service agreements.
- Electromechanical:Motorized articulation and force-feedback mechanisms power next-generation robotic instruments.
- Fiber Optic:Illumination and image transmission through coherent glass bundles remains the baseline for flexible endoscopy.
- Ultrasonic:High-frequency mechanical vibration enables tissue dissection with simultaneous hemostasis.
- Laser-Assisted:Focused energy delivery targets precise tissue ablation in ophthalmic and dermatologic applications.
By installed base, Fiber Optic dominates. By expansion trajectory, Navigation is climbing the fastest.
Application:
Customer type concentration varies by surgical specialty, with general surgery and gynecology anchoring high-volume ambulatory procedures while cardiothoracic interventions remain concentrated in academic tertiary centers.
- General Surgery:Cholecystectomy, hernia repair, and appendectomy procedures constitute the foundational volume driving disposable instrument consumption. United States ambulatory surgical centers absorb these cases as reimbursement migration accelerates outpatient procedural migration.
- Gynecological Procedures:Hysterectomy and myomectomy approaches have shifted decisively toward minimally invasive techniques, with single-port robotic systems gaining traction in German academic medical centers for reduced port-site complications.
- Orthopedic Surgeries:Arthroscopic joint reconstruction and sports medicine interventions target younger patient demographics.
- Urological Operations:Prostatectomy and nephrectomy procedures leverage robotic platforms for deep pelvic access.
- Cardiothoracic Interventions:Valve repair and coronary bypass through thoracoscopic approaches demand specialized instrumentation.
By procedure count, General Surgery leads. By platform premiumization, Cardiothoracic Interventions is gaining share fastest.
End User:
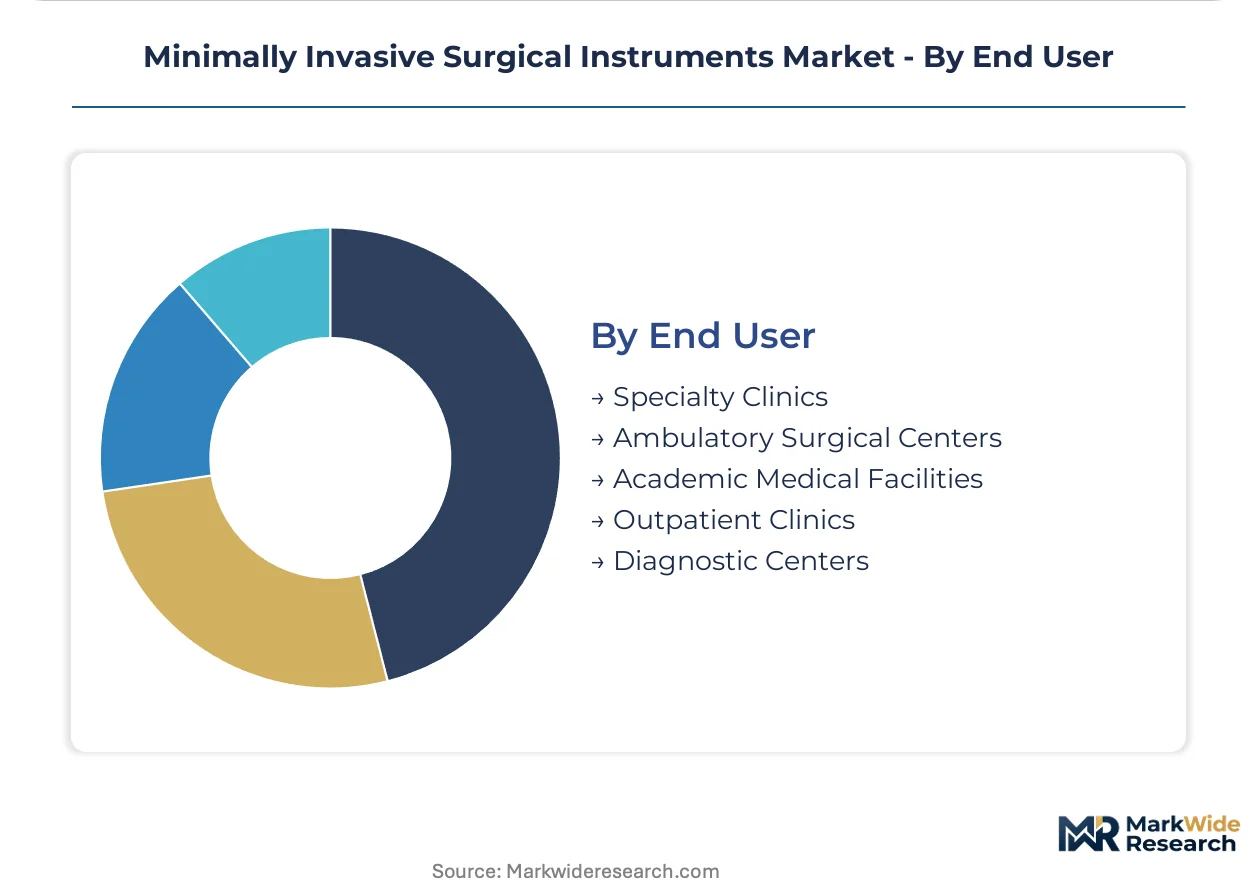
Geography and maturity stratification separates established hospital systems from expanding outpatient networks, with procurement flexibility and capital access determining technology adoption speed.
- Ambulatory Surgical Centers:United States outpatient facilities prioritize per-procedure cost transparency and instrument-only supply agreements separate from maintenance obligations. German hospital purchasing cooperatives are replicating this unbundling model, fragmenting traditional bundled contracting structures.
- Academic Medical Facilities:Teaching hospitals combine high surgical volume with research mandates, driving early adoption of navigation and AI-enabled platforms. FDA software-as-a-medical-device guidance reshapes their procurement evaluation criteria for intelligent instruments.
- Specialty Clinics:Focused ophthalmology and gastroenterology practices concentrate specific procedure types.
- Outpatient Clinics:Lower-acuity settings absorb diagnostic and minor therapeutic interventions.
- Diagnostic Centers:Imaging-focused facilities require endoscopic capabilities for tissue acquisition.
By facility count, Outpatient Clinics leads. By technology upgrade frequency, Ambulatory Surgical Centers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary distribution hub for precision electromechanical subassemblies serving European surgical instrument manufacturers. FDA 510(k) clearance pathways and EU MDR recertification timelines compress product cycles across Atlantic trade routes. Demand concentrates in three metropolitan clusters where academic medical centers anchor high-volume robotic system placements.
United States
Ambulatory surgical centers in Texas and Florida absorb complex procedures previously restricted to inpatient settings, expanding disposable instrument kit demand. FDA software-as-a-medical-device guidance clarifies predicate logic for AI-enabled platforms. The Greater Boston corridor hosts early adopters of navigation-integrated robotic systems for oncologic resections.
Germany
University hospitals in Baden-Württemberg and Bavaria amortize million-dollar robotic consoles across high surgical volumes. EU MDR technical documentation requirements force accelerated next-generation platform launches. The Stuttgart precision engineering cluster supplies electromechanical subassemblies with micrometer tolerances to global instrument manufacturers.
Japan
Academic medical centers in Tokyo and Osaka pilot intraoperative CT-compatible robotic platforms for thoracic procedures. PMDA regulatory frameworks govern software-embedded instrument approvals with risk classification frameworks. The Nagoya manufacturing belt produces high-tolerance titanium alloy components for laparoscopic tool assemblies.
United Kingdom
NHS procurement consolidation drives bundled contracting models pairing capital equipment with multi-year service agreements. MHRA post-Brexit regulatory alignment with EU MDR extends approval timelines for legacy instrument recertification. The Cambridge-Oxford-London triangle concentrates navigation technology R&D for fluorescence-guided visualization platforms.
Switzerland
Swissmedic certification requirements attract premium-tier instrument manufacturers seeking dual EU-Swiss market access. The Basel-Zurich corridor hosts precision polymer composite fabrication for single-port robotic access systems. University Hospital Zurich pilots augmented reality overlay systems for real-time tissue characterization.
Minimally Invasive Surgical Instruments Market Key Industry Players
On the supply side, the industry is consolidating around integrated surgical ecosystems that lock in recurring revenue through proprietary instrument-cartridge architectures. Three strategic archetypes dominate: diversified medical technology conglomerates with orthopedics-to-surgery portfolio breadth, pure-play robotic platform vendors with decade-long maintenance contracts, and precision component specialists supplying electromechanical subassemblies. M&A activity targets navigation and imaging software capabilities, while geographic expansion concentrates on underpenetrated Asian markets.
Among diversified conglomerates, Medtronic and Johnson & Johnson occupy positions spanning capital equipment through disposable consumables. Intuitive Surgical exemplifies the pure-play robotic archetype with console-instrument-cartridge integration that raises customer switching costs. Stryker represents the orthopedic-surgical convergence vector, leveraging sports medicine volume to fund minimally invasive platform development.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Intuitive Surgical |
| Stryker |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Olympus Corporation |
| Zimmer Biomet |
| CONMED Corporation |
| Others |
Cost & Logistics Intelligence
The Stuttgart precision engineering cluster anchors European electromechanical subassembly capacity, with its micrometer-tolerance fabrication constraints translating directly into tiered instrument pricing power for vendors serving German university hospitals and United States academic medical centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with FDA 510(k) clearance tier and ISO 13485 certification grade serving as the primary price differentiation drivers. Cost compression in disposable laparoscopic kits is intensifying because ambulatory surgical centers in Texas and Florida prioritize per-procedure cost transparency over bundled long-term commitments. Academic medical centers demonstrate the least price sensitivity as they amortize million-dollar robotic consoles across high surgical volumes.
Supply Chain Analysis
Export-control restrictions on precision electromechanical components limit flows of high-tolerance servo motors and embedded sensor arrays from German and Japanese suppliers to third-country assemblers. The supply chain draws from titanium alloy feedstock in Japan, medical-grade stainless steel from German mills, and polymer composites from Swiss fabrication facilities. Single-source vulnerability concentrates in Stuttgart and Nagoya manufacturing belts where specialized component suppliers lack qualified alternatives. Distribution runs through hospital purchasing cooperatives and GPO contracts that consolidate procurement across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as console-instrument-cartridge integration raises switching costs and locks in recurring revenue, with FDA software-as-a-medical-device guidance accelerating the shift toward intelligent instrument ecosystems.
For Market Incumbents: Harden proprietary instrument-cartridge architectures against third-party reprocessor encroachment by embedding firmware-dependent authentication protocols. Deepen backward integration into Nagoya titanium alloy component supply to insulate against single-source vulnerability. Prioritize navigation and AI-enabled platform R&D to maintain premium positioning against emerging pure-play robotic vendors.
For New Entrants and Emerging Players: Establish a beachhead in Japanese robotic surgery markets where penetration lags United States benchmarks substantially. Target ambulatory surgical centers in United States outpatient settings with instrument-only supply agreements that bypass bundled maintenance contracts. Pursue EU MDR recertification acceleration services for legacy instrument manufacturers facing compressed approval windows.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors navigation software specialists with fluorescence-guided visualization and augmented reality overlay capabilities. Long-term viability rests on acquisition targets demonstrating intraoperative imaging compatibility and hospital IT infrastructure integration. Watch FDA AI risk classification frameworks as the signal for intelligent instrument commercialization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed EU MDR timelines force parallel regulatory pathways for dual-market access. |
| Hospital System Partnership | Bundled contracting with United States ASC networks locks in disposable kit volume. |
| Navigation Software Acquisition | Real-time fluorescence overlay extends addressable case mix into oncologic resections. |
| CE Marking Pathway Investment | Technical documentation capabilities reduce recertification bandwidth constraints. |
| Software Companion Development | AI-enabled tissue characterization aligns with evolving SaMD predicate logic. |
Research Approach
A spread of perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Bottom-up instrument shipment estimates and top-down capital equipment placement data were triangulated to anchor volume projections.
Demand-supply-balance framing shaped the analytical framework across the projection horizon, with segmentation modeled across product type, technology tier, surgical application, and end-user facility category. CAGRs were derived from procedure volume elasticity to platform placement rates and disposable kit consumption patterns. Forecast inputs incorporated ambulatory surgical center expansion trajectories, EU MDR recertification cycle compression, and navigation technology adoption curves in German and Japanese academic medical centers.
Stress conditions across FDA software guidance evolution, EU AI Act risk classification implementation, and supply chain geographic concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about outpatient migration speed and robotic credentialing pipeline constraints. Material shifts in PMDA regulatory frameworks or intraoperative imaging reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Disposable Laparoscopic Instruments Market