
 Global Bioabsorbable Stents Market | 2026-2036
Global Bioabsorbable Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioabsorbable Stents Market Foresight
Interventional cardiologist training capacity is reorganizing how quickly bioabsorbable platforms penetrate tertiary care networks. Abbott Laboratories leverages its structural heart portfolio to anchor cath-lab loyalty across North American academic medical centers. BIOTRONIK sustains European market presence through dedicated magnesium alloy R&D pipelines. Meril Life Sciences dominates price-sensitive Asian markets with localized manufacturing and distributor depth.
Bioabsorbable stents are implantable scaffolds fabricated from biodegradable polymers or corrodible metals that provide transient luminal support before resorbing completely, with magnesium-based variants degrading through controlled electrochemical corrosion over 9-12 months to restore natural vascular physiology. Poly-L-Lactic Acid platforms lead current revenue due to extensive clinical validation and established reimbursement codes across OECD health systems. Coronary artery disease applications capture the deepest margin pools, while peripheral vascular disease represents the fastest-growing addressable segment as below-the-knee interventions demand temporary scaffolding without permanent metal constraints.
FDA pre-market approval pathways and EU MDR clinical evidence requirements shape product development timelines and commercial access for bioabsorbable platforms in the United States and Europe. Japan's PMDA Sakigake designation system accelerates review for novel biomaterial devices, creating regulatory arbitrage opportunities for firms with concurrent Japan filing strategies. Stakeholders must monitor biomaterial degradation kinetic standardization efforts across FDA, EMA, and PMDA to anticipate harmonized performance benchmarks that will reshape competitive differentiation.
Market Dynamics
The EU MDR's tightened long-term implant surveillance requirements are forcing cath-lab procurement committees to reevaluate permanent metal stent portfolios against bioabsorbable alternatives that eliminate late-stage complication liabilities.
Growth Catalysts
- Polymer degradation kinetics:Poly-L-Lactic Acid platforms now demonstrate predictable 24-month resorption timelines that satisfy Japan's PMDA Sakigake evidentiary thresholds for accelerated approval pathways.
- Below-the-knee interventions:Peripheral vascular disease applications are expanding as interventional radiologists seek temporary scaffolding for tibial lesions where permanent metal constrains future revascularization options.
- Magnesium alloy electrochemistry:Controlled corrosion rates of 9-12 months restore natural vascular physiology without chronic inflammation, aligning with Germany's cardiology clinic preferences for physiological restoration over permanent implantation.
Market Restraints
- Biomaterial input concentration:High-purity lactic acid monomer supply concentrates among three specialty chemical producers in Switzerland and Germany, creating price volatility exposure for stent manufacturers.
- EU MDR clinical evidence burdens:Post-market surveillance requirements for absorbable implants demand 10-year patient follow-up registries that extend commercial payback periods beyond traditional device financing models.
- Drug-eluting metal stent substitution:Thin-strut cobalt-chromium platforms with biodegradable polymer coatings offer comparable restenosis rates at 40% lower procedure costs in price-sensitive hospital systems.
Strategic Opportunities
- India's tertiary cardiac centers:CDSCO's streamlined medical device registration for absorbable implants creates first-mover advantages for firms establishing local distributor networks before domestic manufacturing scales.
- Pediatric congenital heart defect repair:Bioabsorbable pulmonary artery stents address vessel growth accommodation without repeat interventions, an application absent from current commercial portfolios.
- Outcome-based cath-lab contracting:Medicare's transitional coverage for emerging technologies enables risk-sharing arrangements where hospital reimbursement ties to 12-month target lesion revascularization rates.
Industry Challenges
- Interventional cardiologist retraining:Deployment technique modifications for absorbable scaffolds require 40-60 supervised cases before proficiency certification, constraining adoption velocity in community hospital settings.
- ISO 10993 biocompatibility testing timelines:Degradation product toxicology studies add 18-24 months to preclinical development schedules compared to permanent metal stent equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioabsorbable Stents Market |
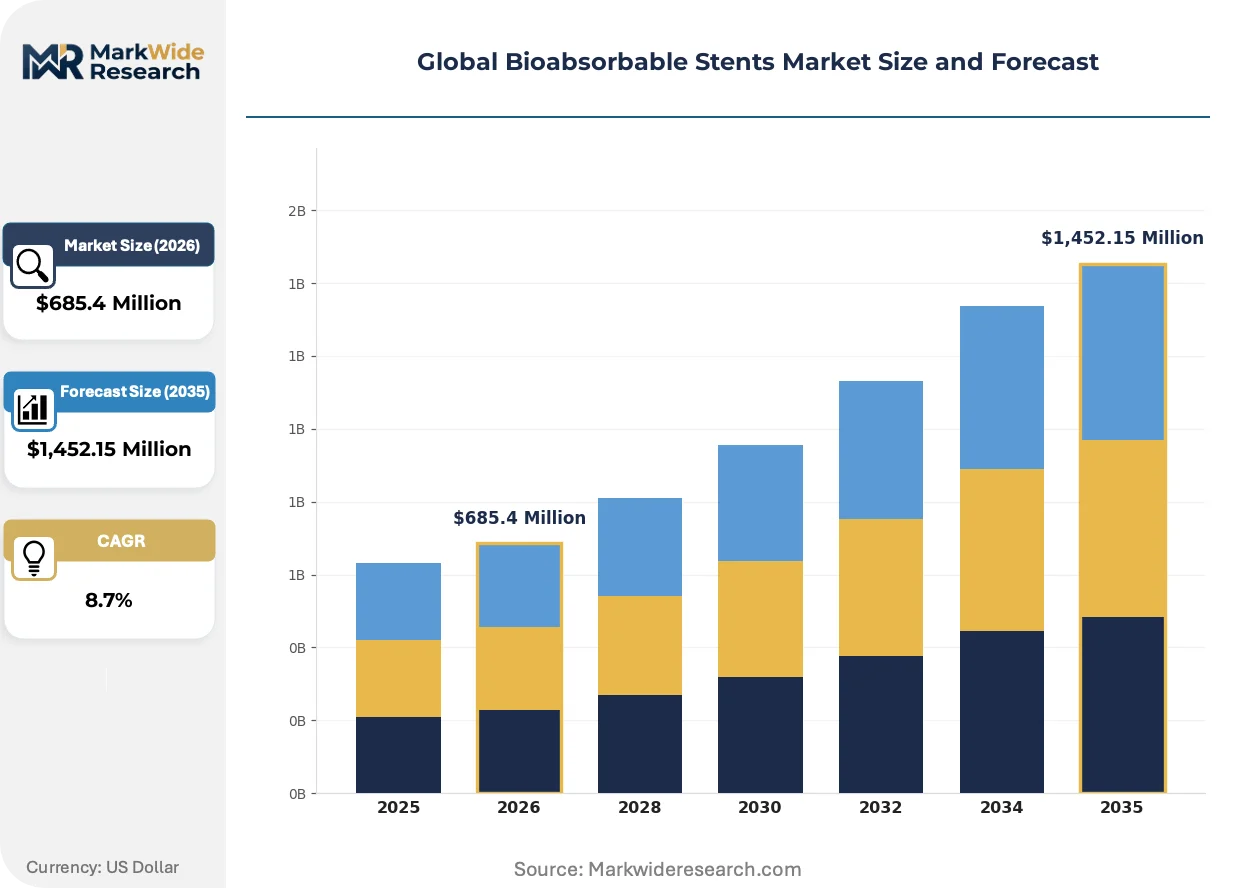
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poly-L-Lactic Acid, Magnesium-Based, Iron-Based, Polymer Composite Application: Coronary Artery Disease, Peripheral Vascular Disease, Neurovascular Interventions, Urological Procedures End User: Cardiology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Research Institutes Deployment: Balloon-Expandable, Self-Expandable, Drug-Eluting, Bare Metal |
| Companies Covered | Abbott Laboratories, BIOTRONIK, REVA Medical, Elixir Medical Corporation, Arterius Ltd., Kyoto Medical Planning Co., Ltd., MicroPort Scientific Corporation, Boston Scientific Corporation, Meril Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioabsorbable Stents Market Shifts & Advancements
Biomaterial degradation kinetics standardization is compressing competitive differentiation around predictable resorption timelines rather than acute mechanical performance metrics alone.
Magnesium-rare earth alloy formulations are fragmenting the absorbable metal segment as BIOTRONIK and academic consortia optimize corrosion rate control through yttrium and neodymium micro-additions. German cardiology clinics are piloting these platforms for bifurcation lesions where polymer flexibility constraints limit deliverability. The technology is fragmenting established competitive positions by rewarding electrochemical engineering capabilities over traditional polymer processing expertise.
The FDA's 2023 guidance on absorbable coronary scaffold pivotal trial design is mandating larger primary endpoint event counts and extended angiographic follow-up compared to metal stent benchmarks. This regulatory recalibration is extending development timelines and favoring firms with existing structural heart trial infrastructure. Coronary applications face the steepest evidentiary escalation while peripheral indications maintain relatively streamlined pathways.
Hospital value analysis committees are consolidating purchasing authority for absorbable devices into centralized cardiovascular service line contracts rather than physician-directed preference items. This procurement consolidation is displacing traditional distributor relationships with direct manufacturer agreements in US academic medical centers. The shift is most pronounced in California and Texas health systems where cath-lab consolidation has created super-regional purchasing entities.
Global Bioabsorbable Stents Market Segmentation
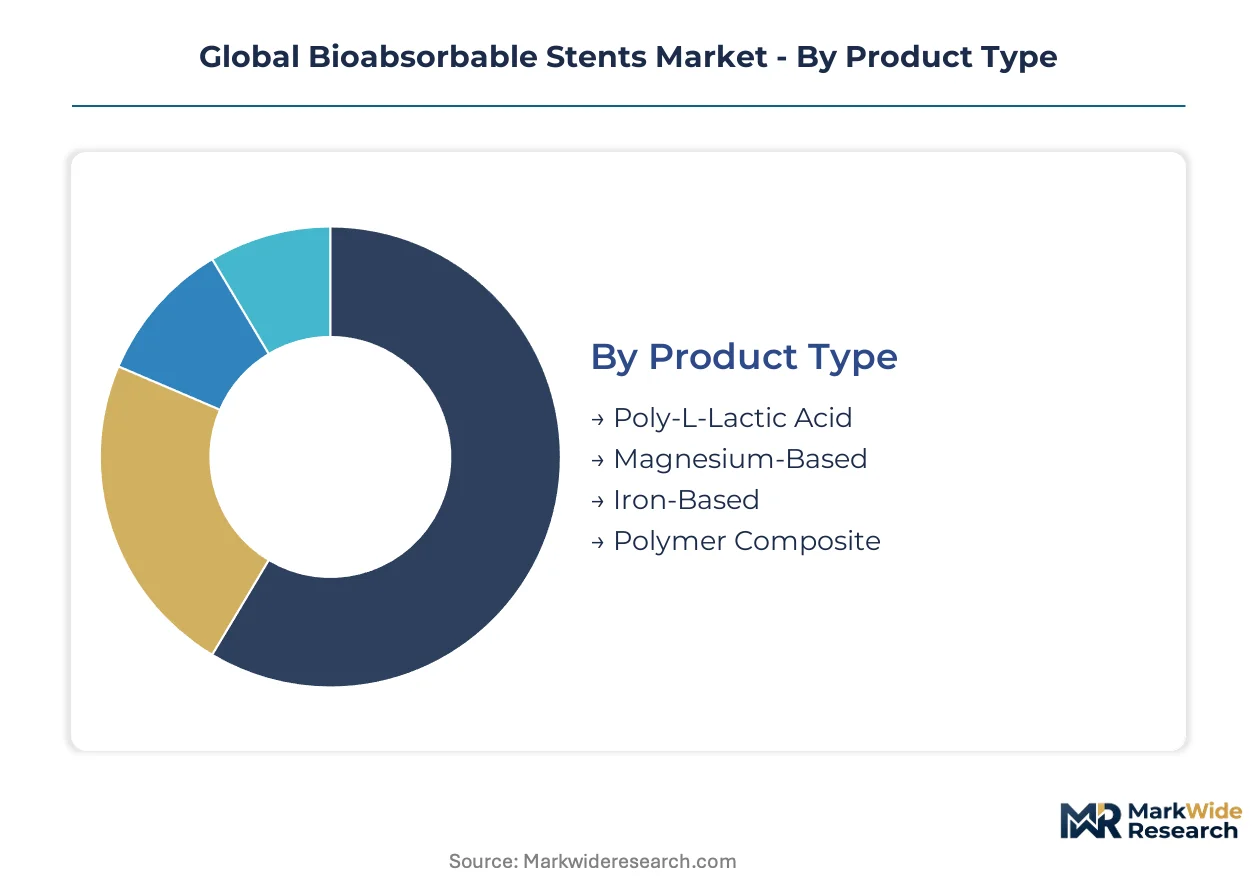
Bioabsorbable stent segmentation reflects divergent regulatory pathways across FDA, EMA, and PMDA jurisdictions, with biomaterial classification determining clinical evidence requirements and reimbursement eligibility. Manufacturers align product portfolios to specific degradation kinetic profiles that match regional evidentiary thresholds.
Product Type:
FDA pre-market approval timelines vary substantially across polymer and metallic absorbable platforms, with corrosion rate predictability serving as the primary regulatory gating factor.
- Poly-L-Lactic Acid:Semicrystalline polymer scaffolds degrade through hydrolysis into lactic acid metabolites over 24-36 months. Germany's cardiology clinics favor these platforms for bifurcation lesions where controlled mechanical support duration aligns with vessel remodeling physiology.
- Magnesium-Based:Electrochemically active alloys corrode through surface oxidation to yield magnesium hydroxide and hydrogen gas, with rare earth micro-additions modulating degradation rates between 9-12 months. Japan's PMDA Sakigake designation accelerates review for these platforms when corrosion kinetics demonstrate standard deviation below 15%.
- Iron-Based:Ferrous alloys degrade through electrochemical reduction to ferrous hydroxide, offering superior radial strength but slower resorption timelines extending 18-24 months.
- Polymer Composite:Blended matrices incorporating polyglycolic acid or polycaprolactone modify degradation rates and mechanical compliance for niche anatomical applications.
Established volume favors Poly-L-Lactic Acid; emerging adoption favors Magnesium-Based.
Application:
Procedure reimbursement codes and target lesion revascularization benchmarks segment demand across anatomical territories with distinct clinical outcome expectations.
- Coronary Artery Disease:Transient scaffolding of epicardial vessels requires platforms demonstrating non-inferiority to drug-eluting metal stents in 12-month late lumen loss. US academic medical centers concentrate procurement through cardiovascular service line contracts that bundle absorbable scaffolds with structural heart programs.
- Peripheral Vascular Disease:Below-the-knee tibial interventions demand temporary support without permanent metal constraints that complicate future bypass grafting. Interventional radiologists in India's tertiary cardiac centers are piloting these applications where amputation avoidance drives value-based reimbursement.
- Neurovascular Interventions:Intracranial aneurysm neck bridging and intracranial atherosclerotic disease applications require ultra-thin strut profiles and rapid endothelialization.
- Urological Procedures:Ureteral stricture management and prostatic obstruction represent emerging applications with limited commercial product availability.
Coronary applications dominate current revenue; peripheral indications are expanding most quickly.
End User:
Cath-lab infrastructure investment and interventionalist training capacity determine adoption velocity across facility types with divergent case volume thresholds.
- Cardiology Clinics:Germany's outpatient interventional facilities are expanding magnesium-based platform adoption as EU MDR post-market surveillance requirements elevate preference for implants without late-stage complication liabilities.
- Specialty Hospitals:High-volume cardiac centers in Japan leverage METI-backed biomaterial innovation grants to establish first-mover positions in next-generation absorbable platforms.
- Ambulatory Surgical Centers:Freestanding facilities concentrate on peripheral vascular procedures with shorter recovery protocols and lower capital equipment requirements.
- Research Institutes:Academic medical centers in the United States manage FDA-mandated extended follow-up registries that generate long-term degradation kinetic datasets.
Specialty hospitals capture premium pricing; ambulatory surgical centers are gaining share fastest.
Deployment:
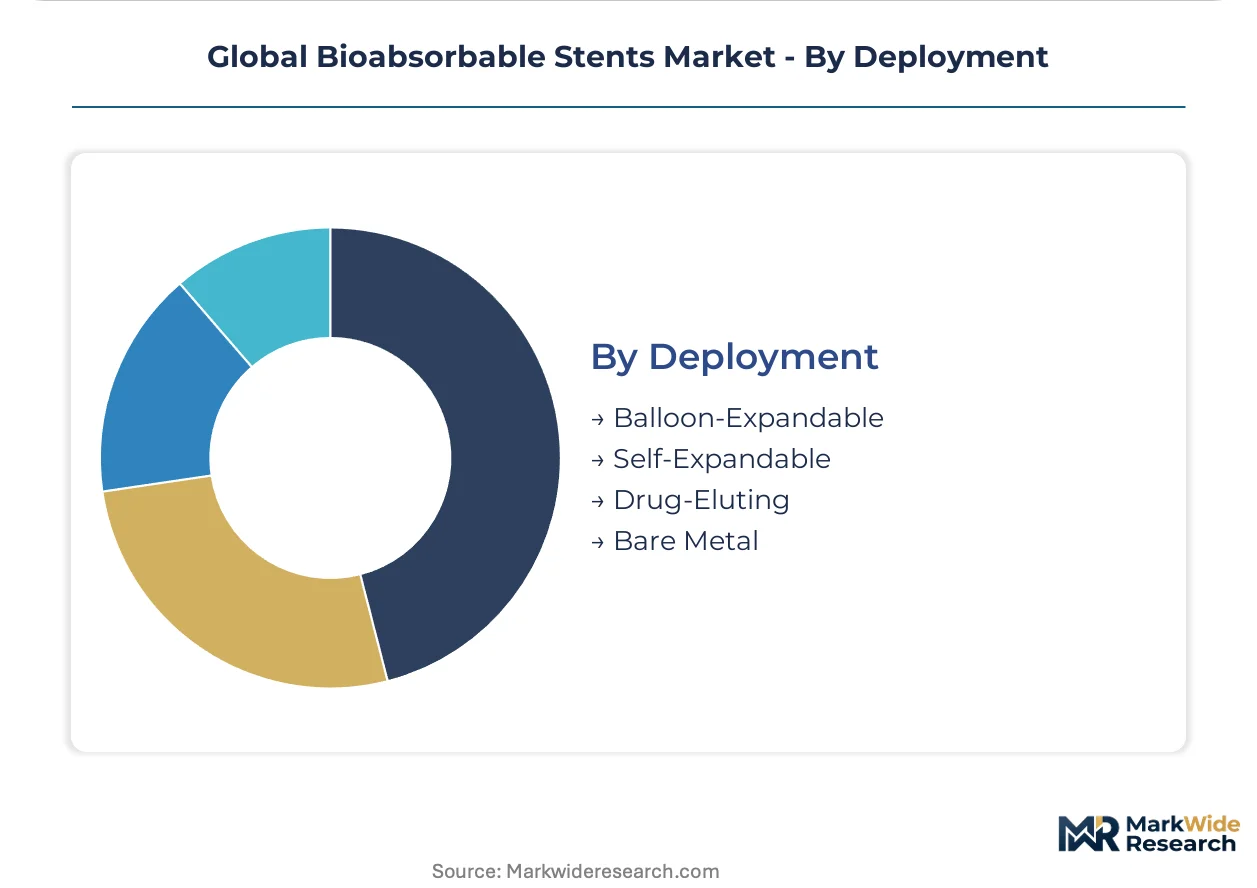
Delivery system engineering and drug integration strategies segment competitive positioning across mechanical expansion modalities.
- Balloon-Expandable:Predilatation-dependent deployment systems deliver precise sizing for coronary applications where acute recoil resistance determines procedural success.
- Self-Expandable:Nitinol constraint sleeves enable deployment in tortuous peripheral anatomy where balloon inflation risks vessel dissection.
- Drug-Eluting:Sirolimus or everolimus coatings suppress neointimal proliferation during the critical 3-6 month endothelialization window.
- Bare Metal:Unmodified absorbable scaffolds serve research applications and cost-sensitive markets where polymer coating adds manufacturing complexity.
Drug-eluting platforms command margin premiums; self-expandable configurations show steepest expansion trajectory in peripheral indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pre-market approval pathways anchor North American market access while Japan's PMDA Sakigake designation and Germany's EU MDR compliance frameworks shape adoption trajectories in their respective markets.
United States
Academic medical centers in California and Texas drive demand through cardiovascular service line consolidation. FDA's 2023 absorbable scaffold trial guidance mandates extended angiographic follow-up, favoring firms with existing structural heart infrastructure. The Cleveland Clinic and Mayo Clinic anchor multi-site registry networks generating long-term degradation kinetic datasets.
Germany
Outpatient cardiology clinics in Bavaria and North Rhine-Westphalia expand magnesium-based platform adoption. EU MDR post-market surveillance requirements elevate preference for implants without late-stage complication liabilities. Berlin's Charité hospital network pilots rare earth alloy formulations for bifurcation lesions.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas accelerate clinical uptake of absorbable platforms. METI-backed biomaterial innovation grants enable first-mover positioning in next-generation scaffolds. Nagoya's medical device cluster concentrates PMDA Sakigake designation applications for corrosion-controlled magnesium variants.
India
Tertiary cardiac centers in Maharashtra and Karnataka pilot below-the-knee peripheral interventions. CDSCO's streamlined medical device registration for absorbable implants creates first-mover advantages for distributor network establishment. Delhi-NCR hospitals drive value-based reimbursement models around amputation avoidance.
Switzerland
Specialty chemical producers in Basel concentrate high-purity lactic acid monomer supply for Poly-L-Lactic Acid platforms. Swissmedic's alignment with EU MDR clinical evidence requirements shapes regional manufacturing quality standards. Zurich's precision polymer processing cluster serves as a critical input node for stent manufacturers.
Global Bioabsorbable Stents Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the bioabsorbable stents market. Abbott Laboratories and Boston Scientific Corporation leverage structural heart portfolios to anchor cath-lab loyalty, while BIOTRONIK and Meril Life Sciences occupy differentiated positions through material science specialization. Competitive moves concentrate on portfolio diversification into peripheral vascular applications and strategic partnerships with academic medical centers for extended follow-up registry generation.
Among North American integrated leaders, Abbott Laboratories and Boston Scientific Corporation exemplify the cath-lab loyalty archetype through cardiovascular service line bundling. BIOTRONIK represents the European electrochemical engineering specialist tier with its magnesium alloy focus. Meril Life Sciences occupies the price-sensitive market anchor position across Asian geographies through localized manufacturing scale.
| Leading Market Players |
|---|
| Abbott Laboratories |
| BIOTRONIK |
| REVA Medical |
| Elixir Medical Corporation |
| Arterius Ltd. |
| Kyoto Medical Planning Co., Ltd. |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Meril Life Sciences |
| Others |
Supply & Pricing Matrix
Magnesium-rare earth alloy formulations displacing polymer platforms in German bifurcation applications simultaneously concentrate electrochemical expertise in Bavaria and fragment pricing power away from established polymer processors toward specialized metallurgical suppliers. This substitution dynamic compresses margins for Poly-L-Lactic Acid manufacturers while rewarding alloy innovators with premium positioning in EU MDR-compliant procurement channels.
Pricing Analysis
Long-term offtake agreements with Swiss and German specialty chemical producers anchor Poly-L-Lactic Acid platform economics, while spot purchasing dominates magnesium alloy inputs where rare earth micro-addition formulations command project-based premiums. Price differentiation rests on corrosion rate predictability certification and PMDA Sakigake designation status. Pricing pressure stems from thin-strut cobalt-chromium drug-eluting metal stents offering comparable restenosis rates at lower procedure costs. Price-sensitive hospital systems in India and Southeast Asia resist premium absorbable scaffolds, while Japanese academic medical centers accept premium tiers for physiological restoration benefits.
Supply Chain Analysis
Switzerland and Germany concentrate high-purity lactic acid monomer production for Poly-L-Lactic Acid platforms, while China and Japan anchor magnesium alloy smelting and rare earth micro-addition processing. Raw material dependencies center on pharmaceutical-grade lactic acid, high-purity magnesium ingots, and yttrium-neodymium rare earth elements. Single-source vulnerability concentrates in Swiss-German monomer supply where three producers control specialty chemical output. Distribution runs through cardiology clinic procurement committees in Germany, GPO contracts in US academic medical centers, and localized distributor networks in Asian price-sensitive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
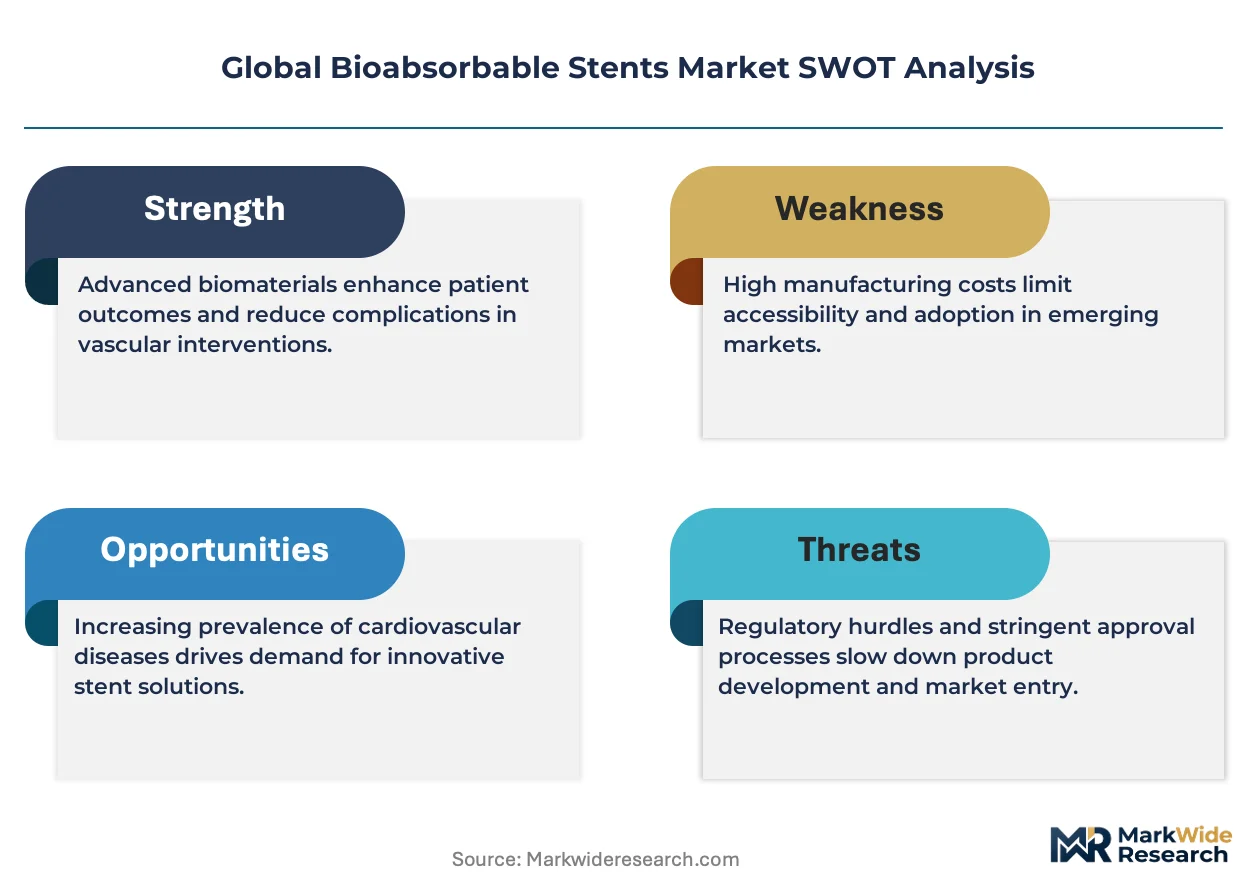
Incumbents face sustained substitution pressure from thin-strut drug-eluting metal stents with biodegradable polymer coatings that match absorbable scaffold efficacy at lower cost points, requiring defensive portfolio repositioning around physiological restoration narratives and EU MDR compliance advantages.
For Market Incumbents: Fortify cath-lab loyalty through cardiovascular service line bundling that absorbs extended follow-up registry costs into structural heart program economics. Secure backward integration into high-purity lactic acid monomer supply through captive agreements with Swiss-German specialty chemical producers. Defend against magnesium alloy substitution by accelerating Poly-L-Lactic Acid degradation kinetic standardization through FDA-EMA-PMDA harmonization initiatives. For New Entrants and Emerging Players: Pediatric congenital heart defect repair represents an underserved service layer where vessel growth accommodation creates first-mover advantages absent from current commercial portfolios. Below-the-knee peripheral vascular interventions in India's tertiary cardiac centers offer penetrable entry points through CDSCO's streamlined absorbable implant registration. Establish outcome-based cath-lab contracting capabilities aligned with Medicare's transitional coverage for emerging technologies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrochemical engineering specialists possessing magnesium-rare earth alloy corrosion control IP and established PMDA Sakigake filing track records. Long-term viability across the analysis window hinges on biomaterial degradation kinetic standardization convergence across FDA, EMA, and PMDA jurisdictions. Monitor ISO 10993 biocompatibility testing timeline compression as inflection signal for preclinical development cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Designation Pathway | Accelerated Japanese review rewards corrosion rate predictability below 15% standard deviation. |
| EU MDR Post-Market Surveillance Compliance | Ten-year patient follow-up registries satisfy tightened long-term implant surveillance requirements. |
| Hospital System Partnership | Cardiovascular service line consolidation in California and Texas displaces traditional distributor relationships. |
| Biomaterial Innovation Grant Capture | METI-backed funding in Nagoya's medical device cluster enables first-mover positioning. |
| Reimbursement Strategy | Medicare transitional coverage enables risk-sharing tied to target lesion revascularization rates. |
Research Methodology
Operator-level perspectives from interventional cardiologists, cath-lab procurement committee directors, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA PMA filings, PMDA Sakigake designation records, EUDAMED post-market surveillance databases, and hospital procurement contract disclosures. Bottom-up procedure volume modeling and top-down market sizing triangulated across OECD health system expenditure data and manufacturer revenue disclosures.
Sensitivity analysis tested degradation kinetic assumptions, regulatory pathway timelines, and substitution elasticity across the projection horizon. Segmentation dimensions modeled include biomaterial classification, anatomical application territory, end-user facility type, and deployment modality. CAGRs derived from procedure volume trajectories weighted by reimbursement code adoption curves and interventionalist training capacity expansion. Forecast inputs incorporated EU MDR clinical evidence burden timelines and PMDA Sakigake review acceleration effects.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA regimes; material policy shifts would require re-modeling. Specific risks include biomaterial input price volatility from Swiss-German monomer supply concentration, ISO 10993 testing timeline extensions, and drug-eluting metal stent efficacy improvements. Recalibration cycles align with material shifts in regulatory harmonization progress, interventionalist certification velocity, and outcome-based contracting adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Spinal Fusion Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Antimicrobial Coated Medical Devices Market