
 Non-Absorbable Sutures Market | 2026-2036
Non-Absorbable Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Absorbable Sutures Market Analytics
Multi-sourced polymer procurement is recalibrating cost structures across the non-absorbable sutures supply base. Johnson & Johnson (Ethicon) leverages captive filament production to shield margin pools from nylon and polypropylene price volatility. Medtronic anchors its position through concentrated R&D spending on high-strength braided configurations for cardiac applications. B. Braun competes via geographic density in European hospital supply chains, where it controls direct distribution to tier-one surgical centers.
Non-absorbable sutures are permanent wound-closure devices manufactured from synthetic polymers or natural silk, engineered to retain tensile strength exceeding 60 days post-implantation with diameters typically ranging from 5-0 to 2 USP gauge. Their primary commercial purpose is to secure tissue apposition in high-tension anatomical sites where prolonged mechanical support outlasts the healing cascade. Polypropylene monofilament dominates cardiovascular and ophthalmic applications due to minimal tissue reactivity and smooth passage through fascia. Polyester braided configurations capture premium positioning in orthopedic repairs where knot security and handling precision command superior pricing. Silk multifilament occupies mature demand niches in dental procedures and ligature applications where absorbable alternatives lack sufficient initial strength.
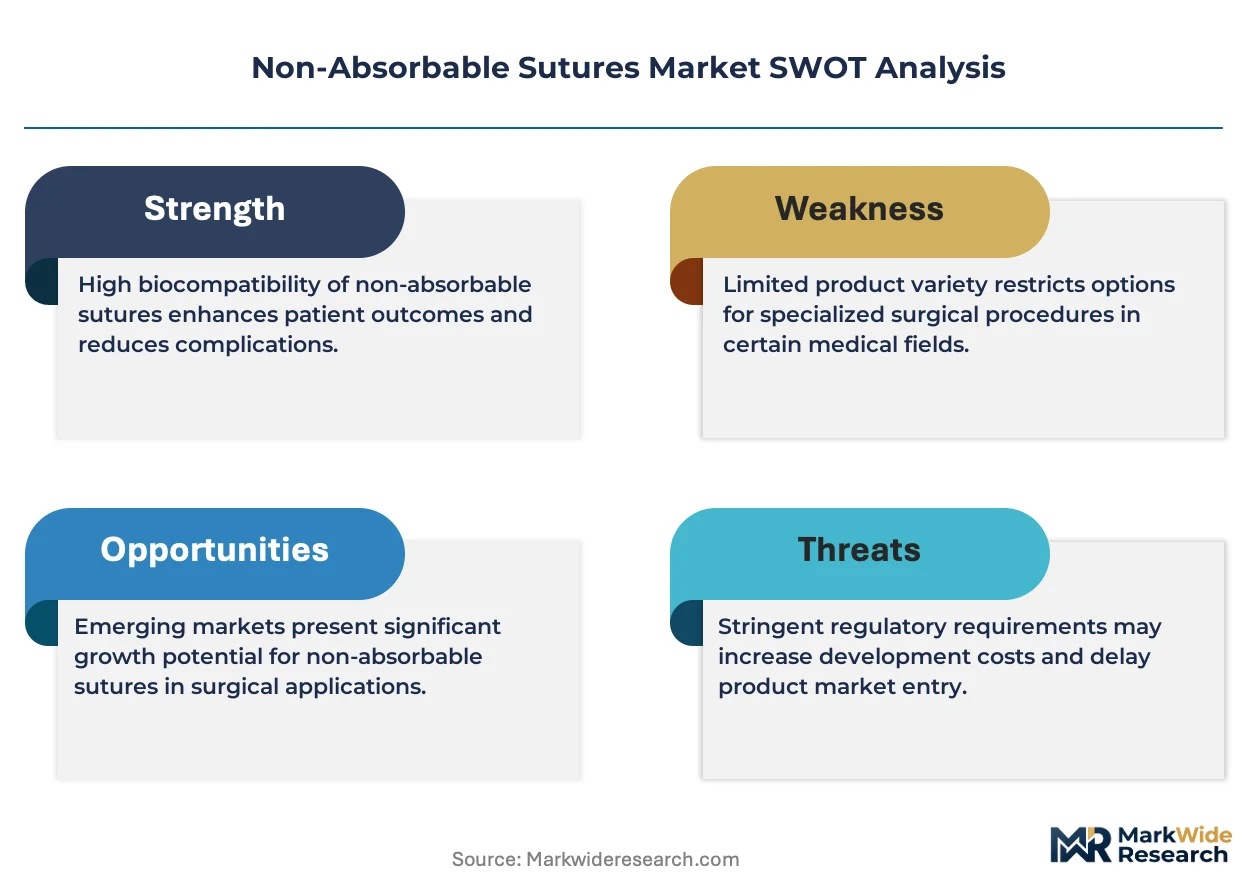
The FDA enforces 21 CFR Part 820 quality system regulations and biocompatibility testing under ISO 10993 for all permanent implant sutures, while the EU Medical Device Regulation mandates notified-body conformity assessment and clinical evidence documentation for Class IIa and above surgical threads. These frameworks elevate barriers for new entrants and sustain incumbent advantages through validated sterilization protocols and traceable batch records. Stakeholders must monitor evolving polymer biocompatibility standards and reimbursement shifts toward outpatient surgical settings to align portfolio development with where procedural economics are migrating.
Market Dynamics
Polypropylene and polyester filament supply concentration in Asian manufacturing clusters is compressing margin pools for Western converters while accelerating regional self-sufficiency in suture production.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States federal reimbursement incentives under CMS outpatient prospective payment systems are redirecting hernia repairs and minor orthopedic procedures to freestanding surgical facilities, elevating consumption of silk and nylon ligatures.
- EU Medical Device Regulation:MDR clinical evidence requirements for Class IIa surgical threads are consolidating supplier bases toward incumbents with validated sterilization protocols, insulating premium polyester braided portfolios from price erosion.
- Orthopedic Procedure Volumes:Aging demographics in Japan and Germany are sustaining elevated demand for high-tension wound closure in joint reconstruction and tendon repair applications.
Market Restraints
- Petrochemical Feedstock Volatility:Naphtha-derived caprolactam and purified terephthalic acid price swings are destabilizing polyamide and polyester suture cost structures for non-integrated manufacturers.
- Single-Source Filament Dependency:Medical-grade polypropylene monofilament production concentrates in South Korean and Chinese petrochemical complexes, exposing converters to export licensing disruptions.
- Absorbable Polymer Substitution:Extended-absorption polydioxanone and polyglyconate variants are capturing select cardiovascular anastomosis applications where 90-day strength retention suffices.
Strategic Opportunities
- Brazilian Hospital Privatization:ANVISA's streamlined registration pathways for Class IIa devices are opening private hospital procurement channels for European suture manufacturers with established CE-MDR documentation.
- Antimicrobial Suture Coatings:Triclosan and chlorhexidine-impregnated braided configurations are penetrating sternal closure and contaminated wound applications where surgical site infection reduction commands reimbursement premiums.
- Direct-to-Ambulatory Distribution:Specialized logistics providers are disintermediating hospital purchasing cooperatives to serve United States ambulatory surgery centers with just-in-time suture replenishment.
Industry Challenges
- Polymer Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization study queues at contracted laboratories are extending new product introduction timelines by 8-14 months.
- Legacy ERP Integration:United States suture manufacturers with SAP or Oracle implementations face UDI (Unique Device Identification) compliance reconfiguration costs for lot-level traceability mandates.
- Needle Attachment Automation:Swage crimping precision requirements for microsurgical ophthalmic needles demand capital-intensive robotic assembly lines that mid-scale converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Absorbable Sutures Market |
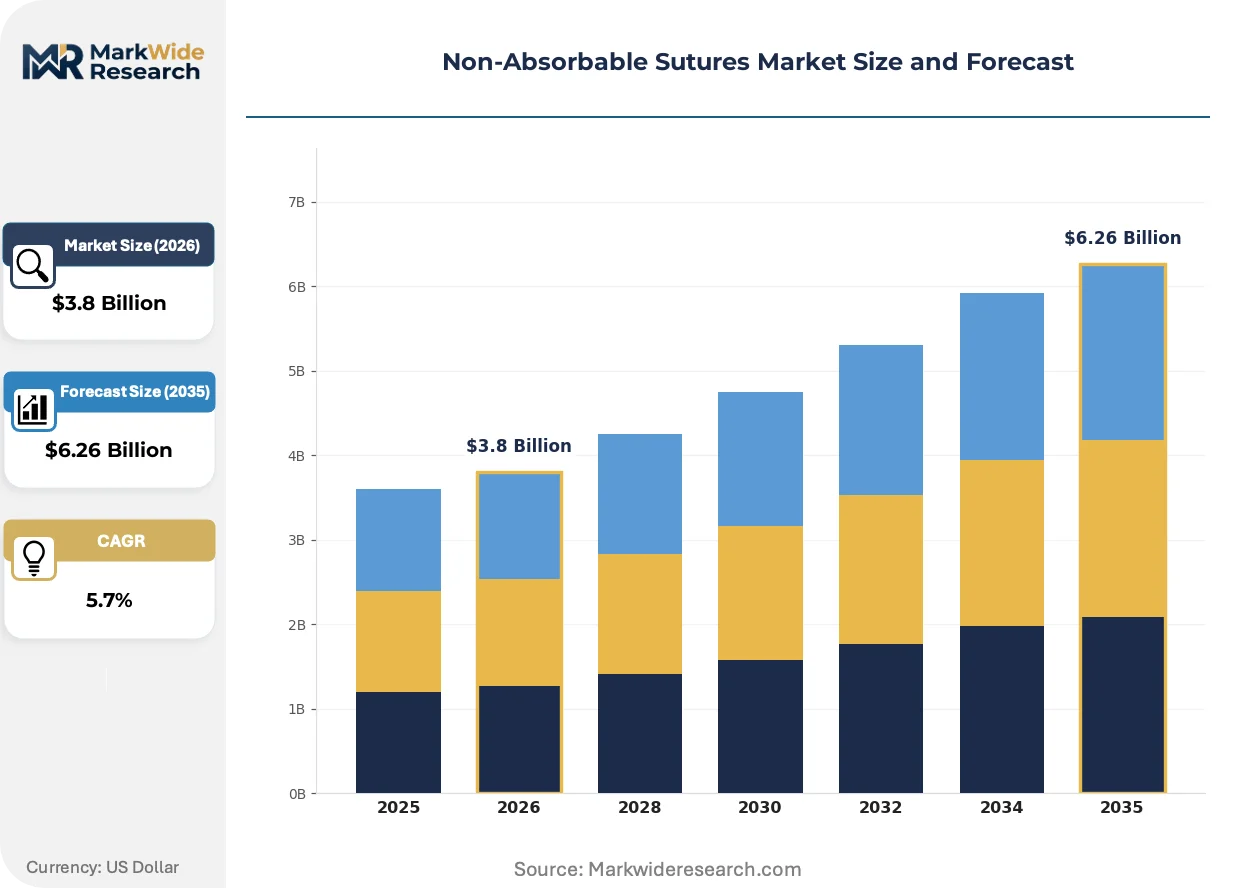
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk Sutures, Nylon Sutures, Polyester Sutures, Polypropylene Sutures Application: Surgical Suturing, Dental Procedures, Orthopedic Repairs, Cosmetic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgical Centers Form: Monofilament, Multifilament, Braided, Coated |
| Companies Covered | Johnson & Johnson (Ethicon), Medtronic, B. Braun, Peters Surgical, DemeTech Corporation, Teleflex Incorporated, Advanced Medical Solutions Group, Smith+Nephew, SERAG-WIESSNER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Absorbable Sutures Market Evolving Landscape
Braided suture architecture is fragmenting into application-specific configurations while regulatory evidence burdens and procurement centralization are compressing commercial timelines for new entrants.
Barbed knotless suture technology is modularizing tension distribution across wound edges without traditional knot stacks. Cardiac surgeons in German university hospitals are adopting V-Loc and Quill configurations for rapid sternal closure. This shift is modularizing operating room throughput metrics and compressing anesthesia exposure times.
REACH Annex XVII restrictions on microplastic release are pressuring polyester multifilament manufacturers to validate biodegradation pathways or reformulate coatings. Industrial consequence includes accelerated R&D spending on bio-based polymer alternatives at European headquarters operations. Cardiovascular suture lines with documented environmental fate profiles are capturing preferred supplier status at Netherlands and Scandinavian hospital systems.
Hospital purchasing cooperatives in the United States are consolidating suture procurement under single-source national agreements that bundle premium cardiovascular, standard general surgery, and economy dental ligature tiers. Independent distributors are losing shelf space at tier-one academic medical centers. This concentration is most visible in Texas and Florida health systems where HCA and Tenet operations dominate procedural volume.
Non-Absorbable Sutures Market Segmentation
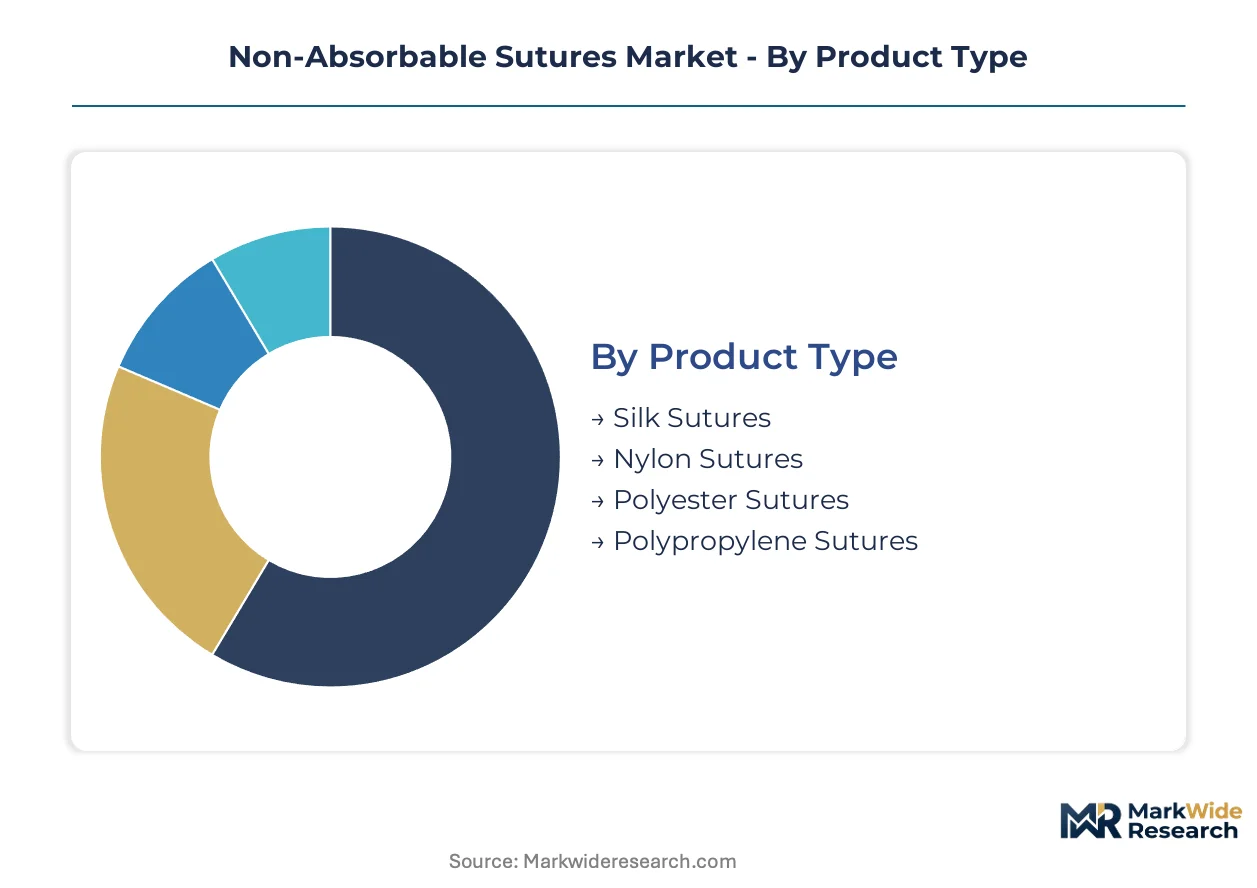
Non-absorbable sutures fragment across material chemistry, procedural setting, and physical construction. Each dimension carries distinct capital requirements, regulatory pathways, and margin profiles that shape manufacturer portfolio decisions.
Product Type:
Capital intensity peaks with synthetic polymer extrusion, where medical-grade filament production demands cleanroom infrastructure and validated sterilization tunnels.
- Polypropylene Sutures:Monofilament construction from isotactic polypropylene delivers minimal tissue drag and predictable degradation resistance. Demand concentrates in United States cardiovascular centers where FDA-cleared cardiac valve repair protocols specify this material for long-term implantation.
- Polyester Sutures:Braided polyethylene terephthalate filaments provide superior knot security and tensile strength retention. German orthopedic departments and Japanese trauma centers specify these for tendon reattachment where mechanical load-bearing exceeds six months.
- Nylon Sutures:Polyamide monofilament serves general soft tissue approximation with moderate strength loss over two years. Microsurgical ophthalmic procedures in France and Italy drive premium pricing for ultra-fine gauge configurations.
- Silk Sutures:Natural protein fiber from Bombyx mori sericin coating offers exceptional handling characteristics. Dental ligature applications in India and Brazil sustain volume despite synthetic substitution in most surgical fields.
Most installed capacity flows through polypropylene. Expansion is steepest in polyester.
Application:
Procedure reimbursement tiers determine suture specification, with cardiac and orthopedic commands justifying premium material selection over cost-minimized alternatives.
- Orthopedic Repairs:High-tension wound closure in joint reconstruction and sports medicine demands braided polyester or heavy-gauge polypropylene. Aging populations in Japan and Germany sustain procedural volume for rotator cuff and Achilles tendon repairs.
- Surgical Suturing:General abdominal and thoracic closure represents the volume base across hospital systems. United States ambulatory surgery centers are capturing hernia repair volume previously handled in inpatient settings.
- Cosmetic Surgery:Aesthetic procedures require minimal scarring and fine-gauge precision. Brazilian and South Korean private clinics specify coated nylon for rhinoplasty and blepharoplasty applications.
- Dental Procedures:Oral surgery and periodontal ligature use silk and nylon in configurations optimized for moist environments. Extraction socket closure in Mexican and Turkish dental tourism markets sustains steady consumption.
Orthopedic applications command the highest material specification. Cosmetic surgery is expanding most quickly.
End User:
Procurement centralization varies sharply by facility type, with hospital systems leveraging volume aggregation while ambulatory centers prioritize just-in-time logistics relationships.
- Hospitals:Tier-one academic medical centers in Texas and Florida operate under national purchasing cooperative agreements bundling cardiovascular, orthopedic, and general surgery suture portfolios.
- Ambulatory Surgical Centers:Freestanding facilities under United States CMS outpatient prospective payment systems redirect hernia and minor orthopedic volume from inpatient settings.
- Specialty Surgical Centers:Cardiac and ophthalmic focused facilities in Germany and Switzerland maintain direct supplier relationships for procedure-specific configurations.
- Clinics:Office-based surgical suites in India and Brazil handle minor wound closure with economy-tier silk and nylon ligatures.
Hospital systems absorb the majority of premium polyester volume. Ambulatory surgical centers are gaining share fastest.
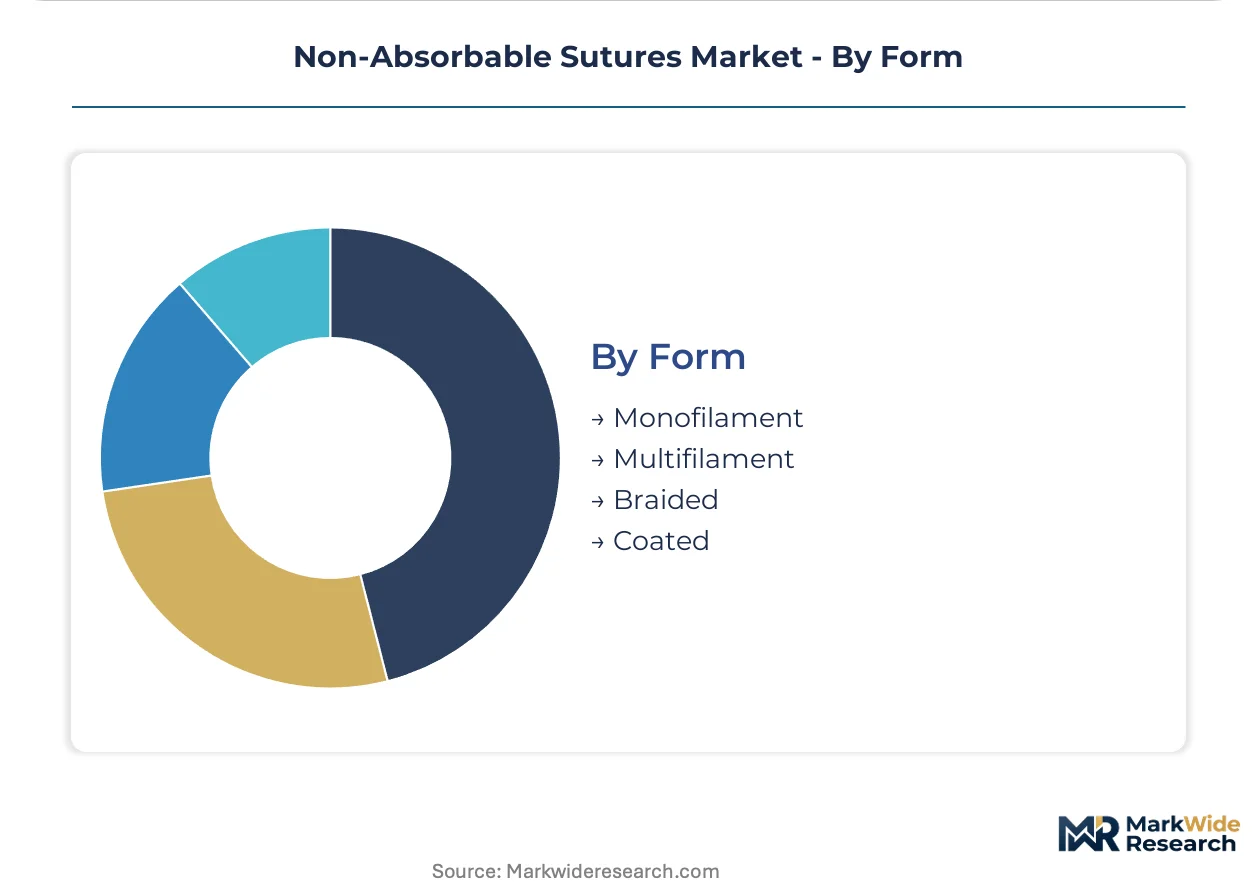
Form:
Manufacturing complexity escalates from simple monofilament extrusion through braided architectures to coated configurations requiring secondary processing lines.
- Monofilament:Single-strand construction minimizes tissue reaction and bacterial wicking. Polypropylene monofilament dominates cardiovascular anastomosis where smooth passage through calcified vessels is essential.
- Braided:Interwoven filament architecture maximizes knot security and tensile strength. Orthopedic tendon repair in German university hospitals specifies braided polyester for load-bearing applications.
- Multifilament:Twisted or braided natural or synthetic fibers offer pliability and handling ease. Silk multifilament retains niche positioning in dental and ligature applications.
- Coated:Silicone or polymer surface treatments reduce tissue drag and capillarity. Microsurgical ophthalmic needles from European manufacturers specify coated configurations for corneal suturing.
Most installed capacity flows through monofilament. Braided configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johnson & Johnson's Ethicon division anchors manufacturing capacity in Cincinnati, Ohio, where polypropylene monofilament extrusion lines supply cardiovascular centers across the United States. This cluster shapes procurement patterns for permanent wound closure devices in North America.
United States
Ambulatory surgical centers in Texas and Florida capture hernia repair volume redirected from inpatient settings under CMS outpatient prospective payment systems. FDA 21 CFR Part 820 quality system regulations mandate validated sterilization protocols for all permanent implant sutures. Cincinnati and San Juan Bautista, Puerto Rico host concentrated filament production and needle attachment operations serving domestic demand.
Germany
University hospitals in Berlin and Munich specify braided polyester configurations for tendon reattachment procedures in aging patient populations. EU Medical Device Regulation notified-body conformity assessments elevate documentation burdens for Class IIa surgical threads. The Tuttlingen surgical instrument cluster integrates suture distribution with laparoscopic and orthopedic device supply chains.
Japan
Joint reconstruction procedures in Tokyo and Osaka sustain demand for high-tension wound closure in sports medicine applications. PMDA biocompatibility testing under ISO 10993 extends product registration timelines for imported polyester braided portfolios. The Kobe medical device manufacturing zone hosts regional distribution hubs serving Kansai prefecture surgical centers.
China
Domestic petrochemical complexes in Ningbo and Shanghai supply medical-grade polypropylene monofilament to local converters reducing import dependency. NMPA medical device registration requirements for Class II implantable threads mandate domestic clinical evidence generation. The Suzhou industrial park concentrates suture finishing and packaging operations for Asia-Pacific export markets.
Brazil
Private hospital procurement in São Paulo and Rio de Janeiro opens channels for European manufacturers with established CE-MDR documentation. ANVISA streamlined registration pathways for Class IIa devices accelerate market access timelines. The Campinas medical technology corridor hosts distribution infrastructure serving southeastern state surgical networks.
Non-Absorbable Sutures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue antimicrobial coating differentiation and ambulatory-focused logistics relationships. The vendor base concentrates around diversified medical device conglomerates with captive polymer supply and specialized surgical thread manufacturers dependent on third-party filament procurement. Three archetypes dominate: integrated polymer-to-suture converters, regional distribution specialists, and coating technology licensors. Competitive moves center on backward integration into medical-grade resin production and direct-to-ambulatory distribution partnerships bypassing hospital purchasing cooperatives.
Among diversified healthcare conglomerates, Johnson & Johnson (Ethicon), Medtronic, and B. Braun exemplify scale-driven positions with integrated manufacturing footprints. These entities represent archetypes spanning captive polymer production, concentrated R&D allocation, and geographic density in direct hospital supply relationships. Their positioning anchors competitive dynamics for premium cardiovascular and orthopedic suture tiers where validated sterilization protocols and traceable batch records constitute minimum entry requirements.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Medtronic |
| B. Braun |
| Peters Surgical |
| DemeTech Corporation |
| Teleflex Incorporated |
| Advanced Medical Solutions Group |
| Smith+Nephew |
| SERAG-WIESSNER |
| Others |
Value Network & Pricing Analysis
Medical-grade polypropylene resin costs cascade through filament extrusion, sterile packaging, and needle attachment to stratify final suture pricing across premium cardiovascular, standard orthopedic, and economy dental tiers. Naphtha-derived caprolactam price swings in Asian petrochemical complexes compress margin pools for Western converters lacking captive polymer supply.
Pricing Analysis
Input-cost pass-through from purified terephthalic acid and caprolactam volatility governs polyester and nylon suture pricing, with non-integrated manufacturers absorbing margin compression while integrated players shield portfolios through captive filament production. Pricing stratifies across premium, standard, and economy tiers driven by ISO 10993 biocompatibility certification grade and brand premium at cardiovascular centers versus volume scale at ambulatory surgery centers. Price erosion runs through economy silk and nylon ligatures as Indian and Brazilian converters expand capacity. Ambulatory surgery centers exhibit highest price sensitivity due to CMS reimbursement constraints, while German university hospitals show lowest sensitivity for braided polyester tendon repair configurations.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled suture lots require temperature-controlled returns to certified destruction facilities, adding complexity to just-in-time replenishment models at United States ambulatory centers. Medical-grade polypropylene monofilament production concentrates in South Korean and Chinese petrochemical complexes, with purified terephthalic acid and caprolactam feeding from naphtha crackers in Ningbo and Ulsan. Single-source filament dependency creates vulnerability to export licensing disruptions. Distribution runs through hospital purchasing cooperatives in Texas and Florida, with specialized logistics providers disintermediating cooperatives to serve freestanding surgical facilities directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-absorbable sutures function as a stable compounder anchored by aging demographics and procedural volume expansion in orthopedic and cardiovascular applications. Regulatory barriers and sterilization protocol requirements sustain incumbent advantages against price erosion.
For Market Incumbents: Anticipate antimicrobial coating substitution threats from triclosan-impregnated braided configurations by accelerating R&D spending on chlorhexidine alternatives and securing preferred supplier status at Netherlands hospital systems prioritizing environmental fate documentation. Defend margin position through backward integration into medical-grade resin production and direct distribution partnerships with United States ambulatory surgery centers bypassing purchasing cooperatives. For New Entrants and Emerging Players: Antimicrobial coating technology offers entry wedge into sternal closure and contaminated wound applications where surgical site infection reduction commands reimbursement premiums. Target Brazilian private hospital procurement channels opened by ANVISA streamlined registration pathways for Class IIa devices with established CE-MDR documentation. Pursue coating technology licensing agreements with European headquarters operations facing REACH Annex XVII microplastic restrictions. For Investors and Strategic Acquirers: Roll-up economics work for regional distribution specialists with direct hospital relationships because procurement centralization under national purchasing cooperatives is displacing independent distributors at tier-one academic medical centers. Five-to-ten year viability hinges on sterilization protocol validation assets and traceable batch record systems. Monitor FDA 21 CFR Part 820 quality system regulation enforcement intensity as inflection indicator for regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Development | Triclosan and chlorhexidine-impregnated braided configurations penetrate sternal closure applications commanding infection-reduction premiums. |
| Backward Integration into Filament Production | Captive polypropylene and polyester extrusion shields margin pools from Asian petrochemical price volatility. |
| Direct-to-Ambulatory Distribution Partnerships | Specialized logistics providers disintermediate hospital purchasing cooperatives serving CMS-reimbursed freestanding surgical facilities. |
| CE-MDR Documentation Investment | Notified-body conformity assessment accelerates Brazilian ANVISA registration pathways for European manufacturers. |
| Environmental Fate Profile Validation | REACH-compliant biodegradation documentation captures preferred supplier status at Scandinavian hospital systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and Brazil, with primary inputs from each market combining structured interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at suture manufacturers with secondary validation. Secondary sources include FDA 510(k) filings, EMA notified-body conformity assessments, CMS Medicare outpatient prospective payment system data, and ANVISA registration databases. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue allocations.
Granularity-level modeling disaggregates the analysis window by material chemistry (polypropylene, polyester, nylon, silk), procedural application (orthopedic repair, cardiovascular anastomosis, general surgery, dental ligature), and end-user facility type (hospital system, ambulatory surgical center, specialty surgical center, clinic). CAGRs derive from procedure volume forecasts weighted by suture units per procedure and material-specific pricing trajectories. Forecast inputs incorporate PMDA biocompatibility testing timeline extensions and CMS reimbursement tier shifts toward outpatient settings.
The model holds under stable petrochemical feedstock pricing and continued CMS outpatient payment incentives; deviation in naphtha-derived caprolactam volatility or FDA quality system regulation enforcement intensity would shift volume and value trajectories. Practitioners should monitor ISO 10993 cytotoxicity study queue lengths and REACH Annex XVII microplastic restriction implementation for early signals of regulatory cost escalation or coating reformulation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Laparoscopic Sutures Market