
 Global Microsurgical Instruments Market | 2026-2036
Global Microsurgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microsurgical Instruments Market Foresight
ISO 13485 certification cycles is rotating faster than three years ago, forcing smaller forge shops to exit the microsurgical supply base. Carl Zeiss Meditec leverages its captive optics foundry to control tolerances on sub-millimeter retinal instruments. B. Braun Melsungen anchors European hospital procurement through direct sterilization-service bundling. Olympus Corporation competes in Japan by dominating the domestic ENT micro-instrument rebuild market.
Microsurgical instruments encompass precision-manufactured hand tools and powered devices engineered from titanium alloys or stainless steel with tip geometries below 0.3 millimeters, designed to manipulate tissue under magnification during procedures where visual access is constrained. Forceps and scissors command the largest revenue pools due to replacement frequency and SKU proliferation across surgical disciplines, while robotic-assisted technology represents the fastest-expanding segment as da Vinci and competing platforms require proprietary instrument cartridges with embedded chip authentication. Manual instruments remain margin-diluted despite volume leadership because price competition from Indian and Pakistani forge clusters compresses realized pricing.
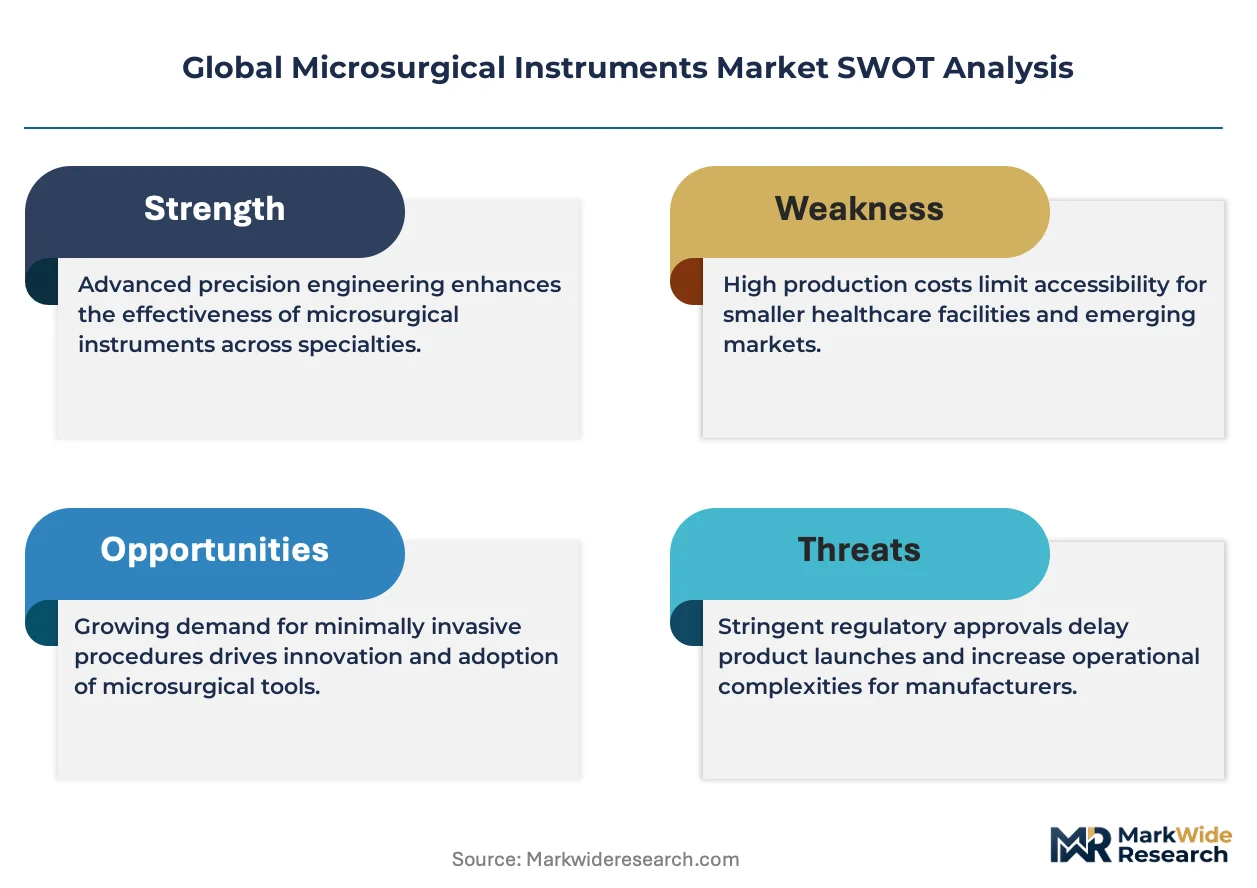
FDA 510(k) pathways and EU MDR technical documentation requirements are extending time-to-market for new micro-instrument families by twelve to eighteen months, advantaging incumbents with established quality management systems. Japan's PMDA enforces stricter biocompatibility retesting for reprocessed instruments, shaping domestic purchasing toward single-use disposables. China's NMPA has harmonized with ISO standards for ophthalmic microsurgical devices, accelerating local manufacturer access. Stakeholders must monitor regulatory divergence between FDA digital health guidance and EU AI Act risk classification for robotic-assisted platforms to anticipate where development capital will face friction.
Market Dynamics
Robotic-assisted surgical platforms are compressing instrument design cycles while fragmenting procurement authority between hospital supply chains and OEM cartridge programs. This bifurcation is reshaping supplier relationships across ophthalmology, neurosurgery, and ENT disciplines.
Growth Catalysts
- Cataract procedure volume:Aging demographics in Germany and Japan are expanding instrument procurement through dedicated ophthalmology clinics. Surgical volume growth in metropolitan clusters is accelerating replacement cycles for forceps and scissors.
- EU MDR harmonization:Standardized technical documentation requirements are consolidating supplier qualification toward ISO 13485-certified manufacturers. This regulatory clarity is reducing buyer due diligence overhead for European hospital systems.
- Titanium alloy advances:Improved machinability of Ti-6Al-4V ELI is enabling sub-millimeter tip geometries with enhanced fatigue resistance. Forge shops with electron beam melting capabilities are capturing premium instrument contracts.
Market Restraints
- Plasma sterilization validation costs:Reusable instrument requalification under FDA 510(k) pathways requires capital-intensive bioburden testing. Smaller manufacturers lack resources to maintain dual FDA-MDR dossiers.
- Pakistani forge cluster concentration:Manual instrument price compression originates from Sialkot-based suppliers with limited traceability documentation. Western buyers face audit complexity when sourcing from this supply base.
- Single-use substitution:Japan's PMDA biocompatibility retesting mandates for reprocessed instruments are shifting domestic demand toward disposable alternatives. This regulatory friction disadvantages reusable instrument portfolios.
Strategic Opportunities
- South Korean specialty surgery centers:Construction acceleration in Seoul and Busan metropolitan clusters is creating greenfield procurement opportunities. First-mover sterilization-service bundling can anchor long-term supply contracts.
- Chip-authenticated instrument cartridges:Convergence of RFID tracking with robotic platform compatibility is enabling usage-based pricing models. Embedded authentication is creating aftermarket revenue streams for OEMs.
- India PLI scheme alignment:Domestic manufacturing incentives for medical devices are reducing import dependence for stainless steel instrument families. Local forge capacity expansion is qualifying for government hospital procurement preference.
Industry Challenges
- Electron microscopy technician scarcity:Sub-millimeter tip inspection requires specialized operators with scanning electron microscopy certification. Training pipelines lag instrument complexity advancement.
- Legacy ERP integration:Hospital procurement systems struggle to reconcile robotic cartridge authentication data with existing inventory management workflows. Middleware development is extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microsurgical Instruments Market |
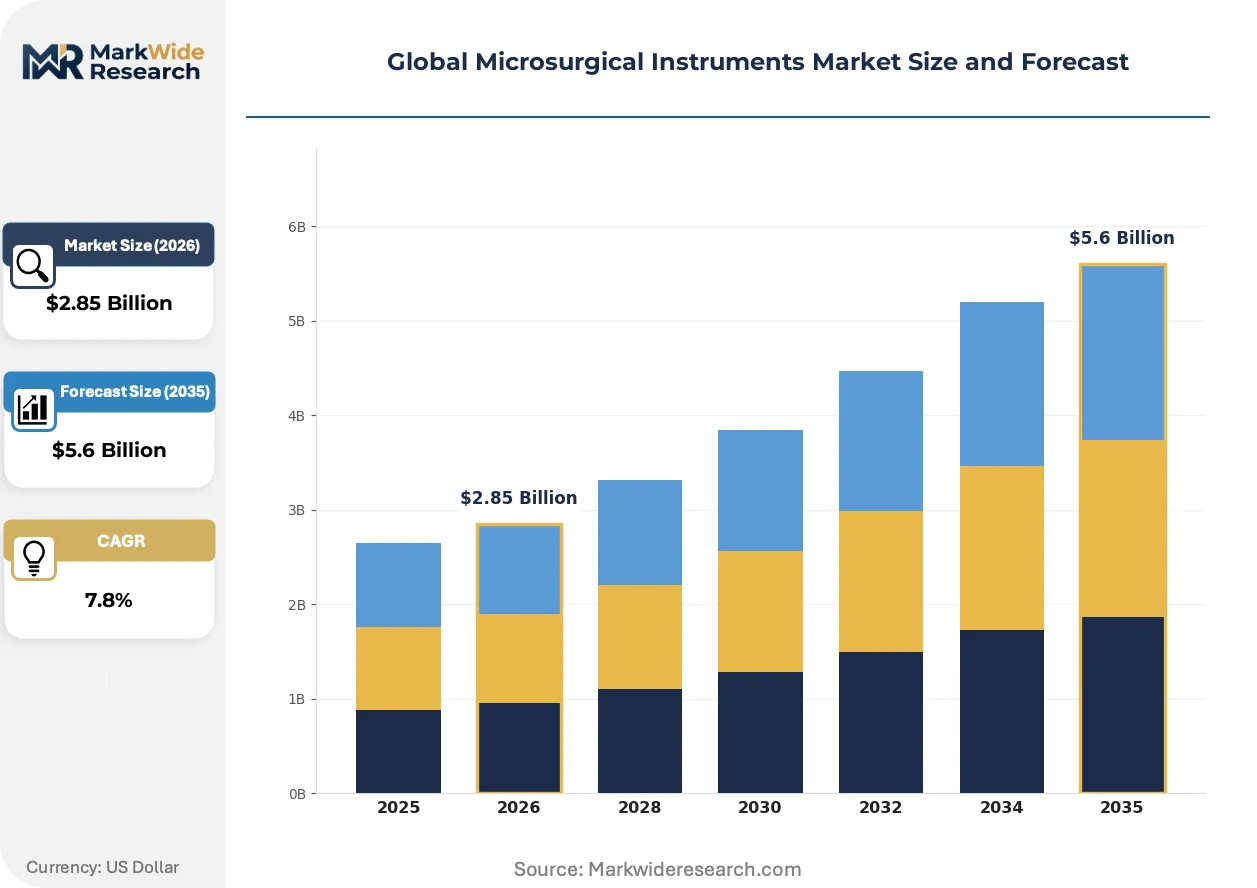
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forceps, Scissors, Needle Holders, Retractors, Speculums Technology: Manual, Powered, Ultrasonic, Laser, Robotic-assisted Application: Neurosurgery, Ophthalmology, Plastic Surgery, ENT, Cardiovascular End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research Institutes |
| Companies Covered | B. Braun Melsungen, Carl Zeiss Meditec, Olympus Corporation, Leica Microsystems, Johnson & Johnson, Medtronic, Stryker Corporation, Integra LifeSciences, Haag-Streit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microsurgical Instruments Market Shifts & Advancements
Precision manufacturing convergence with embedded sensing is transforming instrument functionality from passive tools to data-generating devices. This instrumentation shift is redrawing competitive boundaries between traditional metalworkers and electronics integrators.
Nitinol shape-memory actuation is miniaturizing instrument tip articulation for retinal and cochlear procedures. Academic medical centers in the United States are piloting these adaptive geometries for tremor compensation. The technology is miniaturizing access corridors while demanding new metrology protocols for superelastic alloy characterization.
EU MDR Article 10 technical documentation requirements are extending sterilization validation timelines for reusable instrument families. European notified bodies are prioritizing audits for high-risk surgical device categories. German hospital procurement consortia are responding by consolidating supplier panels toward MDR-certified incumbents with established quality management systems.
Direct sterilization-service bundling is displacing traditional instrument-only transactions in European hospital systems. B. Braun Melsungen's integrated offering is capturing multi-year contracts through total cost-of-ownership guarantees. This model is most visible in German and Swiss university hospital clusters where reprocessing liability concentration favors outsourced sterilization management.
Global Microsurgical Instruments Market Segmentation
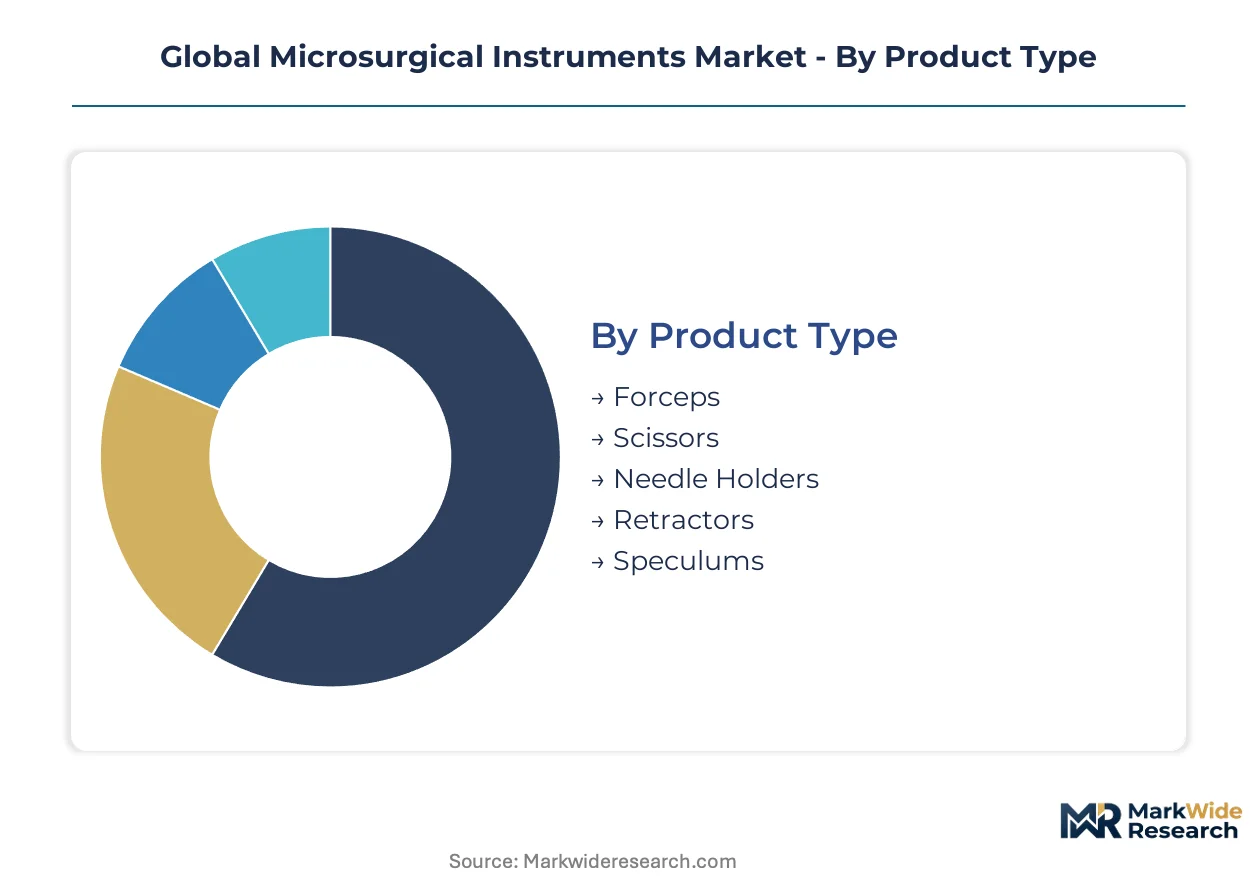
Microsurgical instrument segmentation reveals divergent compliance burdens and margin structures across product architectures. Regulatory pathways for powered and robotic-assisted platforms extend development timelines compared to manual stainless steel families.
Product Type:
FDA 510(k) clearance complexity varies sharply by instrument geometry and tissue contact duration. EU MDR classification rules elevate scrutiny for scissors and needle holders due to sustained vascular engagement.
- Forceps:Titanium alloy or stainless steel designs with sub-millimeter tip geometries dominate replacement frequency across surgical disciplines. German ophthalmology clinics and Japanese vitreoretinal centers are expanding procurement as cataract volumes rise.
- Scissors:Precision-ground blade assemblies with fatigue-resistant Ti-6Al-4V ELI construction command premium positioning. South Korean specialty surgery center construction is accelerating demand for single-use and reusable variants with validated sterilization protocols.
- Needle Holders:Ratchet-lock mechanisms for microsuture manipulation in cardiovascular and plastic procedures.
- Retractors:Low-profile designs for constrained visual access corridors in neurosurgery and ENT.
- Speculums:Adjustable aperture instruments for ophthalmic anterior segment exposure.
Forceps handles the majority of throughput; Scissors is climbing the fastest on share.
Technology:
Cost tier stratification separates capital-intensive platforms from high-volume manual instruments. Electron beam melting capabilities and embedded authentication chips differentiate premium positioning.
- Manual:Pakistani forge clusters compress realized pricing for stainless steel forceps and scissors families. Western buyers face audit complexity when sourcing from Sialkot-based suppliers with limited traceability documentation.
- Powered:Electric or pneumatic handpieces for bone and tissue cutting in neurosurgery and ENT applications.
- Ultrasonic:High-frequency vibration tips for precise tissue dissection with minimal thermal spread.
- Laser:Fiber-delivered energy systems for retinal and dermatological microsurgery.
- Robotic-assisted:Proprietary instrument cartridges with embedded RFID chip authentication enable usage-based pricing models. da Vinci and competing platforms fragment procurement authority between hospital supply chains and OEM cartridge programs.
Manual instruments anchor volume throughput; Robotic-assisted platforms are expanding most quickly on revenue contribution.
Application:
Customer type concentration shapes instrument specification requirements. Academic medical centers demand adaptive geometries while ambulatory settings prioritize sterilization efficiency.
- Neurosurgery:Sub-millimeter tip tolerances and tremor-compensation technologies for cranial and spinal access. Nitinol shape-memory actuation is miniaturizing instrument articulation at United States academic medical centers.
- Ophthalmology:Cataract and vitreoretinal procedure volume expansion in Germany and Japan drives dedicated clinic procurement. Forceps and scissors replacement cycles accelerate with surgical volume growth in metropolitan clusters.
- Plastic Surgery:Aesthetic and reconstructive microvascular anastomosis instruments.
- ENT:Cochlear and sinus access tools with enhanced visualization compatibility.
- Cardiovascular:Microvascular clamps and needle holders for coronary and peripheral bypass procedures.
Ophthalmology handles the majority of throughput; Neurosurgery is gaining share fastest on technology premium.
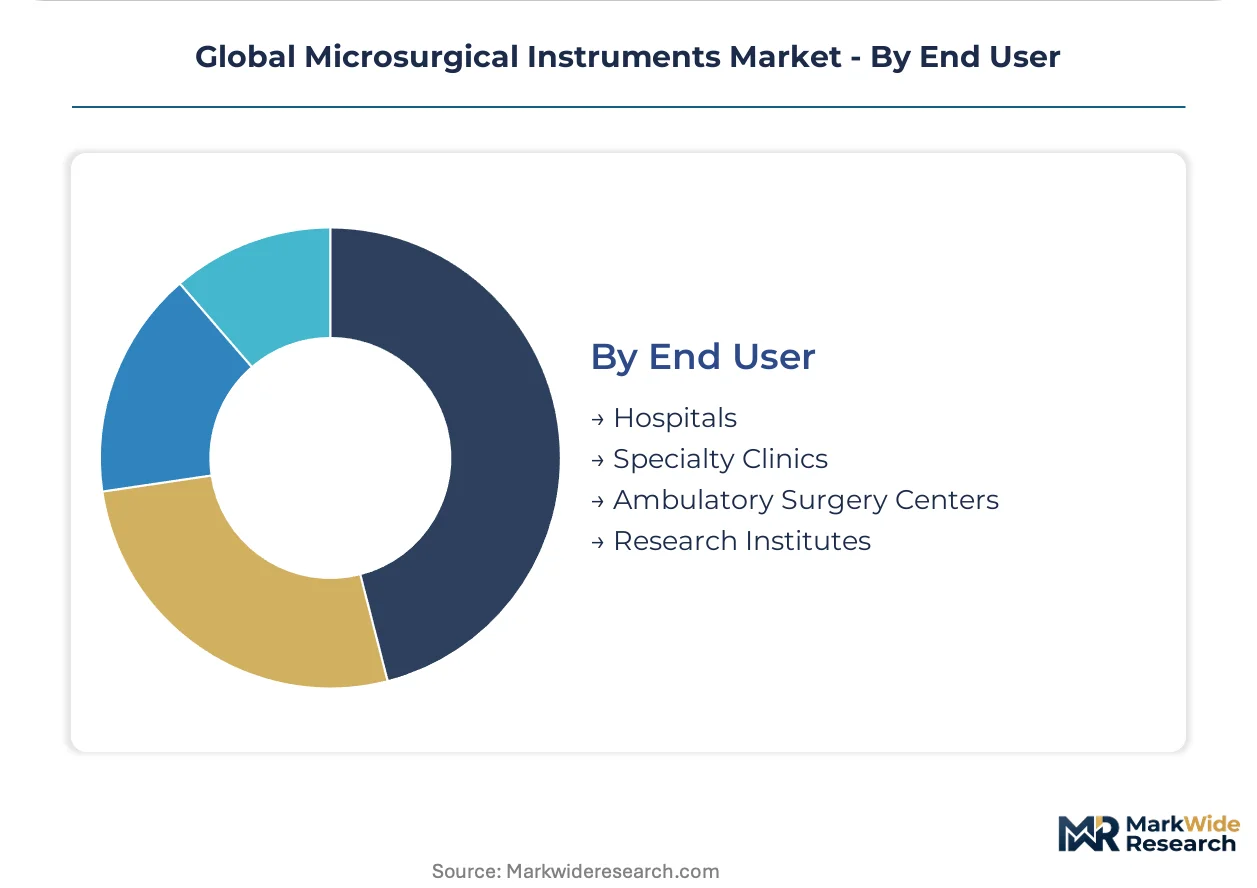
End User:
Geography determines procurement consolidation patterns. Metropolitan hospital clusters in India and South Korea concentrate demand while sterilization-service bundling reshapes European contracting.
- Hospitals:Integrated health systems with captive sterilization infrastructure or outsourced reprocessing management. B. Braun Melsungen anchors German and Swiss university hospital contracts through total cost-of-ownership guarantees.
- Specialty Clinics:Ophthalmology and ENT-focused facilities with procedure-specific instrument portfolios. Construction acceleration in Seoul and Busan metropolitan clusters creates greenfield procurement opportunities.
- Ambulatory Surgery Centers:High-throughput settings favoring single-use disposables to minimize reprocessing liability.
- Research Institutes:Academic medical centers piloting nitinol adaptive geometries and embedded sensing prototypes.
Hospitals handle the majority of throughput; Specialty Clinics are expanding most quickly on construction activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives in India and South Korea are accelerating specialty surgery center construction. EU MDR harmonization compresses supplier qualification windows toward ISO 13485-certified manufacturers. Regulatory divergence between FDA digital health guidance and EU AI Act risk classification shapes capital allocation.
United States
Academic medical centers in Boston and Baltimore pilot nitinol shape-memory actuation for tremor compensation. FDA 510(k) pathways extend sterilization validation timelines for reusable instrument families. The Research Triangle and Greater Boston clusters concentrate reprocessing liability management outsourcing.
Germany
Ophthalmology clinics in Munich and Hamburg expand instrument procurement as cataract procedure volumes rise. EU MDR Article 10 technical documentation requirements prioritize audits for high-risk surgical device categories. Bavarian and North Rhine-Westphalian hospital consortia consolidate supplier panels toward MDR-certified incumbents.
Japan
Vitreoretinal centers in Tokyo and Osaka drive dedicated clinic procurement for sub-millimeter retinal instruments. PMDA enforces stricter biocompatibility retesting for reprocessed instruments, shifting domestic purchasing toward single-use disposables. Olympus Corporation dominates the domestic ENT micro-instrument rebuild market through metropolitan service networks.
India
Metropolitan hospital clusters in Mumbai and Delhi concentrate demand for stainless steel instrument families. PLI scheme alignment for medical devices reduces import dependence and qualifies local forge capacity for government hospital procurement preference. Maharashtra and Gujarat forge shops expand electron beam melting capabilities for premium contracts.
South Korea
Specialty surgery center construction accelerates in Seoul and Busan metropolitan clusters. MFDS harmonization with ISO standards streamlines qualification for domestic manufacturers. Greenfield procurement opportunities favor first-mover sterilization-service bundling to anchor long-term supply contracts.
Global Microsurgical Instruments Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities, creating tiered positioning around FDA and MDR dossier maintenance. The vendor base stratifies between consolidated sterilization-service bundlers, captive-optics integrators, and forge-dependent manual instrument suppliers. Three archetypes dominate: integrated health system contractors, precision manufacturing specialists with electron beam melting capabilities, and regional rebuild service operators. M&A activity concentrates sterilization validation assets while geographic expansion targets South Korean and Indian metropolitan clusters.
Within the integrated service tier, B. Braun Melsungen anchors European hospital procurement through total cost-of-ownership guarantees. Carl Zeiss Meditec exemplifies the captive-capability archetype through optics foundry control. Among Japanese rebuild specialists, Olympus Corporation occupies a dominant position in domestic ENT service networks.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| Carl Zeiss Meditec |
| Olympus Corporation |
| Leica Microsystems |
| Johnson & Johnson |
| Medtronic |
| Stryker Corporation |
| Integra LifeSciences |
| Haag-Streit Group |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day sterilization validation lead times for reusable instrument families compress supplier qualification windows while amplifying pricing power for ISO 13485-certified incumbents with established FDA and MDR dossiers. This inventory friction feeds back into procurement consolidation, as hospital systems trade unit price transparency for total cost-of-ownership guarantees from integrated sterilization-service bundlers.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between titanium alloy forceps and scissors families, with MDR-certified manufacturers commanding premium positioning over Sialkot-based suppliers with limited traceability documentation. Three-tier pricing structure across premium, standard, and economy levels reflects electron beam melting capabilities, embedded RFID authentication, and after-sales service bundling. Cost compression in manual stainless steel segments intensifies because Pakistani forge clusters flood Western spot markets with undifferentiated SKUs. Ambulatory surgery centers exhibit highest price sensitivity due to single-use disposable preference, while German university hospital consortia prioritize total cost-of-ownership over per-unit acquisition cost.
Supply Chain Analysis
Ninety-day electron beam powder inventory cycles at German and Indian forge shops tether premium titanium instrument production to aerospace alloy allocation priorities. Geographic supply concentration centers on Germany for precision-ground retinal instruments, India for stainless steel manual families, and Japan for ENT micro-instrument rebuild services. Raw material dependencies rest on Ti-6Al-4V ELI aerospace-grade titanium, surgical-grade stainless steel 316L, and nitinol shape-memory wire. Single-source vulnerability concentrates in electron beam melting equipment suppliers. Distribution runs through hospital procurement consortia in metropolitan clusters, GPO contracts, and direct OEM cartridge programs for robotic-assisted platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because regulatory entrenchment through FDA 510(k) and EU MDR dossier maintenance creates switching costs that lock hospital systems into incumbent supply relationships.
For Market Incumbents: Compound sterilization-service bundling penetration in German and Swiss university hospital clusters to deepen captive reprocessing relationships. Add electron beam melting capacity in Maharashtra or Gujarat to capture Indian PLI scheme procurement preference and defend margin position against Sialkot-based price compression. For New Entrants and Emerging Players: MFDS harmonization fast-track with ISO standards opens South Korean specialty surgery center construction as the most penetrable geography for greenfield sterilization-service contracts. Target Seoul and Busan metropolitan clusters with first-mover bundled reprocessing offerings to bypass entrenched European incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and MDR compliance timeline compression continuously filters out undercapitalized competitors. Acquire electron beam melting-equipped precision manufacturers with existing ISO 13485 certification rather than manual instrument forge shops facing price erosion. Monitor PMDA biocompatibility retesting mandate enforcement intensity as the signal indicating acceleration or deceleration in Japan's single-use disposable substitution trend.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Fast-Track Investment | Accelerates European hospital procurement qualification ahead of notified body audit backlogs. |
| Sterilization-Service Bundling Expansion | Captures multi-year German and Swiss university hospital contracts through liability transfer. |
| Electron Beam Melting Capacity Addition | Qualifies for premium titanium instrument contracts requiring sub-millimeter tip geometries. |
| RFID Chip Authentication Integration | Enables usage-based pricing models with da Vinci and competing robotic platform OEMs. |
| South Korean Specialty Surgery Center Partnership | Anchors long-term supply contracts in Seoul and Busan metropolitan greenfield construction. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR notified body audit schedules, and hospital procurement database records preceded structured interviews with ophthalmology clinic purchasing managers, biomedical engineers, GPO contracts managers, and electron beam melting forge shop operators. Secondary validation drew from ISO certification registries, trade customs data for titanium alloy imports, and surgical procedure volume statistics. Bottom-up instrument SKU-level demand modeling triangulated against top-down healthcare expenditure allocation estimates.
Variance decomposition across product type, technology tier, application discipline, and end-user facility category shaped the analytical framework over the projection horizon. CAGRs derived from procedure volume elasticity coefficients, replacement cycle assumptions, and robotic platform penetration curves. Industry-specific forecast inputs incorporated cataract surgery demographic projections, EU MDR implementation phase transitions, and India PLI scheme disbursement trajectories.
Underlying assumptions cover stable FDA-MDR regulatory divergence, titanium alloy aerospace allocation continuity, and hospital consolidation patterns, with deviation risk concentrated in PMDA biocompatency retesting mandate enforcement and single-use substitution acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Brazil General Surgical Devices Market