
 Mexico Wound Care Management Devices Market | 2026-2036
Mexico Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Wound Care Management Devices Market Insights
COFEPRIS Good Manufacturing Practice certification is unwinding the competitive landscape for wound care device suppliers entering Mexico. Smith & Nephew leverages its established regulatory dossiers to sustain premium positioning in advanced dressings. Molnlycke anchors its presence through direct hospital contracts in major metropolitan zones. Cardinal Health competes on distribution breadth, extending logistics coverage into secondary cities where procurement centralization is accelerating.
Wound care management devices encompass dressings, negative pressure systems, and bioengineered skin substitutes designed to maintain moist healing environments and accelerate tissue regeneration through controlled exudate management and barrier protection. These products serve primarily to reduce infection rates, shorten hospital stays, and enable transition of post-operative and chronic wound treatment from acute care to outpatient settings. Advanced dressings dominate current procurement volumes in Mexico, while negative pressure therapy represents the fastest-expanding technology segment as hospital infection control protocols intensify. Bioengineered skin applications remain concentrated in specialized burn centers, reflecting higher unit costs and restricted reimbursement pathways that limit broader adoption.
COFEPRIS maintains oversight of medical device registration and post-market surveillance, enforcing alignment with NOM standards that govern sterility, biocompatibility, and clinical evidence requirements for wound care imports. The Secretaría de Economía administers tariff classifications and origin rules under USMCA provisions, shaping cost structures for suppliers manufacturing outside North America. Stakeholders must monitor impending NOM revisions for active wound care devices and assess whether localized sterilization partnerships or maquiladora assembly can satisfy evolving domestic content expectations without triggering regulatory requalification cycles.
Market Dynamics
COFEPRIS registration timelines are compressing market entry windows for wound care suppliers, forcing accelerated dossier preparation and sterilization validation cycles that reshape competitive positioning before products reach hospital procurement committees.
Growth Catalysts
- USMCA tariff reclassification:Origin rule adjustments for medical devices manufactured in Mexican maquiladoras are reducing landed costs for negative pressure wound therapy systems, stimulating import substitution from Asian suppliers.
- Tertiary hospital expansion:Mexico City and Guadalajara health networks are consolidating procurement under centralized supply chains, creating volume commitments that justify advanced dressing technology adoption.
- Home care protocol maturation:Post-surgical discharge guidelines from the Secretaría de Salud are extending reimbursement coverage for outpatient negative pressure systems, shifting treatment venues from inpatient wards.
Market Restraints
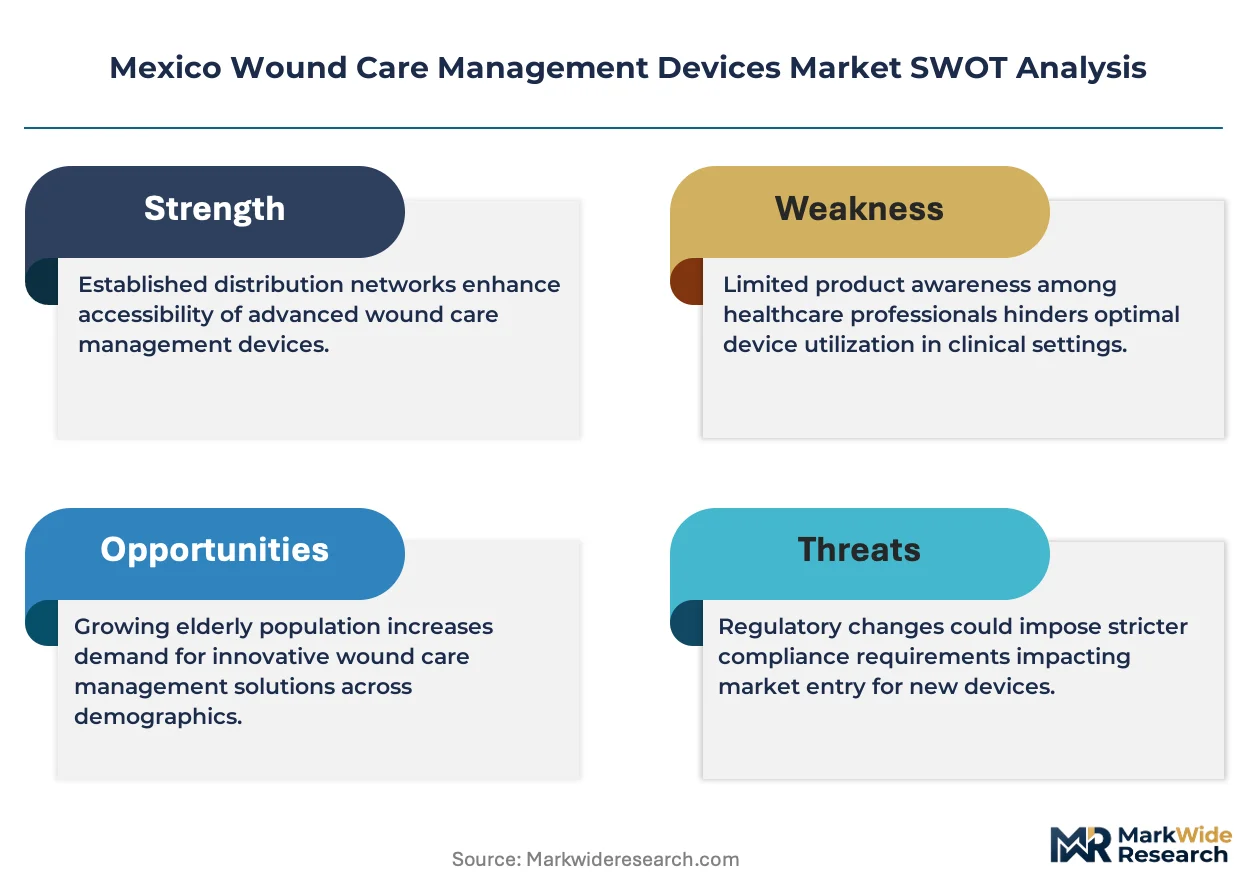
- Ethylene oxide sterilization capacity:Limited contract sterilization infrastructure in central Mexico creates bottlenecks for imported advanced dressings requiring terminal sterilization, extending lead times by 6-8 weeks.
- Reimbursement fragmentation:Seguro Popular and IMSS maintain divergent formularies for bioengineered skin substitutes, restricting patient access in states where IMSS dominates public sector procurement.
- Silver alginate substitution:Conventional gauze and saline-soaked dressings retain preference in secondary city public hospitals where procurement budgets prioritize volume over clinical outcomes.
Strategic Opportunities
- Nuevo León manufacturing zone:Monterrey's medical device cluster offers sterilization partnerships and logistics infrastructure to serve northern border hospitals with reduced customs clearance friction.
- Active wound care convergence:Integration of antimicrobial ionic silver with negative pressure systems creates differentiated positioning against passive dressing competitors in burn center tenders.
- Direct-to-home distribution:Bypassing hospital central supply through specialized wound care distributors enables patient-managed therapy for diabetic foot ulcers in Yucatán and Quintana Roo resort corridor populations.
Industry Challenges
- Clinical specialist scarcity:Certified wound care nurses concentrate in Mexico City and Guadalajara tertiary centers, limiting protocol compliance for advanced negative pressure therapy in provincial IMSS facilities.
- NOM requalification cycles:Pending revisions to active medical device standards risk forcing sterilization process revalidation for established suppliers, compressing margin structures during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Wound Care Management Devices Market |
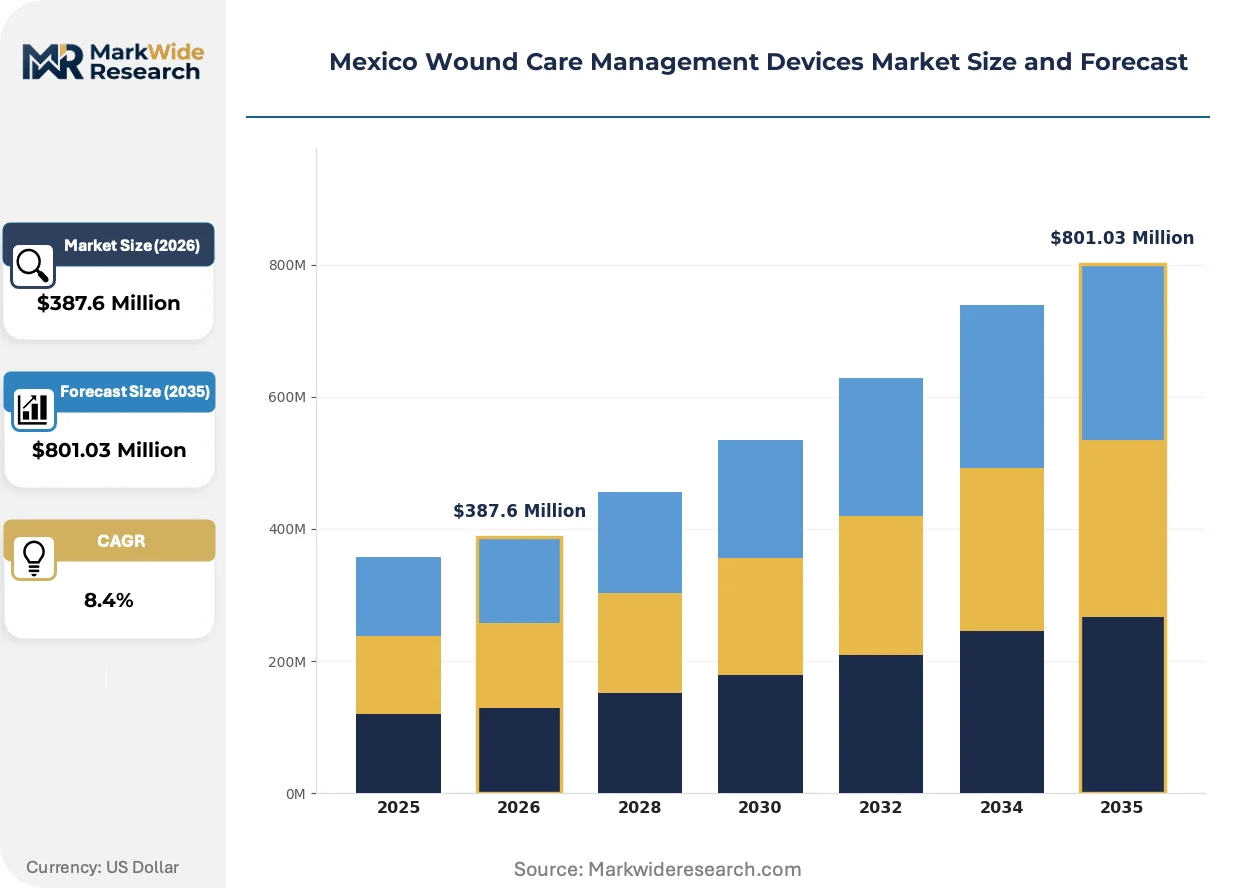
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bandages, Dressings, Antiseptics, Skin Grafts End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Moist Wound Healing, Negative Pressure Therapy, Hydrogel, Bioengineered Skin Application: Chronic Wounds, Surgical Wounds, Burns, Ulcers |
| Companies Covered | Smith & Nephew, Solventum, ConvaTec, Coloplast, Molnlycke, 3M, DeRoyal Industries, Cardinal Health, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Wound Care Management Devices Market Trends and Innovations
Portable negative pressure systems are displacing stationary hospital units as the dominant technology investment, with manufacturers prioritizing battery life and dressing integration over suction power specifications.
Single-use negative pressure canisters with integrated exudate measurement sensors are miniaturizing therapy systems for ambulatory patients. Home health agencies in Jalisco and Nuevo León are adopting these devices at twice the rate of stationary systems. This miniaturization is compressing reimbursement coding distinctions between inpatient and outpatient wound care, forcing payers to consolidate payment schedules.
COFEPRIS is aligning post-market surveillance requirements with FDA Medical Device Reporting standards, mandating adverse event documentation in Spanish within 30-day windows. Device importers must now maintain localized quality management systems with Mexican-resident regulatory correspondents. Negative pressure therapy suppliers with existing FDA 510(k) clearances are leveraging parallel dossier structures to accelerate COFEPRIS approvals.
Hospital purchasing cooperatives are consolidating tender participation requirements, disqualifying distributors without ISO 13485-certified warehousing. Group purchasing organizations in Mexico City now represent 60% of advanced dressing volume, squeezing independent regional distributors into secondary product categories. This concentration is most visible in Guanajuato and Querétaro, where private hospital chains have merged procurement functions under shared services organizations.
Mexico Wound Care Management Devices Market Segmentation
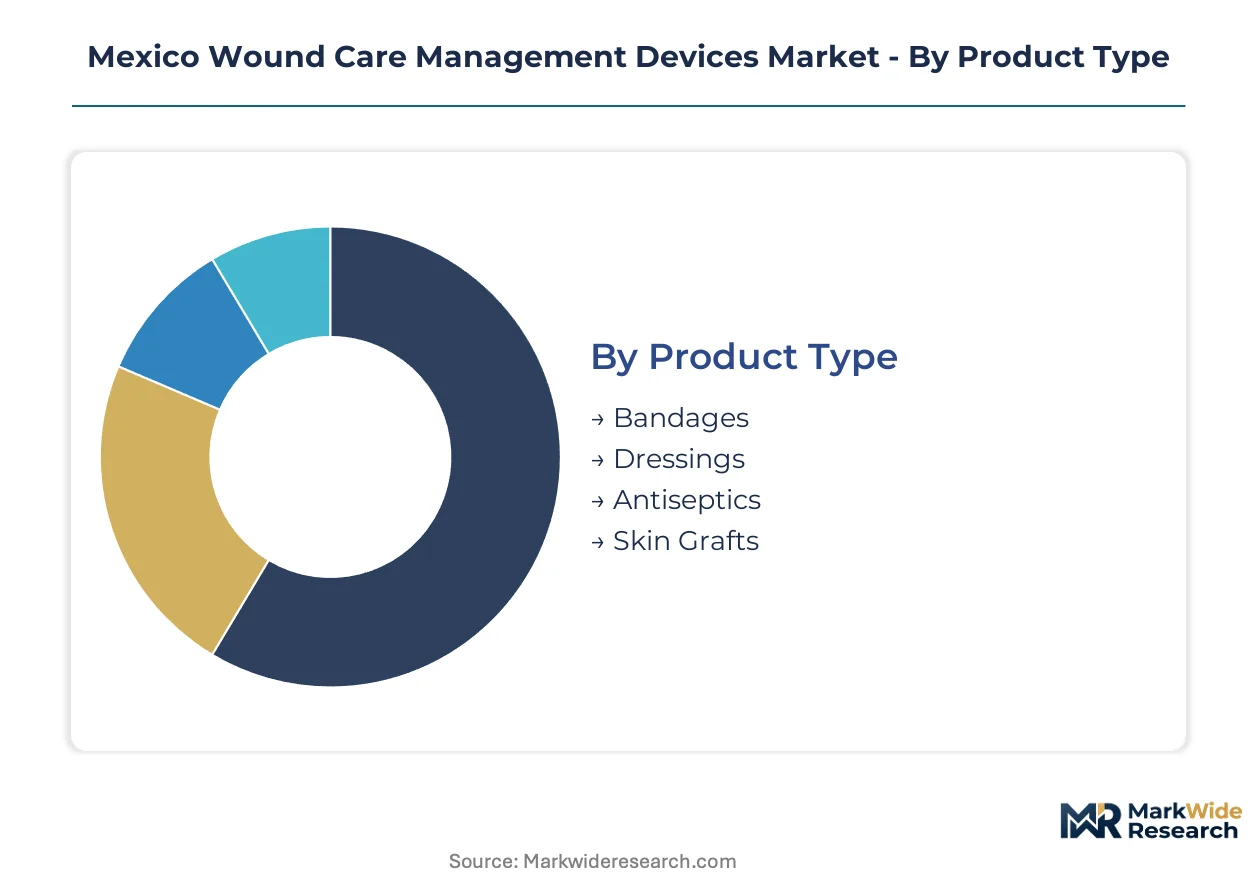
Wound care procurement in Mexico fragments across product tiers, care settings, and reimbursement pathways. Understanding substitution pressures and technology migration patterns across these dimensions determines supplier positioning and margin sustainability.
Product Type:
Conventional gauze and saline-soaked dressings exert persistent substitution pressure on premium advanced materials, particularly in public sector tenders where procurement committees prioritize unit cost over clinical outcomes.
- Dressings:Advanced alginate, foam, and hydrocolloid formulations maintain moist healing environments while managing exudate through controlled absorption. Demand concentrates in Mexico City tertiary networks where infection control protocols mandate sterile barrier properties, though COFEPRIS registration timelines compress margin structures for imported variants.
- Skin Grafts:Autologous and bioengineered substitutes serve specialized burn centers and diabetic foot clinics with restricted reimbursement pathways. IMSS formulary limitations constrain patient access in states where Seguro Popular coverage gaps persist.
- Bandages:Elastic and compression wraps support venous ulcer management and post-surgical stabilization across primary care settings.
- Antiseptics:Iodine and silver-based solutions provide antimicrobial prophylaxis prior to dressing application in outpatient wound clinics.
Dressings anchor the volume base while skin grafts gain share at the steepest rate among product categories.
End User:
Care venue migration from inpatient wards to outpatient settings is redistributing procurement authority away from hospital central supply toward specialized distributors and patient-managed therapy channels.
- Hospitals:Tertiary centers in Guadalajara and Monterrey drive procurement volumes for negative pressure systems and advanced dressings through consolidated supply chains. Group purchasing organizations now control sixty percent of advanced dressing volume, squeezing independent distributors into secondary categories.
- Home Care:Post-surgical discharge protocols from the Secretaría de Salud extend reimbursement coverage for portable negative pressure systems, enabling diabetic foot ulcer management in Yucatán and Quintana Roo resort corridor populations.
- Clinics:Outpatient wound centers in Jalisco and Nuevo León adopt miniaturized therapy devices at twice the rate of stationary systems.
- Rehabilitation Centers:Long-term care facilities manage pressure ulcer prevention through basic dressing protocols with limited technology adoption.
Hospitals retain procurement dominance while home care demonstrates the steepest expansion trajectory among end user categories.
Technology:
Active therapeutic modalities are displacing passive moisture management as the primary investment focus, with battery miniaturization and sensor integration reshaping competitive differentiation.
- Negative Pressure Therapy:Portable systems with integrated exudate measurement sensors are miniaturizing therapy for ambulatory patients. USMCA origin rule adjustments for maquiladora-manufactured devices reduce landed costs versus Asian imports, stimulating procurement volume in northern border hospitals.
- Moist Wound Healing:Hydrocolloid and foam dressings maintain established positions in post-operative care protocols across IMSS facilities where clinical specialist scarcity limits advanced technology adoption.
- Hydrogel:Amorphous and sheet formulations provide hydration for necrotic wound debridement in burn center protocols.
- Bioengineered Skin:Cultured epidermal autografts and acellular matrices remain concentrated in specialized centers with restricted formulary access.
Moist wound healing technology anchors the volume base while negative pressure therapy climbs the fastest among technology categories.
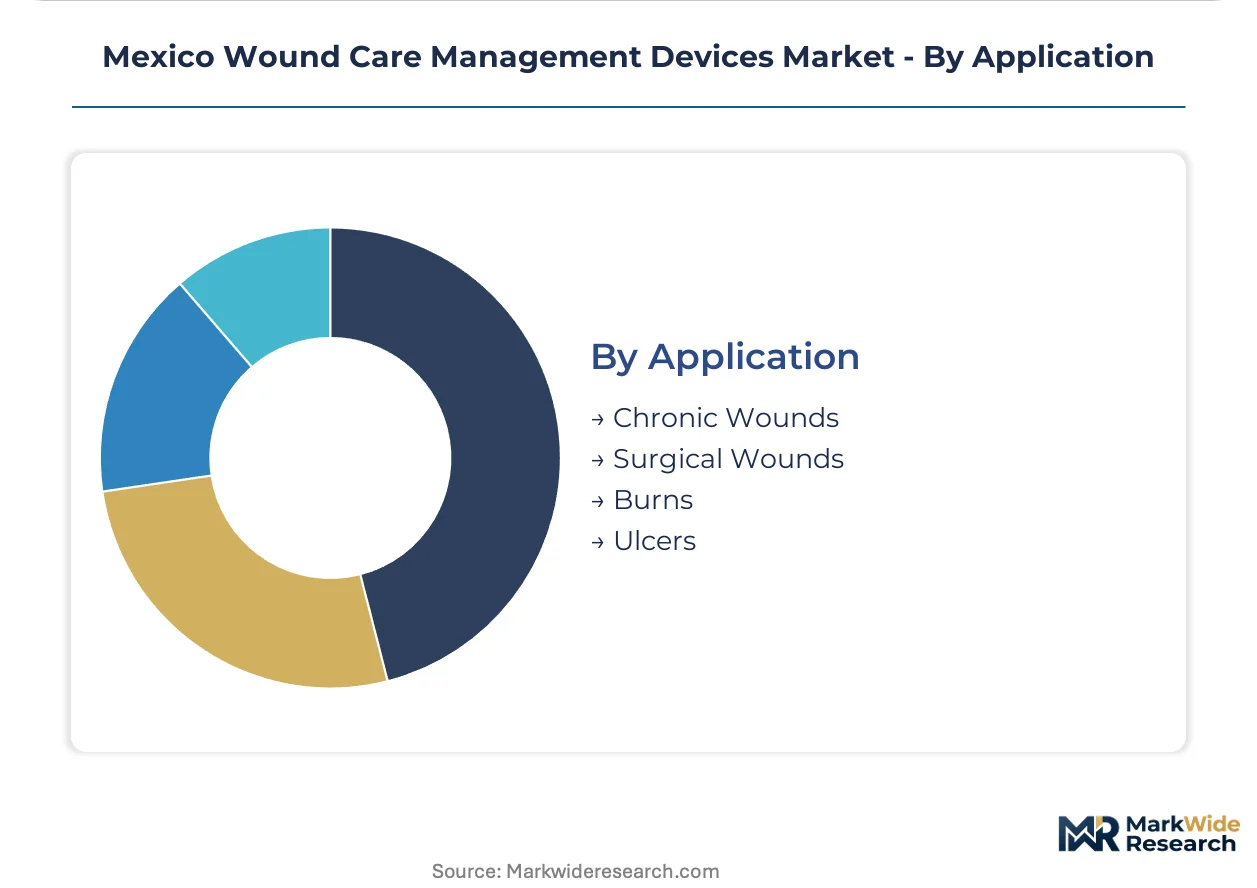
Application:
Chronic wound prevalence is expanding the addressable market beyond acute surgical applications, though reimbursement fragmentation across Seguro Popular and IMSS formularies creates access disparities.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers drive sustained demand for advanced dressings and negative pressure systems in metropolitan zones with endocrinology specialist concentration. Silver alginate substitution pressure from conventional gauze persists in secondary city public hospitals.
- Surgical Wounds:Post-operative incision management supports high-volume dressing consumption across tertiary hospital networks with centralized procurement functions.
- Burns:Thermal and chemical injuries require specialized bioengineered skin applications with concentrated demand in Mexico City burn centers.
- Ulcers:Pressure ulcer prevention protocols in rehabilitation settings generate steady demand for basic protective dressings.
Surgical wounds anchor the volume base while chronic wounds gain share at the steepest rate among application categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USMCA origin rule adjustments for maquiladora-manufactured devices are redistributing procurement advantage toward northern production zones. COFEPRIS registration timelines compress market entry windows, forcing suppliers to pre-position regulatory infrastructure before tender participation.
Mexico City Metro
Tertiary hospital networks in the capital drive procurement volumes for negative pressure systems and advanced alginate dressings. COFEPRIS maintains its headquarters here, creating regulatory proximity advantages for dossier-intensive product categories. The metropolitan health consortium centralizes supply chain decisions, squeezing independent distributors into secondary procurement tiers.
Nuevo León
Monterrey's medical device cluster offers sterilization partnerships and logistics infrastructure serving northern border hospitals. The Secretaría de Economía administers tariff classifications under USMCA provisions from this industrial hub. Maquiladora assembly operations here reduce landed costs versus Asian imports for negative pressure wound therapy systems.
Jalisco
Guadalajara health networks consolidate procurement under centralized supply chains, creating volume commitments for advanced dressing technology. Home health agencies in this state adopt miniaturized portable negative pressure devices at twice the rate of stationary systems. Outpatient wound centers here drive ambulatory therapy adoption.
Bajío Region
Group purchasing organizations in Guanajuato and Querétaro have merged procurement functions under shared services organizations. Private hospital chains here disqualify distributors without ISO 13485-certified warehousing from tender participation. This concentration squeezes independent regional distributors into secondary product categories.
Yucatán Peninsula
Resort corridor populations in Yucatán and Quintana Roo generate demand for patient-managed diabetic foot ulcer therapy outside hospital settings. Direct-to-home distribution channels bypass hospital central supply in this region. Post-surgical discharge protocols from the Secretaría de Salud extend reimbursement coverage for portable systems here.
Mexico Wound Care Management Devices Market Competitive Landscape
Player mix skews toward multinational medical device conglomerates with established regulatory dossiers. Market structure concentrates procurement influence through group purchasing organizations controlling sixty percent of advanced dressing volume. Three strategic archetypes dominate: premium-tier suppliers with COFEPRIS pre-clearances, mid-tier competitors competing on distribution breadth into secondary cities, and regional specialists leveraging maquiladora assembly for cost positioning. Competitive moves center on sterilization partnership formation in central Mexico and direct hospital contract anchoring in metropolitan zones.
Within the premium-tier segment, Smith & Nephew and Molnlycke occupy positions defined by regulatory dossier depth and direct hospital contract penetration. Cardinal Health represents the distribution-breadth archetype, extending logistics coverage into procurement-centralizing secondary markets. These three entities exemplify how competitive positioning in Mexico's wound care market derives from pre-existing regulatory infrastructure rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Smith & Nephew |
| Solventum |
| ConvaTec |
| Coloplast |
| Molnlycke |
| 3M |
| DeRoyal Industries |
| Cardinal Health |
| Medtronic |
| Others |
Pricing and Supply Chain Analysis
Silver alginate substitution for conventional gauze in secondary city public hospitals is simultaneously compressing procurement budgets and redirecting supply flows toward lower-cost Asian manufacturers, fragmenting pricing power across Mexico's wound care procurement tiers.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium advanced dressings and commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates, with COFEPRIS registration status and sterilization validation cycles as the key differentiation drivers. Cost compression in the economy tier is intensifying because Seguro Popular procurement committees prioritize unit cost over clinical outcomes. Public sector tenders exhibit the highest price sensitivity, while tertiary hospital networks in Mexico City demonstrate willingness to absorb premiums for regulatory-cleared negative pressure systems.
Supply Chain Analysis
Just-in-time inventory strategies dominate among hospital central supply departments, though ethylene oxide sterilization bottlenecks in central Mexico force strategic stockpiling of terminal-sterilized advanced dressings. Manufacturing concentrates in the United States, Ireland, and Sweden for premium-tier suppliers, while contract sterilization capacity draws from localized Mexican maquiladora partnerships. Single-source vulnerability runs through ethylene oxide sterilization infrastructure, where limited central Mexican capacity extends lead times. Distribution runs through group purchasing organizations controlling sixty percent of advanced dressing volume, with Cardinal Health and regional specialists extending logistics coverage into procurement-centralizing secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through COFEPRIS dossier depth constructs formidable defensive moats, as requalification cycles and sterilization validation requirements create switching costs that lock hospital procurement committees into established supplier relationships.
For Market Incumbents: Secure sterilization partnerships in Nuevo León and Jalisco to defend against maquiladora-assembled competitors exploiting USMCA origin advantages. Deepen backward integration into contract sterilization capacity to offset ethylene oxide bottlenecks threatening margin structures. Anchor direct hospital contracts in Guadalajara and Monterrey procurement consortiums before GPO concentration squeezes independent distributors entirely from tender participation.
For New Entrants and Emerging Players: Anchor in Yucatán Peninsula home care channels where direct-to-home distribution bypasses hospital central supply and reimbursement coverage for portable negative pressure systems is expanding. Target diabetic foot ulcer management in resort corridor populations as the most penetrable application segment. Pursue maquiladora assembly partnerships in Monterrey to exploit tariff reclassification under USMCA provisions and undercut landed costs of Asian imports.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier distributors with ISO 13485-certified warehousing and established GPO relationships in the Bajío Region, where procurement consolidation under shared services organizations is accelerating. Long-term viability hinges on regulatory infrastructure depth rather than manufacturing scale alone. Watch for NOM revision announcements as the inflection indicator forcing sterilization process revalidation and compressing margin structures during transition periods.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Acceleration | Parallel FDA 510(k) dossier structures compress approval timelines for negative pressure therapy entrants. |
| Maquiladora Sterilization Partnership | Localized ethylene oxide capacity in Nuevo León reduces customs clearance friction for northern border hospitals. |
| GPO Contract Consolidation | Shared services organizations in Guanajuato disqualify uncertified distributors from tender participation. |
| Portable System Reimbursement Strategy | Secretaría de Salud outpatient coverage extension enables patient-managed therapy in Yucatán resort corridors. |
| Antimicrobial Integration R&D | Ionic silver convergence with negative pressure systems differentiates positioning in burn center procurement. |
Research Methodology
Desk research of COFEPRIS registration databases, IMSS formulary publications, and USMCA tariff classification precedents preceded structured interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and home health agency operators. Secondary validation drew from hospital procurement databases, GPO tender documentation, and Secretaría de Economía trade statistics. Bottom-up demand modeling across product categories triangulated against top-down market sizing from import volume analysis and distributor revenue aggregation.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension: product type (dressings, skin grafts, bandages, antiseptics), end user (hospitals, home care, clinics, rehabilitation centers), technology (negative pressure, moist wound healing, hydrogel, bioengineered skin), and application (chronic wounds, surgical wounds, burns, ulcers). CAGRs derive from logistic growth curve fitting to historical adoption patterns, with negative pressure therapy penetration rates and home care protocol maturation as key wound care-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued USMCA origin rule stability and COFEPRIS alignment with FDA Medical Device Reporting standards; material deviation would warrant model refresh. Specific risk factors include NOM revision timing, ethylene oxide sterilization capacity expansion delays, and Seguro Popular formulary harmonization failures. Revision becomes warranted when reimbursement fragmentation across IMSS and Seguro Popular crosses thresholds that fundamentally alter patient access economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Irrigation Solutions Market
Wound Care
Wound Care Sealants Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Liquid Bandages Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Wound Evacuators Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Foam Dressing Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Maggot Debridement Market
Wound Care
Italy Wound Care Market
Wound Care
Vascular Dressings Market
Wound Care
Wound Care Centers Market
Wound Care
Wound Healing Nutrition Market