
 Monopolar Electrosurgery Instrument Market | 2026-2036
Monopolar Electrosurgery Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Monopolar Electrosurgery Instrument Market Intelligence
Aftermarket service revenue is reconfiguring margin capture across the monopolar electrosurgery landscape. Johnson & Johnson leverages its broad hospital contracting infrastructure to lock in multi-year instrument servicing agreements. Medtronic PLC anchors its position through deep integration of energy platforms with surgical navigation systems. Erbe Elektromedizin GmbH specializes in high-frequency generator technology that commands premium placement in European tertiary centers.
Monopolar electrosurgery instruments deliver high-frequency electrical current through a single active electrode to cut or coagulate tissue, with generators typically operating between 300 kHz and 3 MHz to minimize neuromuscular stimulation while achieving thermal tissue effect. Cutting electrodes dominate unit volume in general surgery applications where precision dissection commands priority, while coagulating electrodes capture expanding share in gynecological and urological procedures where hemostasis requirements intensify. Hospitals remain the anchor end-user segment by installed base, though ambulatory surgery centers represent the fastest-growing channel as outpatient procedural migration accelerates.
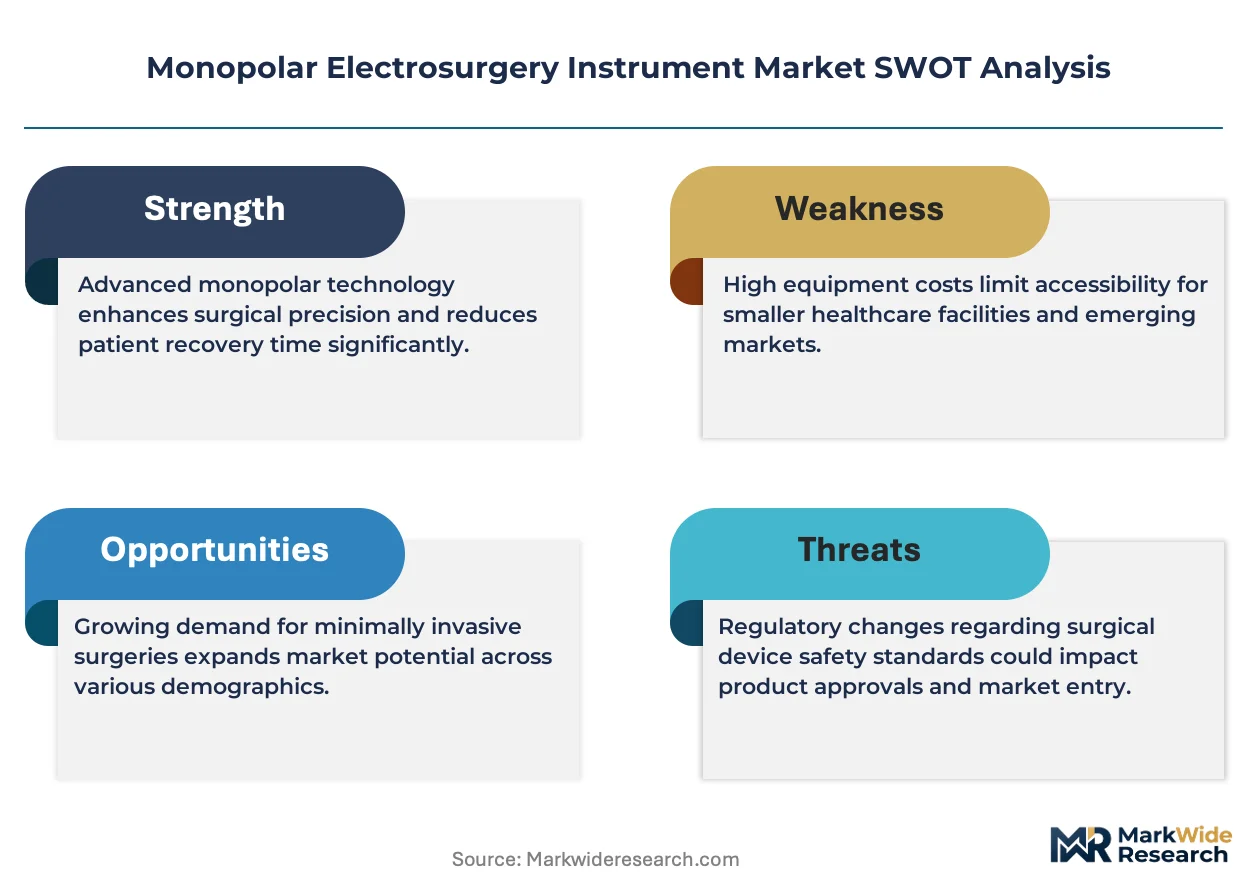
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product launch timelines and clinical evidence burdens for monopolar instrument manufacturers. ISO 13485 quality management standards and IEC 60601-2-2 electrical safety specifications govern design controls and post-market surveillance obligations across major markets. Stakeholders must monitor evolving sterilization validation requirements and single-use disposable conversion trends that threaten reusable instrument revenue streams.
Market Dynamics
EU MDR compliance deadlines are compressing product development cycles and forcing manufacturers to consolidate technical documentation portfolios ahead of notified body capacity constraints.
Growth Catalysts
- Ambulatory surgery center expansion:United States outpatient procedural migration accelerates demand for compact, portable monopolar generators that integrate with minimally invasive suites. These facilities prioritize equipment with rapid sterilization turnaround and smaller footprints.
- FDA 510(k) predicate pathway refinement:Streamlined clearance mechanisms for electrosurgical accessories reduce time-to-market for iterative electrode designs. Manufacturers leverage substantial equivalence claims to extend product families.
- Aging surgical populations in Germany and Japan:Demographic shifts sustain procedure volumes requiring hemostatic intervention. Tertiary hospitals in these markets maintain procurement budgets for premium generator platforms.
Market Restraints
- Copper and precious metal input volatility:Electrode manufacturing depends on conductive alloys subject to commodity price swings. Cost pass-through mechanisms face resistance from group purchasing organizations.
- Single-use disposable conversion:Reusable instrument revenue streams erode as hospitals adopt disposable electrodes to address sterilization validation burdens. This shift compresses service contract attach rates.
- EU MDR technical documentation requirements:Clinical evidence burdens for legacy products force portfolio rationalization. Smaller manufacturers exit rather than absorb notified body audit costs.
Strategic Opportunities
- Integration with surgical navigation systems:Energy platforms that communicate with robotic and image-guided systems command premium placement. Convergence of electrosurgery and navigation is displacing standalone generator sales in advanced centers.
- Underpenetrated Latin American markets:Brazil and Mexico present white space for mid-tier generator platforms as private hospital networks modernize. Local distributors seek exclusive representation agreements.
- Japan's reimbursement incentives for minimally invasive procedures:METI-aligned healthcare policy accelerates adoption of precision electrosurgical tools. Manufacturers with PMDA approval pathways capture preference in high-volume centers.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 series validation for new electrode coatings extends development schedules. Contract research organization capacity constraints create bottlenecks.
- Legacy generator fleet interoperability:New electrode designs must maintain compatibility with installed base units spanning multiple manufacturer generations. Engineering resources fragment across backward compatibility requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monopolar Electrosurgery Instrument Market |
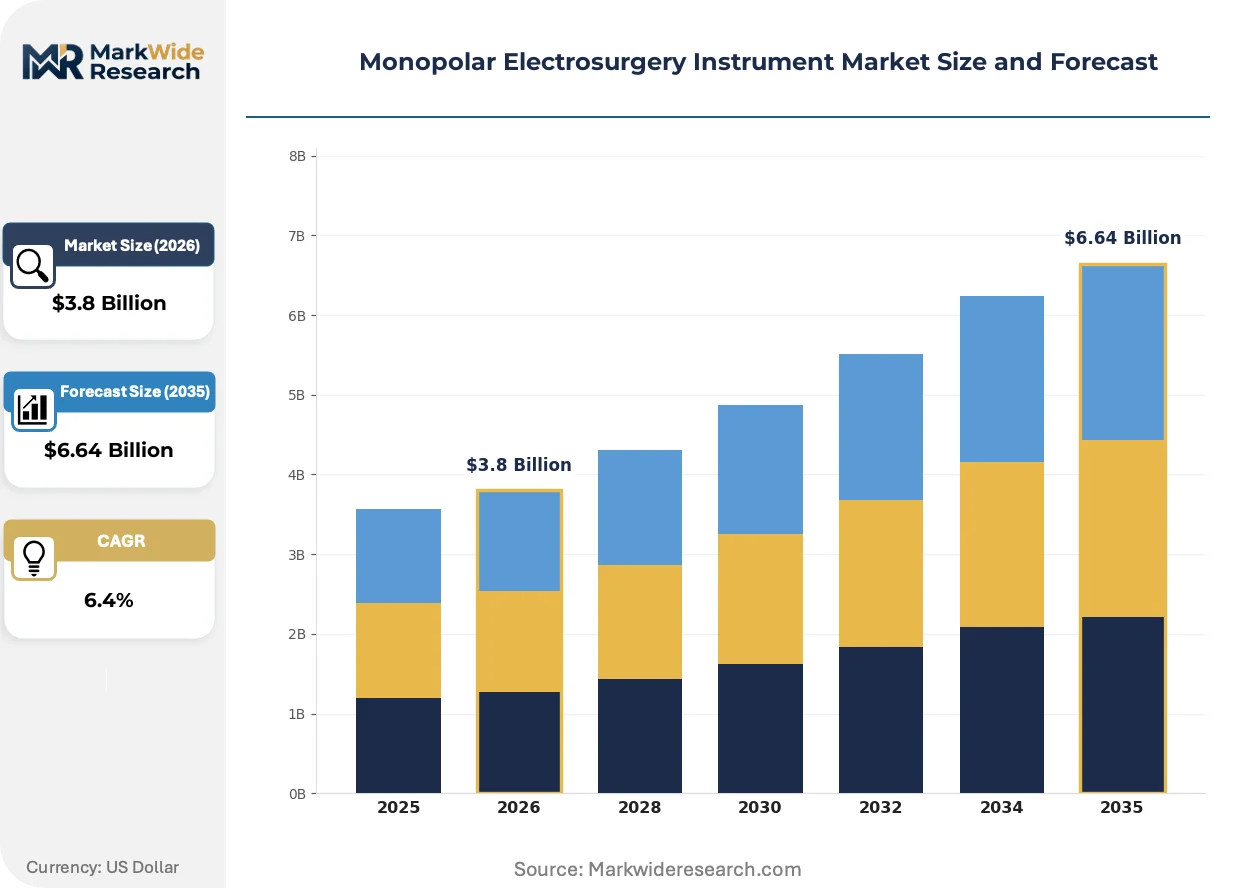
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Electrodes, Coagulating Electrodes, Blades, Accessories Application: General Surgery, Gynecology, Urology, Orthopedics End User: Hospitals, Ambulatory Surgery Centers, Clinics, Academic Institutions Technology: RF Technology, Capacitive Coupling, High-Frequency, Low-Frequency |
| Companies Covered | Apyx Medical Corporation, Johnson & Johnson, CONMED Corporation, BOWA MEDICAL, Erbe Elektromedizin GmbH, Olympus Corporation, Encision Inc., KLS Martin Group, Medtronic PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monopolar Electrosurgery Instrument Market Strategic Shifts & Innovations
Digital energy delivery algorithms and connected device architectures are reconfiguring how surgical teams interact with electrosurgical platforms, shifting value from hardware to data-enabled performance optimization.
Adaptive impedance monitoring technology is virtualizing tissue response feedback in real-time, enabling automatic power modulation during dissection. Academic medical centers in the United States and Germany are piloting these systems for complex oncologic procedures. This capability is virtualizing the role of surgeon manual adjustment, compressing training curves while raising hardware specification requirements.
EU MDR Article 10 post-market surveillance obligations now mandate systematic collection of device-related adverse events across all risk classes. Electrosurgical manufacturers must establish periodic safety update report rhythms and maintain electronic data capture infrastructure. High-frequency generator suppliers face particular scrutiny due to thermal injury reporting thresholds, driving investment in clinical follow-up networks.
Hospital procurement committees now unbundle after-sales service from capital equipment purchases, negotiating maintenance contracts through separate competitive tenders. This behavior disrupts traditional manufacturer lock-in strategies and elevates third-party service providers in the United States and Western Europe. Tertiary centers with dedicated biomedical engineering staff increasingly favor this separation to optimize total cost of ownership across mixed-vendor installed bases.
Monopolar Electrosurgery Instrument Market Segmentation
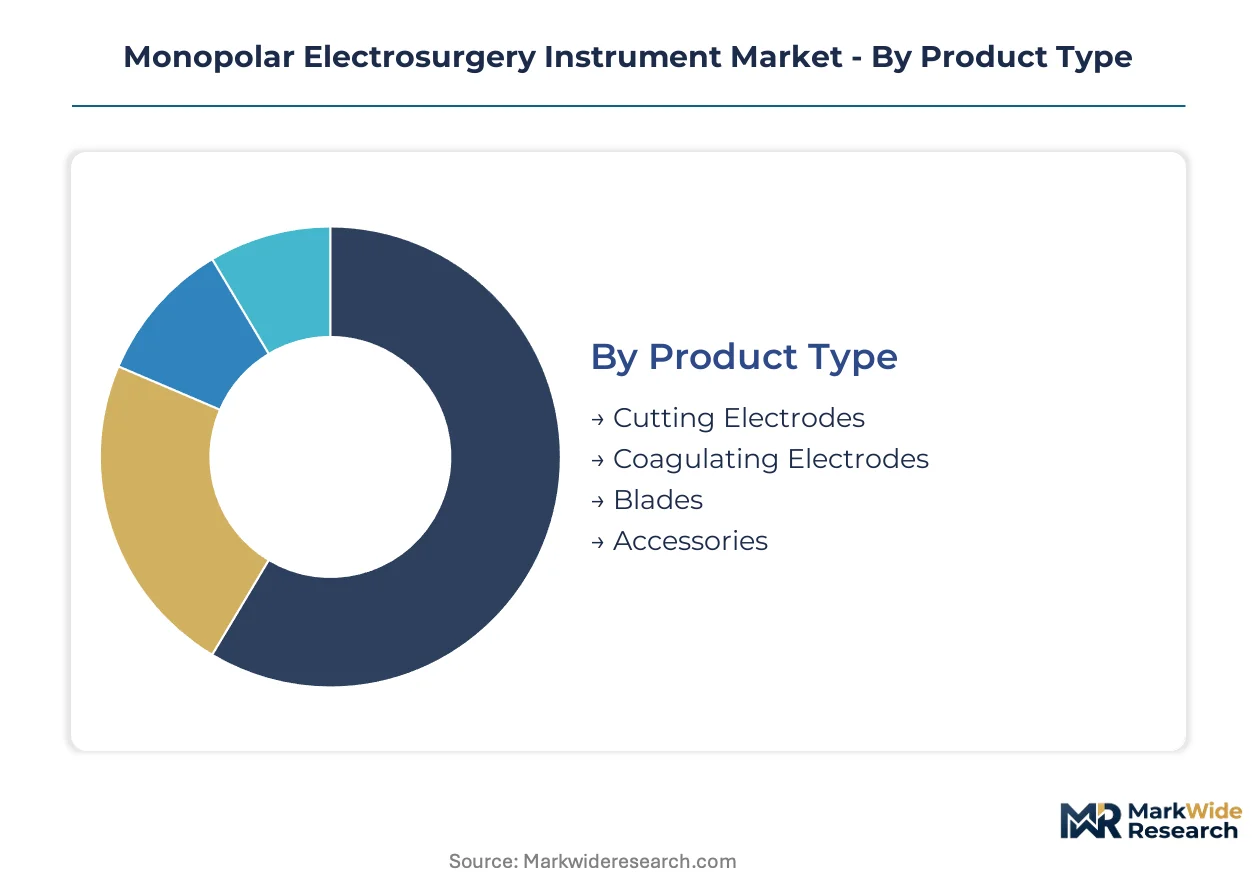
Segmentation in the monopolar electrosurgery instrument market reveals distinct procurement patterns across clinical settings and technological platforms. Electrosurgical device purchasing committees evaluate product categories against procedure-specific requirements, sterilization workflows, and capital equipment compatibility matrices.
Product Type:
Mature segments dominate revenue capture while emerging configurations reshape competitive positioning.
- Cutting Electrodes:These instruments deliver precise tissue dissection through concentrated current density at the active tip. General surgery departments in United States tertiary hospitals drive procurement volumes for laparoscopic and open procedures requiring clean incisions. FDA 510(k) predicate pathways accelerate iterative design launches for specialized tip geometries.
- Coagulating Electrodes:Designed for hemostasis through broader current dispersion patterns, these electrodes command premium placement in gynecological suites where bleeding control determines procedural efficiency. German university hospitals prioritize ball-end and needle configurations for oncologic resections.
- Blades:Disposable blade electrodes address sterilization validation burdens in high-throughput ambulatory settings.
- Accessories:Patient return electrodes and connection cables complete circuit integrity for safe energy delivery.
Cutting electrodes handle the majority of throughput; coagulating electrodes are the fastest mover on share.
Application:
Volume concentration tracks surgical procedure migration patterns across care settings.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair generate sustained electrode consumption in high-volume centers. United States community hospitals maintain standing orders for standardized electrode kits.
- Gynecology:Hysterectomy and myomectomy procedures drive demand for specialized coagulating tips with extended insulation. Japanese obstetrics-gynecology departments prioritize precision instruments under METI-aligned reimbursement incentives.
- Urology:Transurethral resection procedures require elongated electrode shafts for endoscopic access.
- Orthopedics:Soft tissue dissection in joint procedures utilizes robust electrode constructions.
General surgery commands the installed base; gynecology is climbing the fastest on procedural volume expansion.
End User:
Customer type stratification reflects capital intensity and sterilization infrastructure differentiation.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling electrodes with generator service contracts. These facilities maintain central sterile processing departments capable of reusable instrument turnaround.
- Ambulatory Surgery Centers:Outpatient procedural migration accelerates demand for single-use disposable electrodes eliminating reprocessing overhead. United States ASC chains prioritize compact generator platforms with rapid setup protocols.
- Clinics:Limited procedure volumes favor economical electrode sourcing through distributor channels.
- Academic Institutions:Teaching hospitals absorb premium pricing for advanced energy platforms supporting resident training programs.
Hospitals anchor procurement volume; ambulatory surgery centers are expanding most quickly as procedural sites shift.
Technology:
Platform architecture determines compatibility matrices and upgrade pathway economics.
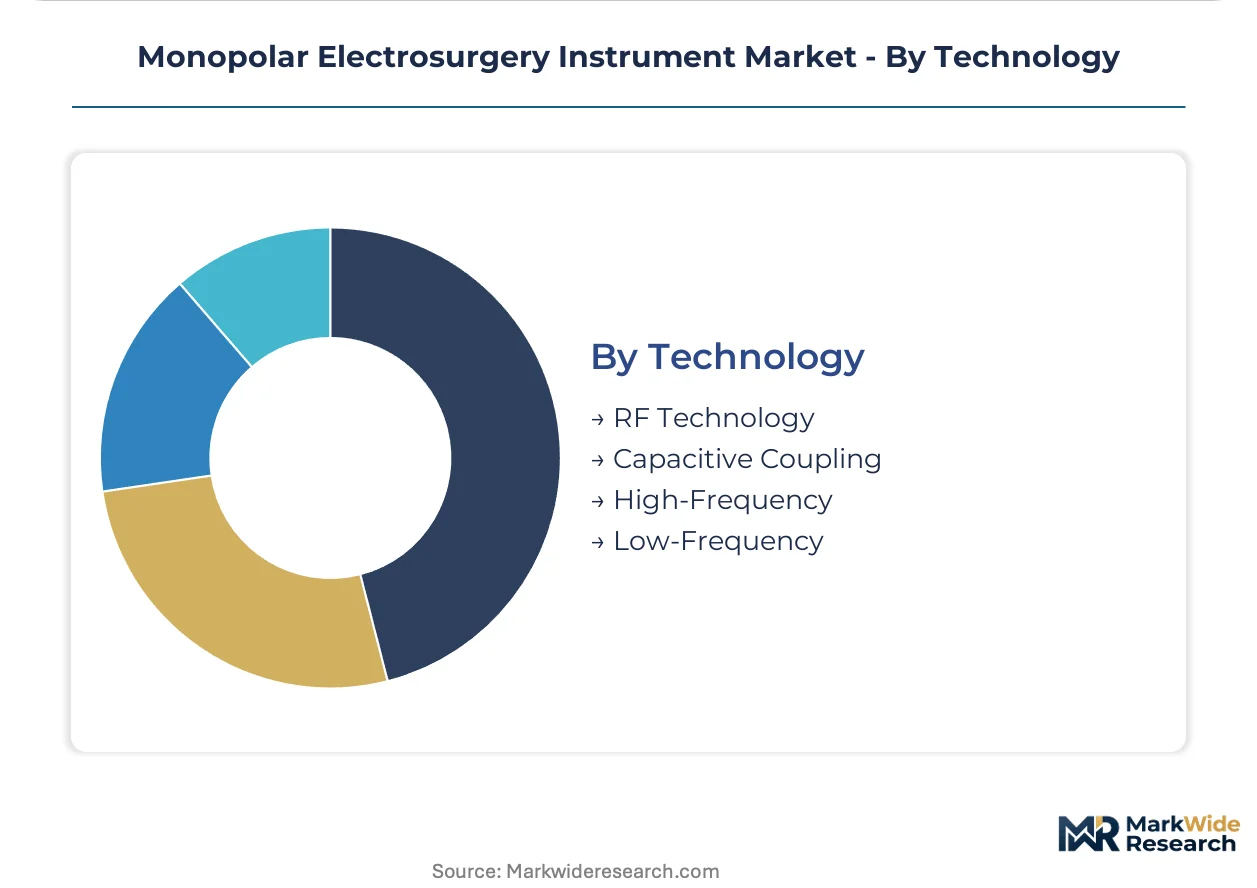
- RF Technology:Radiofrequency generators operating between 300 kHz and 3 MHz constitute the dominant installed base. Medtronic PLC and Johnson & Johnson anchor their energy platforms on proprietary RF algorithms with tissue response feedback.
- Capacitive Coupling:Emerging architectures reduce direct tissue contact requirements, enabling novel electrode form factors for confined anatomical spaces. German manufacturers pilot these systems in minimally invasive oncology applications.
- High-Frequency:Extended frequency ranges support rapid cutting modes with minimized thermal spread.
- Low-Frequency:Reduced frequency settings address specialized coagulation requirements in delicate tissue planes.
RF technology handles the majority of installed generators; capacitive coupling is gaining share fastest on innovation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. United States hospital networks negotiate aggressive group purchasing terms, while Japanese tertiary centers absorb premium pricing for precision platforms. German university hospitals balance cost discipline with technology advancement mandates.
United States
Ambulatory surgery center expansion and outpatient procedural migration drive compact generator demand. FDA 510(k) clearance pathways accelerate iterative electrode launches for specialized tip geometries. Texas and Florida ASC chains prioritize rapid sterilization turnaround equipment.
Germany
Aging surgical populations sustain hemostatic intervention volumes in oncologic resections. EU MDR technical documentation requirements compress product development cycles ahead of notified body capacity constraints. Baden-Württemberg and Bavaria anchor European tertiary center procurement.
Japan
METI-aligned reimbursement incentives accelerate minimally invasive procedure adoption. PMDA approval pathways capture preference in high-volume Tokyo and Osaka centers. Kanto region hospitals maintain budgets for precision electrosurgical tool procurement.
China
Private hospital network modernization expands mid-tier generator platform demand. NMPA regulatory harmonization streamlines import clearance for energy delivery systems. Yangtze River Delta surgical centers pilot advanced impedance monitoring technologies.
Brazil
Private hospital network expansion creates white space for distributor-exclusive representation agreements. ANVISA registration requirements shape product localization strategies. São Paulo and Rio de Janeiro metropolitan areas concentrate procurement decision-making.
Monopolar Electrosurgery Instrument Market Key Industry Players
Capability concentration sits with specialized high-frequency generator developers; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: integrated energy platform providers, electrode manufacturing specialists, and regional distribution-focused entities. Dominant competitive moves include strategic partnerships with surgical navigation system developers and portfolio rationalization ahead of EU MDR compliance deadlines.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic PLC occupy positions anchoring integrated energy platform strategies. Erbe Elektromedizin GmbH represents the specialized generator technology archetype with European manufacturing heritage. These three entities exemplify distinct competitive vectors: multi-year hospital contracting infrastructure, surgical navigation integration capabilities, and premium tertiary center placement respectively.
| Leading Market Players |
|---|
| Apyx Medical Corporation |
| Johnson & Johnson |
| CONMED Corporation |
| BOWA MEDICAL |
| Erbe Elektromedizin GmbH |
| Olympus Corporation |
| Encision Inc. |
| KLS Martin Group |
| Medtronic PLC |
| Others |
Cost & Logistics Intelligence
Copper and precious metal commodity volatility determines both pricing tier spreads and supply chain shape across monopolar electrosurgery manufacturing. Electrode producers face margin compression when conductive alloy costs spike, forcing tiered pricing structures that separate premium generator-integrated platforms from standard disposable electrodes and economy-grade accessories.
Pricing Analysis
After-sales service revenue tiers drive lifetime value capture for monopolar electrosurgery manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates integrated energy platforms with multi-year maintenance contracts from standalone generators and disposable electrode SKUs. Price differentiation hinges on ISO 13485 certification grade and after-sales bundling intensity. Cost compression in the standard tier intensifies because group purchasing organizations resist full alloy cost pass-through. Ambulatory surgery centers exhibit highest price sensitivity; German tertiary centers absorb premium pricing for precision platforms with navigation integration.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for electrode manufacturers. Component sourcing concentrates in Germany, Switzerland, and Malaysia for precision-machined conductive tips and high-frequency generator subassemblies. Raw material procurement draws from Chilean copper suppliers, South African platinum group metal refiners, and Chinese rare earth processors. Single-source vulnerability persists for specialized high-frequency capacitors used in generator power modulation circuits. Distribution runs through hospital group purchasing organizations in North America and specialized surgical device distributors in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines constitute a regulatory inflection accelerating consolidation among monopolar electrosurgery manufacturers. This disruption concentrates capability among firms with notified body relationships and clinical evidence infrastructure.
For Market Incumbents: Harden market position through backward integration into high-frequency generator core component manufacturing and exclusive long-term service contracts with United States integrated delivery networks. Medtronic PLC and Johnson & Johnson already anchor energy platform strategies; smaller competitors must match their hospital contracting infrastructure or cede procurement committee influence. Priority investment targets ISO 13485-certified electrode coating facilities to compress biocompatibility validation timelines. For New Entrants and Emerging Players: Build out specialized capacitive coupling electrode portfolios for minimally invasive oncology applications where German academic medical centers pilot novel form factors. Brazil and Mexico present the most penetrable geographies for mid-tier generator platforms, with São Paulo private hospital networks actively seeking distributor-exclusive representation. Go-to-market execution should prioritize ANVISA registration pathway expertise and local clinical training partnerships over direct sales infrastructure. For Investors and Strategic Acquirers: EU MDR Article 10 post-market surveillance obligations reshape the acquisition landscape toward firms with established clinical follow-up networks and electronic data capture infrastructure. Long-term viability across the next decade favors targets with PMDA approval pathways in Japan and FDA 510(k) predicate libraries in the United States. Acquisition target archetype: specialized high-frequency generator developers with European manufacturing heritage and tertiary center placement. Signal to watch: notified body audit queue compression forcing portfolio rationalization among sub-scale manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Consolidation | Notified body capacity constraints force portfolio rationalization ahead of compliance deadlines. |
| Surgical Navigation System Integration | Energy platforms communicating with robotic systems command premium placement in advanced centers. |
| Single-Use Disposable Electrode Conversion | Hospitals adopting disposable SKUs eliminate sterilization validation burdens and reprocessing overhead. |
| Adaptive Impedance Monitoring Deployment | Real-time tissue response feedback virtualizes surgeon manual adjustment in complex oncologic procedures. |
| Latin American Distributor Partnership Expansion | Brazil and Mexico private hospital networks seek exclusive representation for mid-tier generator platforms. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and electrosurgical device manufacturing executives. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, hospital procurement contract repositories, and ISO 13485 certification registries. Bottom-up electrode unit volume estimates triangulated against top-down generator installed base calculations across the analysis window.
Calibration against historical procedure volume data and capital equipment replacement cycles anchored the analytical framework. Segmentation dimensions modeled include product type, application specialty, end-user facility category, and technology platform architecture. CAGRs were derived from regression analysis of procedural migration patterns and reimbursement incentive alignment. Forecast inputs incorporated METI-aligned policy trajectories in Japan and outpatient procedural shift rates in United States ambulatory settings.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese mid-tier generator manufacturers or accelerated single-use disposable conversion by United States ASC chains would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Disposable Surgical Devices Market