
 Global Surgical Stapler Market | 2026-2036
Global Surgical Stapler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Stapler Market Foresight
Multi-source procurement of stapling cartridges is shifting toward captive supply arrangements among top-tier manufacturers. Medtronic Plc anchors its position through backward integration into reload production. Johnson & Johnson (Ethicon, Inc.) leverages its suture-stapler portfolio synergy to control hospital formulary access. B. Braun SE competes on European manufacturing scale with dedicated cleanroom assembly for sterile disposable reloads.
A surgical stapler is a mechanical medical device that deploys preformed titanium or stainless steel staples to create anastomoses or close tissue incisions during open and minimally invasive procedures, typically firing 6-8 rows of staples simultaneously with integrated blade systems for tissue transection. The device serves to reduce operative time, standardize wound closure quality, and minimize tissue trauma compared to manual suturing. Powered staplers now lead capital equipment sales as hospitals prioritize ergonomic firing mechanisms that reduce hand fatigue during lengthy laparoscopic cases. Disposable staplers and reloads capture recurring revenue streams with higher margin profiles than reusable instrument platforms. General surgery applications dominate procedure volume, while cardiothoracic and gynecological segments offer premium pricing for specialized articulating cartridges.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for stapler manufacturers seeking market access. ISO 13485 quality management standards govern manufacturing consistency across global production networks, with notified bodies conducting unannounced audits of sterilization validation protocols. Stakeholders must monitor evolving FDA guidance on powered surgical stapler malfunctions and corresponding design control expectations for next-generation firing systems.
Market Dynamics
Powered stapling systems are compressing the competitive landscape by rewarding manufacturers with in-house battery and motor engineering capabilities, while disposable reload economics lock hospitals into recurring procurement relationships that favor scale players.
Growth Catalysts
- EU MDR conformity pathways:Stricter clinical evidence requirements for Class IIb surgical devices are accelerating hospital preference toward established manufacturers with robust technical documentation and notified body relationships.
- Ambulatory surgical centers:Same-day discharge protocols for bariatric and colorectal procedures are expanding addressable procedure volumes beyond traditional inpatient settings.
- Titanium-nitride coated staple lines:Enhanced staple formation consistency in thick tissue applications is reducing anastomotic leak rates and driving premium cartridge uptake in cardiothoracic suites.
Market Restraints
- Supply concentration in precision motor manufacturing:Miniature DC motors and gearboxes for powered handles concentrate among Japanese and German component suppliers, creating input bottlenecks during demand surges.
- Staple material cost volatility:Medical-grade titanium wire pricing fluctuates with aerospace demand cycles, compressing reload margins during commodity spikes.
- Reusable platform persistence:Cost-conscious public health systems in Eastern Europe and Latin America continue manual stapler use, limiting premium device penetration.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting component suppliers to establish cleanroom facilities near Hyderabad and Bengaluru, reducing import dependency for South Asian markets.
- Natural orifice specimen extraction:NOTES-compatible articulating staplers enable single-incision colorectal resections, opening premium positioning in academic medical centers pursuing scarless surgery differentiation.
- RFID-enabled cartridge tracking:Integration of wireless authentication into reload packaging supports hospital inventory automation and expiration management, creating software-adjacent revenue streams.
Industry Challenges
- EU MDR technical documentation remediation:Legacy device portfolios require substantial clinical data supplementation for recertification, straining regulatory affairs bandwidth across mid-tier manufacturers.
- Legacy ERP integration with serialized device tracking:Hospital customers demand real-time staple usage data feeds into their procurement systems, forcing stapler vendors to maintain multiple middleware compatibility layers.
- Cleanroom technician scarcity:Sterile disposable assembly requires specialized aseptic technique certification that outpaces vocational training program output in key manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Stapler Market |
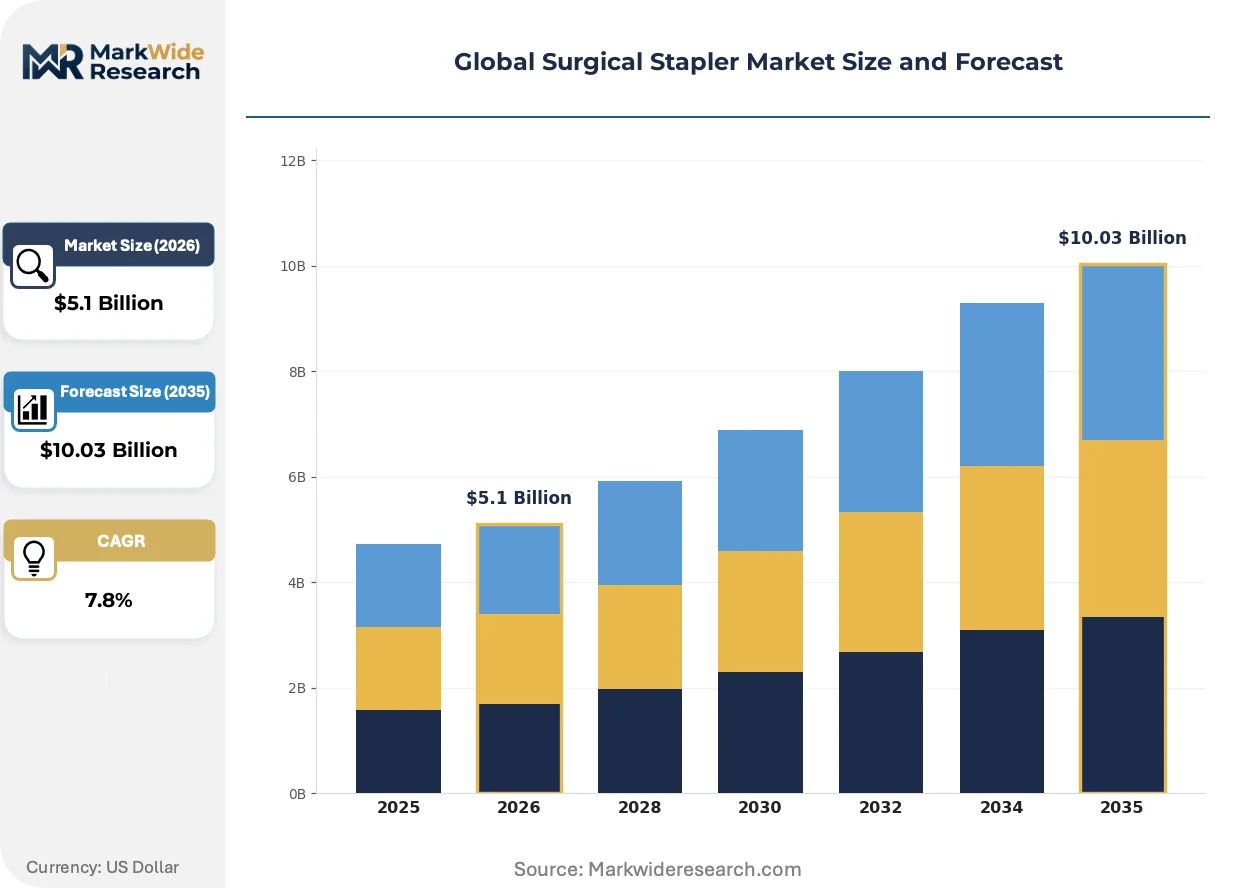
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.03 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Staplers, Powered Staplers, Disposable Staplers, Reloads Application: General Surgery, Cardiothoracic Surgery, Gynecological Surgery, Orthopedic Procedures, Neurosurgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Teaching Institutions Technology: Linear Stapling, Circular Stapling, Cartridge Reload, Articulating Mechanism |
| Companies Covered | Conmed Corporation, 3M Company, Medtronic Plc, Lepu Medical Technology (Beijing) Co., Ltd., Smith+Nephew, Johnson & Johnson (Ethicon, Inc.), B. Braun SE, Purple Surgical, Intuitive Surgical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Stapler Market Shifts & Advancements
Battery-integrated firing mechanisms and smart cartridge recognition are redefining device architecture, while regulatory data requirements push manufacturers toward embedded sensing and automated documentation.
Smart staplers with integrated load-sensing algorithms are decentralizing tissue compression decisions from surgeon tactile feedback to real-time motor torque modulation. Academic medical centers in the United States and Germany are piloting these systems for consistent staple formation across trainee skill levels. This capability shift is compressing the performance gap between high-volume specialists and general surgeons, altering training program equipment specifications.
FDA guidance on powered surgical stapler malfunctions issued in 2019 continues reshaping design control documentation expectations for next-generation firing systems. Manufacturers must now submit comprehensive malfunction complaint trending and root cause analysis for 510(k) submissions. Cardiothoracic stapler lines face the steepest compliance burden given the severity consequences of misfires in vascular tissue.
Hospital value analysis committees now mandate total cost-of-ownership modeling that bundles device price with leak-rate outcomes and operative time savings. Integrated delivery networks in the United States are consolidating formulary decisions to system-level contracts, displacing individual hospital purchasing autonomy. This concentration is visible most acutely in the Midwest and Southeast regions where Catholic health systems and for-profit chains command multi-hospital scale.
Global Surgical Stapler Market Segmentation
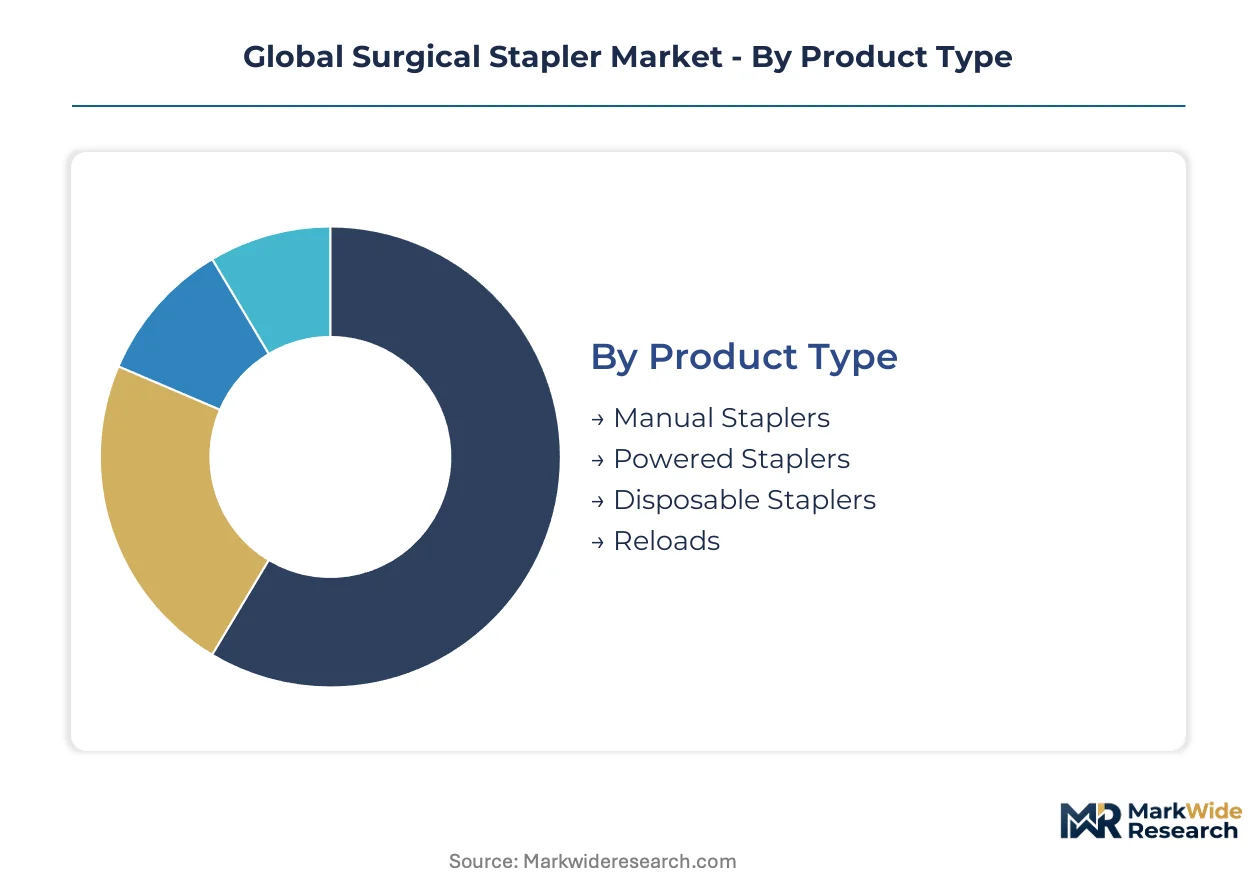
Surgical stapler segmentation reveals how regulatory burden, technology complexity, and procurement economics fragment commercial opportunity across distinct customer workflows. Manufacturers must align certification investment with segment-specific margin profiles and replacement cycle dynamics.
Product Type:
FDA 510(k) pathways dominate manual and disposable stapler approvals, while powered systems face escalating clinical evidence demands under EU MDR Class IIb designations. Battery-integrated handles require additional electromagnetic compatibility testing beyond mechanical stapler submissions.
- Manual Staplers:Hand-actuated mechanical devices with stainless steel firing mechanisms and fixed anvil configurations. Demand concentrates in Eastern European public hospitals and Latin American tier-2 facilities where capital constraints limit powered system procurement. Reusable platform economics sustain procurement despite ergonomic limitations.
- Powered Staplers:Motor-driven firing systems with integrated battery packs and programmable compression algorithms. United States academic medical centers drive specification, prioritizing torque consistency across trainee surgeons and reduced hand fatigue during multi-hour laparoscopic cases. FDA malfunction guidance has lengthened design control documentation cycles.
- Disposable Staplers:Single-use sterile devices preloaded with titanium staple cartridges, eliminating reprocessing logistics. Ambulatory surgery centers favor the inventory simplicity and infection control certainty.
- Reloads:Sterile disposable cartridges containing preformed staple lines and cutting blades, generating recurring revenue streams with higher margin profiles than instrument handles. German and Japanese component suppliers dominate precision motor and gearbox inputs.
Leading the category by volume: Reloads. Growing fastest: Powered Staplers.
Application:
Procedure complexity determines cartridge specification, with tissue thickness and vascularity driving staple line selection across surgical disciplines.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair procedures utilizing linear and circular stapling configurations. High-volume community hospitals in the United States and China generate baseline demand for standard cartridge formats.
- Cardiothoracic Surgery:Vascular anastomosis and lung resection applications requiring titanium-nitride coated staples for thick tissue penetration. German cardiothoracic suites drive premium articulating cartridge uptake, with leak-rate outcomes directly impacting device selection.
- Gynecological Surgery:Hysterectomy and ovarian procedure applications with specialized curved cartridge geometries for pelvic access. United States integrated delivery networks consolidate formulary decisions for these procedures.
- Orthopedic Procedures:Soft tissue approximation in joint reconstruction and trauma fixation, utilizing heavy-duty staple configurations. Demand concentrates in academic medical center orthopedic departments.
- Neurosurgery:Cranial and spinal dural closure applications with microstaple formats requiring extreme precision. Smallest addressable volume but highest per-procedure device cost.
General Surgery commands absolute procedure volume. Cardiothoracic Surgery shows the steepest expansion trajectory in premium device value.
End User:
Capital allocation authority and reimbursement frameworks segment purchasing behavior across institutional settings.
- Hospitals:Inpatient surgical departments with centralized procurement committees negotiating system-level contracts. United States Catholic health systems and for-profit chains in the Midwest and Southeast command multi-hospital scale for formulary consolidation.
- Ambulatory Surgery Centers:Same-day discharge facilities expanding bariatric and colorectal procedure volumes beyond traditional inpatient settings. Medicare reimbursement shifts accelerate capital equipment refresh cycles.
- Specialty Clinics:Focused surgical practices in ophthalmology, dermatology, and plastic surgery with limited stapler utilization. Procurement concentrates on disposable formats for occasional use.
- Teaching Institutions:Academic medical centers in Germany and the United States piloting smart stapler systems with load-sensing algorithms. Training program equipment specifications favor consistent performance across resident skill levels.
Hospitals dominate installed base. Ambulatory Surgery Centers are climbing the fastest as site-of-care migration accelerates.
Technology:
Mechanical architecture determines manufacturing complexity and sterile assembly requirements.
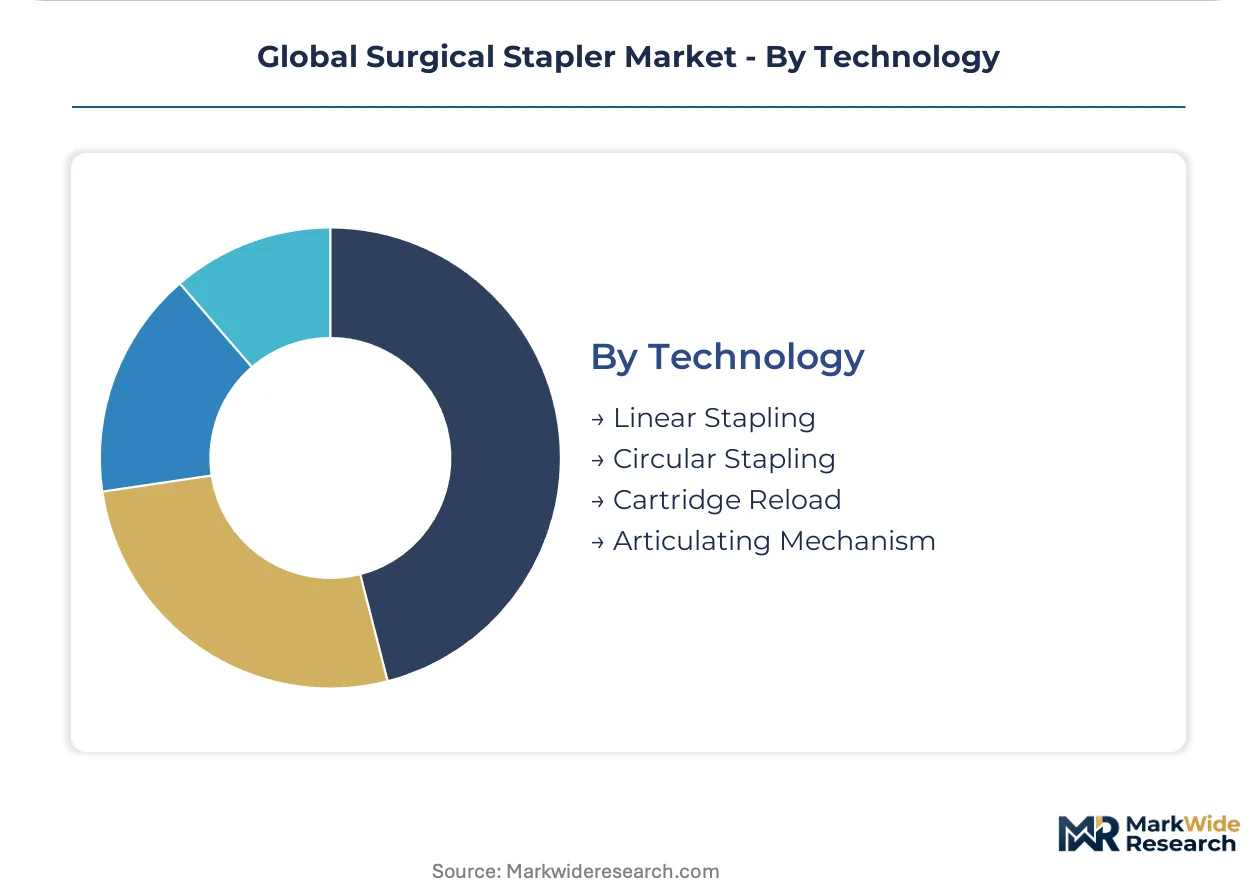
- Linear Stapling:Straight-line staple deployment for tissue transection and closure, dominating general surgery applications. Cleanroom assembly concentrates in European manufacturing facilities with dedicated sterile reload production.
- Circular Stapling:Cylindrical staple formation for end-to-end anastomosis in colorectal and esophageal procedures. Higher device cost reflects complex anvil and cartridge alignment mechanisms.
- Cartridge Reload:Modular staple loading systems enabling rapid intraoperative format switching. RFID-enabled authentication variants support hospital inventory automation.
- Articulating Mechanism:Multi-axial head rotation for natural orifice and single-incision access. NOTES-compatible configurations command premium positioning in academic centers pursuing scarless surgery differentiation.
Linear Stapling leads procedure volume. Articulating Mechanism is expanding most quickly in minimally invasive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium wire feedstock from Japanese and German precision metal suppliers anchors the geographic distribution of surgical stapler manufacturing, with final assembly clustering near major hospital procurement networks in North America, Western Europe, and East Asia.
United States
Academic medical centers in Boston and the Research Triangle drive specification for powered stapling systems with load-sensing algorithms. FDA 510(k) clearance pathways and 2019 malfunction guidance shape design control documentation for next-generation firing mechanisms. Minneapolis anchors Medtronic's backward integration into reload production with dedicated cleanroom facilities.
Germany
Cardiothoracic suites in Heidelberg and Berlin command premium articulating cartridge uptake based on leak-rate outcome data. EU MDR Class IIb conformity assessments and notified body relationships favor established manufacturers with robust technical documentation. B. Braun SE maintains European manufacturing scale with sterile disposable assembly in Melsungen.
China
Domestic surgical volumes in Shanghai and Guangzhou accelerate demand for cost-optimized linear stapling configurations. NMPA regulatory pathways and hospital procurement centralization under volume-based purchasing compress pricing for standard cartridge formats. Hyderabad and Bengaluru component clusters reduce import dependency through India's PLI scheme spillover effects.
Japan
Precision motor and gearbox suppliers in Nagoya and Osaka concentrate inputs for powered handle manufacturing. PMDA quality management standards and METI industrial policy support domestic device assembly for East Asian export markets. Miniature DC motor production bottlenecks during demand surges create regional supply constraints.
India
Tier-2 hospital expansion in Maharashtra and Karnataka sustains manual stapler demand amid capital constraints. CDSCO medical device regulations and domestic manufacturing incentives under the PLI scheme attract cleanroom facility investment near Hyderabad. Cost-conscious public procurement limits premium powered system penetration outside academic medical centers.
Global Surgical Stapler Market Competitive Landscape
Backward integration into reload production dominates the current landscape as manufacturers seek captive supply arrangements and margin protection. The vendor base concentrates among three to five scale players with in-house sterile assembly capabilities, while mid-tier competitors face EU MDR technical documentation remediation burdens. Two strategic archetypes prevail: diversified medical technology conglomerates with suture-stapler portfolio synergies, and specialized surgical instrument manufacturers with European cleanroom scale. M&A activity and capacity expansion in South Asian component clusters represent the dominant competitive moves.
Among diversified technology conglomerates, Medtronic Plc and Johnson & Johnson (Ethicon, Inc.) exemplify the integrated portfolio archetype with formulary control capabilities. B. Braun SE occupies a position within the European manufacturing specialist tier. Lepu Medical Technology (Beijing) Co., Ltd. represents the Asia-Pacific scale challenger archetype. These three anchors demonstrate how geographic manufacturing concentration and regulatory relationships determine competitive positioning across manual, powered, and disposable product categories.
| Leading Market Players |
|---|
| Conmed Corporation |
| 3M Company |
| Medtronic Plc |
| Lepu Medical Technology (Beijing) Co., Ltd. |
| Smith+Nephew |
| Johnson & Johnson (Ethicon, Inc.) |
| B. Braun SE |
| Purple Surgical |
| Intuitive Surgical Inc. |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States Midwest and Southeast command multi-hospital scale that compresses pricing into system-level contracts, displacing individual hospital purchasing autonomy and forcing manufacturers toward bundled service agreements to defend margin.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium powered stapler contracts from unbundled disposable reload transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in standard linear staplers intensifies because NMPA volume-based purchasing in China and CDSCO cost-conscious procurement in India limit premium penetration. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while German cardiothoracic suites show lowest sensitivity given leak-rate outcome prioritization.
Supply Chain Analysis
Refurbishment and remanufacturing flows for reusable manual stapler handles concentrate in Eastern European service depots, though disposable cartridge growth diminishes reverse-logistics volume. Precision motor and gearbox manufacturing anchors in Japan and Germany, while titanium wire feedstock draws from Japanese and German precision metal suppliers. Single-source vulnerability in miniature DC motor production creates bottlenecks during demand surges. Distribution runs through GPO contracts in the United States and hospital procurement centralization in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with in-house sterile assembly capabilities, as EU MDR technical documentation remediation burdens force mid-tier competitors toward exit or acquisition.
For Market Incumbents: Hedge against commodity volatility through backward integration into titanium wire processing and captive reload production. Expand cleanroom capacity near Hyderabad to exploit India's PLI scheme spillover effects. Battery engineering capabilities represent the priority defensive lever against powered system commoditization.
For New Entrants and Emerging Players: Capture white-space in RFID-enabled cartridge authentication and software-adjacent inventory management solutions. India's tier-2 hospital expansion offers the most penetrable geography given capital constraints limiting premium device uptake. Pursue hospital system partnerships through GPO channel access rather than direct formulary displacement.
For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with EU MDR technical documentation already remediated and established notified body relationships. Long-term viability rests on sterile assembly scale and regulatory bandwidth rather than product innovation alone. Monitor FDA guidance evolution on powered stapler malfunction reporting as inflection indicator for design control investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reload Production | Medtronic's Minneapolis cleanroom facilities demonstrate margin protection through captive titanium staple cartridge supply. |
| EU MDR Technical Documentation Remediation | B. Braun's Melsungen sterile assembly investments satisfy notified body expectations for Class IIb device recertification. |
| RFID-Enabled Cartridge Authentication | Wireless reload tracking supports hospital inventory automation and creates software-recurring revenue streams. |
| India PLI Scheme Manufacturing Expansion | Hyderabad and Bengaluru component clusters reduce import dependency for South Asian surgical stapler markets. |
| Hospital System Partnership Development | Ethicon's suture-stapler portfolio synergy controls formulary access across Catholic health system networks. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR conformity assessment durations, and hospital procurement contract values anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and sterile processing department heads. Secondary validation drew from FDA malfunction complaint databases, CMS Medicare reimbursement schedules, NMPA volume-based purchasing announcements, and ISO 13485 audit records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation.
Input-output matrices mapped surgical stapler shipments across product type, application specialty, end-user facility class, and technology architecture throughout the projection horizon. CAGRs derived from logistic diffusion curves fitted to powered system adoption patterns and manual platform replacement cycles. Titanium wire pricing volatility and precision motor supply constraints informed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, aerospace demand cycles affecting titanium feedstock, and FDA guidance evolution on smart stapler classification. Practitioners should monitor powered stapler malfunction complaint trending and hospital value analysis committee consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
US Surgical Sutures Market