
 US Veterinary Surgical Instruments Market | 2026-2036
US Veterinary Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
US Veterinary Surgical Instruments Market Analysis
Aftermarket service revenue for instrument refurbishment and sterilization validation is fragmenting across regional service depots and manufacturer-direct programs. B. Braun Vet Care leverages its centralized reprocessing infrastructure to capture recurring maintenance contracts. Medtronic competes through proprietary sterilization container systems that lock in multi-year service agreements. Jorgensen Laboratories specializes in regional distributor partnerships that extend repair turnaround advantages to independent practices.
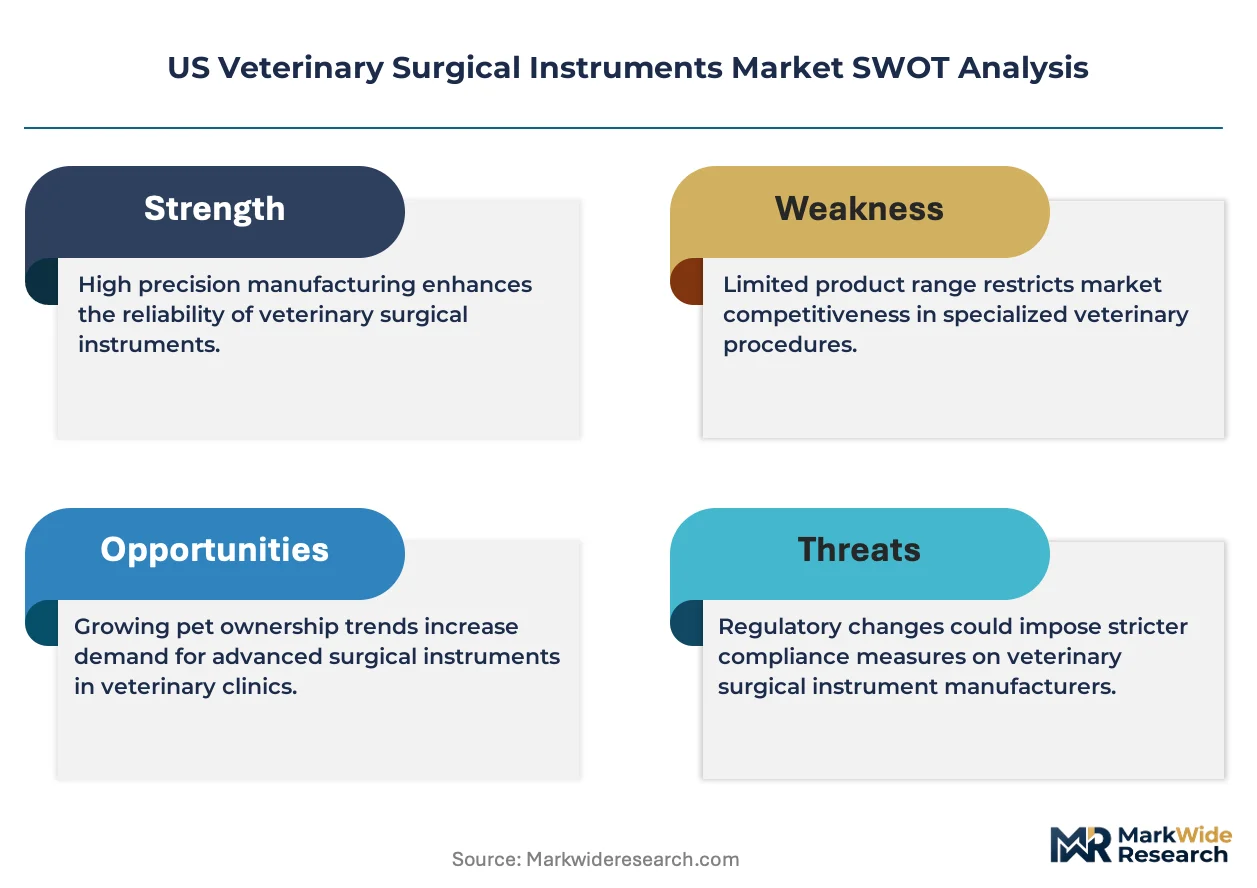
US veterinary surgical instruments encompass precision-engineered hand tools, powered devices, and ancillary equipment fabricated from medical-grade stainless steel, titanium alloys, and carbon steel composites, designed for sterile intervention in animal patients ranging from companion animals to livestock. Their primary purpose is to enable tissue dissection, hemostasis, bone manipulation, and minimally invasive access with biocompatibility and corrosion resistance meeting surgical standards. Scalpel and scissors categories anchor the product mix due to universal procedural necessity and shorter replacement cycles, while laparoscopic surgery application segments attract premium pricing as veterinary practices invest in video-assisted platforms. Titanium material grades command expanding preference in orthopedic suites where instrument weight reduction and magnetic resonance imaging compatibility reduce surgical fatigue and imaging conflicts.
FDA Center for Veterinary Medicine oversight and NIOSH sharps safety guidelines shape instrument design standards, sterilization validation requirements, and workplace hazard mitigation protocols that manufacturers must embed before market access. The USDA Animal and Plant Health Inspection Service coordinates with state veterinary boards to establish equipment sanitation benchmarks for interstate mobile surgical services. Stakeholders must monitor how state-level scope-of-practice expansions for veterinary technicians reshape purchasing authority and instrument complexity requirements.
Market Dynamics
Minimally invasive surgical techniques are redistributing capital budgets across US veterinary practices as video-assisted platforms displace open-procedure instrument sets in high-volume companion animal hospitals.
Growth Catalysts
- FDA Center for Veterinary Medicine device clearance pathways:Streamlined 510(k) submissions for titanium alloy instruments accelerate product launches and reduce time-to-revenue for manufacturers targeting orthopedic suites.
- NIOSH sharps safety guidelines:Federal workplace hazard mandates drive replacement cycles for non-compliant legacy instruments, creating pull-through demand for safety-engineered scalpel handles and retractable blade systems.
- Texas and California hospital network concentration:Large regional purchasing cooperatives in these states aggregate procurement volume, enabling economies of scale that subsidize technology upgrades for independent practices.
Market Restraints
- Medical-grade titanium alloy input volatility:Aerospace and human medical device sectors compete for limited titanium sponge supply, pressuring margins on premium instrument portfolios.
- Supply concentration in German and Pakistani forging facilities:Specialized heat-treatment and precision grinding capacity clusters overseas, exposing US distributors to shipping disruptions and extended lead times.
- Laparoscopic platform incompatibility:Proprietary trocar and port designs from competing manufacturers fragment the accessory ecosystem, forcing practices into single-vendor lock-in or redundant capital expenditure.
Strategic Opportunities
- USDA-APHIS mobile surgical service sanitation benchmarks:Interstate transport regulations create demand for portable sterilization validation systems and instrument tracking software serving rural livestock practitioners.
- Veterinary technician scope-of-practice expansion:State-level authorization for surgical assistance in California, Texas, and Florida reshapes purchasing authority toward mid-complexity instrument sets designed for technician-led preoperative preparation.
- Carbon steel composite material convergence:Hybrid metallurgy combining stainless steel durability with carbon steel edge retention opens price-accessible tiers for cost-sensitive mixed-animal practices.
Industry Challenges
- Sterilization validation technician scarcity:ISO 17665 steam sterilization and ISO 11137 radiation dose verification expertise concentrates in human healthcare, forcing veterinary service depots to compete for certified personnel.
- Legacy instrument inventory integration:Practices with substantial sunk investment in non-titanium sets face workflow friction when introducing MRI-compatible instrument suites requiring parallel storage and sterilization tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Veterinary Surgical Instruments Market |
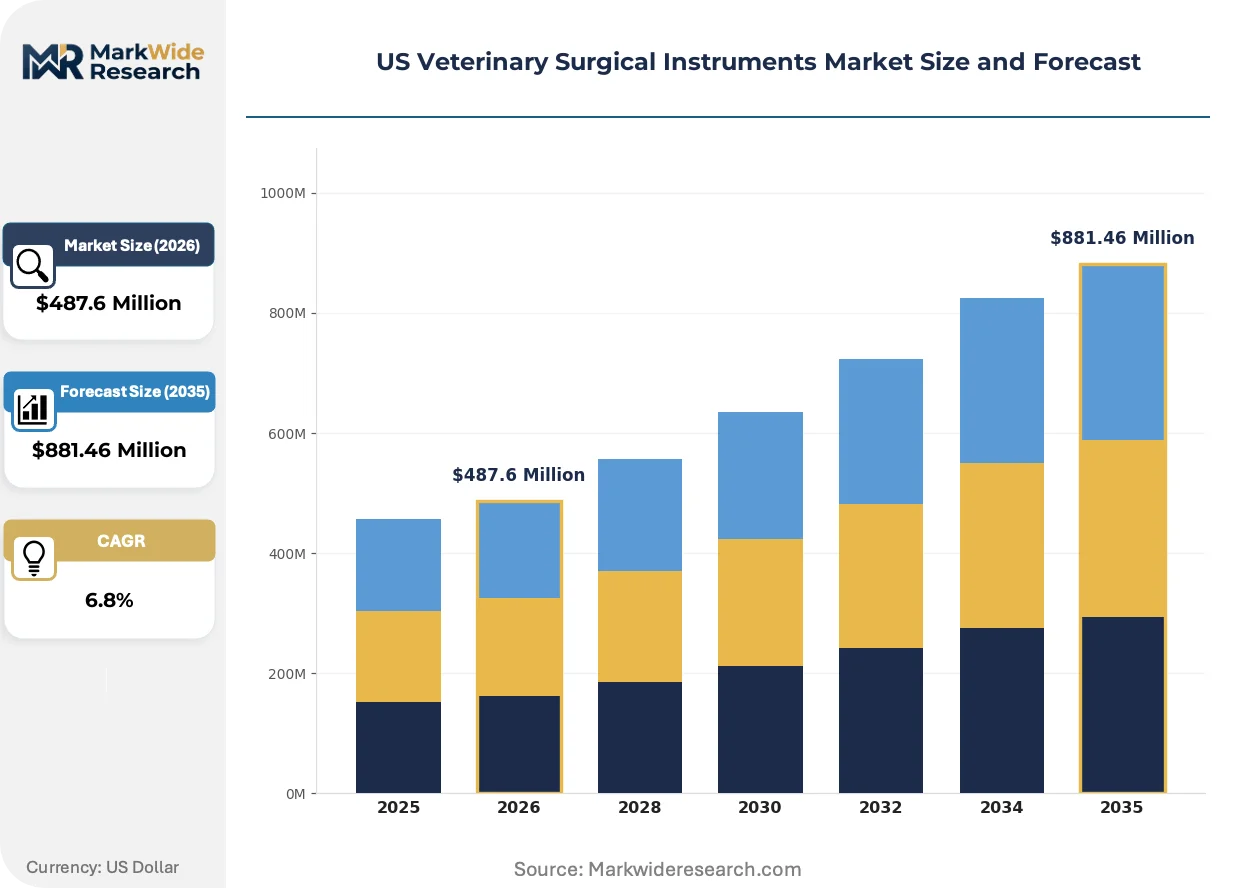
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
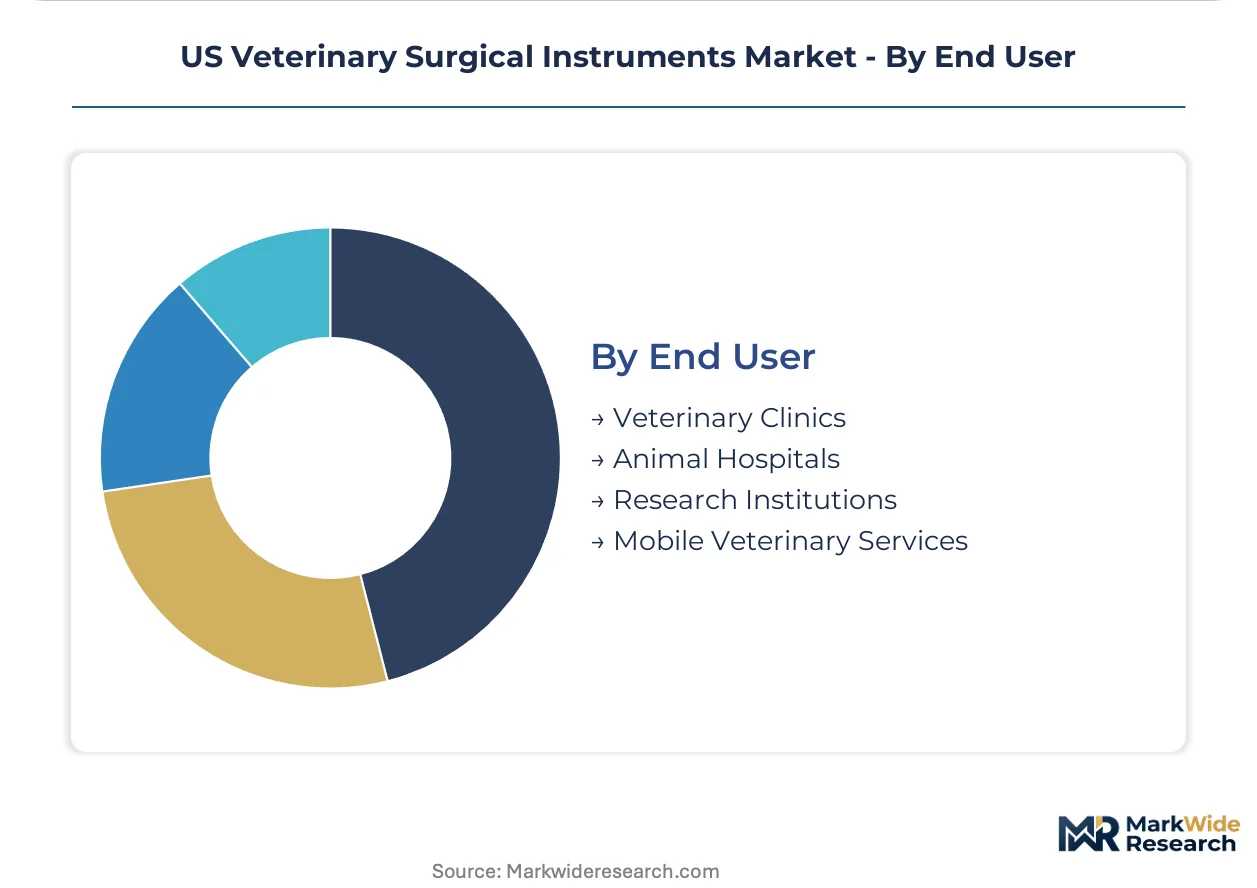
| Segmentation | Product Type: Scissors, Forceps, Scalpel, Needle Holders Material: Stainless Steel, Carbon Steel, Titanium, Plastic Application: Soft Tissue Surgery, Orthopedic Surgery, Dental Procedures, Laparoscopic Surgery End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services |
| Companies Covered | B. Braun Vet Care, Medtronic, Ethicon, Arthrex, Integra LifeSciences, STERIS, GerMedUSA, Jorgensen Laboratories, Neogen Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Veterinary Surgical Instruments Market Emerging Trajectories
Titanium-grade instrument portfolios are compressing procurement timelines as veterinary orthopedic surgeons prioritize weight reduction and imaging compatibility over legacy stainless steel alternatives.
Single-use disposable instrument kits are collapsing the economics of sterilization infrastructure for mobile and emergency surgical services. Rural mixed-animal practitioners in Montana and Wyoming are adopting pre-sterilized procedure packs to eliminate capital investment in autoclave systems. The shift is compressing addressable market for traditional reusable instrument refurbishment providers.
FDA Center for Veterinary Medicine guidance documents on 3D-printed patient-specific surgical guides are clarifying regulatory pathways for additive-manufactured osteotomy plates and cutting jigs. Manufacturers are submitting device master files referencing ASTM F3001 titanium powder specifications to preempt agency questions on material traceability. Large companion animal referral hospitals in California and New York are piloting these guides for complex angular limb deformity corrections.
Consolidated procurement through corporate veterinary groups is fragmenting the independent distributor channel. Mars Veterinary Health and Vetcor are centralizing instrument purchasing through direct manufacturer agreements, bypassing traditional regional distributors that previously served standalone practices. Independent hospitals in the Southeast and Midwest are responding by forming buying cooperatives to preserve volume leverage.
US Veterinary Surgical Instruments Market Segmentation
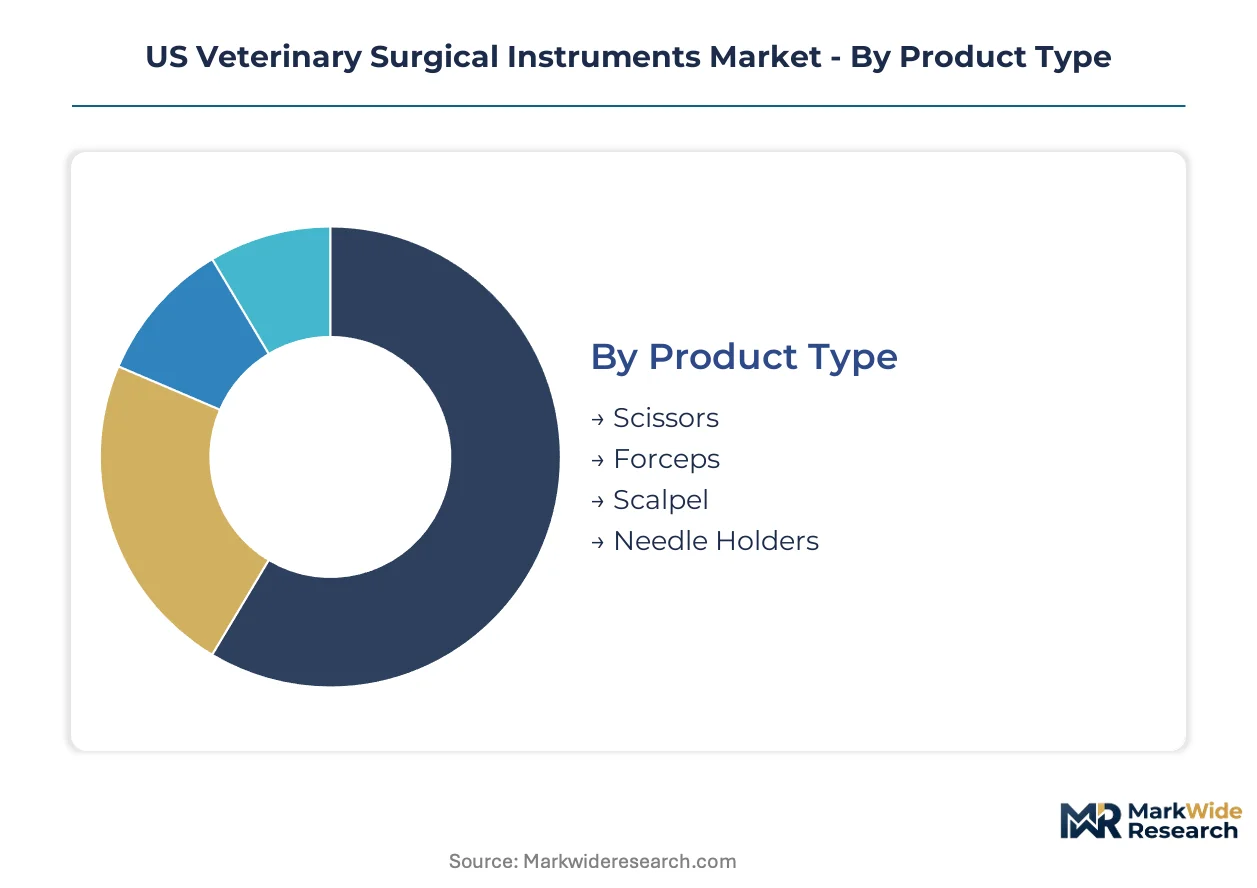
Veterinary surgical instrument procurement varies sharply across practice settings, with capital intensity and procedure mix dictating material preferences and product complexity. Understanding these segment boundaries clarifies where premium titanium portfolios displace legacy stainless steel and which customer tiers drive replacement cycle velocity.
Product Type:
Mature categories anchor procurement volume while emerging designs reshape surgical workflows in high-throughput companion animal hospitals.
- Scissors:Fabricated from medical-grade stainless steel or titanium alloys with tungsten carbide inserts for edge retention, these instruments face concentrated demand in Texas and California hospital networks where high sterilization throughput accelerates replacement cycles. Serrated and Metzenbaum variants dominate soft tissue suites.
- Scalpel:Safety-engineered handles with retractable blade systems are displacing fixed-handle legacy inventory under NIOSH workplace hazard mandates, pulling through demand in large corporate veterinary groups consolidating procurement. Disposable blade compatibility varies by handle standard.
- Forceps:Thumb and ratchet-lock designs span tissue grasping to hemostatic applications.
- Needle Holders:Carbide-jaw variants target suturing precision in orthopedic and soft tissue procedures.
Scissors retain volume leadership; Scalpel holds the steepest expansion curve.
Material:
Cost tiers separate premium imaging-compatible grades from price-accessible alternatives serving mixed-animal rural practices.
- Titanium:MRI-compatible alloys with reduced ferromagnetic interference and 40% weight reduction versus stainless steel are commanding preference in California and New York referral hospitals investing in advanced imaging suites. ASTM F136 implant-grade specifications anchor orthopedic instrument sourcing.
- Stainless Steel:AISI 400-series martensitic and 300-series austenitic grades dominate mid-tier procurement through established distributor channels, with 304L and 316L variants balancing corrosion resistance against cost constraints in high-volume sterilization environments.
- Carbon Steel:Superior edge retention supports specialized cutting applications where hardness outweighs corrosion resistance requirements.
- Plastic:Single-use instrument handles and disposable components are collapsing sterilization infrastructure economics for mobile services.
Stainless Steel retains volume leadership; Titanium climbs the fastest.
Application:
Procedure complexity stratifies instrument requirements from routine tissue manipulation to video-assisted platform integration.
- Laparoscopic Surgery:Video-assisted platforms demand proprietary trocar systems, insulated graspers, and articulating dissectors that fragment accessory ecosystems and force single-vendor commitments or redundant capital expenditure in high-volume companion animal hospitals. FDA 510(k) pathways for instrument sets lag behind human medical clearances.
- Orthopedic Surgery:Bone saws, drills, and plate-bending instruments require titanium-grade portfolios to reduce surgeon fatigue during prolonged procedures and eliminate MRI scheduling conflicts.
- Soft Tissue Surgery:Universal scalpel, scissor, and forcep requirements sustain replacement cycle velocity across all practice types.
- Dental Procedures:Elevators, extraction forceps, and periodontal probes serve companion animal dental suites with specialized tip geometries.
Soft Tissue Surgery retains volume leadership; Laparoscopic Surgery gains share fastest.
End User:
Customer scale determines procurement centralization, with corporate consolidation fragmenting independent distributor channels.
- Animal Hospitals:Mars Veterinary Health and Vetcor direct agreements are bypassing regional distributors, aggregating volume for titanium instrument upgrades and laparoscopic platform investments. Multi-site networks in Texas and California anchor national purchasing benchmarks.
- Veterinary Clinics:Independent practices in the Southeast and Midwest are forming buying cooperatives to preserve leverage against manufacturer-direct pricing erosion.
- Mobile Veterinary Services:USDA-APHIS interstate sanitation regulations drive portable sterilization validation and instrument tracking software demand.
- Research Institutions:Specialized protocols and species-specific instrument requirements sustain niche procurement channels with extended validation documentation.
Animal Hospitals retain volume leadership; Mobile Veterinary Services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US states, with rural mixed-animal practitioners in the Mountain West exhibiting the highest price sensitivity while California and Texas referral hospitals absorb premium titanium instrument premiums without volume contraction.
California
Specialty companion animal hospitals in Los Angeles and San Francisco Bay Area drive titanium instrument procurement for MRI-compatible orthopedic suites. FDA Center for Veterinary Medicine 510(k) submissions cluster in San Diego's medical device corridor, accelerating clearance timelines for additive-manufactured surgical guides. The state's veterinary technician scope-of-practice expansion authorizes surgical assistance, redirecting instrument purchasing toward mid-complexity sets.
Texas
Corporate veterinary networks anchored in Dallas-Fort Worth and Houston aggregate procurement volume for laparoscopic platform investments. USDA-APHIS coordinates with state veterinary boards on mobile surgical service sanitation benchmarks, creating demand for portable sterilization validation systems in rural Panhandle livestock operations. Large hospital purchasing cooperatives subsidize technology upgrades for independent practices.
New York
Referral hospitals in New York City and Long Island pilot 3D-printed patient-specific osteotomy plates under FDA guidance documents. The state's concentration of academic veterinary medical centers sustains niche procurement channels with extended validation documentation requirements. Upstate mixed-animal practices lag in minimally invasive adoption due to capital constraints.
Florida
Veterinary technician scope-of-practice authorization for surgical assistance reshapes purchasing authority toward technician-led preoperative preparation instrument sets. Corporate consolidation in Miami and Tampa bypasses traditional regional distributors through direct manufacturer agreements. Mobile equine surgical services along the I-4 corridor drive demand for instrument tracking software.
Illinois
Chicago-area specialty practices concentrate procurement of safety-engineered scalpel handles under NIOSH workplace hazard mandates. The Midwest's independent hospital networks form buying cooperatives to preserve volume leverage against manufacturer-direct pricing erosion. Rural mixed-animal practitioners in central Illinois remain cost-sensitive, favoring stainless steel over titanium grades.
US Veterinary Surgical Instruments Market Vendor Landscape
Capability concentration sits with specialized manufacturers commanding metallurgical expertise and FDA regulatory navigation; scale advantage sits with diversified medical device conglomerates leveraging centralized reprocessing infrastructure and multi-year service contracts. The market structure tiers into three archetypes: integrated human-veterinary crossover players, pure-play veterinary instrument specialists, and regional distributor-aligned fabricators. Dominant competitive moves include backward integration into titanium alloy sourcing and strategic partnerships with corporate veterinary groups for direct procurement agreements.
Within the integrated crossover tier, B. Braun Vet Care and Medtronic occupy positions anchored by human healthcare infrastructure repurposed for veterinary applications. Among pure-play specialists, Jorgensen Laboratories exemplifies the regional distributor partnership model. These three represent distinct strategic postures: centralized reprocessing scale, proprietary sterilization container lock-in, and repair turnaround speed for independent practices.
| Leading Market Players |
|---|
| B. Braun Vet Care |
| Medtronic |
| Ethicon |
| Arthrex |
| Integra LifeSciences |
| STERIS |
| GerMedUSA |
| Jorgensen Laboratories |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Pakistani forging capacity compresses pricing tier spreads while simultaneously exposing US distributors to tariff exposure and logistics chokepoints that reshape procurement economics across premium titanium and standard stainless steel segments.
Pricing Analysis
Aftermarket service revenue from instrument refurbishment contracts and sterilization validation programs drives lifetime value beyond initial hardware sales. Three-tier pricing structure across premium titanium, standard stainless steel, and economy carbon steel levels reflects MRI compatibility certification and aerospace-grade material traceability. Cost compression in the carbon steel tier is intensifying because single-use disposable kits are collapsing sterilization infrastructure economics for mobile practitioners. Rural mixed-animal practices in the Mountain West exhibit the highest price sensitivity, while California and Texas referral hospitals absorb titanium premiums without volume contraction.
Supply Chain Analysis
Tariff exposure between the United States and key manufacturing jurisdictions dominates supply chain risk calculations for veterinary instrument distributors. Specialized heat-treatment and precision grinding capacity clusters in Germany, Pakistan, and India, with medical-grade titanium sponge sourcing tethered to aerospace and human medical device competitors. Raw material dependencies center on titanium alloy ingots, martensitic stainless steel billets, and tungsten carbide cutting inserts. Distribution runs through manufacturer-direct agreements with corporate veterinary groups and regional distributor partnerships serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use disposable instrument kits pose a substitution threat that reusable instrument incumbents must navigate through service revenue lock-in and sterilization infrastructure partnerships.
For Market Incumbents: Harden titanium alloy sourcing through backward integration into ASTM F136 implant-grade material supply chains. Deepen centralized reprocessing infrastructure to capture recurring maintenance contracts that offset disposable kit erosion. FDA 510(k) clearance velocity serves as the critical defensive lever against emerging additive-manufactured guide competitors. For New Entrants and Emerging Players: Establish a beachhead in USDA-APHIS mobile surgical service sanitation benchmarks, where portable sterilization validation systems face limited incumbent penetration. Target veterinary technician scope-of-practice expansion states—California, Texas, and Florida—for mid-complexity instrument sets designed for technician-led preoperative preparation. A distributor partnership model with repair turnaround guarantees unlocks independent practice access. For Investors and Strategic Acquirers: FDA Center for Veterinary Medicine guidance document finalization on 3D-printed patient-specific surgical guides reshapes the acquisition landscape toward additive manufacturing specialists with device master file submissions. Long-term viability centers on metallurgical expertise combined with regulatory navigation capability. The signal to watch is state-level veterinary technician scope-of-practice authorization velocity as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined titanium alloy instrument clearances compress time-to-revenue for orthopedic suite targeting. |
| Centralized Reprocessing Infrastructure | B. Braun Vet Care's captive maintenance contracts lock in recurring revenue against disposable kit substitution. |
| Regional Distributor Partnership | Jorgensen Laboratories' repair turnaround advantages preserve independent practice channel access. |
| Proprietary Sterilization Container System | Medtronic's multi-year service agreements create switching costs for hospital network customers. |
| Additive Manufacturing Guide Development | ASTM F3001 titanium powder specifications anchor regulatory preemptive positioning for complex deformity corrections. |
Methodological Framework
A standing panel of veterinary orthopedic surgeons, hospital purchasing committee directors, biomedical equipment technicians, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) device clearance databases, USDA-APHIS interstate transport regulations, state veterinary board scope-of-practice filings, and hospital procurement contract aggregators. Bottom-up instrument shipment data triangulated against top-down capital expenditure surveys from corporate veterinary groups.
Scenario-bracketing around titanium alloy price volatility and disposable kit adoption curves bounded the projection horizon. Segmentation dimensions modeled encompass product type, material grade tier, application complexity, and end-user scale. CAGRs were derived from weighted regression across historical replacement cycle data and forward-looking sterilization infrastructure investment patterns. Veterinary technician authorization timelines and FDA guidance document publication schedules served as industry-specific forecast inputs.
Sensitivities concentrate around titanium sponge supply competition from aerospace and human medical sectors, state-level scope-of-practice regulatory shifts, and single-use disposable kit cost parity achievement. Forecasts reflect documented assumptions on sterilization validation technician availability and corporate veterinary group consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Surgical Stapler Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Stents Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Global Hysteroscopy Instruments Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market