
 United States Healthcare Big Data Analytics Market | 2026-2036
United States Healthcare Big Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Healthcare Big Data Analytics Market Intelligence
Cloud-native infrastructure is shifting the cost structure of healthcare analytics away from capital-heavy on-premises data warehouses toward subscription-based consumption models. Optum leverages its vertically integrated payer-provider data assets to dominate risk-adjustment analytics for Medicare Advantage plans. Oracle sustains competitive positioning through aggressive cloud infrastructure investments targeting HIPAA-compliant workloads. Health Catalyst specializes in outcome improvement applications that tie analytics directly to hospital operational metrics.
Healthcare big data analytics encompasses the computational processing, statistical modeling, and machine learning of large-scale clinical, financial, and operational datasets to generate actionable intelligence for care delivery and business decisions. The discipline requires petabyte-scale distributed computing architectures, real-time streaming pipelines for continuous patient monitoring, and federated learning frameworks that preserve data privacy across institutional boundaries. Software solutions capture the dominant margin pool as hospitals prioritize modular, API-first analytics tools over monolithic platforms. Cloud-based deployment is expanding fastest among mid-size health systems seeking to bypass internal IT capacity constraints. Predictive analytics applications lead clinical adoption, particularly for sepsis detection and deterioration index scoring in intensive care settings.
FDA guidance on artificial intelligence and machine learning in medical devices shapes algorithm validation requirements for clinical decision support tools, while HIPAA and the 21st Century Cures Act establish the data governance framework within which all platforms must operate. CMS reimbursement policies increasingly reward outcomes-based contracts, creating direct financial incentives for providers to invest in population health analytics capabilities. Stakeholders must decide whether to build proprietary data science teams or outsource to specialized vendors as regulatory complexity around algorithmic bias and auditability intensifies.
Market Dynamics
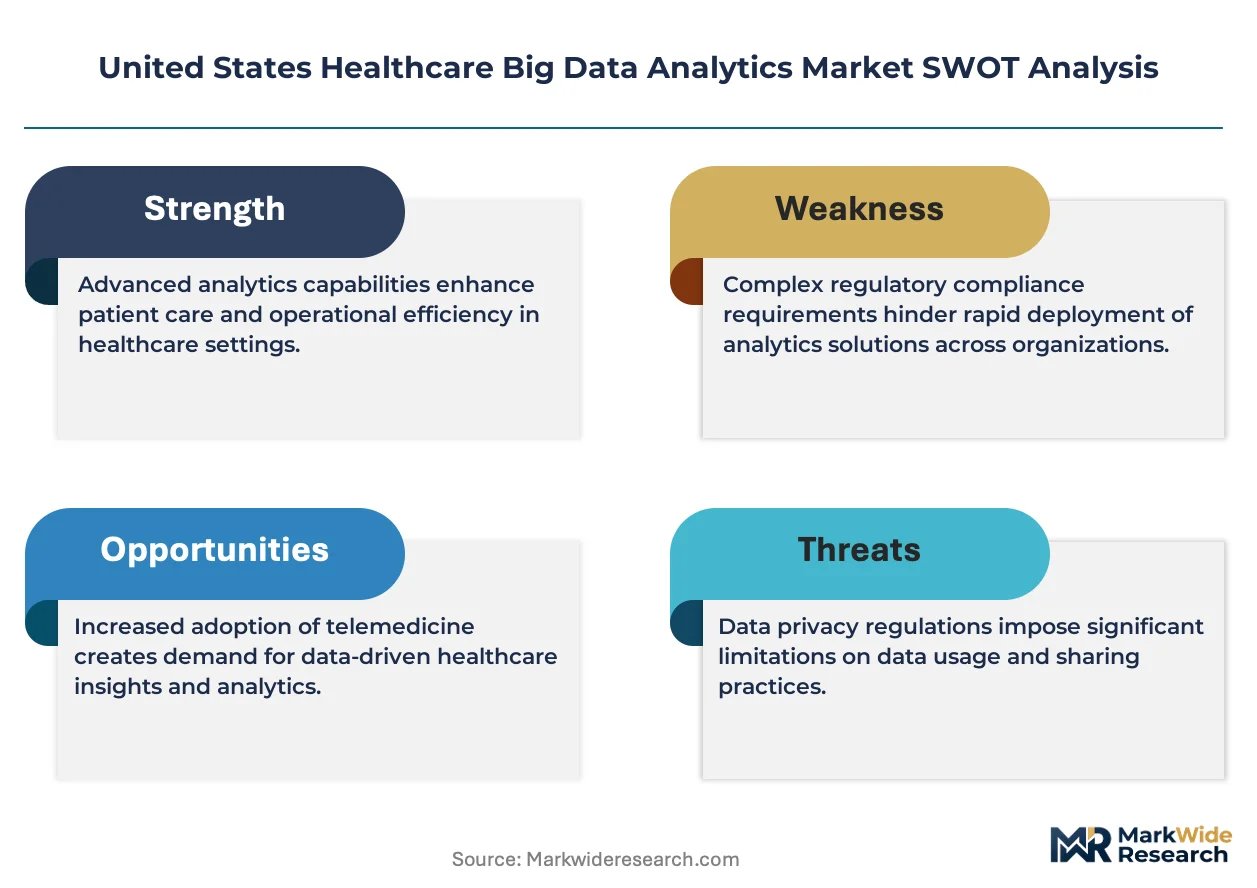
The 21st Century Cures Act interoperability mandates are forcing hospitals to dismantle data silos and invest in federated analytics architectures, compressing the timeline for platform consolidation across health systems.
Growth Catalysts
- CMS value-based reimbursement:Medicare Advantage risk-adjustment contracts reward providers who deploy predictive analytics for population health stratification, accelerating platform procurement cycles.
- Texas and California health system consolidation:Large integrated delivery networks in these states are deploying enterprise data lakes that create template architectures for regional adoption.
- FDA AI/ML medical device guidance:Algorithm validation frameworks for clinical decision support tools clarify commercialization pathways for sepsis detection and deterioration index scoring applications.
Market Restraints
- HIPAA compliance infrastructure costs:Cloud-native deployments require specialized security architectures that inflate total cost of ownership for mid-size health systems.
- Legacy EHR interoperability friction:Proprietary data formats from dominant electronic health record vendors create persistent extraction bottlenecks.
- Specialized talent scarcity:Health informaticists with clinical domain expertise and machine learning engineering skills command compensation premiums that strain hospital IT budgets.
Strategic Opportunities
- Rural health system underpenetration:Critical access hospitals in the Midwest and Southeast lack internal data science capacity, creating white space for managed analytics services.
- Real-time streaming analytics:Continuous patient monitoring in intensive care settings is integrating edge computing with cloud-based inference pipelines.
- Medicaid expansion states:Newly eligible populations in states like North Carolina and Georgia require population health analytics infrastructure that legacy systems cannot support.
Industry Challenges
- Algorithmic bias audit requirements:CMS and state Medicaid agencies are demanding documentation of demographic performance disparities in predictive models.
- Interoperability standard fragmentation:FHIR implementation variations across EHR vendors force costly custom integration work.
- Data governance complexity:Multi-site health systems struggle to maintain consistent consent management and de-identification protocols across state jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Healthcare Big Data Analytics Market |
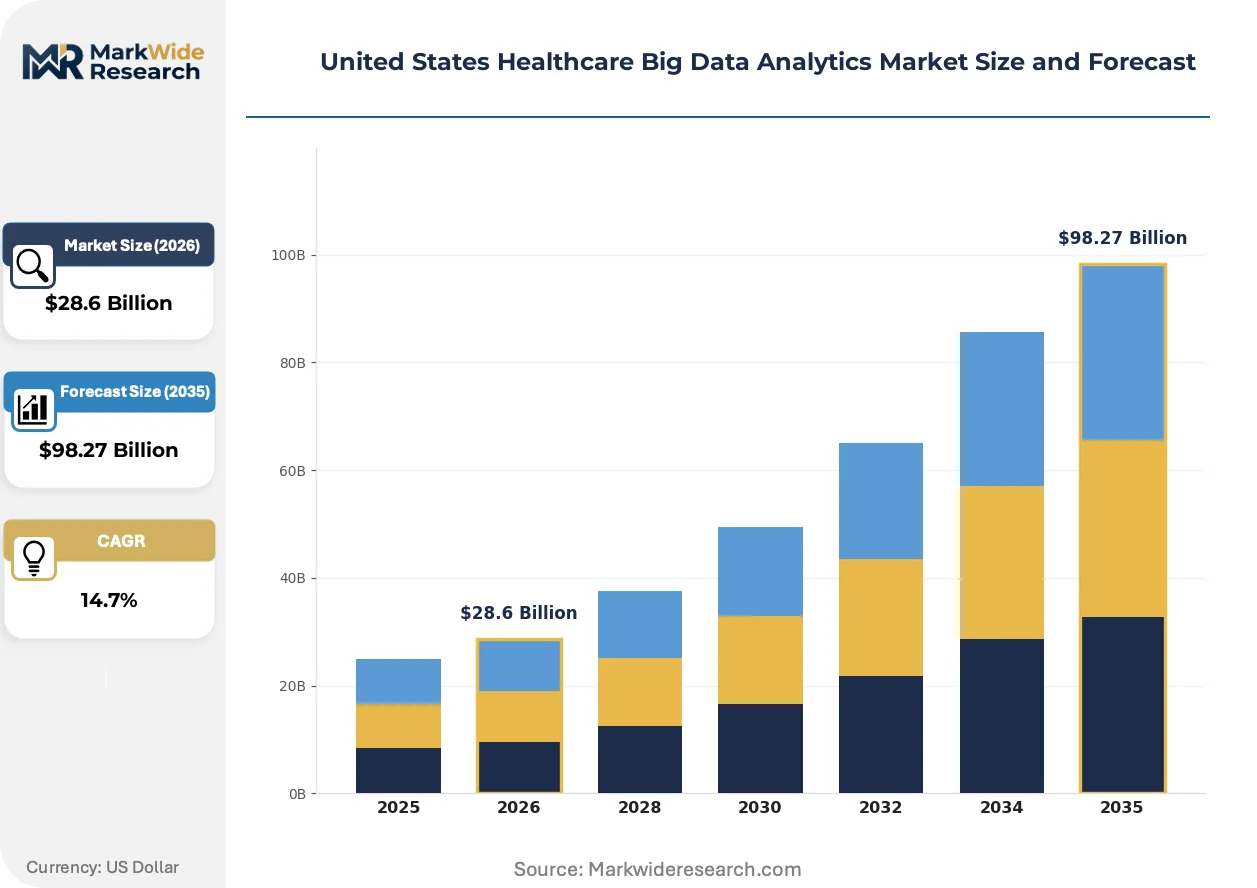
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $98.27 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platforms, Services, Solutions End User: Hospitals, Clinics, Research Institutions, Health Insurance Application: Predictive Analytics, Clinical Decision Support, Population Health, Fraud Detection Deployment: Cloud-based, On-premises, Hybrid, Others |
| Companies Covered | Optum, Oracle, Merative, McKesson Corporation, SAS Institute, Veradigm, IQVIA, Health Catalyst, CitiusTech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Healthcare Big Data Analytics Market Strategic Shifts & Innovations
Cloud-native architectures are compressing deployment timelines while regulatory pressure on algorithmic transparency is reshaping vendor qualification criteria across provider procurement processes.
Real-time streaming analytics platforms are integrating edge computing nodes with centralized cloud inference engines to enable continuous patient monitoring in surgical suites and emergency departments. Large academic medical centers in California and Massachusetts are piloting these architectures for sepsis early warning systems. The technology is integrating previously siloed vital sign streams with laboratory data feeds, collapsing the latency between physiological deterioration and clinical response.
FDA guidance on artificial intelligence and machine learning in medical devices is mandating predetermined change control plans for algorithm updates, forcing vendors to redesign software development lifecycles. Clinical decision support tools now require locked algorithm versions with documented performance across demographic subgroups. Medicare Advantage plans and accountable care organizations in Florida and Arizona are prioritizing vendors with completed FDA premarket submissions.
Hospital procurement committees are unbundling analytics software from EHR vendor bundles, creating evaluation frameworks that weight API flexibility and third-party integration capacity. Mid-size health systems in the Pacific Northwest and Upper Midwest are forming purchasing cooperatives to negotiate standardized platform terms. This behavioral shift is most visible among systems with 200-500 licensed beds that previously deferred to single-vendor strategies.
United States Healthcare Big Data Analytics Market Segmentation
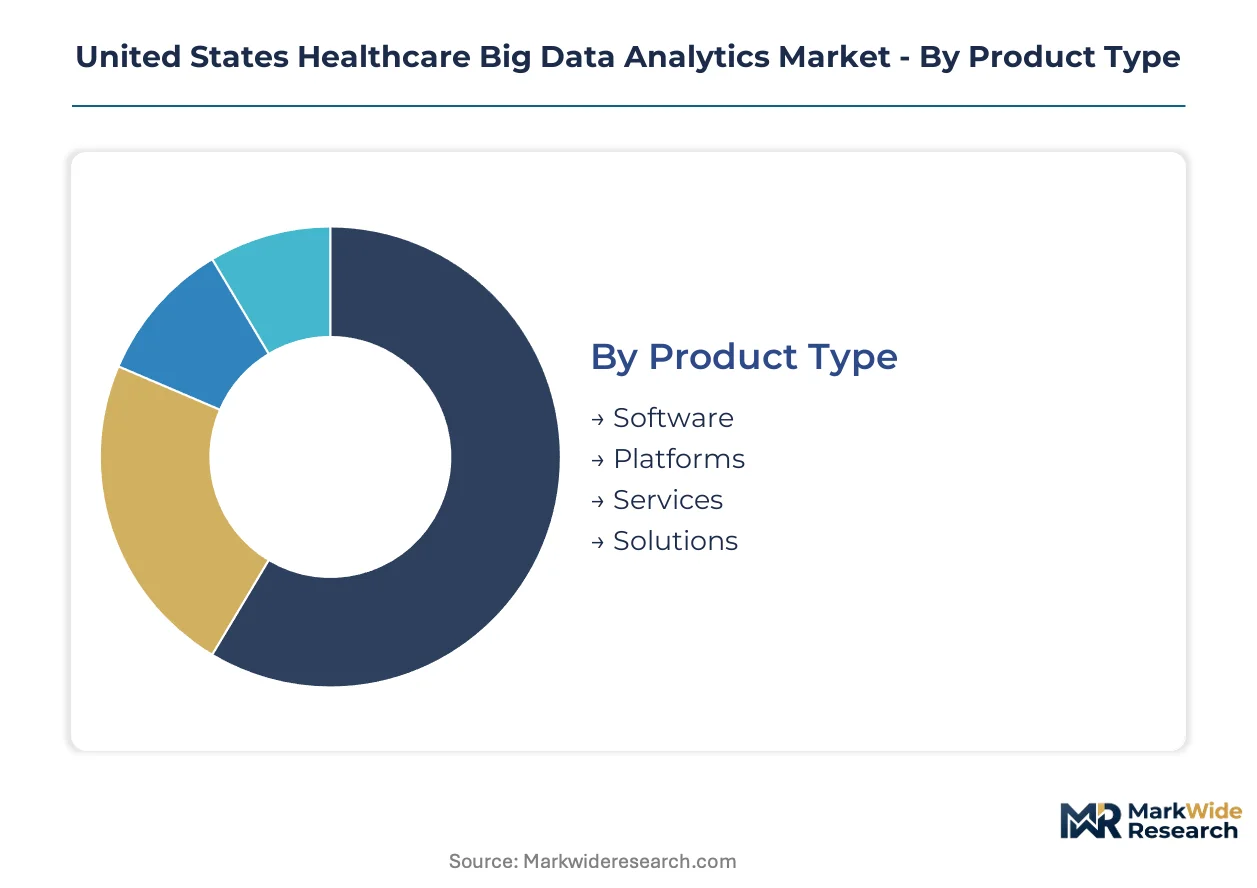
Healthcare analytics procurement in the United States reflects divergent IT maturity, regulatory exposure, and reimbursement model pressures across provider types. Segmentation reveals where capital concentrates versus where subscription models are displacing legacy infrastructure.
Product Type:
Software buyers prioritize modular API-first tools; platform purchasers seek vertically integrated data lakes; services demand signals internal capacity gaps.
- Software:Modular applications with embedded machine learning pipelines dominate hospital procurement cycles. Texas and California health systems deploy these for risk-adjustment scoring under Medicare Advantage contracts.
- Platforms:Enterprise data lakes with federated learning architectures address 21st Century Cures Act interoperability mandates. Large integrated delivery networks in Florida consolidate petabyte-scale clinical and financial repositories on these systems.
- Services:Managed analytics partnerships fill data science talent gaps at critical access hospitals in the Midwest and Southeast.
- Solutions:Outcome-guaranteed bundles tie vendor compensation to operational metric improvements.
Volume sits with Software; growth tilts toward Platforms.
End User:
Reimbursement complexity and patient volume scale differentiate procurement authority across buyer categories.
- Hospitals:Academic medical centers in Massachusetts and California pilot real-time streaming analytics for ICU deterioration detection. CMS value-based penalties for readmissions drive predictive platform investments at systems with 200-plus beds.
- Clinics:Federally qualified health centers in Medicaid expansion states require population health stratification tools for newly eligible populations.
- Research Institutions:NIH-funded centers leverage federated learning frameworks to train algorithms across institutional boundaries without centralizing protected health information.
- Health Insurance:Medicare Advantage plans in Arizona deploy risk-adjustment analytics to optimize HCC coding accuracy and capitation revenue.
Capital deployment concentrates at Hospitals; expanding most quickly among Health Insurance payers.
Application:
Clinical urgency and financial penalty exposure determine algorithm validation requirements and deployment speed.
- Predictive Analytics:Sepsis detection and early warning scores command the largest share of ICU technology budgets. FDA premarket submission requirements for locked algorithm versions slow procurement cycles.
- Clinical Decision Support:Real-time order set recommendations integrate with EHR workflows at Epic and Cerner installations. Texas Medical Center institutions demand predetermined change control plans for algorithm updates.
- Population Health:Medicaid managed care organizations in North Carolina and Georgia stratify attributed members for care management outreach.
- Fraud Detection:CMS Recovery Audit Contractor programs incentivize claims pattern analysis at Medicare Administrative Contractors.
Revenue pools favor Predictive Analytics; steepest expansion trajectory belongs to Population Health.
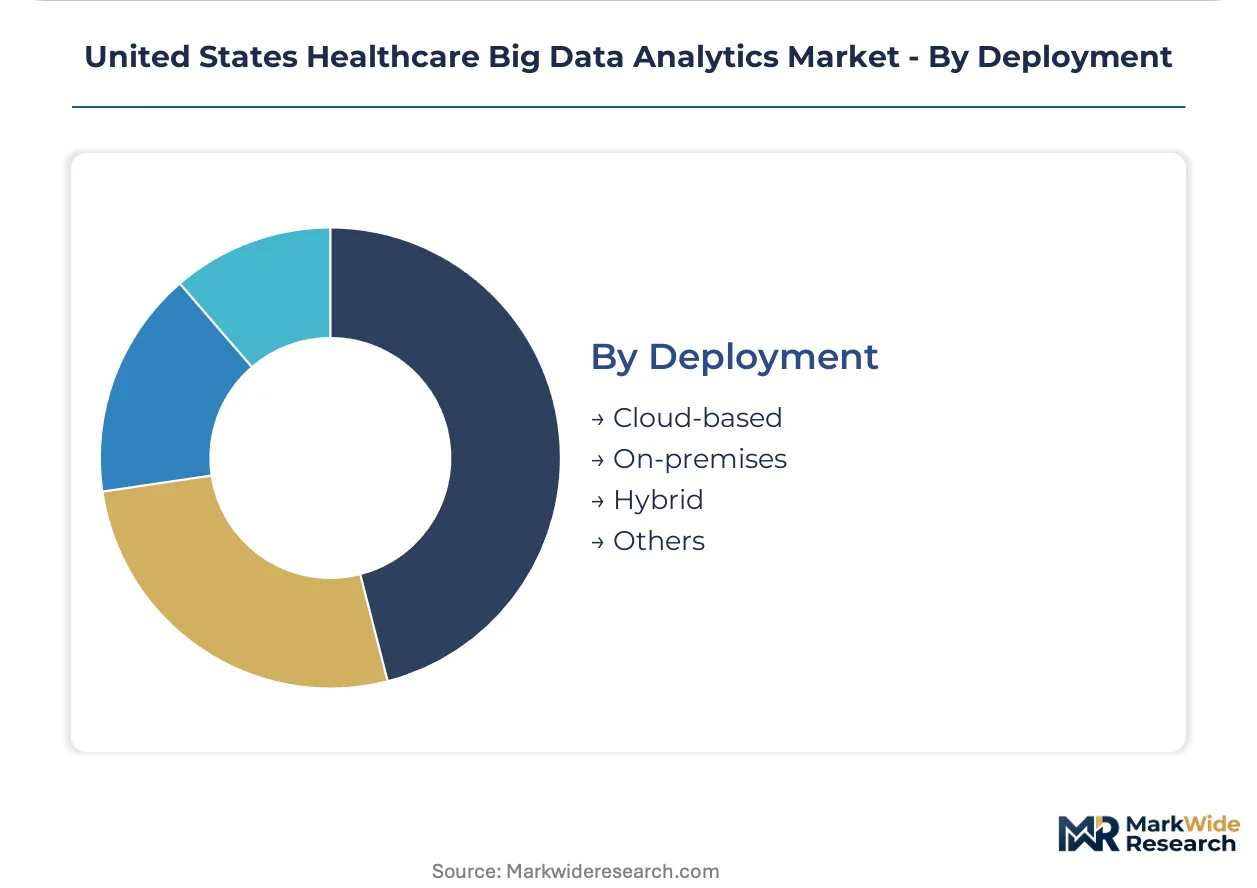
Deployment:
Data sovereignty requirements and internal IT headcount shape infrastructure location decisions.
- Cloud-based:HIPAA-compliant AWS and Azure environments reduce capital expenditure for mid-size health systems in the Pacific Northwest. Subscription consumption models bypass internal data center capacity constraints.
- On-premises:Legacy data warehouses persist at Department of Veterans Affairs facilities and defense health systems with classified network requirements.
- Hybrid:Edge computing nodes in surgical suites stream de-identified inference data to centralized cloud training pipelines.
- Others:Multi-cloud failover architectures address business continuity requirements for disaster-prone Gulf Coast providers.
Installed base remains On-premises; gaining share fastest is Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level tax incentives for healthcare technology investment are concentrating analytics infrastructure deployment in specific metropolitan corridors across the United States.
Texas
The Texas Medical Center in Houston anchors the nation's largest clinical data repository, with Medicare Advantage risk-adjustment contracts driving predictive analytics procurement at Baylor St. Luke's and Memorial Hermann. The state's franchise tax exemption for data center equipment accelerates cloud-native platform investments. Dallas-Fort Worth health systems including Texas Health Resources deploy enterprise data lakes for 21st Century Cures Act compliance.
California
Kaiser Permanente's integrated model generates petabyte-scale datasets that train population health algorithms for Medicaid expansion populations. The California Consumer Privacy Act imposes stricter de-identification standards than federal HIPAA minimums. Stanford Medicine and UCSF Health in the San Francisco Bay Area pilot FDA-aligned validation frameworks for sepsis detection AI.
Massachusetts
Mass General Brigham and Beth Israel Lahey Health anchor federally funded research consortia applying federated learning to multi-site clinical trials. The state's Health Policy Commission mandates cost-growth benchmarks that incentivize outcome-improvement analytics. Boston's Longwood Medical Area concentrates NIH-funded algorithm development for intensive care deterioration scoring.
North Carolina
Medicaid expansion implementation in 2023 created immediate demand for care management stratification tools at Atrium Health and Duke Health. The North Carolina Department of Health and Human Services requires encounter data submission standards that force EHR interoperability upgrades. The Research Triangle Park corridor attracts analytics vendors targeting rural health system underpenetration in surrounding counties.
Florida
Medicare Advantage penetration rates exceeding national averages drive risk-adjustment analytics investment at Humana-affiliated provider groups and Optum's CarePlus operations. The Agency for Health Care Administration's all-payer claims database mandates standardize data formats for fraud detection algorithms. Tampa General Hospital and AdventHealth Orlando consolidate claims and clinical repositories on cloud-native platforms.
United States Healthcare Big Data Analytics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated health services conglomerates commanding risk-adjustment analytics while modular software vendors capture outcome-improvement applications. Market structure tilts toward consolidation at the platform layer and fragmentation at the point-solution tier. Three archetypes dominate: payer-provider integrated data assets, cloud infrastructure specialists with HIPAA-compliant certifications, and clinical outcome improvement pure-plays. Competitive intensity manifests through strategic acquisitions of niche algorithm developers and exclusive cloud partnership arrangements with major health systems.
Within the integrated health services tier, Optum exemplifies the payer-provider data monetization model, while Oracle occupies a position anchoring infrastructure-as-a-service deployments for HIPAA workloads. Health Catalyst represents the outcome-improvement specialist archetype, tying vendor compensation to measurable hospital operational metrics. These three companies illustrate the strategic divergence between data asset control, cloud platform dominance, and clinical application depth.
| Leading Market Players |
|---|
| Optum |
| Oracle |
| Merative |
| McKesson Corporation |
| SAS Institute |
| Veradigm |
| IQVIA |
| Health Catalyst |
| CitiusTech |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up analytics specialists have consolidated fragmented point-solution vendors into platform portfolios, compressing vendor margins through centralized procurement while enforcing subscription pricing discipline across hospital system buyers. This ownership pattern concentrates supply-side pricing power among three scaled platform operators while mid-size health systems face take-it-or-leave-it SaaS terms.
Pricing Analysis
Short lead-time deployments command 15-25% premiums over standard implementation cycles as hospitals race to meet 21st Century Cures Act interoperability deadlines. The dominant pricing structure is tiered SaaS subscriptions stratifying across enterprise, departmental, and point-solution levels, with price differentiation driven by FHIR integration depth and FDA validation status. Cost compression in the mid-market tier is intensifying because cloud hyperscalers are bundling HIPAA-compliant infrastructure with analytics modules at marginal cost. Federally qualified health centers exhibit highest price sensitivity; academic medical centers with dedicated IT capital budgets show least.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-cloud qualification across AWS and Azure for business continuity, preventing single-vendor lock-in. Geographic supply concentration centers on US-based data centers in Virginia, Oregon, and Ohio for latency-sensitive clinical workloads, with secondary disaster recovery nodes in Canada and Ireland. Raw material dependencies include GPU compute clusters from NVIDIA, specialized FHIR middleware from Red Hat and InterSystems, and cybersecurity modules from CrowdStrike and Palo Alto Networks. Single-source vulnerability runs through NVIDIA's datacenter GPU allocation for training workloads. Distribution runs through direct enterprise sales with GPO contract overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is accelerating as algorithmic bias audit requirements from CMS and state Medicaid agencies force subscale vendors to exit. Regulatory compliance complexity serves as the primary pressure eliminating weaker players without dedicated legal and clinical validation teams.
For Market Incumbents: Lock in exclusive cloud partnership arrangements with major health systems in Texas and California before procurement committees finalize standardized platform terms. Deepen backward integration into proprietary clinical data assets through payer-provider joint ventures. Defend against modular API-first entrants by embedding outcome-guaranteed contracts that tie vendor compensation to readmission reduction metrics.
For New Entrants and Emerging Players: Cloud-native managed analytics services targeting critical access hospitals in the Midwest and Southeast represent the most penetrable white space. These rural systems lack internal data science capacity and face 21st Century Cures Act compliance deadlines without IT headcount to execute. Target Medicaid expansion states including North Carolina and Georgia where legacy infrastructure cannot support newly eligible population stratification requirements.
For Investors and Strategic Acquirers: FDA premarket submission completion for sepsis detection algorithms is the leading indicator that a clinical decision support vendor has achieved scalable revenue traction. Long-term viability over the coming decade hinges on locked algorithm versions with documented demographic performance parity. Acquisition targets should display completed 510(k) pathways and established hospital IDN relationships. Watch for CMS reimbursement policy shifts toward outcomes-based contracts as the inflection signal for population health analytics demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Locked algorithm versions with predetermined change control plans satisfy hospital procurement requirements in Texas Medical Center. |
| Hospital System Partnership | Exclusive data-sharing agreements with Kaiser Permanente or Mass General Brigham generate proprietary training datasets for population health models. |
| Cloud Infrastructure Certification | HIPAA-compliant AWS and Azure specializations reduce procurement friction for mid-size health systems in the Pacific Northwest. |
| Acquisition of Specialist Firm | Sepsis detection algorithm developers with ICU validation studies fill capability gaps in broader platform portfolios. |
| Reimbursement Strategy | HCC coding accuracy optimization aligns vendor value proposition with Medicare Advantage plan revenue capture in Florida and Arizona. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital CIOs, health system data science directors, GPO contracts managers, and CMS policy officers. Secondary sources included FDA 510(k) submission databases, CMS Medicare cost reports, hospital procurement databases from Premier and Vizient, and interoperability compliance filings under the 21st Century Cures Act. Bottom-up triangulation across vendor-reported bookings and top-down reconciliation against health system IT expenditure surveys validated market sizing.
Granularity-level modeling deployed product-type, end-user, application, and deployment mode dimensions at the state level for Texas, California, Florida, Massachusetts, and North Carolina, with urban-rural splits for Medicaid expansion impact assessment. CAGRs were derived from logarithmic trend fitting across the projection horizon, with cross-validation against health system capital expenditure plans and cloud hyperscaler healthcare vertical revenue disclosures. Forecast inputs incorporated Medicare Advantage penetration trajectories and FDA AI/ML guidance implementation timelines.
The model holds under stable CMS reimbursement policy and continued 21st Century Cures Act enforcement; deviation in federal interoperability mandate delay or algorithmic bias audit suspension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
US Population Health Management Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Global Chronic Care Management Software Market