
 Disposable Hospital Gowns Market | 2026-2036
Disposable Hospital Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Hospital Gowns Market Intelligence
Polypropylene is recalibrating cost structures across the Disposable Hospital Gowns landscape as manufacturers shift away from woven cotton blends toward spunbond-meltblown-spunbond laminates. Medline Industries leverages captive nonwoven production to control raw material input costs across its hospital supply chain. Cardinal Health anchors its position through direct sales relationships with integrated delivery networks. Owens & Minor competes on logistics density, consolidating gown shipments with broader medical-surgical distribution.
Disposable hospital gowns are single-use protective garments engineered from nonwoven polypropylene or SMS laminates, designed to achieve AAMI Level 1 through Level 4 liquid barrier ratings depending on exposure risk. Their primary purpose is to isolate healthcare workers and patients from cross-contamination during surgical, isolation, or emergency procedures. Surgical gowns command the dominant revenue share due to stringent sterility requirements and higher unit pricing tied to AAMI Level 3 and 4 certifications. SMS fabric is displacing basic polypropylene in mid-tier applications where breathability and splash resistance must balance. Long-term care facilities represent an expanding end-user segment as aging demographics and regulatory scrutiny of nursing home infection rates intensify.
The FDA's liquid barrier classification system and the EU Medical Device Regulation (MDR) establish the foundational compliance thresholds for market entry across North America and Europe. The EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing material scientists to reformulate water-repellent finishes without fluorinated chemistry. ISO 16603 and ISO 16604 blood-borne pathogen resistance standards further segment product tiers by clinical risk exposure. Stakeholders must monitor how PFAS phase-out timelines in the United States and European Union will cascade through coating supply chains and reshape competitive cost positions for waterproof gown variants.
Market Dynamics
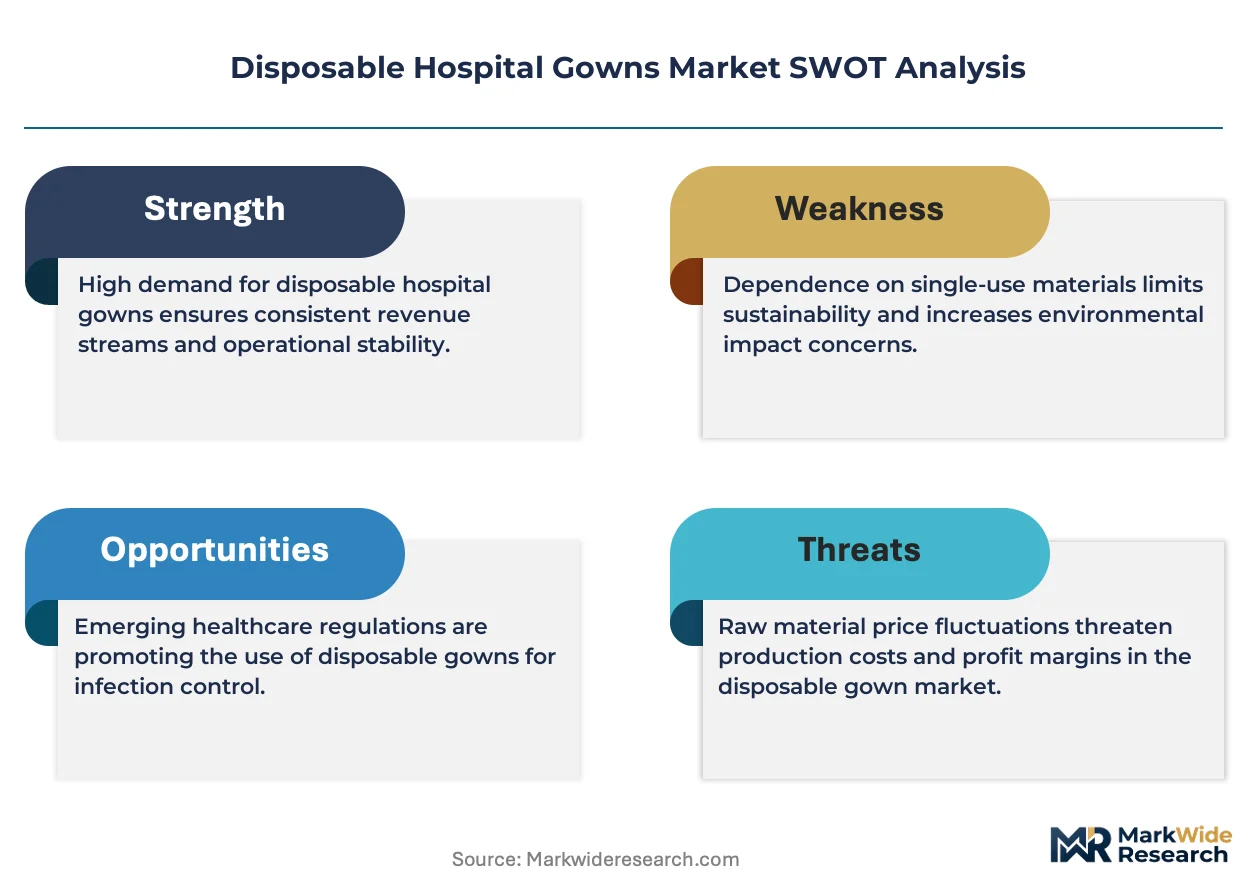
Hospital infection prevention protocols are intensifying demand for AAMI Level 3 and Level 4 certified gowns, forcing manufacturers to retool from basic polypropylene toward SMS laminate constructions that balance breathability with blood-borne pathogen resistance.
Growth Catalysts
- Surgical Volume Expansion:Ambulatory surgical centers in the United States are scaling single-use protective apparel procurement as outpatient procedures migrate from inpatient settings.
- FDA Barrier Performance Guidance:Updated liquid barrier classification requirements are accelerating hospital procurement of higher-certified gown tiers to meet Joint Commission audit standards.
- Spunbond-Meltblown-Spunbond Adoption:SMS fabric technology is penetrating mid-tier applications where splash resistance and wearer comfort must coexist.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer pricing swings directly compress margin structures for nonwoven converters without captive resin supply.
- PFAS Coating Supply Disruption:EPA restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent finishes without proven cost-equivalent substitutes.
- Chinese Nonwoven Concentration:Spunbond capacity clustering in Zhejiang and Jiangsu provinces creates single-source vulnerability for European and North American converters.
Strategic Opportunities
- Long-Term Care Penetration:Nursing facilities in Germany and Japan represent underpenetrated end-use segments as regulatory scrutiny of elder-care infection rates intensifies.
- EU MDR Certification Premium:The Medical Device Regulation's enhanced clinical evidence requirements create pricing power for manufacturers with notified body relationships.
- Direct-to-IDN Distribution:Integrated delivery networks in the United States are consolidating vendor lists, creating white space for suppliers with logistics density and electronic data interchange capabilities.
Industry Challenges
- ISO 16604 Blood-Borne Pathogen Testing Bottlenecks:Certification laboratory capacity constraints are extending product launch timelines for Level 4 gown introductions.
- Legacy ERP Integration Friction:Hospital procurement systems require expensive customization to accommodate real-time inventory visibility and consignment tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Hospital Gowns Market |
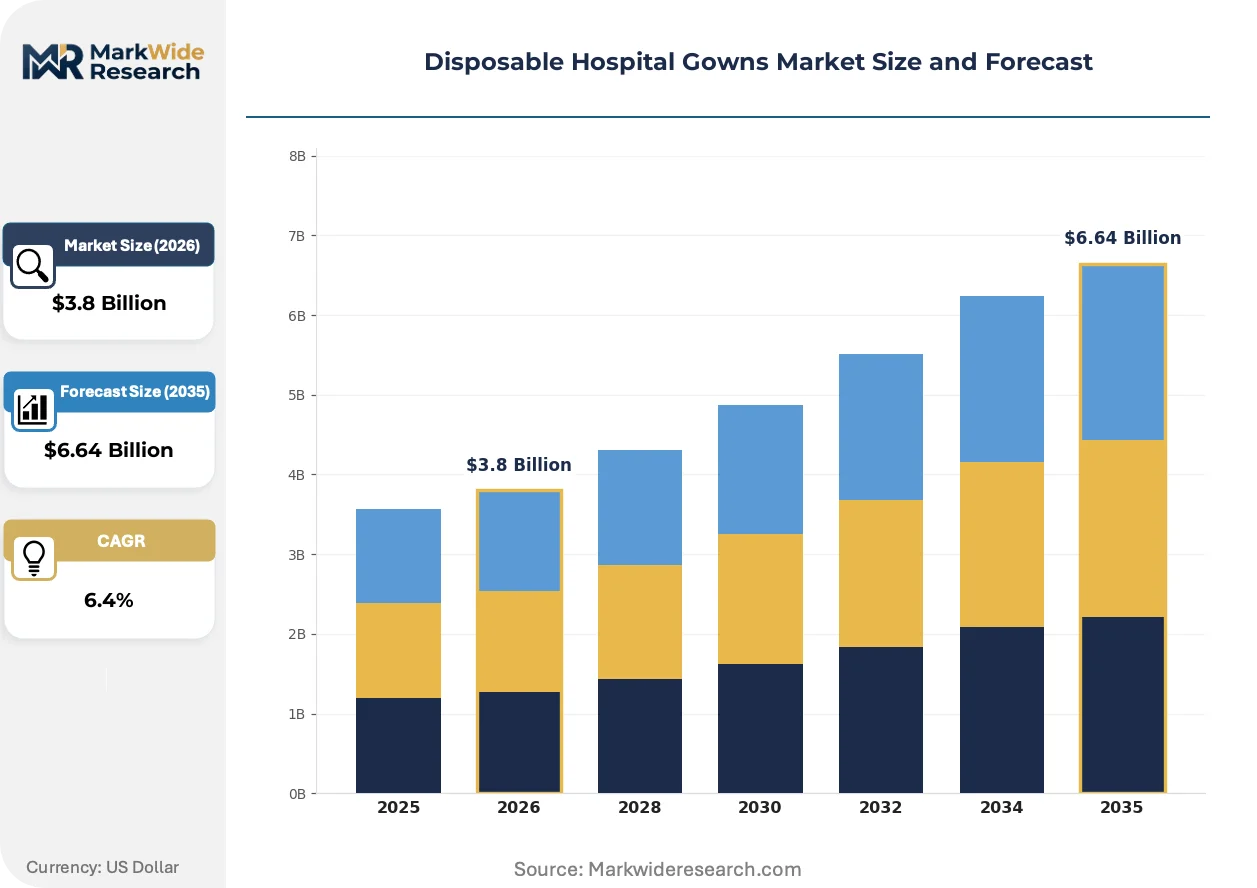
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gowns, Isolation Gowns, Waterproof Gowns, Sterile Gowns Material: Polypropylene, SMS Fabric, Non-Woven, Polyester End User: Hospitals, Clinics, Long-Term Care Facilities, Emergency Departments Distribution Channel: Online, Direct Sales, Retail Stores, Medical Supply Distributors |
| Companies Covered | Standard Textile, TIDI Products, Medline Industries, Angelica, AmeriPride Services, 3M, Owens & Minor, Dynarex, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Hospital Gowns Market Strategic Shifts & Innovations
Material science convergence with regulatory chemistry restrictions is rewriting competitive advantage in protective apparel. Manufacturers must now engineer barrier performance without legacy PFAS formulations.
Bi-component spunbond nonwovens with segmented pie fiber cross-sections are absorbing moisture management and thermal comfort functions previously requiring separate fabric layers. Surgical suites in tertiary hospitals are piloting these constructions for extended wear procedures. The technology is absorbing cost premiums from multi-layer laminates while simplifying sterilization validation.
REACH restrictions on fluorinated substances are forcing European manufacturers to deploy silicone-based and paraffin wax water-repellent finishes ahead of phased PFAS bans. The industrial consequence is a 12-18 month reformulation cycle consuming R&D resources. AAMI Level 3 surgical gowns bound for EU hospitals are most affected, with suppliers accelerating biobased coating partnerships.
Centralized purchasing committees at United States health systems are compressing vendor lists and demanding unit-of-use cost transparency. Traditional distributor markups face displacement by direct manufacturer contracts with price-lock provisions. The shift is most visible in the Southeast and Midwest, where hospital consolidation has created super-IDNs with billion-dollar supply spend authority.
Disposable Hospital Gowns Market Segmentation
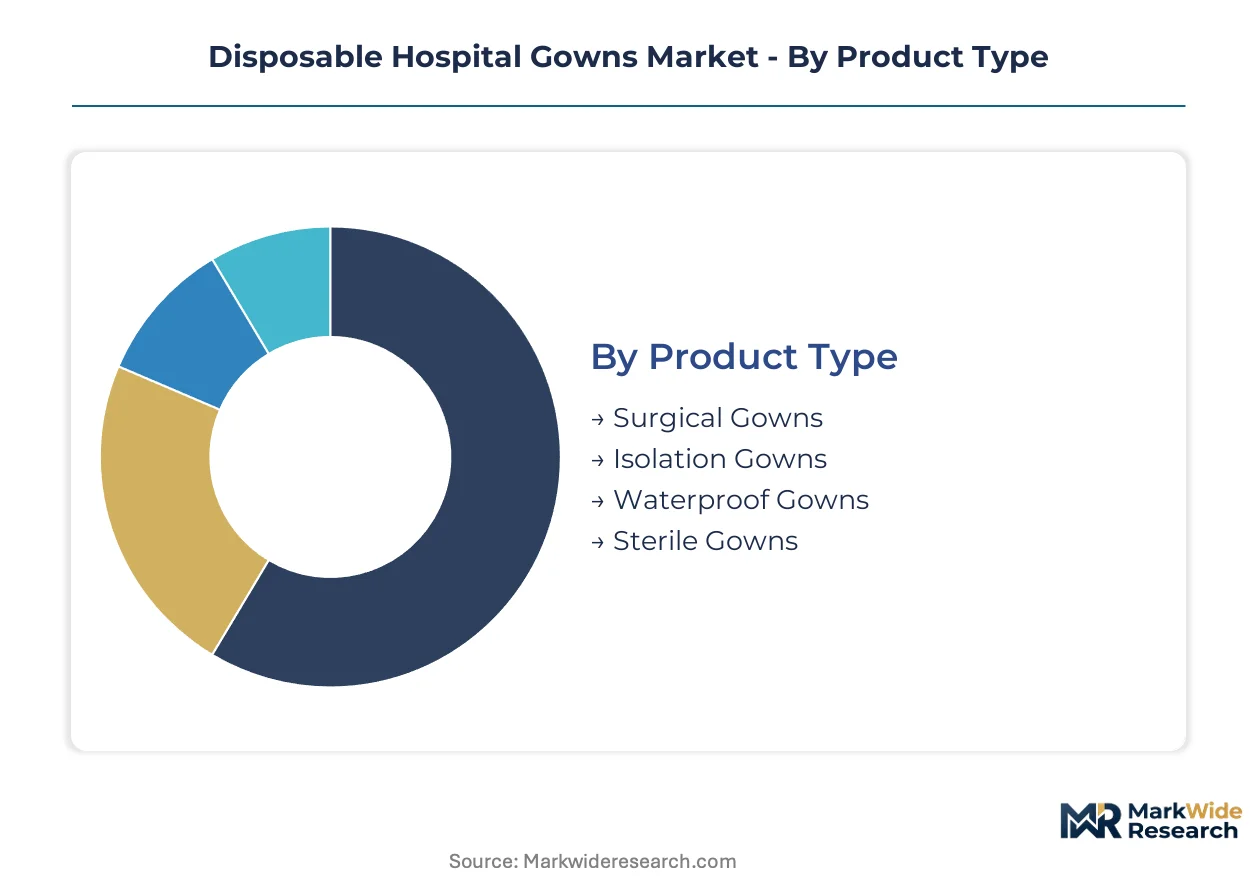
Disposable hospital gown procurement stratifies across four dimensions that determine pricing power and margin capture. Product certification tiers and material specifications create the primary cost differentiation, while end-user concentration and channel control dictate competitive positioning.
Product Type:
Hospital inventory cycles are accelerating replacement of woven reusables with single-use alternatives as AAMI certification requirements tighten across procedure categories.
- Surgical Gowns:Engineered to AAMI Level 3 and 4 liquid barrier standards with reinforced critical zones and sterile packaging. Demand concentrates in United States ambulatory surgical centers migrating outpatient procedures from inpatient settings. Joint Commission audit protocols are forcing procurement upgrades from Level 2 to Level 3 certified inventory.
- Isolation Gowns:Basic polypropylene constructions rated AAMI Level 1 or 2 for contact precaution scenarios. Long-term care facilities in Germany and Japan are expanding procurement as elder-care infection scrutiny intensifies.
- Waterproof Gowns:SMS laminate or polyethylene-coated variants for splash-intensive procedures. EPA PFAS restrictions are forcing reformulation of durable water-repellent finishes without fluorinated chemistry.
- Sterile Gowns:Gamma-irradiated or ethylene oxide-sterilized single-use garments for operating theater use. Sterile packaging requirements add 15-25% unit cost premium over non-sterile equivalents.
Volume placements concentrate in Surgical Gowns; the faster expansion belongs to Isolation Gowns.
Material:
Raw material selection determines barrier performance, breathability, and sterilization compatibility across clinical risk tiers.
- SMS Fabric:Spunbond-meltblown-spunbond laminates delivering intermediate barrier protection with improved wearer comfort. Mid-tier applications in United States hospitals are displacing basic polypropylene as FDA guidance elevates minimum barrier requirements.
- Polypropylene:Spunbond nonwoven base material for economy-tier isolation and visitor gowns. Feedstock volatility in propylene monomer pricing compresses converter margins without captive resin supply.
- Non-Woven:Generic category encompassing spunlace, needlepunch, and thermal-bonded constructions for limited-use applications. Cost positioning suits high-turnover, low-acuity settings.
- Polyester:Woven or nonwoven synthetic for reusable gown systems requiring industrial laundering. Environmental lifecycle assessments favor polyester in markets with established commercial laundry infrastructure.
Procurement volume clusters around SMS Fabric; Polypropylene maintains the steepest expansion trajectory in emerging markets.
End User:
Customer concentration patterns reflect healthcare system consolidation and regulatory enforcement intensity across care settings.
- Hospitals:Integrated delivery networks in the United States Southeast and Midwest are consolidating vendor lists and demanding unit-of-use cost transparency. Billion-dollar supply spend authority enables direct manufacturer contracts with price-lock provisions.
- Long-Term Care Facilities:Nursing homes and assisted living operators face intensified CMS and state-level infection control audits. Germany and Japan represent underpenetrated segments with accelerating regulatory pressure.
- Clinics:Outpatient diagnostic and minor procedure centers with lower barrier certification requirements. Procurement runs through group purchasing organizations or regional distributor relationships.
- Emergency Departments:High-turnover, high-contamination-risk settings requiring rapid donning protocols. Trauma centers prioritize tear-away designs and color-coded sizing systems.
Contract volume concentrates in Hospitals; Long-Term Care Facilities are climbing the fastest as demographic aging accelerates.
Distribution Channel:
Channel structure is bifurcating between consolidated direct relationships and legacy distributor intermediation.
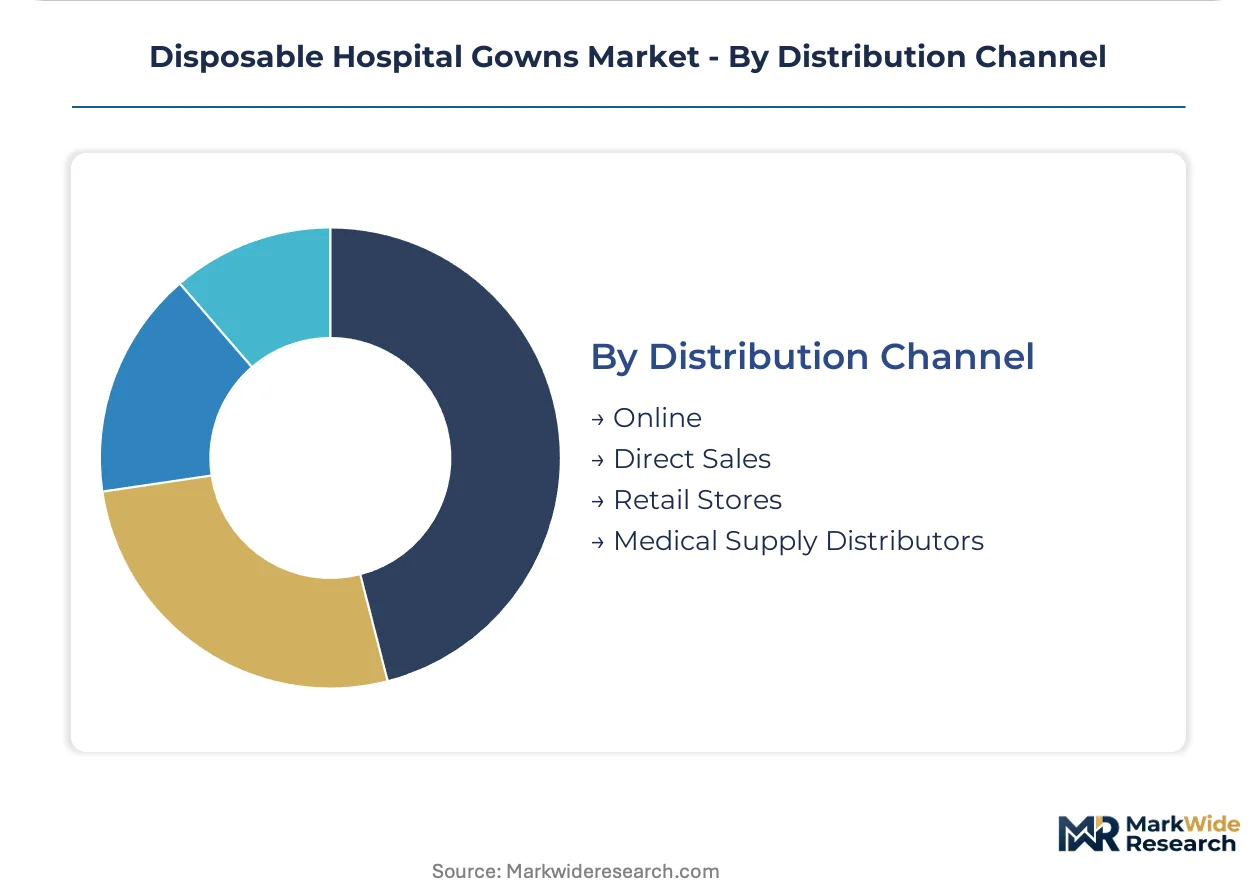
- Direct Sales:Manufacturer contracts with integrated delivery networks and super-IDNs. Electronic data interchange capabilities and logistics density determine competitive qualification.
- Medical Supply Distributors:Owens & Minor and Cardinal Health consolidate gown shipments with broader medical-surgical distribution. Markup compression is displacing traditional distributor economics.
- Online:E-procurement platforms serving smaller clinics and independent practices. Real-time inventory visibility and consignment tracking require expensive ERP customization.
- Retail Stores:Limited presence for consumer-grade protective apparel. Pharmacy chains and medical equipment retailers serve home health and informal caregiver segments.
Shipment value concentrates in Direct Sales; Online channels are gaining share fastest among non-affiliated outpatient providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate sterile apparel manufacturing for North American hospital supply chains, leveraging tariff advantages and FDA-aligned regulatory infrastructure.
United States
Ambulatory surgical centers in Texas and Florida are expanding single-use protective apparel procurement as outpatient migration accelerates. FDA liquid barrier guidance is forcing hospital systems toward AAMI Level 3 certified inventory. Zhejiang and Jiangsu provinces in China supply spunbond nonwoven feedstock to converters in the Southeast and Midwest.
Germany
Nursing facilities in Bavaria and North Rhine-Westphalia face intensified federal infection control audits for elder-care settings. EU MDR certification requirements are elevating clinical evidence standards for gown suppliers. The Eindhoven-Tilburg corridor in the Netherlands hosts coating specialists reformulating water-repellent finishes ahead of REACH PFAS restrictions.
Japan
Long-term care operators in Kansai and Chubu regions are accelerating procurement of isolation gowns as METI enforces stricter nursing home hygiene protocols. PMDA medical device standards align with ISO blood-borne pathogen resistance benchmarks. Osaka-based distributors are consolidating vendor relationships with domestic SMS fabric converters.
China
Spunmelt nonwoven capacity clusters in Yangtze River Delta provinces supply global converters with polypropylene laminates. NMPA medical device registration requirements are tightening for export-oriented manufacturers. Suzhou and Shaoxing industrial zones host meltblown production lines serving Level 4 surgical gown specifications.
India
Hospital procurement committees in Maharashtra and Karnataka are shifting from woven reusables to disposable alternatives as CDSCO aligns with AAMI barrier standards. PLI scheme incentives support domestic nonwoven manufacturing scale-up. Ahmedabad textile clusters are repurposing spunbond capacity for medical-grade SMS constructions.
Disposable Hospital Gowns Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with sterile surgical gown tiers consolidating around direct-IDN relationships while economy isolation gowns fragment across distributor channels. The vendor base organizes into three archetypes: integrated health system suppliers with captive nonwoven production, logistics-heavy distributors consolidating medical-surgical portfolios, and regional converters serving group purchasing organizations. Dominant competitive moves include backward integration into polypropylene resin supply and strategic partnerships with coating formulators navigating PFAS phase-out timelines.
Among North American integrated suppliers, Medline Industries and Cardinal Health occupy positions spanning direct sales and distributor channels. Owens & Minor exemplifies the logistics-density archetype, consolidating gown shipments within broader medical-surgical distribution networks. 3M represents the materials science specialist tier, leveraging polymer expertise across protective apparel categories.
| Leading Market Players |
|---|
| Standard Textile |
| TIDI Products |
| Medline Industries |
| Angelica |
| AmeriPride Services |
| 3M |
| Owens & Minor |
| Dynarex |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Integrated delivery networks in the United States Southeast and Midwest anchor pricing power through billion-dollar supply spend authority and vendor consolidation mandates. Their demand for unit-of-use cost transparency is compressing traditional distributor markups and favoring direct manufacturer contracts with price-lock provisions.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as hospital systems stockpile AAMI Level 3 and 4 certified gowns ahead of Joint Commission audits. Three-tier pricing structure across premium, standard, and economy levels separates sterile surgical gowns from basic isolation garments from visitor-grade polypropylene. Price differentiation hinges on FDA liquid barrier certification tier and captive nonwoven production. Cost compression in economy-tier polypropylene is intensifying because propylene monomer volatility squeezes converter margins. Long-term care facilities exhibit highest price sensitivity; tertiary hospital surgical suites least.
Supply Chain Analysis
Dual-sourcing qualification requirements from United States health systems mandate redundant SMS fabric suppliers across Zhejiang and Jiangsu provinces in China plus domestic converters in the Southeast and Midwest. Raw material flows draw from propylene monomer crackers, meltblown production lines in Suzhou and Shaoxing, and silicone-based coating formulators in the Eindhoven-Tilburg corridor. Single-source vulnerability clusters in Yangtze River Delta spunmelt capacity. Distribution runs through direct sales to super-IDNs and medical-surgical distributors consolidating gown shipments with broader hospital supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA liquid barrier guidance and EU MDR certification erect barrier-to-entry moats favoring manufacturers with notified body relationships and validated sterilization infrastructure.
For Market Incumbents: To counter propylene feedstock volatility and Chinese nonwoven concentration, secure captive resin supply through backward integration into polypropylene production or long-term offtake agreements with Zhejiang-based spunbond converters. Reinforce positioning by accelerating PFAS-free coating partnerships ahead of EPA and REACH phase-out deadlines. For New Entrants and Emerging Players: Begin with nursing facilities in Germany and Japan where regulatory scrutiny of elder-care infection rates is intensifying procurement of AAMI Level 2 isolation gowns. Target group purchasing organization contracts for independent clinics in United States outpatient settings. Pursue EU MDR certification as pricing power anchor. For Investors and Strategic Acquirers: The window for entry favors SMS fabric converters with validated Level 4 gown production and direct-IDN distribution relationships. Long-term viability centers on consolidation plays capturing logistics density and electronic data interchange capabilities. Watch ISO 16604 blood-borne pathogen testing laboratory capacity as inflection signal for Level 4 gown launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Level 3/4 Certification Investment | Joint Commission audit protocols are forcing hospital procurement upgrades from lower-tier inventory. |
| PFAS-Free Coating Partnership | EPA restrictions are forcing reformulation of water-repellent finishes without fluorinated chemistry. |
| Direct-to-IDN Distribution Buildout | Super-IDNs in Texas and Florida are consolidating vendor lists with price-lock contract demands. |
| Captive SMS Fabric Production | Medline Industries leverages in-house nonwoven capacity to control raw material input costs. |
| Long-Term Care Channel Penetration | German and Japanese nursing facilities face intensified federal infection control audits. |
Research Approach
FDA 510(k) filings, EU MDR notified body certificates, and hospital procurement databases formed the secondary backbone of this analysis. Primary interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and SMS fabric converters combined with customs records and SEC 10-K disclosures. Bottom-up and top-down triangulation validated volume estimates across product tiers.
Bottom-up modeling anchored projections across the analysis window by procedure volume migration from inpatient to ambulatory surgical center settings. Segmentation dimensions included AAMI certification level, material specification, end-user care setting, and distribution channel structure. CAGR derivation rested on surgical volume expansion rates and regulatory compliance upgrade cycles. Feedstock cost trajectories and PFAS coating supply disruption timelines served as industry-specific forecast inputs.
Propylene monomer price spikes, ISO 16604 laboratory capacity constraints, and accelerated PFAS phase-out enforcement are the dominant revision risks. Forecasts reflect documented assumptions on surgical procedure migration patterns and health system consolidation trajectories. Deviation in EPA or REACH PFAS restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Global Swab Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Amniotic Products Market
Medical Supplies
Blood Bags Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Global Disposable Blood Bags Market