
 Blood Bags Market | 2026-2036
Blood Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Bags Market Intelligence
Hospital procurement is rewriting how blood bag suppliers secure volume contracts in developed markets. Fresenius Kabi AG leverages its integrated plasma therapy portfolio to anchor long-term supply agreements with transfusion networks. Terumo Corporation competes through manufacturing scale across Asian and European production hubs. Haemonetics Corporation specializes in automated collection systems that bundle disposable blood bags with capital equipment, tightening vendor lock-in.
Blood bags are sterile, single-use containers manufactured from polyvinyl chloride or ethylene vinyl acetate, designed to collect, store, and transfuse blood components while maintaining anticoagulant stability and barrier integrity against oxygen permeation. Whole blood bags retain the largest volume share across hospital use and emergency services, reflecting their foundational role in trauma and surgical protocols. Plasma bags are gaining structural importance as fractionation demand rises for immunoglobulin and albumin production. Polypropylene formulations command premium positioning in platelet storage due to extended shelf-life performance.
FDA leachable and extractable standards, EMA MDR requirements for Class IIa medical devices, and India's CDSCO medical device rules collectively govern material selection, biocompatibility testing, and market access timelines. These frameworks elevate compliance costs for PVC-dependent manufacturers while creating regulatory tailwinds for EVA and polypropylene alternatives. Stakeholders must monitor evolving polymer substitution pathways and regional qualification timelines to align capacity investments with shifting compliance thresholds.
Market Dynamics
Polymer substitution pathways are compressing PVC's dominance as FDA leachable standards and EMA MDR requirements force material qualification cycles that favor ethylene vinyl acetate and polypropylene alternatives with superior barrier performance.
Growth Catalysts
- Surgical Volume Expansion:Rising trauma and oncology procedures across tertiary hospitals are expanding transfusion center procurement cycles. Blood banks in India and Brazil are scaling collection infrastructure to match procedural demand.
- EMA MDR Compliance:Class IIa medical device reclassification is accelerating manufacturer migration toward EVA formulations with documented biocompatibility profiles. European notified bodies are prioritizing polymer substitution dossiers.
- Plasma Fractionation Demand:Immunoglobulin and albumin production lines are driving specialized plasma bag specifications. Fractionators are specifying extended shelf-life polypropylene configurations for cold chain integrity.
Market Restraints
- Phthalate Plasticizer Dependency:DEHP-leachable concerns in PVC formulations are triggering regulatory scrutiny. Manufacturers face reformulation costs and supply chain requalification timelines.
- Specialized Resin Concentration:Medical-grade EVA and polypropylene supply concentrates among petrochemical hubs in Germany, South Korea, and Saudi Arabia. Disruption risks elevate working capital requirements.
- Anticoagulant Integration Complexity:CPDA-1 and SAGM solution stability requirements limit material flexibility. Bag-solution compatibility testing extends product development cycles.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for medical devices are attracting greenfield blood bag manufacturing. CDSCO quality mandates are creating captive demand for domestic EVA extrusion capacity.
- Automated Collection Convergence:Apheresis platform integration with disposable bag sets is tightening vendor relationships. Equipment-bundling models are displacing standalone bag procurement.
- Platelet Additive Solutions:PAS-C and PAS-E formulations are enabling extended platelet storage in specialized polypropylene containers. Transfusion services are specifying these configurations for inventory optimization.
Industry Challenges
- Polymer Science Talent Scarcity:Medical-grade extrusion and film lamination expertise concentrates among aging technical workforces in Japan and Germany. Training pipelines lag EVA adoption curves.
- ISO 3826 Certification Timelines:Blood bag-specific quality management audits require 18-24 month qualification windows. New market entrants face capital lockup before revenue recognition.
- Cold Chain Infrastructure Gaps:Rural collection networks in sub-Saharan Africa and Southeast Asia lack consistent 2-6°C storage. Bag integrity failures compound collection losses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Bags Market |
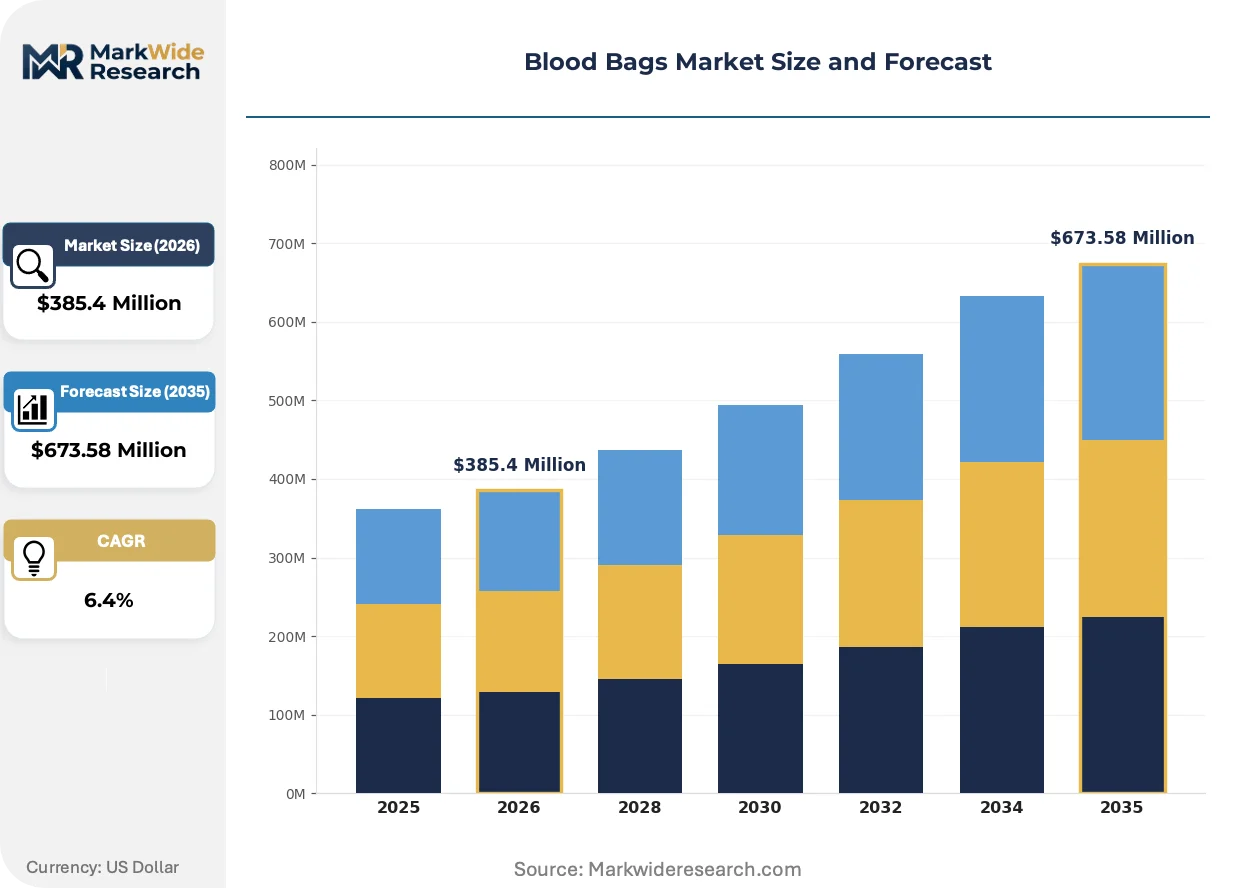
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $673.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Blood Bags, Platelet Bags, Plasma Bags, Storage Bags Material: Polyvinyl Chloride, Ethylene Vinyl Acetate, Polypropylene, PVC Application: Hospital Use, Blood Transfusion Centers, Research Facilities, Emergency Services End User: Blood Banks, Healthcare Providers, Pharmaceuticals, Laboratory Services |
| Companies Covered | Terumo Corporation, Fresenius Kabi AG, Haemonetics Corporation, Grifols S.A., Macopharma, Kawasumi Laboratories Inc., Baxter International Inc., Blood Systems Inc., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Bags Market Strategic Shifts & Innovations
Material science advances are converging with automated manufacturing to redefine blood bag performance specifications. Regulatory pressure on leachable profiles is accelerating polymer substitution beyond traditional PVC formulations.
Ethylene vinyl acetate multilayer films are hybridizing oxygen barrier properties with platelet viability extension. Transfusion centers in Germany and Japan are specifying EVA configurations for extended storage protocols. This material convergence is compressing PVC's installed base while elevating qualification requirements for alternative suppliers.
REACH Annex XVII restrictions on phthalate plasticizers are forcing DEHP elimination timelines across European supply chains. Manufacturers are submitting migration test data to ECHA for EVA and TPE alternatives. Blood bag converters with pre-qualified polymer platforms are capturing requalification-driven procurement shifts.
Consolidated purchasing by hospital networks is displacing fragmented distributor relationships. Integrated delivery networks in the United States are negotiating direct supply agreements with bag manufacturers. This channel compression is most visible in multi-hospital systems seeking standardized inventory across trauma and surgical service lines.
Blood Bags Market Segmentation
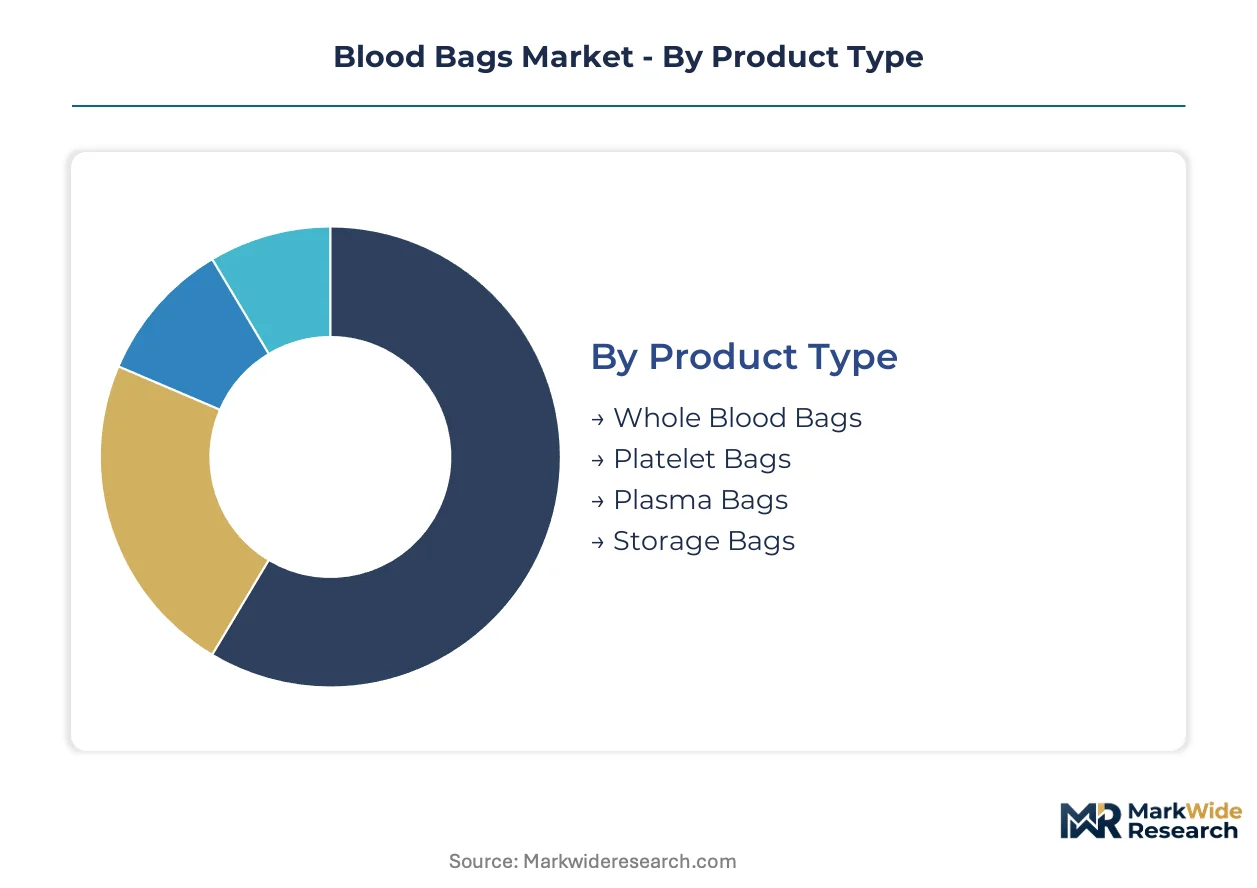
Segmentation in blood bags reflects divergent technical requirements across collection, processing, and storage workflows. Material selection and end-use specifications determine regulatory pathways and procurement economics.
Product Type:
Mature trauma protocols anchor volume in whole blood, while emerging plasma fractionation applications reshape product mix.
- Whole Blood Bags:These units collect and store unseparated blood with CPDA-1 anticoagulant preservation. Hospital emergency departments and military trauma centers in India specify these configurations for massive transfusion protocols.
- Plasma Bags:Designed for apheresis-derived plasma with extended frozen storage compatibility. Fractionation facilities in Germany and the United States are driving demand for specialized barrier films that protect protein integrity through cold chain logistics.
- Platelet Bags:Polypropylene configurations with gas-permeable membranes support 5-7 day platelet viability.
- Storage Bags:Auxiliary containers for cryoprecipitate and red cell concentrates.
Whole blood bags handle the majority of throughput; plasma bags are gaining share fastest on fractionation expansion.
Material:
Cost tiers separate legacy PVC formulations from premium alternatives commanding qualification premiums.
- Polyvinyl Chloride:DEHP-plasticized PVC dominates installed manufacturing capacity with proven extrusion economics. CDSCO and FDA leachable scrutiny is compressing its growth trajectory as hospitals in India and Brazil face requalification deadlines.
- Ethylene Vinyl Acetate:Multilayer EVA films deliver superior oxygen barrier performance with documented biocompatibility profiles. European notified bodies under EMA MDR are fast-tracking EVA dossiers, accelerating substitution in German and French transfusion networks.
- Polypropylene:Rigid formulations for platelet storage with extended shelf-life specifications.
- PVC:Non-DEHP alternatives emerging for pediatric and neonatal applications.
Polyvinyl chloride retains volume leadership; ethylene vinyl acetate climbs the fastest on regulatory tailwinds.
Application:
Customer type concentration distinguishes high-throughput transfusion centers from fragmented point-of-care deployment.
- Blood Transfusion Centers:Centralized collection and processing facilities operate automated apheresis platforms with integrated disposable sets. India's expanding network under the PLI scheme is scaling capacity to match surgical volume growth in tertiary hospitals.
- Hospital Use:Inpatient transfusion services demand just-in-time inventory with cross-matched unit availability. Emergency departments in Brazil and trauma centers in Germany specify pre-screened blood components for rapid deployment.
- Emergency Services:Pre-hospital transfusion in ambulances and military field units.
- Research Facilities:Specialized configurations for cellular therapy and regenerative medicine protocols.
Blood transfusion centers command procurement scale; hospital use is expanding most quickly on surgical volume growth.
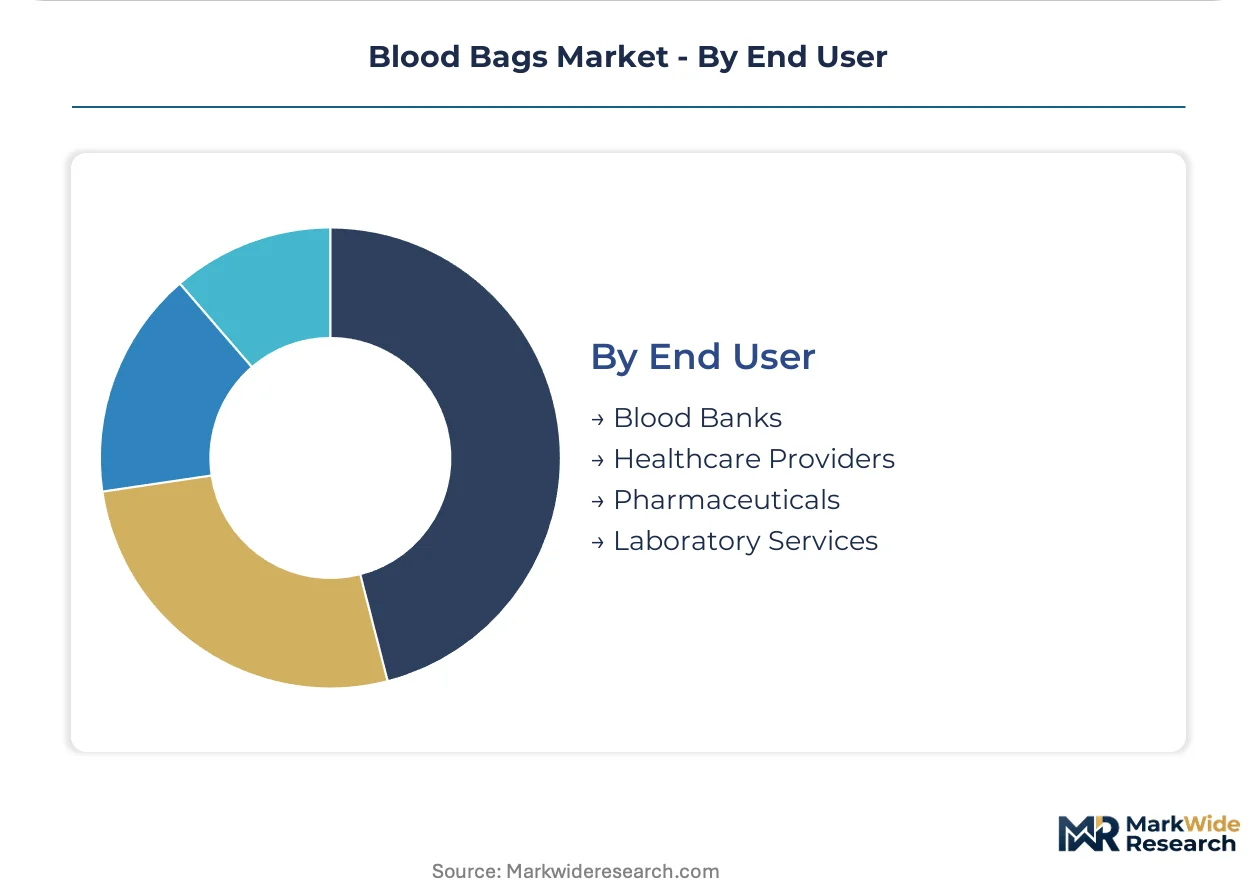
End User:
Margin structures vary across captive blood bank networks versus outsourced laboratory services.
- Blood Banks:National and regional collection networks manage donor recruitment through distribution logistics. India's state-run blood banks are upgrading cold chain infrastructure under CDSCO quality mandates to reduce collection losses.
- Healthcare Providers:Integrated hospital systems negotiate direct supply agreements bypassing distributor markups. Multi-hospital networks in the United States are standardizing blood bag specifications across trauma and surgical service lines.
- Pharmaceuticals:Plasma fractionators sourcing raw material for immunoglobulin and albumin production.
- Laboratory Services:Third-party processing and reference testing operations.
Blood banks anchor procurement volume; healthcare providers are gaining share fastest on channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is catalyzing domestic blood bag manufacturing capacity expansion. CDSCO quality mandates are accelerating facility upgrades across state-run collection networks. Germany, the United States, Brazil, and Japan represent mature markets where regulatory pressure on polymer formulations is reshaping procurement specifications.
India
Tertiary hospital surgical volumes and trauma center expansion are driving transfusion infrastructure investment. CDSCO medical device rules and PLI production-linked incentives are attracting greenfield EVA extrusion facilities. Manufacturing clusters in Gujarat and Maharashtra are scaling domestic supply chains to reduce import dependency.
Germany
Plasma fractionation facilities and automated apheresis platform deployment anchor demand for specialized barrier films. EMA MDR Class IIa reclassification and REACH Annex XVII phthalate restrictions are accelerating EVA formulation adoption. The Rhine-Ruhr industrial corridor hosts concentrated medical-grade polymer compounding capacity serving European transfusion networks.
United States
Integrated delivery network consolidation and military trauma protocol standardization are concentrating procurement volume. FDA leachable and extractable standards for DEHP-plasticized PVC are forcing material requalification timelines. The Boston-Cambridge medical technology cluster anchors automated collection system development with bundled disposable strategies.
Brazil
Blood bank network modernization and oncology procedure expansion are scaling collection infrastructure requirements. ANVISA medical device regulations are aligning with international biocompatibility standards for polymer formulations. São Paulo's industrial corridor concentrates domestic bag conversion capacity serving Latin American distribution networks.
Japan
Aging demographics and surgical volume stabilization are sustaining replacement-driven demand for high-performance storage configurations. PMDA quality management requirements and METI industrial policy are supporting domestic EVA film lamination expertise. The Kansai region maintains concentrated technical workforce pools for medical-grade extrusion processes.
Blood Bags Market Key Industry Players
On the supply side, the industry is consolidating around integrated therapy portfolios and automated platform bundling. Three strategic archetypes dominate: diversified medical technology conglomerates with transfusion product lines, specialized blood management equipment manufacturers with captive disposable supply, and regional polymer converters serving price-sensitive procurement channels. Competitive moves center on polymer qualification dossier submission to European notified bodies and apheresis platform-disposable set integration contracts.
Within the diversified conglomerate tier, Terumo Corporation and Fresenius Kabi AG exemplify integrated portfolio strategies that anchor long-term supply agreements through therapy breadth rather than standalone bag economics. Haemonetics Corporation occupies a specialized position representing the equipment-bundling archetype, where automated collection system deployment creates captive demand for matched disposable sets. These three companies collectively illustrate how competitive positioning in blood bags increasingly depends on system-level relationships rather than component pricing alone.
| Leading Market Players |
|---|
| Terumo Corporation |
| Fresenius Kabi AG |
| Haemonetics Corporation |
| Grifols S.A. |
| Macopharma |
| Kawasumi Laboratories Inc. |
| Baxter International Inc. |
| Blood Systems Inc. |
| Medtronic plc |
| Others |
Cost & Logistics Intelligence
The Rhine-Alpine freight corridor's container rate volatility directly compresses margins for European blood bag converters while amplifying price spreads between medical-grade EVA formulations and legacy PVC alternatives. Supply concentration in German polymer compounding hubs intersects with CDSCO-mandated facility upgrades in India to create divergent cost structures across procurement tiers.
Pricing Analysis
Certification level (ISO 3826/FDA-grade/CE-marked) creates the primary spread between premium EVA configurations and standard PVC alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects qualification timelines and barrier performance specifications. Cost compression in standard PVC tiers is intensifying because DEHP reformulation requirements extend development cycles. Blood transfusion centers in India and Brazil exhibit highest price sensitivity, while plasma fractionators in Germany and the United States prioritize shelf-life performance over unit economics.
Supply Chain Analysis
Tariff exposure between South Korea and India dominates risk calculus for medical-grade EVA resin procurement. Supply concentrates in Germany, South Korea, and Saudi Arabia for specialized polymer compounding, with secondary conversion capacity in India and Brazil. Raw material dependencies include ethylene-vinyl acetate copolymers, medical-grade polypropylene, and DEHP-free plasticizer alternatives. Single-source vulnerability for multilayer film lamination equipment elevates capital lockup for new entrants. Distribution runs through integrated delivery networks in developed markets and fragmented distributor channels in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer substitution timelines are compressing PVC's installed base as EMA MDR Class IIa reclassification and FDA leachable standards converge to reshape procurement specifications. This regulatory inflection creates asymmetric opportunity for qualified alternative suppliers.
For Market Incumbents: Pre-empt margin erosion in PVC-dependent product lines by accelerating EVA qualification dossier submissions to European notified bodies. Anchor long-term supply agreements through apheresis platform bundling that tightens vendor lock-in against emerging entrants. Defensive capacity addition in Gujarat and Maharashtra under India's PLI scheme secures cost-competitive positioning for Asian procurement cycles. For New Entrants and Emerging Players: Rural blood bank networks in sub-Saharan Africa present the most penetrable white-space target, given cold chain infrastructure gaps and fragmented distributor relationships. Specialized platelet additive solution configurations offer technical differentiation with lower certification barriers than whole blood systems. Direct supply contracting with state-run collection networks bypasses entrenched distributor relationships in price-sensitive procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated collection system manufacturers with captive disposable supply and pre-qualified polymer platforms. Long-term viability rests on equipment-bundling models that generate recurring revenue streams across replacement cycles. Acquisition targets should demonstrate EMA MDR dossier progress and established relationships with European transfusion networks. The signal to monitor is CDSCO enforcement action against non-compliant PVC imports, which would accelerate domestic EVA capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EVA Polymer Qualification Dossier | EMA MDR fast-track approval unlocks procurement access across German and French transfusion networks. |
| Apheresis Platform Integration | Automated collection system bundling tightens vendor relationships and displaces standalone bag procurement. |
| India PLI Manufacturing Footprint | Domestic extrusion capacity reduces import dependency and aligns with CDSCO quality mandate timelines. |
| Platelet Additive Solution Development | PAS-C and PAS-E formulations enable extended storage specifications for inventory optimization contracts. |
| Cold Chain Infrastructure Partnership | Rural collection network upgrades in target geographies reduce bag integrity failures and collection losses. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and hospital procurement records. Interviews with biomedical engineers, transfusion center directors, GPO contracts managers, and polymer compounding specialists informed demand-side validation. Secondary sources include FDA 510(k) filings, EMA MDR submission databases, CDSCO medical device registrations, and customs import data for medical-grade polymers. Bottom-up unit economics triangulate against top-down market sizing across product type, material, and end-user segments.
Forecast inputs incorporate surgical volume trajectories, regulatory qualification timelines, and polymer substitution elasticity across the projection horizon. Segmentation dimensions modeled include product type (whole blood, plasma, platelet, storage), material formulation (PVC, EVA, polypropylene), application (transfusion center, hospital, emergency services), and regional regulatory cluster. CAGRs derive from weighted capacity expansion schedules and procurement cycle analysis. Industry-specific inputs include anticoagulant solution compatibility testing durations and ISO 3826 certification audit windows.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by petrochemical conglomerates into medical-grade EVA would shift supply-side pricing power. Macroeconomic volatility in resin feedstock costs, regulatory acceleration of DEHP elimination timelines, or breakthroughs in biodegradable barrier materials would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Medical Liners Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Breast Shells Market
Medical Supplies
Disposable Sanitary Pad Market