
 Isolation Gowns Market | 2026-2036
Isolation Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Isolation Gowns Market Insights
Hospital buyer concentration is decoupling from traditional distributor relationships as integrated delivery networks centralize isolation gown procurement through direct manufacturer contracts. Cardinal Health leverages its captive distribution infrastructure to sustain volume commitments with large health systems. Medline Industries anchors its position through private-label manufacturing scale across multiple material grades. Owens & Minor competes by specializing in logistics-intensive contract structures that reduce carrying costs for consolidated buyers.
Isolation gowns are barrier garments engineered from spunbond-meltblown-spunbond (SMS) composites or polypropylene laminates to achieve specified AAMI liquid-borne pathogen resistance levels for healthcare worker protection. Disposable gowns dominate hospital procurement due to infection control protocols, while reusable polyester gowns retain share in ambulatory surgical centers prioritizing waste reduction programs. Material segmentation shows SMS fabrics capturing premium positioning through superior breathability-to-barrier ratios, whereas polypropylene variants occupy high-volume standard precaution applications.
The FDA enforces AAMI PB70 performance classifications for surgical isolation gowns, while OSHA's Bloodborne Pathogens Standard mandates appropriate barrier protection selection in clinical environments. The EPA regulates antimicrobial claims on treated gown surfaces, creating compliance complexity for manufacturers incorporating silver-ion or other biostatic additives. Stakeholders must monitor evolving AAMI test method revisions and state-level healthcare waste regulations that could alter the disposable-reusable equilibrium without warning.
Market Dynamics
Hospital procurement consolidation is compressing distributor margins and forcing manufacturers to restructure go-to-market economics around direct-contract service models. Integrated delivery networks now centralize gown sourcing through single-source agreements that bundle infection control products across multiple facility tiers.
Growth Catalysts
- Strategic Stockpile Mandates:US health systems are rebuilding pandemic-era reserves under CDC preparedness guidelines, creating durable demand for Level 3 and Level 4 AAMI-rated barrier garments.
- SMS Fabric Technology:Spunbond-meltblown-spunbond composites achieve superior breathability-to-barrier ratios, displacing basic polypropylene in surgical isolation applications.
- India:CDSCO harmonization with international medical device standards is accelerating domestic manufacturing capacity for export-grade isolation gowns.
Market Restraints
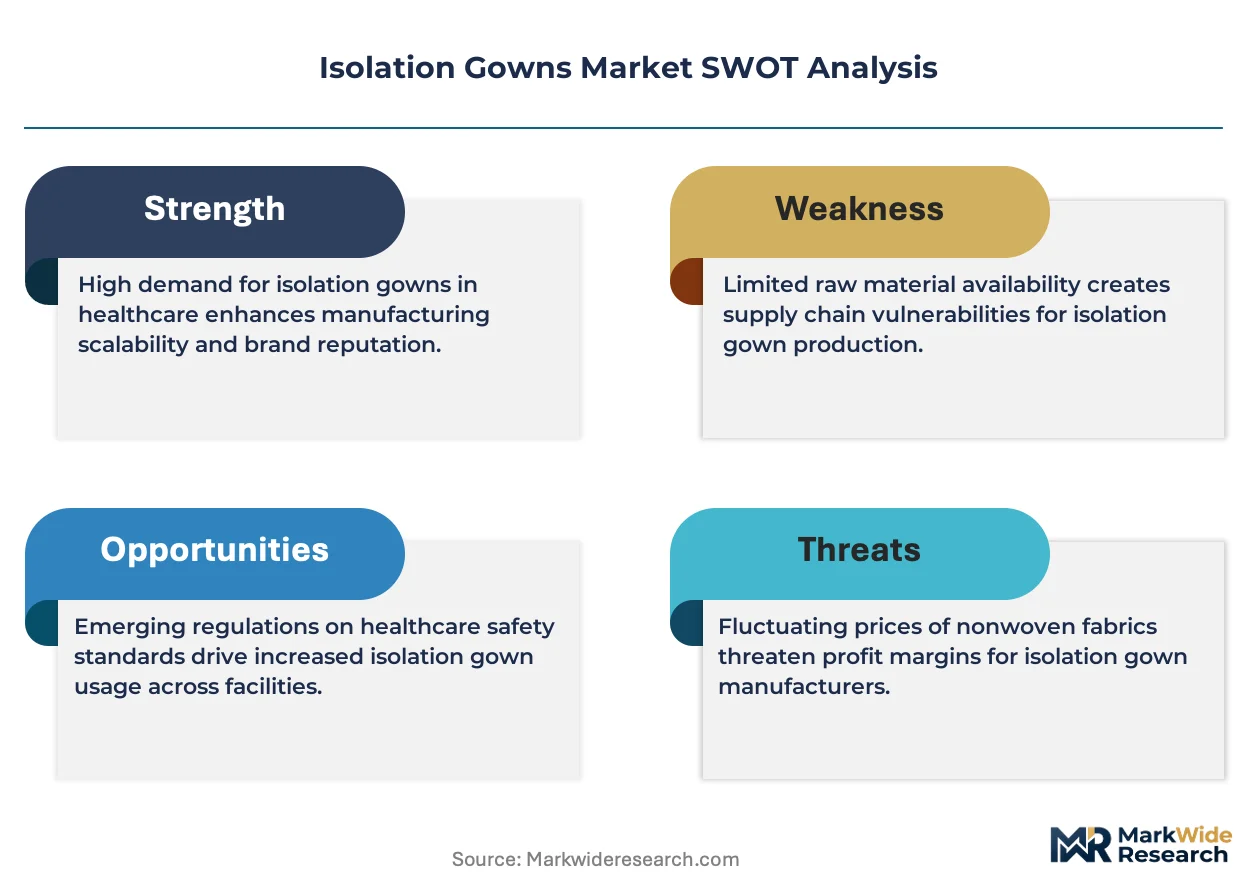
- Polypropylene Feedstock Volatility:Crude-linked propylene monomer costs swing gown manufacturing economics unpredictably, squeezing margin visibility for converters.
- China Concentration Risk:Raw SMS substrate and meltblown media production clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability for global supply chains.
- AAMI PB70 Testing Bottlenecks:Limited accredited laboratory capacity for liquid-borne pathogen resistance certification extends product launch timelines by 4-8 months.
Strategic Opportunities
- Brazil ANVISA Fast-Track:Expedited medical device registration for pandemic preparedness products opens Latin American market entry for compliant manufacturers.
- Reusable Gown Programs:Polyester-based laundering systems penetrate ambulatory surgical centers seeking waste reduction compliance with EPA healthcare waste regulations.
- E-commerce Direct Procurement:Amazon Business and specialized healthcare marketplaces enable mid-size hospital systems to bypass traditional distributor markups.
Industry Challenges
- Antimicrobial Claim Substantiation:EPA FIFRA registration requirements for silver-ion or copper-treated gowns demand extensive efficacy data, delaying commercialization.
- Legacy ERP Integration:Hospital materials management systems require custom EDI mapping for automated reorder triggers on consumption-based contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolation Gowns Market |
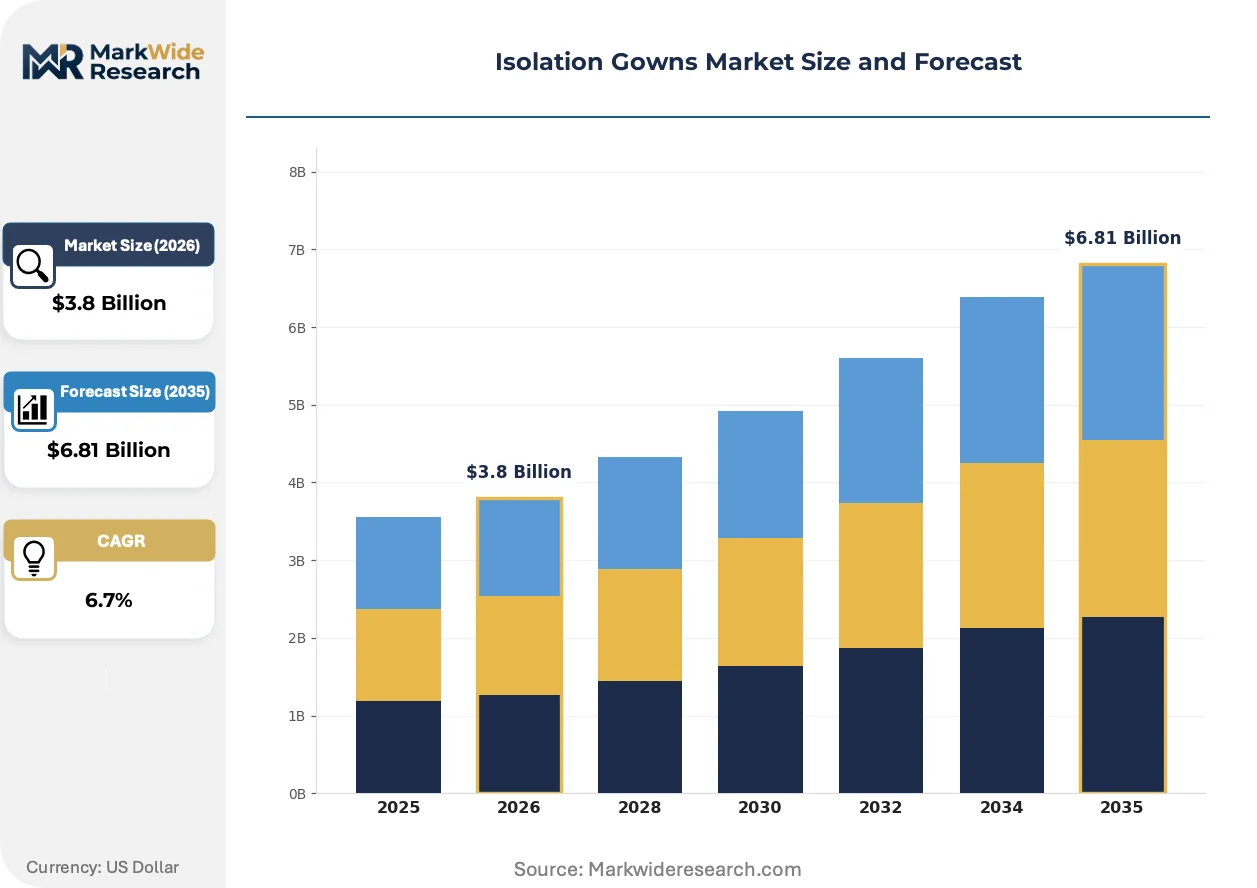
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gowns, Non-Surgical Gowns, Disposable Gowns, Reusable Gowns Material: Polypropylene, SMS, Polyester, PVC End User: Hospitals, Clinics, Home Care, Laboratories Distribution Channel: Online Retail, Direct Sales, Medical Suppliers, Wholesalers |
| Companies Covered | Cardinal Health, Medline Industries, 3M, Mölnlycke Health Care, Kimberly-Clark, Owens & Minor, McKesson, DuPont, Paul Hartmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolation Gowns Market Trends and Innovations
Material science breakthroughs and procurement digitization are converging to redefine how barrier protection is specified, sourced, and consumed across acute care settings. These shifts compress traditional product lifecycles while elevating performance verification standards.
Biodegradable PLA-based nonwovens are integrating into isolation gown construction as health systems face mounting pressure to reduce single-use plastic waste volumes. European hospital groups pilot these materials in standard precaution applications where AAMI Level 1 barrier requirements apply. The technology is integrating circular economy mandates into supplier qualification criteria, forcing incumbent manufacturers to develop compostable alternatives or risk exclusion from sustainability-focused tenders.
REACH restriction proposals on per- and polyfluoroalkyl substances (PFAS) are compelling gown producers to reformulate durable water-repellent finishes on reusable polyester garments. The European Chemicals Agency's 2023 restriction roadmap targets PFAS elimination in textiles by 2026, accelerating fluorine-free chemistry adoption. German and French hospital procurement coalitions now require PFAS-free certifications in competitive bids, shifting R&D investment toward silicone and hydrocarbon-based repellency systems.
Consumption-based replenishment models displace fixed-quantity purchasing contracts as integrated delivery networks seek to reduce carrying costs and obsolescence risk. RFID-tagged gown cabinets track real-time utilization at the unit level, triggering automatic reorders through cloud-based inventory platforms. This pattern is most visible in US multi-hospital systems where Cardinal Health and Owens & Minor deploy vendor-managed inventory infrastructure.
Isolation Gowns Market Segmentation
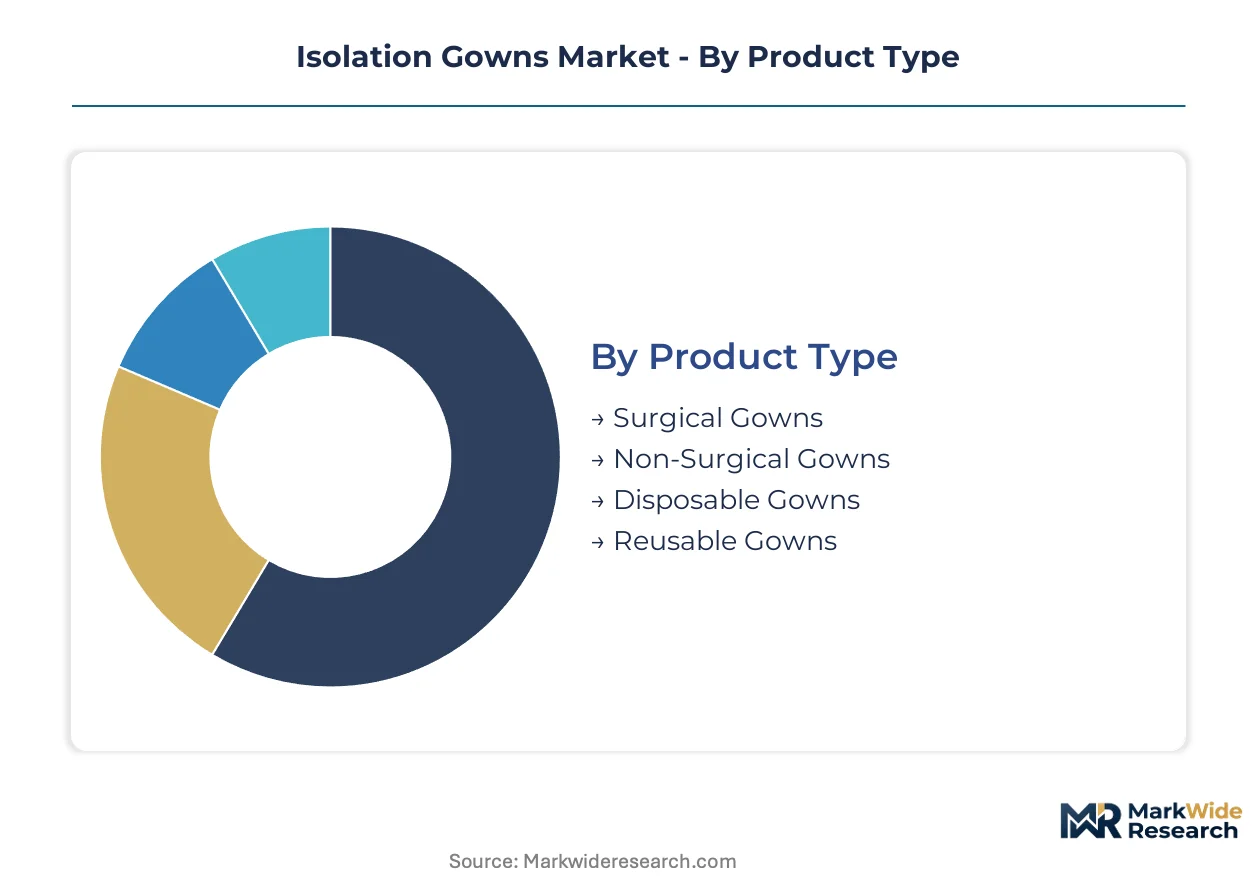
Material specifications and barrier performance ratings determine procurement priorities across acute care settings. Hospital supply chains segment gown sourcing by infection risk level, laundering economics, and end-use environment constraints.
Product Type:
Replacement cycles vary sharply between single-use disposables and laundered reusables, with surgical applications demanding the most frequent turnover.
- Surgical Gowns:Engineered to AAMI PB70 Level 3 and Level 4 standards with reinforced critical zones for invasive procedures. Demand concentrates in US tertiary care centers rebuilding strategic reserves under CDC preparedness guidelines, where single-source vendor contracts bundle these with other barrier products.
- Disposable Gowns:Spunbond-meltblown-spunbond composites dominate this segment for their breathability-to-barrier ratio in high-turnover isolation scenarios. Integrated delivery networks in the United States favor these for standardized precaution protocols across multi-facility systems.
- Non-Surgical Gowns:Basic polypropylene variants serve visitor protection and low-risk clinical encounters where AAMI Level 1 resistance suffices.
- Reusable Gowns:Polyester-based systems with 75-100 wash cycles penetrate ambulatory surgical centers prioritizing waste reduction compliance with EPA healthcare waste regulations.
Volume placements concentrate in Disposable Gowns; the faster expansion belongs to Reusable Gowns.
Material:
Raw material cost tiers separate premium barrier performance from commodity applications, with feedstock volatility reshaping converter economics.
- SMS:Spunbond-meltblown-spunbond tri-laminate structures achieve superior particle filtration while maintaining clinician comfort during extended wear. US hospital procurement coalitions specify SMS for surgical isolation applications where breathability reduces heat stress complaints.
- Polypropylene:Homopolymer spunbond nonwovens occupy high-volume standard precaution applications where cost minimization overrides performance margins. Chinese Zhejiang and Jiangsu province concentration for raw substrate creates supply vulnerability for converters dependent on imported rolls.
- Polyester:Woven or knitted constructions enable industrial laundering cycles for reusable gown programs in sustainability-focused health systems.
- PVC:Impermeable films provide chemical splash protection in laboratory and pharmaceutical manufacturing environments where liquid-borne hazard exposure differs from clinical pathogen risks.
Polypropylene dominates current procurement volumes; SMS gains share fastest in surgical tier upgrades.
End User:
Customer scale and infection control sophistication create divergent specification requirements across care settings.
- Hospitals:Acute care systems with 500+ beds drive Level 3 and Level 4 AAMI-rated demand through centralized materials management. US integrated delivery networks consolidate gown sourcing across 10-50 facility footprints, extracting volume discounts from direct manufacturer contracts.
- Clinics:Outpatient and urgent care settings favor Level 1 and Level 2 disposables for lower-acuity patient encounters with reduced fluid exposure probability.
- Home Care:Family caregivers and home health aides utilize basic barrier garments for immunocompromised patient contact, with procurement fragmented across retail and durable medical equipment channels.
- Laboratories:Research and diagnostic facilities specify chemical-resistant materials distinct from clinical pathogen barriers, creating specialized demand for PVC and coated fabric alternatives.
Hospital systems anchor procurement volumes; home care climbs fastest as post-acute diversion expands.
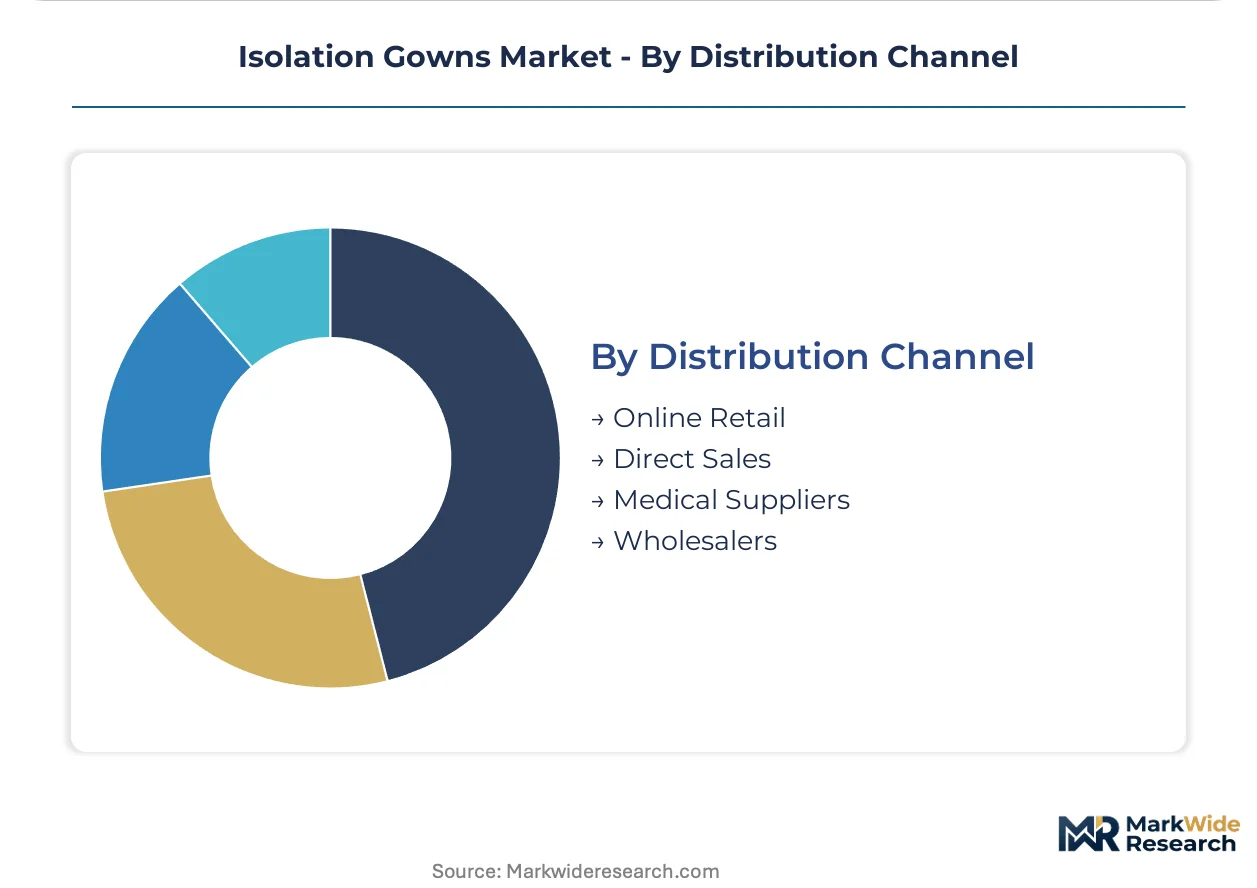
Distribution Channel:
Channel economics determine margin capture between manufacturers and end users, with digitization disrupting traditional intermediaries.
- Direct Sales:Manufacturer contracts with integrated delivery networks eliminate distributor markups for high-volume hospital systems. Cardinal Health and Owens & Minor deploy vendor-managed inventory infrastructure to defend position against this disintermediation.
- Medical Suppliers:Specialized distributors retain relevance for mid-size hospitals lacking procurement scale for direct manufacturer negotiation, bundling gowns with broader infection control portfolios.
- Online Retail:Amazon Business and healthcare marketplaces enable smaller facilities and home care buyers to bypass traditional channel markups with transparent pricing.
- Wholesalers:Regional distributors serve rural and independent facilities outside major health system networks, carrying inventory for emergency replenishment.
Direct Sales commands the largest transaction values; Online Retail expands most quickly as procurement digitization penetrates mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene monomer availability clusters in Texas and Louisiana anchor North American converter economics, while Zhejiang and Jiangsu provinces dominate SMS substrate fabrication for Asian supply chains.
United States
Integrated delivery networks in Texas, California, and the Northeast corridor consolidate procurement through direct manufacturer contracts. CDC strategic stockpile mandates under the Public Health Emergency Preparedness program drive Level 3 and Level 4 AAMI-rated gown demand. Houston and Dallas-Fort Worth host converter operations that source polypropylene from Gulf Coast petrochemical complexes.
China
Raw SMS tri-laminate and meltblown media production concentrates in Zhejiang and Jiangsu provinces for export-grade isolation gown supply. NMPA harmonization with ISO 13485 quality management standards accelerates domestic medical device registration. The Yangtze River Delta industrial corridor houses vertically integrated nonwoven converters serving European and North American hospital procurement channels.
Germany
REACH restriction proposals on PFAS chemicals drive reformulation of durable water-repellent finishes for reusable polyester gowns. The country's national pharmaceutical regulator, BfArM, coordinates with ECHA on textile chemical safety assessments. The North Rhine-Westphalia industrial belt hosts laundering system providers serving ambulatory surgical centers across the Benelux region.
India
CDSCO alignment with international medical device standards accelerates domestic manufacturing capacity for export-grade barrier garments. The Production Linked Incentive scheme for textiles supports nonwoven converter expansion in Gujarat and Tamil Nadu. The Mumbai-Pune industrial corridor attracts contract manufacturers targeting Middle East and African hospital procurement channels.
Brazil
ANVISA fast-track registration for pandemic preparedness products opens Latin American market entry for compliant gown manufacturers. São Paulo and Rio de Janeiro health systems prioritize local sourcing to reduce import dependency for infection control products. The Southeast industrial region hosts emerging converters serving Mercosur hospital networks.
Isolation Gowns Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability-certified and reusable system segments. The vendor base stratifies across three tiers: multinational health supply conglomerates with captive distribution, specialized medical textile converters with regional manufacturing footprints, and commodity nonwoven fabricators competing on polypropylene cost. Three archetypes dominate: integrated distributors bundling gowns across infection control portfolios, pure-play barrier garment specialists with AAMI certification depth, and upstream nonwoven producers forward-integrating into finished goods. Competitive moves concentrate on direct-contract service models and vendor-managed inventory infrastructure.
Among North American integrated distributors, Cardinal Health, Owens & Minor, and McKesson exemplify the scale-driven archetype. These entities anchor their positions through logistics-intensive contract structures and consumption-based replenishment platforms. Cardinal Health represents the distributor-manufacturer hybrid model, while Owens & Minor occupies a position within logistics-centric procurement channels. McKesson sits within the pharmaceutical-distributor diversification archetype, leveraging existing health system relationships.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| 3M |
| Mölnlycke Health Care |
| Kimberly-Clark |
| Owens & Minor |
| McKesson |
| DuPont |
| Paul Hartmann |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer costs originating from Gulf Coast petrochemical complexes flow through converter economics to stratify gown pricing across AAMI certification tiers, with Level 3 and Level 4 surgical barriers commanding substantial premiums over standard precaution polypropylene variants due to SMS tri-laminate material intensity and extended testing protocols.
Pricing Analysis
Service bundling separates vendor-managed inventory agreements with automated replenishment from transactional spot purchases, with the former embedding logistics and carrying cost absorption into contracted unit rates. Three-tier pricing structure across premium, standard, and economy levels aligns with AAMI PB70 Level 4, Level 2-3, and Level 1 barrier ratings respectively. Cost compression in standard precaution tiers is intensifying because Chinese polypropylene substrate imports face margin pressure from domestic converter expansion. Ambulatory surgical centers exhibit highest price sensitivity due to limited procurement scale, while integrated delivery networks leverage volume concentration for least-sensitive positioning.
Supply Chain Analysis
Regional distribution centers in Texas, California, and the Northeast corridor operate hub-and-spoke patterns serving multi-hospital systems with 48-hour replenishment cycles. Raw SMS substrate and meltblown media production clusters in China's Zhejiang and Jiangsu provinces, with secondary converter capacity in India and Vietnam. Single-source vulnerability concentrates in Yangtze River Delta fabric mills where 75-100 wash cycle reusable polyester systems also originate. Distribution runs through direct manufacturer contracts for large health systems, while specialized medical suppliers retain mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where FDA's updated AAMI PB70 guidance and EPA FIFRA antimicrobial claim requirements erect substantial barrier-to-entry moats favoring incumbent manufacturers with established certification infrastructure and testing relationships.
For Market Incumbents: Cement market position by deepening captive SMS manufacturing capacity in Texas and Louisiana corridor to offset China concentration risk, while simultaneously securing exclusive vendor-managed inventory contracts with top-20 integrated delivery networks. Emerging pure-play barrier garment specialists with AAMI certification depth represent the primary competitive threat requiring preemptive channel lock-up.
For New Entrants and Emerging Players: Capture white-space opportunity in PFAS-free reusable polyester gown programs targeting German and French hospital procurement coalitions ahead of ECHA's 2026 restriction enforcement. Brazil's ANVISA fast-track pathway offers the most penetrable regulatory entry point for pandemic preparedness product registration. Go-to-market execution should prioritize direct e-commerce procurement channels via Amazon Business to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: CDSCO harmonization completion with ISO 13485 standards in India is the leading indicator that export-grade manufacturing capacity will consolidate toward Gujarat and Tamil Nadu production clusters. Five-to-ten year viability favors acquisition targets possessing dual AAMI PB70 certification capability and established GPO contract relationships. Watch for EPA FIFRA registration approvals on silver-ion treated gowns as signal of differentiated product pipeline maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| AAMI PB70 Level 4 Certification Investment | Unlocks surgical isolation gown procurement in CDC strategic stockpile channels. |
| PFAS-Free Chemistry Reformulation | Secures competitive bid eligibility under ECHA's 2026 REACH restriction roadmap. |
| Vendor-Managed Inventory Deployment | Defends distributor position against direct manufacturer contract disintermediation. |
| CDSCO Registration Completion | Enables export-grade supply to Middle East and African hospital networks. |
| Reusable Gown Laundering System Partnership | Captures ambulatory surgical center waste reduction compliance demand. |
Research Methodology
Document review covered FDA 510(k) filings, EPA FIFRA registration databases, hospital GPO contract repositories, and AAMI laboratory accreditation records, complemented by interviews with hospital procurement directors, biomedical engineers, infection control specialists, and nonwoven converter operations managers. Secondary validation drew from CDC preparedness guidelines, ECHA restriction roadmaps, and CDSCO medical device registration disclosures. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Output quantification proceeded across material type, barrier performance tier, end-use setting, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis against propylene feedstock price indices, health system capital expenditure cycles, and regulatory compliance cost trajectories. Modeling incorporated AAMI PB70 test method revision timelines and state-level healthcare waste regulation evolution as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to propylene monomer volatility, China-Taiwan logistics disruption, and AAMI standard revision timing. Outputs reflect documented assumptions around health system strategic stockpile rebuild rates and integrated delivery network consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Cooling Mattress Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Menstrual Sponge Market