
 Asia-Pacific Syringe Market | 2026-2036
Asia-Pacific Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Syringe Market Insights
India's Gujarat pharmaceutical corridor is reshaping regional supply dynamics for disposable injection devices. Becton Dickinson and Company leverages its safety-engineered portfolio to dominate high-specification hospital contracts across Southeast Asia. Terumo Corporation sustains manufacturing scale through vertically integrated polymer processing in Japan and Thailand. Hindustan Syringes & Medical Devices Limited anchors India's government tender ecosystem with cost-optimized standard syringe output.
A syringe is a cylindrical medical device fitted with a plunger and hollow needle for precise fluid aspiration or injection, typically manufactured through injection molding of medical-grade polypropylene or borosilicate glass forming with subsequent siliconization for plunger glide. Its primary purpose spans therapeutic drug delivery, vaccine administration, and diagnostic specimen collection across acute and ambulatory care settings. Safety syringes command premium positioning due to needlestick prevention mandates, while prefilled syringes are gaining fastest traction among biologics manufacturers seeking reduced contamination risk and dosing accuracy. Standard syringes retain volume dominance in emerging economies where cost sensitivity governs public health procurement.
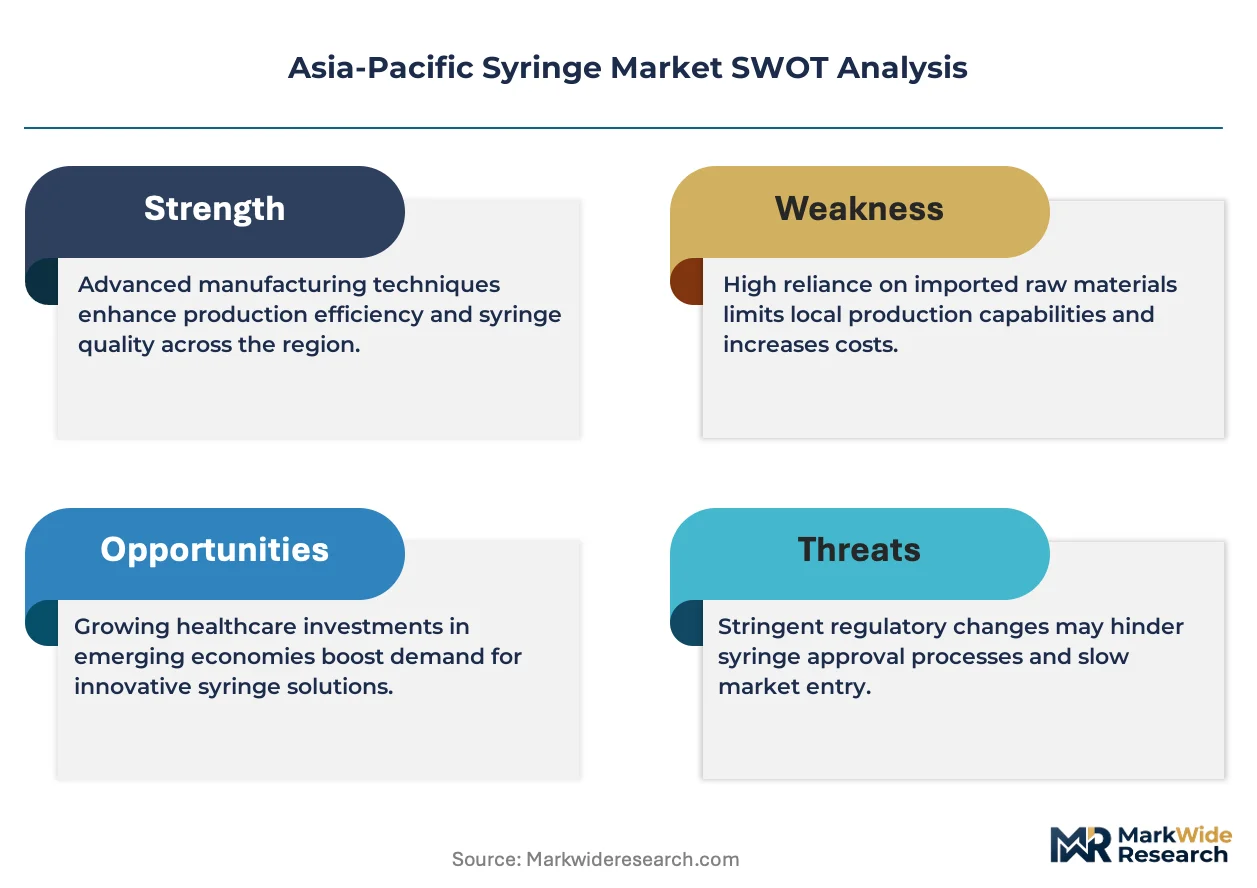
Japan's PMDA enforces stringent quality management system requirements for medical device manufacturing, elevating compliance costs for new entrants. India's CDSCO implements mandatory medical device registration under the Drugs and Cosmetics Act, channeling import substitution toward domestic producers. China's NMPA revised medical device classification rules now require clinical evidence for novel syringe designs, lengthening approval timelines. Stakeholders must monitor evolving prequalification standards for WHO procurement programs and calibrate regional manufacturing footprints against shifting national essential medicines list specifications.
Market Dynamics
Safety-engineered syringe mandates across Southeast Asian hospital systems are compressing procurement cycles for standard devices while elevating technical specifications for tender participation. India's CDSCO medical device registration requirements are channeling import substitution toward domestic polymer processing clusters.
Growth Catalysts
- Immunization program scale-up:India's Universal Immunization Programme and Indonesia's national vaccination drives are expanding institutional procurement of auto-disable syringes for single-use compliance.
- CDSCO regulatory harmonization:India's mandatory medical device registration under the Drugs and Cosmetics Act is accelerating domestic manufacturing certification and reducing import dependency.
- Polymer feedstock localization:Thailand's petrochemical corridor is enabling captive medical-grade polypropylene supply for Southeast Asian syringe molders.
Market Restraints
- Medical-grade polymer price volatility:Polypropylene resin costs fluctuate with naphtha cracking margins, compressing margin stability for high-volume standard syringe producers.
- Single-source sterilization dependency:Gamma irradiation capacity concentrates in Japan and South Korea, creating cross-border logistics vulnerability for ASEAN manufacturers.
- Siliconization chemistry constraints:Dow Corning's medical-grade silicone oil supply tightness limits plunger glide optimization for safety syringe engineering.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing emergence:Ho Chi Minh City's injectables sector is creating demand for prefillable syringe systems for biologics export.
- Japan PMDA quality management elevation:Stringent GMP enforcement is forcing regional competitors toward ISO 13485 certification parity, opening premium hospital contract access.
- Digital twin integration:Mold flow simulation and predictive maintenance convergence is reducing injection molding defect rates for complex safety mechanism geometries.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queue times at accredited Asia-Pacific laboratories, delaying novel safety mechanism launches.
- Cleanroom capex intensity:ISO Class 7 molding environments require $4-6 million per production line for particulate and microbial control compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Syringe Market |
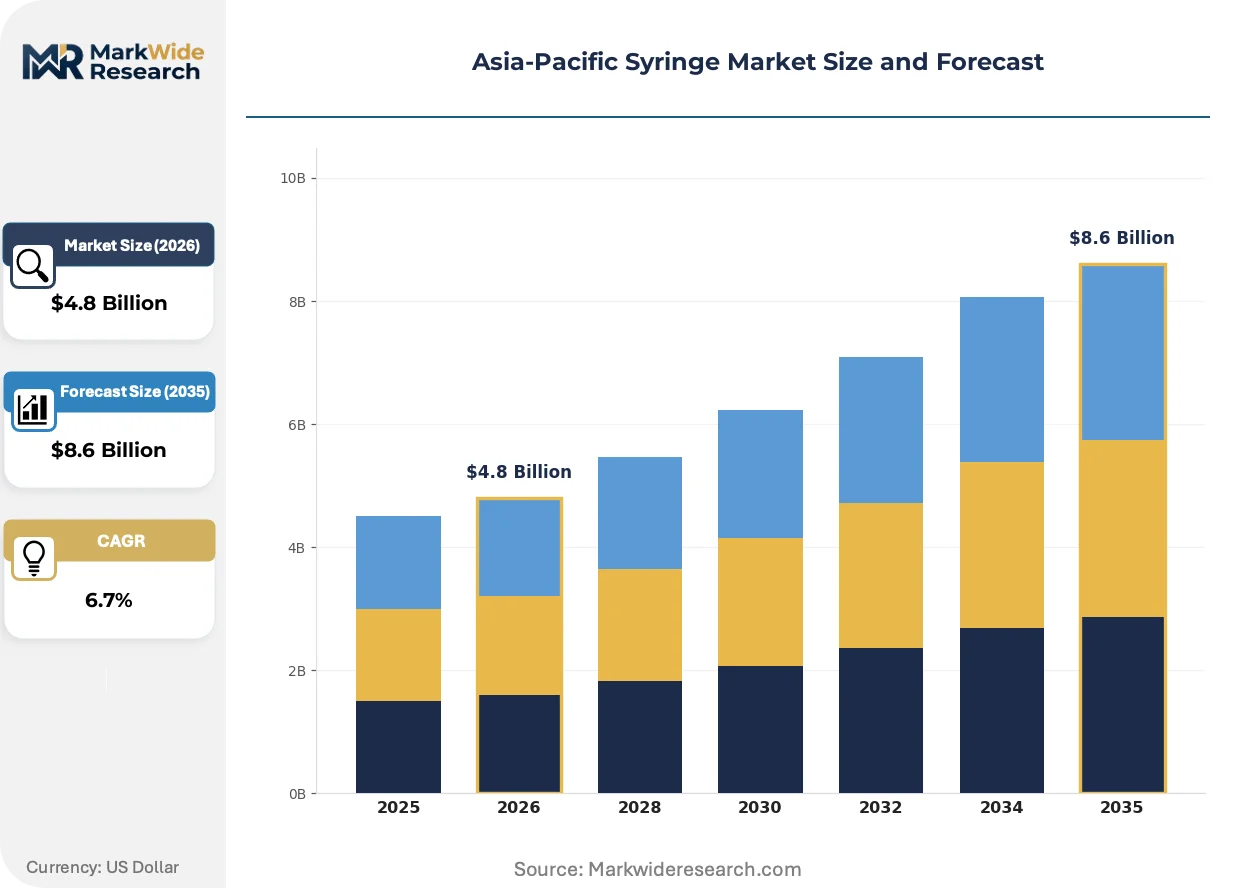
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Syringes, Prefilled Syringes, Standard Syringes, Insulin Syringes Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intradermal End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Material: Plastic, Glass, Metal, Biodegradable Materials |
| Companies Covered | Becton Dickinson and Company, Terumo Corporation, Nipro Corporation, Hindustan Syringes & Medical Devices Limited, Gerresheimer AG, SCHOTT AG, Medtronic plc, B. Braun Medical Inc., Cardinal Health Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Syringe Market Trends and Innovations
Digital manufacturing integration and polymer science advances are compressing development timelines for next-generation safety mechanisms. Regulatory convergence around single-use mandates is reshaping product architecture priorities across the region.
Passive safety syringe engineering is virtualizing needlestick prevention from manual user activation toward automatic retraction triggers. Japanese tertiary hospitals are adopting these devices at accelerated pace for high-risk department coverage. The technology is virtualizing training cost structures and liability exposure for institutional purchasers.
China's NMPA revised medical device classification rules now require clinical evidence dossiers for novel safety mechanism submissions, extending approval timelines for incremental design improvements. Domestic manufacturers are responding by front-loading biocompatibility and human factors studies prior to regulatory filing. Prefilled syringe categories face the most pronounced documentation burden under the new framework.
Hospital procurement consolidation across Australia's state health systems is compressing supplier rosters toward vertically integrated manufacturers with full polymer-to-device traceability. New South Wales and Victoria tender boards now mandate batch-level serialization for safety syringe contracts. This behavioral shift favors Japanese and South Korean producers with captive resin compounding and in-house mold fabrication capabilities.
Asia-Pacific Syringe Market Segmentation
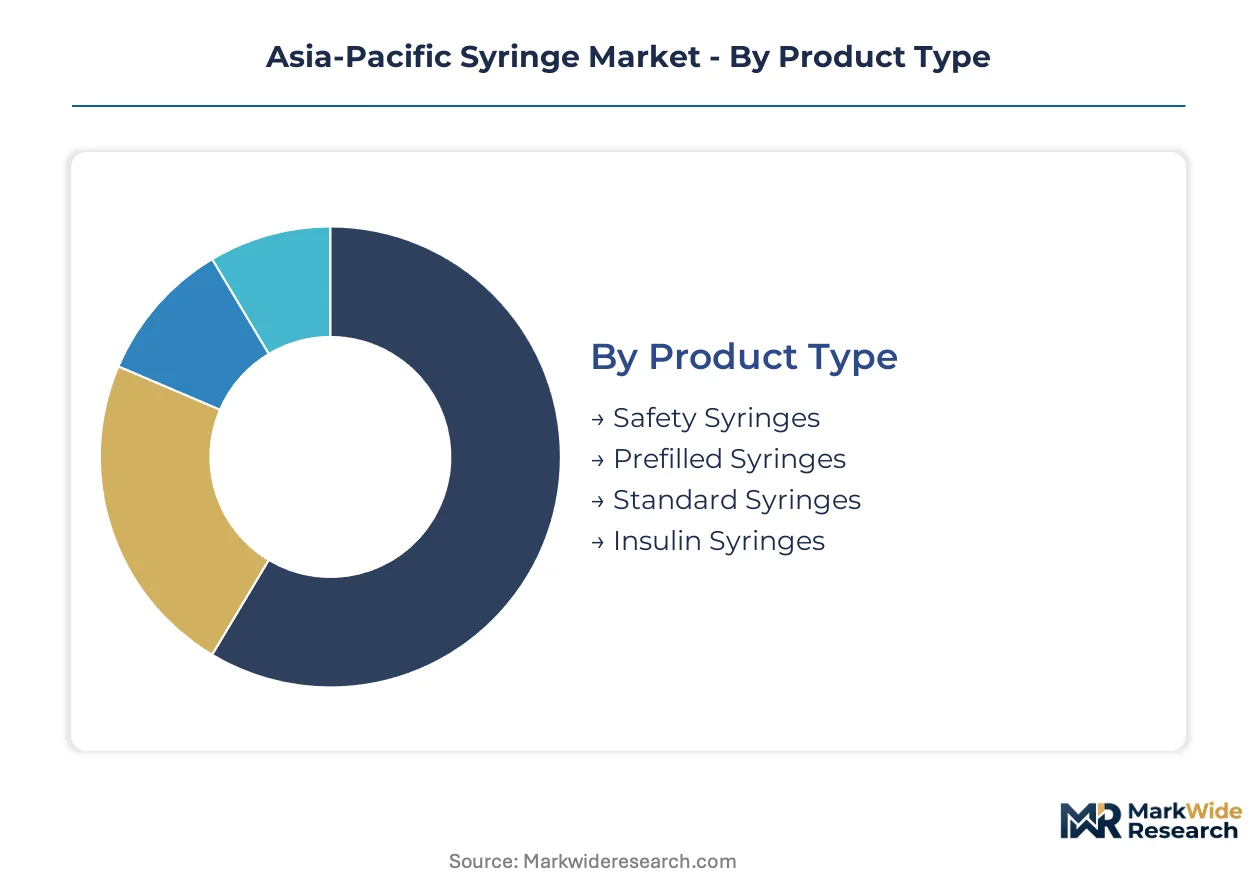
Segmentation reveals distinct procurement rhythms across the Asia-Pacific syringe market. Safety mechanisms and prefilled formats command premium positioning while standard devices sustain volume throughput in public health programs.
Product Type:
Cycle times vary dramatically by product category, with single-use safety devices turning inventory fastest in hospital systems while prefilled formats sit longer in cold chain distribution.
- Safety Syringes:Engineered with needlestick prevention mechanisms including retractable needles or protective shields. Maharashtra and Gujarat hospital procurement boards now mandate these devices for high-risk departments under CDSCO guidance, compressing replacement cycles for legacy standard formats.
- Prefilled Syringes:Factory-loaded with precise drug volumes, eliminating compounding steps at point of care. Ho Chi Minh City's injectables export sector is driving fastest adoption for biologics where contamination control outweighs unit cost premiums.
- Standard Syringes:Basic polypropylene construction without integrated safety features. India's Universal Immunization Programme sustains massive procurement volumes for single-use compliance in rural clinics.
- Insulin Syringes:Ultra-fine gauge needles with unit-specific calibration for diabetes management. Japan's aging demographic is expanding home care consumption through pharmacy channels.
Standard syringes anchor the volume base while prefilled syringes gain share at the steepest rate.
Delivery Mode:
Application setting determines specification intensity, with acute care demanding highest precision while ambulatory formats prioritize patient self-administration.
- Subcutaneous:Shallow tissue injection requiring short bevel needles. Vaccination programs across Indonesia and the Philippines concentrate demand for 25-27 gauge devices.
- Intravenous:Direct vascular access demanding strict sterility assurance. Australian state hospital tenders specify luer-lock compatibility under TGA quality frameworks.
- Intramuscular:Deep tissue delivery for depot formulations and vaccines. India's immunization infrastructure relies on 21-23 gauge standard construction for mass campaign efficiency.
- Intradermal:Dermal layer precision for tuberculosis testing and allergy diagnostics. Thailand's public health laboratories are expanding procurement for Mantoux test standardization.
Intramuscular delivery dominates institutional procurement volumes while intradermal applications show the most rapid expansion trajectory among specialty diagnostics.
End User:
Customer type segmentation maps directly to regulatory oversight intensity and reimbursement pathway complexity across national health systems.
- Hospitals:Tertiary care institutions with centralized procurement and strict adverse event reporting. New South Wales and Victoria tender boards require batch-level serialization for safety syringe contracts.
- Clinics:Outpatient facilities with higher price sensitivity and simpler inventory systems. India's Ayushman Bharat network is standardizing auto-disable specifications for primary health centers.
- Home Care:Patient-directed administration with emphasis on usability and disposal safety. Japan's PMDA post-market surveillance tracks needlestick incidents in domestic settings.
- Specialty Pharmacies:Biologics dispensing with cold chain integration and patient training requirements. South Korea's MFDS regulates these channels for high-value injectable therapies.
Hospitals command the premium tier through specification mandates while home care segments expand most quickly on demographic aging trends.
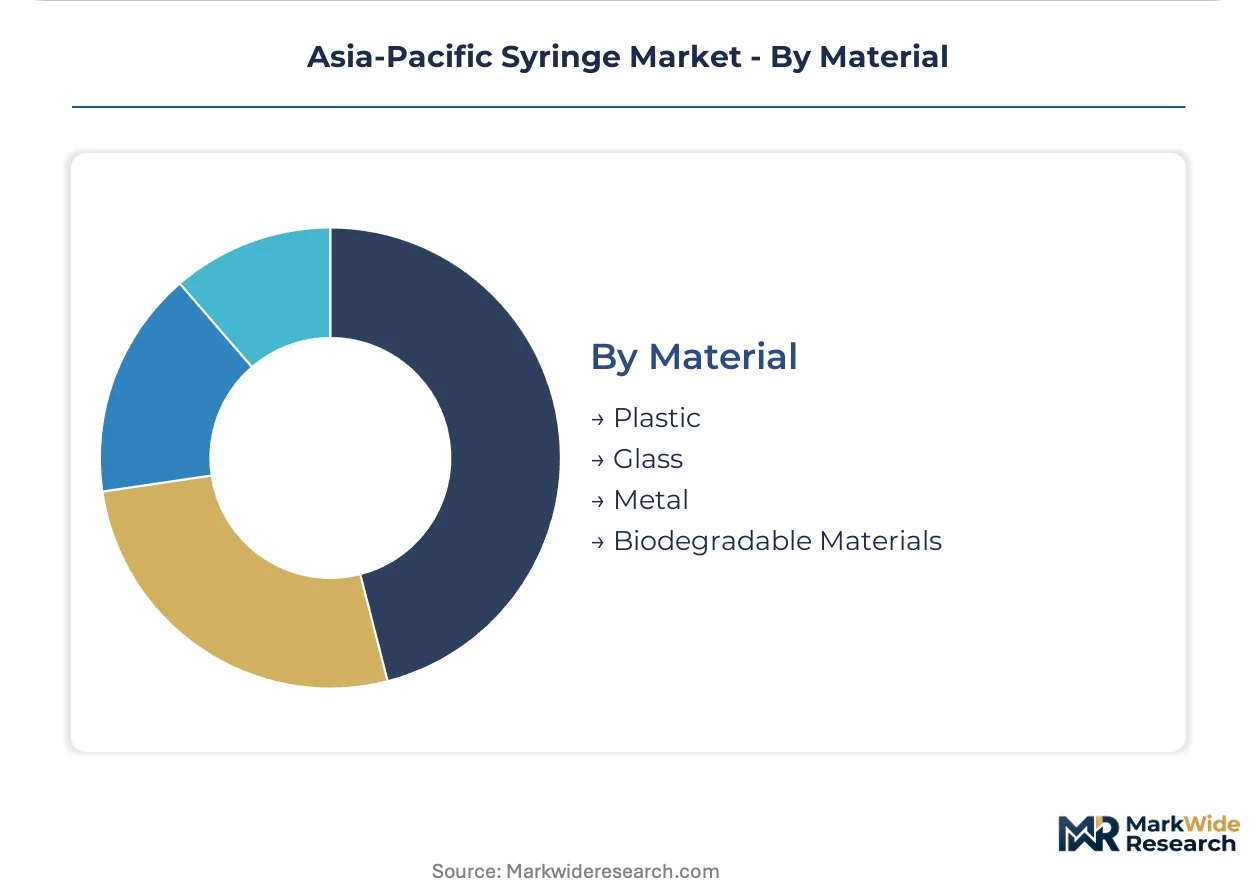
Material:
Feedstock selection governs manufacturing location economics and regulatory clearance pathways for Asia-Pacific producers.
- Plastic:Medical-grade polypropylene dominating disposable production through injection molding. Thailand's petrochemical corridor enables captive resin supply for ASEAN molders.
- Glass:Borosilicate construction for prefilled formats requiring inert drug contact surfaces. China's NMPA clinical evidence requirements now extend to glass delamination studies.
- Metal:Stainless steel needle fabrication with siliconization for plunger glide. Japan maintains precision grinding capabilities for ultra-fine gauge production.
- Biodegradable Materials:Emerging polylactic acid and starch-based alternatives. Australia's TGA has yet to establish equivalence pathways for compostable device registration.
Plastic materials sustain overwhelming volume dominance while biodegradable alternatives climb fastest on sustainability procurement criteria in Australian and Japanese institutional tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding capacity clusters in Thailand and Japan concentrate upstream supply control for regional molders. Hospital procurement boards across five national markets now mandate divergent safety specifications, fragmenting tender participation requirements.
China
Domestic biologics manufacturing expansion in Suzhou and Shanghai is accelerating prefillable syringe demand for export-bound insulin and vaccine formulations. NMPA's revised medical device classification rules now require clinical evidence dossiers for novel safety mechanisms, extending approval timelines for incremental design improvements. Yangtze River Delta pharmaceutical corridors are absorbing the bulk of glass delamination testing capacity for borosilicate prefilled formats.
India
Maharashtra and Gujarat pharmaceutical corridors are reshaping regional supply dynamics through government tender dominance for auto-disable syringes. CDSCO mandatory medical device registration under the Drugs and Cosmetics Act is channeling import substitution toward domestic polymer processing clusters. Faridabad's medical device manufacturing belt anchors the government procurement ecosystem with cost-optimized standard syringe output for the Universal Immunization Programme.
Japan
Aging demographic expansion is driving home care consumption of ultra-fine gauge insulin syringes through pharmacy channels. PMDA stringent quality management system requirements elevate compliance costs for new entrants, forcing regional competitors toward ISO 13485 certification parity. Kanto region tertiary hospitals are adopting passive safety devices at accelerated pace for high-risk department coverage.
Australia
State health system procurement consolidation in New South Wales and Victoria is compressing supplier rosters toward vertically integrated manufacturers. TGA batch-level serialization mandates for safety syringe contracts favor producers with captive resin compounding and in-house mold fabrication capabilities. Sustainability procurement criteria are accelerating biodegradable material pilot programs despite equivalence pathway uncertainty.
South Korea
MFDS regulation of specialty pharmacy channels for high-value injectable therapies is concentrating distribution control for biologics prefillable systems. Gamma irradiation capacity concentration creates cross-border logistics vulnerability for ASEAN manufacturers dependent on sterilization services. Seoul Capital Area medical device clusters are expanding ISO Class 7 molding environments for particulate and microbial control compliance.
Asia-Pacific Syringe Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin compounding and precision mold fabrication. The Asia-Pacific syringe market structures around three tiers: multinational safety-engineered portfolio holders, regional standard device manufacturers, and domestic government tender specialists. Two dominant competitive moves are reshaping positioning: captive polymer supply integration and ISO 13485 certification parity for premium hospital contract access.
Within the multinational safety-engineered tier, Becton Dickinson and Company and Terumo Corporation exemplify platform dominance through vertically integrated polymer processing capabilities. Hindustan Syringes & Medical Devices Limited anchors the domestic government tender specialist archetype, occupying a position calibrated to India's cost-optimized public health procurement requirements. These three entities collectively represent the spectrum from premium hospital specification compliance to high-volume standard device output across the regional market.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Terumo Corporation |
| Nipro Corporation |
| Hindustan Syringes & Medical Devices Limited |
| Gerresheimer AG |
| SCHOTT AG |
| Medtronic plc |
| B. Braun Medical Inc. |
| Cardinal Health Inc. |
| Others |
Pricing and Supply Chain Analysis
Gamma irradiation overcapacity in Japan and South Korea is compressing sterilization service margins while elevating pricing power for ASEAN molders with captive ethylene feedstock. This utilization asymmetry drives supplier consolidation toward integrated polymer-to-device producers and sharpens tier separation between safety-engineered and standard formats.
Pricing Analysis
CDSCO medical device registration dictates the pricing tier structure across India's Maharashtra and Gujarat procurement corridors. Three-tier pricing structure across premium safety-engineered, standard auto-disable, and economy single-use levels separates hospital tenders from immunization program volumes. Cost compression in standard formats is intensifying because polypropylene resin tracks naphtha cracking margins. Government tender specialists exhibit highest price sensitivity; tertiary hospitals with PMDA-equivalent specifications show lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Terumo Corporation's vertically integrated polymer processing in Japan and Thailand, plus Hindustan Syringes & Medical Devices Limited's Faridabad production belt. Geographic supply concentration centers on Thailand's petrochemical corridor, Japan's precision molding clusters, and India's pharmaceutical manufacturing belts. Raw material dependencies draw from medical-grade polypropylene resin, Dow Corning silicone oil for plunger glide, and borosilicate glass tubing. Single-source sterilization vulnerability concentrates gamma irradiation capacity in Japan and South Korea. Distribution runs through government tender boards, GPO contracts, and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific syringe market functions as a regulatory-moat arena where CDSCO, PMDA, and NMPA certification entrenchment creates switching costs that lock hospital procurement committees into validated supplier rosters.
For Market Incumbents: Entrench position through backward integration into medical-grade polypropylene compounding and ISO 13485 certification parity for Australian state health system access. Threat substitution emerges from Vietnamese injectables manufacturers developing captive prefillable syringe capabilities. Capacity addition in Thailand's petrochemical corridor secures resin supply sovereignty against feedstock volatility.
For New Entrants and Emerging Players: Build out biodegradable material pilot programs targeting Australian sustainability procurement criteria despite TGA equivalence pathway uncertainty. Vietnam's Ho Chi Minh City injectables sector offers the most penetrable geography for prefillable syringe system entry. Go-to-market angle: partner with biologics exporters seeking contamination-controlled dosing formats.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated safety-engineered portfolio holders with hospital system partnership depth. Long-term viability favors producers with captive polymer supply and in-house mold fabrication spanning the projection horizon. Acquisition target archetype: regional standard device manufacturers with government tender relationships and unrealized safety mechanism upgrade potential. Signal to watch: CDSCO accelerated approval pathways for domestic manufacturers as import substitution inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Opens premium hospital contract access under PMDA-equivalent quality frameworks. |
| Backward Integration into Polymer Compounding | Captures medical-grade polypropylene margin and insulates against naphtha volatility. |
| Hospital System Partnership | Locks in multi-year safety syringe tenders with New South Wales and Victoria procurement boards. |
| Biocompatibility Testing Front-Loading | Accelerates NMPA novel safety mechanism approval under revised clinical evidence rules. |
| Digital Twin Integration | Reduces injection molding defect rates for complex passive safety geometries. |
Research Methodology
Cross-validation between hospital procurement committee interviews and CDSCO registration database analysis anchors the qualitative findings. Primary engagement spans biomedical engineers, GPO contracts managers, pharmaceutical manufacturing procurement leads, and regulatory affairs specialists across India, Japan, China, and Australia. Secondary sources include NMPA medical device classification filings, TGA batch serialization mandates, WHO prequalification standards, and hospital tender board documentation. Bottom-up volume modeling triangulates against top-down polymer consumption estimates.
Calibration against historical CDSCO registration velocity and NMPA approval timeline shifts refines the analytical framework. Segmentation dimensions span product type, delivery mode, end user, and material grade across the projection horizon. CAGRs derive from immunization program procurement trajectories, biologics manufacturing expansion rates, and safety mandate adoption curves. Industry-specific inputs incorporate auto-disable syringe replacement cycles and prefilled format cold chain distribution intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Vietnamese injectables manufacturers or accelerated biodegradable material equivalence pathways by TGA would shift outcomes. Specific risk factors include medical-grade polymer price volatility, gamma irradiation logistics disruption, and biocompatibility testing queue elongation. Quarterly review of CDSCO registration approval velocity and state health system tender award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Medical Bags Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Suture Wire Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Alcohol Prep Pads Market