
 Canada Hospital Supplies Market | 2026-2036
Canada Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Hospital Supplies Market Outlook
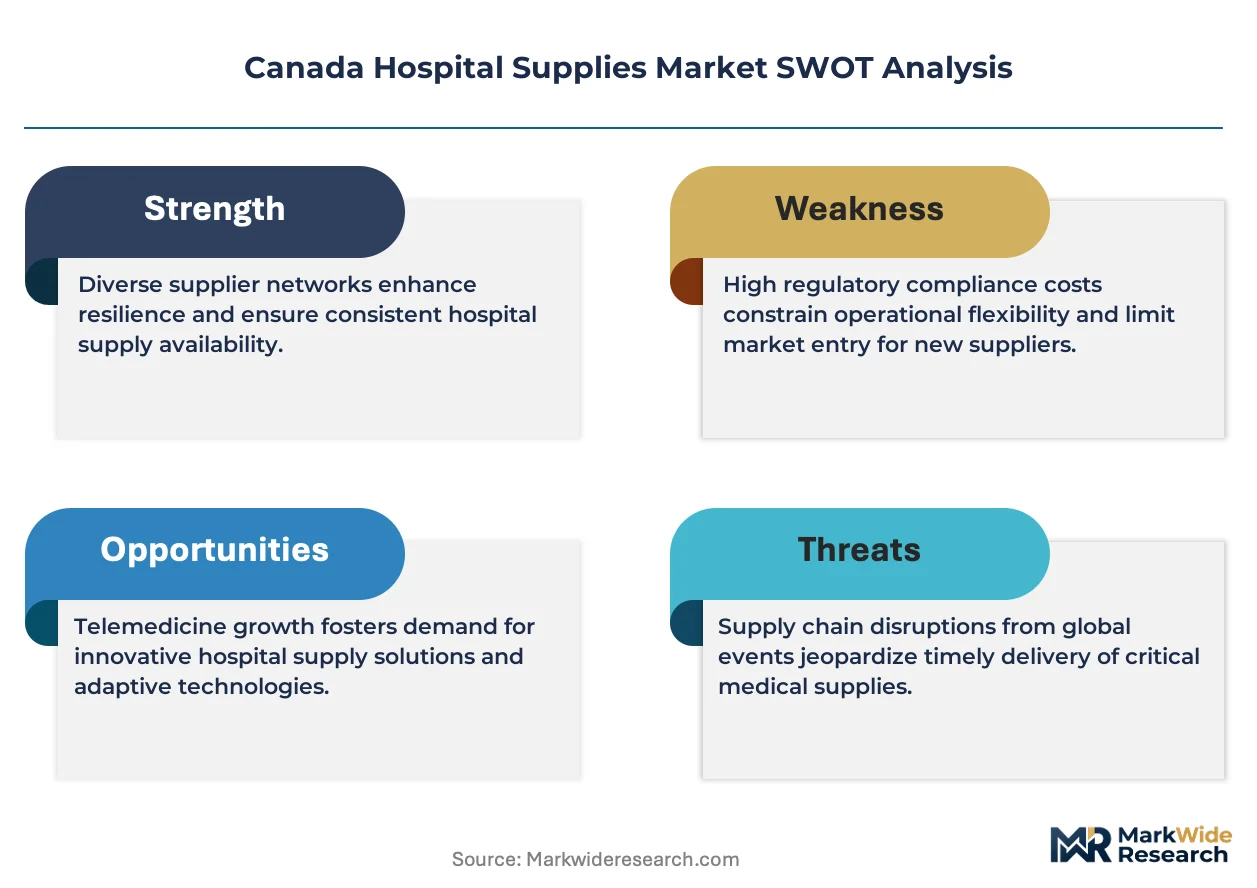
Hospital group purchasing organizations are reconfiguring procurement workflows across Canadian provinces. McKesson Corporation leverages its national distribution network to serve regional health authorities. Cardinal Health Canada anchors its position through centralized sterile processing solutions. Medline Canada competes by specializing in private-label consumables for mid-sized hospitals.
Hospital supplies encompass instruments, equipment, and consumables manufactured to ISO 13485 quality standards for sterile clinical environments. These products serve diagnostic, therapeutic, and patient monitoring functions within regulated healthcare delivery systems. Medical consumables capture recurring revenue streams through high-velocity replenishment cycles. Diagnostic equipment commands premium pricing tied to capital replacement timelines. Monitoring devices are gaining traction as remote patient surveillance expands beyond traditional ward settings.
Health Canada, the Canadian Standards Association, and provincial health ministries collectively govern device licensing, biocompatibility testing, and procurement compliance. Health Canada's Medical Devices Regulations mandate pre-market licensing for Class II through IV products, directly shaping manufacturer market entry requirements. Provincial tendering frameworks further constrain supplier selection through mandatory domestic preference clauses. Stakeholders must track evolving federal interoperability standards and provincial inventory centralization policies to anticipate procurement pathway shifts.
Market Dynamics
Ontario's hospital procurement consortiums are consolidating purchasing power across acute care networks, forcing suppliers to restructure pricing and service models around centralized tender requirements rather than individual hospital relationships.
Growth Catalysts
- Health Canada Medical Devices Regulations:Tightened sterility validation requirements are accelerating hospital replacement cycles for non-compliant inventory, creating sustained demand for certified single-use surgical kits.
- Remote patient surveillance expansion:Monitoring devices are penetrating beyond traditional ward settings into home-based acute care, opening new reimbursement pathways for connected diagnostic equipment.
- ISO 13485 quality standard adoption:Mid-sized hospitals are upgrading supplier qualification criteria, privileging manufacturers with integrated quality management systems over fragmented vendors.
Market Restraints
- Domestic preference clauses:Provincial tendering frameworks in Quebec and British Columbia restrict supplier pools to Canadian-registered entities, limiting price competition from international manufacturers.
- Sterile processing labor costs:Centralized sterile processing solutions require specialized technician certification, constraining operational scale-up in rural health authorities.
- Biocompatibility testing backlogs:Health Canada's pre-market licensing queue for Class III devices extends validation timelines, delaying revenue recognition for novel consumable introductions.
Strategic Opportunities
- Private-label consumable penetration:Mid-sized hospitals in Alberta and Manitoba are abandoning branded sourcing for standardized consumable bundles, creating margin capture opportunities for flexible contract manufacturers.
- Interoperability standard alignment:Federal health data integration mandates are forcing device connectivity upgrades, positioning suppliers with embedded software capabilities for multi-year procurement contracts.
- Atlantic Canada network consolidation:New Brunswick and Nova Scotia health authorities are merging procurement functions, enabling volume-based pricing negotiations previously unavailable to fragmented regional buyers.
Industry Challenges
- Capital equipment replacement cycles:Diagnostic equipment premium pricing depends on extended depreciation schedules, compressing vendor margins as hospitals defer upgrades amid fiscal constraints.
- Inventory centralization complexity:Provincial stockpiling policies require real-time demand forecasting integration with legacy hospital ERP systems, straining supplier logistics coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Hospital Supplies Market |
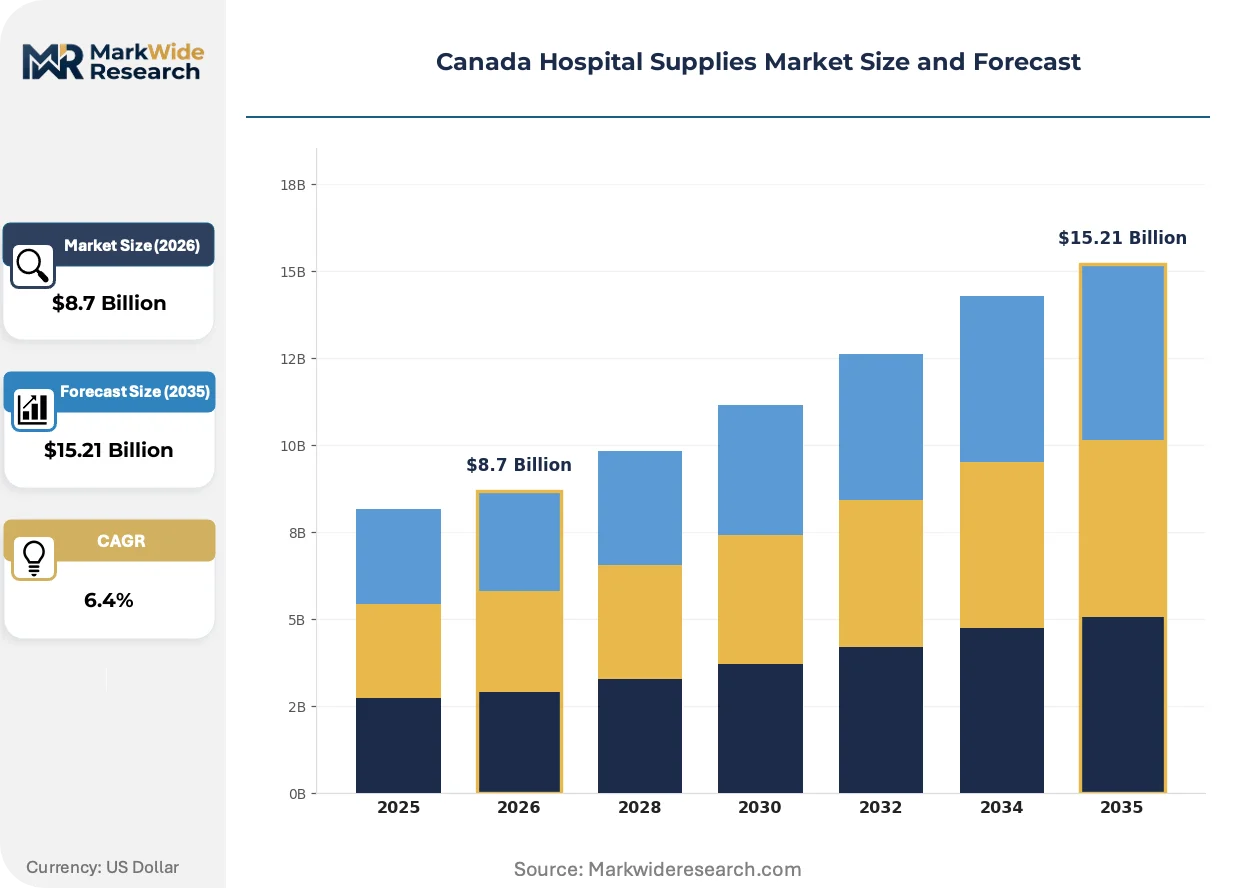
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Medical Consumables, Monitoring Devices End User: Public Hospitals, Private Clinics, Specialized Care Centers, Research Institutions Application: Emergency Care, Surgical Procedures, Chronic Disease Management, Patient Monitoring Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | McKesson Corporation, Cardinal Health Canada, Baxter Canada, 3M Canada, Medline Canada, Henry Schein Canada, GE Healthcare Canada, Stryker Canada, Becton Dickinson Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Hospital Supplies Market Strategic Shifts
Connected device architectures and consolidated procurement governance are restructuring how hospitals source, deploy, and replenish clinical supplies across Canadian provinces.
Smart sensor integration into surgical instruments and patient monitoring equipment is digitizing supply chain visibility from manufacturer to point-of-care. Acute care facilities in Ontario and Quebec are piloting RFID-enabled kit tracking to reduce expiration waste and recall response time. This connectivity layer is digitizing procurement decision-making, compressing the information lag between clinical consumption and replenishment orders.
Health Canada's Medical Devices Regulations are mandating Unique Device Identification compliance for Class II through IV products entering the Canadian market. Manufacturers must now embed standardized labeling and traceability data into product design, adding fixed compliance costs that disproportionately burden low-volume specialty suppliers. Western provincial health authorities are incorporating UDI readiness into tender evaluation scoring, accelerating supplier base consolidation.
Hospital group purchasing organizations are unbundling after-sales service from capital equipment contracts, forcing diagnostic and monitoring device vendors to compete on discrete service line pricing. Ontario's procurement consortiums have pioneered this separation, with Atlantic Canada authorities now adopting similar frameworks. This disaggregation is visible most acutely in imaging equipment segments, where maintenance contract renewals face independent competitive bidding distinct from initial hardware procurement.
Canada Hospital Supplies Market Segmentation
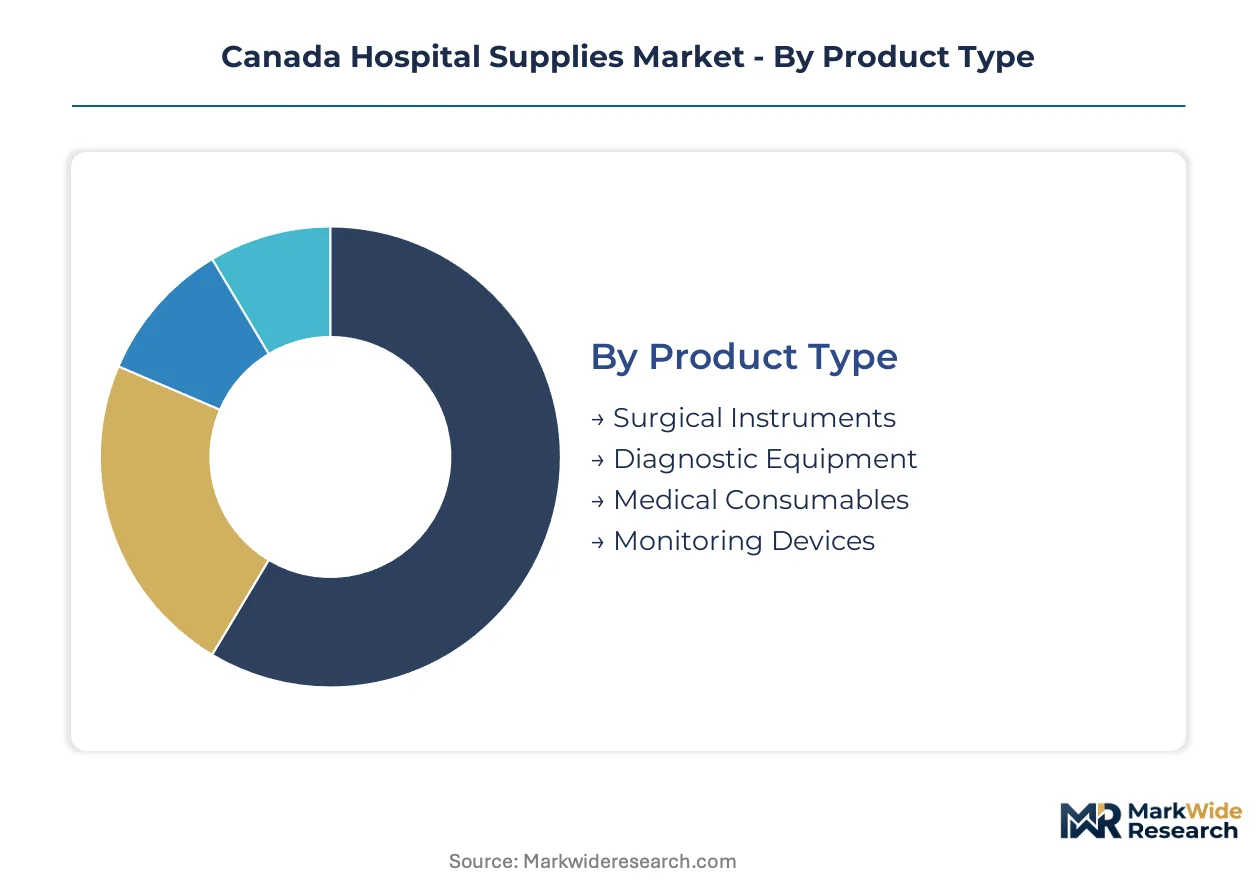
Hospital supplies segmentation in Canada reveals distinct procurement patterns across product categories and care settings. Health Canada's Medical Devices Regulations create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
After-sales service intensity varies dramatically across product categories, with capital equipment demanding multi-year maintenance contracts while consumables rely on logistics performance.
- Medical Consumables:Single-use sterile products manufactured to ISO 13485 standards dominate procurement volume through high-velocity replenishment cycles. Ontario's hospital procurement consortiums are consolidating purchasing power for standardized consumable bundles, compressing margins for fragmented vendors.
- Diagnostic Equipment:Capital-intensive imaging and laboratory systems command premium pricing tied to extended depreciation schedules. Health Canada's pre-market licensing queue for Class III devices constrains vendor revenue recognition timelines for novel equipment introductions.
- Surgical Instruments:Reusable and disposable instrument sets serve acute care surgical volumes with varying sterilization requirements.
- Monitoring Devices:Connected patient surveillance equipment is penetrating home-based acute care settings beyond traditional ward deployments.
By volume, Medical Consumables leads. By growth pace, Monitoring Devices is expanding most quickly.
End User:
Customer concentration patterns shift procurement leverage, with consolidated public networks wielding tender power against fragmented private operators.
- Public Hospitals:Provincial health authorities and regional procurement consortiums govern acquisition through centralized tender frameworks with domestic preference clauses. Quebec and British Columbia restrictions limit supplier pools to Canadian-registered entities, constraining price competition from international manufacturers.
- Private Clinics:Independent surgical and diagnostic facilities prioritize rapid fulfillment and flexible contract terms over volume pricing. Alberta and Manitoba mid-sized hospitals are abandoning branded sourcing for standardized consumable bundles, creating margin capture opportunities for flexible contract manufacturers.
- Specialized Care Centers:Cardiac, oncology, and orthopedic focused facilities require procedure-specific supply configurations.
- Research Institutions:Academic medical centers drive early adoption of novel devices with distinct validation requirements.
Public Hospitals capture the largest procurement value. Private Clinics are climbing the fastest as outpatient surgical volumes expand.
Application:
Clinical use case determines regulatory pathway urgency and inventory criticality, with emergency applications facing zero-tolerance supply constraints.
- Surgical Procedures:Operating room supply chains demand sterile kit integrity with RFID-enabled tracking pilots reducing expiration waste in Ontario and Quebec acute care networks. Health Canada's Unique Device Identification mandate for Class II through IV products accelerates supplier base consolidation.
- Patient Monitoring:Remote surveillance expansion opens new reimbursement pathways for connected diagnostic equipment in home-based acute care settings.
- Emergency Care:Trauma and critical response units require immediate availability of resuscitation and stabilization supplies.
- Chronic Disease Management:Long-term condition monitoring drives recurring demand for durable equipment and disposable sensors.
Surgical Procedures generates the highest absolute spend. Patient Monitoring shows the steepest expansion trajectory as connectivity mandates proliferate.
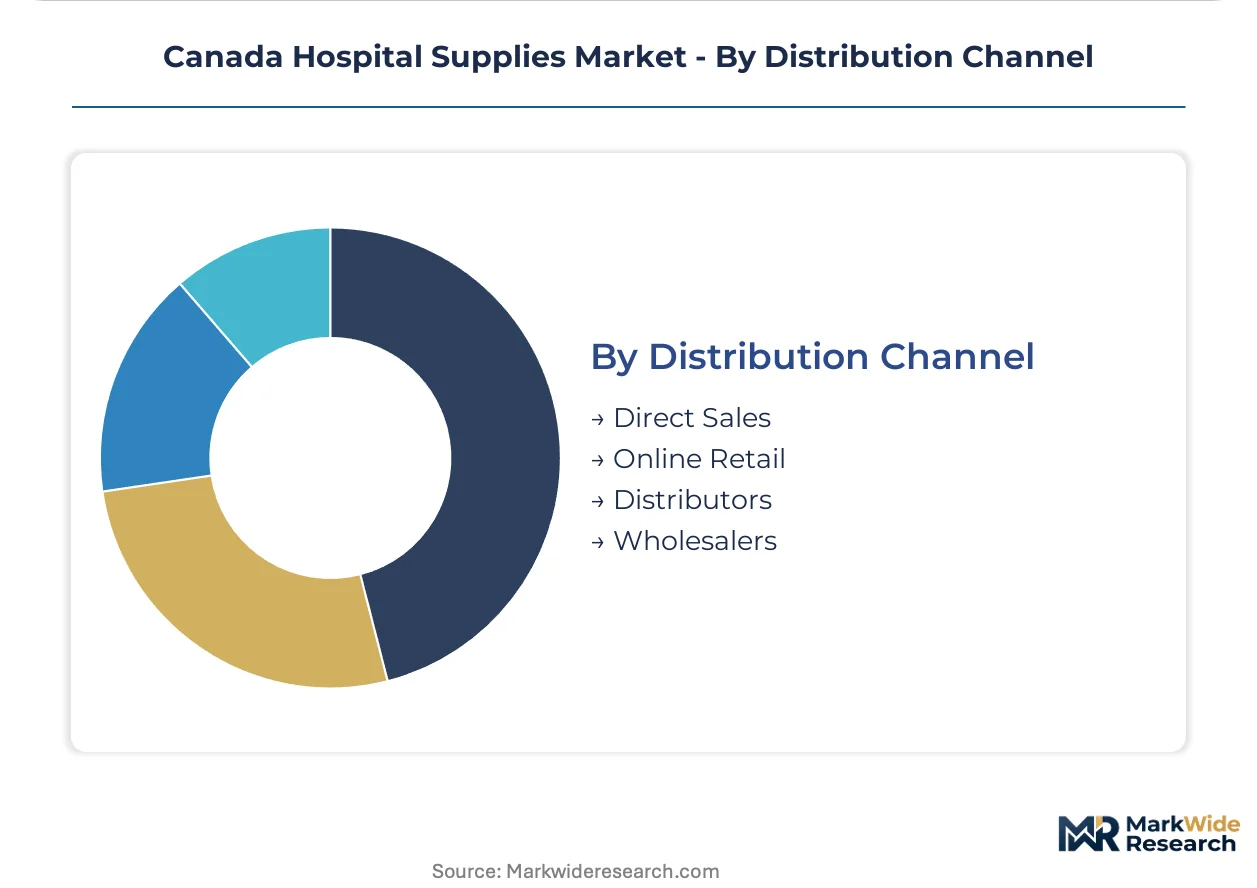
Distribution Channel:
Channel structure determines margin capture and customer intimacy, with direct relationships prized for complex equipment and intermediaries dominating high-velocity consumables.
- Distributors:National networks like McKesson Corporation serve regional health authorities through consolidated logistics infrastructure. Centralized sterile processing solutions require specialized technician certification, constraining operational scale-up in rural health authorities.
- Direct Sales:Capital equipment vendors maintain field service organizations for installation and maintenance. Ontario's procurement consortiums have pioneered unbundling after-sales service from hardware contracts, forcing discrete service line competitive bidding.
- Wholesalers:Bulk intermediaries aggregate demand across fragmented buyers for standardized product flows.
- Online Retail:Digital procurement platforms are penetrating non-critical supply categories with limited regulatory complexity.
Distributors handle the greatest transaction volume. Direct Sales is gaining share fastest as service unbundling reshapes contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's procurement consortiums extract steeper volume discounts than Atlantic Canada's fragmented health authorities, creating a pricing-power asymmetry that reshapes supplier service models across provincial borders.
Ontario
Acute care networks in Toronto and Ottawa are consolidating surgical kit procurement through centralized tenders that mandate ISO 13485 certification and Unique Device Identification compliance. Health Canada's Medical Devices Regulations are accelerating hospital replacement cycles for non-compliant inventory. The Greater Toronto Area hosts the densest cluster of sterile processing facilities serving provincial procurement consortiums.
Quebec
Montreal's university-affiliated hospitals are piloting RFID-enabled surgical instrument tracking to reduce expiration waste and recall response time. Provincial tendering frameworks restrict supplier pools to Canadian-registered entities under domestic preference clauses. The Montreal-Laval corridor concentrates diagnostic equipment vendors adapting to unbundled after-sales service contracts.
British Columbia
Vancouver Coastal Health and Fraser Health authorities are integrating remote patient monitoring into home-based acute care reimbursement pathways. Provincial procurement policies favor suppliers with embedded software capabilities aligned to federal interoperability standards. The Vancouver-Surrey medical technology cluster is expanding sterile processing capacity to serve distributed rural health authorities.
Alberta
Calgary and Edmonton mid-sized hospitals are abandoning branded consumable sourcing for standardized private-label bundles. Alberta Health Services' centralized inventory policies require real-time demand forecasting integration with legacy ERP systems. The Calgary health technology corridor is attracting contract manufacturers offering flexible production runs for regional hospital networks.
Atlantic Canada
New Brunswick and Nova Scotia health authorities are merging procurement functions to enable volume-based pricing negotiations previously unavailable to fragmented regional buyers. Specialized technician certification requirements constrain operational scale-up in centralized sterile processing solutions. The Halifax regional medical center anchors diagnostic equipment procurement for the Maritime provinces.
Canada Hospital Supplies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain, each facing distinct margin pressures from provincial procurement consolidation. The vendor base organizes around three tiers: national distributors with logistics infrastructure, specialized consumable manufacturers with ISO 13485 certification, and capital equipment vendors with field service organizations. Two strategic archetypes dominate competitive positioning: flexible contract manufacturers capturing private-label shifts and integrated platform providers bundling hardware with connectivity solutions. M&A activity concentrates on acquiring sterile processing capabilities, while geographic expansion targets Atlantic Canada's consolidating procurement functions.
Within the national distribution tier, McKesson Corporation and Cardinal Health Canada occupy positions shaped by their scale advantages in serving regional health authorities. Medline Canada exemplifies the specialized consumable archetype, competing through private-label standardization for mid-sized hospital networks. These three entities represent the competitive fault lines between logistics-driven platform control and manufacturing-driven margin capture in a market where provincial tender frameworks increasingly determine supplier viability.
| Leading Market Players |
|---|
| McKesson Corporation |
| Cardinal Health Canada |
| Baxter Canada |
| 3M Canada |
| Medline Canada |
| Henry Schein Canada |
| GE Healthcare Canada |
| Stryker Canada |
| Becton Dickinson Canada |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Ontario's sterile processing facilities drives both supplier capacity investments and pricing premiums for compliant surgical kits. Health Canada's UDI mandate compresses margins for low-volume specialty manufacturers while concentrating procurement leverage within provincial consortiums.
Pricing Analysis
The customization-premium spread between configured-to-order surgical kits and standard consumable bundles reaches its widest point in mid-sized hospital networks. Contract-based long-term procurement agreements dominate, with price differentiation hinging on ISO 13485 certification tier and after-sales service bundling. Cost compression in standard consumables intensifies as Alberta and Manitoba hospitals abandon branded sourcing. Private clinics exhibit the highest price sensitivity due to fragmented purchasing power, while Ontario's procurement consortiums wield volume leverage to suppress premiums.
Supply Chain Analysis
Contract-manufacturing concentration for sterile medical consumables rests in Canada, the United States, and Mexico under the USMCA trade framework. Supply chains draw from polymer resin feedstocks, sterilization packaging materials, and RFID-enabled tracking components. Single-source vulnerability concentrates in ethylene oxide sterilization capacity following regulatory restrictions in multiple jurisdictions. Distribution runs through national logistics platforms serving regional health authorities with centralized inventory management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ontario's hospital procurement consortiums have shifted buyer power decisively toward centralized tender frameworks, compressing supplier margins and forcing service model restructuring.
For Market Incumbents: Harden sterile processing capabilities through backward integration into sterilization services, capturing revenue streams disaggregated from hardware contracts. Invest in Health Canada UDI compliance infrastructure to maintain eligibility for provincial tender scoring. The unbundling of after-sales service threatens capital equipment margins; vertical integration into maintenance networks defends position. For New Entrants and Emerging Players: Atlantic Canada's consolidating health authorities represent the most penetrable entry point for volume-based contract manufacturers. Alberta's mid-sized hospitals abandoning branded consumables create white-space for private-label standardization. A direct sales model bypassing legacy distributor markups offers the strongest go-to-market angle for flexible production specialists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumable manufacturers with ISO 13485 certification and provincial tender eligibility. Long-term viability favors acquisition targets with embedded software capabilities aligned to federal interoperability mandates. Monitor Health Canada's pre-market licensing queue velocity as the inflection indicator for novel device introduction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada UDI Compliance Investment | Provincial tender scoring now privileges manufacturers with embedded traceability infrastructure. |
| Sterile Processing Capacity Expansion | Rural health authority consolidation creates demand for centralized technician-certified facilities. |
| Private-Label Consumable Standardization | Mid-sized hospital networks in Alberta and Manitoba are abandoning branded sourcing. |
| Software Companion Development | Federal interoperability mandates force device connectivity upgrades for procurement eligibility. |
| Atlantic Canada Procurement Consolidation | New Brunswick and Nova Scotia mergers enable volume-based pricing previously unavailable. |
Study Parameters
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sterile processing technicians combined with secondary validation from Health Canada device licensing records, provincial tender announcements, and ISO certification registries. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Calibration against historical procurement cycles and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, clinical application, and distribution channel, with additional granularity on provincial regulatory cluster. CAGRs derive from weighted average growth assumptions applied to segment-level baselines. Forecast inputs incorporate Health Canada licensing queue velocity and provincial inventory centralization policy adoption curves.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles and provincial deficit constraints would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and procurement consolidation momentum. Quarterly review of provincial tender award patterns and Health Canada pre-market licensing backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Dehydrated Culture Media Market