
 Global Swab Market | 2026-2036
Global Swab Market Size, Share, and Industry Trends Forecast 2026-2036
Global Swab Market Foresight
Nylon is decoupling swab economics from traditional cotton and rayon formulations by offering superior sample release rates and lower nucleic acid binding loss. Puritan Medical Products leverages proprietary flocking technology to sustain leadership in diagnostic-grade specimen collection devices. Thermo Fisher Scientific anchors its position through integrated supply chains spanning forensic kits to clinical diagnostics. Copan Diagnostics specializes in automated specimen processing systems that reduce laboratory handling errors.
A swab is a shaft-mounted absorbent tip, typically 150-200mm in length, engineered from cotton, synthetic foam, or flocked nylon fibers for controlled specimen collection and elution. Medical diagnostics applications dominate value generation, with flocked nylon swabs commanding premium positioning due to PCR compatibility and viral transport medium optimization. Foam swabs retain strong share in industrial cleaning where solvent resistance and particulate capture justify repeat procurement. Clinical laboratories represent the most concentrated end-user channel, with bulk sterile packets preferred for high-throughput screening workflows.
The FDA enforces quality system regulation and premarket notification pathways for diagnostic swabs used in infectious disease testing, while the EMA's In Vitro Diagnostic Regulation tightens conformity assessment for European market entry. China's NMPA accelerates registration reviews for domestically manufactured nucleic acid collection products under revised emergency use authorization frameworks. Stakeholders must monitor evolving harmonization between ISO 13485 quality standards and national biocompatibility testing protocols to preserve cross-border commercial access.
Market Dynamics
Flocked nylon fiber technology is rewriting swab economics by displacing cotton and rayon in molecular diagnostics, while FDA's updated in vitro diagnostic guidance compresses qualification timelines for domestic and overseas manufacturers simultaneously.
Growth Catalysts
- Infectious disease surveillance expansion:Molecular diagnostics laboratories across the United States, China, and Germany are scaling specimen collection volumes for pathogen monitoring programs. Hospital laboratory networks are upgrading biobanking infrastructure to handle higher throughput.
- EMA In Vitro Diagnostic Regulation:Tightened conformity assessment requirements for European market entry are accelerating manufacturer investment in quality system upgrades. Diagnostic-grade swab producers are securing CE marking ahead of full MDR implementation.
- Nylon flocking technology:Superior sample release rates and reduced nucleic acid binding loss are driving specification changes in PCR-compatible collection devices. Clinical laboratories are standardizing on synthetic fiber formulations for viral transport medium optimization.
Market Restraints
- Petrochemical input volatility:Nylon resin prices fluctuate with crude oil derivatives, compressing margins for flocked swab manufacturers dependent on synthetic fiber supply chains.
- Supply concentration in East Asian polymer production:Raw material sourcing clusters in specific coastal manufacturing zones create geographic vulnerability for European and North American finished goods producers.
- Technical limitation in foam elution efficiency:Industrial cleaning applications retain polyurethane formulations despite inferior nucleic acid recovery rates, locking out diagnostic crossover opportunities.
Strategic Opportunities
- India's diagnostic infrastructure buildout:CDSCO accelerated registration pathways for nucleic acid collection products under revised emergency use authorization frameworks create first-mover positioning for qualified suppliers.
- At-home specimen collection:Direct-to-consumer diagnostic kits are bypassing traditional hospital laboratory procurement channels, requiring redesigned packaging and stability validation for non-clinical handling conditions.
- ISO 13485 harmonization with national biocompatibility protocols:Cross-border quality standard alignment is reducing duplicate testing burdens for manufacturers serving multiple regulatory jurisdictions simultaneously.
Industry Challenges
- Biocompatibility testing capacity constraints:ISO 10993 cytotoxicity and sensitization study backlogs are extending product qualification timelines for novel swab materials entering clinical diagnostic workflows.
- Legacy equipment integration friction:Automated specimen processing systems from Copan Diagnostics and competing platforms require customized swab geometry specifications, fragmenting production runs for universal-format suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Swab Market |
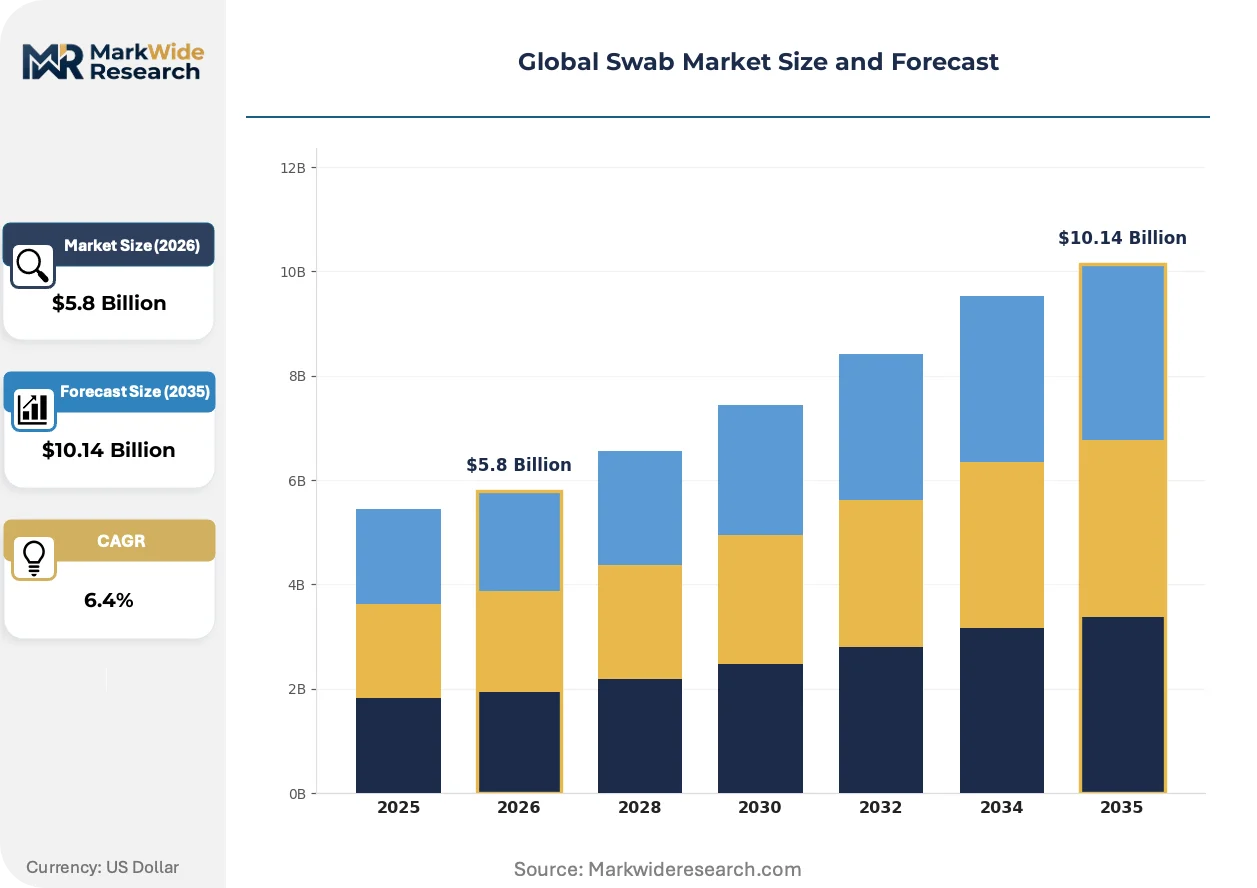
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton Swabs, Foam Swabs, Polyester Swabs, Rayon Swabs, Nylon Swabs Application: Medical Diagnostics, Environmental Testing, Forensic Analysis, Personal Care, Industrial Cleaning End User: Clinical Laboratories, Research Institutes, Government Agencies, Personal Consumers, Academic Institutions Packaging Type: Bulk Packaging, Sterile Packets, Multi-Pack Boxes, Blister Packs, Individually Wrapped |
| Companies Covered | Copan Diagnostics Inc., Puritan Medical Products, Cardinal Health, BD, GPC Medical Ltd., Dynarex Corporation, Thermo Fisher Scientific Inc., Medline Industries, LP., Groupe Lemoine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Swab Market Shifts & Advancements
Specimen collection devices are converging with laboratory automation systems, while regulatory frameworks on three continents tighten synchronously. Material science advances and distribution model disruption are compressing traditional supply chain hierarchies.
Flocked nylon fiber technology is rewriting swab performance standards by delivering controlled specimen release and minimal nucleic acid retention. Clinical laboratories in the United States and Germany are adopting these formulations for high-throughput PCR workflows. The technology is compressing demand for cotton and rayon alternatives in infectious disease testing applications.
China's NMPA revised emergency use authorization frameworks are accelerating registration reviews for domestically manufactured nucleic acid collection products. Domestic producers are securing market position ahead of multinational entrants facing extended documentation requirements. Specimen collection device manufacturers are localizing production to satisfy these expedited pathway conditions.
Hospital laboratory networks are consolidating procurement decisions through centralized purchasing cooperatives, displacing individual department-level ordering authority. Bulk sterile packet specifications are dominating high-throughput screening workflow tenders in the United States. This concentration is visible most acutely in integrated delivery networks spanning multiple states with standardized formulary requirements.
Global Swab Market Segmentation
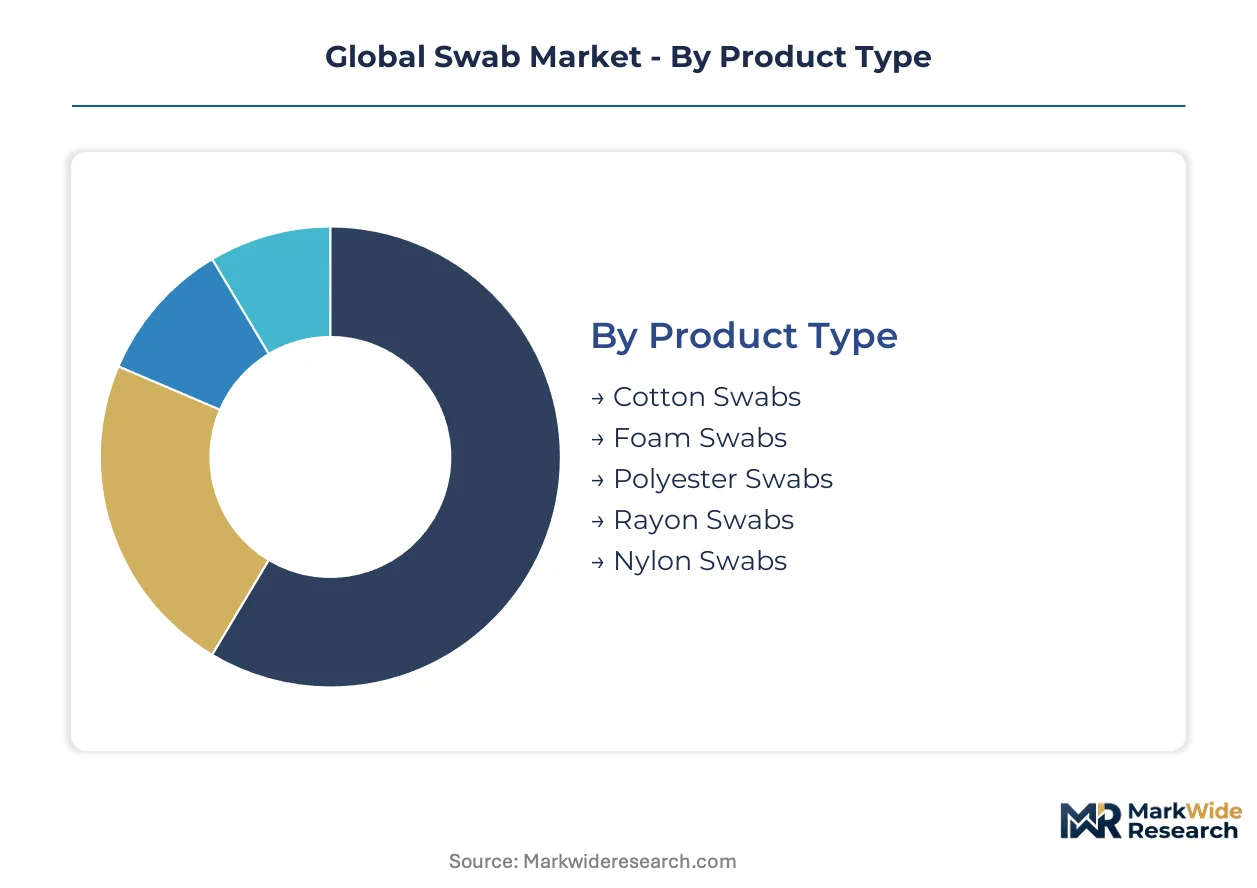
Swab market segmentation reflects divergent technical requirements across diagnostic, industrial, and consumer channels. Material composition, sterility assurance, and elution performance create distinct procurement criteria that fragment supply chain configurations.
Product Type:
Supply concentration tilts toward synthetic fiber production clusters in coastal China and Germany, where polymer extrusion and flocking equipment achieve scale economies.
- Nylon Swabs:Flocked nylon fibers deliver controlled specimen release with minimal nucleic acid binding loss. PCR-compatible formulations command specification dominance in United States and German hospital laboratory networks upgrading viral transport medium protocols.
- Foam Swabs:Open-cell polyurethane construction provides solvent resistance and particulate capture for industrial surface sampling. Demand clusters in electronics manufacturing zones where cleanroom protocols require lint-free substrate contact.
- Cotton Swabs:Cellulose fiber bundles retain legacy positioning in personal care and basic wound cleaning where cost minimization outweighs diagnostic precision requirements.
- Polyester Swabs:Thermoplastic polymer tips offer intermediate elution efficiency for environmental monitoring applications with moderate analytical sensitivity thresholds.
- Rayon Swabs:Regenerated cellulose formulations face displacement pressure from nylon alternatives in clinical settings, retaining residual share in legacy institutional procurement contracts.
Nylon swabs absorb the bulk of installed capacity; foam swabs are expanding most quickly.
Application:
Cost tier differentiation separates premium diagnostic-grade products from commodity formulations serving industrial and personal care segments.
- Medical Diagnostics:Specimen collection devices for infectious disease surveillance and molecular testing require FDA-cleared or CE-marked status with validated viral transport medium compatibility. Hospital laboratory networks in the United States and China drive volume concentration.
- Industrial Cleaning:Solvent-resistant foam and polyester formulations serve electronics, aerospace, and pharmaceutical manufacturing where particulate control mandates repeat procurement.
- Environmental Testing:Surface and water sampling protocols in regulatory compliance programs specify sterile, low-background swabs for contaminant detection workflows.
- Forensic Analysis:DNA collection kits demand chain-of-custody packaging with documented sterility assurance for evidence admissibility standards.
- Personal Care:Consumer cosmetic and hygiene applications prioritize cost efficiency over technical performance, sourcing through retail and e-commerce distribution.
Medical diagnostics commands the highest value per unit; environmental testing is climbing the fastest.
End User:
Customer type fragmentation creates divergent packaging, documentation, and pricing structures across institutional and direct-to-consumer channels.
- Clinical Laboratories:High-throughput screening workflows in integrated delivery networks favor bulk sterile packets with standardized formulary compliance. United States hospital systems consolidate procurement through centralized purchasing cooperatives.
- Research Institutes:Genomics and proteomics facilities require nucleic acid-compatible collection devices with batch traceability for reproducibility protocols.
- Government Agencies:Public health surveillance programs and forensic laboratories mandate domestic sourcing preferences and extended documentation for audit trails.
- Academic Institutions:Teaching hospitals and university research centers balance cost constraints against technical specifications for student training and publication-grade data.
- Personal Consumers:Direct-to-consumer diagnostic kits bypass traditional procurement channels, requiring redesigned stability validation for non-clinical handling conditions.
Clinical laboratories absorb the bulk of installed capacity; personal consumers are expanding most quickly.
Packaging Type:
Volume economics and sterility assurance levels determine packaging selection across automated processing and manual handling workflows.
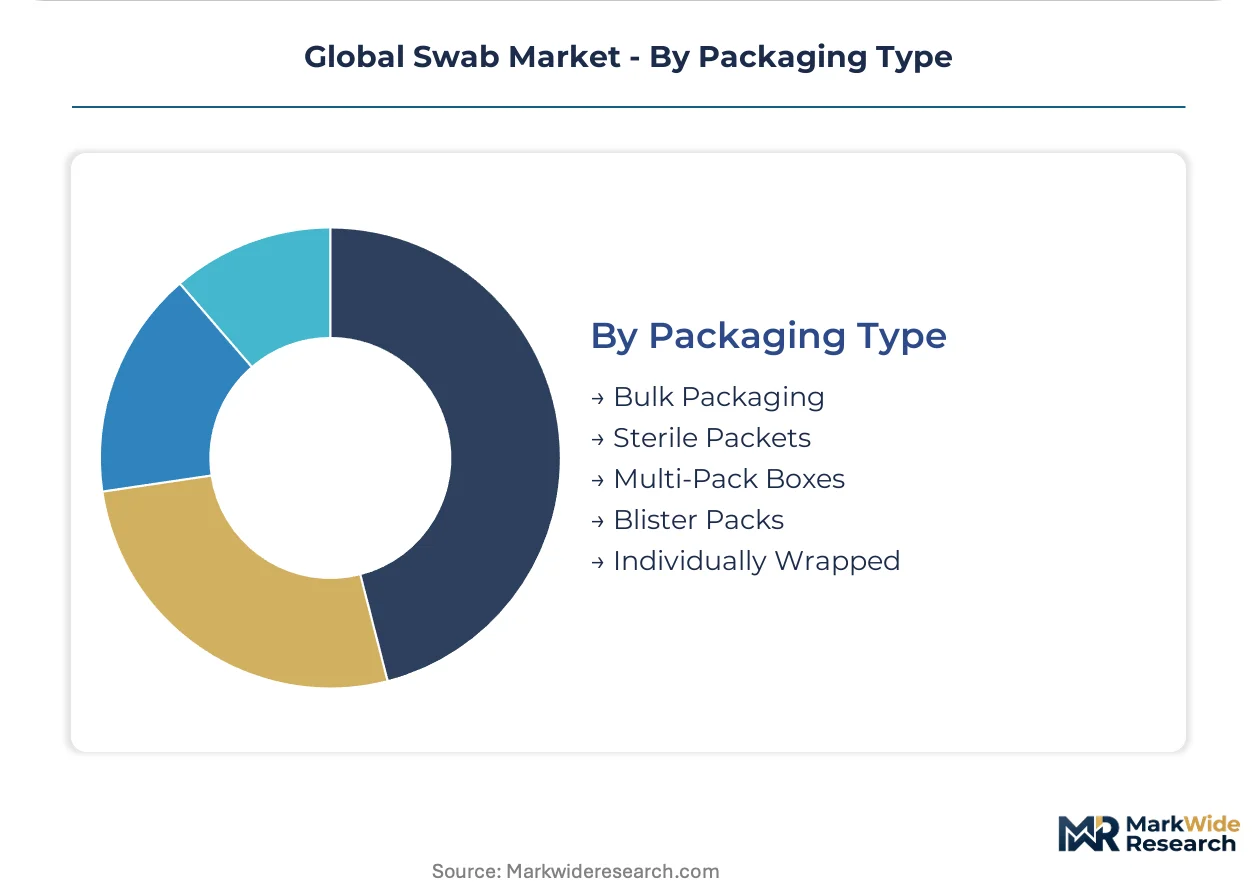
- Sterile Packets:Individual peel-pouch configurations satisfy clinical laboratory requirements for aseptic technique compliance and automated specimen processing system compatibility.
- Bulk Packaging:Non-sterile cartons serve industrial cleaning and personal care segments where downstream sterilization is unnecessary or cost-prohibitive.
- Individually Wrapped:Single-unit sterile barriers support field collection and at-home diagnostic kits requiring extended shelf stability.
- Multi-Pack Boxes:Intermediate quantities balance inventory efficiency against contamination risk for research institute and academic laboratory procurement.
- Blister Packs:Thermoformed tray configurations protect foam and flocked tips during transport for forensic and environmental testing applications.
Sterile packets absorb the bulk of installed capacity; individually wrapped formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate polymer extrusion capacity for flocked nylon fiber production, drawing downstream swab manufacturers to Ningbo and Suzhou industrial parks with tax holidays and streamlined customs processing.
United States
Hospital laboratory networks in the United States are consolidating procurement through integrated delivery networks spanning multiple states with standardized formulary requirements. The FDA enforces quality system regulation and premarket notification pathways for diagnostic swabs used in infectious disease testing. Greater Boston anchors genomics and proteomics research demand, with facilities requiring nucleic acid-compatible collection devices with batch traceability.
Germany
German hospital laboratory networks are upgrading biobanking infrastructure to handle higher specimen throughput for pathogen monitoring programs. The EMA's In Vitro Diagnostic Regulation tightens conformity assessment requirements for European market entry, accelerating manufacturer investment in quality system upgrades. The Rhine-Ruhr metropolitan region concentrates automated specimen processing system deployment, with laboratories standardizing on synthetic fiber formulations for viral transport medium optimization.
China
China's NMPA revised emergency use authorization frameworks are accelerating registration reviews for domestically manufactured nucleic acid collection products. Domestic producers are securing market position ahead of multinational entrants facing extended documentation requirements. The Pearl River Delta clusters polymer resin production and flocking equipment manufacturing, enabling vertical coordination from raw material to finished sterile packets.
India
CDSCO accelerated registration pathways for nucleic acid collection products under revised emergency use authorization frameworks create first-mover positioning for qualified suppliers. The country's national pharmaceutical regulator is prioritizing domestic manufacturing incentives under production-linked incentive schemes. Maharashtra's Mumbai-Pune industrial corridor attracts contract manufacturers serving both domestic diagnostic infrastructure buildout and export markets.
Global Swab Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diagnostic-grade producers commanding premium positioning through regulatory certification while industrial suppliers compete on volume and solvent resistance specifications. The market structure tilts toward consolidated leadership in clinical diagnostics, where FDA-cleared status and viral transport medium compatibility create qualification barriers, and fragmented competition in personal care and industrial cleaning where cost efficiency dominates procurement. Three archetypes define competitive positioning: integrated life science conglomerates with captive distribution, mid-cap specialists with proprietary flocking or foam technologies, and regional contract manufacturers serving private-label demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing polymer supply agreements and automating production lines to serve high-throughput screening workflows.
Among integrated life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the archetype of supply chain control spanning forensic kits to clinical diagnostics. Puritan Medical Products and Copan Diagnostics Inc. occupy positions within the specialist tier, with the former representing proprietary flocking technology capabilities and the latter exemplifying automated specimen processing system integration. These three companies anchor the competitive landscape across distinct strategic vectors without overlapping positioning.
| Leading Market Players |
|---|
| Copan Diagnostics Inc. |
| Puritan Medical Products |
| Cardinal Health |
| BD |
| GPC Medical Ltd. |
| Dynarex Corporation |
| Thermo Fisher Scientific Inc. |
| Medline Industries, LP. |
| Groupe Lemoine |
| Others |
Supply & Pricing Matrix
Nylon resin feedstock costs cascade through three distinct pricing tiers for finished swabs, with polymer price volatility transmitted most acutely to diagnostic-grade flocked products serving United States hospital laboratory networks. Buyers in industrial cleaning segments absorb cost pass-through more readily due to solvent-resistant foam formulations lacking qualified substitutes.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to diagnostic-grade flocked nylon swabs required for emergency infectious disease surveillance programs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared PCR-compatible devices from CE-marked clinical grades and non-sterile industrial formulations. Cost compression in standard-tier cotton and rayon alternatives is intensifying because of displacement by synthetic fiber specifications. Research institutes exhibit highest price sensitivity due to grant-funded procurement constraints, while integrated delivery networks leverage volume consolidation for least sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States integrated delivery networks and German hospital laboratory consortia, while distributor networks serve fragmented research institute and academic procurement. Raw material sourcing clusters in coastal China and the Rhine-Ruhr metropolitan region, with polymer extrusion capacity concentrated in Ningbo, Suzhou, and Düsseldorf industrial zones. Nylon resin, polyurethane foam precursors, and medical-grade adhesives constitute critical input dependencies. Single-source vulnerability in East Asian polymer production creates geographic concentration risk for European and North American finished goods manufacturers. Distribution runs through specialized medical device distributors with cold-chain capabilities for viral transport medium compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints in ISO 10993-certified biocompatibility testing laboratories prop pricing power for qualified manufacturers, creating supply-constrained conditions that favor incumbent margin defense.
For Market Incumbents: To counter emerging regional contract manufacturers in India's Mumbai-Pune corridor, secure backward integration into polymer resin supply through captive agreements with Yangtze River Delta producers. Add automated flocking capacity in Germany to serve EMA In Vitro Diagnostic Regulation compliance timelines ahead of full MDR implementation. For New Entrants and Emerging Players: Begin with CDSCO accelerated registration pathways for nucleic acid collection products targeting India's diagnostic infrastructure buildout. Penetrate at-home specimen collection kits requiring redesigned stability validation as the most accessible white-space segment. Pursue private-label partnerships with established medical device distributors to bypass hospital procurement committee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with proprietary flocking technology in Germany and proprietary foam formulations in United States industrial cleaning segments. Five-to-ten year viability hinges on regulatory certification durability rather than volume scale alone. Monitor NMPA registration review velocity for domestically manufactured products as the critical inflection signal for multinational repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Flocking Capacity Expansion | Puritan Medical Products leverages proprietary technology to serve high-throughput PCR workflow standardization in United States hospital networks. |
| CE Marking Pathway Acceleration | Diagnostic-grade swab producers secure conformity assessment ahead of EMA In Vitro Diagnostic Regulation full implementation across European markets. |
| Hospital System Partnership | Integrated delivery network formulary compliance locks in bulk sterile packet procurement through centralized purchasing cooperatives. |
| Backward Integration into Polymer Supply | Captive nylon resin agreements with Yangtze River Delta producers insulate margins from petrochemical input volatility. |
| Direct-to-Consumer Kit Development | Redesigned packaging and stability validation bypass traditional laboratory procurement channels for at-home diagnostic applications. |
Research Methodology
Independent corroboration across FDA 510(k) filings, EMA technical documentation, and NMPA registration databases underwrites the qualitative findings on regulatory pathway differentiation. Primary interviews with diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and polymer supply procurement leads combined with secondary validation from customs trade data, ISO 13485 certification registries, and hospital procurement databases. Bottom-up demand modeling across clinical laboratory, research institute, and personal consumer channels triangulates with top-down market sizing.
Rate-of-change decomposition separates volume expansion from value migration across material composition tiers, application segments, and end-user channels over the projection horizon. Segmentation dimensions modeled include product type, sterility assurance level, packaging configuration, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year estimates with sensitivity testing around polymer price elasticity and diagnostic testing volume assumptions. Viral transport medium compatibility standards and automated specimen processing system integration requirements constitute industry-specific forecast inputs.
Underlying measurement precision varies by segment; medical diagnostics and clinical laboratory channels carry tighter precision than personal care and industrial cleaning applications given documentation density. Forecasts reflect assumptions on regulatory harmonization velocity, biocompatibility testing capacity expansion, and polymer supply chain resilience that could revise projections if disrupted. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Europe Custom Procedure Kits Market