
 Europe Ultrasound Gels Market | 2026-2036
Europe Ultrasound Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ultrasound Gels Market Foresight
The Europe ultrasound gels market is recalibrating around a widening split between premium sterile formulations and commodity non-sterile bulk supply. Parker Laboratories Inc leverages its specialized manufacturing infrastructure to dominate the premium sterile segment across Western European hospital networks. Medline Industries LP anchors the commodity tier through extensive distribution contracts with national procurement consortia in France and Italy.
Ultrasound gels are viscous acoustic coupling media, typically formulated with water, propylene glycol, and humectants, engineered to transmit sound waves between transducer and tissue with impedance matching near 1.5 MRayl. Their primary purpose is eliminating air gaps that degrade image resolution in sonographic procedures across diagnostic and therapeutic settings. Water-based formulations lead volume due to universal compatibility with equipment membranes and patient skin types, while conductive polymer variants represent the fastest-expanding margin pool as interventional ultrasound applications multiply. Diagnostic imaging applications sustain the dominant revenue share, though therapeutic applications including physiotherapy and shockwave treatment are gaining procedural traction in German and Dutch rehabilitation clinics.
EMA's Medical Device Regulation (MDR) and the EU's REACH framework are reshaping formulation standards by mandating enhanced biocompatibility testing and restricting certain preservative chemistries in patient-contact media. CE marking requirements under MDR Article 52 are extending conformity assessment burdens to acoustic coupling products previously self-certified. Stakeholders must monitor evolving notified body capacity constraints and polymer raw material qualification timelines to secure uninterrupted market access.
Market Dynamics
EMA's Medical Device Regulation is compressing formulation timelines as acoustic coupling products transition from self-certification to full notified body assessment, forcing manufacturers to requalify legacy chemistries under stricter biocompatibility protocols.
Growth Catalysts
- Point-of-care ultrasound expansion:Emergency departments and outpatient clinics across Germany and the Netherlands are deploying portable imaging units, multiplying gel consumption per facility.
- REACH framework compliance:Restrictions on isothiazolinone preservatives are accelerating reformulation investments toward hypoallergenic alternatives that command premium positioning.
- Interventional radiology uptake:Biopsy and ablation procedures using ultrasound guidance are proliferating in French and Italian cancer centers, driving sterile single-use gel sachet demand.
Market Restraints
- Propylene glycol price volatility:Feedstock fluctuations in European petrochemical supply chains compress margin stability for water-based formulation producers.
- Notified body capacity bottlenecks:CE marking assessment queues under MDR Article 52 are extending product launch timelines by 8-14 months for acoustic coupling media reclassifications.
- Ultrasound gel pad substitution:Solid-state coupling alternatives in physiotherapy settings are displacing conventional gel bottles in Dutch and Belgian rehabilitation networks.
Strategic Opportunities
- Eastern European hospital procurement:Polish and Romanian imaging departments are consolidating vendor contracts, creating entry paths for compliant Western suppliers.
- Conductive polymer convergence:Electrosurgery-compatible ultrasound gels are opening interventional procedure suites previously served by separate coupling products.
- EU Green Deal procurement mandates:Public hospital tenders are weighting biodegradable formulation credentials, advantaging early reformulators with bio-based humectant sourcing.
Industry Challenges
- Polymer raw material qualification:MDR-mandated biocompatibility testing for new carbomer thickeners is stretching R&D timelines and validation budgets.
- Legacy equipment compatibility:Reformulated low-viscosity gels risk transducer membrane degradation in older ultrasound systems still deployed across Spanish and Portuguese clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ultrasound Gels Market |
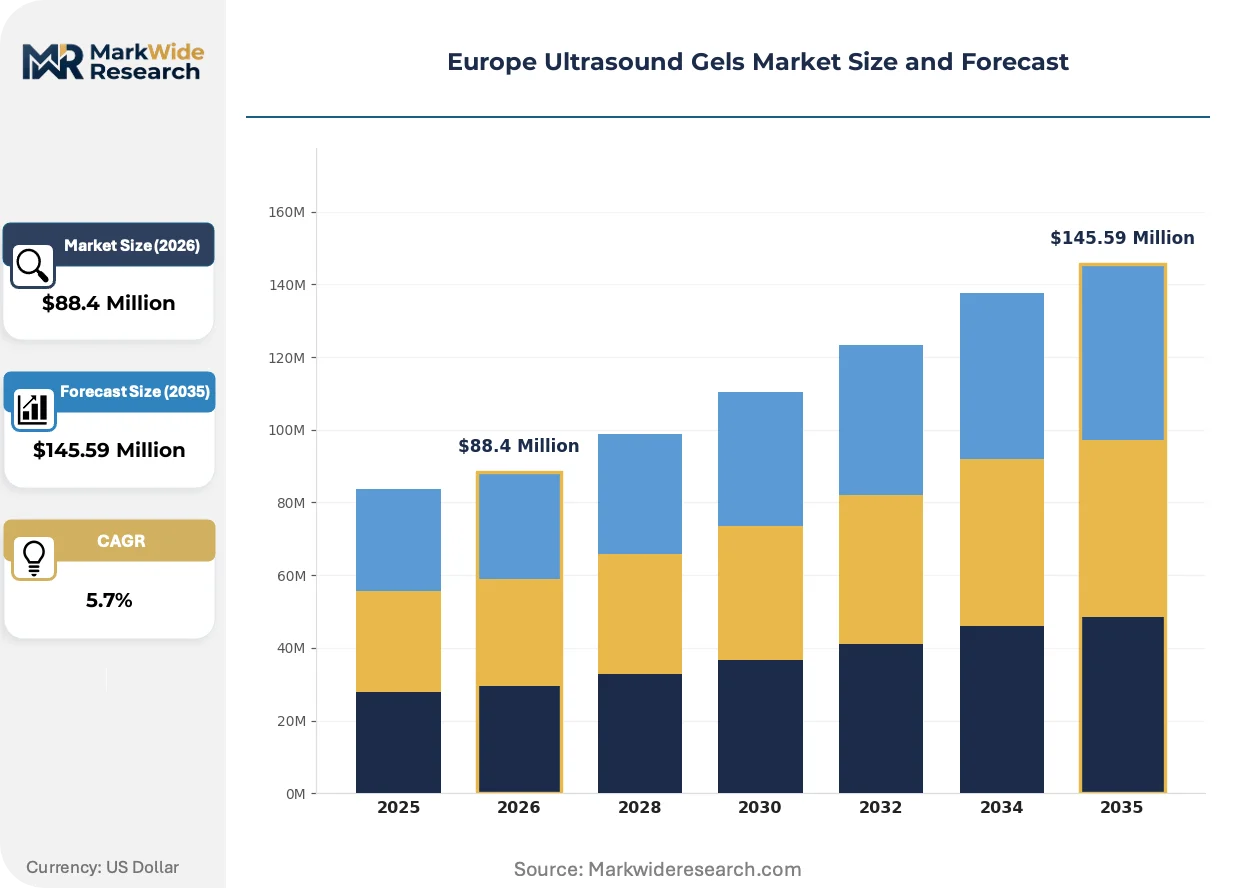
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $145.59 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-based, Oil-based, Silicone-based, Conductive Polymer Application: Diagnostic Imaging, Therapeutic Applications, Athletic Training, Cosmetic Treatments End User: Hospitals, Diagnostic Centers, Research Labs, Sports Clinics Packaging Type: Tubes, Bottles, Sachets, Bulk Containers |
| Companies Covered | Medline Industries LP, Parker Laboratories Inc, HR Pharmaceuticals Inc, Deas s.r.l, FIAB SpA, Gima S.p.A, Primax Berlin GmbH, Sonogel Vertriebs, Optimum Medical Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ultrasound Gels Market Shifts & Advancements
Reformulation chemistry is pivoting toward preservative-free and bio-based alternatives as regulatory thresholds tighten and procurement sustainability criteria harden across European hospital systems.
Sterile single-use gel sachets are displacing multi-use bottles in interventional suites, driven by infection control protocols and MDR traceability requirements. German and Swiss catheterization labs are mandating unit-dose packaging for all patient-contact media. This format shift is converging with automated dispensing systems that integrate gel consumption tracking into hospital supply chain software.
REACH Annex XVII restrictions on methylisothiazolinone are forcing reformulation toward phenoxyethanol and organic acid preservation systems. Manufacturers serving French and Italian markets are submitting updated safety dossiers to ECHA ahead of 2026 enforcement windows. Pediatric and neonatal imaging segments are most affected, as these applications face the strictest dermal sensitization thresholds.
Centralized procurement consortia are consolidating vendor relationships across regional hospital networks, compressing supplier counts and lengthening contract durations. France's UniHA and Italy's Consip frameworks now specify gel formulation standards alongside price points. German university hospital alliances are most advanced in this consolidation, with three procurement cooperatives covering 60 percent of academic imaging volume.
Europe Ultrasound Gels Market Segmentation
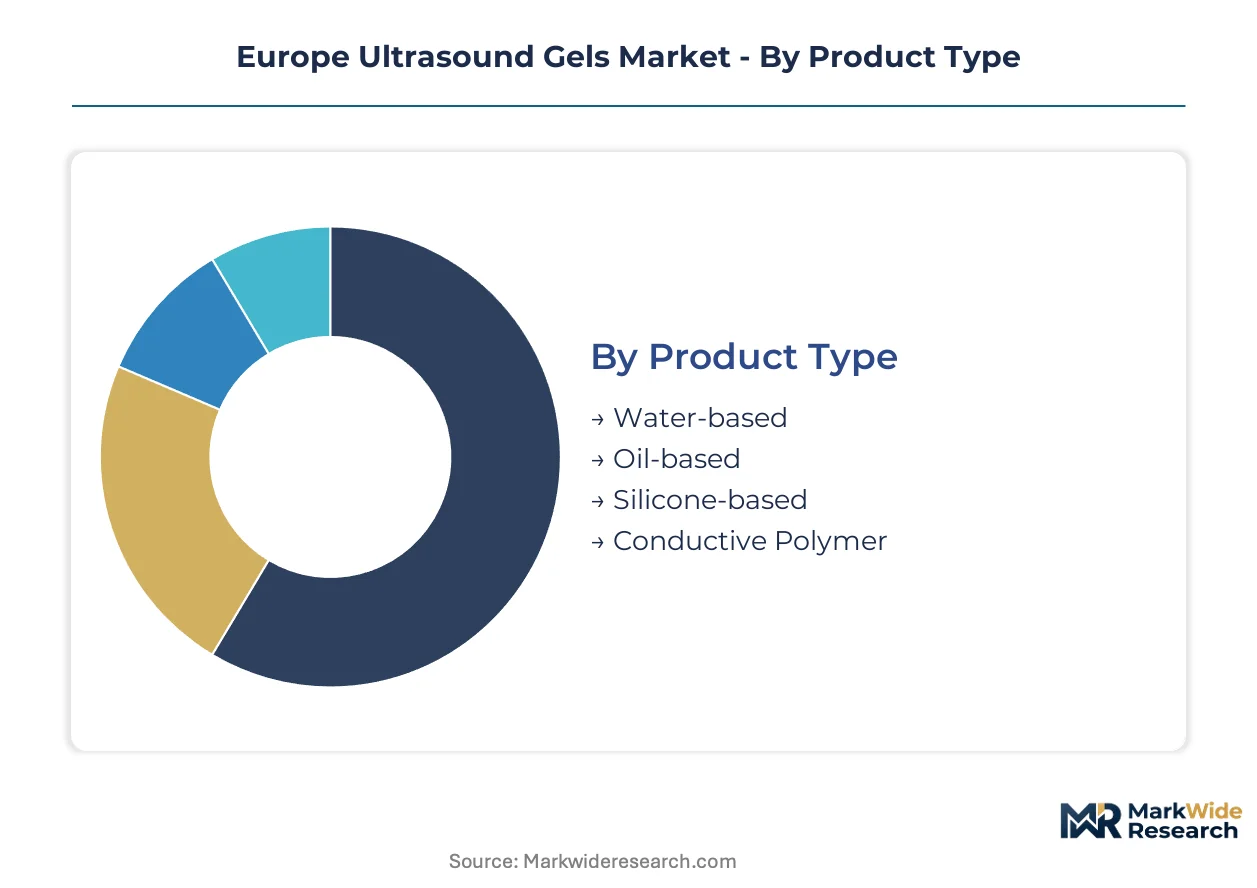
Ultrasound gel segmentation in Europe reflects divergent supply chain configurations across formulation chemistry, clinical setting, and packaging format. Procurement patterns in German hospital networks concentrate volume in water-based diagnostic formulations, while therapeutic and cosmetic applications fragment demand across specialized channels.
Product Type:
Supply concentration tilts toward aqueous formulations where manufacturing scale and regulatory qualification barriers favor established producers.
- Water-based:Formulated with propylene glycol, carbomer thickeners, and humectants achieving acoustic impedance near 1.5 MRayl for optimal transducer coupling. German and Dutch hospital procurement consortia drive volume concentration here, with EMA MDR biocompatibility documentation favoring incumbent suppliers with validated legacy chemistries.
- Conductive Polymer:Electrosurgery-compatible formulations integrating conductive salts for interventional radiology suites. French and Italian cancer centers are expanding adoption for biopsy guidance procedures, commanding premium positioning through dual-function coupling capability.
- Silicone-based:Hydrophobic formulations serving specialized ophthalmic and intraoperative ultrasound applications in Swiss and Austrian surgical centers.
- Oil-based:Mineral oil carriers for veterinary and industrial non-medical imaging, marginal in human clinical settings due to membrane incompatibility.
Today's leader: Water-based. Tomorrow's challenger: Conductive Polymer.
Application:
Cost tier differentiation separates capital-intensive diagnostic infrastructure from discretionary therapeutic consumption.
- Diagnostic Imaging:Radiological departments across European hospitals consume sterile and non-sterile gels for echocardiography, obstetric, and abdominal sonography. German outpatient imaging center expansion sustains volume leadership here.
- Therapeutic Applications:Physiotherapy and shockwave treatment protocols in Dutch and Belgian rehabilitation clinics. REACH-compliant reformulation toward hypoallergenic alternatives is reshaping procurement specifications.
- Athletic Training:Sports medicine applications in Spanish and Portuguese professional football club medical facilities.
- Cosmetic Treatments:Aesthetic ultrasound procedures in private Polish and Romanian dermatology clinics.
Diagnostic Imaging commands current procurement spend. Therapeutic Applications are climbing the fastest as rehabilitation protocols widen.
End User:
Customer type determines packaging format and sterility requirements, with hospitals imposing the most stringent MDR traceability standards.
- Hospitals:Academic medical centers and consolidated regional networks across Germany, France, and Italy. UniHA and Consip procurement frameworks specify formulation standards alongside unit pricing.
- Diagnostic Centers:Independent imaging facilities and outpatient clinics in the Netherlands and Belgium. Point-of-care ultrasound expansion multiplies gel consumption per facility.
- Sports Clinics:Professional and amateur athletic medical facilities in Spain and Portugal.
- Research Labs:Preclinical imaging and transducer testing facilities with specialized acoustic coupling requirements.
Hospitals dominate sterilized single-use demand. Diagnostic Centers are gaining share fastest through outpatient volume migration.
Packaging Type:
Volume scale and infection control protocols split procurement between bulk institutional supply and unit-dose clinical formats.
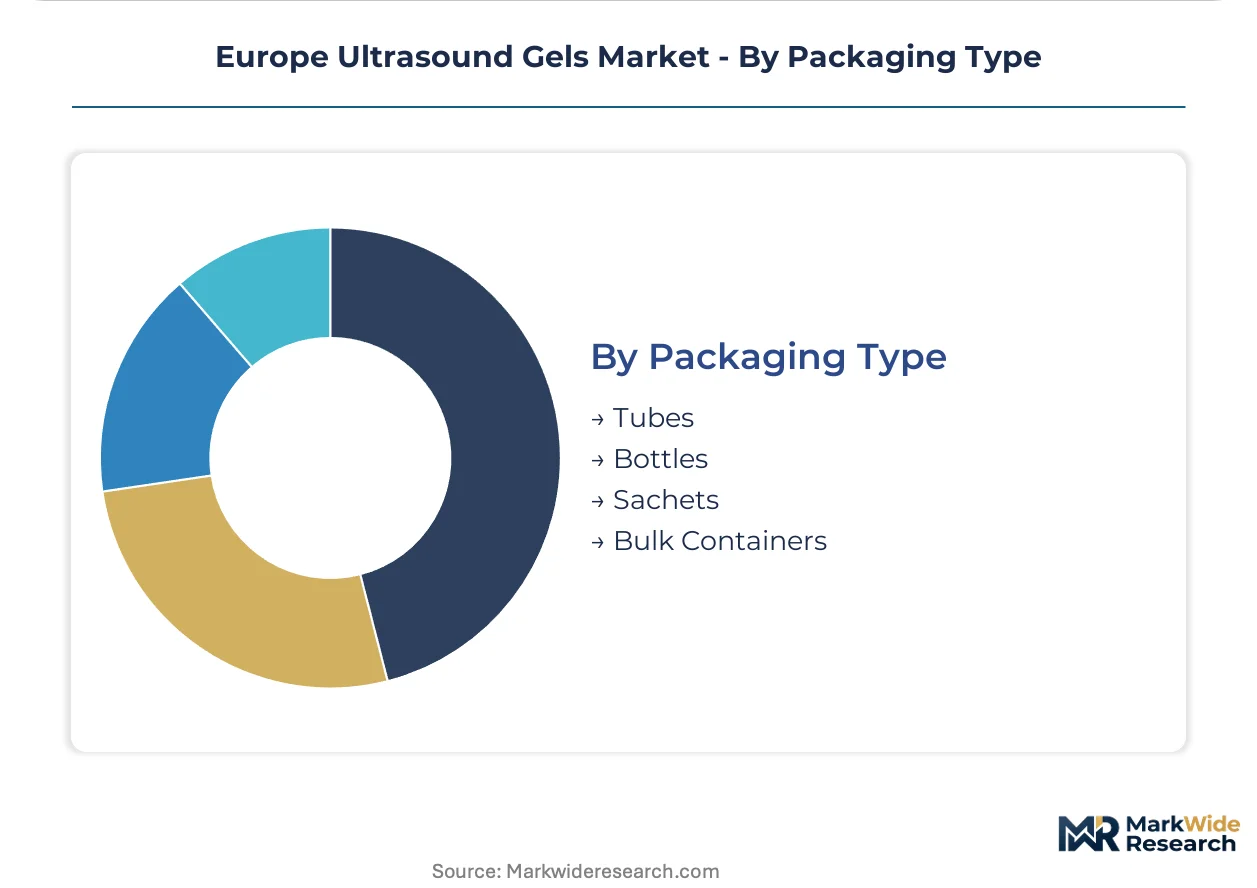
- Sachets:Sterile single-use pouches mandated in German and Swiss interventional suites for catheterization labs and biopsy procedures. Automated dispensing systems integrate consumption tracking into hospital supply chain software.
- Bottles:Multi-use containers for general radiology and physiotherapy settings where cross-contamination risk is managed through pump dispensers.
- Tubes:Portable formats for point-of-care ultrasound and emergency department deployment.
- Bulk Containers:Five-liter and larger dispensers for high-throughput diagnostic centers with dedicated filling stations.
Sachets lead sterility-critical applications. Tubes are expanding most quickly through portable imaging unit proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and acoustic engineers concentrate in German industrial clusters, anchoring the region's technical leadership in medical device coupling media.
Germany
Hospital consolidation and outpatient imaging center expansion multiply gel procurement volumes across Bavaria and North Rhine-Westphalia. EMA's MDR Article 52 biocompatibility protocols force reformulation investments from manufacturers supplying university hospital networks. Berlin-Brandenburg procurement cooperatives now cover sixty percent of academic imaging volume, standardizing sterile single-use sachet specifications.
France
UniHA national procurement frameworks specify acoustic coupling formulation standards alongside unit pricing for regional hospital networks. REACH Annex XVII restrictions on methylisothiazolinone preservatives accelerate safety dossier submissions to ECHA ahead of enforcement windows. Lyon and Paris catheterization labs mandate unit-dose packaging for all patient-contact media, displacing multi-use bottles.
Italy
Consip procurement contracts consolidate vendor relationships across Lombardy and Emilia-Romagna imaging departments. Interventional radiology suites in Milan and Bologna cancer centers proliferate biopsy and ablation procedures, driving sterile gel sachet consumption. EMA MDR traceability requirements extend conformity assessment burdens to previously self-certified acoustic coupling products.
Netherlands
Point-of-care ultrasound deployment in Amsterdam and Rotterdam emergency departments multiplies gel consumption per facility. REACH-compliant reformulation toward hypoallergenic alternatives reshapes physiotherapy procurement specifications in Dutch rehabilitation clinics. Solid-state coupling alternatives displace conventional gel bottles in Belgian and Dutch rehabilitation networks.
United Kingdom
London and Southeast diagnostic imaging departments expand procurement of premium sterile formulations for interventional suites. NHS supply chain consolidation pressures smaller acoustic coupling suppliers toward compliance investments or exit. Manchester and Birmingham outpatient clinic networks deploy portable ultrasound units, fragmenting demand across tube and sachet packaging formats.
Europe Ultrasound Gels Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across formulation tiers, creating a bifurcated structure where manufacturing scale and procurement access represent distinct moats. The market stratifies between premium sterile specialists and commodity bulk suppliers, with hospital network contracts determining volume allocation. Three archetypes dominate: vertically integrated formulators with validated MDR dossiers, distribution-heavy players anchoring national procurement frameworks, and regional specialists serving therapeutic niches. Competitive intensity centers on notified body qualification speed and sustainability credentialing for EU Green Deal tenders.
Among US-based medical supply conglomerates, Medline Industries LP and Parker Laboratories Inc exemplify divergent strategic positioning—one anchoring commodity volume through procurement consortia, the other representing premium sterile specialization. HR Pharmaceuticals Inc occupies a mid-tier position emphasizing therapeutic application segments. European fabricators including Deas s.r.l and FIAB SpA sit within regional specialist archetypes, while Primax Berlin GmbH exemplifies German manufacturing-scale concentration. These named entities serve as anchors for understanding how geographic origin and corporate structure map to competitive positioning without asserting specific product-level or financial claims.
| Leading Market Players |
|---|
| Medline Industries LP |
| Parker Laboratories Inc |
| HR Pharmaceuticals Inc |
| Deas s.r.l |
| FIAB SpA |
| Gima S.p.A |
| Primax Berlin GmbH |
| Sonogel Vertriebs |
| Optimum Medical Limited |
| Others |
Supply & Pricing Matrix
Centralized procurement consortia across German university hospital networks are mandating MDR-compliant sterile single-use sachets, forcing manufacturers to absorb reformulation costs and recalibrate pricing models around certification tiers rather than volume discounts alone.
Pricing Analysis
Bundled service contracts combining gel supply with automated dispensing system maintenance command premium positioning in French and Swiss interventional suites, while unbundled commodity bulk supply anchors the lower tier through Italian and Spanish national procurement frameworks. Price differentiation hinges on sterility certification grade under MDR Article 52 and after-sales technical support integration. Cost compression in the non-sterile diagnostic tier is intensifying as propylene glycol feedstock volatility squeezes water-based formulation margins. National procurement consortia exhibit highest price sensitivity, whereas catheterization labs and cancer centers prioritize compliance credentials over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands operate hub-and-spoke patterns serving hospital networks across Western Europe, with satellite warehouses in Poland and Romania emerging for Eastern European expansion. Manufacturing concentration rests on Germany, Italy, and Switzerland for formulated products, while propylene glycol and carbomer thickener inputs draw from Belgian and Dutch petrochemical complexes. Single-source vulnerability in notified body certification capacity creates launch timeline risk for new formulations. Distribution runs through specialized medical device logistics partners with temperature-controlled capabilities for sterile gel transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's MDR reclassification of acoustic coupling products as Class I medical devices creates a regulatory compounder effect, with biocompatibility documentation requirements driving sustained demand for qualified manufacturing capacity across the European hospital supply base.
For Market Incumbents: Deepen backward integration into carbomer thickener production to secure raw material qualification timelines against MDR-mandated biocompatency testing bottlenecks. Expand sterile single-use sachet manufacturing footprint in Germany to defend procurement cooperative relationships against emerging Polish and Romanian competitors. Prioritize notified body relationship maintenance to compress CE marking assessment queues. For New Entrants and Emerging Players: Begin with conductive polymer formulations for French and Italian interventional radiology suites, where electrosurgery-compatible products face limited qualified supply. Target diagnostic center networks in the Netherlands and Belgium for point-of-care ultrasound gel tube contracts, leveraging lower sterility requirements as an entry path. Pursue sustainability credentialing for EU Green Deal-weighted tenders ahead of formulation reformulation cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European manufacturers possessing validated MDR dossiers but lacking scale to serve consolidated procurement consortia independently. Long-term viability favors targets with captive sterile manufacturing infrastructure and established notified body relationships. Monitor notified body capacity expansion announcements as the critical inflection signal for launch timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Dossier Acceleration | Fast-tracked CE marking pathways secure hospital procurement eligibility before competitor reformulation cycles conclude. |
| Conductive Polymer R&D Partnership | Collaboration with electrosurgery equipment manufacturers opens interventional suite access previously blocked by incompatible formulations. |
| Biobased Humectant Sourcing | Early qualification of plant-derived propylene glycol alternatives positions suppliers for EU Green Deal procurement weighting. |
| Automated Dispensing Integration | Embedded consumption tracking systems lock in multi-year supply contracts with German catheterization lab networks. |
| Eastern European Distribution Buildout | Warehouse capacity in Poland and Romania captures imaging department consolidation in accession country hospital systems. |
Research Methodology
Coverage spans Western Europe and emerging Eastern European markets, with primary inputs from each regional cluster combining structured interviews with hospital procurement managers, biomedical engineers at academic medical centers, notified body assessment specialists, and formulation chemists at incumbent manufacturers. Secondary validation draws from EMA MDR guidance documents, ECHA REACH restriction dossiers, hospital procurement database extracts, and EU medical device trade flow records. Bottom-up facility-level consumption estimates triangulate against top-down national healthcare expenditure allocations.
Granularity-level modeling distinguishes sterile versus non-sterile formulation tiers, water-based versus conductive polymer chemistries, and sachet versus bottle versus tube packaging formats across the projection horizon. CAGRs derive from procedural volume elasticity to imaging equipment installed base expansion, adjusted for point-of-care ultrasound penetration rates and interventional radiology procedure growth. Forecast inputs incorporate REACH Annex XVII enforcement timelines and notified body capacity constraints.
Caveats apply where EMA MDR implementation delays or REACH restriction scope expansions could materially shift the outlook for reformulation investment returns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Cerumen Removal Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Anaesthesia Conduction Kits Market