
 Blood Bag Tube Sealer Market | 2026-2036
Blood Bag Tube Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Bag Tube Sealer Market Outlook
Hospital procurement is pivoting toward centralized purchasing consortiums across North American and Western European health systems. Terumo BCT leverages its integrated blood-component portfolio to anchor long-term supply agreements with regional hospital networks. Haemonetics Corporation competes through specialized automation modules that reduce manual handling errors in high-volume transfusion centers. Fresenius Kabi sustains geographic dominance in European markets through direct distribution relationships with national blood services.
A blood bag tube sealer is a electromechanical device that applies controlled thermal energy to polyethylene or polyvinyl chloride tubing, creating a hermetic seal that maintains sterile containment of blood components during collection, processing, and storage. Heat sealing technology dominates installed base volumes due to proven reliability and lower capital requirements, while ultrasonic sealing represents the fastest-growing segment as facilities adopt cordless, battery-operated units for mobile collection drives. Automatic sealers command premium positioning in hospital end-user settings where throughput and traceability requirements justify higher equipment expenditure.
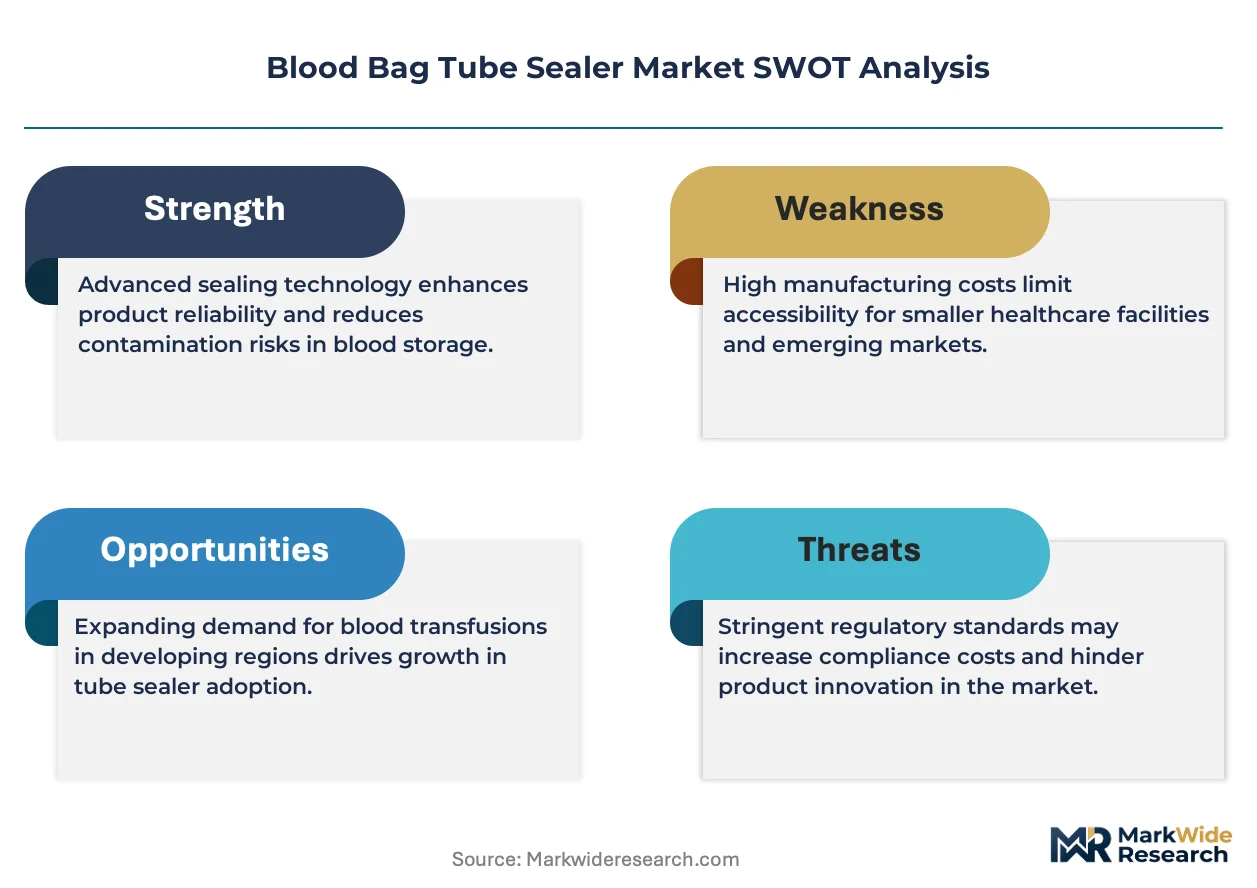
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation shape product development cycles and market access timelines for manufacturers serving transfusion medicine. The EPA and OSHA frameworks in the United States additionally govern workplace exposure limits during device operation and maintenance protocols. Stakeholders must monitor evolving harmonization between FDA quality system regulations and ISO 13485 standards to anticipate compliance cost structures and competitive qualification barriers.
Market Dynamics
Hospital blood banks are consolidating procurement authority into centralized purchasing consortiums, compressing vendor margins while elevating equipment standardization requirements across multi-site networks. This structural shift favors manufacturers with integrated service capabilities and multi-year maintenance contracts.
Growth Catalysts
- EU MDR compliance deadlines:Blood services across Germany, France, and Italy are replacing legacy sealers ahead of 2027 CE marking renewal cycles, creating replacement demand for validated sterile handling equipment.
- Mobile collection expansion:Cordless ultrasonic sealers enable blood drives at remote community centers, corporate campuses, and disaster response sites without electrical infrastructure.
- Polymer tubing standardization:Uniform PVC and polyethylene specifications across Japanese and US blood bag manufacturers reduce sealer calibration complexity and accelerate cross-border equipment deployment.
Market Restraints
- Copper and semiconductor input costs:Thermal sealing element production depends on copper alloy pricing and power electronics availability, exposing manufacturers to commodity volatility.
- Single-source component concentration:Precision heating coils and battery cells for cordless units originate primarily from East Asian suppliers, creating geographic supply risk.
- Reusable instrument substitution:Some European blood services are piloting metal tube crimpers with disposable sleeves as alternatives to heat-based permanent seals.
Strategic Opportunities
- Indian blood banking infrastructure:State-level blood transfusion councils under the National AIDS Control Organization are equipping district hospitals with automated processing equipment.
- Platelet additive solution integration:Sealer manufacturers can bundle equipment with specialized tubing sets for extended platelet storage protocols.
- ISO 13485 harmonization:Converging FDA quality system regulations with international standards reduces duplicate audit burdens for multi-territory suppliers.
Industry Challenges
- Biomedical equipment technician shortages:Hospitals lack personnel trained in electromechanical sealer maintenance, forcing manufacturers to expand field service networks.
- Legacy system integration:Automated sealers must interface with existing laboratory information management systems through proprietary protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Bag Tube Sealer Market |
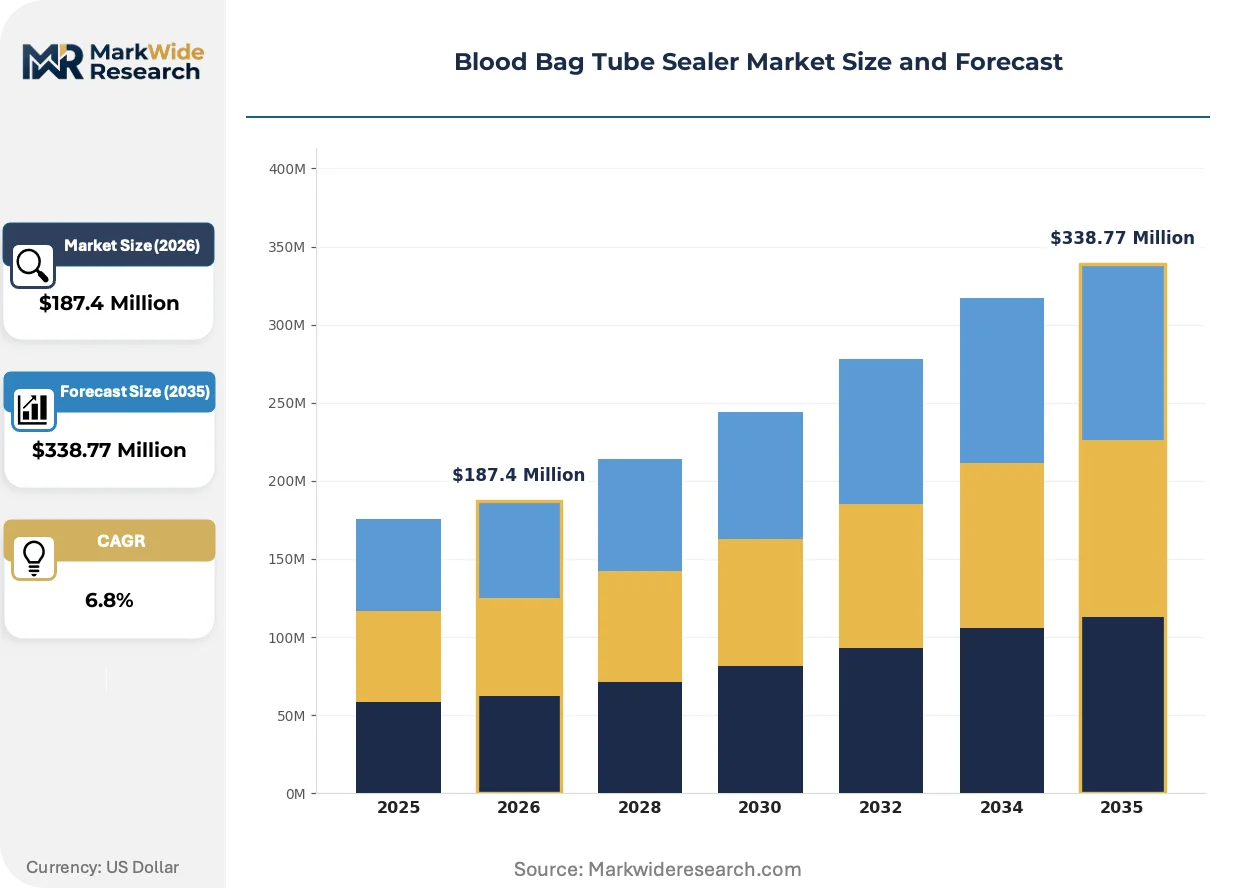
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Sealers, Semi-Automatic Sealers, Automatic Sealers, Portable Sealers Technology: Heat Sealing, Laser Sealing, Ultrasonic Sealing, RF Sealing End User: Hospitals, Blood Banks, Research Labs, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Outlets |
| Companies Covered | Macopharma, Labtron, Terumo BCT, Elektocraft Pvt Ltd, Lasany International, Haemonetics Corporation, New Meditech, Biobase Meihua Trading Co., Ltd, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Bag Tube Sealer Market Strategic Shifts
Sealer technology is bifurcating between high-throughput fixed installations and portable field units, with connectivity features emerging as the decisive differentiator in hospital procurement decisions.
Ultrasonic sealing is absorbing demand from conventional heat-sealing platforms in mobile and point-of-care settings. Blood collection organizations in Japan and Australia are deploying battery-operated units for disaster response and rural outreach programs. This technology is absorbing market share previously held by thermal systems in applications where electrical access is unreliable or absent.
CE marking under the EU Medical Device Regulation now requires clinical evidence documentation for sterile containment claims. Manufacturers serving European blood services must maintain technical files with biocompatibility testing and sterilization validation data. Hospital end-users in Germany and the Netherlands are prioritizing suppliers with established notified body relationships to minimize regulatory delay.
Centralized purchasing consortia are consolidating vendor relationships across regional health systems in the United States and United Kingdom. Independent equipment distributors are losing access to large hospital networks as procurement authority shifts to group purchasing organizations with standardized technical specifications. This concentration is most pronounced in multi-hospital systems across Texas, California, and the National Health Service supply chain.
Blood Bag Tube Sealer Market Segmentation
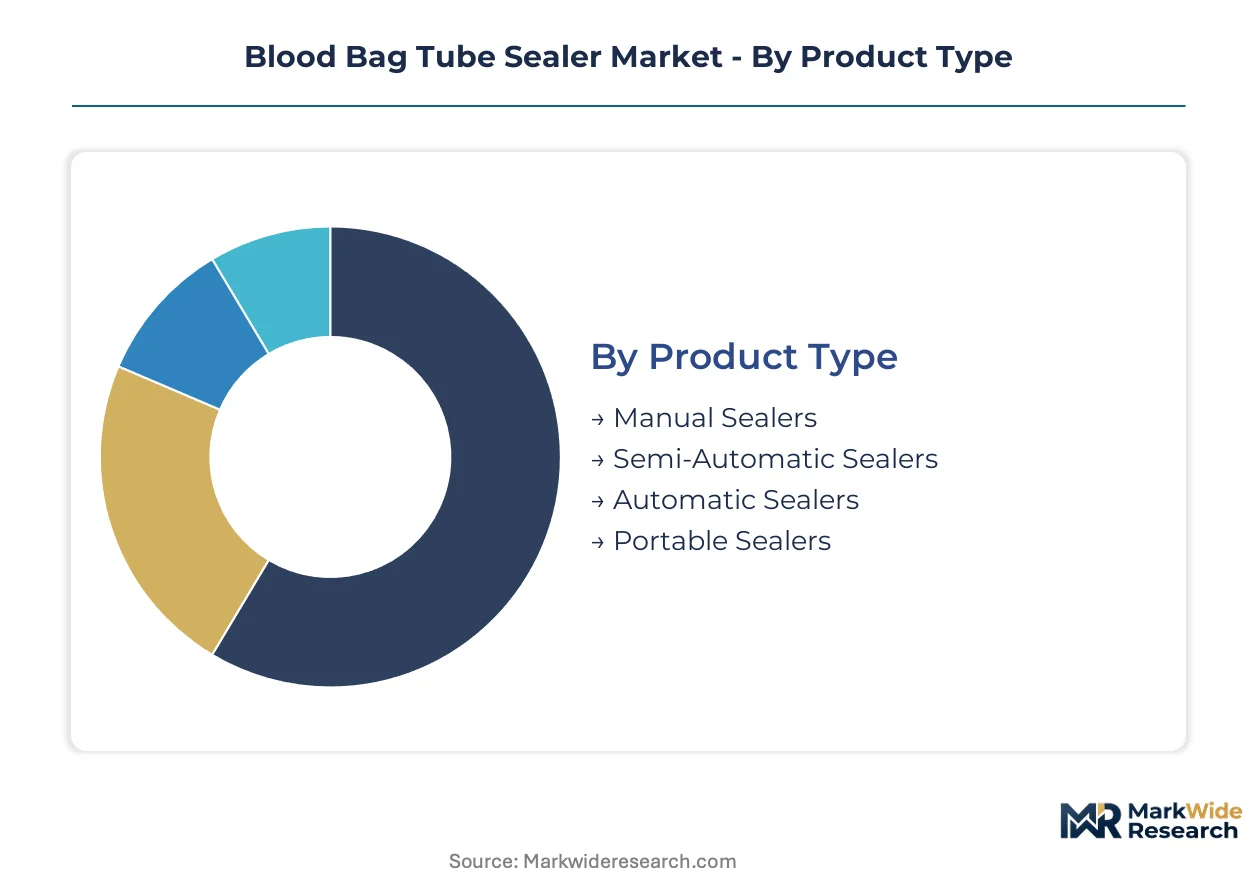
Segmentation in the blood bag tube sealer market reflects divergent operational requirements across transfusion medicine settings. Procurement patterns vary sharply between high-throughput hospital blood banks and mobile collection units, while regulatory validation tiers separate premium automated systems from entry-level equipment.
Product Type:
Automation levels define capital allocation priorities across end-user facilities, with throughput demands and staffing constraints driving equipment selection.
- Automatic Sealers:These units integrate programmable thermal profiles with barcode traceability for high-volume processing lines. Hospital blood banks in Germany and Japan deploy these systems to meet throughput targets exceeding 500 units per hour while maintaining FDA 510(k) compliance documentation.
- Portable Sealers:Battery-powered cordless designs weighing under 2 kilograms enable field deployment at disaster response sites and corporate blood drives. Australian Red Cross mobile collection teams have standardized on these units for rural outreach programs where electrical infrastructure is unavailable.
- Manual Sealers:Hand-operated thermal devices serve low-volume research applications and backup redundancy roles.
- Semi-Automatic Sealers:Foot-pedal activation with preset heating cycles bridges cost and automation gaps for mid-tier blood banks.
Automatic sealers lead on scale; portable sealers lead on momentum.
Technology:
Sealing mechanisms differentiate on energy transfer precision, with thermal methods dominating installed base and ultrasonic platforms capturing mobile expansion.
- Heat Sealing:Resistive heating elements apply controlled temperature to PVC and polyethylene tubing, creating permanent hermetic bonds. This technology commands the largest installed base due to lower capital requirements and established validation protocols under ISO 13485 quality systems.
- Ultrasonic Sealing:High-frequency mechanical vibration generates localized molecular friction without external heat sources. Cordless battery-operated units from Japanese manufacturers are displacing thermal systems in point-of-care settings where sterile field maintenance is critical.
- Laser Sealing:Focused infrared energy enables non-contact sealing for specialized polymer formulations in research applications.
- RF Sealing:Dielectric heating through radio frequency excitation serves niche high-speed production lines with continuous feed requirements.
Heat sealing dominates current deployment; ultrasonic platforms are climbing the fastest.
End User:
Facility type dictates equipment specifications, with regulatory burden and throughput requirements creating distinct procurement profiles.
- Hospitals:Integrated health systems in the United States and United Kingdom are consolidating sealer procurement through group purchasing organizations. These facilities prioritize automated units with laboratory information management system connectivity and multi-year service contracts.
- Blood Banks:National blood services in France and Italy are replacing legacy equipment ahead of EU MDR compliance deadlines. These organizations demand validated sterile containment documentation and notified body certification.
- Research Labs:Academic medical centers and biotechnology facilities utilize manual and semi-automatic units for protocol development and small-batch processing.
- Pharmaceutical Companies:Cell therapy manufacturers and plasma fractionators deploy specialized sealers for closed-system processing under GMP guidelines.
Hospitals lead on scale; blood banks lead on momentum.
Distribution Channel:
Channel structure is reshaping around centralized procurement authority and service integration requirements.
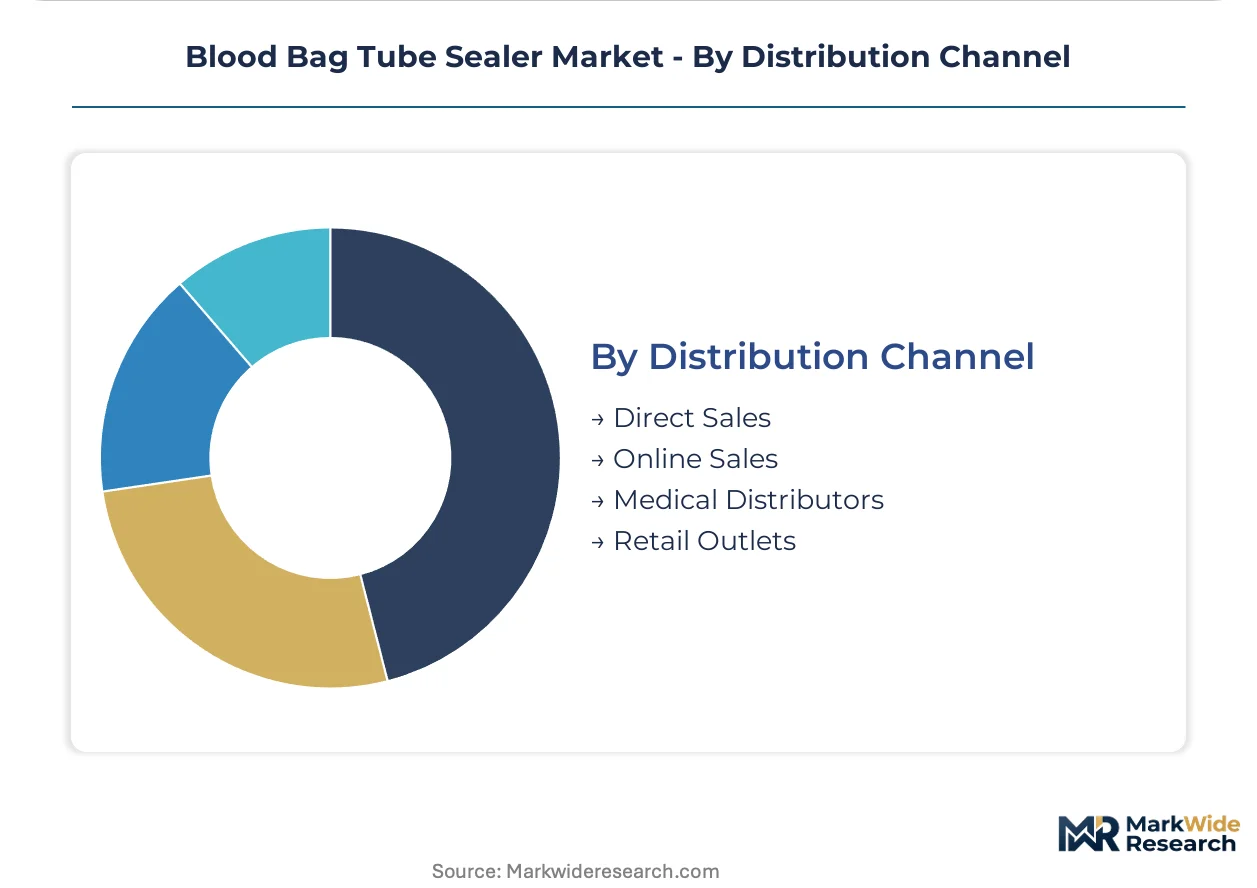
- Direct Sales:Manufacturers maintain field service engineers and application specialists for automated system deployment. Terumo BCT and Haemonetics utilize this channel for multi-hospital system contracts in North America.
- Medical Distributors:Regional specialty distributors serve independent blood banks and mid-tier hospitals with inventory stocking and technical support.
- Online Sales:E-commerce platforms facilitate replacement part procurement and consumable tubing set orders for existing equipment bases.
- Retail Outlets:Limited to emergency replacement units and basic manual sealers for veterinary and non-clinical applications.
Direct sales leads on scale; medical distributors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's blood services are replacing legacy sealers ahead of EU MDR deadlines, while the United States maintains the largest installed base of automated hospital systems. Japan's manufacturers dominate cordless ultrasonic technology for mobile collection drives. India's district hospital expansion and Australia's rural outreach programs represent contrasting infrastructure development trajectories.
United States
Hospital blood banks in Texas and California are consolidating procurement through group purchasing organizations that demand automated sealers with laboratory information management system connectivity. FDA 510(k) clearance requirements shape validation protocols for sterile containment claims. The Greater Boston medical cluster hosts specialized service networks supporting multi-hospital system maintenance contracts.
Germany
National blood services in North Rhine-Westphalia and Bavaria are executing replacement cycles for legacy equipment ahead of 2027 CE marking renewals under EU Medical Device Regulation. The country's notified body relationships minimize regulatory delay for validated sterile handling documentation. Frankfurt and Munich anchor distribution networks serving centralized hospital consortiums across Western Europe.
Japan
Domestic manufacturers in the Kanto region supply battery-operated ultrasonic sealers for disaster response and rural outreach programs where electrical infrastructure is unreliable. METI standards govern polymer tubing specifications that reduce sealer calibration complexity. Osaka-based production clusters serve Australian Red Cross mobile collection teams across the Asia-Pacific.
India
State-level blood transfusion councils under the National AIDS Control Organization are equipping district hospitals in Maharashtra and Karnataka with automated processing equipment. CDSCO medical device regulations are tightening validation requirements for imported sterile handling systems. The Delhi-NCR corridor concentrates distribution relationships with national health program procurement authorities.
Australia
The Australian Red Cross has standardized on portable cordless units for mobile collection drives in Queensland and Western Australia where population density limits fixed infrastructure investment. TGA medical device standards align with ISO 13485 quality systems for cross-border equipment deployment. Sydney and Melbourne host technical service networks supporting remote maintenance requirements.
Blood Bag Tube Sealer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates around three to four integrated manufacturers with established service networks and a fragmented base of regional fabricators serving price-sensitive procurement channels. Strategic archetypes include full-line transfusion medicine suppliers, specialized automation module developers, and contract equipment manufacturers. Dominant competitive moves encompass multi-year maintenance contract bundling and backward integration into precision heating coil production.
Among diversified medical technology conglomerates, Terumo BCT and Fresenius Kabi occupy positions anchored by integrated blood-component portfolios and direct distribution relationships with national health services. Haemonetics Corporation exemplifies the specialized automation archetype through its focus on high-volume transfusion center applications. Labtron and Elektocraft Pvt Ltd represent regional fabricators serving mid-tier hospital blood banks with standardized equipment configurations.
| Leading Market Players |
|---|
| Macopharma |
| Labtron |
| Terumo BCT |
| Elektocraft Pvt Ltd |
| Lasany International |
| Haemonetics Corporation |
| New Meditech |
| Biobase Meihua Trading Co., Ltd |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Copper alloy price indices on the London Metal Exchange cascade through thermal sealer manufacturing costs, compressing margins for mid-tier equipment suppliers while automated system vendors absorb volatility through multi-year hospital maintenance contracts.
Pricing Analysis
Capacity additions in China's power electronics sector are reshaping price floors for cordless ultrasonic sealers. Three-tier pricing structure across premium automated, standard semi-automatic, and economy manual levels separates FDA-validated hospital systems from research-lab backup units. Cost compression in the portable segment is intensifying because battery cell sourcing concentrates in East Asian suppliers. Independent blood banks exhibit highest price sensitivity, while integrated hospital networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Precision heating coil production rests on Japanese and German specialty metalwork suppliers, with battery cell manufacturing anchored in South Korea and China. Copper alloy feedstock, semiconductor power modules, and medical-grade polymer tubing constitute critical input dependencies. Single-source vulnerability in East Asian battery supply creates geographic concentration risk. Distribution runs through direct manufacturer field service networks for automated hospital systems, with regional medical distributors serving mid-tier blood bank procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood bag tube sealer market functions as a stable compounder, with recurring replacement cycles driven by EU MDR compliance deadlines and polymer tubing standardization creating predictable equipment refresh demand.
For Market Incumbents: Lock in multi-year service contracts with hospital purchasing consortia in Texas and California before EU MDR renewal waves peak. Backward integration into precision heating coil production reduces copper price exposure. Defend against cordless ultrasonic substitution by bundling thermal system upgrades with laboratory information management system connectivity.
For New Entrants and Emerging Players: EU MDR compliance deadlines in Germany and France open a window for validated sterile handling equipment positioned below Terumo BCT and Haemonetics price points. Target district hospital blood banks in Maharashtra and Karnataka under India's National AIDS Control Organization expansion. Pursue white-label manufacturing partnerships with Osaka-based ultrasonic technology developers for Asia-Pacific mobile collection markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical equipment technician shortages force manufacturers to expand captive field service networks. Five-to-ten-year viability favors suppliers with established notified body relationships and ISO 13485 quality system documentation. Acquisition target archetype: regional fabricators with CE marking technical files and existing hospital distributor relationships. Watch copper alloy price volatility and battery supply chain disruptions as margin inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Notified body pre-submission reduces regulatory delay for EU MDR renewal cycles in German blood services. |
| Hospital System Partnership | Group purchasing organization contracts in California and Texas lock in multi-year automated sealer deployments. |
| Software Companion Development | Laboratory information management system integration differentiates premium automated units in hospital procurement. |
| Backward Integration into Heating Coils | Captive copper alloy component production insulates margins from London Metal Exchange price volatility. |
| Geographic Expansion into District Hospitals | National AIDS Control Organization procurement in Maharashtra creates volume anchor for portable sealer lines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged hospital blood bank directors, biomedical equipment technicians, GPO contracts managers, and regulatory affairs leads at transfusion medicine manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and ISO 13485 audit registries. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure estimates were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to observed replacement cycles and regulatory compliance waves. Segmentation dimensions modeled include automation level, sealing technology, end-user facility type, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporated polymer tubing standardization timelines and notified body capacity constraints.
Revisions become necessary when copper alloy price spikes exceed historical volatility bands or when EU MDR renewal deadlines shift. Forecasts reflect assumptions about hospital consolidation trajectories and battery supply chain stability. Regulatory harmonization delays and technician workforce shortages warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Medical Bags Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Medical Liners Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Ultrasound Conductivity Gels Market