
 Wash Bottle Market | 2026-2036
Wash Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Wash Bottle Market Analytics
A shortage of polymer chemists with laboratory equipment certification is collapsing the pace of new product development across North American suppliers. Thermo Scientific leverages its captive resin-testing capabilities to sustain faster qualification cycles for fluoropolymer wash bottles. VWR anchors its position through direct distribution contracts with tier-one research universities. BRAND competes on European manufacturing scale, shipping ISO-compliant LDPE bottles to contract laboratories across France and Switzerland.
A wash bottle is a hand-pressurized dispensing vessel, typically fabricated from low-density polyethylene or fluorinated ethylene propylene, designed to deliver controlled streams of solvents, distilled water, or cleaning agents onto laboratory surfaces, glassware, or precision instruments. The 500 ml capacity segment dominates procurement volumes in hospital pathology departments where bench space constraints favor mid-size formats. Polyethylene product types lead material selection due to chemical inertness and squeeze responsiveness, though glass variants retain share in pharmaceutical quality-control labs requiring autoclave compatibility. Laboratory application demand outpaces industrial and education segments, driven by biotech R&D expansion and GLP-compliant facility upgrades.
OSHA laboratory safety standards in the United States mandate vented wash bottles for volatile solvent handling, directly shaping product design requirements and procurement specifications. REACH substance restrictions in the European Union limit certain plasticizer chemistries in laboratory plastics, forcing reformulation of conventional LDPE grades. The FDA's oversight of diagnostic laboratory equipment indirectly influences material traceability demands for wash bottles used in clinical settings. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations, as pending restrictions on fluoropolymer production could disrupt supply chains for high-performance wash bottle materials.
Market Dynamics
REACH substance restrictions and OSHA laboratory safety standards are forcing simultaneous reformulation of legacy LDPE grades and redesign of vented closure systems, compressing qualification timelines for North American and European suppliers.
Growth Catalysts
- Biotech R&D expansion:Venture-funded cell therapy startups in Germany and Switzerland are outfitting GLP-compliant cleanrooms with certified solvent-dispensing equipment. Procurement volumes from these facilities outpace academic laboratory growth.
- REACH compliance mandates:ECHA restrictions on plasticizer chemistries in laboratory plastics are accelerating replacement cycles for non-compliant wash bottle inventories across contract research organizations.
- Precision manufacturing clusters:University research budgets in Baden-Württemberg sustain above-average consumption of laboratory-grade wash bottles for analytical chemistry workflows.
Market Restraints
- Fluoropolymer supply concentration:Pending EU F-Gas Regulation restrictions on FEP and PTFE production threaten supply security for high-performance wash bottle materials used in pharmaceutical QC labs.
- Polymer chemist scarcity:North American suppliers face collapsed new product development timelines due to shortages of laboratory equipment certification specialists capable of resin qualification protocols.
- Glass substitution persistence:Autoclave-compatible borosilicate alternatives retain entrenched share in pharmaceutical quality-control applications where thermal sterilization is mandatory.
Strategic Opportunities
- Underpenetrated clinical diagnostics:Hospital pathology departments in France and Italy currently underserve 500 ml vented format demand relative to Northern European peers, presenting volume expansion potential.
- ISO 17025 laboratory accreditation wave:Third-party certification mandates across European contract testing labs are driving replacement of uncertified dispensing equipment with traceable, documented alternatives.
- Direct distribution channel development:Tier-one research universities are consolidating vendor relationships, favoring suppliers with captive logistics networks over traditional distributor intermediaries.
Industry Challenges
- Dual regulatory qualification timelines:Suppliers must simultaneously satisfy FDA material traceability demands for clinical settings and ECHA substance documentation requirements, stretching technical documentation resources.
- Legacy equipment integration friction:New fluoropolymer wash bottle designs face compatibility verification requirements with existing laboratory furniture and fume hood configurations.
- Per- and polyfluoroalkyl substance liability exposure:Evolving EPA and state-level PFAS regulations create uncertainty around long-term material liability for FEP-based product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wash Bottle Market |
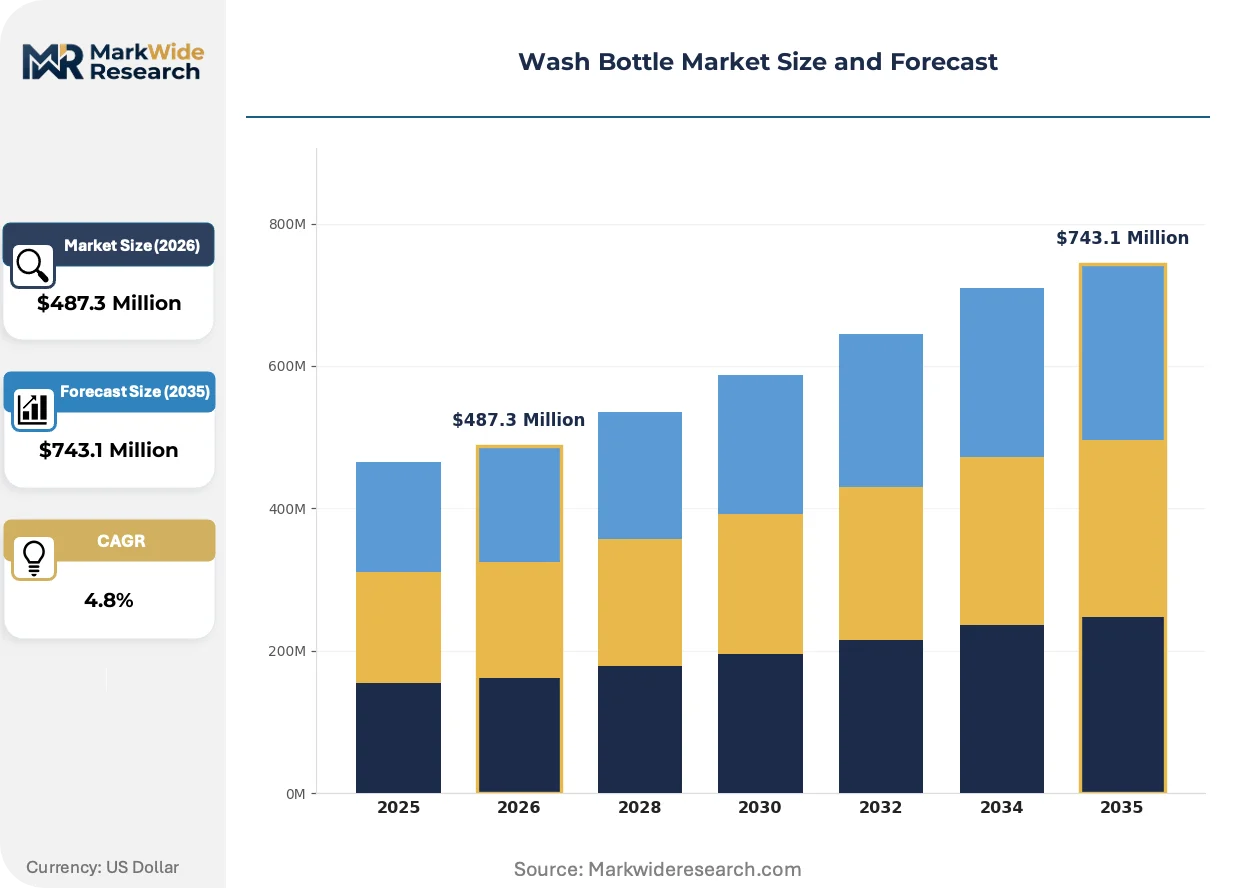
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Polyethylene Application: Laboratory, Hospital, Industrial, Education Capacity: 250 ml, 500 ml, 1000 ml, 2000 ml Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Distributors |
| Companies Covered | Thermo Scientific, VWR, Brkle, Corning Life Sciences, BRAND, Heathrow Scientific, Dynalon, Capitol Scientific, Camlab UK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wash Bottle Market Evolving Landscape
Material science advances and regulatory disclosure requirements are reshaping competitive positioning in laboratory dispensing equipment. Suppliers are racing to qualify next-generation polymer formulations ahead of substance restriction deadlines.
Fluorinated ethylene propylene formulations with enhanced chemical resistance profiles are displacing conventional LDPE in solvent-handling applications where aggressive organics degrade standard polyethylene. Pharmaceutical QC labs in Germany and Switzerland are adopting these formats at accelerated replacement cycles. This material shift is compressing margins for suppliers locked into legacy resin supply contracts without captive fluoropolymer testing capabilities.
REACH Article 33 disclosure obligations now mandate communication of Substances of Very High Concern throughout laboratory plastic supply chains. ECHA enforcement actions against non-compliant importers are redirecting procurement toward ISO-certified European manufacturers with documented substance inventories. Contract laboratories in France and Switzerland are prioritizing suppliers with full material disclosure capabilities.
Research universities are consolidating vendor panels and demanding integrated procurement platforms with real-time inventory visibility. Direct distribution contracts are displacing traditional laboratory supply distributor relationships for high-volume solvent-dispensing equipment. This channel compression is most visible in the United States, where VWR and Thermo Fisher have captured tier-one university contracts through dedicated service agreements.
Wash Bottle Market Segmentation
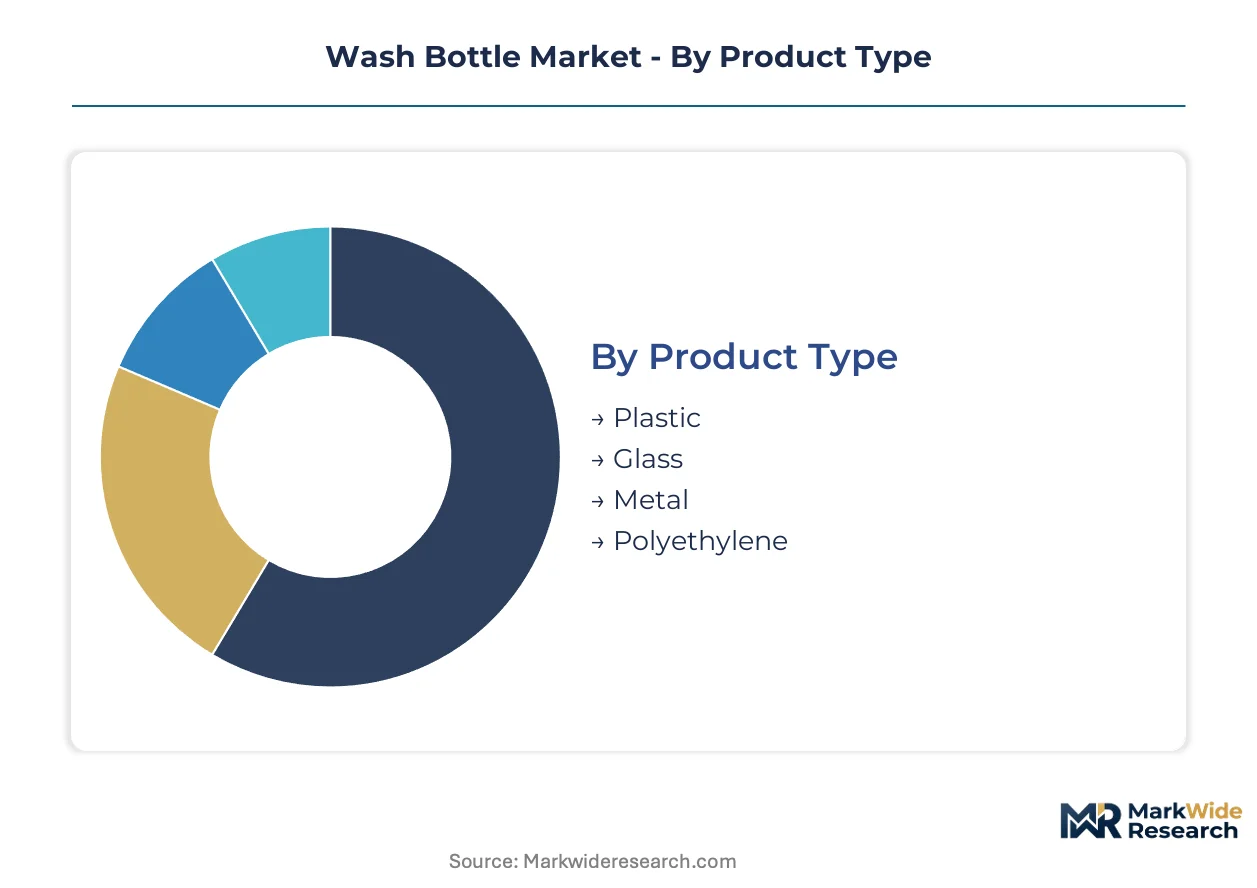
Wash bottle procurement patterns diverge sharply across material chemistry, institutional setting, and procurement channel. Substitution dynamics between polymer and glass formats reshape supplier positioning in each vertical.
Product Type:
Glass formats face the most acute substitution pressure from advanced fluoropolymers in pharmaceutical quality-control environments.
- Polyethylene:Low-density polyethylene dominates procurement due to chemical inertness and squeeze responsiveness. Hospital pathology departments in Germany and Switzerland favor this format for routine solvent dispensing where autoclave sterilization is unnecessary.
- Plastic:Conventional plastic formulations encompass polypropylene and copolymer variants used in educational settings. REACH Article 33 disclosure obligations are redirecting procurement toward ISO-certified European manufacturers with documented substance inventories.
- Glass:Borosilicate glass retains entrenched share in pharmaceutical quality-control labs requiring autoclave compatibility and thermal sterilization protocols.
- Metal:Stainless steel variants serve specialized industrial applications with extreme temperature or pressure requirements.
Polyethylene retains volume leadership; fluoropolymer-enhanced plastic holds the steepest expansion curve.
Application:
Laboratory end-use commands the highest per-unit margins due to certification and traceability requirements.
- Laboratory:Academic research laboratories in the United States and Europe are expanding procurement of certified solvent-dispensing equipment. Biotech R&D expansion and GLP-compliant facility upgrades drive replacement cycles.
- Hospital:Pathology departments favor 500 ml vented formats where bench space constraints favor mid-size configurations. Hospital pathology departments in France and Italy currently underserve demand relative to Northern European peers.
- Industrial:Manufacturing quality-control operations deploy wash bottles for precision instrument cleaning in precision manufacturing clusters.
- Education:University teaching laboratories represent high-volume, low-margin procurement with limited certification requirements.
Laboratory applications generate the highest revenue per unit; hospital settings offer the most visible volume expansion pathway.
Capacity:
Mid-capacity formats concentrate procurement value through volume-marginality tradeoffs in space-constrained environments.
- 500 ml:The dominant procurement format in hospital pathology departments where bench space constraints favor mid-size configurations. VWR and Thermo Fisher have captured tier-one university contracts through dedicated service agreements for this capacity.
- 250 ml:Compact formats serve micro-scale analytical chemistry workflows in Baden-Württemberg precision manufacturing clusters.
- 1000 ml:Extended-capacity bottles support industrial solvent handling with reduced refill frequency requirements.
- 2000 ml:Bulk formats address high-throughput contract research organization operations with centralized solvent dispensing stations.
500 ml holds procurement volume leadership; 250 ml is climbing the fastest in cell therapy startup cleanrooms.
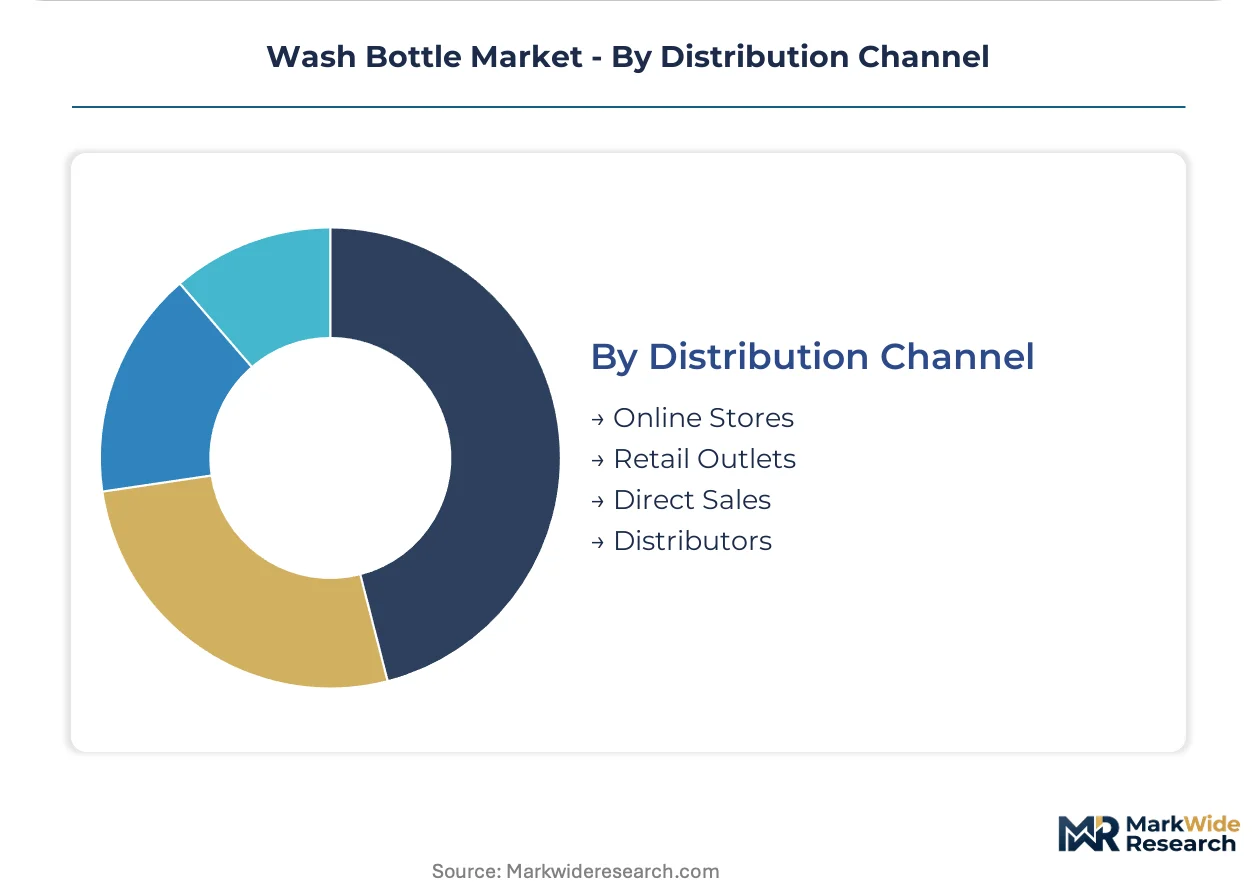
Distribution Channel:
Channel structure concentrates around direct relationships for high-volume institutional buyers.
- Direct Sales:Tier-one research universities are consolidating vendor relationships, favoring suppliers with captive logistics networks over traditional distributor intermediaries. Thermo Scientific leverages direct distribution contracts with dedicated service agreements.
- Distributors:Traditional laboratory supply distributors retain share in mid-market educational and smaller hospital accounts.
- Online Stores:E-commerce platforms serve fragmented small-laboratory procurement with limited volume consolidation potential.
- Retail Outlets:Physical retail channels address emergency replenishment and individual researcher purchases.
Direct sales commands the steepest share gains; distributors defend position in fragmented account tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes laboratory-grade wash bottles at per-capita rates exceeding France and Italy combined, driven by precision manufacturing density and university research intensity that other markets replicate only partially.
United States
OSHA laboratory safety standards mandate vented wash bottles for volatile solvent handling across academic and biotech R&D facilities. FDA material traceability requirements shape procurement specifications for clinical diagnostic applications. Greater Boston and San Diego biotechnology clusters sustain concentrated demand for fluoropolymer-certified dispensing equipment.
Germany
REACH substance restrictions accelerate replacement cycles for non-compliant LDPE wash bottle inventories in contract research organizations. Baden-Württemberg precision manufacturing clusters and university research budgets sustain above-average consumption of laboratory-grade formats. ECHA enforcement actions redirect procurement toward ISO-certified domestic manufacturers.
Switzerland
Venture-funded cell therapy startups in Basel and Zurich are outfitting GLP-compliant cleanrooms with certified solvent-dispensing equipment. Swissmedic oversight of diagnostic laboratories influences material qualification protocols. The country's pharmaceutical QC labs adopt fluoropolymer formats at accelerated replacement cycles.
France
Hospital pathology departments in Île-de-France and Auvergne-Rhône-Alpes currently underserve 500 ml vented format demand relative to Northern European peers. ANSM laboratory equipment guidelines tighten material specifications for chemical-contact surfaces. Contract laboratories across Lyon and Paris prioritize suppliers with full REACH Article 33 material disclosure capabilities.
United Kingdom
Research universities in the Golden Triangle consolidate vendor panels and demand integrated procurement platforms with real-time inventory visibility. The country's departure from EU regulatory frameworks creates parallel qualification requirements for laboratory plastics. London and Cambridge biotech clusters drive GLP-compliant facility upgrades with certified dispensing equipment.
Wash Bottle Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the wash bottle market structure. Thermo Scientific and VWR anchor the upper tier through captive distribution networks and direct university contracts. The middle tier comprises European manufacturers with ISO-certified production and documented substance inventories. Competitive moves concentrate on geographic expansion through distributor acquisitions and portfolio diversification into fluoropolymer formats.
Within the integrated laboratory supply tier, Thermo Scientific and VWR represent the dominant positioning archetype through direct distribution contracts with tier-one research universities. BRAND exemplifies the European manufacturing scale archetype, shipping ISO-compliant formats to contract laboratories across France and Switzerland. These three companies occupy positions that reflect the market's bifurcation between North American channel control and European regulatory compliance specialization.
| Leading Market Players |
|---|
| Thermo Scientific |
| VWR |
| Brkle |
| Corning Life Sciences |
| BRAND |
| Heathrow Scientific |
| Dynalon |
| Capitol Scientific |
| Camlab UK |
| Others |
Value Network & Pricing Analysis
Captive fluoropolymer resin-testing capabilities in Germany and the United States create scale advantages that compress price floors for certified laboratory-grade wash bottles while elevating entry barriers for suppliers lacking in-house qualification protocols. REACH compliance documentation and OSHA vented-closure mandates add fixed-cost layers that favor volume producers with dedicated regulatory affairs teams.
Pricing Analysis
Long-term direct distribution contracts with tier-one research universities anchor pricing stability for incumbent suppliers, while spot procurement through traditional laboratory distributors serves fragmented educational accounts at compressed margins. Price differentiation rests on certification tier—ISO 17025-accredited formats command premiums over uncertified alternatives—and geographic delivery cost differentials between European manufacturing clusters and North American end-users. Cost compression in conventional LDPE grades is intensifying as ECHA substance restrictions force reformulation investments. Hospital pathology departments in Southern Europe exhibit the highest price sensitivity due to budget fragmentation, whereas pharmaceutical QC labs in Switzerland and Germany prioritize chemical resistance over unit cost.
Supply Chain Analysis
Fluoropolymer precursor availability through German and Belgian chemical clusters constitutes a critical chokepoint for high-performance wash bottle production serving pharmaceutical QC applications. Raw material dependencies center on low-density polyethylene resin from Saudi Arabian and U.S. Gulf Coast petrochemical complexes, fluorinated ethylene propylene from specialized European polymer producers, and colorant additives subject to REACH Article 33 disclosure requirements. Single-source vulnerability in FEP resin qualification protocols threatens supply security as pending EU F-Gas Regulation restrictions loom. Distribution runs through captive direct sales networks for high-volume institutional buyers and traditional laboratory supply distributors for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated procurement platforms with real-time inventory visibility are consolidating vendor relationships into winner-take-most dynamics, rewarding suppliers with embedded logistics networks and penalizing fragmented distribution-dependent competitors.
For Market Incumbents: Secure captive fluoropolymer testing capabilities to sustain qualification cycle advantages as REACH substance restrictions tighten. Deepen backward integration into resin supply relationships to defend margin position against raw material volatility. Lock in exclusive direct distribution contracts with tier-one research universities before channel consolidation accelerates. For New Entrants and Emerging Players: ISO 17025 accreditation gaps among mid-sized European contract laboratories present service-layer white space where incumbents under-serve documentation-intensive procurement requirements. Target hospital pathology departments in France and Italy with vented 500 ml formats where Northern European peers currently oversupply. Pursue a certification-first go-to-market angle that front-loads ECHA substance documentation capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors suppliers with documented REACH compliance infrastructure and captive resin-testing capabilities over asset-light distributors vulnerable to channel compression. Long-term viability rests on regulatory compliance moats rather than manufacturing scale alone. Monitor ECHA enforcement action intensity as the inflection signal for procurement redirection toward ISO-certified domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Infrastructure Investment | ECHA enforcement actions redirect procurement toward suppliers with documented substance inventories across French and Swiss contract laboratories. |
| Direct Distribution Channel Development | Tier-one research universities in the United States consolidate vendor relationships, favoring captive logistics networks over traditional intermediaries. |
| Fluoropolymer Format Portfolio Expansion | Pharmaceutical QC labs in Germany and Switzerland adopt FEP-based wash bottles at accelerated replacement cycles driven by aggressive solvent handling requirements. |
| ISO 17025 Accreditation Certification | Third-party certification mandates across European contract testing labs drive replacement of uncertified dispensing equipment with traceable alternatives. |
| Backward Integration into Resin Supply | Captive polymer qualification protocols compress new product development timelines threatened by shortages of laboratory equipment certification specialists. |
Research Methodology
A spread of perspectives from laboratory procurement managers at tier-one research universities, regulatory affairs specialists at European polymer manufacturers, distribution channel partners, and hospital pathology department heads converged on the working assumptions underpinning volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through FDA laboratory safety guidance documents, ECHA substance restriction databases, OSHA technical standards, and ISO 17025 accreditation registries. Bottom-up procurement volume modeling and top-down market sizing triangulated across these independent data streams.
Segmentation dimensions modeled encompass material chemistry, institutional end-use setting, capacity configuration, and geographic regulatory cluster across the projection horizon. CAGRs were derived from trend extrapolation of procurement cycle frequencies, replacement rates driven by compliance mandates, and facility expansion pipelines in biotechnology clusters. Industry-specific forecast inputs include GLP-compliant cleanroom buildout schedules in cell therapy startups and university research budget trajectories in precision manufacturing regions.
Forecasts assume regulatory continuity in REACH substance restriction enforcement and OSHA laboratory safety standards; material policy shifts would require re-modeling of replacement cycle assumptions and material qualification timelines. Specific risk factors include pending EU F-Gas Regulation restrictions on fluoropolymer production and evolving EPA PFAS liability frameworks. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and polymer chemist labor market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Asia-Pacific N95 Mask Market