
 Alcohol Prep Pads Market | 2026-2036
Alcohol Prep Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Prep Pads Market Analysis
Hospital group purchasing organization contracts are tilting toward suppliers with captive non-woven fabric mills and sterilization infrastructure. Cardinal Health Inc. leverages its integrated distribution network to sustain shelf-space dominance across acute-care systems. Becton, Dickinson and Company anchors its position through R&D intensity in aseptic delivery formats. Medline Industries LP competes on manufacturing scale, operating multiple US-based pad conversion lines that reduce lead times for institutional buyers.
Alcohol prep pads are sterile or non-sterile wipes saturated with isopropyl alcohol, typically at 70% concentration by volume, used for skin disinfection prior to injection, venipuncture, or minor surgical procedures. The pads employ thermal-bonded or spunlace non-woven substrates to balance liquid retention with fiber shedding resistance below 50 particles per square centimeter. Single-use pads dominate volume due to infection control protocols that prohibit multi-patient contact, while premoistened formats in individual sachets command margin pools in ambulatory and home care channels where portability drives purchasing decisions. Non-woven fabric substrates lead material demand because cotton alternatives generate higher lint counts that compromise clean-field requirements.
The US FDA oversees antiseptic efficacy labeling under its ongoing monograph revision, while the EPA regulates the pre-registration of antimicrobial claims on non-medical alcohol wipes. India's CDSCO enforces isopropyl alcohol concentration disclosure on imported and domestic prep pad packaging, shaping how regional manufacturers formulate and label products for hospital tenders. Stakeholders must monitor whether FDA finalizes its 2017 proposed rule on healthcare antiseptics, as this would force reformulation investments and recertification timelines across the supplier base.
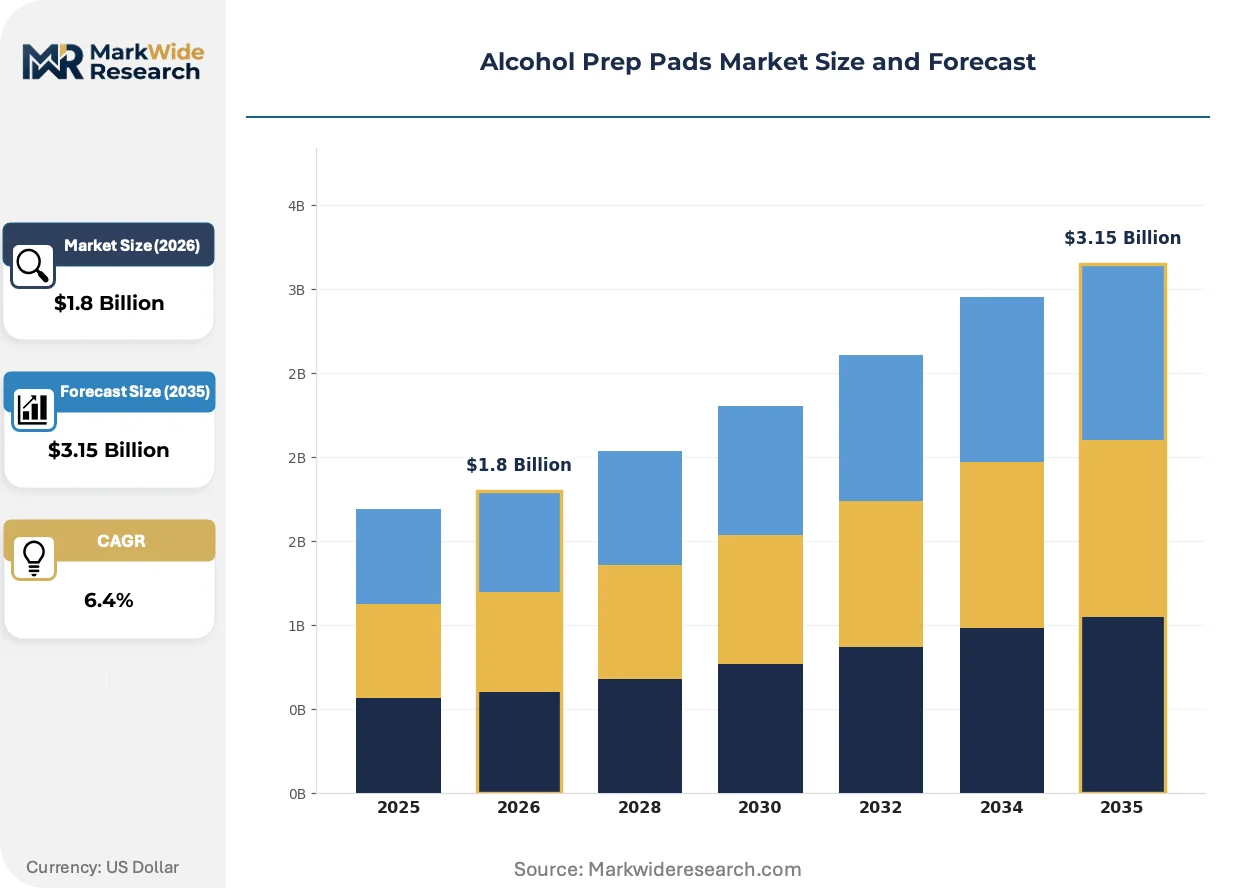
Market Dynamics
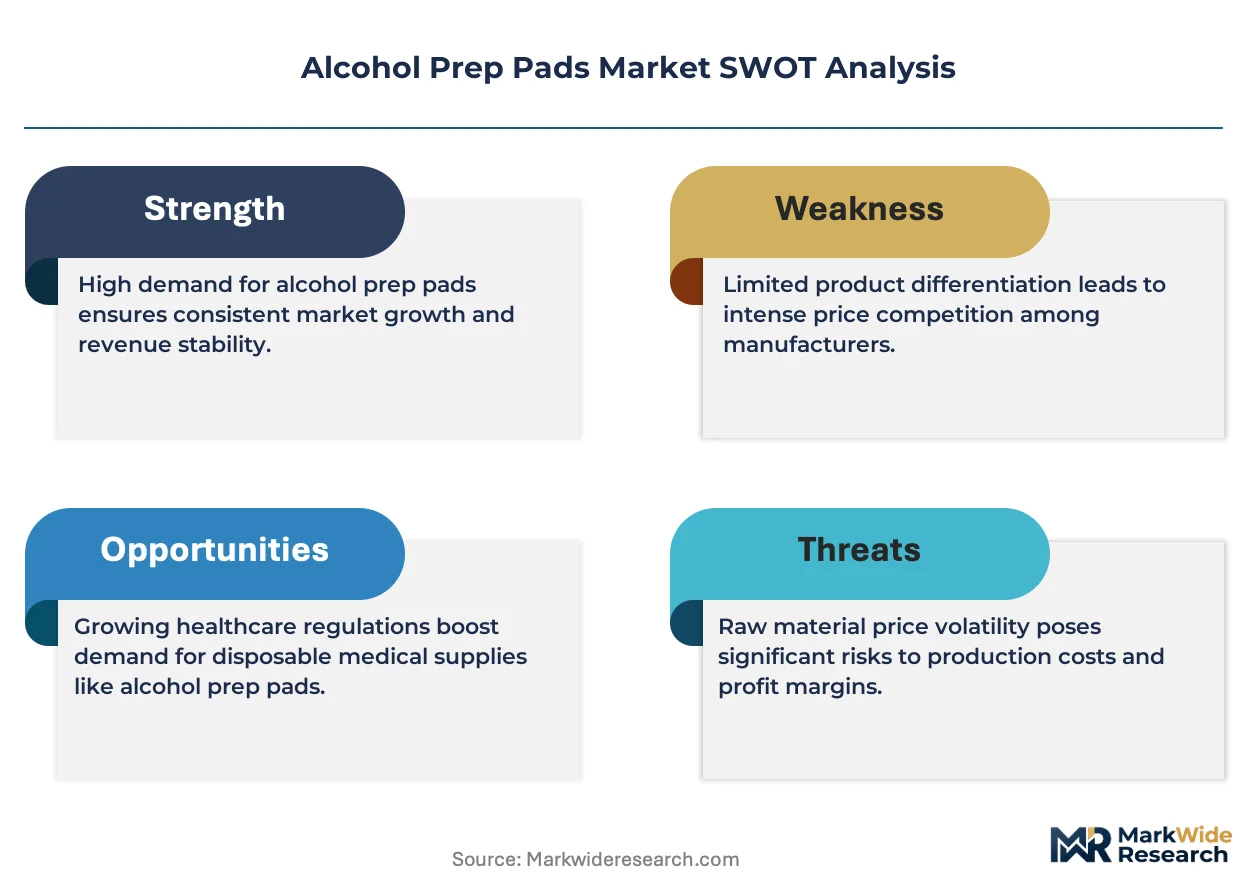
Hospital procurement consolidation and FDA monograph revision pressure are compressing supplier margins while rewarding manufacturers with captive sterilization infrastructure and non-woven substrate control.
Growth Catalysts
- US FDA Monograph Revision:The agency's updated over-the-counter antiseptic framework is compelling manufacturers to elevate isopropyl alcohol purity thresholds, accelerating facility upgrades among domestic converters.
- India PLI Scheme:Production-linked incentives for medical textiles are scaling domestic non-woven capacity in Gujarat and Maharashtra, reducing import dependency for hospital tenders.
- Outpatient Surgery Volume:Ambulatory surgical centers in the United States are expanding single-use antiseptic protocols, driving sachet-format demand for portable preoperative skin preparation.
Market Restraints
- Isopropyl Alcohol Feedstock Volatility:Propylene pricing swings and energy cost spikes at Gulf Coast refineries are compressing margin pools for pad converters without long-term supply contracts.
- Spunlace Non-Woven Concentration:Three Southeast Asian substrate suppliers control 60% of global thermal-bonded fabric output, creating geographic chokepoints for European and North American pad manufacturers.
- Cotton Lint Substitution Ceiling:Natural fiber alternatives exceed 50 particles per square centimeter shedding thresholds, blocking entry into clean-field surgical applications despite sustainability premiums.
Strategic Opportunities
- Brazil ANVISA Tender Modernization:The regulator's 2023 hospital supply catalog digitization is opening direct procurement channels for imported sterile pad formats previously blocked by distributor intermediaries.
- Home Infusion Therapy Expansion:Self-administered biologic injection protocols are creating demand for premium individual sachets with extended moisture retention beyond institutional bulk packaging.
- EU MDR Sterility Assurance Harmonization:The Medical Device Regulation's consolidated sterilization validation requirements are favoring pad converters with in-house gamma or ethylene oxide capability against outsource-dependent competitors.
Industry Challenges
- Gamma Sterilization Capacity Bottlenecks:Cobalt-60 source shortages and facility queue times are extending lead times for sterile pad SKUs, forcing converters to prioritize high-margin hospital contracts over retail channels.
- FDA 510(k) Recertification Burden:The 2017 proposed healthcare antiseptic rule's pending finalization is freezing R&D roadmaps as manufacturers delay formulation investments until compliance thresholds clarify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Prep Pads Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Multi-use, Premoistened, Bulk Material: Non-woven Fabric, Cotton, Vinyl, Plastic End User: Hospitals, Clinics, Pharmacies, Home Care Packaging Type: Box, Pouch, Sachet, Dispenser |
| Companies Covered | 3M Company, Cardinal Health Inc., Becton, Dickinson and Company, Medline Industries LP, McKesson Corporation, Thermo Fisher Scientific Inc., B. Braun SE, Dynarex Corporation, GOJO Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Prep Pads Market Emerging Trajectories
Material science advances and procurement digitization are reshaping competitive positioning, with substrate engineering and regulatory automation emerging as primary differentiation vectors.
Electrospun nanofiber non-woven substrates with sub-micron fiber diameters are achieving 40% higher isopropyl alcohol retention than conventional spunlace materials. Academic medical centers in Germany and the United States are piloting these formats for extended-duration surgical preparation. The technology is rendering obsolete thermal-bonded pads in procedures exceeding 30-minute skin contact windows.
REACH microplastic restrictions are compelling European manufacturers to reformulate wet wipes with biodegradable cellulose alternatives ahead of 2027 enforcement deadlines. Pad converters with integrated pulp processing capabilities are securing preferential shelf space in French and German hospital tenders. Sterile format suppliers without cellulose substrate access are facing forced portfolio rationalization or acquisition dependency.
Hospital buying consortiums are consolidating annual antiseptic contracts under outcome-based compliance metrics rather than unit-cost bidding. Integrated delivery networks in Texas and California are penalizing suppliers for stockout incidents or lot-traceability failures. This behavior concentrates procurement authority among distributors with real-time inventory visibility systems and multi-site logistics networks.
Alcohol Prep Pads Market Segmentation
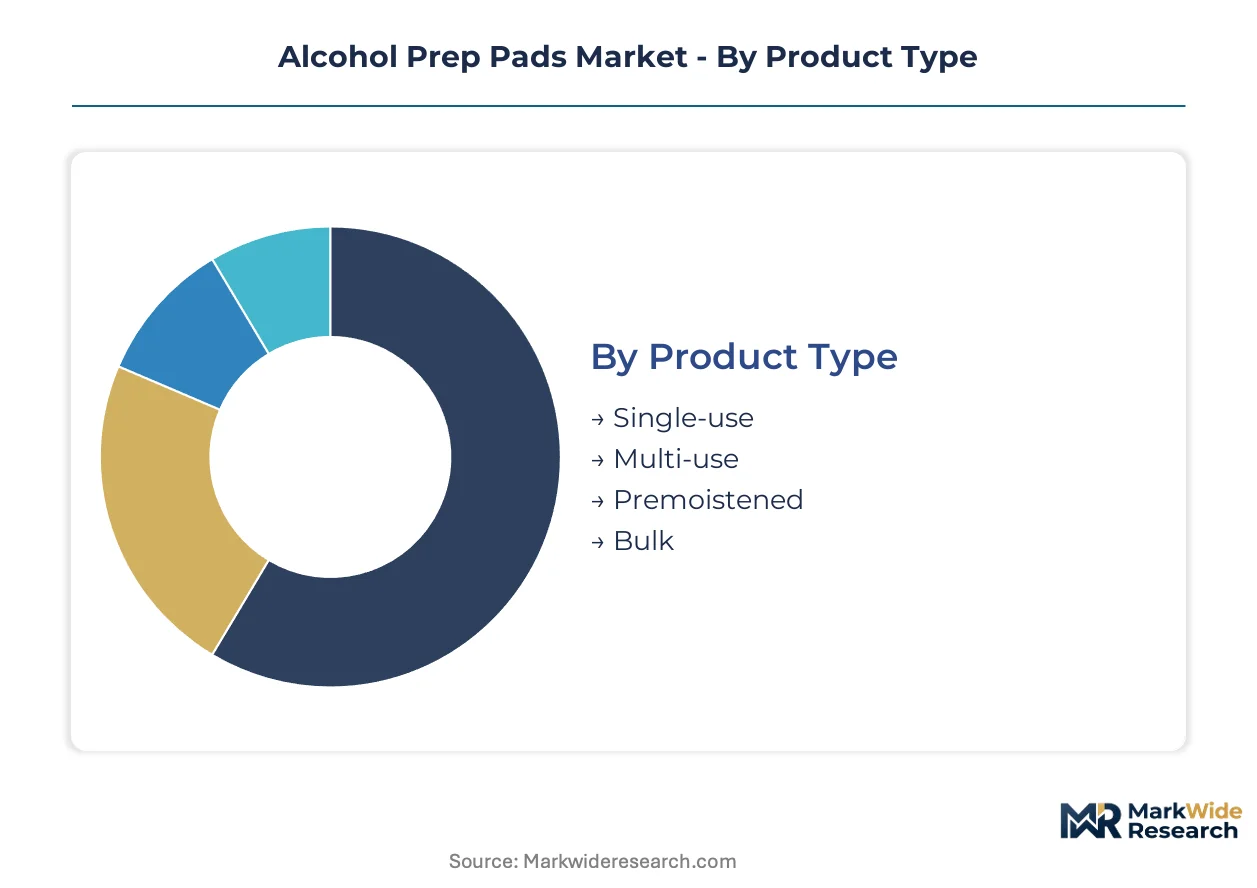
Segmentation in alcohol prep pads reveals how infection control protocols, substrate engineering, and procurement channels fragment demand across distinct performance tiers. Manufacturers align production lines to specific segment requirements rather than pursuing universal formats.
Product Type:
After-sales service intensity varies sharply across product types, with sterile single-use formats demanding lot-traceability systems and recall-response capabilities that bulk non-sterile alternatives do not require.
- Single-use:Individually packaged sterile pads saturated with 70% isopropyl alcohol, sealed in tear-open foil or paper-plastic laminate. Hospital surgical suites in the United States and Germany drive volume as joint commission protocols mandate one-pad-one-patient disposal to eliminate cross-contamination risk.
- Premoistened:Extended-moisture sachets employing vapor-barrier films to prevent alcohol evaporation over 24-month shelf lives. Home infusion therapy patients in India's tier-one cities favor these for self-administered biologic injections where pharmacy refill intervals stretch to 90 days.
- Multi-use:Canister or tub formats containing 100-200 pads for high-frequency clinical environments. Dermatology clinics and dialysis centers accept marginal sterility trade-offs for cost efficiency.
- Bulk:Unpackaged pad stacks for automated packaging lines or institutional repackaging. Contract manufacturers serving private-label retail brands absorb this segment.
By volume, Single-use leads. By growth pace, Premoistened is ahead.
Material:
Cost tier stratification in substrate selection determines which manufacturers can serve clean-field surgical applications versus commodity outpatient markets.
- Non-woven Fabric:Spunlace or thermal-bonded synthetic substrates engineered below 50 particles per square centimeter lint shedding. Cardinal Health and BD source captive non-woven mills to secure supply continuity for FDA-regulated sterile pad production.
- Cotton:Natural fiber pads exceeding lint thresholds for surgical use but acceptable in veterinary and consumer first-aid applications. Sustainability premiums in European retail channels partially offset performance limitations.
- Vinyl:Synthetic backing layers in two-pad constructions for enhanced moisture barrier properties. Limited to specialized dental and ophthalmic preparation kits.
- Plastic:Rigid dispenser components and overwrap films rather than active wiping surfaces. Polypropylene supply contracts with Gulf Coast refineries influence converter margin structures.
Non-woven Fabric commands the revenue pool. Cotton faces steepest share erosion as REACH microplastic restrictions reshape European procurement.
End User:
Customer type concentration shapes pricing power, with integrated delivery networks extracting compliance concessions that fragmented home care channels cannot demand.
- Hospitals:Acute-care systems purchasing through group purchasing organizations with outcome-based contract terms. Texas and California IDNs penalize suppliers for stockout incidents, concentrating procurement among distributors with multi-site logistics networks.
- Clinics:Outpatient facilities including ambulatory surgical centers expanding single-use antiseptic protocols. Sachet-format demand climbs as procedure volumes shift from inpatient settings.
- Pharmacies:Retail and institutional dispensers serving prescription injection patients. Brazil's ANVISA tender digitization is opening direct procurement channels for imported sterile formats.
- Home Care:Self-administered therapy patients requiring extended-shelf-life individual packaging. Moisture retention beyond institutional bulk formats commands 40-60% price premiums.
Hospitals dominate absolute consumption. Home Care climbs fastest as biologic self-injection protocols proliferate.
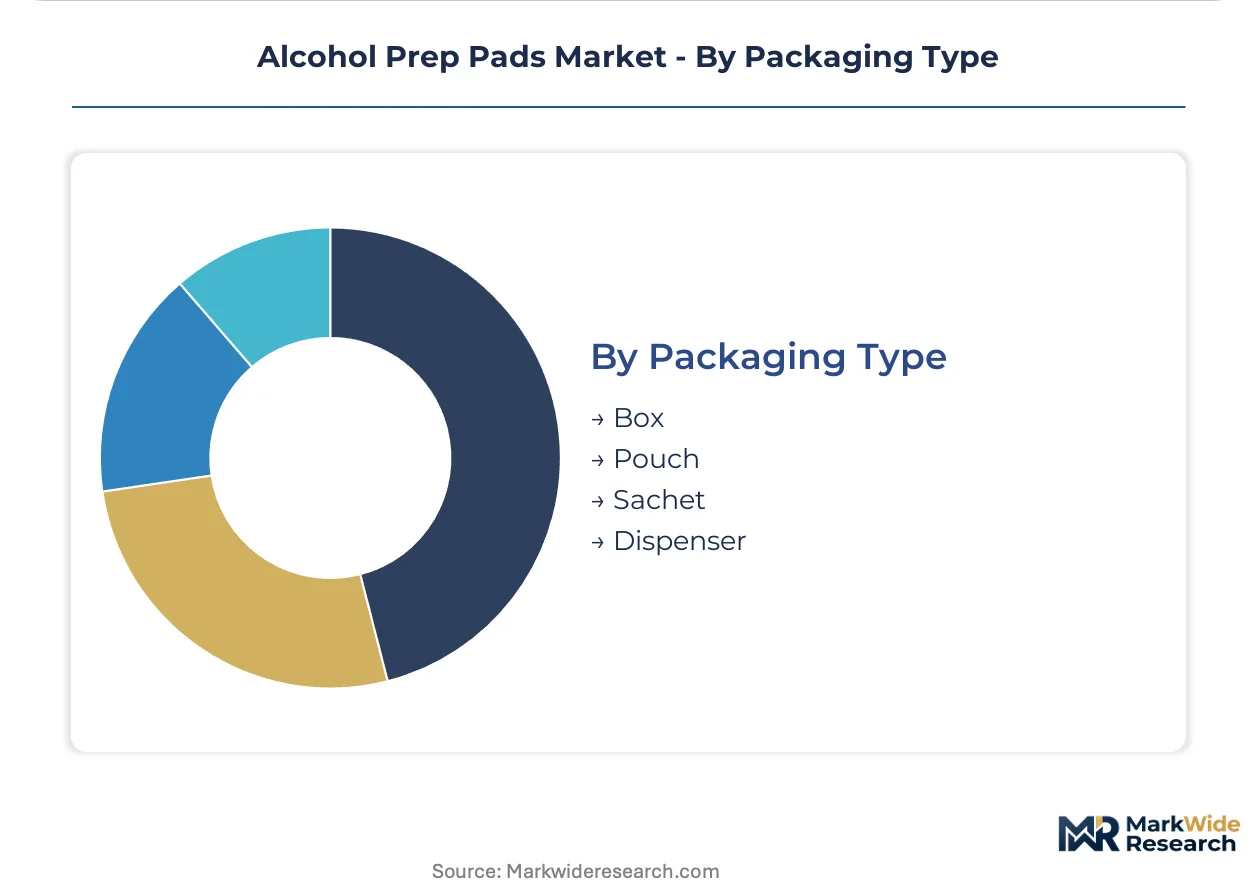
Packaging Type:
Supply concentration in flexible film converting creates geographic chokepoints that favor pad manufacturers with captive packaging capabilities.
- Sachet:Individual foil or metallized film pouches for maximum portability and shelf stability. German and US academic medical centers pilot nanofiber substrates in sachet formats for extended-duration surgical preparation.
- Box:Rigid paperboard containers holding 100-200 pads for countertop dispensing. Standard in US hospital central supply and retail pharmacy channels.
- Pouch:Flexible multi-pad bags for institutional bulk purchasing. Cost-sensitive clinics in India's tier-two cities favor pouch formats under PLI-scheme domestic production.
- Dispenser:Wall-mounted or countertop canister systems with one-at-a-time delivery mechanisms. Infection control benefits in high-traffic emergency departments justify hardware investment.
Box formats lead by unit volume. Sachet packaging gains share fastest on home care and ambulatory surgery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites North American isopropyl alcohol feedstock security for pad converters serving hospital networks across the southern United States. This infrastructure anchors a regional supply chain that extends through Gulf Coast refineries to non-woven fabric mills in the southeastern states.
United States
Ambulatory surgical centers in Texas and California are expanding single-use antiseptic protocols as procedure volumes shift from inpatient settings. The FDA's ongoing healthcare antiseptic monograph revision is compelling domestic manufacturers to elevate isopropyl alcohol purity thresholds ahead of anticipated finalization. Cardinal Health leverages its integrated distribution network to sustain shelf-space dominance across acute-care systems in the Midwest and Southeast.
Germany
Academic medical centers in Bavaria and Baden-Württemberg are piloting electrospun nanofiber substrates for extended-duration surgical preparation exceeding 30-minute skin contact windows. REACH microplastic restrictions are compelling manufacturers to reformulate wet wipes with biodegradable cellulose alternatives ahead of 2027 enforcement deadlines. The Eindhoven-Randstad corridor supplies thermal-bonded non-woven substrates to German pad converters seeking supply continuity.
India
Outpatient volumes in Mumbai, Delhi-NCR, and Bangalore are surging as domestic production scales under the PLI scheme for medical textiles. CDSCO enforces isopropyl alcohol concentration disclosure on imported and domestic prep pad packaging, shaping how regional manufacturers formulate products for hospital tenders. Gujarat and Maharashtra are scaling non-woven capacity to reduce import dependency for institutional procurement.
Brazil
ANVISA's 2023 hospital supply catalog digitization is opening direct procurement channels for imported sterile pad formats previously blocked by distributor intermediaries. São Paulo and Rio de Janeiro health systems are consolidating annual antiseptic contracts under outcome-based compliance metrics. The regulatory modernization is favoring pad converters with real-time inventory visibility systems over traditional import-reliant distributors.
China
Yangtze River Delta medical device clusters are expanding gamma sterilization capacity to address cobalt-60 source shortages affecting global lead times. NMPA oversight of antiseptic efficacy labeling is aligning domestic manufacturers with international purity standards for export-oriented production. Shanghai-based converters are securing long-term propylene supply contracts with Sinopec refineries to hedge feedstock volatility.
Alcohol Prep Pads Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with captive non-woven fabric mills and in-house sterilization infrastructure. Hospital group purchasing organization contracts are tilting toward suppliers with integrated distribution networks that reduce lead times for institutional buyers. Three strategic archetypes dominate: diversified healthcare conglomerates with medical supply divisions, specialized antiseptic product manufacturers, and private-label contract converters serving retail channels. Competitive intensity centers on backward integration into substrate production and geographic expansion into emerging hospital procurement markets.
Among diversified healthcare suppliers, Cardinal Health Inc., Becton, Dickinson and Company, and Medline Industries LP exemplify distinct positioning archetypes. Cardinal Health occupies a position anchored by distribution scale across acute-care networks. Becton, Dickinson and Company represents R&D-intensive positioning in aseptic delivery formats. Medline Industries LP sits within the manufacturing-scale tier, operating multiple US-based conversion lines that reduce procurement friction for institutional buyers.
| Leading Market Players |
|---|
| 3M Company |
| Cardinal Health Inc. |
| Becton, Dickinson and Company |
| Medline Industries LP |
| McKesson Corporation |
| Thermo Fisher Scientific Inc. |
| B. Braun SE |
| Dynarex Corporation |
| GOJO Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta non-woven substrate mills is compressing spot pricing for thermal-bonded fabrics while simultaneously pressuring European and North American converters to absorb margin erosion or accelerate backward integration into captive production.
Pricing Analysis
Three-tier pricing structure across sterile premium, standard institutional, and economy retail levels dominates contract negotiations. Price differentiation rests on FDA 510(k) certification status and gamma sterilization validation, with hospital GPOs extracting steepest discounts on multi-year volume commitments. Cost compression in the standard tier is intensifying because propylene feedstock volatility at Gulf Coast refineries squeezes converters lacking long-term supply agreements. Retail pharmacy channels exhibit highest price sensitivity, while home infusion therapy patients accept 40-60% premiums for extended-moisture sachet formats.
Supply Chain Analysis
Tariff exposure between Southeast Asian substrate suppliers and European pad converters dominates risk matrices for sterile format manufacturers. Geographic supply concentrates in China, Vietnam, and Thailand for spunlace non-woven output, while isopropyl alcohol feedstock draws from Gulf Coast and Middle Eastern petrochemical complexes. Single-source vulnerability in cobalt-60 gamma sterilization facilities is extending lead times for sterile SKUs. Distribution runs through integrated healthcare distributors with multi-site logistics networks serving hospital IDNs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against chlorhexidine gluconate wipes gaining traction in extended-duration surgical preparation protocols, requiring rapid response in substrate innovation and clinical validation investment.
For Market Incumbents: Pre-empt chlorhexidine displacement by accelerating electrospun nanofiber substrate commercialization for procedures exceeding 30-minute skin contact windows. Secure captive gamma sterilization capacity through facility acquisition or long-term queue contracts to defend sterile SKU margins against outsource-dependent competitors. Prioritize backward integration into non-woven fabric production to hedge Southeast Asian supply concentration. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-digitized hospital tender channels where regulatory modernization has disintermediated traditional import distributors. Target India's tier-two city clinics scaling under PLI-scheme domestic production with pouch-format bulk positioning against premium sachet incumbents. Lead with real-time inventory visibility systems to satisfy outcome-based contract metrics from São Paulo and Rio de Janeiro health systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pad converters with integrated sterilization infrastructure and multi-year GPO contracts anchoring hospital system relationships. Long-term viability favors manufacturers with cellulose substrate capabilities ahead of REACH microplastic enforcement. Monitor FDA finalization of the 2017 healthcare antiseptic rule as the critical inflection signal for reformulation investment cycles and recertification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Non-Woven Mill Acquisition | Backward integration into substrate production secures supply continuity for FDA-regulated sterile pad output. |
| Gamma Sterilization Facility Investment | In-house cobalt-60 capacity eliminates queue-time bottlenecks and prioritizes high-margin hospital contracts. |
| Electrospun Nanofiber R&D Partnership | Academic medical center pilots in Germany and the United States validate extended-duration surgical preparation performance. |
| Cellulose Substrate Reformulation | Biodegradable alternatives secure preferential shelf space ahead of REACH microplastic enforcement deadlines. |
| Real-Time Inventory System Deployment | Multi-site logistics visibility satisfies outcome-based compliance metrics from Texas and California IDNs. |
Methodological Framework
Operator-level perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and non-woven substrate plant managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EPA antimicrobial claim registrations, CDSCO packaging disclosure records, and customs trade data for isopropyl alcohol and propylene derivatives. Bottom-up volume modeling across sterile and non-sterile product tiers triangulated against top-down market sizing from hospital expenditure databases and medical device production statistics.
Scenario-bracketing across feedstock volatility bands, regulatory finalization timelines, and sterilization capacity constraints bounded the projection horizon. Segmentation dimensions modeled include product type, substrate material, end-user channel, packaging format, and regional regulatory cluster. CAGRs derived from trend extrapolation of surgical volume growth, outpatient procedure migration, and biologic self-injection protocol adoption. Industry-specific forecast inputs incorporated propylene pricing cycles, gamma facility queue times, and PLI scheme capacity buildout trajectories.
Stress conditions across cobalt-60 source availability, FDA monograph purity thresholds, and REACH enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory finalization, feedstock shocks, or substrate technology disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Ostomy Care Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Safety Needles Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Global Adhesive Bandages Market