
 Global Disposable Blood Bags Market | 2026-2036
Global Disposable Blood Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Blood Bags Market Foresight
Asian polymer converters is consolidating medical-grade PVC compounding capacity for blood-contact films. Terumo Corporation leverages captive resin partnerships to secure supply continuity for high-volume bag production. Fresenius Kabi anchors European demand through integrated plasma fractionation networks. Haemonetics Corporation specializes in automated collection systems that bundle proprietary disposable sets.
Disposable blood bags are sterile, single-use containers manufactured from plasticized polyvinyl chloride or alternative polymers, designed to collect, store, transport, and transfuse human blood and blood components while maintaining cell viability and preventing coagulation. Leukocyte reduction bags command premium positioning due to filtration membrane complexity and downstream transfusion safety benefits. Triple and quadruple bag configurations dominate blood processing workflows as they enable component separation during initial collection. Blood banks represent the most concentrated end-user channel, with procurement decisions driven by national tender frameworks and cold-chain compatibility requirements.
FDA blood bag biocompatibility standards, EU MDR Class IIa device classification, and ISO 3826 specifications govern material extractables, sterilization validation, and shelf-life labeling across major supply jurisdictions. These frameworks elevate barriers for new entrants lacking established regulatory dossiers and audited manufacturing sites. Stakeholders must monitor polymer substitution trends as diethylhexyl phthalate-free formulations gain preference in European and North American procurement specifications.
Market Dynamics
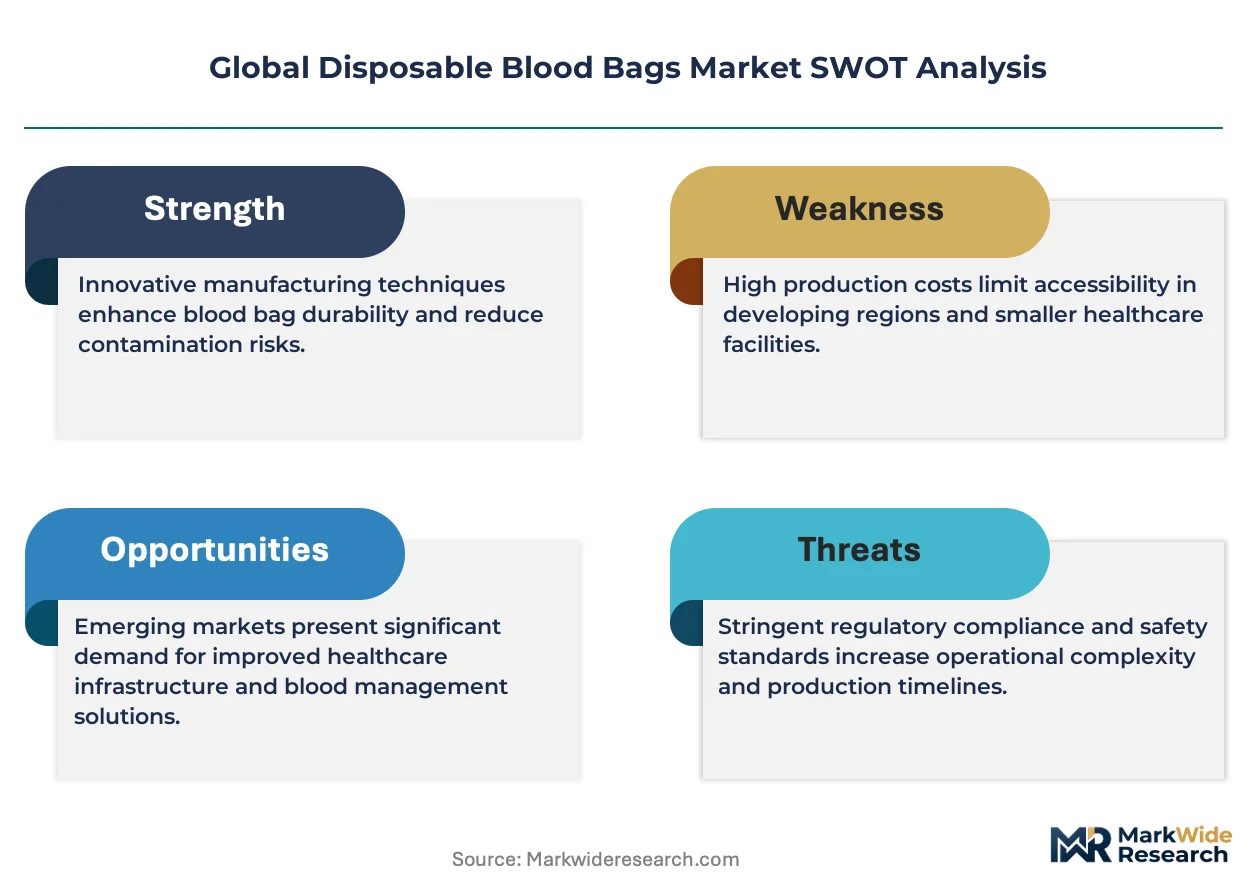
Polymer substitution pressure is restructuring the disposable blood bags market as diethylhexyl phthalate-free formulations displace conventional plasticized PVC in procurement specifications across European and North American hospital systems.
Growth Catalysts
- EU MDR sterilization mandates:The EU Medical Device Regulation's tightened traceability requirements for single-use blood contact devices is accelerating hospital system upgrades to compliant bag inventories.
- India's cold-chain modernization:Government-funded blood donation drives and improved refrigerated logistics infrastructure are expanding collection network capacity in tier-2 and tier-3 cities.
- Leukocyte reduction filtration:Advanced membrane complexity in specialized bags commands premium positioning as transfusion safety protocols harden in tertiary care facilities.
Market Restraints
- Medical-grade PVC compounding concentration:Asian polymer converters control the majority of blood-contact film resin supply, creating geographic single-source vulnerability for Western manufacturers.
- DEHP substitution cost inflation:Alternative plasticizers and polymer formulations carry 15-30% raw material cost premiums versus conventional phthalate-based compounds.
- ISO 3826 certification timelines:Extended sterilization validation and shelf-life documentation requirements delay new product market entry by 18-24 months.
Strategic Opportunities
- Automated collection system bundling:Proprietary disposable set integration with apheresis platforms creates recurring revenue streams and technical switching costs for blood processing centers.
- Southeast Asia infrastructure expansion:Hospital blood banks in Vietnam, Thailand, and Indonesia are building collection capacity without legacy equipment replacement burdens.
- Triple-quadruple bag workflow dominance:Component separation capability during initial collection positions multi-chamber configurations for standard-of-care adoption in emerging markets.
Industry Challenges
- Polymer formulation expertise scarcity:Blood-contact biocompatibility engineering and extractables testing capability concentrates among a limited pool of compounders with FDA master file experience.
- Legacy sterilization asset stranding:Ethylene oxide and gamma irradiation facility investments face utilization pressure as electron beam and X-ray alternatives gain regulatory preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Blood Bags Market |
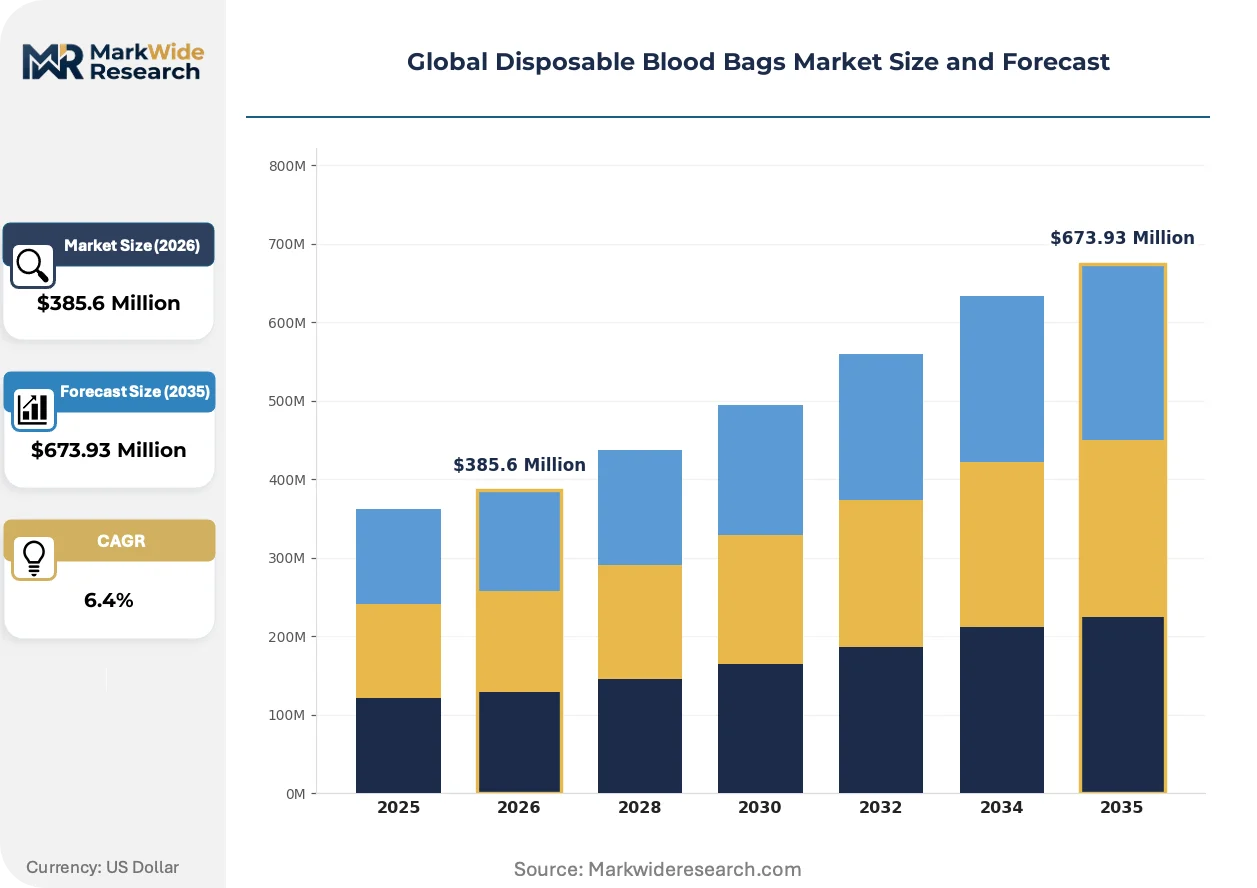
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blood Bags, Leukocyte Reduction Bags, Pediatric Bags, Triple Bags, Quadruple Bags Material: Polyvinyl Chloride, Polyethylene, Silicone, Thermoplastic Elastomers, Polypropylene Application: Blood Collection, Blood Storage, Plasma Collection, Platelet Collection, Stem Cell Harvesting End User: Blood Banks, Research Institutions, Diagnostic Laboratories, Medical Clinics, Surgical Centers |
| Companies Covered | Terumo Corporation, Fresenius Kabi, Haemonetics Corporation, Grifols, S.A., Macopharma, Poly Medicure Limited, HLL Lifecare Limited, Neomedic International, TERUMO PENPOL Pvt. Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Blood Bags Market Shifts & Advancements
Material science advancement and regulatory chemistry restrictions are converging to accelerate polymer platform transitions, while procurement centralization and integrated collection technology reshape competitive positioning in blood component handling.
Diethylhexyl phthalate-free PVC and alternative polyolefin formulations are overtaking conventional plasticized blood bag materials in European and North American tender specifications. Hospital procurement committees in Germany, France, and the United Kingdom now mandate DEHP-free labeling for neonatal and pediatric transfusion products. This chemistry transition is compressing margins for compounders without validated alternative formulations while rewarding early movers with multi-year supply agreements.
The EU MDR Class IIa device classification and associated technical documentation requirements are forcing blood bag manufacturers to rebuild regulatory dossiers for entire product portfolios. Sterilization validation protocols now demand extractables testing under multiple storage temperature conditions. French and Italian notified bodies are processing submissions at reduced throughput, delaying product recertification timelines and constraining available supplier pools for national health service tenders.
Integrated apheresis platform procurement is consolidating buyer power among large-scale blood collection operators. Automated collection systems that bundle proprietary disposable sets are displacing standalone bag purchases in American Red Cross and European plasma fractionation networks. This equipment-locked consumption model is most visible in the United States and Germany, where high-volume collection centers prioritize workflow automation over component commodity sourcing.
Global Disposable Blood Bags Market Segmentation
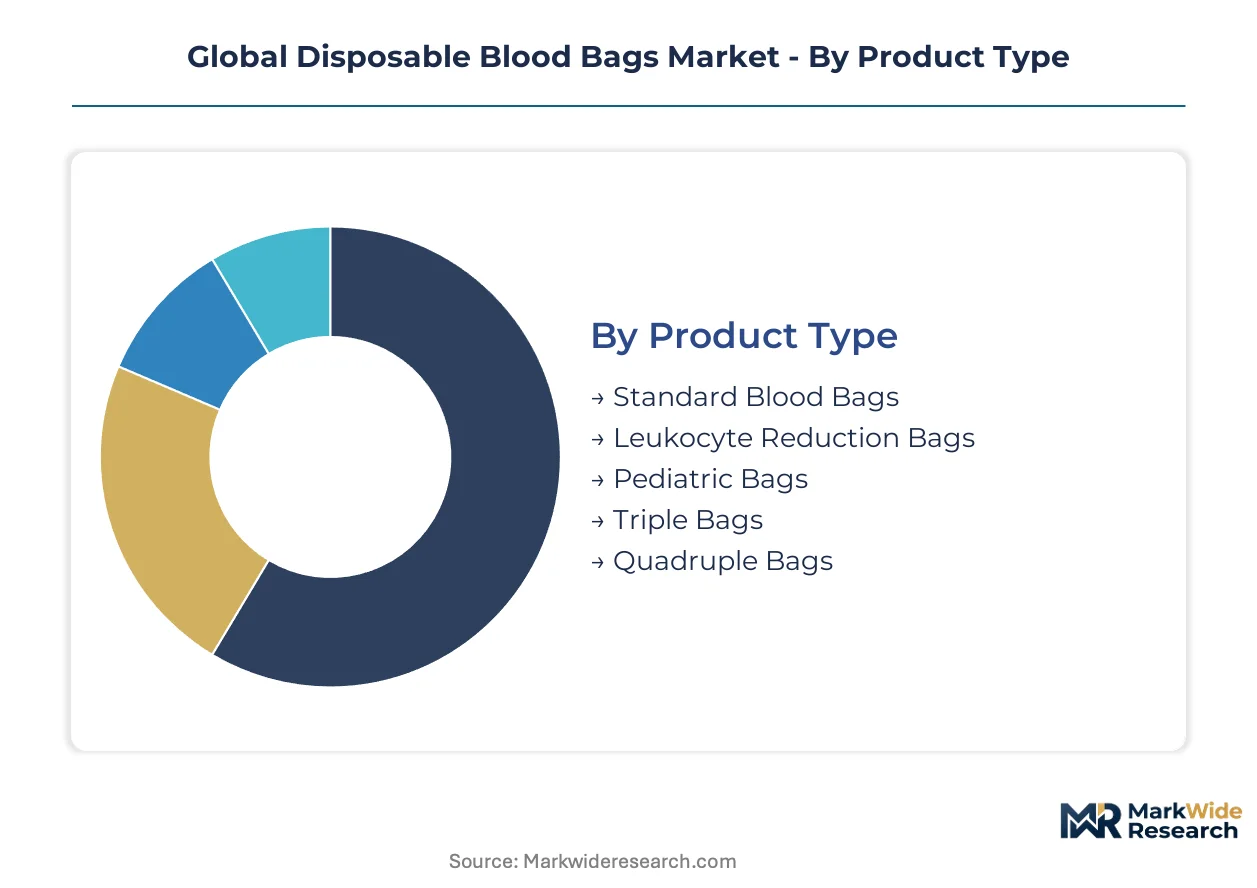
Product configurations and material chemistry drive distinct procurement patterns across blood processing workflows. Component separation capabilities and biocompatibility specifications create tiered demand structures that reward specialized manufacturing competencies.
Product Type:
Volume concentrates in multi-chamber systems while premium positioning accrues to specialized filtration configurations.
- Standard Blood Bags:Single-chamber PVC containers serve baseline whole blood collection without component separation capability. Demand concentrates in India's government-funded donation drives where cost minimization dominates tender specifications and cold-chain infrastructure remains limited.
- Leukocyte Reduction Bags:Integrated filtration membranes remove white blood cells during collection to prevent transfusion-associated complications. Tertiary care facilities in Germany and France command premium positioning as transfusion safety protocols harden and neonatal-pediatric specifications mandate DEHP-free compatibility.
- Pediatric Bags:Reduced volume configurations with precise anticoagulant dosing for low-body-weight recipients.
- Triple Bags:Three-chamber systems enable concurrent separation of red cells, plasma, and platelets during initial collection.
- Quadruple Bags:Four-chamber configurations add buffy coat isolation for extended component processing flexibility.
Today's leader: Triple Bags. Tomorrow's challenger: Leukocyte Reduction Bags.
Material:
Regulatory chemistry restrictions are restructuring procurement specifications toward alternative plasticizers and polymer platforms.
- Polyvinyl Chloride:Conventional plasticized formulations face substitution pressure as EU MDR and FDA biocompatibility standards tighten extractables limits. Blood banks in the United Kingdom and Netherlands now mandate DEHP-free labeling for pediatric applications, compressing margins for legacy compounders.
- Polyethylene:Alternative polyolefin platforms eliminate phthalate plasticizers entirely while maintaining oxygen permeability requirements for platelet storage. North American hospital systems are expanding procurement specifications to include polyethylene options as sterilization validation protocols mature.
- Silicone:High-purity elastomer formulations serve specialized apheresis and stem cell harvesting applications requiring extended biocompatibility profiles.
- Thermoplastic Elastomers:Block copolymer structures combine processing advantages of thermoplastics with rubber-like flexibility for tubing integration.
- Polypropylene:Rigid polymer segments provide structural stability for connector manifolds and transfer ports in multi-chamber configurations.
Polyvinyl Chloride retains installed base dominance. Polyethylene captures specification momentum fastest.
Application:
Workflow automation is bundling collection and processing functions, reducing standalone bag procurement for discrete storage applications.
- Blood Collection:Initial venipuncture and anticoagulant mixing represents the highest-volume consumption node across all geographies. Automated collection systems from Haemonetics and Fresenius Kabi are displacing manual collection workflows in American Red Cross and European plasma fractionation networks.
- Plasma Collection:Apheresis-based extraction demands specialized bag sets with extended storage stability and protein preservation characteristics. German and Austrian plasma fractionation centers drive premium specification requirements as source plasma volumes expand for immunoglobulin manufacturing.
- Blood Storage:Post-collection refrigeration compatibility and shelf-life labeling govern secondary procurement decisions.
- Platelet Collection:Agitation-resistant configurations with controlled oxygen permeability support five-day storage protocols.
- Stem Cell Harvesting:Cryopreservation-compatible materials and minimal extractables profiles serve cellular therapy manufacturing requirements.
Blood Collection maintains volume supremacy. Plasma Collection shows steepest expansion trajectory.
End User:
Procurement centralization concentrates buyer power among national blood service operators while fragmenting demand across research and diagnostic channels.
- Blood Banks:National tender frameworks and cold-chain compatibility requirements dominate purchasing decisions for high-volume whole blood processing. India's National AIDS Control Organization and Germany's DRK-Blutspendedienst represent concentrated demand nodes with multi-year supply agreements.
- Research Institutions:Cell therapy development and transfusion medicine studies require small-batch, high-traceability configurations with extended documentation packages. Academic medical centers in Boston and Heidelberg drive specification innovation for next-generation bag designs.
- Diagnostic Laboratories:Quality control and reference standard applications consume limited volumes with precise certification requirements.
- Medical Clinics:Peripheral transfusion sites prioritize inventory minimization and standardized compatibility with regional blood bank supply chains.
- Surgical Centers:Intraoperative autotransfusion and emergency transfusion protocols demand rapid-availability configurations with universal connector standards.
Blood Banks command procurement leverage today. Research Institutions shape tomorrow's specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and India present contrasting procurement dynamics, with German hospital systems enforcing DEHP-free mandates while Indian government tenders prioritize volume-scale collection infrastructure.
United States
FDA biocompatibility standards and American Red Cross procurement centralization drive specification rigor. Automated collection system bundling displaces standalone bag purchases across high-volume plasma fractionation networks. Boston and Philadelphia academic medical centers pilot next-generation leukocyte reduction configurations for tertiary care protocols.
Germany
DRK-Blutspendedienst national tender frameworks concentrate buyer power among integrated blood service operators. EU MDR Class IIa recertification timelines constrain supplier pools as French and Italian notified bodies process submissions at reduced throughput. Bavarian and Baden-Württemberg hospital networks mandate DEHP-free labeling for pediatric transfusion products.
India
National AIDS Control Organization-funded donation drives expand collection capacity into tier-2 and tier-3 cities. CDSCO medical device registration requirements and improving cold-chain logistics enable geographic network penetration. Maharashtra and Gujarat polymer converters consolidate medical-grade PVC compounding capacity for domestic bag manufacturers.
France
ANSM sterilization validation protocols demand extractables testing under multiple storage temperature conditions. Etablissement Français du Sang procurement centralization rewards suppliers with established regulatory dossiers. Lyon and Paris hospital clusters drive premium positioning for leukocyte reduction bags as transfusion safety protocols harden.
Japan
PMDA master file requirements elevate barriers for compounders lacking blood-contact biocompatibility engineering capability. METI industrial policy supports domestic resin partnerships to secure supply continuity. Osaka and Tokyo metropolitan hospital systems prioritize cold-chain compatibility for platelet storage protocols.
Global Disposable Blood Bags Market Competitive Landscape
Japanese producers anchor one tier; European specialists hold integrated fractionation networks; Asian compounders control resin supply continuity. Market structure concentrates among vertically integrated device manufacturers with captive polymer partnerships and audited regulatory dossiers. Strategic archetypes include automated collection platform bundlers, multi-chamber configuration specialists, and DEHP-free formulation early movers. Dominant competitive moves encompass backward integration into medical-grade resin compounding and strategic partnerships with national blood service operators.
Within the integrated device-fractionation tier, Terumo Corporation and Fresenius Kabi exemplify platform bundling strategies that lock recurring disposable consumption. Haemonetics Corporation occupies a position among automated collection specialists, anchoring proprietary disposable set integration with apheresis workflows. These three entities represent distinct archetypes: resin-secured Japanese manufacturing, European plasma network integration, and American automation-platform bundling.
| Leading Market Players |
|---|
| Terumo Corporation |
| Fresenius Kabi |
| Haemonetics Corporation |
| Grifols, S.A. |
| Macopharma |
| Poly Medicure Limited |
| HLL Lifecare Limited |
| Neomedic International |
| TERUMO PENPOL Pvt. Limited |
| Others |
Supply & Pricing Matrix
EU MDR sterilization mandates gate qualified supply for premium-tier pricing access, as notified bodies in France and Italy process submissions at reduced throughput. This regulatory bottleneck rewards compounders with validated DEHP-free dossiers while compressing margins for legacy PVC manufacturers lacking alternative formulations.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for standard blood bag configurations in Indian government tenders. Three-tier pricing structure across premium, standard, and economy levels separates leukocyte reduction bags with DEHP-free certification from conventional PVC units. Price differentiation rests on ISO 3826 compliance grade and volume scale in national tender frameworks. Margins are tightening for Western manufacturers facing 15-30% raw material cost premiums on alternative plasticizers versus phthalate-based compounds. Blood banks in tier-2 Indian cities exhibit highest price sensitivity; German DRK-Blutspendedienst tenders show lowest sensitivity due to technical specification rigor.
Supply Chain Analysis
Refrigerated logistics costs concentrate supply chain decisions around cold-chain hub proximity in India, Vietnam, and Indonesia. Medical-grade PVC resin draws from Asian polymer converters in Maharashtra and Gujarat, while DEHP-free alternative formulations hinge on European and North American compounders with FDA master file experience. Single-source vulnerability runs through gamma irradiation and ethylene oxide sterilization facility networks as electron beam alternatives gain regulatory preference. Distribution runs through national blood service operators with multi-year supply agreements rather than fragmented hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German DEHP-free mandate premiums and Indian volume-scale collection infrastructure, with regulatory compliance cost differentials exceeding raw material spreads.
For Market Incumbents: To counter polymer substitution pressure from polyethylene and alternative polyolefin platforms, Terumo Corporation and Fresenius Kabi should deepen captive resin partnerships in Osaka and Tokyo metropolitan clusters. Backward integration into medical-grade compounding secures supply continuity against Asian converter concentration. CE marking pathway acceleration through French and Italian notified bodies preserves tender eligibility for EU MDR Class IIa recertification.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities offer the most penetrable geography as National AIDS Control Organization funding expands cold-chain networks without legacy equipment replacement burdens. DEHP-free formulation specialization for pediatric and neonatal applications creates differentiation against incumbent PVC portfolios. Hospital system partnerships in Vietnam, Thailand, and Indonesia bypass automated collection platform bundling that dominates American and German markets.
For Investors and Strategic Acquirers: Roll-up economics work for regional blood bag specialists with established CDSCO or PMDA regulatory dossiers because certification timelines create 18-24 month barriers to organic entry. Platform consolidation targets compounders with FDA master file experience in blood-contact biocompatibility engineering. The signal to monitor is EU MDR notified body throughput recovery, which would decompress premium-tier supply constraints and revalue compliant manufacturing assets.
| Strategic Initiative | Industry Significance |
|---|---|
| DEHP-Free Formulation Scale-Up | European hospital procurement committees in Germany and France now mandate phthalate-free labeling for pediatric applications. |
| Automated Collection Platform Integration | Haemonetics and Fresenius Kabi bundle proprietary disposable sets that lock recurring revenue in American Red Cross networks. |
| Backward Integration into Resin Compounding | Terumo Corporation leverages captive partnerships with Japanese polymer suppliers to secure medical-grade PVC continuity. |
| Southeast Asia Distribution Partnership | Vietnam, Thailand, and Indonesia blood banks build collection capacity without legacy equipment replacement burdens. |
| ISO 3826 Certification Acceleration | Extended sterilization validation timelines delay new product entry, rewarding early movers with audited manufacturing sites. |
Research Methodology
Multiple input streams — primary interviews with blood bank procurement managers, biomedical engineers, and GPO contracts directors; secondary validation through FDA 510(k) filings, CDSCO medical device registrations, and hospital procurement databases; plus customs records on medical-grade resin trade flows — were reconciled through bottom-up and top-down triangulation. Clinicians at tertiary care facilities in Boston, Heidelberg, and Lyon provided workflow-level demand validation. EMA submission databases and EU MDR notified body disclosure records supplied regulatory timeline intelligence.
Data-stream reconciliation anchored volume and value outputs across product type, material chemistry, application workflow, and end-user procurement channel dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included blood donation drive frequency from National AIDS Control Organization disclosures, cold-chain logistics penetration metrics, and leukocyte reduction adoption rates in German and French hospital networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body throughput, DEHP substitution cost curves, and automated collection platform bundling intensity in plasma fractionation networks. Forecasts reflect assumptions about regulatory compliance timelines and polymer formulation availability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Global Adhesive Bandages Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Sterile IV Containers Market