
 Unit Dose Tubes Market | 2026-2036
Unit Dose Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Unit Dose Tubes Market Outlook
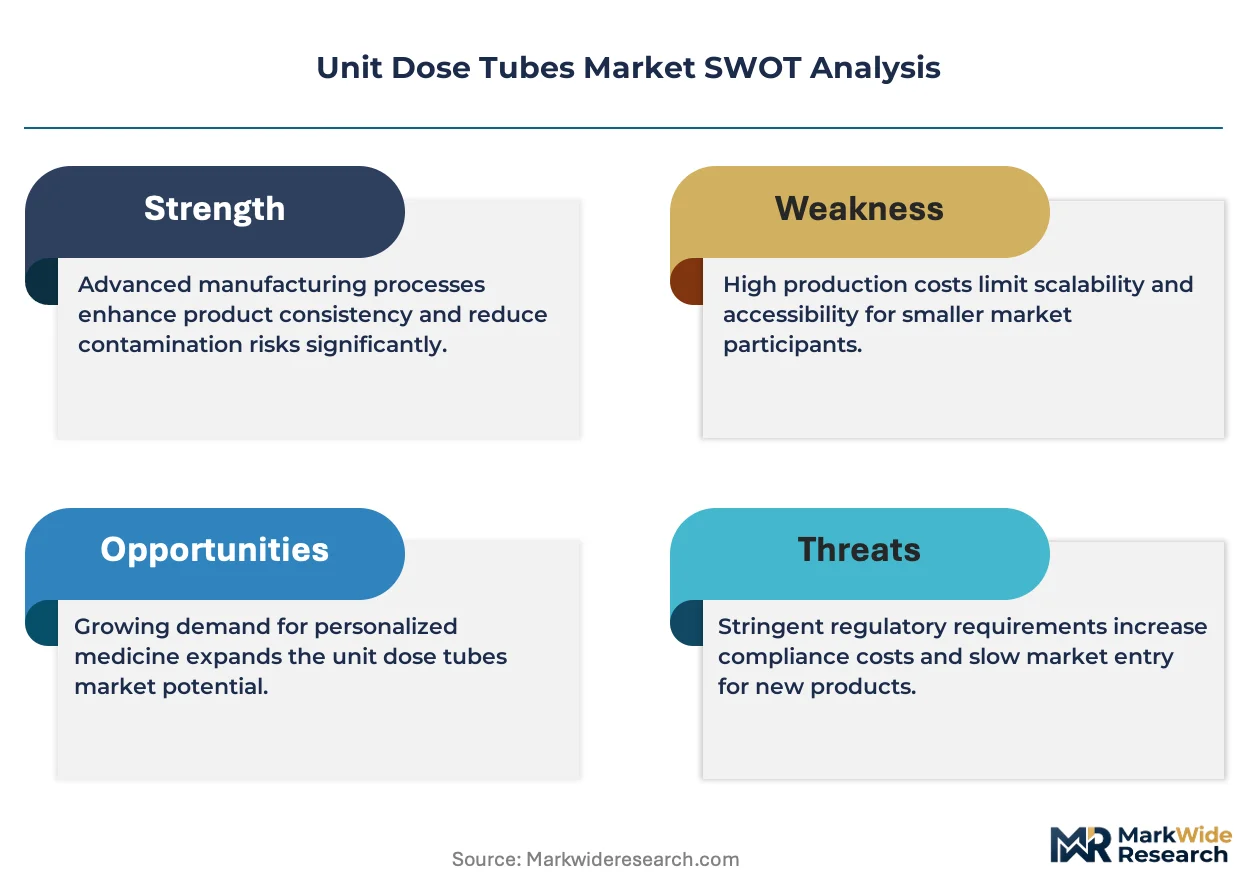
REACH compliance is shifting the cost-of-entry calculus for European suppliers of unit dose tubes, forcing reformulation of adhesives and barrier coatings. Amcor Limited leverages its vertically integrated film operations to sustain margin control across composite tube lines. Unicep Packaging anchors North American capacity through dedicated cleanroom manufacturing for pharmaceutical customers. AptarGroup, Inc. competes on precision-dispensing closure integration, while Berry Global, Inc. dominates high-volume plastic tube extrusion for over-the-counter applications.
Unit dose tubes are single-portion containers, typically 5 ml to 30 ml in fill volume, manufactured through extrusion blow molding, laminate welding, or aluminum impact extrusion to deliver pre-measured product doses with tamper-evident seals. Plastic tubes lead volume due to cost-efficient extrusion and decoration flexibility, though aluminum tubes retain share in pharmaceutical applications where oxygen and light barrier properties command premium positioning. Blister packs represent the fastest-growing packaging type as unit-dose oral solid formats expand into nutraceuticals and veterinary medicine, while seal packs maintain maturity in topical cream and ointment segments where peel-open convenience drives compliance.
The US FDA enforces child-resistant packaging standards under the Poison Prevention Packaging Act, while EMA's Annex 1 sterile manufacturing guidelines elevate cleanroom requirements for tube filling operations. ISO 15378 certifies primary packaging materials for medicinal products, creating a compliance hierarchy that filters supplier bases. China's NMPA has tightened registration requirements for imported pharmaceutical packaging, adding documentation burdens for Western converters. Stakeholders must monitor evolving serialization mandates across FDA, EMA, and emerging market regulators to align tube decoration and coding investments with compliance timelines.
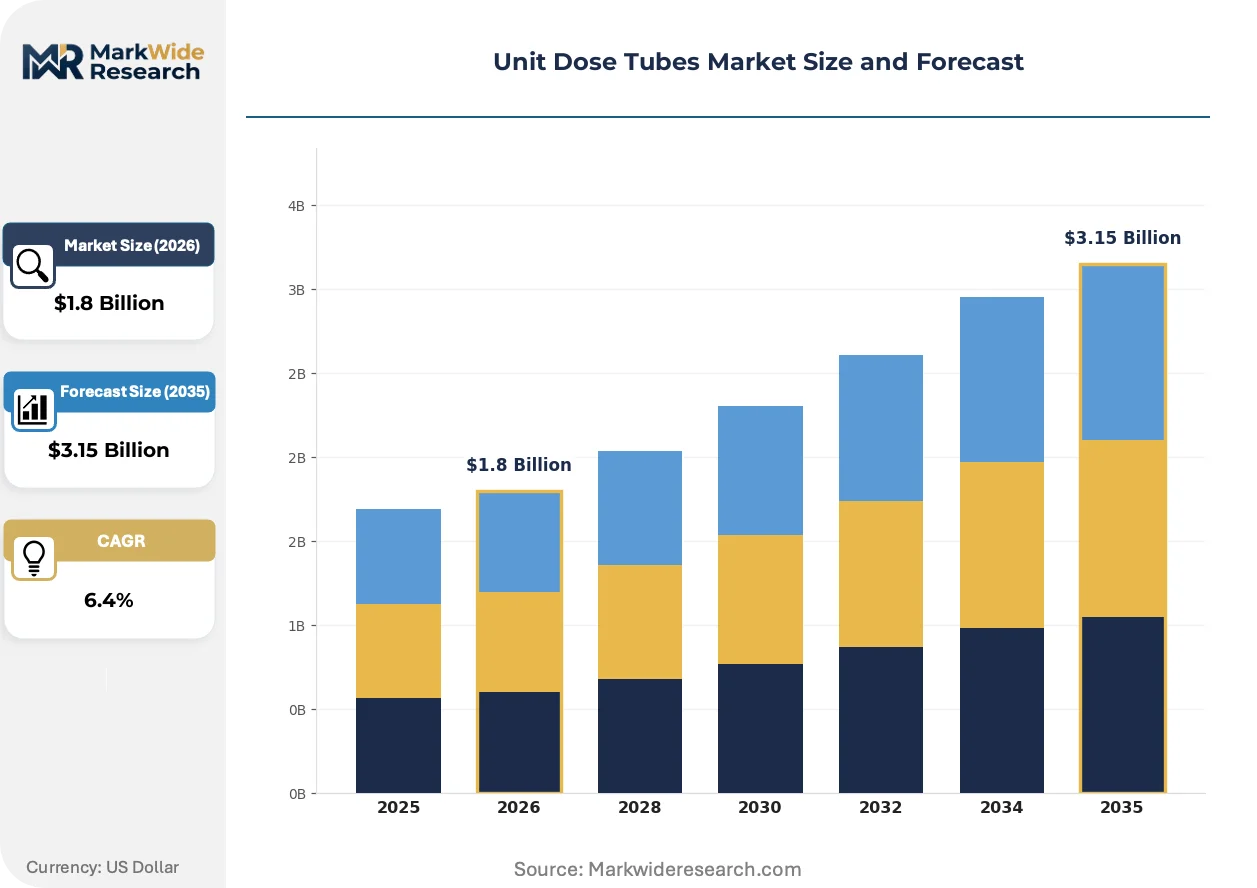
Market Dynamics
Serialization mandates from the US FDA and EMA are compressing investment timelines for track-and-trace-ready tube formats, forcing converters to reallocate capital from decoration flexibility toward compliance infrastructure before patent cliffs hit several blockbuster drug portfolios.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:The US FDA's child-resistant standards for oral solid doses drive demand for tamper-evident tube closures in pediatric and geriatric therapeutics.
- Cleanroom manufacturing expansion:Pharmaceutical contract manufacturers in Germany's Rhine-Main cluster are adding dedicated single-use packaging lines to serve European sterile fill-finish networks.
- Aluminum barrier properties:Oxygen and light impermeability specifications for photosensitive APIs preserve aluminum tube share despite plastic extrusion cost advantages.
Market Restraints
- REACH compliance costs:ECHA-mandated reformulation of tube adhesives and barrier coatings elevates European supplier cost-of-entry versus North American competitors.
- Raw material concentration:Specialty laminate films depend on petrochemical feedstock pricing tied to volatile naphtha markets in the US Gulf Coast.
- Blister pack substitution:Unit-dose oral solid formats in nutraceuticals and veterinary medicine are migrating toward cold-form foil blisters for moisture protection.
Strategic Opportunities
- China NMPA registration pathways:Tightened documentation requirements for imported pharmaceutical packaging create first-mover advantages for Western converters with established dossier capabilities.
- Precision-dispensing convergence:Integration of metered-dose pumps with laminate tubes opens compliance-driven segments in hormone replacement and ophthalmic therapies.
- Veterinary medicine expansion:Companion animal pharmaceutical spending in Germany and France drives demand for peel-open topical tubes with tamper-evident seals.
Industry Challenges
- ISO 15378 certification timelines:Primary packaging material qualification for medicinal products requires 18-24 month validation cycles that delay new supplier entry.
- Serialization line retrofit capex:Track-and-trace coding equipment for tube decoration demands seven-figure investments per production line with limited vendor options.
- Cross-functional talent scarcity:Combined pharmaceutical packaging and digital authentication expertise remains concentrated among a narrow pool of specialists in Basel and Boston.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unit Dose Tubes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Glass Tubes, Aluminum Tubes, Composite Tubes Application: Cosmetics, Pharmaceuticals, Food Industry, Industrial Applications Size: 5 ml, 10 ml, 15 ml, 30 ml Packaging Type: Seal Packs, Blister Packs, Cartons, Others |
| Companies Covered | Amcor Limited, Unicep Packaging, LF of America, Reagent Chemical, Unette Corporation, AptarGroup, Inc., Berry Global, Inc., WestRock Company, West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unit Dose Tubes Market Strategic Shifts
Active pharmaceutical ingredient stability requirements and patient adherence metrics are converging to reshape tube specification priorities, with barrier performance and dispensing precision now outweighing decoration flexibility in converter R&D allocation.
Multi-layer coextruded barrier films incorporating ethylene vinyl alcohol are absorbing oxygen transmission rate specifications previously met by aluminum tubes, enabling plastic formats to penetrate light-sensitive API categories. Ophthalmic and dermal biologic manufacturers in Switzerland and Massachusetts are qualifying these laminates for 24-month shelf life claims. The technology is absorbing premium positioning from metal formats while compressing per-unit packaging costs for high-volume generics.
EMA's Annex 1 sterile manufacturing guidelines are elevating cleanroom classification requirements for tube filling operations, mandating Grade A environments for terminal sterilization processes. Converter investments in isolator technology and continuous monitoring systems now precede commercial qualification. Aseptic cream and ointment segments in Ireland and Denmark are responding with dedicated barrier tube supply agreements that lock in multi-year capacity.
Hospital and long-term care procurement is consolidating unit dose specifications around peel-open convenience and medication adherence verification, displacing traditional bulk tube formats in institutional channels. Group purchasing organizations in the US and pharmacy networks in France are standardizing on pre-measured topical doses with barcode authentication. This pattern is most visible in wound care and dermatology verticals where nursing labor costs drive compliance preference toward single-use formats.
Unit Dose Tubes Market Segmentation
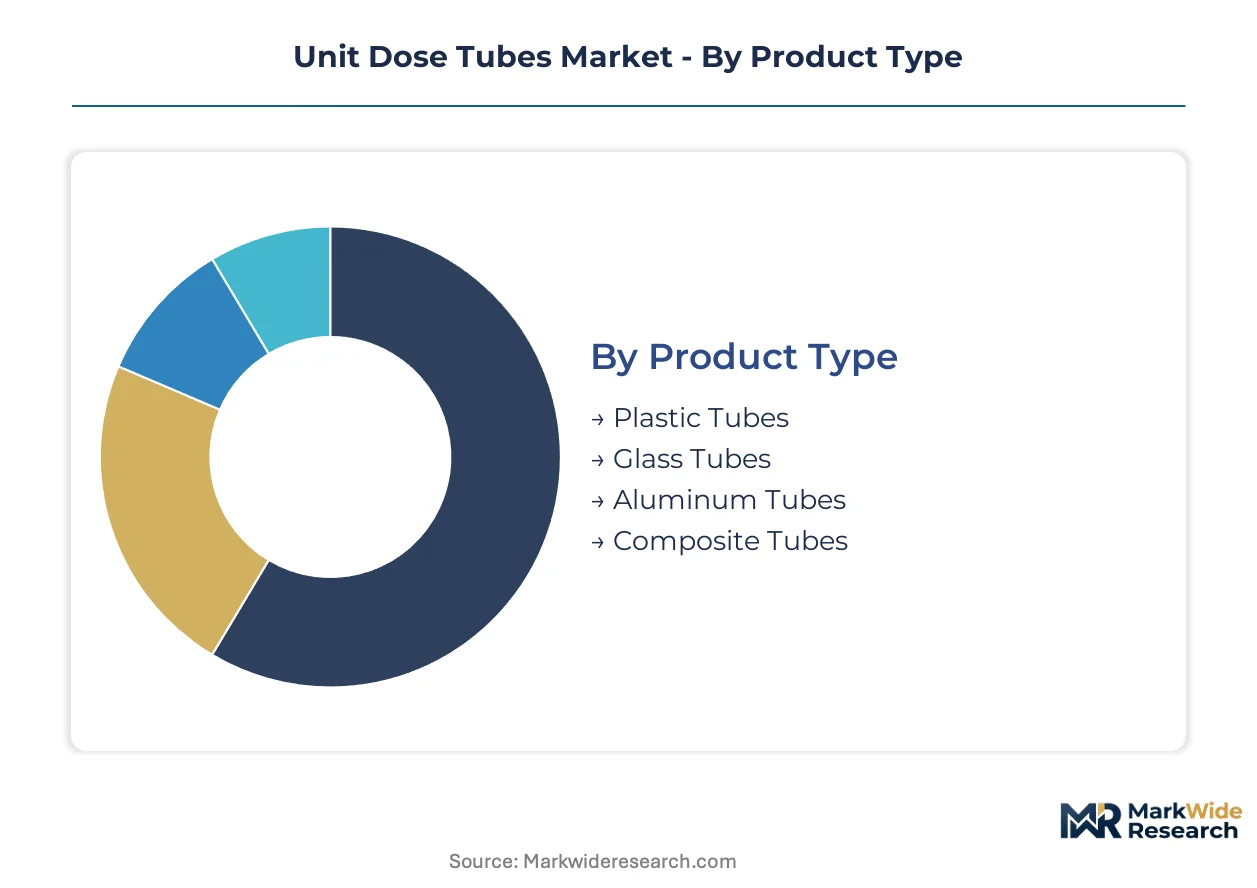
Unit dose tube specifications diverge sharply across pharmaceutical, cosmetic, and industrial end-uses, with material selection and barrier performance determining compliance eligibility and shelf-life claims. Converter R&D allocation now prioritizes oxygen transmission rates and child-resistant closure integration over decoration flexibility.
Product Type:
Material selection governs barrier specifications, sterilization compatibility, and cost structures across pharmaceutical and cosmetic applications.
- Plastic Tubes:Multi-layer coextruded structures incorporating ethylene vinyl oxygen barriers absorb specifications previously requiring aluminum. Swiss and Massachusetts biologic manufacturers qualify these laminates for 24-month stability claims in ophthalmic and dermal therapies.
- Aluminum Tubes:Impact-extruded seamless construction delivers absolute oxygen and light impermeability for photosensitive APIs. Germany's Rhine-Main packaging cluster maintains dedicated capacity for sterile fill-finish networks requiring terminal sterilization compatibility.
- Glass Tubes:Borosilicate and soda-lime formats serve parenteral and diagnostic applications where chemical inertity outweighs fragility concerns.
- Composite Tubes:Laminate-welded constructions combine aluminum barrier layers with plastic decoration surfaces for premium cosmetic positioning.
Plastic tubes lead on scale; aluminum tubes lead on momentum in sterile pharmaceutical applications.
Application:
End-use requirements fragment demand across compliance tiers, with pharmaceutical specifications commanding premium positioning and extended validation cycles.
- Pharmaceuticals:FDA child-resistant mandates under the Poison Prevention Packaging Act and EMA Annex 1 sterile guidelines drive specification intensity. Cleanroom manufacturing requirements in Germany and isolator technology investments filter supplier bases to ISO 15378-certified converters.
- Cosmetics:Decoration flexibility and sustainability credentials dominate procurement, with European REACH compliance forcing adhesive reformulation for regional supply.
- Food Industry:Portion-control formats for condiments and nutraceuticals leverage existing pharmaceutical converter capacity during off-peak cycles.
- Industrial Applications:Adhesives, sealants, and lubricants prioritize chemical resistance and puncture durability over barrier precision.
Pharmaceuticals command margin premiums; cosmetics deliver volume throughput for amortized extrusion lines.
Size:
Fill volume specifications align with dosing precision requirements and institutional procurement patterns across topical and oral solid formats.
- 5 ml:Ophthalmic drops, single-dose vaccines, and diagnostic reagents concentrate demand in Switzerland and Massachusetts biologic corridors.
- 10 ml:Hormone replacement therapies and veterinary companion animal topicals in France and Germany standardize on this format for peel-open convenience.
- 15 ml:Mid-volume dermatology and wound care applications balance material efficiency with nursing labor reduction in US hospital group purchasing organizations.
- 30 ml:Maximum unit-dose threshold for oral solid compliance packaging, approaching multi-dose bulk alternatives.
10 ml formats anchor European veterinary demand; 5 ml formats gain share fastest in precision biologic delivery.
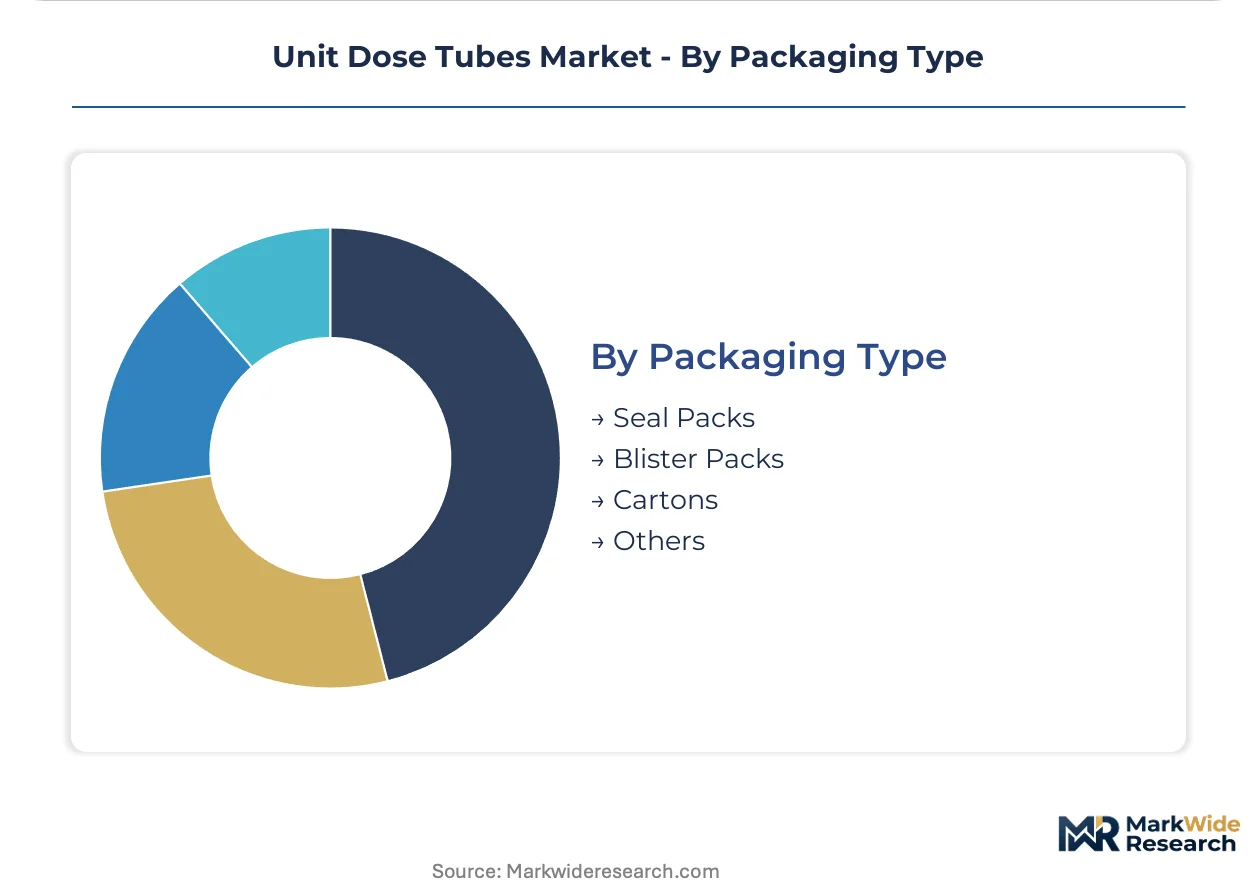
Packaging Type:
Secondary packaging configuration determines authentication capabilities, shelf presentation, and institutional dispensing efficiency.
- Blister Packs:Cold-form foil constructions with moisture barriers expand fastest in nutraceuticals and veterinary oral solids. Unit-dose cavity formats with barcode authentication displace bulk tubes in US and French pharmacy networks.
- Seal Packs:Peel-open foil-laminate pouches dominate topical cream and ointment segments where nursing labor costs drive single-use preference in wound care and dermatology.
- Cartons:Paperboard secondary packaging carries serialization codes and patient information leaflets for retail pharmacy distribution.
- Others:Rigid plastic shells and vacuum-formed trays serve specialty diagnostic and surgical kit applications.
Seal packs maintain maturity in topical segments; blister packs climb the fastest in oral solid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist packaging engineers and sterile manufacturing technicians concentrate in Germany's Rhine-Main corridor and Switzerland's Basel biotech cluster, anchoring European capacity for pharmaceutical-grade unit dose tubes.
United States
FDA serialization mandates under the Drug Supply Chain Security Act compress investment timelines for track-and-trace-ready tube formats. The Poison Prevention Packaging Act enforces child-resistant closure standards for pediatric and geriatric therapeutics. Greater Boston's biotech corridor drives 5 ml format demand for ophthalmic and single-dose vaccine applications.
Germany
EMA Annex 1 sterile manufacturing guidelines elevate cleanroom classification requirements for tube filling operations. REACH compliance forces reformulation of tube adhesives and barrier coatings, elevating supplier cost-of-entry. The Rhine-Main packaging cluster maintains dedicated single-use packaging lines serving European sterile fill-finish networks.
Switzerland
Ophthalmic and dermal biologic manufacturers qualify multi-layer coextruded barrier films for 24-month shelf life claims. Swissmedic maintains stringent primary packaging material standards that filter supplier bases to ISO 15378-certified converters. The Basel biotech corridor anchors precision-dispensing convergence in hormone replacement therapies.
China
NMPA tightened registration requirements for imported pharmaceutical packaging, adding documentation burdens for Western converters. Domestic contract manufacturers expand single-use packaging lines to reduce cross-contamination risks. Yangtze River Delta converters invest in serialization-ready tube decoration to capture export market share.
France
Companion animal pharmaceutical spending drives demand for peel-open topical tubes with tamper-evident seals. Pharmacy networks standardize on pre-measured topical doses with barcode authentication for institutional procurement. The Île-de-France region concentrates veterinary medicine packaging demand for 10 ml unit dose formats.
Unit Dose Tubes Market Competitive Environment
The competitive structure tilts toward vertically integrated film operations and precision-dispensing specialists. Converter margins compress between raw material volatility and compliance infrastructure investments. Three archetypes dominate: integrated material suppliers controlling laminate film supply, cleanroom-certified specialists serving sterile pharmaceutical networks, and high-volume extrusion houses amortizing decoration flexibility across cosmetic and over-the-counter portfolios. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with serialization line retrofits demanding seven-figure capital commitments per production line.
Among integrated packaging conglomerates, Amcor Limited and Berry Global, Inc. occupy positions defined by captive film supply and extrusion scale respectively. AptarGroup, Inc. exemplifies the precision-dispensing archetype through closure integration capabilities. Unicep Packaging anchors North American cleanroom manufacturing specialization for pharmaceutical customers. These three company structures represent the strategic vectors—material integration, dispensing technology, and sterile manufacturing certification—through which competitive positioning consolidates.
| Leading Market Players |
|---|
| Amcor Limited |
| Unicep Packaging |
| LF of America |
| Reagent Chemical |
| Unette Corporation |
| AptarGroup, Inc. |
| Berry Global, Inc. |
| WestRock Company |
| West Pharmaceutical Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialty laminate films from US Gulf Coast petrochemical feedstocks cascade through three distinct pricing tiers before reaching pharmaceutical converters, with REACH-compliant European suppliers absorbing 15-20% cost premiums against North American competitors.
Pricing Analysis
Bundled cleanroom manufacturing services command 30-40% premiums over unbundled tube supply, with ISO 15378 certification tiers separating premium sterile-grade from standard cosmetic-grade positioning. Price differentiation rests on oxygen transmission rate specifications and precision-dispensing closure integration, with German and Swiss buyers showing lowest sensitivity due to EMA Annex 1 compliance mandates. Pricing pressure intensifies in high-volume over-the-counter segments where plastic extrusion houses compete on decoration flexibility.
Supply Chain Analysis
China's NMPA domestic-content documentation requirements are reshaping sourcing patterns for Western converters seeking Yangtze River Delta manufacturing partnerships. Raw material supply concentrates in Germany, Switzerland, and China's coastal provinces, with ethylene vinyl alcohol barrier films and aluminum impact-extruded seamless tubing as critical inputs. Single-source vulnerability in specialty laminate films exposes converters to naphtha price volatility. Distribution runs through pharmaceutical contract manufacturers in Rhine-Main and Basel clusters before hospital group purchasing organization consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unit dose tubes constitute a late-cycle quality story as EMA Annex 1 sterile guidelines and FDA serialization mandates shift procurement toward barrier performance and track-and-trace authentication over decoration economics.
For Market Incumbents: Anchor sterile manufacturing certification through isolator technology investments in Germany's Rhine-Main corridor, locking multi-year capacity agreements with biologic fill-finish networks. Deepen backward integration into captive ethylene vinyl alcohol film supply to defend margin compression from petrochemical volatility. Counter blister pack substitution threats by qualifying multi-layer laminates for 24-month ophthalmic stability claims.
For New Entrants and Emerging Players: Launch via veterinary medicine packaging partnerships in France's Île-de-France region, where companion animal pharmaceutical spending outpaces regulatory complexity. Target 10 ml peel-open topical formats for institutional pharmacy networks standardizing on barcode authentication. Exploit white space in China's NMPA registration pathways by building dossier capabilities ahead of Western competitors.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 15378 certification timelines stretch 18-24 months and seven-figure serialization retrofits filter sub-scale converters. Five-to-ten year viability favors cleanroom-certified specialists with established sterile fill-finish relationships over undifferentiated extrusion houses. Monitor EMA Annex 1 enforcement patterns as inflection signals for barrier tube demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Line Retrofit | FDA DSCSA compliance mandates seven-figure capital commitments per production line with limited vendor options. |
| Cleanroom Certification Expansion | EMA Annex 1 Grade A environments filter supplier bases to isolator-equipped converters in Basel and Rhine-Main. |
| Barrier Film Backward Integration | Captive ethylene vinyl oxygen barrier supply defends margin control against US Gulf Coast naphtha volatility. |
| Precision-Dispensing Closure Integration | Metered-dose pump convergence opens hormone replacement and ophthalmic therapy compliance segments. |
| NMPA Dossier Capability Buildout | Western converters with established China registration pathways capture first-mover advantages in tightened import requirements. |
Study Parameters
Coverage spans Germany, Switzerland, the United States, China, and France, with primary inputs from each market cluster combining regulatory affairs specialists at EMA and FDA, pharmaceutical packaging procurement managers at European fill-finish networks, and cleanroom manufacturing engineers in Basel and Boston. Secondary validation drew from FDA DSCSA guidance documents, EMA Annex 1 sterile manufacturing revisions, NMPA registration requirement updates, and ISO 15378 certification databases. Bottom-up unit dose tube demand modeling triangulated against top-down pharmaceutical packaging market sizing.
Granularity-level modeling tracked plastic, aluminum, glass, and composite material formats across pharmaceutical, cosmetic, food, and industrial end-uses, with fill volume specifications from 5 ml to 30 ml and packaging type configurations including blister packs, seal packs, and cartons. CAGRs derived from weighted average of historical growth patterns and regulatory-driven demand inflections across the projection horizon, incorporating oxygen transmission rate specification shifts and serialization mandate compliance timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH adhesive reformulation delays or NMPA documentation requirement escalations. Projections reflect assumptions of continued EMA Annex 1 enforcement and FDA serialization timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Lumbar Puncture Trays and Needles Market