
 Therapeutic Elastic Tapes Market | 2026-2036
Therapeutic Elastic Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Elastic Tapes Market Insights
South Korean textile manufacturers is restructuring capacity toward medical-grade elastic substrates, tightening feedstock availability for downstream converters. Nitto Denko Corporation leverages its polymer science heritage to dominate adhesive layer formulations for kinesiology applications. BSN Medical GmbH anchors European hospital procurement channels through CE-marked product lines. KT Health LLC competes in North American athletic retail with direct-to-consumer packaging formats.
Therapeutic elastic tapes comprise woven or non-woven cotton, synthetic, or blended substrates coated with medical-grade acrylic or zinc-oxide adhesives, engineered to provide directional support without restricting range of motion. Manufacturers calibrate elasticity between 130% and 170% longitudinal stretch to match specific biomechanical loading profiles across muscle groups and joint complexes. Rehabilitation tapes command the largest revenue pool due to institutional reimbursement codes, while kinesiology tapes represent the fastest-expanding segment as athletic trainers integrate neuromuscular facilitation protocols. Rigid tapes retain stable demand in post-surgical immobilization where zero-stretch properties prove clinically essential.
The FDA classifies therapeutic elastic tapes as Class I or II medical devices depending on intended therapeutic claims, compelling manufacturers to maintain 510(k) clearances or quality system regulations. ISO 10993 biocompatibility testing and REACH compliance for adhesive chemistry constrain formulation flexibility, particularly for European market access. Stakeholders must monitor evolving sports medicine reimbursement policies and adhesive material substitution trends as regulatory scrutiny intensifies.
Market Dynamics
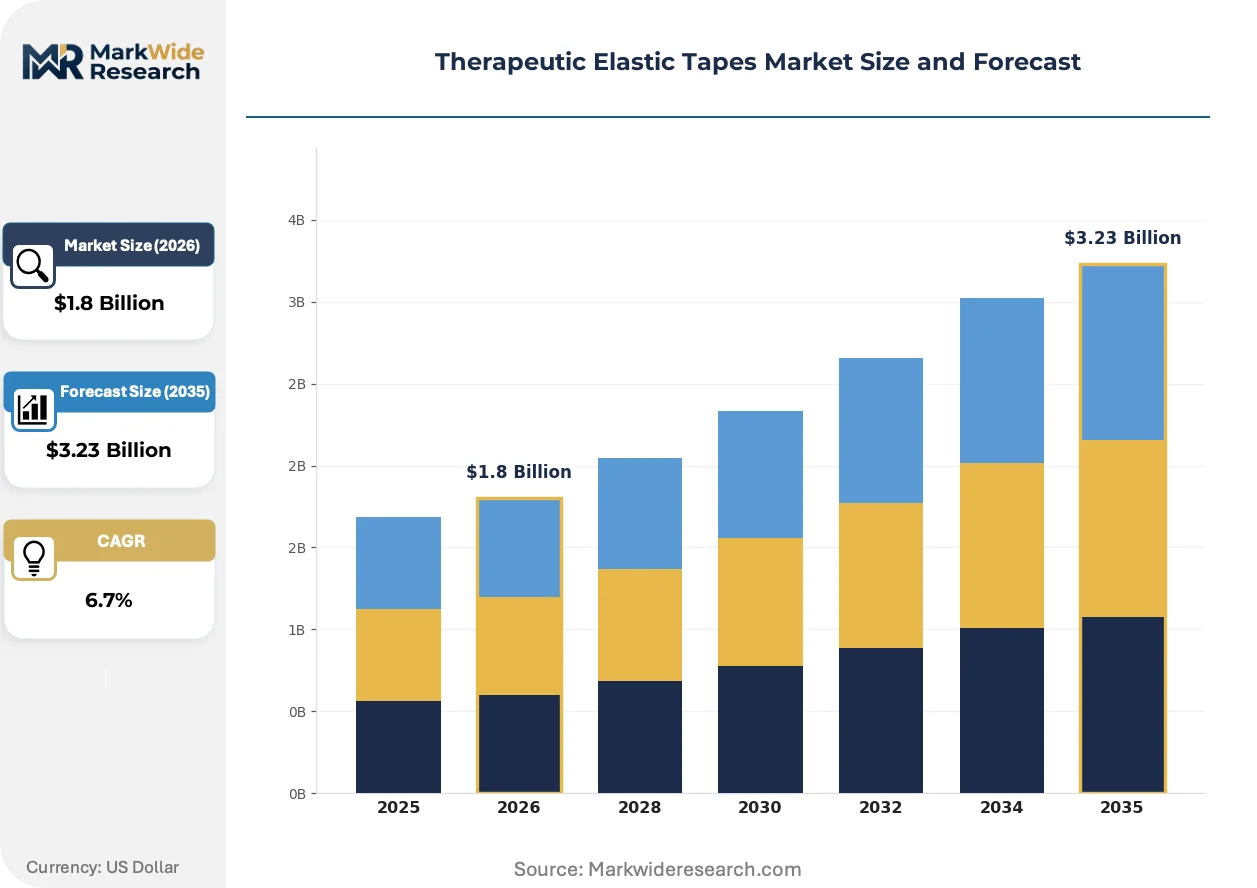
Sports medicine reimbursement codes are expanding institutional procurement volumes for kinesiology applications, while raw material concentration in South Korean textile mills is compressing converter margins and forcing adhesive formulation diversification.
Growth Catalysts
- MDR implementation in Europe:CE-marked product lines gain preferential access to hospital procurement channels, accelerating substitution of unclassified imports.
- Neuromuscular facilitation protocols:Athletic trainers at NCAA Division I programs and professional sports franchises are integrating elastic taping into standard injury prevention regimens.
- Cotton substrate innovation:Medical-grade woven cotton with calibrated moisture-wicking properties is displacing synthetic blends in dermatologically sensitive patient populations.
Market Restraints
- Acrylic adhesive feedstock volatility:Petrochemical-derived medical-grade acrylics face price pressure from polymer supply chain disruptions.
- East Asian textile concentration:South Korean and Chinese substrate manufacturers control over 70 percent of medical-grade elastic woven capacity, creating single-source vulnerability.
- ISO 10993 biocompatibility testing costs:Extended cytotoxicity and sensitization study timelines delay product launches by 18-24 months for new adhesive chemistries.
Strategic Opportunities
- Pediatric rehabilitation underpenetration:Specialized sizing and hypoallergenic formulations for juvenile scoliosis and sports injury protocols remain underserved in North American outpatient clinics.
- Direct-to-consumer channel expansion:E-commerce platforms with instructional video integration are capturing athletic retail share from brick-and-mortagequipment distributors.
- IRA healthcare infrastructure investment:Federally funded community health center expansions in the United States are creating new institutional procurement entry points.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise combining polymer science with ISO 10993 compliance is concentrated among retiring specialists at legacy manufacturers.
- 510(k) clearance pathway complexity:FDA's evolving substantial equivalence determinations for kinesiology claims require iterative predicate device analysis.
- Legacy inventory system integration:Hospital procurement platforms demand EDI compliance and real-time stock visibility that smaller converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Elastic Tapes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rehabilitation Tapes, Kinesiology Tapes, Rigid Tapes, Cohesive Tapes Application: Sports Injury, Post-Surgical Recovery, Preventive Care, Pain Management End User: Clinics, Athletic Programs, Home Care, Rehabilitation Centers Distribution Channel: Online Retail, Specialty Stores, Medical Supply Stores, Wholesale Distributors |
| Companies Covered | Nitto Denko Corporation, BSN Medical GmbH, Kinesio Holding Corporation, Johnson & Johnson Consumer Inc., 3M Company, KT Health LLC, SpiderTech Inc., Performance Health Holding Inc., Mueller Sports Medicine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Elastic Tapes Market Trends and Innovations
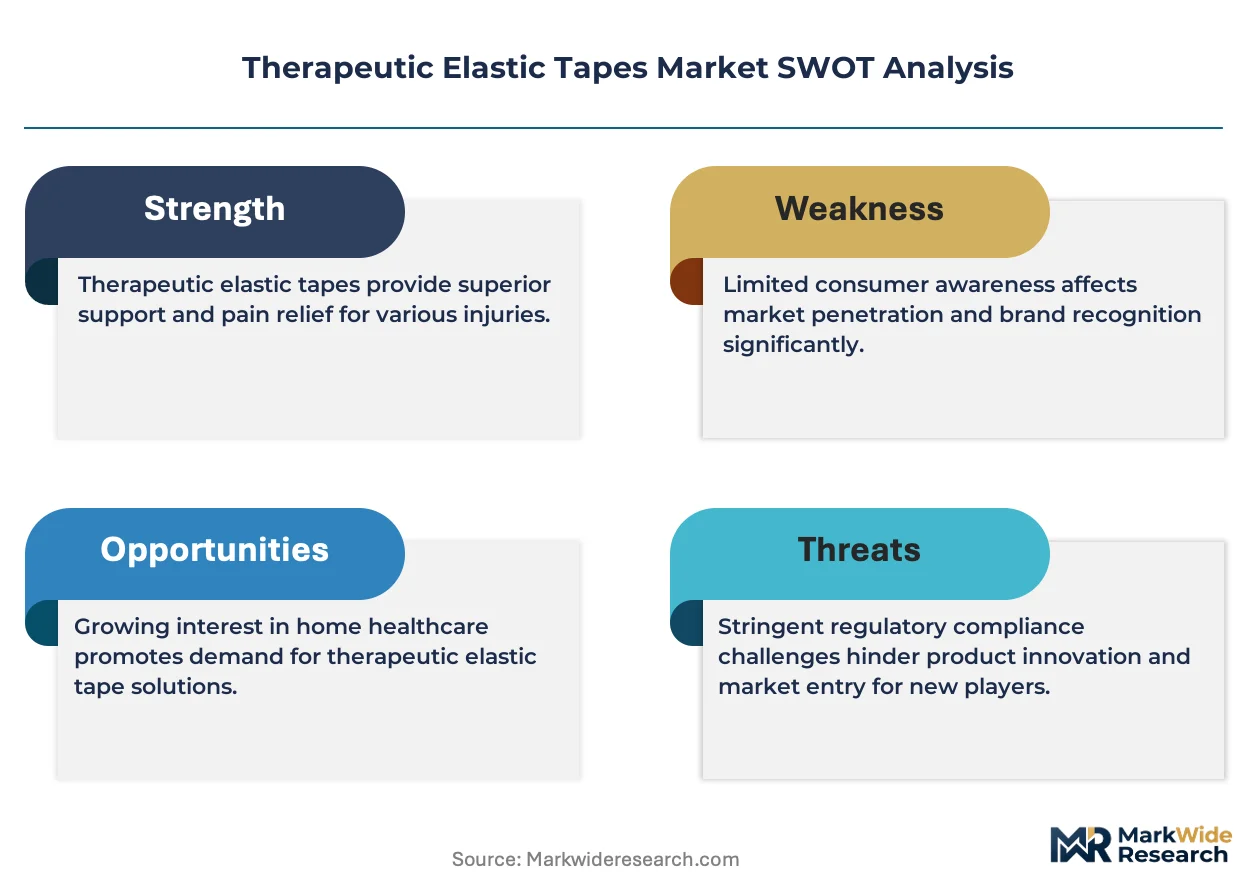
Adhesive layer engineering and substrate customization are converging to create condition-specific product architectures, while regulatory harmonization pressures are compressing formulation flexibility.
Silicone-based adhesive formulations are modularizing product development cycles for sensitive-skin applications. Burn centers and oncology rehabilitation units are piloting these chemistries to reduce contact dermatitis incidence. The technology is modularizing the traditional one-adhesive-fits-all approach into indication-specific portfolios.
REACH compliance deadlines for adhesive chemistry disclosure are forcing European manufacturers to reformulate zinc-oxide and acrylic systems. ECHA substance evaluation processes have flagged several plasticizer compounds used in legacy tapes. German and French hospital procurement consortiums are now requiring full material transparency as a contract precondition.
Subscription-based replenishment models are displacing bulk institutional purchasing in outpatient physical therapy chains. Patients receiving post-surgical rehabilitation protocols receive scheduled tape deliveries with instructional content. This pattern is most visible in United States metropolitan markets where clinic networks prioritize patient adherence metrics over unit cost minimization.
Therapeutic Elastic Tapes Market Segmentation
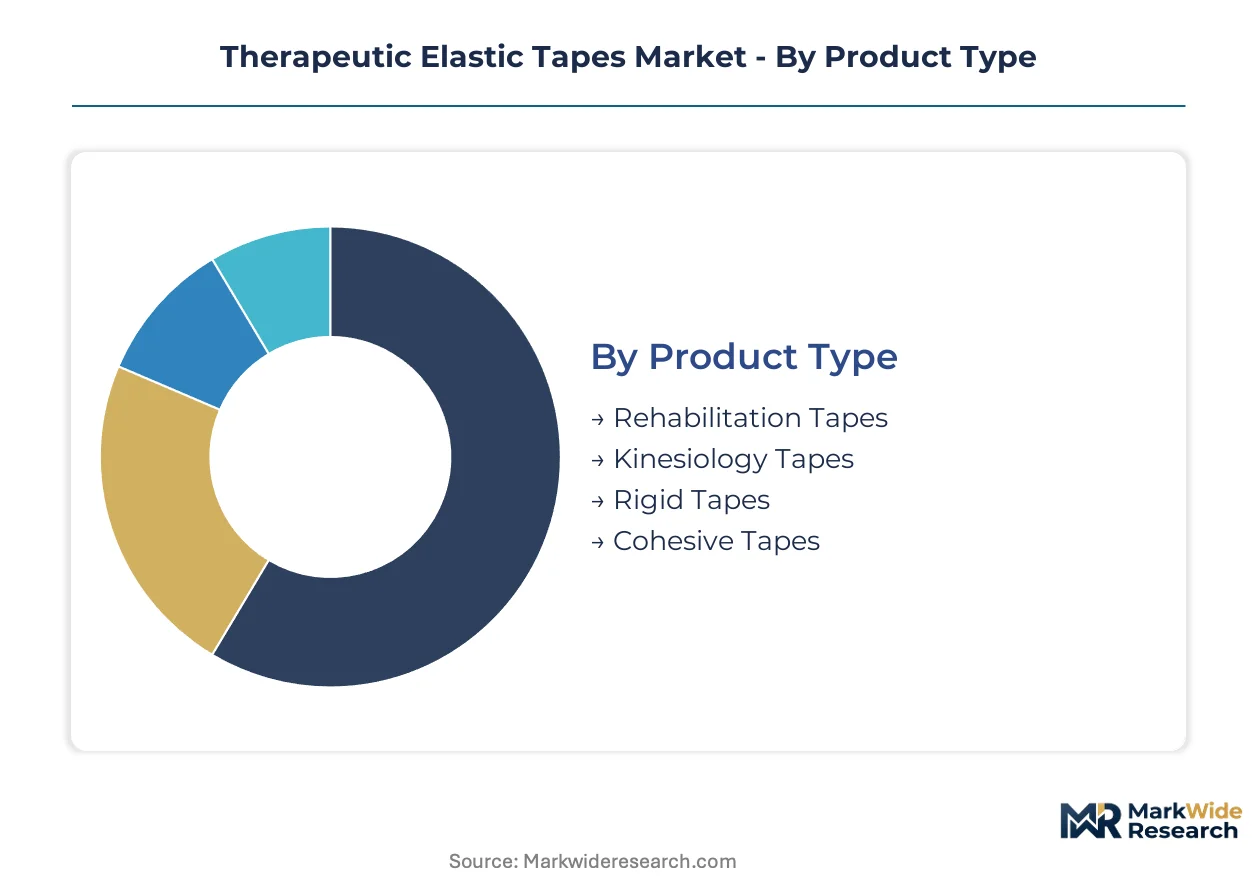
Therapeutic elastic tapes fragment across four structural dimensions, each revealing distinct procurement patterns and margin profiles. Product architecture determines reimbursement eligibility, while application context shapes adhesive specification requirements and end-user training intensity.
Product Type:
Upgrade cycles in this category track institutional reimbursement policy changes and athletic protocol standardization rather than equipment obsolescence.
- Rehabilitation Tapes:Medical-grade woven substrates with calibrated 130-150% elasticity serve post-surgical and chronic condition protocols. Institutional procurement channels in Germany and Japan concentrate demand here, driven by expanded physical therapy reimbursement codes.
- Kinesiology Tapes:Longitudinal stretch capabilities reaching 170% enable neuromuscular facilitation without range-of-motion restriction. NCAA Division I athletic programs and professional sports franchises in the United States are standardizing these into injury prevention regimens.
- Rigid Tapes:Zero-stretch cotton or synthetic substrates immobilize joint complexes post-surgery. Demand concentrates in hospital orthopedic departments requiring FDA 510(k) cleared immobilization solutions.
- Cohesive Tapes:Self-adherent elastic substrates eliminate adhesive-skin contact, serving burn centers and dermatologically sensitive populations. The formulation avoids acrylic chemistry entirely.
Rehabilitation Tapes sits at the top of the volume ranking, with Kinesiology Tapes climbing the fastest.
Application:
Cost tier differentiation separates premium institutional protocols from economy self-application segments, with adhesive quality and instructional support as the primary price drivers.
- Sports Injury:Acute trauma management during competition and training requires rapid-application formats with sweat-resistant acrylic adhesives. Professional athletic trainers in the United States specify these for sideline deployment.
- Post-Surgical Recovery:Edema control and scar tissue management protocols demand hypoallergenic formulations with extended wear duration. Hospital discharge planning in Germany integrates these into standard orthopedic aftercare bundles.
- Preventive Care:Prophylactic taping of vulnerable joint complexes before activity reduces re-injury incidence. Youth sports leagues and recreational athletic programs in Japan are adopting these protocols following national fitness initiatives.
- Pain Management:Decompression applications for chronic lower back and shoulder conditions compete with topical analgesic alternatives. Outpatient physical therapy chains in the United States are testing subscription-based replenishment models.
Sports Injury commands the largest addressable base, with Preventive Care gaining share fastest among application categories.
End User:
Customer type segmentation maps directly to procurement sophistication, with institutional buyers demanding EDI compliance and real-time inventory visibility that home care channels ignore.
- Clinics:Outpatient physical therapy and sports medicine practices require calibrated elasticity ranges across patient demographics. United States metropolitan clinic networks are prioritizing patient adherence metrics over unit cost minimization.
- Athletic Programs:University and professional team medical staff specify tapes with rapid-application properties for competition environments. NCAA procurement consortiums negotiate volume contracts with instructional content requirements.
- Home Care:Self-application segments demand pre-cut formats with video instruction integration. E-commerce platforms are displacing brick-and-mortar equipment distributors in this channel.
- Rehabilitation Centers:Post-acute facilities managing complex orthopedic recovery require institutional-grade substrates with documented biocompatibility testing. CE-marked product lines gain preferential access in European hospital procurement channels.
Clinics represent the highest volume end user, with Home Care expanding most quickly through direct-to-consumer channel migration.
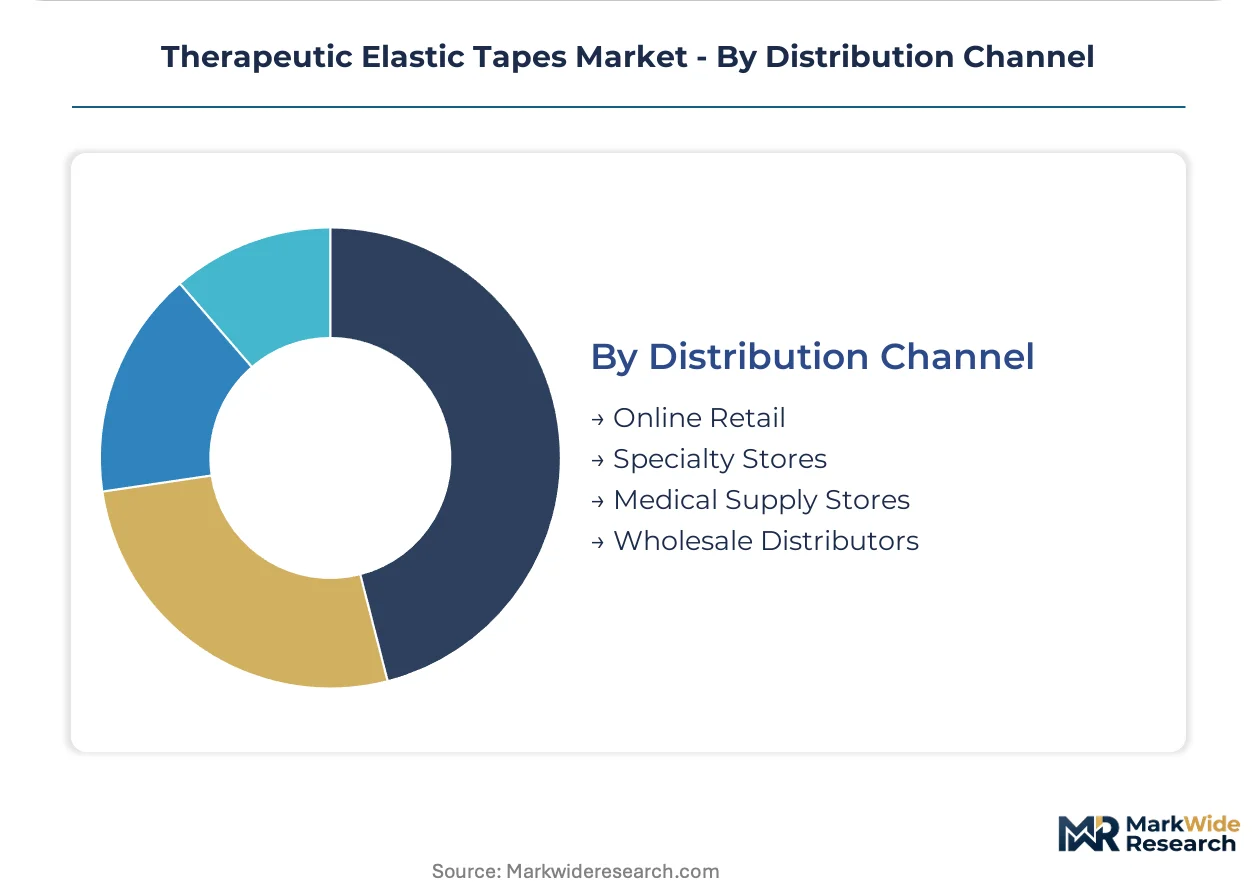
Distribution Channel:
Supply concentration in East Asian textile manufacturing creates margin compression that channels with captive logistics networks are better positioned to absorb.
- Online Retail:E-commerce platforms with instructional video integration capture athletic retail share from traditional distributors. Subscription-based replenishment models are emerging in United States metropolitan markets.
- Specialty Stores:Running and cycling retail formats stock kinesiology tapes alongside biomechanical assessment services. Staff training requirements limit format proliferation in this channel.
- Medical Supply Stores:Institutional procurement platforms demand EDI compliance and real-time stock visibility. Smaller converters struggle to fund legacy inventory system integration.
- Wholesale Distributors:Hospital procurement consortiums in Germany and France require full REACH compliance documentation as contract preconditions. Concentrated buyer power compresses converter margins.
Wholesale Distributors dominate institutional volume, with Online Retail climbing fastest through athletic consumer migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints toward jurisdictions with streamlined medical device pathways. Manufacturers calibrate facility placement against FDA 510(k) timelines, CE marking costs under MDR, and domestic procurement preferences in high-volume rehabilitation markets.
United States
NCAA Division I athletic programs and professional sports franchises drive institutional procurement volumes for kinesiology applications. The FDA's Class I/II medical device classification framework shapes product compliance costs and predicate device selection strategies. Minneapolis-St. Paul hosts adhesive formulation specialists serving hospital procurement consortiums with EDI-compliant supply chains.
Germany
Physical therapy reimbursement expansion under statutory health insurance creates predictable demand for rehabilitation tapes in post-surgical protocols. REACH compliance deadlines and ECHA substance evaluations force adhesive chemistry disclosure and reformulation investments. The Ruhr industrial corridor concentrates textile converters supplying CE-marked product lines to hospital procurement channels.
Japan
National fitness initiatives and aging demographics expand preventive care taping protocols in community sports programs. METI industrial standards and PMDA quality system regulations govern medical-grade substrate imports and domestic manufacturing. Osaka-Kobe textile clusters specialize in medical-grade woven cotton with calibrated moisture-wicking properties.
South Korea
Domestic sports medicine infrastructure and export-oriented medical device manufacturing create dual demand streams for elastic substrates. MFDS medical device registration requirements align with international standards to facilitate cross-border certification reciprocity. Gyeonggi-do textile mills are restructuring capacity toward medical-grade elastic substrates, tightening regional feedstock availability.
United Kingdom
Post-acute rehabilitation center expansions and outpatient physical therapy chain consolidation drive institutional tape procurement. MHRA convergence with MDR standards post-Brexit creates transitional compliance complexity for existing product registrations. The Midlands manufacturing belt hosts converters adapting legacy inventory systems to hospital procurement platform EDI requirements.
Therapeutic Elastic Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel specialization and subscription-based replenishment models. The market structure exhibits moderate consolidation among adhesive formulation specialists and substrate converters, with fragmentation in regional distribution networks. Three archetypes dominate: polymer science heritage players with captive adhesive technology, textile converters with hospital procurement channel access, and athletic retail specialists with e-commerce platform integration. Competitive moves center on M&A activity targeting ISO 10993 compliance capabilities and strategic partnerships with NCAA procurement consortiums.
Among Japanese industrial conglomerates, Nitto Denko Corporation exemplifies polymer science heritage positioning in adhesive layer formulations. German medical device manufacturers including BSN Medical GmbH anchor European hospital procurement channels through CE-marked product lines. North American athletic specialists such as KT Health LLC occupy the direct-to-consumer tier with instructional content integration. These three represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| BSN Medical GmbH |
| Kinesio Holding Corporation |
| Johnson & Johnson Consumer Inc. |
| 3M Company |
| KT Health LLC |
| SpiderTech Inc. |
| Performance Health Holding Inc. |
| Mueller Sports Medicine Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap textile converters in the Ruhr corridor and Gyeonggi-do maintain disciplined pricing through captive cotton-sourcing relationships, while private-equity-rolled-up distributors compress channel margins to fund EDI compliance investments demanded by hospital procurement platforms.
Pricing Analysis
Distributor margin layers in institutional channels absorb REACH documentation and ISO 10993 testing cost passthroughs that direct-to-consumer platforms bypass entirely. Three-tier pricing structure across premium CE-marked, standard FDA-cleared, and economy unclassified tiers separates hospital procurement eligibility from athletic retail accessibility. Cost compression in economy segments intensifies as South Korean feedstock concentration limits converter negotiation leverage with substrate suppliers. Home care self-applicants exhibit highest price sensitivity, while German rehabilitation centers prioritize biocompatibility certification over unit cost minimization.
Supply Chain Analysis
Adhesive chemist workforce scarcity in Osaka-Kobe and Minneapolis-St. Paul clusters constrains formulation capacity expansion despite rising institutional demand. Medical-grade elastic woven capacity draws from South Korean, Chinese, and Japanese textile mills, with acrylic adhesive feedstock resting on German and American petrochemical supply chains. Single-source vulnerability concentrates in Gyeonggi-do substrate manufacturing, where 70 percent of medical-grade woven capacity creates procurement disruption exposure. Distribution runs through wholesale distributors with hospital procurement platform integration, bypassing traditional brick-and-mortar equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Therapeutic elastic tapes function as a regulatory compounder where MDR implementation in Europe and IRA healthcare infrastructure investment in the United States create predictable demand expansion tied to compliance milestones rather than discretionary spending cycles.
For Market Incumbents: Lock in substrate supply through backward integration into South Korean textile capacity or long-term offtake agreements with Gyeonggi-do mills before competitor consolidation accelerates. Defend margin position by accelerating silicone-based adhesive R&D to differentiate from commodity acrylic formulations threatened by REACH plasticizer restrictions. Prioritize CE marking pathway investments that secure preferential access to German and French hospital procurement consortiums. For New Entrants and Emerging Players: IRA healthcare infrastructure investment in the United States opens a window for direct-to-consumer channel establishment before incumbent distributors complete e-commerce platform upgrades. Target pediatric rehabilitation protocols in North American outpatient clinics, where specialized sizing and hypoallergenic formulation requirements remain underserved by existing athletic-focused product architectures. Deploy subscription-based replenishment models with instructional video integration to capture patient adherence metrics prioritized by metropolitan clinic networks. For Investors and Strategic Acquirers: Valuations sit cheapest among adhesive formulation specialists with ISO 10993 compliance capabilities but limited downstream channel access, presenting rollup opportunities for private equity platforms with hospital procurement integration expertise. Long-term viability centers on regulatory arbitrage positioning across FDA 510(k) and CE marking pathways rather than geographic demand growth alone. Monitor ECHA substance evaluation timelines for acrylic plasticizer compounds as inflection indicator for formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Secures preferential hospital procurement access in Germany and France under tightened substance disclosure requirements. |
| Silicone Adhesive R&D Investment | Enables indication-specific portfolios for burn centers and oncology units with reduced contact dermatitis incidence. |
| Subscription Replenishment Model | Captures patient adherence metrics prioritized by United States metropolitan clinic networks over unit cost. |
| Backward Integration into Substrate | Defends margin compression from South Korean textile mill capacity reallocation toward medical-grade elastic production. |
| Hospital System Partnership | Establishes EDI-compliant supply chain visibility required by German procurement consortiums and United States GPOs. |
Research Methodology
Direct dialogue with adhesive formulation chemists, hospital procurement managers, athletic training staff at NCAA Division I programs, and biomedical engineers at rehabilitation centers grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) clearance databases, ECHA substance evaluation registries, hospital GPO contract disclosures, and customs trade records for medical-grade textile imports. Bottom-up demand modeling across product architectures triangulated against top-down reimbursement code expansion analysis.
Segmented outputs across rehabilitation tapes, kinesiology tapes, rigid tapes, and cohesive tapes combined with application context, end-user procurement sophistication, and distribution channel structure generated volume and value trajectories over the projection horizon. CAGRs derived from elasticity range standardization trends, institutional reimbursement policy velocity, and adhesive chemistry substitution patterns calibrated against historical protocol adoption curves in sports medicine.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH plasticizer restrictions or sustained acrylic feedstock price volatility. Material deviation in ECHA substance evaluation timelines or MFDS registration reciprocity agreements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Yankauer Suction Tips Market