
 Netherlands Endoscopy Devices Market | 2026-2036
Netherlands Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Endoscopy Devices Market Foresight
Single-use endoscopy is reconfiguring device economics and infection control protocols across Dutch healthcare. Olympus Corporation leverages its optical heritage to sustain dominance in reusable flexible platforms. Medtronic PLC anchors its position through integrated surgical ecosystems spanning visualization and energy. KARL STORZ competes via rigid endoscope specialization for laparoscopic and arthroscopic workflows.
Endoscopy devices comprise instrumented tubular systems with fiber-optic or digital image sensors, illumination channels, and working ports for biopsy or therapeutic intervention, manufactured through precision glass drawing, CMOS sensor integration, and medical-grade polymer extrusion. These systems enable minimally invasive diagnostic visualization and surgical access through natural orifices or small incisions. Single-use devices command expanding share as Dutch hospitals prioritize cross-contamination elimination and OR turnaround efficiency. Robot-assisted endoscopy represents the fastest-growing technology segment, though conventional video platforms retain the largest installed base. Hospitals absorb the majority of capital expenditure, while ambulatory surgical centers drive incremental volume for lower-acuity procedures.
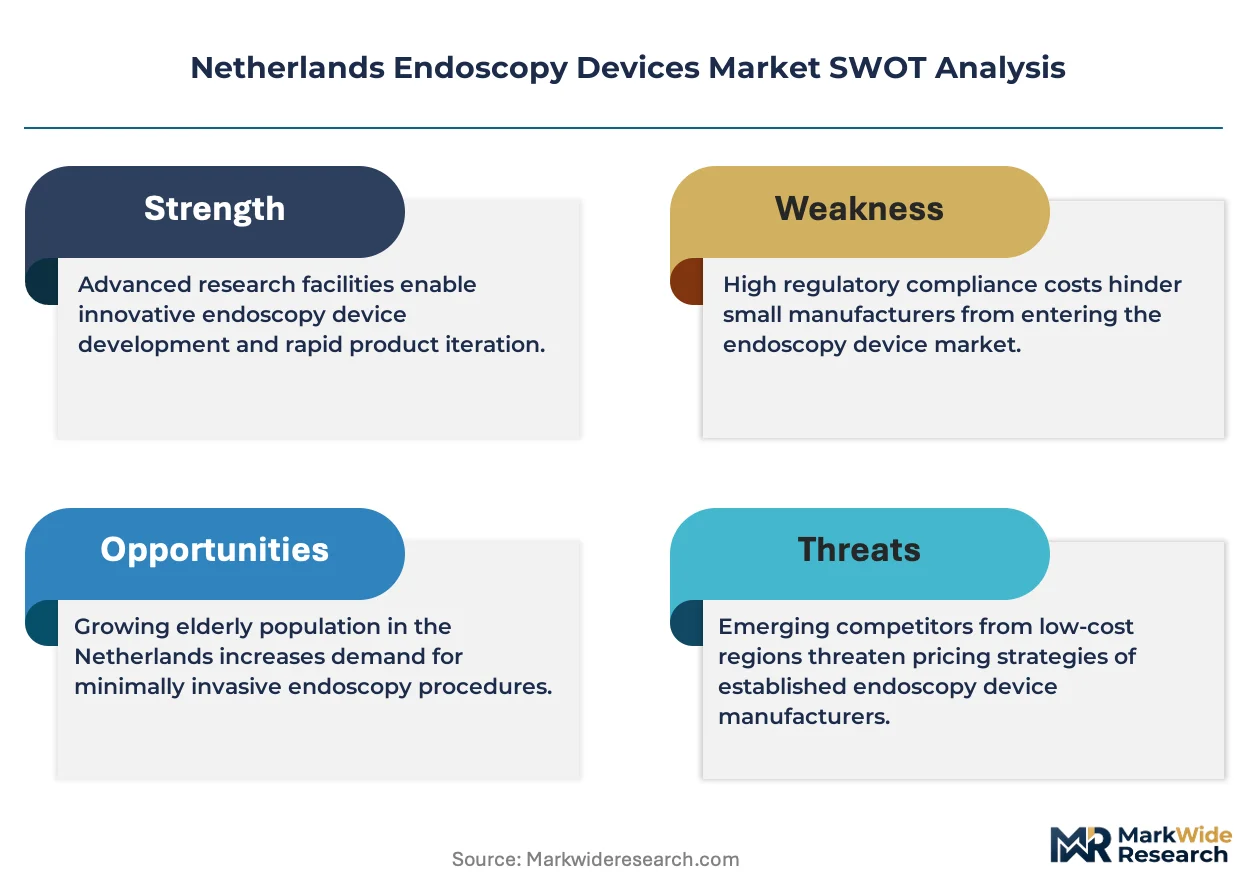
MDR framework and CE marking requirements govern device approval, with the Dutch national competent authority evaluating conformity for EU market access. The Netherlands Health and Youth Care Inspectorate enforces post-market surveillance and adverse event reporting, tightening quality accountability. Stakeholders must monitor reimbursement parity between reusable and disposable platforms as health technology assessments evolve.
Market Dynamics
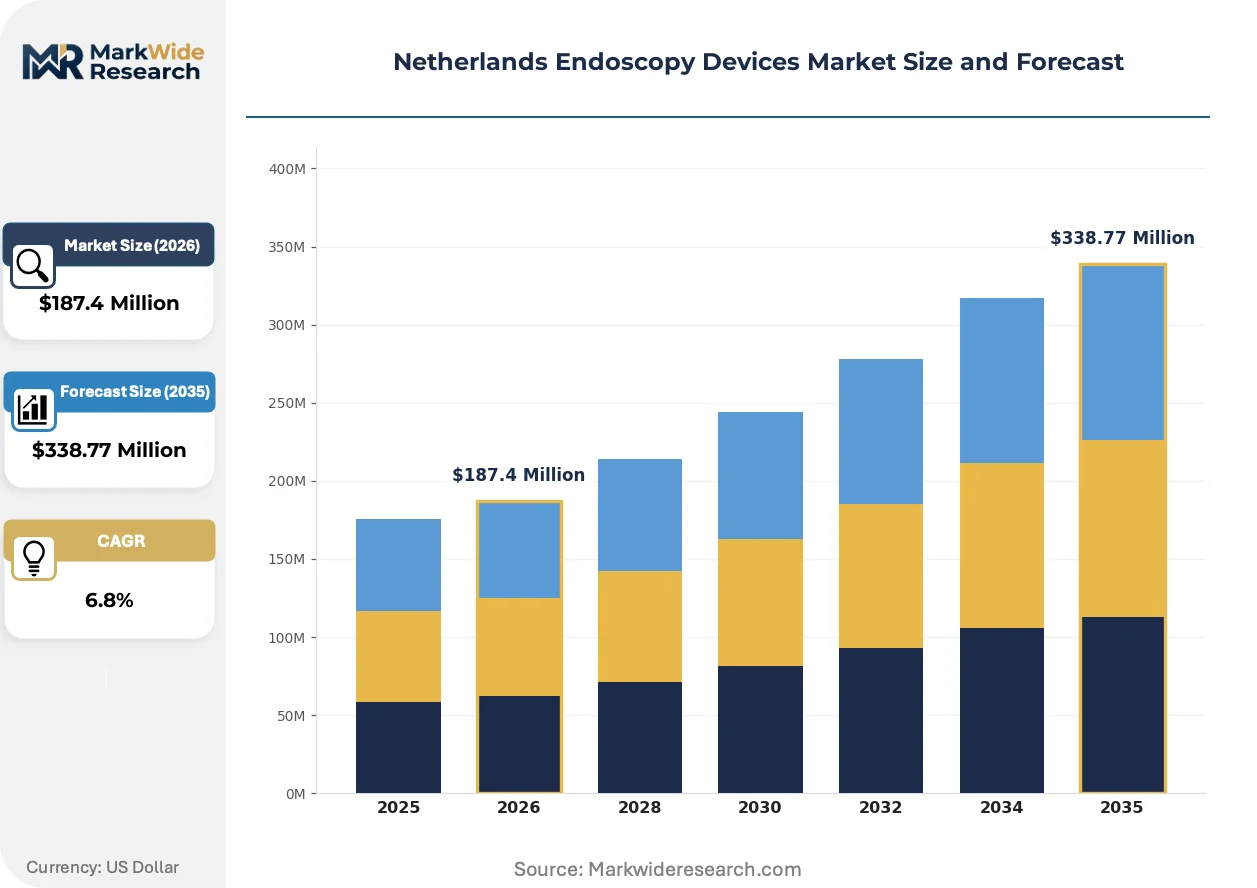
The Netherlands Endoscopy Devices Market is restructuring around MDR compliance deadlines and the sterilization mandate shift from reusable to single-use platforms. Dutch university medical centers drive procurement concentration while regional hospitals face capital rationing.
Growth Catalysts
- MDR Framework Implementation:The EU Medical Device Regulation tightens quality accountability and accelerates replacement cycles for legacy equipment across Dutch hospitals.
- Randstad Hospital Consolidation:University medical centers in Amsterdam, Rotterdam, and Utrecht centralize purchasing power for advanced visualization systems.
- Single-Use Sterilization Mandates:Infection control protocols favor disposable endoscopes, eliminating cross-contamination risk and reducing OR turnaround times.
Market Restraints
- CMOS Sensor Supply Concentration:Image sensor fabrication concentrates in East Asian foundries, exposing Dutch distributors to geopolitical supply disruptions.
- MDR Certification Timelines:Extended conformity assessment periods delay product launches and freeze procurement decisions at mid-sized hospitals.
- Capital Equipment Substitutes:Robot-assisted surgical platforms absorb budget allocations that previously flowed to conventional video endoscopy systems.
Strategic Opportunities
- Regional Hospital Underpenetration:Peripheral facilities in Limburg and Groningen lag Randstad centers in minimally invasive surgical program maturity.
- AI-Enabled Diagnostic Convergence:Real-time computer vision integration with flexible endoscopy platforms creates new reimbursement categories.
- Direct-to-Hospital Distribution:Manufacturers bypass distributor markups through dedicated sales teams serving Dutch academic medical center networks.
Industry Challenges
- Specialized Technician Scarcity:Endoscope repair and reprocessing expertise concentrates in aging workforces without adequate training pipeline replacement.
- Legacy System Integration Friction:New digital platforms require costly adapter bridges to interface with installed base video processors and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Endoscopy Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Devices, Single-Use Devices, Diagnostic Devices, Surgical Devices Technology: Conventional Endoscopy, Capsule Endoscopy, Robot-Assisted Endoscopy, Video Endoscopy End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Procedure Type: Gastrointestinal Procedures, Respiratory Procedures, Urological Procedures, Bariatric Procedures |
| Companies Covered | Olympus Corporation, Medtronic PLC, Johnson & Johnson, Boston Scientific Corporation, Cook Group Incorporated, Fujifilm Holdings Corporation, KARL STORZ, Stryker Corporation, Conmed Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Endoscopy Devices Market Shifts & Advancements
Dutch healthcare providers are reconfiguring endoscopy service delivery around disposable platforms, AI-augmented diagnostics, and consolidated procurement frameworks. Technology trajectories favor elimination of reprocessing infrastructure.
Digital image processing is virtualizing the optical pathway in flexible endoscopy systems. Academic hospitals in Leiden and Nijmegen deploy software-defined visualization to reduce hardware obsolescence. This architecture is virtualizing the traditional distinction between processor units and camera heads, compressing capital replacement cycles.
MDR post-market surveillance requirements impose real-world performance tracking on all CE-marked devices. Dutch manufacturers must maintain clinical evidence registries and report adverse events to the Netherlands Health and Youth Care Inspectorate. High-risk reusable endoscopes face intensified scrutiny, accelerating single-use platform adoption in gastroenterology suites.
Hospital buying groups now aggregate demand across multi-site networks, displacing individual facility procurement autonomy. The eight Dutch university medical centers coordinate technology assessments through joint horizon-scanning committees. This concentration is visible in Randstad corridor purchasing patterns, where standardization agreements lock in preferred vendor relationships for five-year terms.
Netherlands Endoscopy Devices Market Segmentation
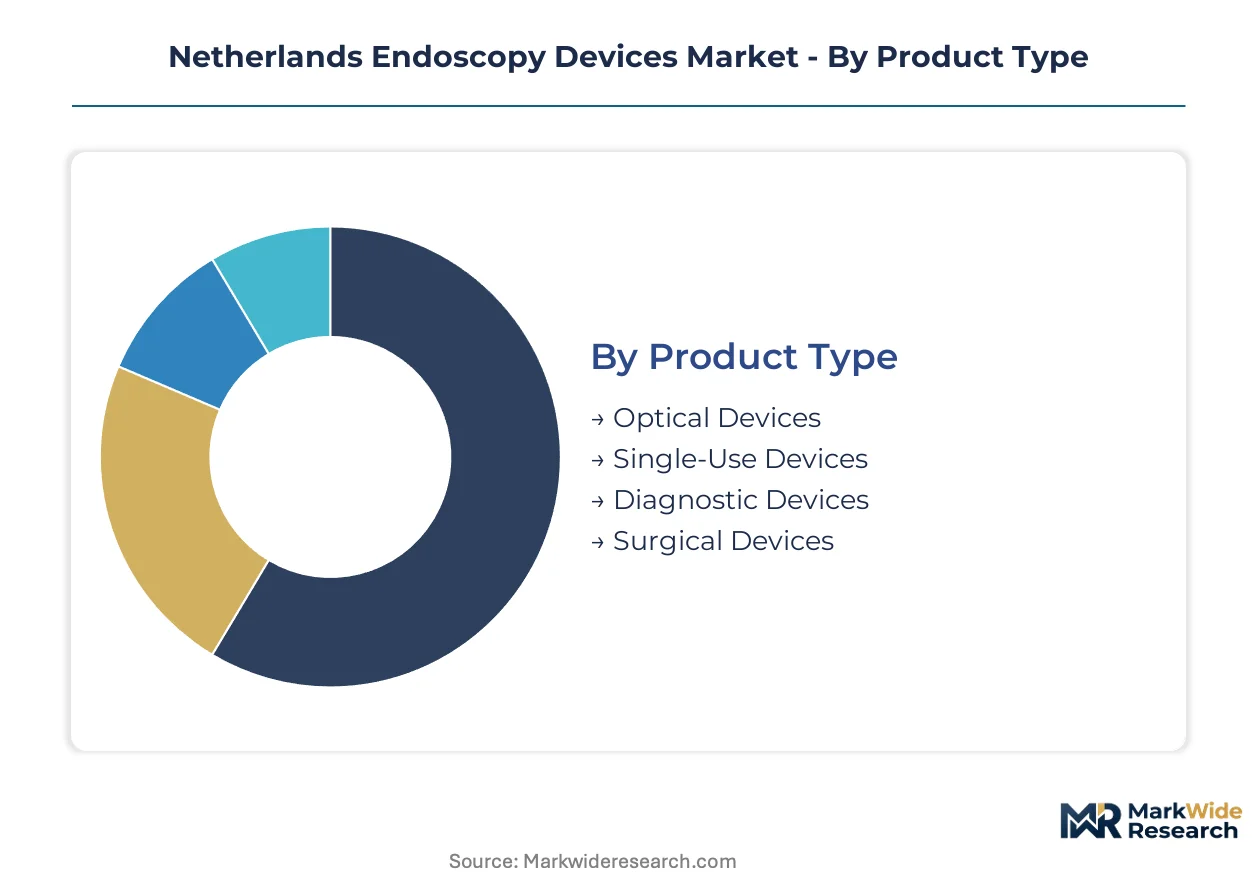
Segmentation in the Dutch endoscopy market reveals distinct procurement rhythms across product lifecycles and care settings. University medical centers in Amsterdam and Rotterdam drive premium technology adoption while regional hospitals lag in replacement velocity.
Product Type:
Replacement cycles stretch from months for disposables to seven-to-ten years for capital equipment, creating divergent revenue recognition patterns across Dutch hospital procurement departments.
- Optical Devices:Fiber-optic and rod-lens systems built from precision-ground glass and sapphire windows deliver core visualization for rigid laparoscopic workflows. Academic centers in Leiden and Nijmegen maintain these platforms for training consistency despite digital migration pressure.
- Single-Use Devices:Polymer-based bronchoscopes and colonoscopes eliminate reprocessing infrastructure while satisfying MDR traceability mandates. Dutch infection control protocols at university hospitals favor these for immunocompromised patient populations.
- Diagnostic Devices:Biopsy forceps, cytology brushes, and specimen retrieval tools constitute high-velocity consumable demand across outpatient endoscopy suites.
- Surgical Devices:Electrosurgical hooks, scissors, and graspers integrate with energy platforms for therapeutic intervention during minimally invasive procedures.
Optical devices anchor the volume base while single-use platforms gain share at the steepest rate.
Technology:
Capital intensity stratifies sharply between installed-base video processors and emerging autonomous platforms requiring entirely new infrastructure commitments from Dutch healthcare providers.
- Conventional Endoscopy:Fiber-optic bundles and halogen illumination persist in budget-constrained regional hospitals across Limburg and Groningen where replacement cycles extend beyond depreciation schedules.
- Capsule Endoscopy:Ingestible camera pills with wireless image transmission enable small-bowel examination without sedation infrastructure. Dutch gastroenterology practices deploy these for Crohn's disease monitoring in outpatient settings.
- Robot-Assisted Endoscopy:Magnetic steering and autonomous navigation systems command premium positioning at Amsterdam UMC and Erasmus MC for complex polyp resection.
- Video Endoscopy:CMOS-based digital platforms with 4K resolution and narrow-band imaging dominate new procurement at Randstad academic centers replacing legacy fiber-optic inventories.
Video endoscopy captures the largest installed base while robot-assisted platforms expand most quickly through dedicated capital allocations.
End User:
Budget authority and procedure complexity determine technology tier access across Dutch healthcare delivery organizations.
- Hospitals:University medical centers and teaching hospitals concentrate advanced visualization procurement through centralized technology assessment committees serving multi-site networks.
- Clinics:Independent gastroenterology practices in Utrecht and Eindhoven drive flexible endoscope volume for routine screening colonoscopy programs.
- Ambulatory Surgical Centers:Specialized day-procedure facilities prioritize single-use platforms to maximize OR throughput and eliminate reprocessing labor costs.
- Research Laboratories:Academic medical center research divisions at Maastricht UMC+ and UMC Utrecht acquire pre-commercial platforms for clinical validation studies.
Hospitals absorb the dominant capital share while ambulatory surgical centers generate the highest disposable utilization intensity per procedure slot.
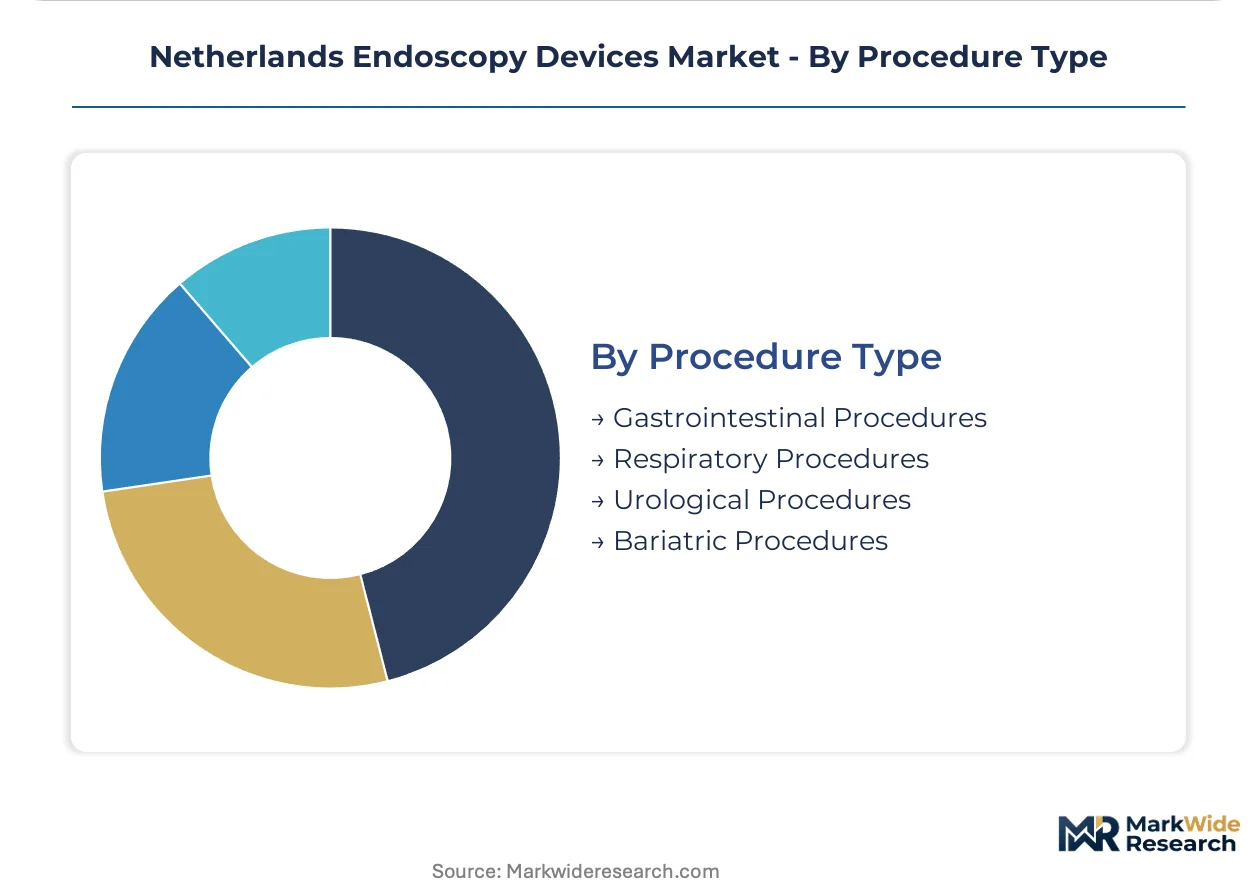
Procedure Type:
Screening program scale and reimbursement density shape device selection across therapeutic domains.
- Gastrointestinal Procedures:Colonoscopy and esophagogastroduodenoscopy constitute the procedural backbone of Dutch endoscopy services with population-based screening programs driving predictable volume.
- Respiratory Procedures:Bronchoscopy for lung cancer staging and interventional pulmonology applications concentrates at specialized thoracic centers in Rotterdam and Groningen.
- Urological Procedures:Cystoscopy and ureteroscopy for hematuria evaluation and stone management distribute across hospital urology departments.
- Bariatric Procedures:Endoscopic sleeve gastroplasty and intragastric balloon placement emerge at metabolic surgery centers addressing obesity-related comorbidity.
Gastrointestinal procedures anchor the volume base while bariatric applications climb the fastest as Dutch health insurers expand metabolic intervention coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University medical centers in Amsterdam, Rotterdam, and Utrecht concentrate procurement authority for advanced visualization systems, while regional hospitals in Limburg and Groningen face capital rationing constraints.
Randstad
Amsterdam UMC and Erasmus MC drive premium technology adoption for complex polyp resection and robot-assisted platforms. The Netherlands Health and Youth Care Inspectorate enforces MDR post-market surveillance requirements across these academic centers. Leiden and Nijmegen academic hospitals deploy software-defined visualization to reduce hardware obsolescence.
Brabant
Eindhoven's high-tech manufacturing ecosystem supplies precision optical components and CMOS sensor integration for endoscope fabrication. Regional hospitals here lag Randstad centers in minimally invasive surgical program maturity. Philips Healthcare spin-offs and medical device suppliers cluster around Eindhoven's Brainport region.
Northern Netherlands
University Medical Center Groningen anchors respiratory endoscopy demand for lung cancer staging and interventional pulmonology. Extended MDR certification timelines freeze procurement decisions at mid-sized hospitals across Friesland and Drenthe. Groningen's medical technology research corridor validates pre-commercial platforms for clinical studies.
Netherlands Endoscopy Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies in Dutch healthcare. Olympus Corporation and Medtronic PLC anchor consolidated positions through direct hospital relationships and integrated surgical ecosystems. Three strategic archetypes dominate: optical heritage specialists, diversified medtech conglomerates, and rigid endoscope pure-plays. M&A activity targets AI-enabled diagnostic capabilities, while strategic partnerships secure CMOS sensor supply from East Asian foundries.
Within the diversified conglomerate tier, Medtronic PLC and Johnson & Johnson occupy positions spanning visualization, energy, and surgical instrumentation. KARL STORZ exemplifies the rigid endoscope specialization archetype for laparoscopic and arthroscopic workflows. Olympus Corporation represents the optical heritage anchor, sustaining dominance in reusable flexible platforms through direct academic medical center relationships. Boston Scientific Corporation and Fujifilm Holdings Corporation sit within the flexible platform and imaging technology vectors respectively.
| Leading Market Players |
|---|
| Olympus Corporation |
| Medtronic PLC |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Cook Group Incorporated |
| Fujifilm Holdings Corporation |
| KARL STORZ |
| Stryker Corporation |
| Conmed Corporation |
| Others |
Supply & Pricing Matrix
Eindhoven's Brainport precision optics cluster channels CMOS sensor integration capacity toward Dutch medical device distributors, translating East Asian fabrication bottlenecks into tiered pricing power for visualization platforms. This geographic concentration of critical component supply enables foundry partners to extract premium positioning while Randstad hospital buying groups leverage procurement scale to compress distributor markups on capital equipment.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement agreements between Dutch university medical centers and device manufacturers, with CMOS sensor pricing volatility passed through via quarterly adjustment clauses. Three-tier pricing structure across premium 4K digital platforms, standard HD video systems, and economy fiber-optic bundles reflects certification grade differentiation under MDR frameworks. Pricing pressure stems from robot-assisted surgical platforms absorbing capital budgets previously allocated to conventional endoscopy. Regional hospitals in Limburg exhibit highest price sensitivity due to extended replacement cycles, while Amsterdam UMC maintains lowest sensitivity through dedicated innovation budgets.
Supply Chain Analysis
Export control regimes restricting advanced semiconductor fabrication equipment to Chinese foundries limit CMOS sensor supply diversification for Dutch endoscope manufacturers. Component sourcing concentrates in Taiwan, South Korea, and Japan for image sensors, with German and Swiss suppliers providing precision optical glass. Supply chain risk centers on single-source vulnerability for 4K CMOS arrays amid geopolitical trade restrictions. Distribution runs through manufacturer-direct sales teams serving academic medical center networks, bypassing traditional distributor channels for capital equipment while consumables flow through specialized medical device wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through the eight Dutch university medical centers coordinating procurement via joint horizon-scanning committees, fragmenting individual hospital autonomy and compressing vendor margins. This consolidation demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Entrench platform dominance through backward integration into CMOS sensor supply partnerships with East Asian foundries, securing allocation priority amid export control friction. Fortify direct hospital relationships by embedding biomedical engineers within Randstad academic center networks, countering emerging AI-enabled diagnostic entrants threatening conventional visualization margins. For New Entrants and Emerging Players: Pursue white-space penetration in peripheral Limburg and Groningen regional hospitals where minimally invasive surgical programs lag Randstad maturity. Target single-use bronchoscope segments for immunocompromised patient protocols at university hospitals, leveraging MDR traceability mandates as regulatory entry pathway. Deploy direct-to-hospital distribution bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core visualization assets amid portfolio rationalization. Long-term viability hinges on AI-augmented diagnostic convergence creating new reimbursement categories. Monitor health technology assessment parity rulings between reusable and disposable platforms as inflection signal for single-use platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR compliance timelines determine market access priority for Dutch hospital procurement cycles. |
| Hospital System Partnership | Direct relationships with Amsterdam UMC and Erasmus MC lock in five-year standardization agreements. |
| Software Companion Development | AI-enabled real-time polyp detection creates new reimbursement categories at Dutch academic centers. |
| Backward Integration into Sensors | CMOS supply partnerships with Taiwanese foundries mitigate geopolitical allocation risk for manufacturers. |
| Reimbursement Strategy | Health technology assessment parity between reusable and disposable platforms shapes procurement decisions. |
Research Methodology
The analysis maps rigid endoscope, flexible platform, single-use disposable, and robot-assisted system sub-sectors, each validated through hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at Dutch notified bodies. Primary intelligence combines with secondary validation from MDR conformity assessment databases, Netherlands Health and Youth Care Inspectorate adverse event registries, hospital procurement records, and CE marking documentation. Bottom-up demand modeling across procedure volumes and capital replacement cycles triangulates with top-down manufacturer revenue attribution.
Assumptions held fixed include MDR enforcement intensity and Randstad hospital consolidation trajectory, while CMOS sensor supply availability and health technology assessment rulings were stress-tested across scenarios. Segmentation dimensions modeled span product lifecycle stage, technology architecture, end-user budget authority, and procedure reimbursement density. CAGRs derive from installed base replacement velocity and disposable utilization intensity per procedure slot. Forecast inputs incorporate Dutch population screening program expansion rates and single-use platform adoption curves in infection control protocols.
Sensitivities concentrate around export control escalation affecting CMOS sensor supply, MDR certification timeline extensions freezing procurement, and health insurer reimbursement policy shifts favoring disposable platforms. Forecasts reflect documented assumptions on technology substitution rates and hospital capital allocation priorities. Material shifts in EU semiconductor trade policy or Dutch health technology assessment methodology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Colonic Stents Market
Endoscopy
China Arthroscopy Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Bronchoscopy Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market