
 Global Dental Bone Graft Substitutes Market | 2026-2036
Global Dental Bone Graft Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Bone Graft Substitutes Market Intelligence
The increasing complexity of alveolar ridge augmentation and sinus lift procedures is repositioning procedural volume from general dental practices toward specialized oral surgery hospitals and centers. Geistlich Pharma AG specializes in regenerative biomaterials, building on its strong scientific heritage in xenografts. Institut Straumann AG leverages its extensive global implant portfolio to drive cross-selling of its bone graft materials. Dentsply Sirona competes through its vast distribution network that supports both private dental practices and larger clinics.
Dental bone graft substitutes are biocompatible materials surgically placed to repair or regenerate bone defects in the jaw. These materials, engineered with specific porosity and controlled resorption rates, act as a scaffold for new bone formation in sites compromised by periodontitis, trauma, or tooth loss. Xenograft and allograft products dominate due to extensive clinical history, while synthetic grafts based on calcium phosphates represent the fastest-growing product type. Granules remain the preferred delivery mode, offering handling versatility for diverse defect morphologies.
Market access requires navigating stringent regulatory pathways, including the FDA's 510(k) clearance process in the United States and CE marking under the EU's Medical Device Regulation (MDR). In China, the NMPA's approval for imported medical devices presents a significant hurdle, while Japan's PMDA has its own distinct requirements. Future competitive advantage depends on developing materials with enhanced osteoinductive properties and securing broader reimbursement coverage from national payers.
Market Dynamics
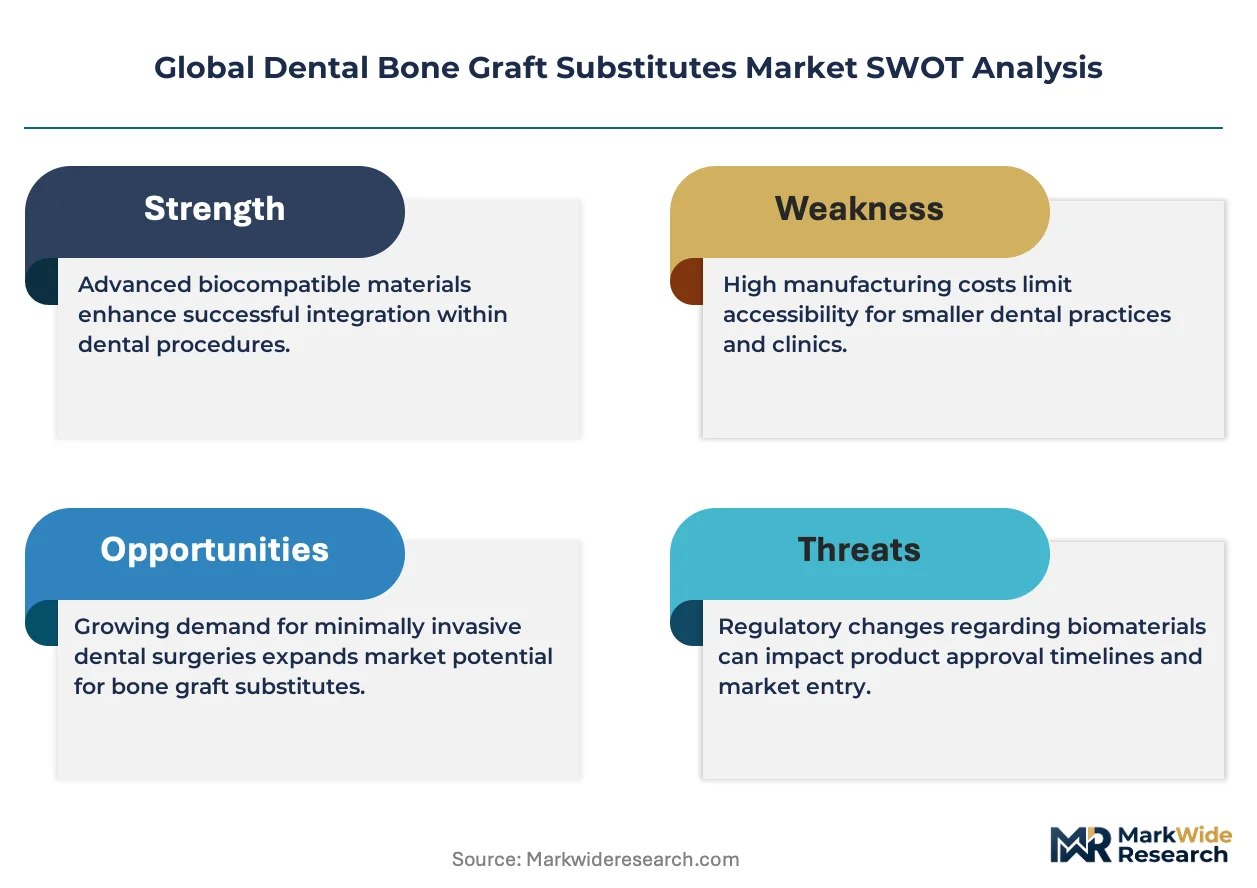
The primary structural force shaping the market is the bifurcation of procedural settings. Rising complexity in alveolar ridge augmentation and sinus lifts is concentrating advanced cases in specialized oral surgery centers, while general dental practices focus on less demanding applications.
Growth Catalysts
- Advanced Synthetic Materials:Development of biocompatible synthetic grafts, such as those based on calcium phosphates, offers a safe and readily available alternative to human or animal-derived materials, meeting demand for predictable clinical outcomes.
- Implant Dentistry Expansion:The increasing prevalence of tooth loss, coupled with patient demand for aesthetic and functional restorations, drives the volume of dental implant procedures that frequently require bone grafting, particularly in Germany and the United States.
- Regulatory Validation:Stringent product approval pathways, including the US FDA's 510(k) process and Europe's CE marking, serve as a quality benchmark, increasing clinician confidence and supporting adoption of cleared products.
Market Restraints
- High Procedural Costs:The significant cost of bone graft materials, especially allografts and certain xenografts, combined with limited or inconsistent reimbursement policies from insurers, can render treatments financially inaccessible for many patients.
- Stringent Regulatory Hurdles:Navigating the complex and lengthy approval processes for imported medical devices, such as those mandated by China's NMPA and Japan's PMDA, creates substantial barriers to entry and delays market access.
- Biological Performance Variability:A key technical limitation is the unpredictable resorption rate of some graft materials, which can fail to synchronize with the body's natural pace of new bone formation, potentially compromising clinical results.
Strategic Opportunities
- Osteoinductive Formulations:Significant opportunity exists in the research and development of grafts with enhanced osteoinductive properties, incorporating growth factors or bioactive molecules to actively stimulate and accelerate bone regeneration.
- Emerging Market Penetration:Expanding distribution networks into markets with improving dental healthcare infrastructure, such as Brazil and Mexico, offers access to a large, underserved patient population requiring dental implant and reconstructive therapies.
- Patient-Specific Grafts:The convergence of 3D printing and medical imaging enables the creation of custom-scaffolded bone grafts tailored to the precise morphology of a patient's bone defect, improving fit and potentially enhancing outcomes.
Industry Challenges
- Specialized Skill Shortages:A deficit of oral surgeons and periodontists trained in advanced bone grafting techniques, particularly for complex vertical and horizontal ridge augmentations, constrains the adoption of more sophisticated procedures and materials.
- Regulatory Compliance Burden:Adherence to the EU's rigorous Medical Device Regulation (MDR) requires substantial investment in clinical data generation and post-market surveillance, posing a significant operational challenge for manufacturers of all sizes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Bone Graft Substitutes Market |
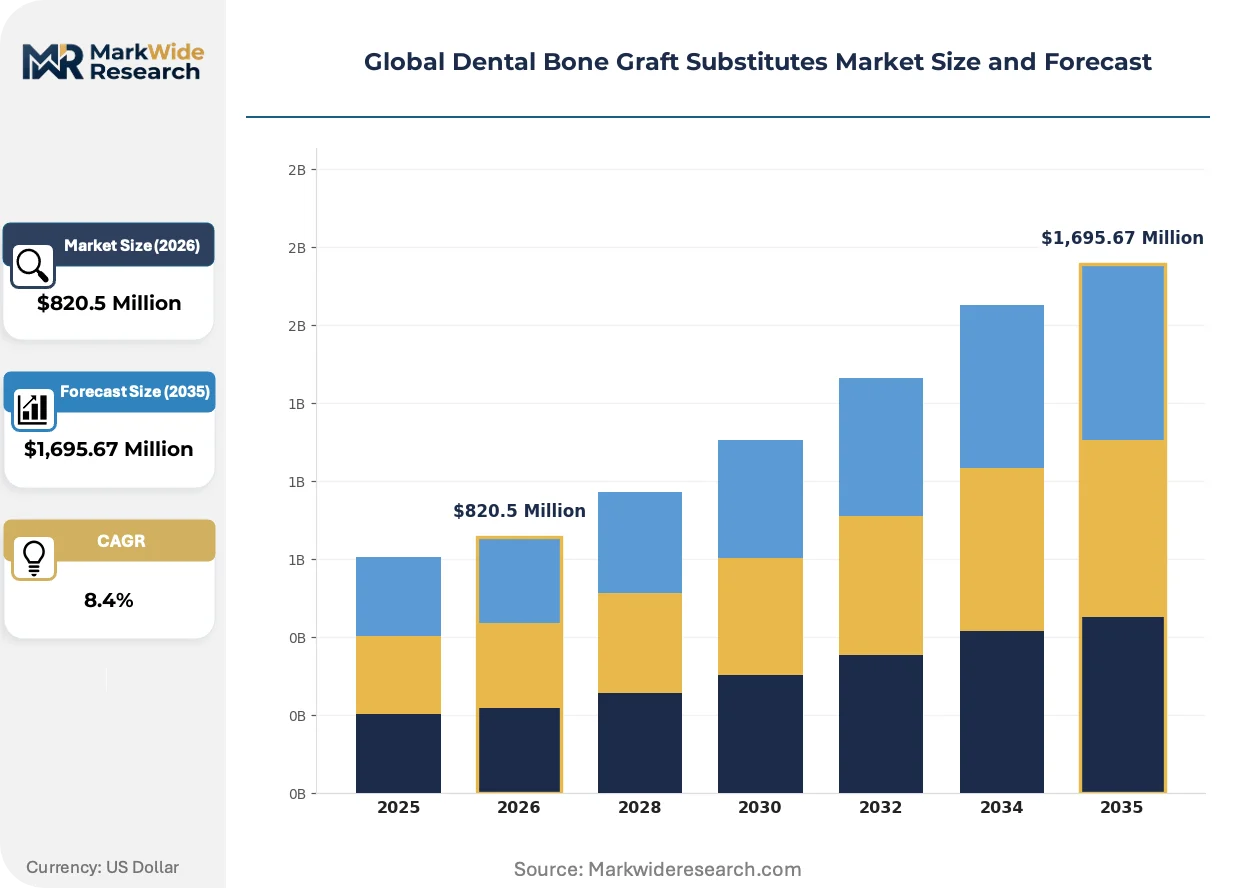
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,695.67 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autograft, Allograft, Xenograft, Synthetic, Composite Application: Periodontal Regeneration, Alveolar Ridge Augmentation, Sinus Lift, Oral & Maxillofacial Surgery, Implant Dentistry End User: Dental Clinics, Specialty Surgery Centers, Academic Research Institutes, Oral Surgery Hospitals, Private Dental Practices Delivery Mode: Granules, Blocks, Putty, Paste, Membranes |
| Companies Covered | Dentsply Sirona, Institut Straumann AG, Medtronic, ZimVie Inc., Geistlich Pharma AG, Envista, Johnson & Johnson, BioHorizons, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Bone Graft Substitutes Market Strategic Shifts & Innovations
The convergence of advanced material science with digital treatment planning is transforming bone graft substitutes from simple void fillers into engineered regenerative solutions. This shift allows for greater clinical precision and more predictable patient outcomes in complex dental reconstruction cases.
Bioactive glass and composite polymer materials provide a resorbable scaffold that actively stimulates osteogenesis by releasing specific ions. Specialized dental hospitals and university clinics are leading the adoption of these materials to improve results in compromised patient sites. This innovation is modularizing the product portfolio, enabling manufacturers to offer grafts with tunable resorption rates and handling properties for specific procedures like socket preservation or sinus floor elevation.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on clinical evidence and supply chain traceability. This regulation forces manufacturers to provide more robust data supporting the safety and performance of their products, especially for those of biological origin. Xenograft and allograft products are most impacted, requiring significant investment in updated clinical trials and quality management systems to maintain CE marking and market access in Europe.
A notable behavioral shift is occurring within large dental service organizations (DSOs) and hospital purchasing groups. These entities are moving from fragmented, single-product orders toward consolidated procurement contracts that bundle bone grafts with dental implants, membranes, and surgical instruments. This trend, most visible in North America, disrupts the traditional sales model focused on individual private practices and favors suppliers with a comprehensive regenerative portfolio.
Global Dental Bone Graft Substitutes Market Segmentation
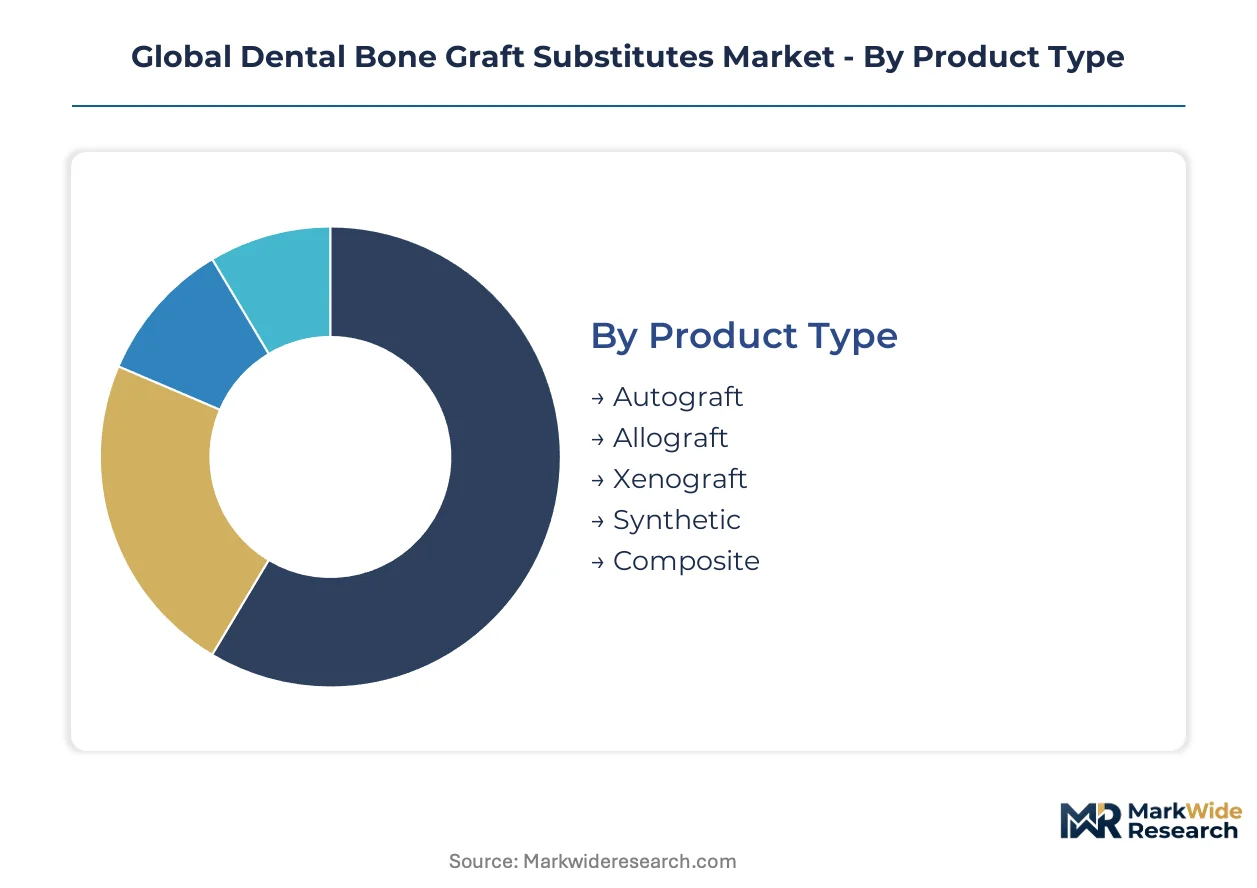
The segmentation of the global dental bone graft substitutes market reveals distinct dynamics influenced by material science, clinical application, and end-user preferences. Understanding these categories is crucial for manufacturers to align product development with regulatory requirements and clinician demand.
Product Type:
Regulatory pathways, such as the US FDA's 510(k) process and Europe's CE marking, significantly influence the market access and adoption of different dental bone graft product types.
- Xenograft:Derived from animal sources, typically bovine or porcine, these grafts are widely used due to their osteoconductive properties and extensive clinical history. Demand for xenografts remains strong in established markets like Germany, driven by predictable clinical outcomes and long-term data.
- Synthetic:These engineered materials, often calcium phosphate-based, offer a readily available and pathogen-free alternative to natural grafts, providing a scaffold for new bone formation. Adoption of synthetic grafts is expanding rapidly in the United States, propelled by advancements in biocompatibility and controlled resorption rates.
- Autograft:Bone harvested from the patient's own body, considered the gold standard for osteoinductivity and histocompatibility.
- Allograft:Processed bone tissue sourced from human cadavers, requiring stringent donor screening and sterilization protocols.
- Composite:Formulations combining two or more graft types, blending their respective advantages for enhanced regenerative potential.
Leading the category by volume: Xenograft. Growing fastest: Synthetic.
Application:
The procedural complexity and anticipated volume of dental applications dictate material selection and surgical approach across the market.
- Implant Dentistry:This application involves grafting to support dental implant placement, often necessitated by insufficient bone volume following tooth loss or trauma. Demand for grafts in implant dentistry is concentrated in countries with high implant penetration, such as South Korea, due to increasing patient acceptance of permanent tooth replacement solutions.
- Alveolar Ridge Augmentation:Procedures aimed at increasing the height or width of the jawbone to accommodate dental implants or improve prosthetic fit, frequently requiring complex grafting techniques. These cases are increasingly referred to specialized oral surgery centers, reflecting the advanced skill set required.
- Periodontal Regeneration:Grafts used to restore bone and supporting tissues lost due to periodontal disease around natural teeth.
- Sinus Lift:A surgical procedure that adds bone to the upper jaw in the area of the molars and premolars, often required before implant placement.
- Oral & Maxillofacial Surgery:Broader surgical interventions addressing trauma, pathology, or congenital defects in the oral and facial regions.
Implant Dentistry represents the largest application volume, while Alveolar Ridge Augmentation exhibits the steepest expansion trajectory.
End User:
End-user procurement patterns vary significantly, driven by case complexity, patient volume, and the ability to manage diversified material inventories.
- Specialty Surgery Centers:These facilities handle complex cases like advanced alveolar ridge augmentations and intricate sinus lifts, requiring a broad portfolio of high-performance graft materials. Their procurement decisions often prioritize clinical efficacy and material versatility.
- Private Dental Practices:General dental practices primarily manage less complex bone grafting procedures, such as socket preservation following tooth extraction. Their purchasing behavior is often influenced by ease of use and cost-effectiveness for routine applications.
- Dental Clinics:Facilities offering a range of dental services, including some grafting procedures, often balancing cost with clinical necessity.
- Oral Surgery Hospitals:Tertiary care centers that manage the most challenging reconstructive cases, integrating advanced imaging and surgical techniques.
- Academic Research Institutes:Institutions focused on developing and testing novel bone graft materials and surgical protocols, influencing future market trends.
High-volume procurement concentrates in Specialty Surgery Centers, and Private Dental Practices show the fastest growth in adopting new material forms.
Delivery Mode:
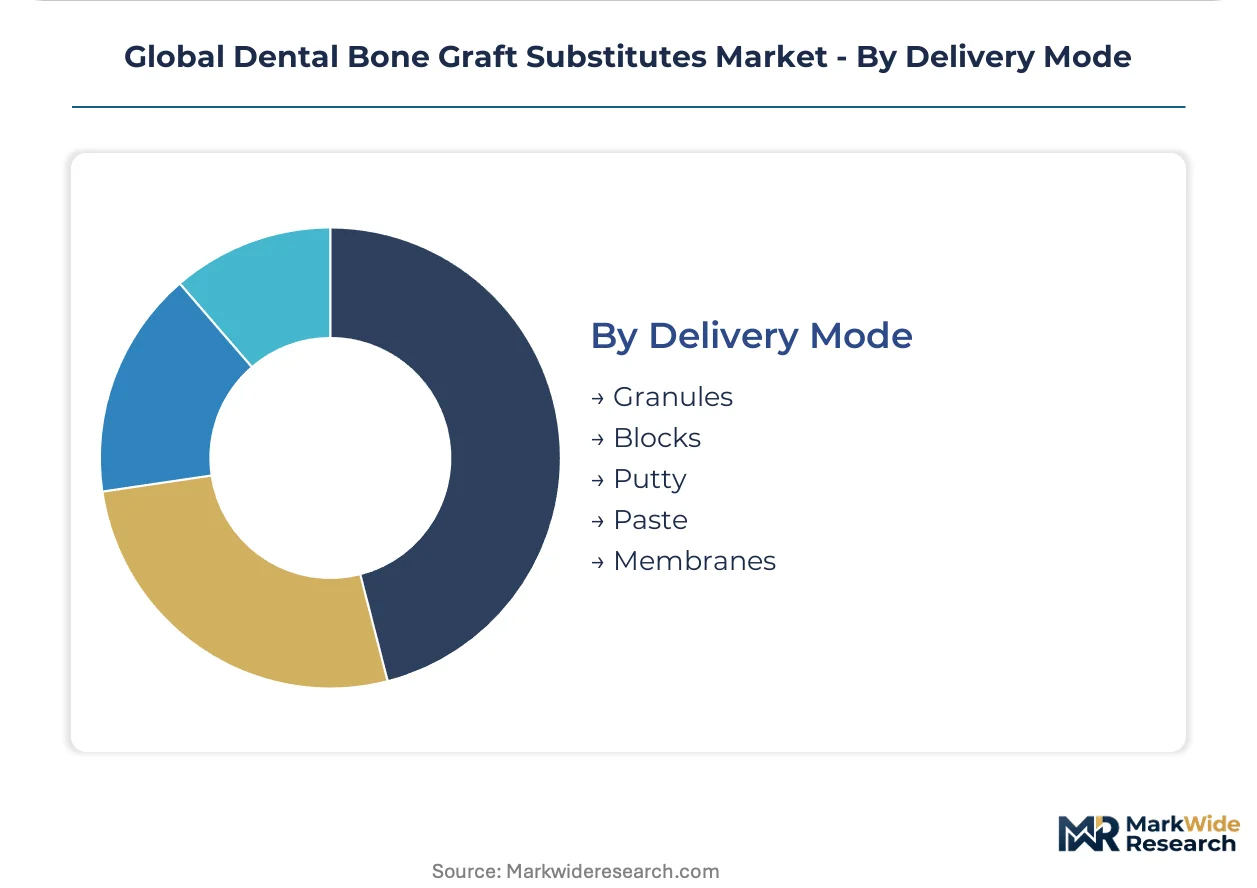
The physical form factor of bone graft substitutes directly impacts surgical handling, application versatility, and integration into diverse defect morphologies.
- Granules:Small particles of bone graft material that can be packed into various defect shapes, offering high adaptability and surface area for cellular attachment. Granules are the preferred delivery mode due to their handling versatility for diverse defect morphologies in general dentistry.
- Blocks:Pre-formed, solid pieces of graft material used for large volume defects or structural augmentation, offering dimensional stability. Demand for blocks is notable in specialized oral surgery hospitals for extensive reconstructive cases.
- Putty:A malleable and cohesive form of graft material, providing excellent handling characteristics and conforming to irregular defect sites.
- Paste:Injectable or extrudable formulations that offer ease of application and good adaptation within confined spaces.
- Membranes:Used in guided bone regeneration to create a barrier, protecting the graft and guiding tissue growth.
Granules remain the most frequently utilized form, with Putty and Paste gaining share fastest due to enhanced handling properties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in regions such as Minnesota's Medical Alley drives significant innovation within the global dental bone graft substitutes market. This hub, alongside other specialized medical device clusters, fosters advanced material development and clinical adoption across multiple geographies.
United States
High implant dentistry prevalence drives demand for bone graft substitutes in the United States. The FDA's 510(k) clearance process ensures product quality and clinician confidence. Boston's biotech corridor fosters significant research and development in new graft formulations. This region remains a primary market for advanced regenerative solutions.
Germany
Germany exhibits robust demand for dental bone graft substitutes, supported by its mature implant dentistry market. CE marking under the EU's Medical Device Regulation ensures stringent product oversight. The Medical Valley EMN region concentrates leading manufacturers and research institutions. This concentration drives continuous innovation in biomaterials.
South Korea
South Korea shows substantial growth in dental implant procedures, directly boosting bone graft substitute consumption. The MFDS approval process guides market entry for medical devices. The Daegu-Gyeongbuk Medical Cluster supports local manufacturing and clinical trials. This area is a key hub for advanced dental solutions.
Japan
Japan's aging demographic contributes to a steady demand for restorative dental procedures requiring bone grafts. The PMDA mandates rigorous clinical evidence for product approval. Tokyo's medical device industry serves as a center for innovation and distribution. This market prioritizes high-quality, clinically validated materials.
United Kingdom
The United Kingdom's expanding private dental sector fuels demand for bone graft substitutes. The MHRA ensures medical device safety and performance standards. London's specialized dental clinics adopt advanced grafting techniques and materials. This market segment emphasizes aesthetic and functional outcomes.
Global Dental Bone Graft Substitutes Market Key Industry Players
Top-tier vendors anchor the premium segment of the global dental bone graft substitutes market, while specialized mid-sized companies focus on niche applications. The market exhibits a tiered structure, with established players leveraging broad portfolios and smaller innovators introducing advanced formulations. Strategic archetypes include diversified dental solution providers and biomaterial specialists. Companies are primarily engaging in portfolio diversification and strategic partnerships to expand their market reach.
Within the diversified dental solution provider archetype, Dentsply Sirona, a US-based corporation, leverages its extensive distribution network across private dental practices and larger clinics. Institut Straumann AG, a Swiss-based AG, exemplifies a comprehensive implant portfolio approach, driving cross-selling opportunities for bone graft materials. Geistlich Pharma AG, another Swiss-based AG, anchors the specialized biomaterials segment, building on its strong scientific heritage in xenografts. These entities collectively shape product innovation and market access across various end-user segments.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Institut Straumann AG |
| Medtronic |
| ZimVie Inc. |
| Geistlich Pharma AG |
| Envista |
| Johnson & Johnson |
| BioHorizons |
| Henry Schein |
Cost & Logistics Intelligence
Consolidated procurement contracts from large dental service organizations (DSOs) and hospital purchasing groups are reshaping supplier strategies, driving a shift towards bundled offerings and influencing pricing negotiations across the dental bone graft substitutes market.
Pricing Analysis
Premium pricing often applies to bone graft materials available for immediate delivery, reflecting the urgency of clinical needs. Transactional pricing dominates for routine orders, while long-term contracts with large institutions feature volume discounts. Price differentiation stems from the quality grade, often validated by stringent FDA 510(k) clearances and CE marking, alongside brand premium established by companies like Geistlich. Pricing pressure stems from inconsistent reimbursement policies from insurers, particularly impacting patient access in less developed healthcare systems. Private dental practices typically exhibit higher price sensitivity compared to specialized oral surgery centers handling complex, high-value procedures.
Supply Chain Analysis
Domestic-content mandates in certain regions, such as NMPA requirements in China, are reshaping sourcing strategies for global manufacturers. Geographic supply concentration for advanced biomaterials includes Germany, Switzerland, and the United States, reflecting established R&D and manufacturing capabilities. The market draws from key raw material dependencies like bovine and porcine tissue for xenografts and specific calcium phosphates for synthetic alternatives. Regulatory restriction, particularly navigating diverse national approval pathways, presents a structural supply chain risk. Distribution runs through extensive networks supporting both private practices and larger clinics, increasingly managed through direct sales for specialized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players actively pursuing comprehensive regenerative portfolios as a key downstream lever to control product bundling and market access.
For Market Incumbents: Anticipate continued pressure from stringent regulatory compliance, particularly the EU's Medical Device Regulation, by investing heavily in clinical data generation and post-market surveillance. Diversify product portfolios to offer complete regenerative solutions, bundling grafts with membranes and implants to counter single-product procurement shifts. Focus R&D on advanced osteoinductive formulations to maintain a technological edge against emerging synthetic materials. Strengthen distribution networks in high-growth implant dentistry markets like South Korea.
For New Entrants and Emerging Players: Capture white space in emerging markets such as Brazil and Mexico, where dental healthcare infrastructure is improving and demand for implant therapies is rising. Target patient-specific grafts enabled by 3D printing, offering customized solutions for complex defect morphologies. A strong go-to-market angle involves developing cost-effective synthetic materials with predictable clinical outcomes. Focus on securing initial adoption within private dental practices, which show the fastest growth in embracing new material forms due to ease of use.
For Investors and Strategic Acquirers: The window for entry favors specialized biomaterial innovators with strong intellectual property in enhanced osteoinductive formulations, offering long-term viability over the next 5-10 years. Seek companies demonstrating robust clinical evidence for their products, particularly those navigating complex regulatory approvals like CE marking under MDR. The signal to watch is broadened reimbursement coverage from national payers, which will significantly expand market accessibility and drive adoption of advanced graft technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation | Supports CE marking and FDA clearance, enhancing clinician confidence and market access. |
| Geographic Expansion | Penetrates underserved emerging markets like Brazil, capturing new patient populations. |
| Osteoinductive Formulations | Develops advanced grafts that actively stimulate bone regeneration, improving patient outcomes. |
| Consolidated Procurement Partnerships | Secures bundled contracts with DSOs and hospital groups, optimizing sales and distribution. |
| Patient-Specific Graft Development | Leverages 3D printing for custom solutions, addressing unique patient anatomical needs. |
Research Approach
Independent corroboration across industry whitepapers, regulatory filings, and academic research underwrites the qualitative findings within this study. The analysis integrates insights from primary interviews with oral surgeons, periodontists, dental practice owners, and hospital procurement managers. Secondary validation draws from FDA 510(k) clearances, CE marking registries, NMPA approvals, and PMDA guidelines. This approach enables a comprehensive understanding through bottom-up and top-down triangulation.
The forecast framework anchored the modeling period to historical reference periods, ensuring data consistency across the analysis window. Segmentation dimensions modeled include product type, application, end user, and delivery mode, alongside industry-specific material compositions like calcium phosphate. Compound annual growth rates were derived from a synthesis of historical trends and projected future demand. Key forecast inputs include dental implant procedure volumes and regulatory approval rates for novel bone graft materials.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory changes and shifts in reimbursement policies. Forecasts reflect assumptions regarding technological advancements and market dynamics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Calipers Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Nano Dentistry Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Chile Dental Devices Market
Dental Devices
US Orthodontics Market