
 Auto-Disable Syringes Market | 2026-2036
Auto-Disable Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Auto-Disable Syringes Market Outlook
WHO prequalification standards are repositioning the cost-of-entry calculus for auto-disable syringe manufacturers, forcing upstream investments in sterile filling capacity and biocompatibility testing. BD leverages its integrated manufacturing footprint across multiple continents to sustain volume commitments to UNICEF and PAHO procurement frameworks. Hindustan Syringes & Medical Devices Ltd anchors its competitive stance through cost-optimized mechanical auto-disable designs purpose-built for high-volume national immunization schedules.
Auto-disable syringes incorporate an irreversible locking mechanism—typically a metal clip or frangible plunger rod—that activates upon full depression, rendering the device non-reusable and mitigating needle-stick injury risk; most units utilize polypropylene barrels and latex-free elastomeric stoppers sterilized via ethylene oxide or gamma irradiation, with dead volumes calibrated below 0.05 mL for precise dose delivery in vaccine administration. Safety syringes dominate current procurement volumes due to their balance of unit economics and clinician familiarity, while prefilled auto-disable formats are capturing disproportionate investment as pharmaceutical companies seek to integrate drug-device combination products for insulin delivery and biologics. Mechanical auto-disable technology occupies the largest installed base, though integrated features combining needle retraction with dose verification are gaining traction in hospital settings where liability exposure drives specification upgrades.
FDA enforcement of needle-stick prevention mandates under the Bloodborne Pathogens Standard shapes US hospital purchasing criteria, while EMA's Medical Device Regulation and WHO prequalification protocols collectively define the compliance frontier for export-oriented manufacturers. India's CDSCO and BIS certification requirements are tightening for imported safety devices, creating localization incentives that favor domestic producers with in-house molding and sterilization assets. Stakeholders must monitor the divergence between mechanical reliability standards in emerging markets and the sensor-integration specifications gaining ground in European and North American institutional procurement.
Market Dynamics
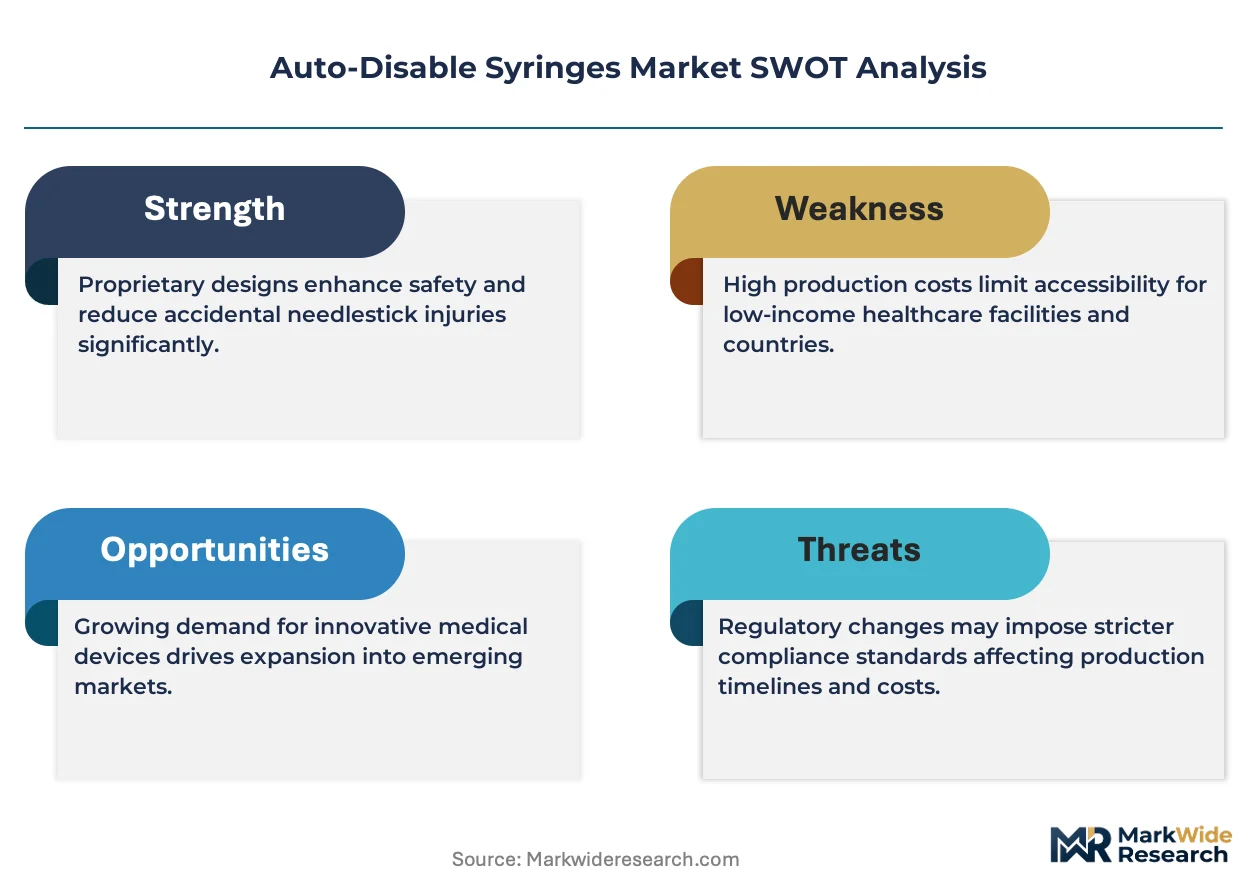
WHO prequalification mandates are compressing the supplier base for auto-disable syringes, forcing manufacturers to absorb sterilization validation costs and biocompatibility documentation burdens that smaller molders cannot sustain.
Growth Catalysts
- Immunization program scale-up:Sub-Saharan African ministries of health are consolidating vaccine procurement under Gavi co-financing frameworks, creating pooled demand for safety-engineered injection devices.
- EMA Medical Device Regulation:MDR Class IIa reclassification of auto-disable syringes is accelerating CE-marked product registrations among export-oriented manufacturers seeking European hospital access.
- Domestic production incentives:India's PLI scheme for medical devices is subsidizing cleanroom expansion and ethylene oxide sterilization capacity for local safety syringe producers.
Market Restraints
- Polypropylene resin volatility:Medical-grade polymer feedstock prices fluctuate with crude oil benchmarks, compressing margin buffers for high-volume disposable manufacturers.
- Sterilization asset concentration:Gamma irradiation capacity clusters in Belgium and the United States, creating logistics bottlenecks for Asian producers seeking WHO prequalification.
- Mechanical reliability thresholds:Frangible plunger rod failure rates above 0.1% trigger batch rejection under UNICEF technical specifications, disqualifying lower-tier molders.
Strategic Opportunities
- Prefilled combination products:Insulin and biologic drug-device integration is opening specification windows for auto-disable syringes with integrated needle shields and dose verification features.
- CDSCO fast-track pathways:India's streamlined regulatory review for safety-engineered devices reduces time-to-market for domestic manufacturers with BIS-certified molding operations.
- Direct government contracting:National immunization programs in Indonesia and Nigeria are bypassing distributor networks, enabling margin capture through tender participation.
Industry Challenges
- Sterile filling technician scarcity:Aseptic processing expertise concentrates in pharmaceutical hubs, forcing syringe manufacturers to poach talent or invest in six-month certification programs.
- Biocompatibility testing backlogs:ISO 10993 cytotoxicity and sensitization studies face 14-week queues at accredited laboratories, delaying WHO prequalification submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto-Disable Syringes Market |
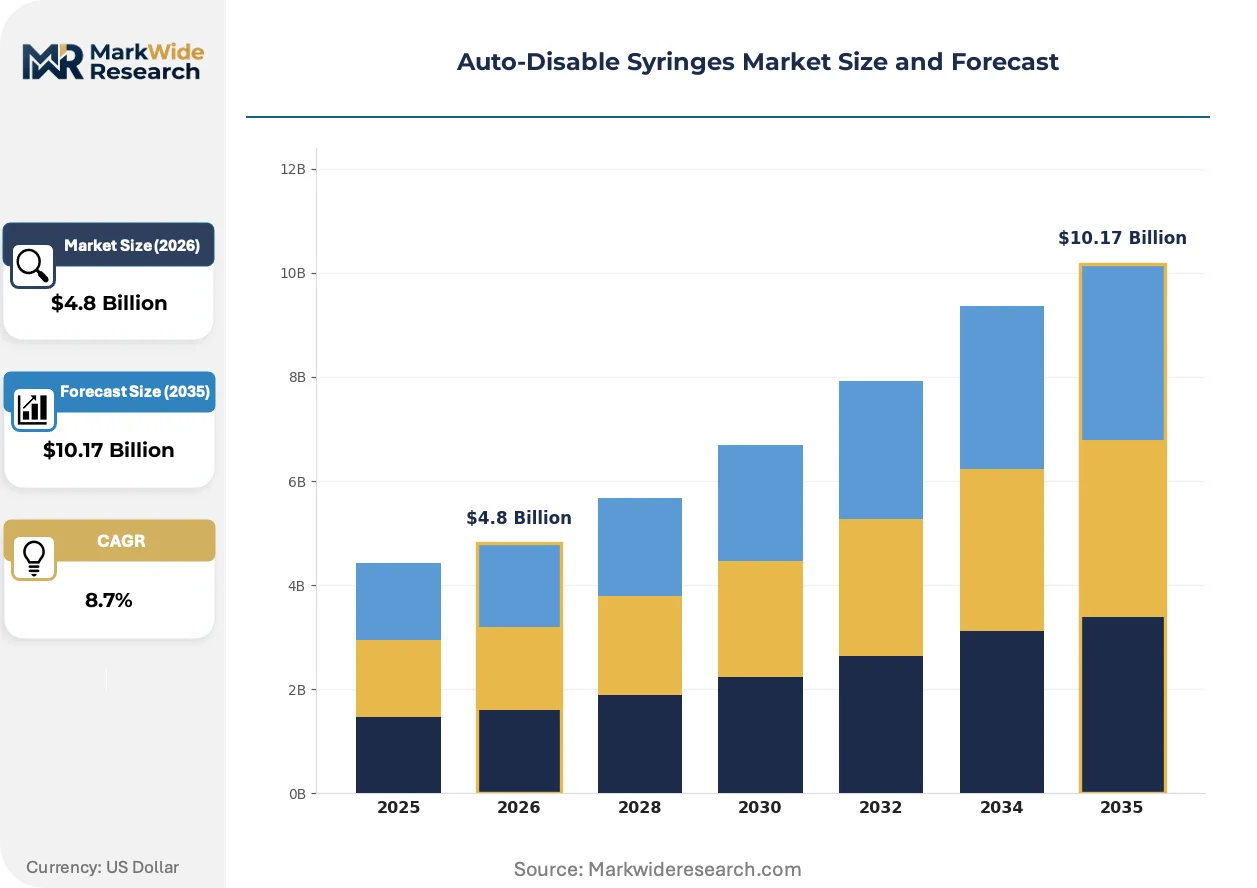
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Safety Syringes, Prefilled Syringes, Reusable Syringes End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies Technology: Mechanical Auto-Disable, Electronic Auto-Disable, Integrated Features, Single-Use Design Application: Vaccination, Insulin Delivery, Anesthesia, Pain Management |
| Companies Covered | BD, Terumo Corporation, Hindustan Syringes & Medical Devices Ltd, Nipro Corporation, B. Braun SE, Smiths Group plc, Medtronic, Retractable Technologies, Inc., ISCON SURGICALS LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto-Disable Syringes Market Strategic Shifts
Device intelligence and materials science are reshaping auto-disable syringe architectures, with sensor integration and sustainable polymers displacing conventional mechanical designs in premium procurement segments.
Needle retraction mechanisms is converging with dose verification electronics in hospital-grade auto-disable syringes. Tertiary care institutions in Germany and Japan are piloting RFID-enabled units that log injection events to electronic health records. This convergence is compressing the addressable market for purely mechanical safety devices to commodity immunization settings.
REACH restrictions on phthalate plasticizers are compelling elastomer reformulation for syringe stoppers and plunger tips. Compounders serving European device manufacturers are certifying thermoplastic elastomer alternatives to latex and PVC. Injection molders with validated cleanroom lines are absorbing reformulation costs to maintain EMA-registered device submissions.
Consolidated tendering by multilateral procurement agencies is displacing fragmented national purchasing. UNICEF Supply Division and PAHO Revolving Fund are harmonizing technical specifications around ISO 7886-4 compliance, forcing regional distributors to cede margin to direct manufacturer relationships. This concentration is most visible in Sub-Saharan Africa, where Gavi-eligible countries are pooling demand under single-source framework agreements.
Auto-Disable Syringes Market Segmentation
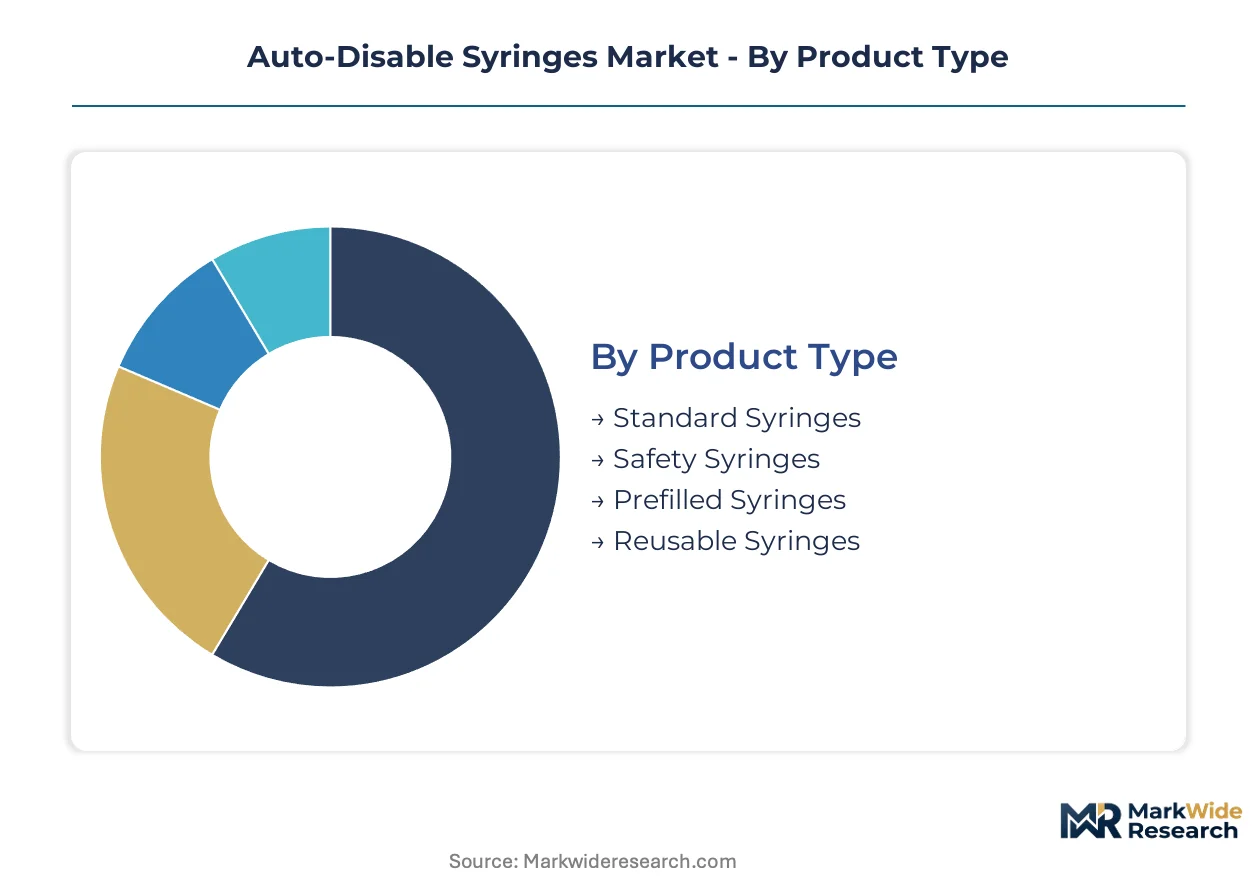
Auto-disable syringe procurement splits across four distinct dimensions, each carrying divergent compliance burdens and margin structures. WHO prequalification requirements, EMA MDR classifications, and national immunization tender specifications create tiered barriers that reshape competitive positioning within each segment category.
Product Type:
WHO prequalification demands escalate from basic ISO 7886 compliance for standard units through combination product filings for prefilled formats requiring pharmaceutical partnership documentation.
- Safety Syringes:These units balance mechanical auto-disable reliability with unit economics suited to high-volume Gavi procurement frameworks. UNICEF Supply Division tenders concentrate demand in Sub-Saharan African national immunization programs where frangible plunger rod designs dominate specifications.
- Prefilled Syringes:Drug-device combination products integrating insulin or biologic formulations require EMA MDR Class IIa registration plus pharmaceutical sponsor quality agreements. European hospital systems and Japanese tertiary care institutions drive specification windows for needle shield integration and dose verification electronics.
- Standard Syringes:Basic polypropylene barrel configurations with metal clip locking mechanisms serve emerging market commodity procurement.
- Reusable Syringes:Limited commercial presence outside specialized veterinary and research applications due to infection control liability exposure.
Leading the category by volume: Safety Syringes. Growing fastest: Prefilled Syringes.
End User:
Customer procurement sophistication spans from centralized multilateral tendering through direct hospital contracting to retail pharmacy channels with diverging technical specifications.
- Hospitals:Tertiary care institutions in Germany and Japan specify integrated needle retraction with electronic dose logging. FDA Bloodborne Pathogens Standard enforcement shapes US hospital purchasing criteria toward liability-minimizing device architectures.
- Clinics:Outpatient vaccination centers in India and Indonesia prioritize cost-optimized mechanical auto-disable designs under government tender participation.
- Home Care:Patient self-administration of insulin drives demand for prefilled formats with intuitive locking feedback.
- Pharmaceutical Companies:Drug-device combination product sponsors require sterile filling capacity and biocompatibility documentation for regulatory submissions.
Procurement volume concentrates in Hospitals. Steepest expansion trajectory: Pharmaceutical Companies.
Technology:
Patent landscapes and manufacturing asset requirements fragment competitive intensity across mechanical, electronic, and hybrid architectures.
- Mechanical Auto-Disable:Metal clip and frangible plunger rod mechanisms occupy the largest installed base. India's domestic manufacturers anchor production through cost-optimized designs purpose-built for CDSCO and BIS certification pathways.
- Integrated Features:Needle retraction combined with dose verification sensors commands premium positioning in European and North American institutional procurement.
- Electronic Auto-Disable:RFID-enabled injection event logging remains pilot-stage in German and Japanese hospital systems.
- Single-Use Design:Irreversible locking without reuse capability constitutes baseline WHO prequalification requirement across all procurement frameworks.
Volume leadership: Mechanical Auto-Disable. Technology investment intensity: Integrated Features.
Application:
Dose precision requirements and injection frequency patterns differentiate specification priorities across therapeutic categories.
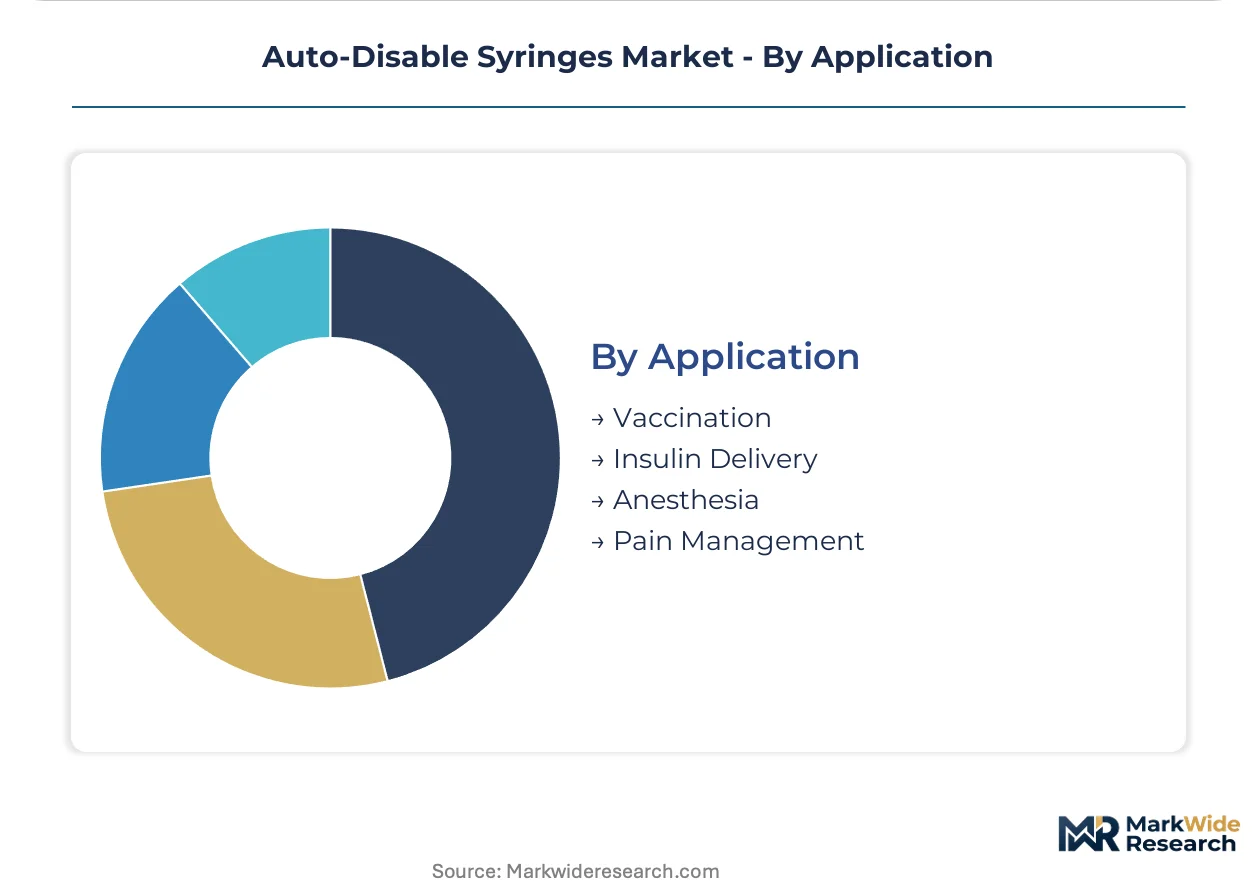
- Vaccination:Mass immunization campaigns in Sub-Saharan Africa and South Asia specify dead volumes below 0.05 mL for precise antigen delivery. Gavi co-financing frameworks consolidate demand under UNICEF technical specifications.
- Insulin Delivery:Chronic disease management drives prefilled format preference with integrated needle shields for patient safety.
- Anesthesia:Operating room environments specify rapid-activation locking mechanisms with clinician tactile feedback.
- Pain Management:Opioid delivery applications face heightened diversion control requirements in US institutional settings.
Procurement scale leader: Vaccination. Application segment climbing fastest: Insulin Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement volume for auto-disable syringes through government immunization tenders, while Sub-Saharan African ministries pool demand under multilateral frameworks. Manufacturing clusters span sterile filling sites in Belgium, gamma irradiation facilities in the United States, and domestic molding operations in Gujarat and Haryana.
United States
FDA enforcement of the Bloodborne Pathogens Standard drives hospital procurement toward needle-stick prevention devices. The agency's device classification rules shape domestic manufacturing compliance costs. Gamma irradiation capacity clusters in Illinois and California, creating sterilization bottlenecks for Asian exporters seeking US market entry.
India
Domestic production capacity is expanding through CDSCO fast-track pathways and PLI scheme subsidies for cleanroom assets. BIS certification requirements for imported safety devices are tightening, favoring local molders with in-house ethylene oxide sterilization. Manufacturing concentrates in Haryana's Faridabad-Gurgaon corridor and Gujarat's Ahmedabad-Sanand belt.
Germany
EMA Medical Device Regulation Class IIa reclassification is accelerating CE-marked registrations for export-oriented manufacturers. REACH restrictions on phthalate plasticizers are forcing elastomer reformulation for European device submissions. Tertiary care institutions in Berlin and Munich are piloting RFID-enabled injection event logging systems.
Brazil
ANVISA's medical device registration pathways are harmonizing with PAHO technical specifications for safety-engineered injection devices. National immunization program scale-up is consolidating procurement under federal tender frameworks. Production assets concentrate in São Paulo state's medical device corridor, with sterilization validation partnerships extending to Argentine facilities.
Nigeria
Federal Ministry of Health tenders are bypassing distributor networks for direct manufacturer contracting under Gavi co-financing arrangements. WHO prequalification compliance is filtering supplier participation in national vaccine campaigns. Cold chain infrastructure investments in Lagos and Kano are expanding last-mile delivery capacity for temperature-sensitive auto-disable units.
Auto-Disable Syringes Market Competitive Environment
Indian producers anchor the cost-optimized tier for high-volume immunization procurement; European and Japanese specialists hold premium positioning in institutional safety device segments. The supplier base compresses under WHO prequalification sterilization validation burdens that disqualify smaller molders. Three archetypes dominate: integrated multinationals with UNICEF framework agreements, domestic champions with government tender specialization, and retractable-needle technology licensors. Capacity expansion and biocompatibility documentation partnerships represent the dominant competitive moves.
Within the integrated multinational tier, BD exemplifies manufacturers sustaining volume commitments across multiple continental production footprints. Terumo Corporation occupies a position among Japanese specialists with hospital-grade safety device portfolios. Hindustan Syringes & Medical Devices Ltd anchors the domestic champion archetype through CDSCO-certified operations purpose-built for national immunization scale.
| Leading Market Players |
|---|
| BD |
| Terumo Corporation |
| Hindustan Syringes & Medical Devices Ltd |
| Nipro Corporation |
| B. Braun SE |
| Smiths Group plc |
| Medtronic |
| Retractable Technologies, Inc. |
| ISCON SURGICALS LTD. |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification mandates for sterile filling capacity and biocompatibility documentation are compressing the supplier base, forcing manufacturers to absorb fixed validation costs that reshape pricing power toward integrated producers with UNICEF framework agreements.
Pricing Analysis
Volume-margins split sharply between commodity immunization procurement and premium institutional segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EMA MDR Class IIa registration commanding substantial premia over basic ISO 7886 compliance. Cost compression in the economy tier intensifies as Indian domestic manufacturers scale CDSCO-certified operations for government tenders. National immunization programs in Sub-Saharan Africa exhibit highest price sensitivity; Japanese tertiary care institutions show lowest sensitivity due to liability-driven specification requirements.
Supply Chain Analysis
Reverse-logistics flows remain minimal given single-use device classification, though batch rejection protocols for frangible plunger rod failure rates above 0.1% create quality-control feedback loops. Manufacturing concentrates in India, Belgium, and the United States, with gamma irradiation capacity clustering in Illinois and California. Polypropylene resin and medical-grade elastomeric stoppers anchor raw material dependencies. Single-source vulnerability in gamma sterilization infrastructure creates supply chain risk. Distribution runs through UNICEF Supply Division and PAHO Revolving Fund for pooled procurement, with direct manufacturer contracting gaining share in Nigeria and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification standards function as a cost-of-compliance moat, filtering supplier participation through sterilization validation burdens that smaller molders cannot sustain and consolidating competitive advantage among integrated multinationals.
For Market Incumbents: Cement framework agreement positioning by expanding ethylene oxide sterilization capacity in Gujarat and Haryana manufacturing corridors to capture PLI scheme subsidies. Defend against retractable-needle technology licensors by accelerating integrated sensor development for dose verification electronics in European hospital procurement. Prioritize biocompatibility documentation partnerships to reduce ISO 10993 testing backlogs. For New Entrants and Emerging Players: Enter via CDSCO fast-track pathways for safety-engineered devices, targeting India's domestic tender participation where BIS certification requirements disadvantage imports. Focus on prefilled combination products for insulin delivery, where pharmaceutical sponsor partnerships create specification windows absent incumbent lock-in. Pursue direct contracting with Indonesia's national immunization program bypassing distributor networks. For Investors and Strategic Acquirers: The window for entry favors domestic champions with government tender specialization and in-house molding assets over pure-play technology licensors. Long-term viability hinges on sterilization capacity ownership rather than outsourced validation. Monitor WHO prequalification submission queues as inflection indicator for supplier base compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Submission | UNICEF Supply Division tenders require prequalification compliance for pooled African procurement frameworks. |
| EMA MDR Class IIa Registration | CE marking unlocks European hospital access for prefilled drug-device combination products. |
| Domestic Cleanroom Expansion | India's PLI scheme subsidizes ethylene oxide sterilization capacity for CDSCO-certified producers. |
| Pharmaceutical Partnership Agreement | Drug-device integration for insulin and biologics opens premium specification windows. |
| Gamma Irradiation Capacity Addition | Belgium and United States capacity clusters create logistics bottlenecks for Asian exporters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital procurement managers, biomedical engineers, GPO contracts specialists, and sterile filling technicians. WHO prequalification databases, CDSCO submission records, UNICEF tender documentation, and gamma irradiation facility certifications provided validation layers. Bottom-up manufacturer capacity assessments triangulated against top-down immunization program procurement forecasts.
Granularity-level modeling disaggregated volume and value across the projection horizon by product type, end user, technology architecture, and application, with regional regulatory clusters and national tender frameworks as cross-cutting dimensions. CAGRs derived from immunization program scale-up trajectories, domestic production incentive uptake, and sterilization capacity expansion timelines. Dose precision requirements and mechanical reliability thresholds informed application-segment assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene resin volatility and gamma irradiation capacity constraints. Practitioners should monitor WHO prequalification queue lengths, CDSCO fast-track approval velocities, and Gavi co-financing framework renewals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Swab Cups Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Plastic Syringes Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Powder-Free Disposable Medical Gloves Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Europe Intravenous Solutions Market