
 Hospital Gowns Market | 2026-2036
Hospital Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Gowns Market Intelligence
Market Context
Ambulatory surgery centers is realigning demand away from traditional hospital procurement channels toward specialized distributors. Medline Industries leverages its direct sales infrastructure to control supply chain access across outpatient facilities. Cardinal Health sustains competitive pressure through scale advantages in disposable gown manufacturing. Owens & Minor anchors its position via logistics networks serving integrated delivery networks.
Technical Definition and Segment Structure
Hospital gowns are single-use or multi-use garments engineered from spunbond-meltblown-spunbond (SMS) fabric, polyethylene, or cotton blends, designed to provide fluid barrier protection, patient modesty, and contamination control in clinical environments. The product serves infection prevention protocols across acute care, surgical, and diagnostic settings. Surgical gowns command premium positioning due to stringent AAMI Level 3 and Level 4 barrier requirements, while disposable isolation gowns experience accelerated volume growth driven by pandemic-hardened stockpiling behaviors. Reusable cotton gowns retain share in long-term care facilities where laundering economics outperform single-use alternatives, and polyethylene variants dominate mass vaccination and low-risk examination applications where cost minimization governs procurement.
Regulatory Framework and Outlook
The FDA governs hospital gowns as Class I medical devices under 21 CFR 878.4040, with AAMI PB70 establishing liquid barrier performance tiers that manufacturers must validate through synthetic blood penetration testing. The EPA registers antimicrobial treatments applied to gown surfaces, while OSHA's Bloodborne Pathogens Standard mandates appropriate personal protective equipment selection in healthcare workplaces. Stakeholders must monitor evolving FDA guidance on supply chain resilience and domestic manufacturing incentives embedded in the Infrastructure Investment and Jobs Act, as these frameworks will reshape qualification criteria and sourcing geography for barrier apparel.
Market Dynamics
Centralized purchasing through group purchasing organizations is compressing supplier margins while consolidating procurement volume toward manufacturers with direct distribution infrastructure.
Growth Catalysts
- Outpatient surgical volume expansion:Ambulatory surgery centers in the United States are scaling disposable isolation gown procurement as same-day procedures migrate from inpatient settings.
- AAMI PB70 barrier tier upgrades:The FDA's tightening enforcement of liquid penetration standards is forcing replacement cycles for legacy gown inventories across acute care networks.
- Spunbond-meltblown-spunbond (SMS) fabric advances:Improved meltblown layer density is enabling lighter-weight gowns to meet Level 3 certification without polyester reinforcement.
Market Restraints
- Polypropylene feedstock volatility:SMS fabric costs fluctuate with propylene monomer pricing tied to Gulf Coast petrochemical capacity.
- Single-source meltblown concentration:Domestic North American meltblown nonwoven supply remains concentrated among three specialized converters.
- Reusable cotton substitution in long-term care:Industrial laundering economics outperform disposables in nursing home settings with captive linen services.
Strategic Opportunities
- India outpatient infrastructure buildout:Central government health scheme expansion is creating first-time demand for standardized barrier apparel in tier-2 and tier-3 cities.
- Antimicrobial surface treatments:EPA-registered silver-ion and copper-based coatings command pricing premiums in oncology and immunocompromised patient settings.
- Domestic manufacturing incentives:The Infrastructure Investment and Jobs Act allocates capital access for reshoring SMS production lines to reduce import dependency.
Industry Challenges
- AAMI PB70 validation timeline compression:Third-party laboratory testing backlogs extend new product qualification cycles beyond 18 months.
- Sterile supply chain integration:Gown manufacturers must synchronize sterile packaging workflows with hospital sterilization department protocols.
Report Scope
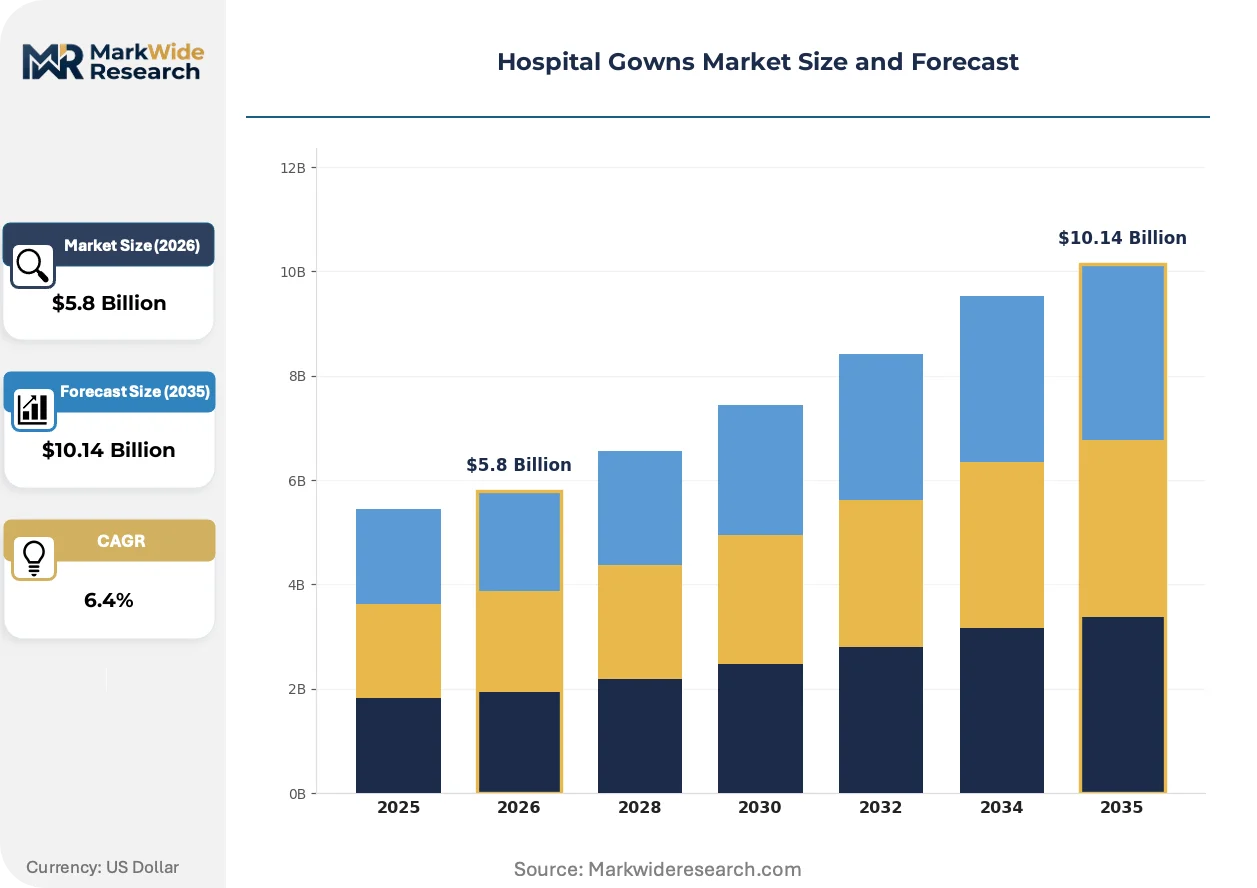
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Gowns Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical, Isolation, Examination, Patient, Reusable, Disposable Material: Polyethylene, SMS Fabric, Cotton, Polyester, Nonwoven, Spunbond End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Nursing Homes, Clinics, Long-term Care Facilities Distribution Channel: Direct Sales, Medical Supply Distributors, Online Retailers, Drug Stores, Government Agencies, Wholesalers |
| Companies Covered | Owens & Minor, AmeriPride Services Inc., Cardinal Health, Ahlstrom-Munksj, Angelica Corporation, Medline Industries, Inc., Standard Textile Co., Inc., Johnson & Johnson Services, Inc., 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Gowns Market Strategic Shifts & Innovations
Material science advances and procurement centralization are reshaping competitive advantage toward integrated manufacturers with captive nonwoven production.
Biodegradable spunlaid polylactic acid (PLA) nonwovens are absorbing pilot demand from sustainability-mandated health systems in California and Washington. These facilities prioritize landfill diversion metrics over per-unit cost in purchasing criteria. The technology is absorbing volume previously captured by polypropylene SMS in non-surgical applications where barrier requirements permit lower basis weights.
REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are compelling European manufacturers to reformulate durable water-repellent finishes on reusable surgical gowns. The ECHA's proposed universal PFAS ban accelerates substitution toward silicone-based and hydrocarbon alternatives. German and French hospital networks are front-loading procurement to secure inventory ahead of anticipated 2025 restriction implementation.
Stockless inventory programs administered by distributors are displacing hospital-owned warehouse models across integrated delivery networks. Cardinal Health and Owens & Minor embed consignment arrangements that transfer working capital burden from provider to supplier. This shift concentrates most visibly in the southeastern United States where hospital consolidation has created multi-facility systems with standardized formulary requirements.
Hospital Gowns Market Segmentation
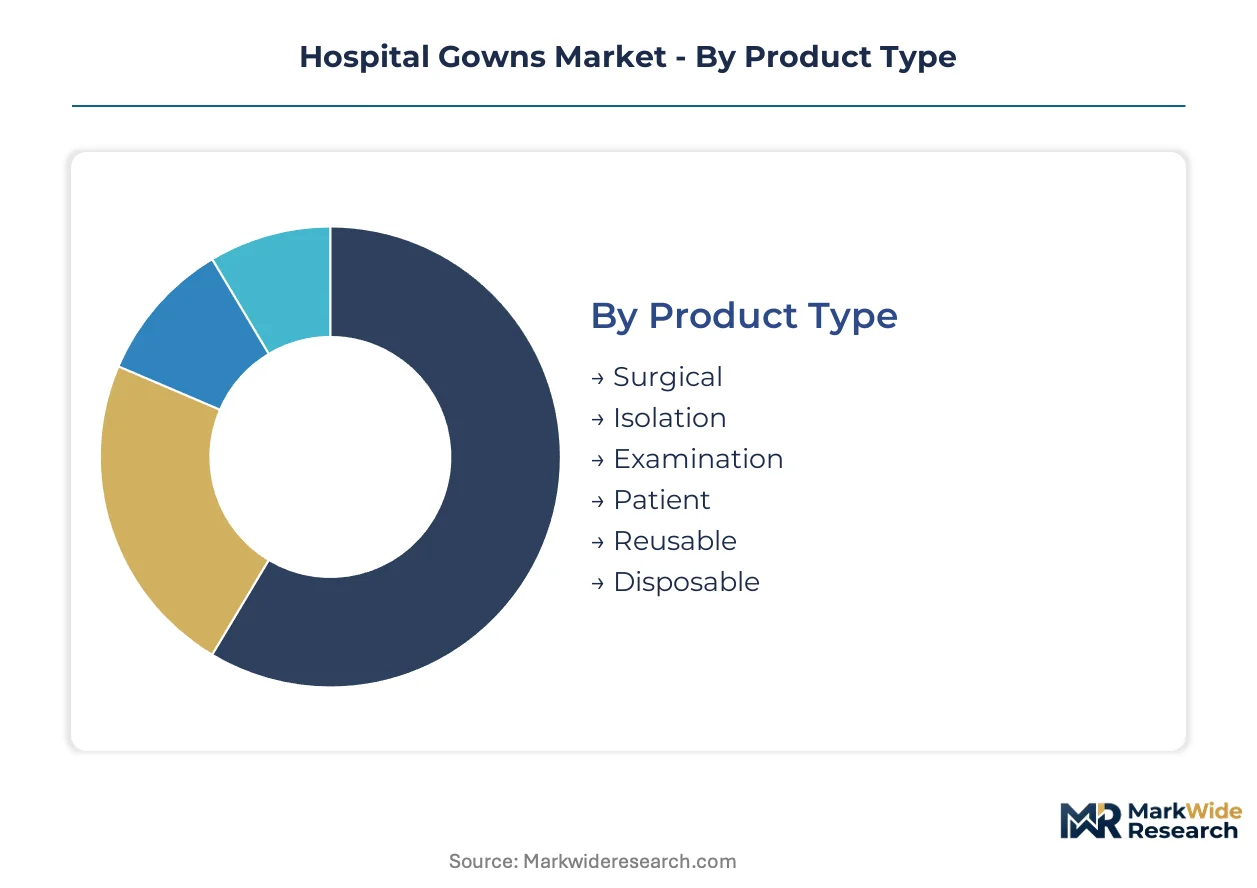
Hospital gown procurement patterns diverge sharply across clinical settings, with barrier-performance requirements and laundering economics driving distinct material and product-type preferences. Understanding these segment boundaries reveals where manufacturers must maintain dual certification portfolios versus single-product specialization.
Product Type:
Surgical and isolation gowns anchor standalone procurement workflows with dedicated inventory management, while examination and patient variants typically embed within broader linen or apparel contracts.
- Surgical:Engineered to AAMI PB70 Level 3 and Level 4 standards with reinforced critical zones and synthetic blood penetration resistance. Demand concentrates in United States acute care networks where FDA enforcement of barrier validation has accelerated replacement cycles for legacy inventory.
- Isolation:Disposable SMS fabric construction dominates pandemic-hardened stockpiling behaviors across ambulatory surgery centers. The segment's expansion is fastest where outpatient volumes migrate from inpatient settings and same-day procedure protocols require single-use contamination control.
- Examination:Polyethylene variants serve mass vaccination and low-risk diagnostic applications where cost minimization governs procurement decisions.
- Patient:Cotton-polyester blends prioritize modesty and comfort over barrier performance in general ward settings.
- Reusable:Industrial laundering economics outperform disposables in nursing home settings with captive linen services and extended patient stays.
- Disposable:Single-use polypropylene SMS dominates surgical and isolation applications where contamination elimination outweighs per-unit cost.
Volume placements concentrate in disposable isolation gowns; the faster expansion belongs to surgical gowns as AAMI tier upgrades force facility-wide inventory refreshes.
Material:
Cost tiers separate premium barrier fabrics from economy alternatives, with raw material volatility creating divergent margin pressures across the supply base.
- SMS Fabric:Spunbond-meltblown-spunbond laminates deliver AAMI Level 3 certification through meltblown layer density without polyester reinforcement. United States manufacturers prioritize domestic SMS sourcing following Infrastructure Investment and Jobs Act incentives for reshoring production lines.
- Polyethylene:Cast film extrusion produces low-cost impermeable barriers for examination and patient transport applications where breathability is secondary to fluid strike-through prevention.
- Cotton:Natural fiber construction supports reusable gown programs in long-term care facilities with on-premise laundering infrastructure.
- Polyester:Woven and knitted variants reinforce surgical gown critical zones when standalone SMS basis weight proves insufficient for Level 4 penetration resistance.
- Nonwoven:Spunlaid and needlepunched constructions serve general patient apparel where barrier requirements remain minimal.
- Spunbond:Single-layer polypropylene webs provide economical alternatives to full SMS laminates in low-risk examination settings.
Procurement volume clusters in SMS fabric for barrier-critical applications; polyethylene maintains cost-driven placement in high-volume, low-acuity channels.
End User:
Customer type determines whether gowns flow through centralized group purchasing organization contracts or direct manufacturer relationships.
- Hospitals:Integrated delivery networks leverage scale advantages through GPO-negotiated formularies that consolidate surgical and isolation gown procurement. These facilities demand comprehensive AAMI certification portfolios and sterile supply chain integration.
- Ambulatory Surgery Centers:Outpatient-focused facilities prioritize disposable isolation gown availability through specialized distributors with consignment inventory programs. Same-day procedure growth is expanding procurement faster than traditional hospital channels.
- Diagnostic Laboratories:Specimen collection and processing workflows require fluid-resistant examination gowns with lower barrier tier requirements than surgical applications.
- Nursing Homes:Captive linen services and extended patient stays favor reusable cotton gown economics over disposable alternatives.
- Clinics:Independent physician practices source through medical supply distributors with mixed product-type availability across examination and patient gown categories.
- Long-term Care Facilities:Industrial laundering infrastructure supports reusable programs where per-use cost calculations favor cotton-polyester blends.
Revenue concentration sits with hospital systems; ambulatory surgery centers are climbing the fastest as outpatient migration accelerates.
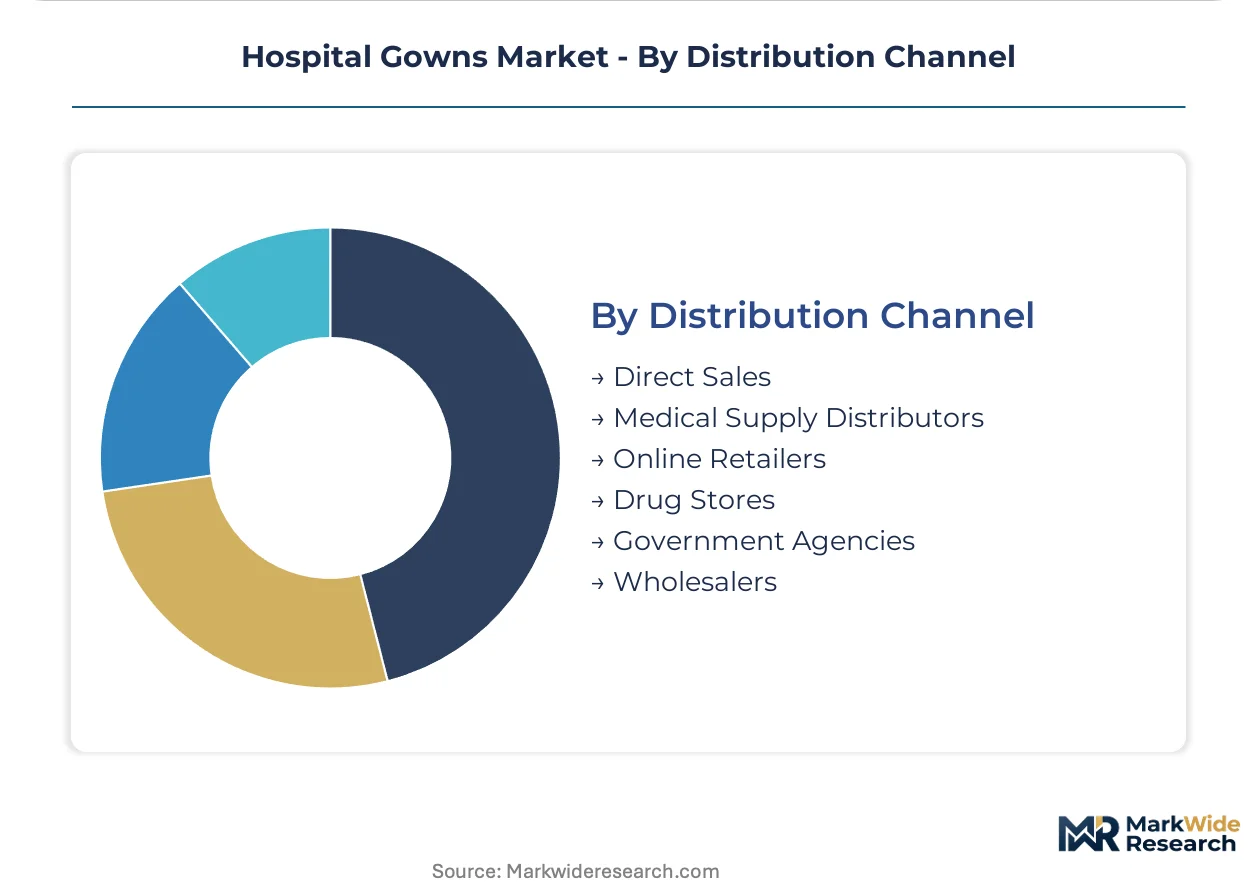
Distribution Channel:
Supply concentration varies from manufacturer-direct relationships to fragmented wholesale networks, with inventory ownership models shifting working capital burdens.
- Direct Sales:Large manufacturers maintain dedicated field organizations serving integrated delivery networks with customized formulary management and consignment arrangements. These relationships capture premium surgical gown volume through multi-year contracts.
- Medical Supply Distributors:Regional and national distributors aggregate fragmented clinic and nursing home demand through warehouse stock-and-ship models with limited technical support.
- Online Retailers:E-commerce platforms absorb small-practice and individual purchaser demand with standardized product offerings and rapid fulfillment.
- Drug Stores:Retail pharmacy chains serve consumer-facing patient gown needs with limited clinical-grade inventory.
- Government Agencies:Federal and state emergency stockpile procurement flows through dedicated contracting vehicles with surge capacity requirements.
- Wholesalers:Traditional medical product wholesalers intermediate between manufacturers and smaller facilities without direct sales coverage.
Direct sales infrastructure commands surgical gown placement; medical supply distributors are expanding most quickly as ambulatory surgery center networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Gujarat and Shenzhen are concentrating medical textile manufacturing through duty-exempt raw material imports and streamlined customs processing for SMS fabric production.
United States
Group purchasing organizations consolidate surgical gown procurement across integrated delivery networks in the Southeast and Midwest. The FDA enforces AAMI PB70 barrier validation through synthetic blood penetration testing for Level 3 and Level 4 certifications. Charlotte, North Carolina anchors distribution infrastructure where Owens & Minor operates logistics hubs serving multi-facility health systems.
Germany
REACH restrictions on PFAS chemicals are accelerating reformulation of durable water-repellent finishes for reusable surgical gowns ahead of ECHA's proposed universal ban. German hospital networks in Bavaria and North Rhine-Westphalia front-load procurement to secure inventory. The Frankfurt-Rhine-Main cluster hosts specialized nonwoven converters supplying barrier apparel to Central European acute care networks.
India
Ayushman Bharat health scheme expansion generates first-time demand for standardized isolation gowns in tier-2 and tier-3 cities across Maharashtra and Karnataka. The Bureau of Indian Standards mandates textile quality specifications for medical protective equipment under harmonized national standards. The Delhi-Mumbai Industrial Corridor attracts SMS fabric investments targeting domestic substitution of Chinese polypropylene imports.
China
Dual carbon goals and provincial emissions trading schemes are pressuring Zhejiang and Jiangsu-based spunbond manufacturers to retrofit production lines for energy efficiency. The National Medical Products Administration governs gown registration as Class I medical devices with barrier performance documentation. The Yangtze River Delta maintains concentration of meltblown nonwoven capacity serving both domestic hospital procurement and export markets.
Japan
Metropolitan Tokyo hospitals prioritize antimicrobial surface treatments for oncology and immunocompromised patient settings where EPA-registered silver-ion coatings command pricing premiums. The Ministry of Economy, Trade and Industry promotes domestic manufacturing resilience for critical medical supplies through supply chain diversification subsidies. The Osaka-Kobe industrial zone specializes in high-basis-weight SMS laminates for Level 4 surgical applications.
Hospital Gowns Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated distributors commanding surgical gown placement while regional converters absorb isolation gown volume. The vendor base concentrates around three archetypes: diversified health care conglomerates with captive nonwoven production, specialized medical textile manufacturers with AAMI certification depth, and logistics-centric distributors embedding consignment inventory programs. Competitive moves center on backward integration into SMS fabric production and strategic partnerships with ambulatory surgery center networks.
Among diversified health care suppliers, Cardinal Health and Medline Industries occupy positions exemplifying scale-driven distribution infrastructure, while Owens & Minor anchors the logistics-centric archetype through integrated delivery network relationships. These three entities represent the dominant competitive configuration in United States acute care procurement channels.
| Leading Market Players |
|---|
| Owens & Minor |
| AmeriPride Services Inc. |
| Cardinal Health |
| Ahlstrom-Munksj |
| Angelica Corporation |
| Medline Industries, Inc. |
| Standard Textile Co., Inc. |
| Johnson & Johnson Services, Inc. |
| 3M |
| Others |
Cost & Logistics Intelligence
Family-owned SMS converters in the southeastern United States anchor supply discipline through multi-generational capital stewardship, translating into stable contract pricing for integrated delivery networks while resisting spot-market volatility that disrupts polyethylene-focused competitors.
Pricing Analysis
Short lead-time premiums command pricing advantages for AAMI Level 4 surgical gowns when hospital sterilization departments face emergency replenishment scenarios. Three-tier pricing structure across premium, standard, and economy levels separates sterile surgical inventory from non-sterile isolation and basic examination variants. Cost compression in polyethylene examination gowns is intensifying because ambulatory surgery centers consolidate volume through group purchasing organization formulary negotiations. Price sensitivity concentrates in nursing home procurement committees where reusable cotton programs outperform disposable economics on per-use calculations.
Supply Chain Analysis
Polypropylene resin supply rests on Gulf Coast petrochemical capacity, meltblown nonwoven production clusters in North Carolina and South Carolina, and finished garment assembly in Mexico and Central America under nearshoring arrangements. Spunbond-meltblown-spunbond laminates, cast polyethylene films, and cotton-polyester blends constitute the critical input trinity. Single-source vulnerability pervades domestic meltblown capacity where three specialized converters control barrier-layer supply. Distribution runs through consignment inventory programs administered by logistics-centric distributors embedded within integrated delivery network warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centralized purchasing through group purchasing organizations is compressing supplier margins and forcing sub-scale manufacturers toward exit or acquisition, consolidating viable competitors toward integrated producers with captive nonwoven operations.
For Market Incumbents: Anticipate AAMI PB70 validation timeline compression as third-party laboratory testing backlogs extend qualification cycles beyond sustainable product development windows. Prioritize backward integration into domestic SMS production lines to capture Infrastructure Investment and Jobs Act capital incentives and insulate margin structures from propylene monomer volatility. Defend hospital system placement through sterile supply chain integration capabilities that synchronize packaging workflows with biomedical engineering protocols. For New Entrants and Emerging Players: Ayushman Bharat health scheme expansion in India opens a window for standardized isolation gown penetration in tier-2 and tier-3 cities where first-time demand outpaces established supplier coverage. Target ambulatory surgery center networks in the southeastern United States with consignment inventory programs that transfer working capital burden from outpatient facilities. Pursue antimicrobial surface treatment differentiation through EPA-registered silver-ion coatings that command pricing premiums in oncology settings. For Investors and Strategic Acquirers: FDA guidance tightening on personal protective equipment supply chain resilience is the leading indicator that domestic manufacturing qualification criteria will reshape sourcing geography and elevate asset values for reshored production capacity. Frame five-to-ten-year viability around manufacturers with captive meltblown nonwoven operations and AAMI certification depth across Level 3 and Level 4 tiers. Monitor Bureau of Indian Standards harmonization implementation as the signal for India outpatient infrastructure procurement formalization.| Strategic Initiative | Industry Significance |
|---|---|
| AAMI PB70 Certification Investment | Level 4 barrier validation secures placement in acute care networks replacing legacy inventory. |
| Domestic SMS Production Reshoring | Infrastructure Investment and Jobs Act incentives reduce import dependency for critical meltblown supply. |
| Antimicrobial Surface Treatment Development | EPA-registered coatings capture pricing premiums in immunocompromised patient care settings. |
| Ambulatory Surgery Center Network Partnership | Consignment arrangements embed inventory within fastest-growing outpatient procedure channels. |
| Sterile Supply Chain Integration | Synchronized packaging workflows meet hospital sterilization department protocol requirements. |
Research Approach
Document review covered FDA 510(k) filings, AAMI technical standards documentation, and hospital procurement database extracts, complemented by interviews with GPO contracts managers, biomedical engineers, and sterile processing department directors. Secondary validation drew from SEC 10-K disclosures of listed healthcare distributors, customs trade data on polypropylene resin imports, and CMS Medicare cost report filings. Bottom-up volume estimates from facility-level procurement patterns triangulated against top-down market sizing from manufacturer shipment data.
Historical shipment trajectories cross-referenced against panel input from supply chain executives and purchasing committee members anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, barrier certification level, end-user facility category, and regional regulatory cluster. CAGRs derived from weighted average growth assumptions across ambulatory surgery center expansion rates, AAMI tier upgrade replacement cycles, and material science substitution patterns for biodegradable alternatives.
The model assumes a particular technology adoption path; alternative pathways for spunlaid polylactic acid nonwovens would alter the outlook if sustainability-mandated health systems accelerate landfill diversion priorities. Forecasts reflect assumptions regarding FDA enforcement continuity, propylene monomer pricing stability, and outpatient migration velocity. A small set of named triggers warrants ongoing watch: ECHA PFAS restriction implementation, Bureau of Indian Standards enforcement ramp, and Infrastructure Investment and Jobs Act capital allocation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Medical Gas Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Global Needles Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Burn Ointment Market