
 Qatar Senior Living Market | 2026-2036
Qatar Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Senior Living Market Analytics
The gap between luxury retirement communities and basic care homes is consolidating as developers target Qatar's affluent aging population with differentiated service portfolios. Hamad Medical Corporation anchors the clinical infrastructure layer through its national hospital network and home health referrals. Qatar Care competes on specialized nursing staffing and regulatory compliance breadth across Doha and Al Wakrah. Qatari Diar Real Estate extends its development footprint into integrated senior housing within Lusail's master-planned districts.
Senior living encompasses residential and healthcare services designed for adults requiring varying levels of assistance with daily activities, medical supervision, or cognitive support, typically delivered through staffed facilities with clinical oversight ratios, emergency response systems, and therapeutic programming. The primary purpose is to maintain functional independence while providing graduated care intensity that reduces acute hospitalization frequency. Independent living and assisted living command the premium margin pools as self-pay resident capacity outstrips supply, while memory care represents the fastest-growing segment amid rising dementia prevalence recognition. Nursing care retains institutional scale but faces margin compression from staffing cost inflation and MOHP reimbursement benchmarks.
The Ministry of Public Health and Qatar Financial Centre Regulatory Authority shape market access through facility licensing, staff credentialing mandates, and investment vehicle structuring for healthcare real estate. MOHP's 2022 long-term care standards introduced minimum nurse-to-resident ratios and physical environment specifications that filter out undercapitalized operators. Stakeholders must monitor how the National Health Strategy's aging population targets intersect with Qatari Diar's infrastructure commitments and whether foreign operator partnerships accelerate service model imports from European or North American benchmarks.
Market Dynamics
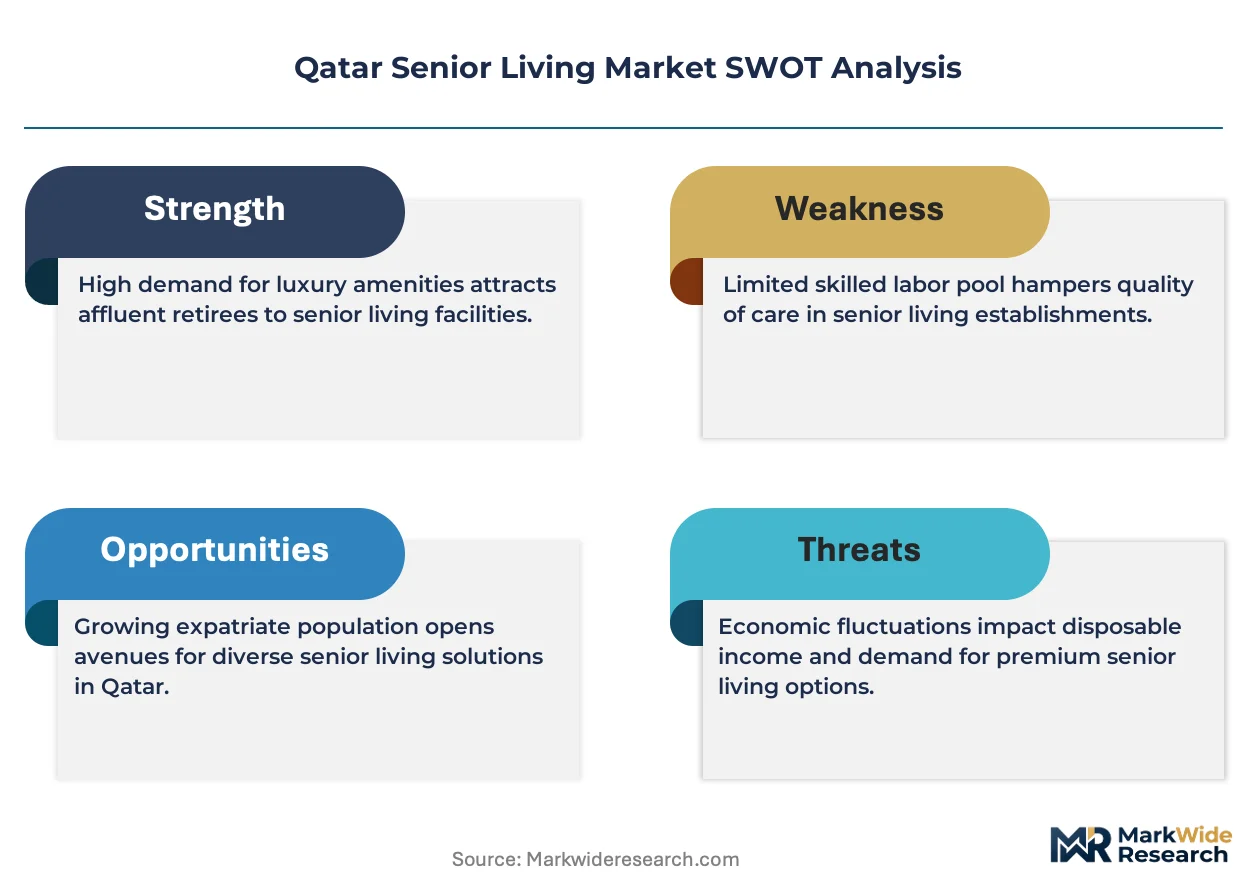
The Ministry of Public Health's 2022 long-term care standards are compressing operator margins while filtering out undercapitalized entrants, forcing a consolidation wave among Doha's assisted living providers.
Growth Catalysts
- Regulatory Licensing Framework:MOHP's mandatory facility licensing creates operational barriers that protect compliant incumbents from price competition. Licensed operators gain preferential referral access from Hamad Medical Corporation's hospital network.
- Expatriate Retiree Inflows:Qatar's visa reforms attract high-net-worth retirees from GCC neighbors seeking premium assisted living outside saturated Dubai and Riyadh markets.
- Dementia Prevalence Recognition:Rising clinical diagnosis rates for Alzheimer's and related dementias expand addressable demand for specialized memory care units with higher per-bed economics.
Market Restraints
- Specialized Nursing Labor Scarcity:Qatar's dependence on Filipino and Indian nursing imports creates wage inflation and turnover risk when source-country emigration policies tighten.
- Real Estate Cost Concentration:Premium land parcels in Doha's West Bay and Lusail command development costs that exclude mid-market senior housing formats.
- Substitution by Home Healthcare:Hamad Medical Corporation's expanding home health referral network diverts lower-acuity seniors from facility-based care.
Strategic Opportunities
- Al Wakrah Expansion:This southern municipality offers lower land costs and proximity to Hamad Hospital's Al Wakrah facility for clinical overflow partnerships.
- Technology-Enabled Monitoring:Integration of IoT fall-detection systems with Qatar's 5G infrastructure reduces night staffing ratios while maintaining regulatory compliance.
- MOHP Reimbursement Benchmarks:New government payment schedules for nursing care create revenue visibility that attracts institutional capital to the sector.
Industry Challenges
- Clinical Staff Credentialing Timelines:MOHP's verification process for foreign nursing qualifications extends 4-6 months, delaying facility openings and inflating pre-operational burn rates.
- Intergenerational Care Model Integration:Operators struggle to blend traditional Qatari family caregiving expectations with institutional service delivery without alienating conservative family decision-makers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Senior Living Market |
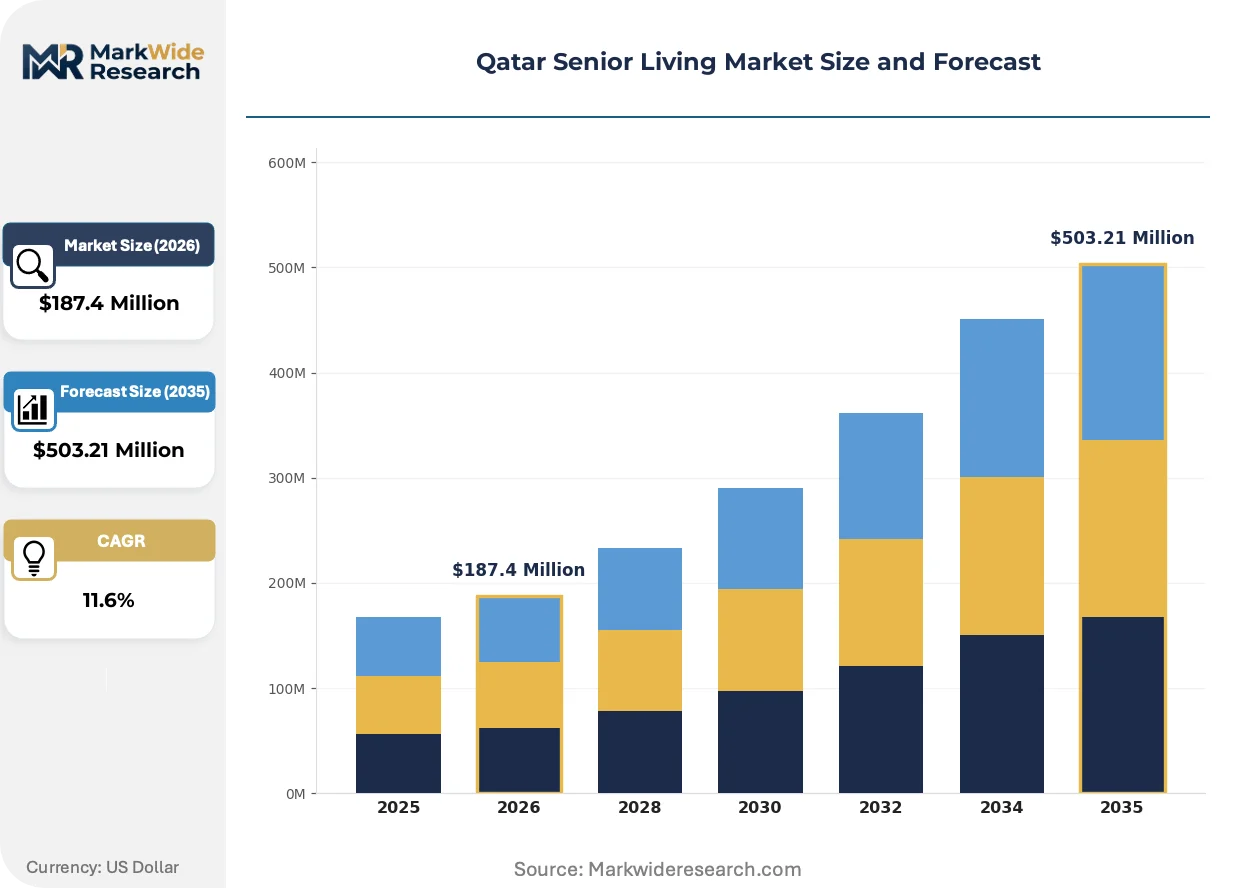
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Independent Living, Assisted Living, Memory Care, Nursing Care Facility Type: Apartment Complexes, Retirement Communities, Care Homes, Rehabilitation Centers Pricing Model: Monthly Subscription, Pay-Per-Service, One-Time Fee, Sliding Scale Care Setting: In-Home Care, Community Centers, Adult Day Care, Long-Term Care Facilities |
| Companies Covered | KIMS Health at Home, Hamad Medical Corporation, Qatar Care, Qatari Diar Real Estate, Barwa Real Estate Company, EHSAN, AECOM, Aman Medical & Healthcare Services, Home Care Middle East, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Senior Living Market Evolving Landscape
Digital health infrastructure and regulatory standardization are converging to reshape how senior care is delivered and financed across Qatar's emerging retirement corridor.
Remote patient monitoring platforms are expanding into assisted living workflows as operators deploy wearable vitals tracking and automated medication adherence systems. High-end facilities in Lusail's waterfront districts are adopting these tools to differentiate from basic nursing homes. This technology compression is enabling lower nurse-to-resident ratios without sacrificing MOHP compliance metrics.
MOHP's 2022 physical environment specifications mandate private rooms, natural lighting minimums, and therapeutic garden access for all new licensed facilities. These rules eliminate shared-room economics and force developers toward luxury positioning. Memory care units face the strictest spatial requirements, accelerating capital deployment into specialized construction.
Family procurement of senior services is fragmenting across multiple touchpoints rather than consolidating through single hospital referrals. Adult children now independently research facilities via digital channels before involving clinical gatekeepers. This behavioral shift is most visible among Qatari nationals under age fifty, who prioritize amenity portfolios over pure clinical proximity in facility selection.
Qatar Senior Living Market Segmentation
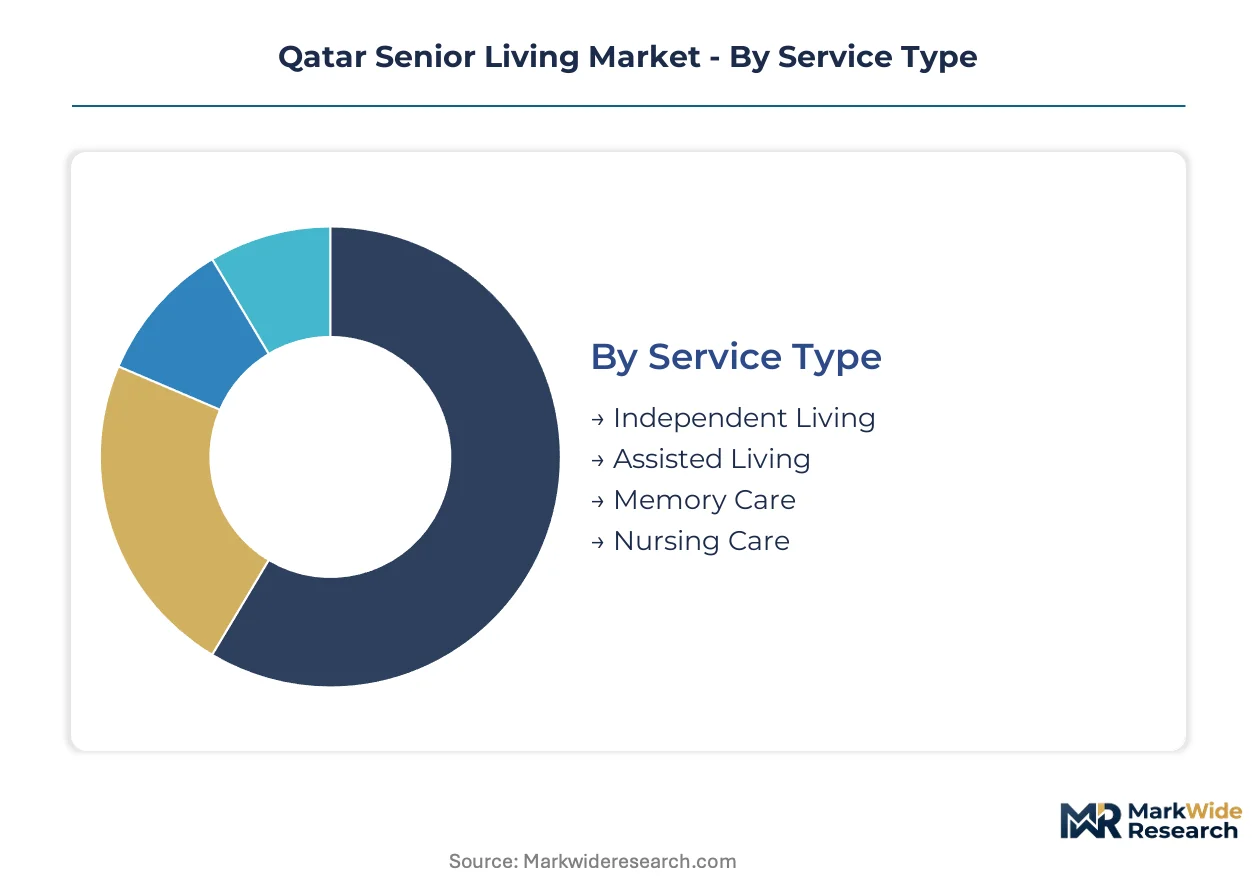
Qatar's senior living market fragments across four distinct dimensions that determine operator strategy and capital deployment. Service intensity requirements, facility economics, payment structures, and care delivery settings each create separate competitive arenas with divergent margin profiles and regulatory exposure.
Service Type:
Buyers differentiate primarily by acuity level and desired independence preservation, which determines staffing ratios and clinical infrastructure requirements.
- Independent Living:Self-contained residential units with minimal medical supervision, targeting mobile seniors seeking amenity-rich environments. Demand concentrates in Lusail's waterfront districts where Qatari Diar integrates senior housing into master-planned communities, driven by affluent nationals prioritizing lifestyle maintenance over clinical proximity.
- Assisted Living:Moderate support for daily activities with 24-hour staffing and medication management protocols. Doha's West Bay corridor attracts high-net-worth expatriate retirees from Saudi Arabia and Kuwait, constrained by MOHP's mandatory nurse-to-resident ratios that inflate operational costs.
- Memory Care:Secured environments with specialized dementia programming and higher supervision density. Hamad Medical Corporation's rising Alzheimer's diagnosis referrals expand addressable demand, though MOHP's strict spatial requirements for therapeutic gardens and private rooms accelerate capital deployment.
- Nursing Care:Continuous skilled nursing and post-acute medical management for highest-acuity residents. Reimbursement benchmarks from the Ministry of Public Health create revenue visibility that attracts institutional investors, offsetting margin pressure from Filipino nursing wage inflation.
Volume sits with Nursing Care; growth tilts toward Memory Care.
Facility Type:
Capital intensity and land use efficiency separate facility formats, with developers choosing between vertical urban density and horizontal campus models.
- Apartment Complexes:Multi-unit residential buildings with aging-in-place modifications and concierge services. Al Wakrah's lower land costs enable mid-market positioning that Doha's premium parcels exclude, though clinical overflow partnerships with Hamad Hospital's southern facility remain underdeveloped.
- Retirement Communities:Master-planned campuses integrating housing, wellness centers, and social programming. Lusail's integrated districts concentrate Qatar Care's specialized nursing staffing alongside Qatari Diar's real estate developments, capturing intergenerational family visitation patterns.
- Care Homes:Smaller-scale residential facilities with family-style caregiving ratios. Regulatory compliance breadth requirements from MOHP's 2022 standards filter out undercapitalized operators, consolidating share among established Doha and Al Wakrah providers.
- Rehabilitation Centers:Post-acute and therapeutic-focused facilities with intensive physical therapy infrastructure. Hamad Medical Corporation's national hospital network anchors referral flows, though home health diversion threatens lower-acuity occupancy.
Development gravity centers on Retirement Communities; regulatory pressure is compressing Care Homes most severely.
Pricing Model:
Resident financial capacity and risk tolerance determine payment structure adoption, with implications for operator cash flow stability and capital access.
- Monthly Subscription:Recurring fee structures covering base housing and standard services with predictable budgeting. Premium assisted living facilities in Doha's West Bay favor this model for self-pay Qatari nationals, though staffing cost inflation erodes contracted margins.
- Pay-Per-Service:Unbundled pricing for discrete care episodes and optional amenities. Adult children under fifty increasingly research facilities via digital channels before involving clinical gatekeepers, fragmenting procurement across multiple touchpoints.
- One-Time Fee:Entrance fee models with partial refund guarantees and lifetime care commitments. High-net-worth expatriate retirees from GCC neighbors seek capital preservation alongside care security, constrained by Qatar Financial Centre Regulatory Authority investment vehicle structuring requirements.
- Sliding Scale:Income-adjusted pricing tiers expanding access beyond top decile wealth concentration. MOHP reimbursement benchmarks for nursing care create partial subsidy mechanisms, though coverage gaps persist for mid-market assisted living.
Revenue concentration follows Monthly Subscription; Pay-Per-Service is climbing the fastest among digitally-engaged family decision-makers.
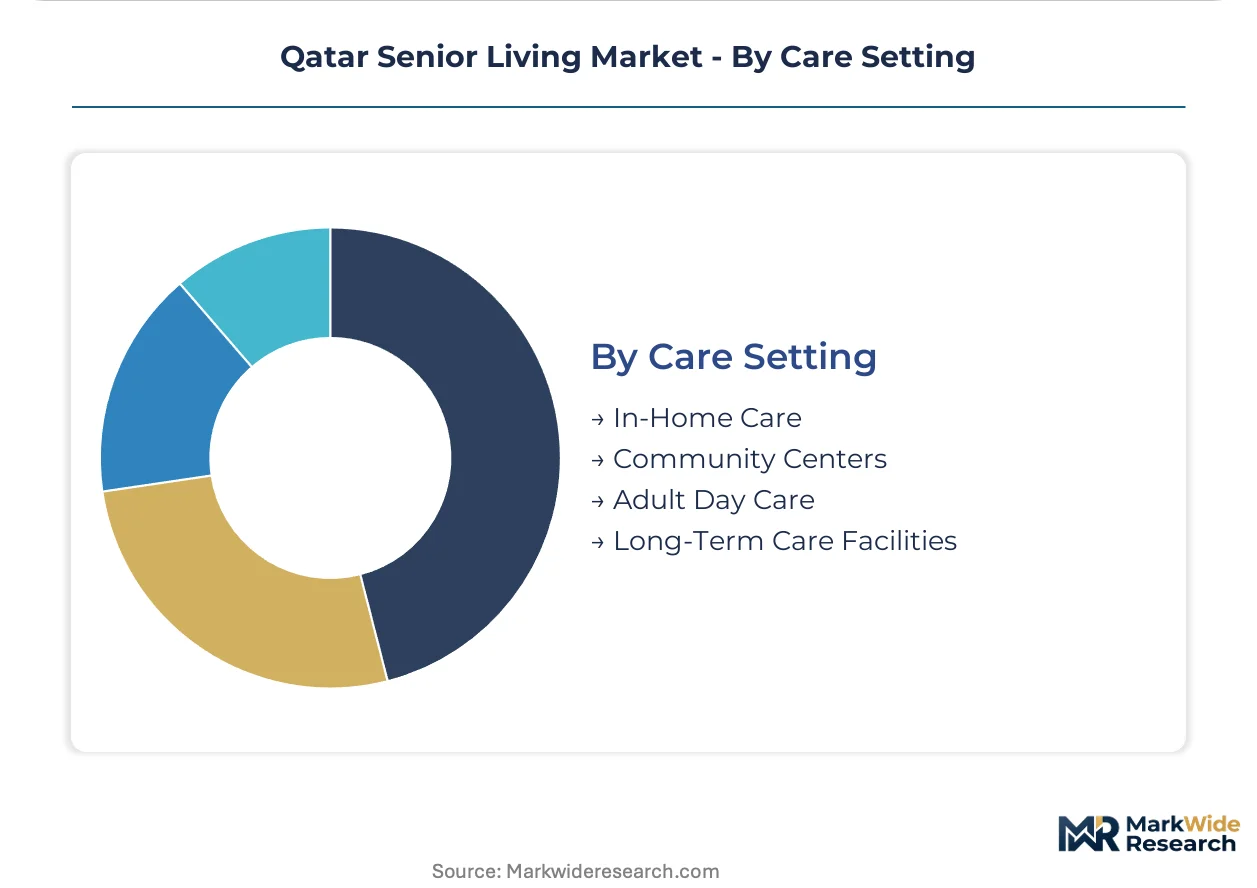
Care Setting:
Institutional versus home-based delivery reflects cultural expectations, clinical acuity, and technology enablement.
- In-Home Care:Domestic staffing and visiting nurse services preserving familiar environments. Traditional Qatari family caregiving expectations clash with institutional service delivery, creating tension for operators blending models without alienating conservative decision-makers.
- Community Centers:Day programs and social engagement hubs without overnight residential commitment. Lusail's 5G infrastructure enables IoT fall-detection integration that reduces staffing ratios while maintaining MOHP compliance, differentiating high-end facilities.
- Adult Day Care:Structured daytime supervision for cognitive or physical impairment with family respite. Dementia prevalence recognition expands addressable demand, though transportation logistics across Doha's dispersed geography limit penetration.
- Long-Term Care Facilities:24-hour residential medical and personal care for permanent placement. Mandatory MOHP licensing creates operational barriers protecting compliant incumbents, with preferential referral access from Hamad Medical Corporation's hospital network.
Placement volume favors Long-Term Care Facilities; In-Home Care is gaining share fastest through technology-enabled monitoring expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha concentrates Qatar's senior living infrastructure along its West Bay corridor, where premium land costs and proximity to Hamad Medical Corporation's hospital network shape development patterns. Lusail's master-planned waterfront districts anchor second-wave expansion as Qatari Diar integrates retirement housing into its mixed-use communities.
Doha Metropolitan Area
High-net-worth Qatari nationals and GCC expatriate retirees drive demand for premium assisted living in West Bay and The Pearl-Qatar. The Ministry of Public Health's 2022 long-term care standards mandate minimum nurse-to-resident ratios and private room specifications that filter out undercapitalized operators. New retirement community developments cluster near Hamad Hospital and the Heart Hospital to capture clinical overflow referrals.
Lusail
This northern municipality offers integrated senior housing within master-planned districts that blend residential, wellness, and retail programming. Qatari Diar Real Estate extends its development footprint here as MOHP licensing creates operational barriers protecting compliant incumbents. 5G infrastructure deployment enables IoT fall-detection integration that reduces night staffing ratios while maintaining regulatory compliance.
Al Wakrah
Lower land costs in this southern municipality attract mid-market positioning that Doha's premium parcels exclude. Proximity to Hamad Hospital's Al Wakrah facility creates clinical overflow partnership opportunities for assisted living operators. Qatar Care competes here on specialized nursing staffing breadth and regulatory compliance depth.
Al Khor and Northern Municipalities
Industrial zone adjacency and lower population density limit senior living penetration in these peripheral areas. Traditional family caregiving expectations remain strongest here, creating tension for institutional service delivery models. Sparse healthcare infrastructure concentrates demand in Doha and Lusail rather than local facility development.
Al Rayyan
This western municipality balances residential expansion with emerging healthcare infrastructure near Education City and Qatar Foundation assets. Expatriate retiree inflows from saturated Dubai and Riyadh markets seek premium assisted living alternatives here. Development lags Doha and Lusail but offers future absorption capacity as regulatory standards mature.
Qatar Senior Living Market Competitive Landscape
Capital-heavy real estate developers compete with asset-light healthcare service providers for margin capture across Qatar's senior living value chain. The market structure consolidates around vertically integrated operators who control both facility development and care delivery, filtering out pure-play landlords or standalone nursing agencies. Three archetypes dominate: state-affiliated healthcare anchors, diversified real estate conglomerates with healthcare verticals, and specialized regional care operators. Competitive dynamics center on MOHP licensing acquisition speed and Hamad Medical Corporation referral network access rather than price competition.
Within the state-affiliated anchor tier, Hamad Medical Corporation exemplifies the clinical infrastructure layer through its national hospital network and home health referral dominance. Among diversified real estate developers, Qatari Diar Real Estate and Barwa Real Estate Company occupy positions extending master-planned community expertise into integrated senior housing formats. Specialized regional operators include Qatar Care, which represents the regulatory compliance and staffing breadth archetype across Doha and Al Wakrah. These three patterns illustrate how market access depends on pairing capital deployment capability with MOHP licensing and clinical partnership depth.
| Leading Market Players |
|---|
| KIMS Health at Home |
| Hamad Medical Corporation |
| Qatar Care |
| Qatari Diar Real Estate |
| Barwa Real Estate Company |
| EHSAN |
| AECOM |
| Aman Medical & Healthcare Services |
| Home Care Middle East |
| Others |
Value Network & Pricing Analysis
Sovereign-backed real estate developers anchor Qatar's senior living supply base, pairing Qatari Diar's master-planned community expertise with MOHP licensing requirements to enforce pricing discipline across premium and mid-market tiers. This ownership pattern concentrates development leverage in state-affiliated hands while filtering out undercapitalized operators through mandatory facility standards.
Pricing Analysis
Value-based pricing tied to clinical outcome metrics anchors Qatar's senior living fee structures, with Hamad Medical Corporation referral networks rewarding facilities demonstrating reduced hospital readmission rates. Three-tier pricing structure across premium, standard, and economy levels separates Lusail waterfront developments from Al Wakrah mid-market formats and basic nursing homes. Cost compression in mid-market assisted living intensifies because Filipino nursing wage inflation outpaces MOHP reimbursement benchmark adjustments. Expatriate retirees from GCC neighbors exhibit lowest price sensitivity, while Qatari nationals under fifty prioritizing amenity portfolios over clinical proximity drive fragmentation in family procurement patterns.
Supply Chain Analysis
Refurbishment flows for medical equipment and facility infrastructure remain underdeveloped across Qatar's senior living sector, creating stranded asset risk as MOHP's 2022 physical environment specifications mandate private rooms and therapeutic garden access. Equipment sourcing draws from Germany, the United States, and South Korea for diagnostic and monitoring systems, while construction materials for specialized memory care units rest on imports from China and Turkey. Single-source vulnerability concentrates in Filipino and Indian nursing labor pipelines, where source-country emigration policy shifts disrupt staffing ratios. Distribution runs through Hamad Medical Corporation's hospital network for clinical referrals, with direct-to-family digital channels fragmenting procurement for independent living and assisted living segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's senior living sector sits at a technology-transition inflection, with IoT-enabled fall detection and remote patient monitoring platforms displacing legacy night-staffing models across Lusail's 5G-enabled developments.
For Market Incumbents: To counter home healthcare diversion from Hamad Medical Corporation's expanding referral network, operators should deepen clinical overflow partnerships with Al Wakrah's southern hospital facility and invest in technology-enabled monitoring to reduce nurse-to-resident ratios without sacrificing MOHP compliance metrics. For New Entrants and Emerging Players: MOHP's 2022 long-term care standards in Qatar open a window for specialized memory care operators targeting the fastest-growing segment amid rising dementia prevalence recognition, with Al Wakrah offering lower land costs and underdeveloped clinical partnerships as the most penetrable geography for mid-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated operators with existing MOHP licenses in Doha's West Bay corridor, where regulatory barriers protect compliant incumbents from price competition; practitioners should monitor Filipino nursing emigration policy shifts and MOHP reimbursement benchmark revisions as early signals of margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MOHP Licensing Acquisition | Mandatory facility licensing from Qatar's Ministry of Public Health filters out undercapitalized competitors and secures preferential Hamad Medical Corporation referral access. |
| Technology-Enabled Monitoring Deployment | IoT fall-detection systems integrated with Qatar's 5G infrastructure reduce night staffing ratios while maintaining regulatory compliance across Lusail developments. |
| Clinical Overflow Partnership | Strategic alliances with Hamad Hospital's Al Wakrah facility capture post-acute referrals and differentiate operators in lower land-cost southern municipalities. |
| Memory Care Unit Specialization | Dedicated dementia programming with MOHP-mandated private rooms and therapeutic gardens commands premium per-bed economics in fastest-growing segment. |
| Family Digital Engagement Channel | Direct-to-consumer platforms targeting adult children under fifty fragment procurement away from traditional hospital gatekeepers for independent living selection. |
Research Methodology
Document review covered MOHP regulatory filings, Hamad Medical Corporation annual reports, and Qatar Financial Centre investment vehicle disclosures, complemented by interviews with facility operations directors, nursing workforce planners, real estate development executives, and family decision-makers in Doha and Lusail. Secondary validation drew from Qatar's Ministry of Public Health licensing databases, construction permit records, and healthcare workforce statistics. Bottom-up facility capacity modeling and top-down demographic projection triangulation anchored market sizing across the analysis window.
Cross-referencing historical occupancy patterns against expert panel input shaped the analytical framework for segment-level growth trajectories across service type, facility format, pricing model, and care setting dimensions. CAGRs were derived from weighted scenario modeling incorporating MOHP regulatory implementation timelines and expatriate retiree inflow assumptions. Industry-specific forecast inputs included dementia prevalence projections and Filipino nursing supply elasticity estimates.
The model assumes a particular technology adoption path for IoT-enabled remote monitoring; alternative pathways for wearable vitals tracking integration would alter the outlook for staffing ratio economics and facility margin structures. Forecasts reflect assumptions about MOHP enforcement consistency and GCC neighbor retiree mobility patterns. Practitioners should monitor MOHP reimbursement benchmark revisions and source-country nursing emigration policy shifts for early signals of market trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Facilities
US Hospital Facilities Market
Healthcare Facilities
US Assisted Living Facility Market
Healthcare Facilities
Bedless Hospitals Market
Healthcare Facilities
Longevity Clinic Chain Infrastructure Market
Healthcare Facilities
Global Ambulatory Surgery Centers (Ascs) Market
Healthcare Facilities
Asia-Pacific Smart Hospital Market
Healthcare Facilities
US Skilled Nursing Facility and Rehabilitation Market
Healthcare Facilities
US Office-Based Labs Market
Healthcare Facilities
Global Healthcare Facilities Management Market
Healthcare Facilities
Hospital Lighting Market
Healthcare Facilities
US Skilled Nursing Facility Market
Healthcare Facilities
Private Office-Based Clinics Market
Healthcare Facilities
Assisted Living Facilities Market
Healthcare Facilities
Micro-Hospitals Market
Healthcare Facilities
US Ambulatory Surgical Centers Market
Healthcare Facilities
US Ambulatory Surgery Centers Market