
 Amniotic Products Market | 2026-2036
Amniotic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Amniotic Products Market Intelligence
The division between cryopreserved, high-viability grafts and shelf-stable, dehydrated amniotic sheets is recalibrating competitive positioning. MiMedx Group specializes in dehydrated human amnion/chorion membrane allografts for specific clinical indications. In contrast, Organogenesis Inc. leverages its portfolio of living cell-based products, targeting complex wound care scenarios. Smith+Nephew competes with a broad regenerative medicine offering, integrating amniotic products into its larger wound management platform.
Amniotic products are allografts derived from placental tissues, including the amniotic membrane and amniotic fluid, processed to preserve bioactive components. These products contain essential growth factors, cytokines, and extracellular matrix proteins that support tissue repair and modulate inflammation. Amniotic membranes, available as both cryopreserved and dehydrated sheets, dominate the product landscape due to their established use in wound care and ophthalmology. Injectable amniotic fluid and extract formulations represent a high-growth category, finding new applications in orthopedics for joint pain management.
The regulatory environment is defined by stringent oversight from bodies like the U.S. FDA, which classifies products under its HCT/P regulations. In Europe, the European Medicines Agency (EMA) governs certain amniotic products as Advanced Therapy Medicinal Products (ATMPs), creating distinct pathways for market approval. Future investment decisions hinge on navigating these evolving regulatory classifications and demonstrating clear clinical efficacy to secure reimbursement.
Market Dynamics
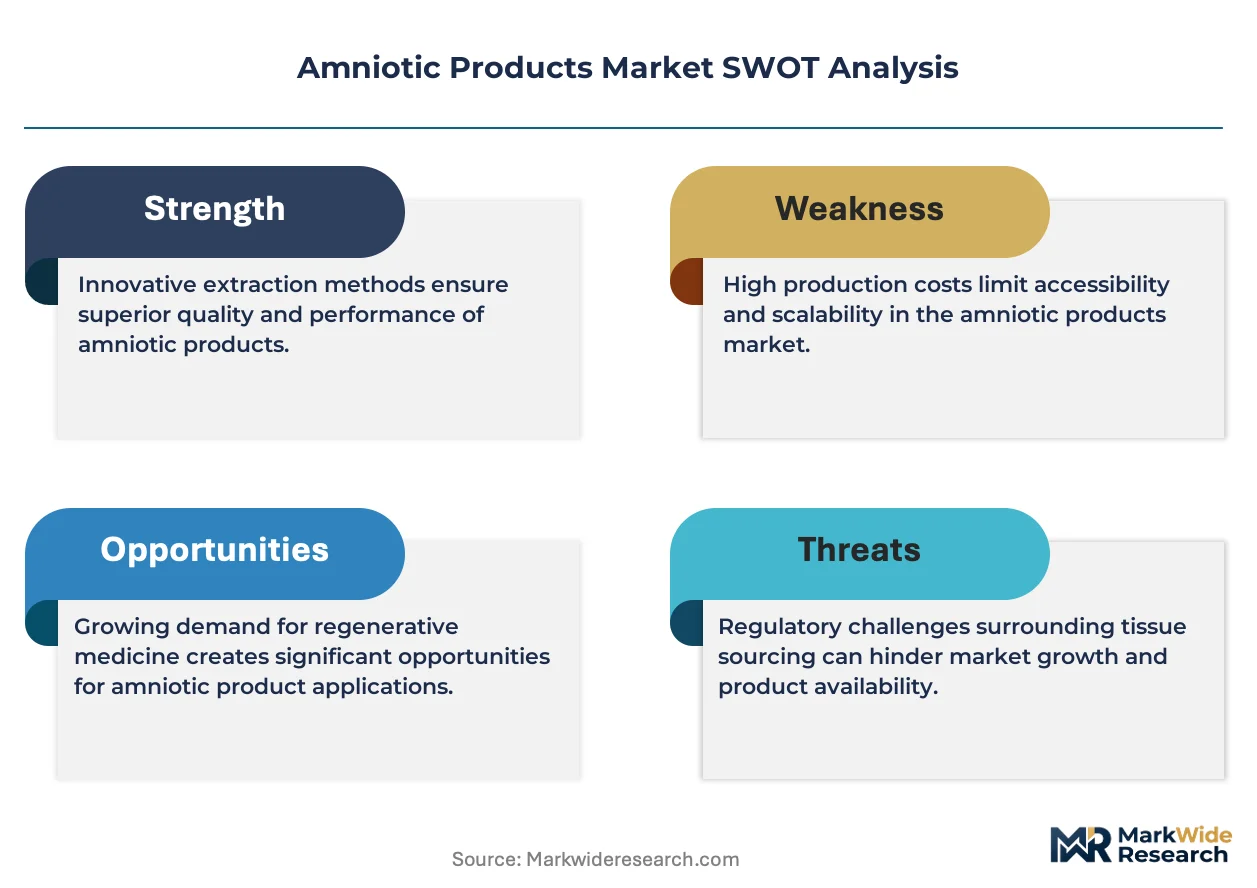
The central structural force in the amniotic products market is the regulatory bifurcation between products marketed as minimally manipulated tissue allografts and those requiring full biologic drug approval, a distinction enforced by the FDA's HCT/P framework.
Growth Catalysts
- Chronic Wound Care Demand:The rising prevalence of diabetic foot ulcers is expanding the use of amniotic membranes in specialized wound care centers, particularly within the United States and Germany, where established treatment protocols exist.
- Regulatory Pathway Clarification:Frameworks like the FDA's HCT/P regulations and the EMA's designation for Advanced Therapy Medicinal Products (ATMPs) provide more defined routes for market authorization, encouraging investment in clinical validation.
- Orthopedic Application Expansion:Advancements in processing amniotic fluid into injectable formulations are creating new uses in sports medicine and orthopedics for managing joint pain and inflammation, broadening the addressable patient base.
Market Restraints
- Reimbursement Ambiguity:Inconsistent coverage and coding policies among public and private payers, especially for newer product formats, create economic uncertainty for healthcare providers and can slow patient access to therapies.
- High Product Cost:The significant expense tied to aseptic collection, processing, and testing of donor placental tissue results in a high cost basis for final products, limiting adoption in cost-sensitive healthcare systems.
- Ethical Sourcing Constraints:The supply of viable placental tissue is fundamentally limited by the number of live births and the stringent protocols for informed consent and donor screening, which can create supply chain vulnerabilities.
Strategic Opportunities
- Ophthalmic Market Penetration:Developing specialized amniotic membrane grafts for ocular surface diseases, including persistent epithelial defects and chemical burns, presents a high-value niche with unmet clinical needs.
- Geographic Expansion in Asia:Markets such as Japan and South Korea, with their advanced healthcare infrastructure and aging populations, offer significant growth potential for amniotic products with proven efficacy in orthopedics.
- Development of Combination Products:Integrating amniotic-derived growth factors with synthetic scaffolds or other biologics offers a pathway to create next-generation regenerative therapies with enhanced and targeted functional properties.
Industry Challenges
- Clinical Evidence Generation:The requirement to fund and execute large-scale, randomized controlled trials to satisfy regulators like the FDA and secure favorable reimbursement is a significant financial and operational burden for manufacturers.
- Potency Assay Standardization:A lack of industry-wide standards for measuring the bioactivity and consistency of critical growth factors in amniotic allografts complicates product comparisons and dose determination for clinicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amniotic Products Market |
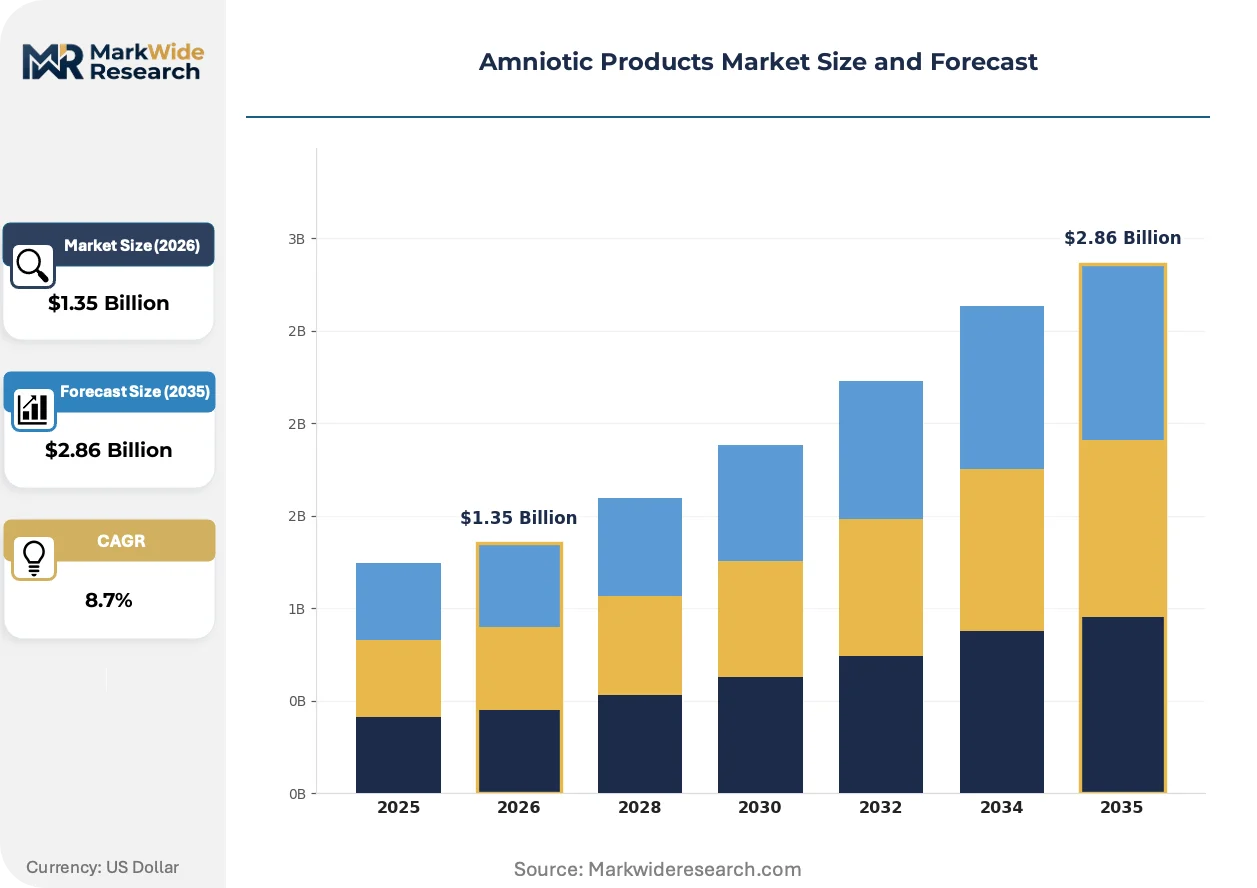
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
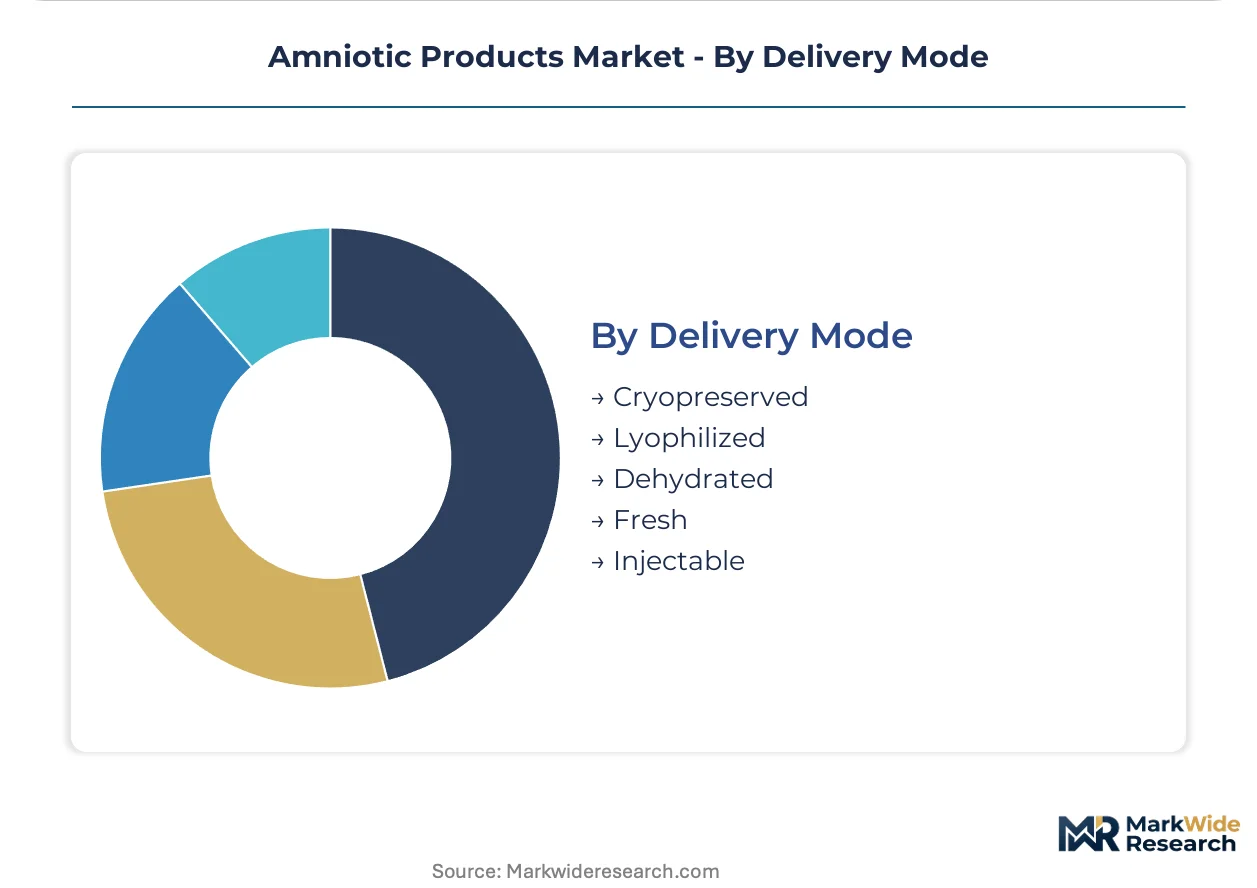
| Segmentation | Product Type: Amniotic Membrane, Amniotic Fluid, Amniotic Extract, Amniotic Suspension, Placental Extract Application: Wound Care, Ophthalmology, Orthopedics, Plastic Surgery, Dental Regeneration End User: Research Institutes, Specialty Clinics, Ambulatory Surgical Centers, Regenerative Medicine Centers Delivery Mode: Cryopreserved, Lyophilized, Dehydrated, Fresh, Injectable |
| Companies Covered | MiMedx Group, Smith+Nephew, Organogenesis Inc., Integra LifeSciences Holdings Corporation, Stryker Corporation, Applied Biologics, Lucina BioSciences, TissueTech, AlloSource, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amniotic Products Market Strategic Shifts & Innovations
Product innovation is shifting focus from passive, structural support toward active, biochemical modulation of the healing environment. This evolution is driven by advanced processing techniques that better preserve the delicate growth factors and cytokines inherent in amniotic tissues.
Advanced characterization techniques are becoming central to quality control and product differentiation. High-content screening and proteomic analysis allow manufacturers to quantify the bioactive components in each allograft lot. This data-driven approach is automating the process of batch selection, ensuring that products delivered for specific clinical indications, such as diabetic foot ulcers, possess a consistent and therapeutically relevant profile of growth factors.
Regulatory bodies are increasing their scrutiny of product claims and manufacturing processes. The European Medicines Agency's (EMA) classification of certain products as Advanced Therapy Medicinal Products (ATMPs) mandates more stringent clinical data and manufacturing controls, similar to pharmaceuticals. This affects manufacturers of living cell-based grafts most directly, forcing them to invest in drug-level development pathways to maintain market access in the EU.
A notable shift in purchasing behavior is occurring within large hospital networks. Procurement decisions are moving away from individual physician preference and toward value analysis committees that demand comparative clinical and economic evidence. This change is most prominent in the United States, where integrated delivery networks require manufacturers to demonstrate not just efficacy but also a positive impact on total cost of care before granting formulary approval.
Amniotic Products Market Segmentation
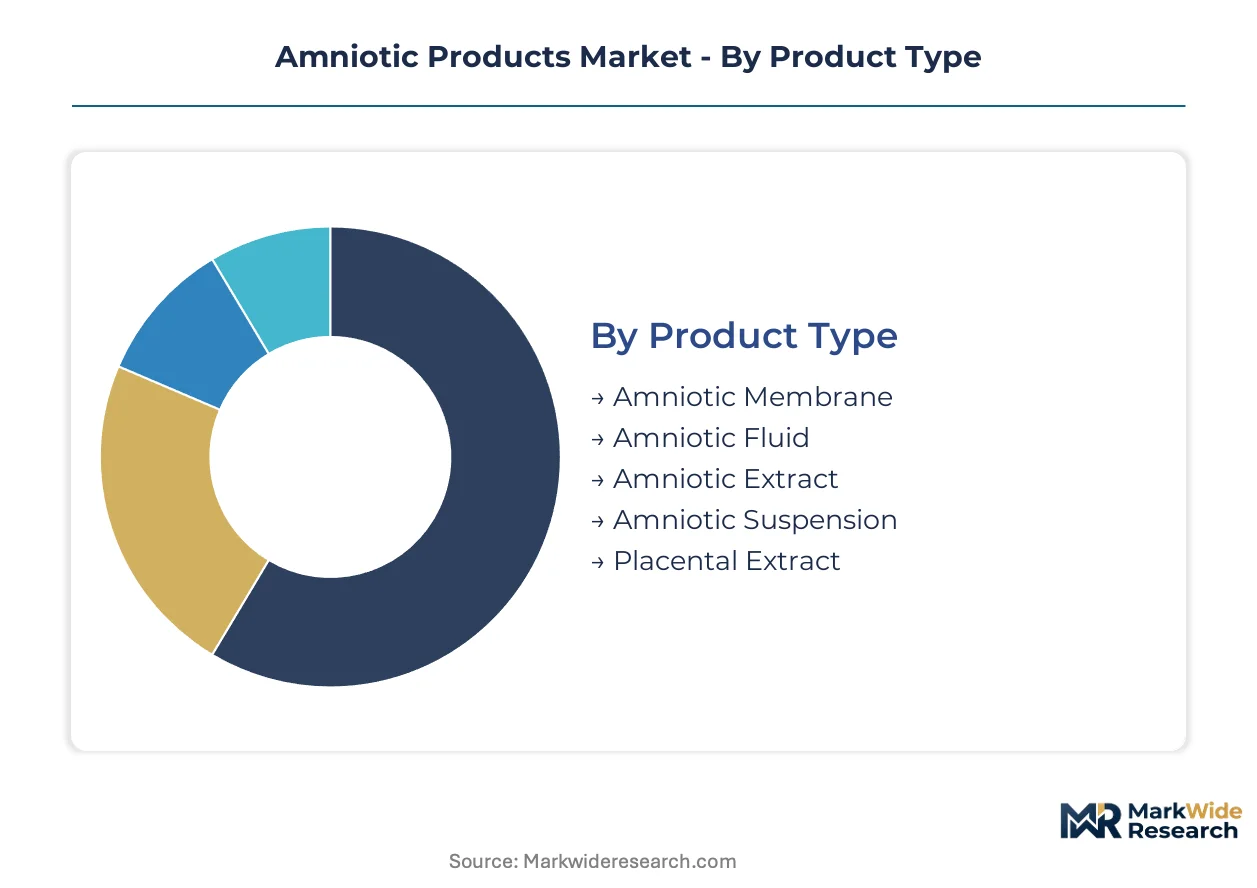
Segmentation within the amniotic products market provides a clear lens into distinct product characteristics, clinical applications, and end-user demands. This analysis highlights where innovation is concentrated and how different delivery methods impact market accessibility, guiding strategic investment and product development efforts across various therapeutic areas.
Product Type:
The product type segmentation reveals where significant capital investment is required for advanced processing and preservation technologies, influencing manufacturing complexity and product cost structures.
- Amniotic Membrane:These structural allografts, rich in extracellular matrix proteins and growth factors, provide a biological scaffold for tissue repair. Demand concentrates in chronic wound care within the United States and ophthalmology, driven by established clinical protocols and regulatory clarity from bodies like the U.S. FDA.
- Amniotic Fluid:This liquid formulation contains essential growth factors, cytokines, and hyaluronic acid, supporting tissue regeneration and inflammation modulation. Demand is rapidly expanding in orthopedics for joint pain management and sports medicine, owing to its injectable convenience and regenerative potential.
- Amniotic Extract:Derived from amniotic tissue, these concentrated formulations deliver a potent mix of bioactive molecules for targeted therapeutic effects.
- Amniotic Suspension:Comprising micronized or particulate amniotic tissue, these suspensions are often used for injectable applications in regenerative medicine.
- Placental Extract:Processed from both amniotic and chorionic membranes, placental extracts offer a broad spectrum of growth factors and anti-inflammatory agents.
Amniotic Membrane absorbs the bulk of installed capacity; Amniotic Fluid is expanding most quickly.
Application:
Understanding application segments highlights the diverse clinical needs driving product development and patient access across various medical specialties.
- Wound Care:Amniotic products are extensively used for managing chronic wounds, particularly diabetic foot ulcers, by promoting healing and reducing inflammation. This application sees high demand in specialized wound care centers across the United States and Germany, benefiting from established treatment guidelines.
- Orthopedics:This segment utilizes amniotic products for joint pain, cartilage repair, and soft tissue regeneration, often through injectable formulations. Markets in Japan and South Korea are showing significant growth, driven by an aging population and advancements in sports medicine.
- Ophthalmology:Amniotic membranes are critical for treating ocular surface diseases, persistent epithelial defects, and chemical burns, leveraging their anti-inflammatory and regenerative properties.
- Plastic Surgery:Applications include scar revision, reconstructive procedures, and enhancing tissue regeneration following surgical interventions.
- Dental Regeneration:Amniotic products support periodontal tissue regeneration, guided bone regeneration, and oral soft tissue healing in dental and maxillofacial surgery.
Wound Care applications currently generate the most clinical evidence, while Orthopedics applications are gaining significant investment for future trials.
End User:
The end-user segmentation illustrates how different healthcare settings integrate amniotic products into their service delivery models and procurement strategies.
- Regenerative Medicine Centers:These specialized facilities focus on advanced biological therapies and complex cases, often acting as early adopters for innovative amniotic products. These centers in the United States and Germany drive significant procurement due to specialized expertise and favorable reimbursement for advanced therapies.
- Specialty Clinics:Including dermatology, podiatry, and ophthalmology clinics, these settings integrate amniotic products for a range of specific conditions. These clinics are expanding access to amniotic therapies in local communities, driven by growing awareness and less invasive procedures.
- Research Institutes:Academic and commercial research institutions utilize amniotic products for preclinical studies, clinical trials, and developing next-generation regenerative therapies.
- Ambulatory Surgical Centers:These outpatient facilities provide a cost-effective setting for minor surgical procedures and offer a growing avenue for amniotic product utilization.
Regenerative Medicine Centers are primary procurement hubs for advanced amniotic products, with Specialty Clinics driving broader adoption.
Delivery Mode:
Delivery mode segmentation highlights the diverse preservation technologies enabling product shelf-life, clinical utility, and logistical considerations for healthcare providers.
- Cryopreserved:These products maintain cellular viability and biological activity through ultra-low temperature storage, requiring a robust cold chain. Regenerative medicine centers and complex surgical cases prefer cryopreserved products due to their superior biological activity, despite higher logistical costs.
- Dehydrated:Processed to remove water content, these products offer ambient storage and extended shelf stability, making them highly accessible. Dehydrated products dominate wound care applications and broader distribution channels due to their logistical ease and user-friendliness.
- Lyophilized:Freeze-dried amniotic products offer an extended shelf life while retaining a significant portion of their bioactive components, balancing stability and efficacy.
- Fresh:Minimally processed, fresh amniotic products are used immediately after collection, preserving maximal biological activity for specific clinical indications.
- Injectable:Formulated as liquids or suspensions, injectable amniotic products offer non-invasive administration for localized treatment, particularly in orthopedics and sports medicine.
Dehydrated products hold significant market share due to logistics, while Injectable formats are rapidly expanding their footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's robust biotech cluster drives significant innovation in amniotic products. This hub fosters advanced regenerative medicine therapies. Specialized centers here accelerate product adoption and clinical validation for complex cases.
United States
Chronic wound care, particularly for diabetic foot ulcers, fuels substantial demand for amniotic products. The FDA's HCT/P framework clarifies market access, encouraging new product development. California's medical device industry actively pioneers new processing techniques and clinical applications.
Germany
Established wound care protocols and expanding orthopedic applications generate strong demand. The EMA's ATMP designation influences product approval pathways for advanced therapies. Munich's biotech corridor focuses on developing and manufacturing living cell-based amniotic products.
Japan
An aging population and growing interest in orthopedic joint pain management stimulate product uptake. The PMDA streamlines approval for regenerative medicine, fostering market growth. Tokyo's medical technology firms invest in injectable amniotic formulations for sports medicine.
South Korea
Advanced healthcare infrastructure and a focus on sports medicine drive demand for regenerative solutions. The MFDS supports research and development for innovative biologics. Seoul's research institutions lead in developing next-generation combination amniotic products.
United Kingdom
Ocular surface diseases and reconstructive procedures represent specific demand drivers. The MHRA oversees tissue-based product regulations, ensuring safety and efficacy. London's specialized clinics integrate amniotic membranes for treating complex eye conditions and chronic wounds.
Amniotic Products Market Key Industry Players
Premium-margin players sit above commodity-margin players across product processing complexity and regulatory burden. The market structure features specialized innovators focusing on high-viability grafts. Broader regenerative medicine companies integrate amniotic products into wider portfolios. Strategic partnerships for distribution and extensive clinical evidence generation are dominant competitive moves.
Within the specialized regenerative medicine segment, Organogenesis Inc. exemplifies leadership in living cell-based products. MiMedx Group, a US-based firm, anchors the dehydrated human amnion/chorion membrane allograft market. Smith+Nephew, a UK-domiciled entity, represents the broader medical technology companies integrating amniotic offerings into comprehensive wound management platforms.
| Leading Market Players |
|---|
| MiMedx Group |
| Smith+Nephew |
| Organogenesis Inc. |
| Integra LifeSciences Holdings Corporation |
| Stryker Corporation |
| Applied Biologics |
| Lucina BioSciences |
| TissueTech |
| AlloSource |
| Others |
Cost & Logistics Intelligence
Aseptic collection costs, combined with the rigorous processing and testing of donor placental tissue, establish a high cost basis for final products, influencing pricing tiers downstream. These upstream expenses necessitate premium pricing for advanced amniotic therapies, particularly those requiring stringent regulatory oversight.
Pricing Analysis
Outcome-based pricing models are gaining traction, linking product value directly to clinical efficacy in wound healing or joint pain reduction. Price differentiation stems from the product's regulatory classification, such as FDA HCT/P versus EMA ATMP designation, and the specific clinical evidence supporting its use. Pricing pressure stems from value analysis committees within large hospital networks, which demand clear economic benefits for formulary inclusion. Cost-sensitive healthcare systems, especially public payers, represent the most price-sensitive buyers, while specialized regenerative medicine centers demonstrate lower sensitivity for innovative, effective therapies.
Supply Chain Analysis
Donor placental tissue supply relies heavily on live births and stringent donor screening protocols, primarily sourced within the United States and Germany. Specialized processing reagents and cryopreservation media constitute critical component dependencies for high-viability grafts. Ethical sourcing constraints and the inherent biological variability of human tissue present a structural risk, creating potential supply chain vulnerabilities. Downstream distribution runs through a dual model, leveraging specialized medical distributors for advanced therapies and direct sales teams for broader hospital network penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for consolidation, as the significant burden of clinical evidence generation and regulatory compliance pressures smaller, less capitalized players. Larger entities with established infrastructure can absorb these costs more effectively.
For Market Incumbents: To counter the persistent reimbursement ambiguity and high product costs, incumbents must invest heavily in large-scale, randomized controlled trials. Securing favorable regulatory classifications, such as full biologic drug approval, will reinforce market leadership and justify premium pricing. Strategic partnerships with specialized wound care centers and orthopedic clinics can expand market reach for established product lines.
For New Entrants and Emerging Players: Begin with targeting niche applications, such as persistent epithelial defects in ophthalmology or specific orthopedic indications with high unmet needs. Focusing on regions with streamlined regulatory pathways, like Japan for regenerative medicine, offers a lower barrier to entry. A go-to-market strategy emphasizing clear, compelling clinical data from smaller, targeted trials will attract early adopters and build initial market credibility.
For Investors and Strategic Acquirers: Clear reimbursement policies for novel injectable formulations in orthopedics is the leading indicator that signals accelerated market adoption and revenue growth. Long-term viability within this market hinges on sustained innovation in bioactive component preservation and targeted delivery mechanisms. Acquisition targets should include specialized innovators with proprietary processing techniques or strong early-stage clinical data in high-growth application areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates efficacy for new indications like joint pain management, expanding addressable patient populations. |
| Regulatory Approval Pathway | Secures market access for advanced therapy medicinal products in Europe, enabling broader commercialization. |
| Manufacturing Scale-Up | Reduces per-unit costs for dehydrated amniotic sheets in wound care, improving market competitiveness. |
| Strategic Partnership | Expands distribution channels for injectable amniotic fluid in orthopedics, reaching more healthcare providers. |
| Product Launch | Introduces specialized amniotic membrane grafts for ocular surface diseases, addressing unmet clinical needs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews with industry stakeholders. We engaged wound care specialists, orthopedic surgeons, regulatory affairs leads, and hospital procurement managers to gather expert insights. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Market volume and value outputs were modeled at a granular level across product type, application, end-user, delivery mode, and regional adoption patterns. Our analytical framework employed quantitative models and qualitative assessments to project market trajectory over the analysis window. Compound annual growth rates were derived from historical growth trends and projected market drivers, incorporating inputs like the rising prevalence of chronic wounds and orthopedic procedure volumes.
Shifts in reimbursement policy, changes in regulatory classifications, and the emergence of alternative regenerative therapies are the dominant revision risks for market forecasts. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Italy Hospital Supplies Market