
 North America Nasal Spray Market | 2026-2036
North America Nasal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nasal Spray Market Analytics
Pharmaceutical-grade formulation standards is reorganizing competitive dynamics across the North America Nasal Spray Market. GlaxoSmithKline plc dominates prescription corticosteroid segments through sustained R&D investment in aqueous delivery platforms. Johnson & Johnson Services, Inc. anchors over-the-counter positioning via channel control across mass retail and pharmacy networks.
A nasal spray comprises a liquid, suspension, or gel formulation delivered through a metered or non-metered atomizing device into the nasal cavity, with droplet size distribution typically engineered between 20-200 microns to optimize mucosal deposition and systemic absorption. Its primary commercial purpose spans symptomatic relief of allergic rhinitis, nasal congestion, and localized hormone delivery. Prescription Spray categories command premium pricing due to clinical validation requirements, while Over-the-Counter Spray segments expand fastest through pharmacy self-selection trends. Metered Dose delivery systems concentrate margin pools where dose consistency underpins reimbursement eligibility.
FDA bioequivalence guidance and Health Canada stability protocols shape product development timelines and market access thresholds for new entrants. EPA environmental assessments for propellant-based systems add compliance layers that favor aqueous formulation transitions. Stakeholders must monitor evolving regulator positions on complex generic pathways for locally acting nasal products.
Market Dynamics
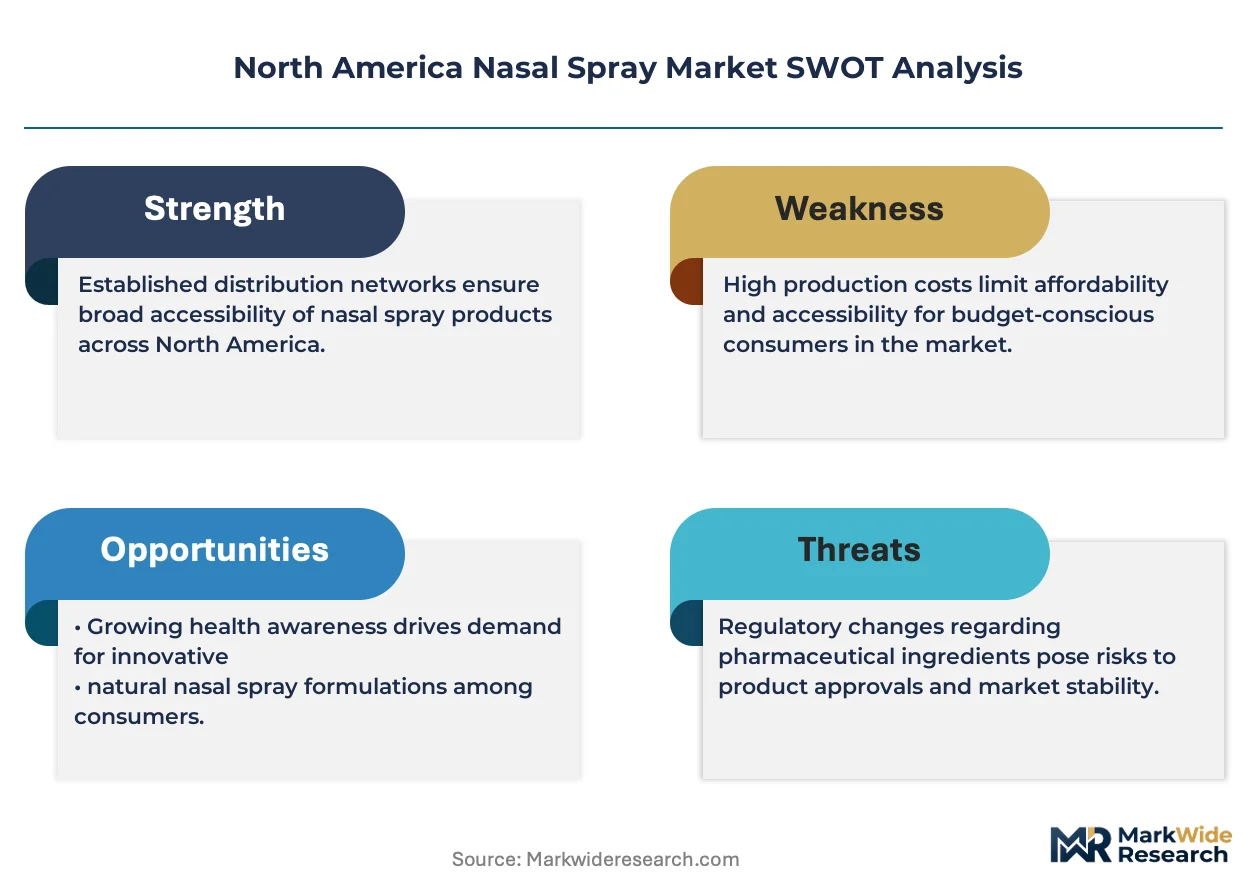
FDA bioequivalence tightening for locally acting nasal products is compressing development timelines and elevating capital requirements for generic entrants across the United States and Canada. This regulatory pressure is concentrating competitive advantage among incumbents with established aqueous formulation platforms and clinical validation archives.
Growth Catalysts
- Seasonal allergen intensity:Rising pollen burden across the United States Southeast and Midwest sustains year-round demand cycles for symptomatic relief products. Pediatric allergists increasingly prescribe intranasal corticosteroids as first-line therapy.
- Health Canada stability protocol harmonization:Streamlined approval pathways for complex generics accelerate market access for Canadian manufacturers with advanced spray characterization capabilities.
- Aqueous propellant transition:EPA environmental assessments are forcing rapid phase-out of chlorofluorocarbon systems, opening formulation services demand for hydrofluoroalkane alternatives.
Market Restraints
- API supply concentration:Fluticasone propionate and mometasone furoate active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, exposing formulators to import tariff volatility.
- Device sourcing fragility:Metered-dose pump mechanisms rely on a limited supplier base in Switzerland and Germany, creating single-source risk for dose-consistency-critical products.
- Clinical endpoint complexity:FDA bioequivalence studies for locally acting nasal sprays require expensive pharmacokinetic and clinical endpoint trials that deter mid-cap generic entrants.
Strategic Opportunities
- Central Canada distribution hub:Underpenetrated pharmacy networks in Ontario and Quebec provinces offer volume expansion for direct-to-consumer delivery platforms with cold-chain capabilities.
- Hormone replacement convergence:Intranasal testosterone and estrogen delivery systems intersect with aging demographic demand across Florida, Arizona, and California retirement corridors.
- Complex generic pathway acceleration:FDA draft guidance on physiologically-based pharmacokinetic modeling creates regulatory tailwinds for sponsors with advanced simulation capabilities.
Industry Challenges
- Spray characterization talent scarcity:Specialized analytical chemists capable of droplet size distribution validation and plume geometry analysis command premium compensation in Boston and Research Triangle Park clusters.
- Legacy ERP integration:Batch record systems at established United States manufacturers resist seamless incorporation of continuous manufacturing process analytical technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nasal Spray Market |
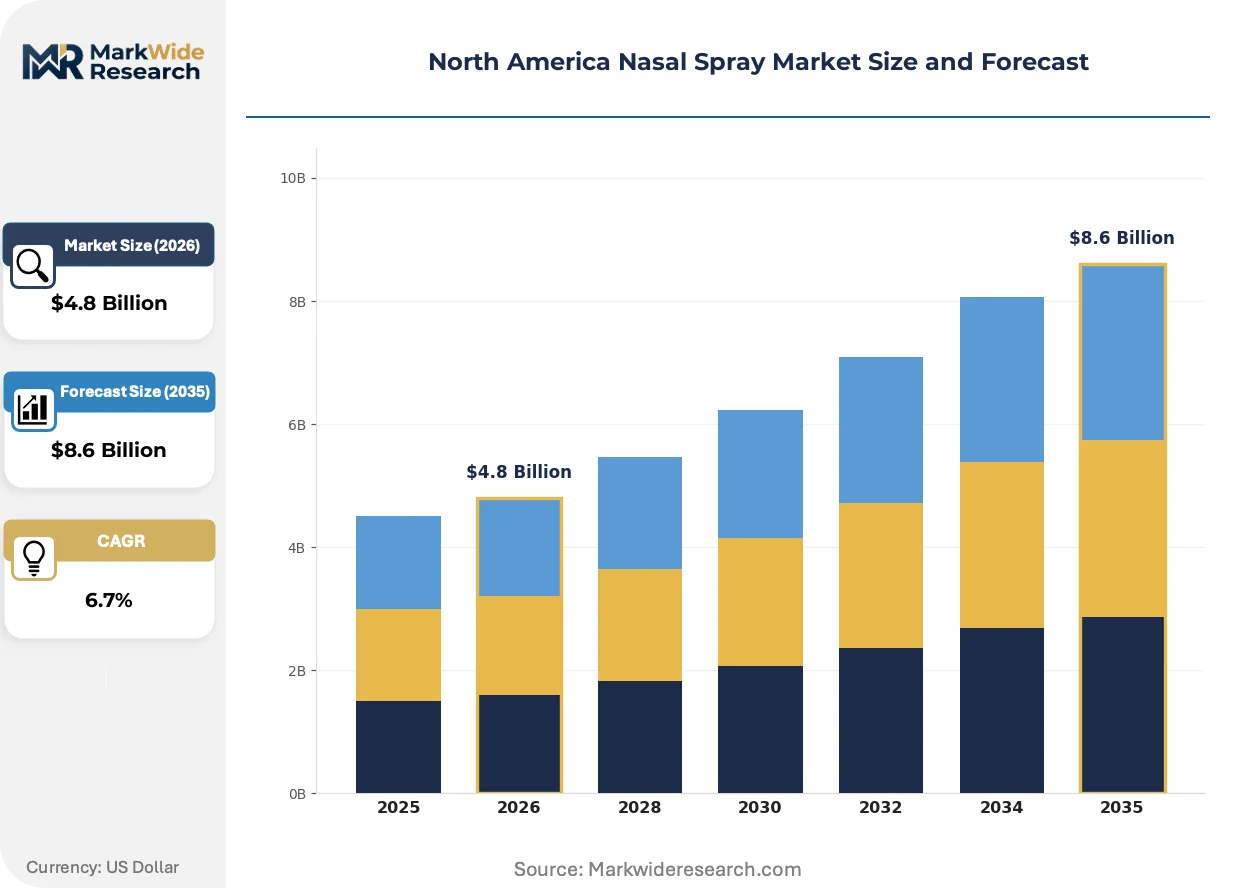
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Spray, Over-the-Counter Spray, Herbal Spray, Combination Spray Formulation Type: Aqueous Solution, Suspension, Emulsion, Gel Delivery Mode: Metered Dose, Non-Metered Dose, Pump Spray, Spray Bottle Indication: Allergic Rhinitis, Nasal Congestion, Nasal Inflammation, Hormonal Treatment |
| Companies Covered | Viatris Inc., NeilMed Pharmaceuticals Inc., GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Bayer AG, Merck & Co., Inc., Bausch Health Companies Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nasal Spray Market Evolving Landscape
Formulation science and delivery mechanism engineering are converging to redefine therapeutic efficacy benchmarks across prescription and over-the-counter nasal spray categories. Device manufacturers and pharmaceutical sponsors are co-investing in platform technologies that compress development cycles while tightening dose reproducibility.
Preservative-free multidose systems are supplanting benzalkonium chloride-stabilized formulations in pediatric and chronic-use segments. United States allergists and otolaryngologists are accelerating adoption of these systems for patients with mucosal sensitivity or prolonged treatment durations. This shift is compressing margins for legacy aqueous formulations while opening premium positioning for novel antimicrobial closure technologies.
EPA propellant phase-down mandates under the Significant New Alternatives Policy are restructuring environmental compliance obligations for United States manufacturers. Hydrofluoroalkane transition timelines are compressing, forcing simultaneous reformulation and device redesign investments. Aqueous-based pump systems in allergic rhinitis applications are capturing displaced volume from pressurized metered-dose inhaler architectures.
Direct-to-consumer subscription models are disrupting traditional pharmacy replenishment patterns for chronic rhinitis sufferers. Telehealth platforms in Texas and California are integrating automated refill algorithms with symptom-tracking applications. This channel innovation concentrates most visibly among millennial and Generation X patient cohorts seeking price transparency and delivery convenience.
North America Nasal Spray Market Segmentation
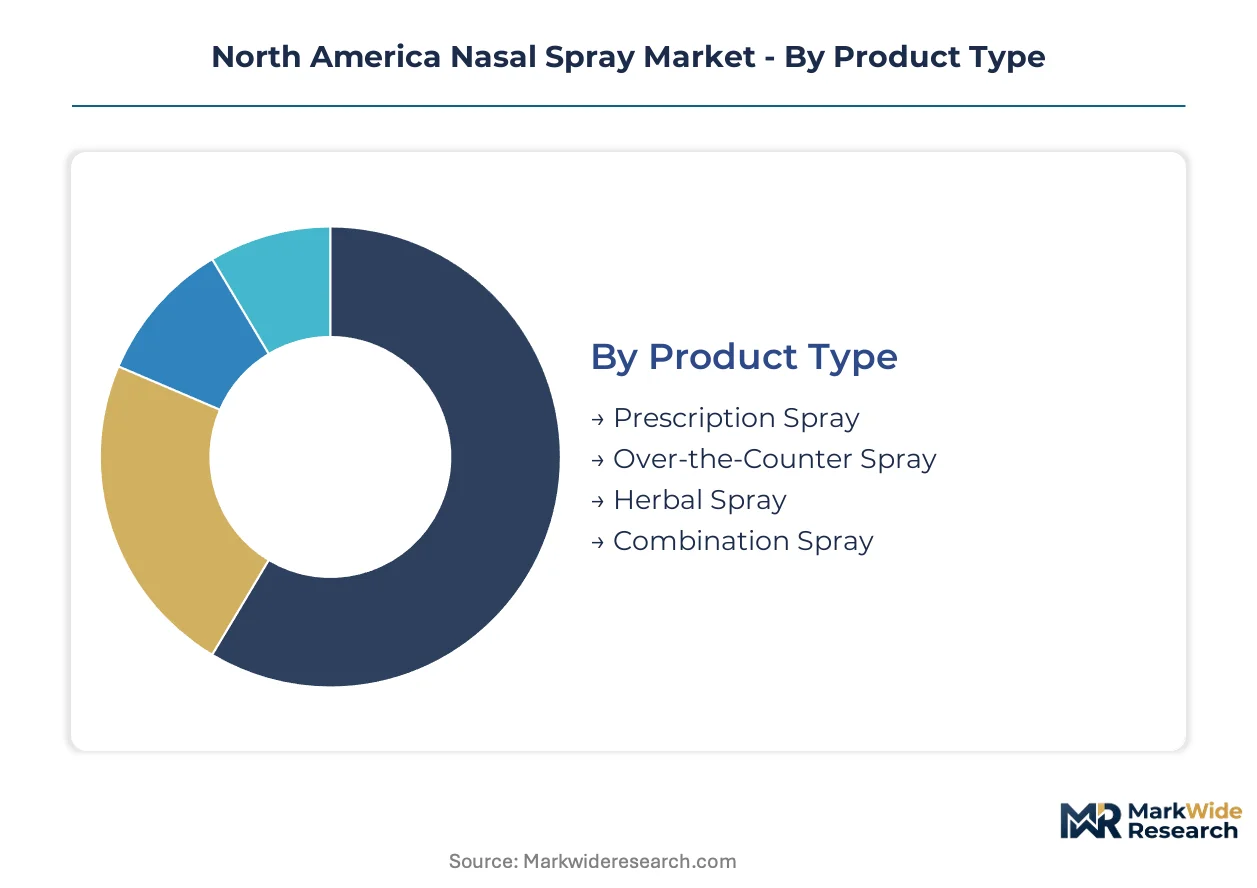
Segmentation in the North America Nasal Spray Market reveals distinct margin architectures across therapeutic categories. Prescription and over-the-counter pathways operate under divergent regulatory burdens, pricing flexibility, and channel economics that shape strategic positioning.
Product Type:
Margin pools concentrate where clinical validation requirements create pricing power and reimbursement leverage.
- Prescription Spray:Corticosteroid and antihistamine formulations requiring FDA New Drug Application or Abbreviated New Drug Application approval. Demand concentrates among pediatric allergists in the United States Southeast prescribing intranasal corticosteroids as first-line therapy, where clinical endpoint studies justify premium positioning.
- Over-the-Counter Spray:Decongestant and saline formulations sold without prescription through pharmacy and mass retail channels. Volume leadership sits with direct-to-consumer platforms in California and Texas, where telehealth-integrated subscription models compress traditional pharmacy replenishment cycles.
- Herbal Spray:Botanical extract formulations including eucalyptus and peppermint oil suspensions marketed for natural positioning.
- Combination Spray:Fixed-dose combinations of corticosteroid and antihistamine active pharmaceutical ingredients.
The dominant share belongs to Prescription Spray, while Over-the-Counter Spray is gaining share fastest through self-selection trends and channel disruption.
Formulation Type:
Cost tier differentiation separates aqueous platforms from complex dispersion systems requiring specialized manufacturing infrastructure.
- Aqueous Solution:Homogeneous water-based formulations with dissolved active pharmaceutical ingredients. United States manufacturers in Research Triangle Park clusters are accelerating aqueous transitions as EPA propellant phase-down mandates compress hydrofluoroalkane transition timelines.
- Suspension:Heterogeneous systems with micronized drug particles dispersed in aqueous or non-aqueous media. Health Canada stability protocol harmonization is streamlining approval pathways for Canadian manufacturers with advanced spray characterization capabilities in Ontario.
- Emulsion:Oil-in-water or water-in-oil systems for lipophilic active pharmaceutical ingredient delivery.
- Gel:Viscous formulations with enhanced mucoadhesive properties for prolonged nasal cavity residence.
Aqueous Solution commands the largest installed base, though Suspension is climbing the fastest as complex generic pathways mature.
Delivery Mode:
Volume concentration tracks device sourcing reliability and dose consistency validation requirements.
- Metered Dose:Precision pump mechanisms delivering fixed-volume actuations with documented spray pattern and droplet size distribution. FDA bioequivalence tightening for locally acting nasal products elevates capital requirements for metered-dose system validation, concentrating advantage among incumbents with established aqueous platforms.
- Non-Metered Dose:Manual squeeze bottles or simple pump systems without volume standardization. Demand persists in price-sensitive segments and acute decongestant applications across Canadian pharmacy networks.
- Pump Spray:Mechanical actuation systems with finger-operated compression.
- Spray Bottle:Squeeze-activated plastic containers for saline irrigation and rinse applications.
Metered Dose holds the revenue concentration, with Non-Metered Dose expanding most quickly in private-label pharmacy channels.
Indication:
Application maturity varies across symptomatic relief versus chronic disease management paradigms.
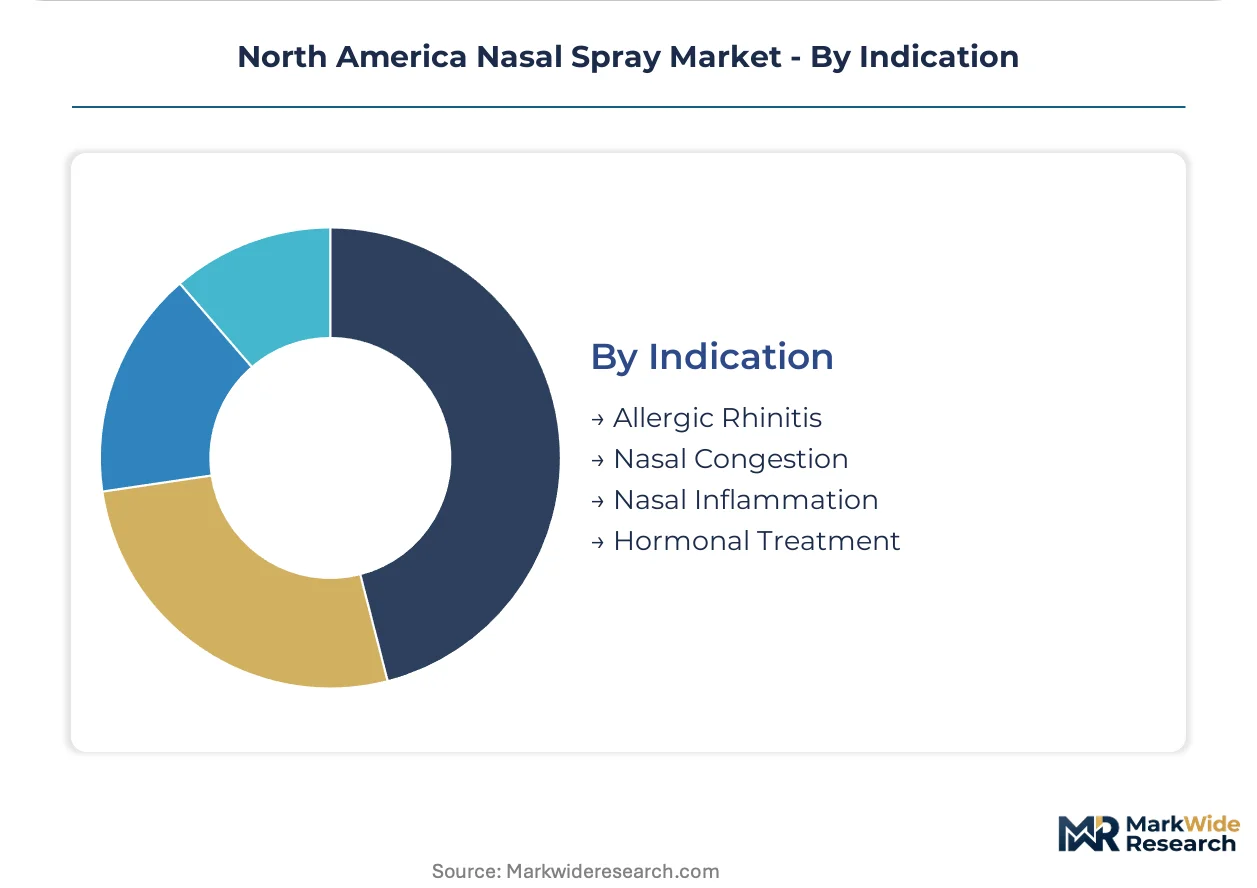
- Allergic Rhinitis:Symptomatic treatment of seasonal and perennial allergic responses to pollen, dust mites, and pet dander. Pediatric allergists in the United States Midwest are expanding intranasal corticosteroid prescriptions as pollen burden intensifies.
- Nasal Congestion:Acute decongestant applications for upper respiratory infection and sinusitis. Arizona and Florida retirement corridors sustain volume for combination decongestant-antihistamine formulations through Medicare Part D channels.
- Nasal Inflammation:Chronic rhinosinusitis and post-surgical anti-inflammatory management.
- Hormonal Treatment:Intranasal testosterone and estrogen delivery for hormone replacement therapy.
Allergic Rhinitis anchors the indication mix, while Hormonal Treatment shows the steepest expansion trajectory intersecting with aging demographic demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation expertise clusters along FDA-regulated corridors and Health Canada oversight zones, with device manufacturing capabilities concentrating in precision-engineering hubs across the continent. Market access dynamics diverge sharply between reimbursement-heavy prescription pathways and direct-to-consumer pharmacy channels.
United States
Pollen burden intensification across the Southeast and Midwest sustains year-round demand cycles for symptomatic relief products. FDA bioequivalence tightening for locally acting nasal products elevates capital requirements for generic entrants. Research Triangle Park in North Carolina anchors aqueous formulation development as EPA propellant phase-down mandates compress hydrofluoroalkane transition timelines.
Canada
Health Canada stability protocol harmonization streamlines approval pathways for complex generics with advanced spray characterization capabilities. Pediatric and geriatric patient populations represent the fastest-expanding end-use cohort across Ontario and Quebec provinces. Toronto-area manufacturers accelerate metered-dose pump validation investments to capture displaced volume from pressurized systems.
Mexico
Direct-to-consumer pharmacy networks in Mexico City and Guadalajara sustain volume expansion for over-the-counter decongestant and saline formulations. COFEPRIS regulatory alignment with FDA bioequivalence standards tightens quality benchmarks for imported finished products. Baja California manufacturing clusters attract contract formulation services for US-bound aqueous spray production.
North America Nasal Spray Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Nasal Spray Market. Prescription corticosteroid segments concentrate among incumbents with established clinical validation archives and aqueous platform expertise. Over-the-counter and private-label channels fragment across mass retail suppliers with pharmacy network control. Dominant competitive moves include strategic partnerships between device manufacturers and formulation sponsors, plus portfolio diversification into preservative-free multidose systems.
Among UK-based pharmaceutical multinationals, GlaxoSmithKline plc exemplifies the prescription-focused archetype with sustained aqueous delivery platform investment. Johnson & Johnson Services, Inc. anchors over-the-counter positioning through mass retail and pharmacy channel control across the United States. Teva Pharmaceutical Industries Ltd. represents the complex generic pathway specialist segment navigating FDA bioequivalence requirements for locally acting products.
| Leading Market Players |
|---|
| Viatris Inc. |
| NeilMed Pharmaceuticals Inc. |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Bayer AG |
| Merck & Co., Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for fluticasone propionate and mometasone furoate APIs lock in supply access and price visibility for North American formulators, insulating incumbents from Indian and Chinese contract manufacturer tariff volatility while compressing margin flexibility for spot-market buyers.
Pricing Analysis
FDA bioequivalence standards for locally acting nasal products dictate the pricing tier structure across prescription and over-the-counter pathways. Three-tier pricing structure across premium, standard, and economy levels separates validated aqueous corticosteroid platforms from benzalkonium chloride-stabilized legacy formulations and private-label decongestants. Cost compression in the OTC tier is intensifying because direct-to-consumer subscription models force pharmacy networks into price-matching behavior. Medicare Part D beneficiaries in Florida and Arizona retirement corridors show least price sensitivity for hormone replacement nasal therapies, while millennial self-selectors in Texas pharmacy channels exhibit highest elasticity.
Supply Chain Analysis
Port congestion on the Ningbo-Los Angeles trade lane elevates inbound logistics costs for API shipments from Zhejiang province contract manufacturers. Active pharmaceutical ingredient supply concentrates in India and China, with device pump mechanisms sourcing from Switzerland and Germany. Formulation science talent clusters in Research Triangle Park and Boston draw from specialized analytical chemistry programs at Duke and MIT. Single-source vulnerability pervades metered-dose pump validation equipment, where Swiss suppliers command twelve-month order backlogs. Distribution runs through McKesson and Cardinal Health wholesale networks for prescription tiers, with Amazon Pharmacy and CVS Caremark direct-to-consumer platforms capturing OTC volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from preservative-free multidose systems and telehealth-integrated subscription platforms that disintermediate traditional pharmacy replenishment cycles for chronic rhinitis sufferers.
For Market Incumbents: Shield aqueous formulation margins by accelerating backward integration into spray characterization laboratory capabilities in Research Triangle Park, insulating against analytical chemist talent scarcity. Secure exclusive capacity reservation agreements with Swiss pump mechanism suppliers before hydrofluoroalkane transition timelines compress further. FDA draft guidance on physiologically-based pharmacokinetic modeling threatens to erode clinical validation archives as competitive moats.
For New Entrants and Emerging Players: Subscription-layer service gaps in automated refill algorithms with symptom-tracking applications offer white-space entry points where Johnson & Johnson and GlaxoSmithKline under-serve millennial cohorts. Target Ontario and Quebec pharmacy networks with cold-chain direct-to-consumer delivery platforms, the most penetrable geography given Health Canada stability protocol harmonization. Pursue complex generic pathway acceleration through partnerships with Toronto-area manufacturers possessing advanced plume geometry analysis capabilities.
For Investors and Strategic Acquirers: Formulation-development boutiques with FDA-established aqueous platform expertise and clinical endpoint study archives represent the highest-conviction acquisition archetype for portfolio diversification. Long-term viability hinges on EPA propellant phase-down compliance positioning and telehealth channel integration depth. Watch FDA bioequivalence guidance finalization timing as the critical inflection signal for generic pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Multidose Transition | Pediatric allergist prescribing shifts in the United States Southeast favor mucosal-sensitive formulations. |
| Aqueous Platform Scale-Up | EPA Significant New Alternatives Policy mandates force hydrofluoroalkane system phase-out investments. |
| Telehealth Subscription Integration | Texas and California millennial cohorts demand price-transparent automated refill algorithms. |
| Complex Generic Pathway Investment | Health Canada stability protocol harmonization accelerates Ontario manufacturer market access. |
| Spray Characterization Talent Acquisition | Boston and Research Triangle Park clusters face premium compensation inflation for analytical chemists. |
Research Methodology
Desk research of FDA bioequivalence guidance documents, Health Canada stability protocols, and EPA Significant New Alternatives Policy filings preceded structured interviews with regulatory affairs leads at aqueous formulation developers, pediatric allergists in the United States Southeast and Midwest, pharmacy benefit managers at CVS Caremark and Express Scripts, and spray characterization laboratory directors in Research Triangle Park. Secondary validation drew from FDA Orange Book listings, ClinicalTrials.gov intranasal corticosteroid endpoint studies, CMS Medicare Part D utilization data, and customs import records for fluticasone propionate API shipments. Bottom-up patient population modeling and top-down pharmaceutical manufacturer revenue triangulation anchored market sizing.
Variance decomposition across the projection horizon isolated volume, price, and mix drivers by therapeutic category, formulation type, and delivery mode. Segmentation dimensions modeled include prescription versus over-the-counter pathway, aqueous versus suspension versus emulsion formulation, metered versus non-metered dose mechanism, and allergic rhinitis versus nasal congestion versus hormonal treatment indication. CAGRs derived from regression-adjusted historical growth rates applied to demographic and pollen burden projections. Forecast inputs incorporated EPA propellant phase-down compliance cost curves and telehealth subscription platform penetration trajectories.
Material uncertainties — FDA bioequivalence guidance finalization timing, Indian and Chinese API import tariff volatility, Swiss pump mechanism supplier capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding Health Canada stability protocol harmonization pace and direct-to-consumer pharmacy channel share capture. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Europe Ultrasound Gels Market
Medical Supplies
Human Acellular Dermis Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Amniotic Membrane Market